
 Global Advanced Authentication Market | 2026-2036
Global Advanced Authentication Market Size, Share, and Industry Trends Forecast 2026-2036
Global Advanced Authentication Market Intelligence
Passwordless architecture is rewriting enterprise security roadmaps. Microsoft leverages its Entra identity platform to anchor cloud-native authentication across Fortune 500 deployments. Thales Group specializes in hardware security modules and PKI credentialing for defense and government clients. IBM competes through its Verify portfolio, integrating AI-driven risk analytics with legacy mainframe environments.
Advanced authentication encompasses multi-factor identity verification systems that combine cryptographic tokens, biometric templates, behavioral telemetry, and risk scoring algorithms to establish trust in digital transactions. These systems operate through FIDO2/WebAuthn protocols, liveness detection in facial recognition, and continuous adaptive risk and trust assessment engines that evaluate device posture, location signals, and user behavior patterns in real time. Biometrics and risk-based authentication command the deepest margin pools as enterprises abandon static passwords for continuous verification models. Cloud deployment modes are expanding fastest among mid-market adopters seeking elastic capacity without capital-intensive on-premises infrastructure. Token-based methods retain substantial share in regulated sectors where hardware-backed assurance remains mandatory.
FDA guidelines for healthcare data access, the EU AI Act's biometric surveillance restrictions, and India's RBI mandates on multi-factor authentication for digital payments collectively shape product roadmaps and market access requirements. Compliance with GDPR's data minimization principles and ISO/IEC 30107-3 presentation attack detection standards now determines competitive viability in European procurement cycles. Stakeholders must monitor how quantum-resistant cryptography standards from NIST will force certificate-based infrastructure refreshes.
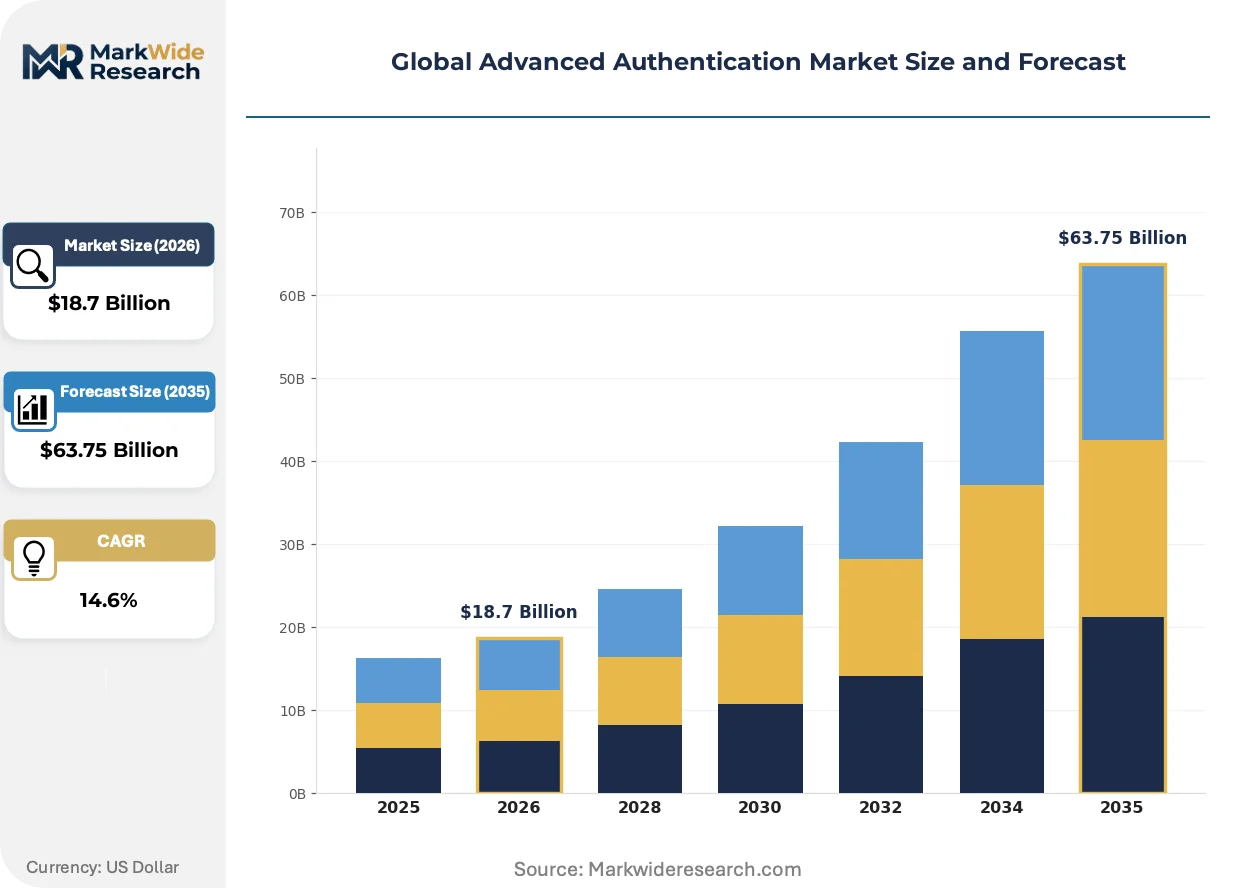
Market Dynamics
Passwordless authentication is compressing enterprise procurement cycles as CIOs mandate FIDO2-compliant identity stacks ahead of NIST's post-quantum cryptography deadlines. This architectural pivot is redistributing vendor power toward platform-native providers and fragmenting hardware token incumbents.
Growth Catalysts
- EU AI Act biometric governance:The regulation's liveness detection mandates for high-risk applications are accelerating ISO/IEC 30107-3 certified solution deployments across European financial services.
- UPI transaction volume surge:India's central bank mandates on multi-factor authentication for digital payments are forcing banking infrastructure upgrades toward risk-based behavioral models.
- Post-quantum cryptography standards:NIST's algorithm finalization is driving certificate infrastructure refreshes across defense and government identity systems.
Market Restraints
- Hardware security module concentration:Foundry capacity for FIPS 140-3 Level 4 certified silicon concentrates in German and Taiwanese manufacturing clusters.
- Biometric template storage costs:GDPR data minimization requirements impose encrypted vault architectures that inflate operational expenditure for mid-market deployments.
- Behavioral telemetry latency:Real-time risk scoring demands sub-100ms edge compute infrastructure that remains unevenly distributed across emerging markets.
Strategic Opportunities
- Indonesian digital banking licensing:The country's central bank is issuing new digital banking permits with explicit biometric onboarding requirements for unbanked population segments.
- Healthcare identity convergence:FDA guidelines for healthcare data access are creating procurement specifications that merge clinical authentication with enterprise identity fabrics.
- Continuous authentication protocols:Integration of keystroke dynamics with facial liveness detection is opening zero-trust architecture contracts in remote workforce management.
Industry Challenges
- FIDO2 implementation expertise scarcity:Enterprise IT departments lack sufficient WebAuthn protocol engineering capacity to execute passwordless migrations on contracted timelines.
- Legacy mainframe integration friction:IBM Z-series environments require custom cryptographic module bridging that extends deployment cycles and inflates professional services dependency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Advanced Authentication Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $63.75 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Authentication Technology: Biometrics, Token-Based, Knowledge-Based, Risk-Based, Behavioral, Certificate-Based Deployment Mode: Cloud, On-Premises, Hybrid, Hosted, Virtual, Edge Application Sector: Banking & Finance, E-Commerce, Government Services, Telecommunications, Insurance, Education End User: Financial Institutions, Online Retailers, Public Agencies, Telecom Operators, Educational Institutions, Healthcare Providers |
| Companies Covered | Microsoft, IBM, Okta, NEC Corporation, Fujitsu, Broadcom, Dell Technologies, Thales Group, RSA Security, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Advanced Authentication Market Strategic Shifts & Innovations
Authentication architecture is fragmenting across cloud-native, edge-deployed, and sovereign-hosted models as data residency requirements multiply. This divergence is forcing vendors to maintain parallel product lines with divergent compliance postures.
Behavioral biometrics is migrating from static session login toward continuous transaction monitoring. Retail banking platforms in Singapore and the Netherlands are embedding keystroke dynamics and mouse-trajectory analysis into mobile applications. This shift is compressing fraud detection windows from batch overnight processing to real-time intervention.
The EU AI Act's prohibition on emotion recognition in workplace and educational settings is redrawing product roadmaps for facial analysis vendors. Industrial consequence includes mandatory disclosure requirements for biometric data retention periods and processing purposes. Financial services procurement teams in Frankfurt and Paris are now requiring algorithmic impact assessments as standard contract terms.
Enterprise buyers are consolidating authentication spend under platform contracts rather than point-solution procurement. Security leaders in Fortune 500 technology and pharmaceutical sectors are demanding unified identity fabrics that span workforce, consumer, and machine-to-machine use cases. This concentration is most visible in North American enterprise renewals where multi-year identity platform commitments are displacing annual token refresh cycles.
Global Advanced Authentication Market Segmentation
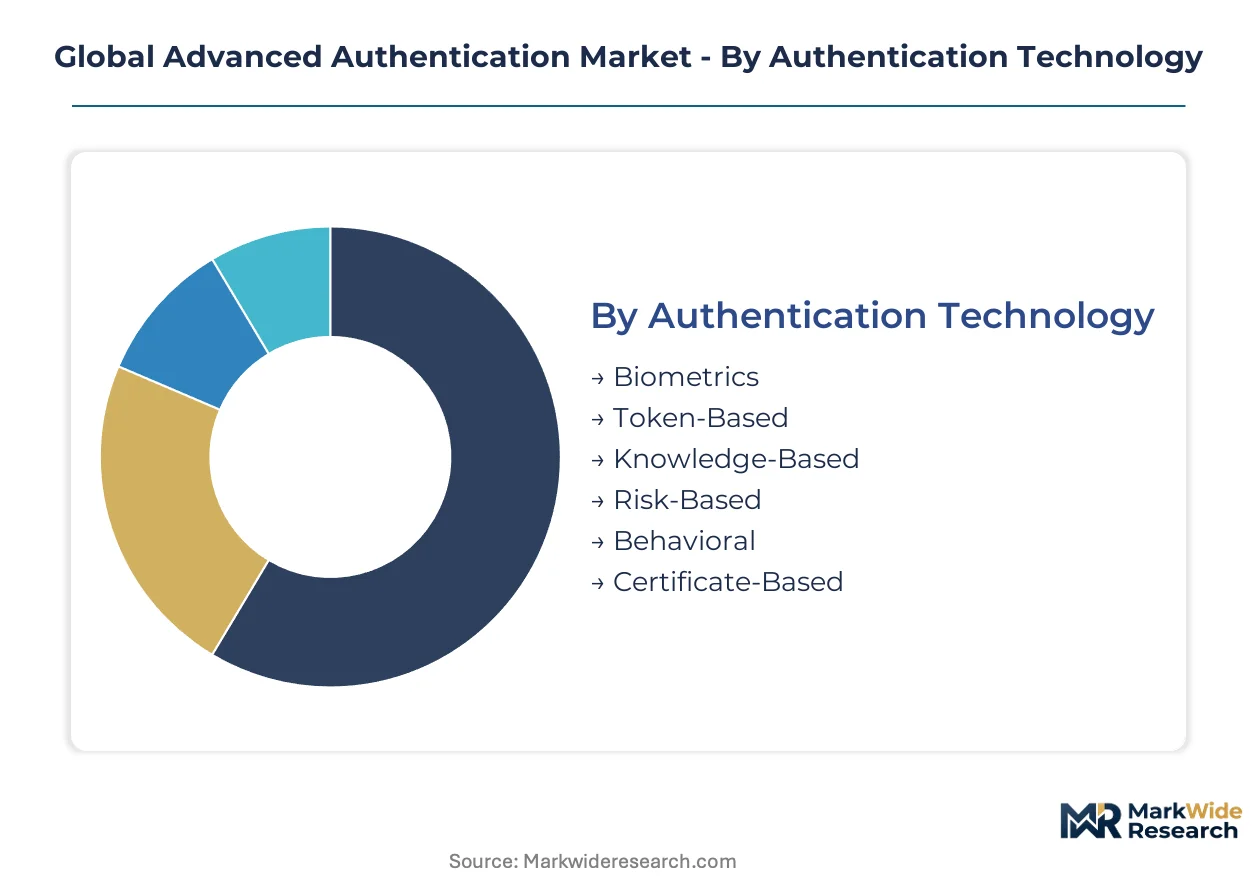
Segmentation in advanced authentication reveals how procurement priorities diverge across technology maturity cycles. Deployment timelines stretch from months for cloud-native rollouts to years for hardware-backed government systems.
Authentication Technology:
Biometric and token-based systems command the longest refresh cycles, while risk-based and behavioral methods iterate quarterly as algorithms improve.
- Biometrics:Fingerprint, facial, and iris recognition systems with liveness detection per ISO/IEC 30107-3 standards. German financial institutions and Singaporean banks are expanding facial recognition deployments under tightening EU AI Act governance.
- Token-Based:Hardware security modules and cryptographic tokens delivering FIPS 140-3 Level 3+ assurance. Defense and government clients in the US and Germany mandate these for classified system access despite supply constraints from concentrated foundry capacity.
- Knowledge-Based:Static password and PIN systems with declining enterprise adoption.
- Risk-Based:Continuous scoring engines analyzing device posture, location, and behavioral signals.
- Behavioral:Keystroke dynamics and mouse-trajectory analysis for seamless verification.
- Certificate-Based:PKI credentialing systems facing NIST post-quantum cryptography migration pressures.
Token-based systems anchor the volume base while risk-based authentication gains share at the steepest rate.
Deployment Mode:
Cost structures separate elastic cloud subscriptions from capital-intensive sovereign hosting requirements.
- Cloud:Multi-tenant SaaS delivery with elastic capacity scaling. Mid-market enterprises in India and Brazil prefer this model to avoid data center capital expenditure.
- On-Premises:Dedicated infrastructure within enterprise-controlled facilities. Regulated sectors in Germany and Switzerland require these deployments for data residency compliance.
- Hybrid:Split architectures balancing cloud agility with sensitive workload containment.
- Hosted:Single-tenant managed services with vendor-operated infrastructure.
- Virtual:Containerized authentication services abstracted from underlying hardware.
- Edge:Distributed processing nodes delivering sub-100ms latency for real-time risk scoring.
Cloud deployments dominate new procurement while edge infrastructure expands most quickly among latency-sensitive use cases.
Application Sector:
Transaction volumes and fraud exposure levels determine authentication sophistication requirements across sectors.
- Banking & Finance:Multi-factor verification for wire transfers, account access, and high-value transactions. India's UPI volume surge is forcing infrastructure upgrades toward behavioral risk models under RBI mandates.
- E-Commerce:Frictionless checkout authentication balancing conversion rates with chargeback protection.
- Government Services:Citizen identity verification with sovereign data control requirements.
- Telecommunications:SIM swap prevention and subscriber onboarding verification.
- Insurance:Claims processing authentication with fraud detection integration.
- Education:Student identity verification with EU AI Act restrictions on biometric surveillance in educational settings.
Banking & Finance anchors the volume base while e-commerce authentication climbs the fastest as digital transaction volumes accelerate.
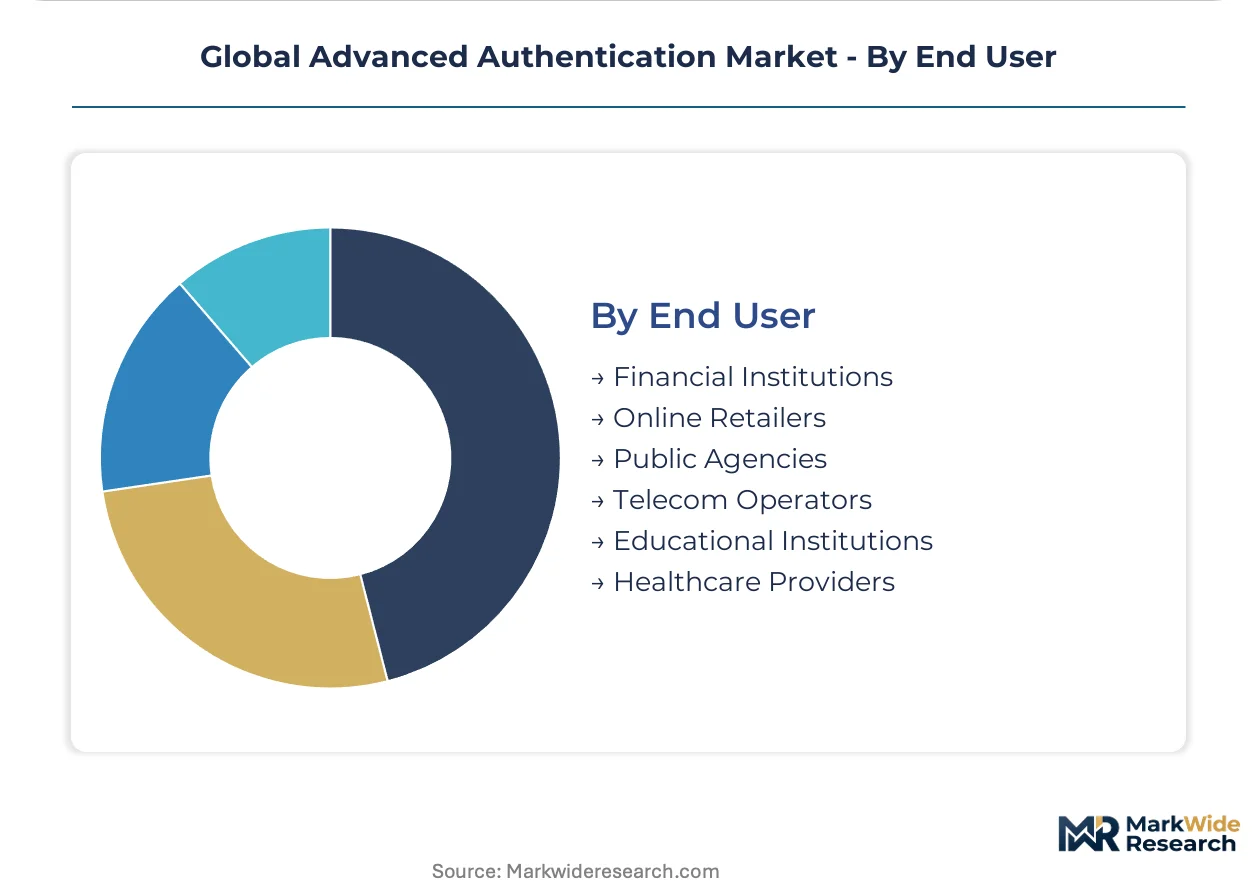
End User:
Procurement sophistication separates enterprise security operations from resource-constrained institutional buyers.
- Financial Institutions:Tier-1 banks with dedicated identity engineering teams and multi-year platform contracts. Frankfurt and Singapore headquarters are consolidating authentication spend under unified identity fabrics.
- Online Retailers:Conversion-optimized authentication with abandoned-cart minimization priorities.
- Public Agencies:Citizen-facing services with accessibility and inclusivity mandates.
- Telecom Operators:Subscriber lifecycle management with regulatory Know-Your-Customer obligations.
- Educational Institutions:Campus access and remote learning verification systems.
- Healthcare Providers:Clinical authentication merging with enterprise identity under FDA healthcare data access guidelines.
Financial institutions anchor the volume base while healthcare providers are expanding most quickly as clinical and enterprise identity systems converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial institutions in Frankfurt, Singapore, and Mumbai are consolidating authentication procurement under unified identity platforms. Sovereign data requirements and biometric governance frameworks are fragmenting deployment architectures across jurisdictions.
United States
Defense agencies and healthcare systems are driving FIPS 140-3 Level 4 hardware demand. FDA guidelines for clinical data access are merging enterprise and medical authentication specifications. Washington DC and Northern Virginia host concentrated federal identity infrastructure deployments.
Germany
Automotive OEMs and banking consortia are mandating ISO/IEC 30107-3 certified facial liveness detection. The EU AI Act's biometric surveillance restrictions are forcing algorithmic impact assessments into standard procurement terms. Munich and Frankfurt financial clusters are expanding behavioral risk model deployments.
Singapore
Digital banking licenses and wealth management platforms are embedding continuous authentication protocols. The Monetary Authority of Singapore's technology risk management guidelines require multi-factor verification for high-value wire transfers. Marina Bay financial district anchors regional identity platform operations.
India
UPI transaction volumes exceeding 10 billion monthly payments are forcing banking infrastructure toward risk-based behavioral models. RBI mandates on multi-factor authentication for digital payments are compressing vendor procurement cycles. Mumbai and Bengaluru fintech clusters are deploying cloud-native identity stacks.
United Kingdom
Open banking APIs and real-time payment systems are requiring stepped-up authentication for third-party data access. The Financial Conduct Authority's operational resilience requirements are extending identity verification to critical third-party providers. London's Canary Wharf hosts concentrated financial services identity engineering teams.
Global Advanced Authentication Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented procurement hierarchies. Platform-native providers with cloud identity fabrics are displacing hardware token incumbents in mid-market enterprise segments. Three archetypes dominate: hyperscale cloud platforms with integrated security stacks, defense-specialist hardware security module manufacturers, and pure-play identity SaaS vendors. Competitive moves concentrate on strategic partnerships with system integrators and portfolio diversification into adjacent zero-trust infrastructure.
Within the platform-native tier, Microsoft and Okta occupy positions anchoring cloud-first enterprise migrations. Thales Group exemplifies the hardware assurance archetype serving defense and government clients with FIPS-certified modules. IBM sits within the legacy integration tier, bridging mainframe environments with modern authentication protocols.
| Leading Market Players |
|---|
| Microsoft |
| IBM |
| Okta |
| NEC Corporation |
| Fujitsu |
| Broadcom |
| Dell Technologies |
| Thales Group |
| RSA Security |
| Others |
Cost & Logistics Intelligence
FIPS 140-3 Level 4 foundry concentration in German and Taiwanese manufacturing clusters determines both premium-tier pricing spreads and hardware security module supply chain architecture. This single-source dependency for certified silicon creates procurement chokepoints that compress margin pools for mid-market token vendors while amplifying pricing power for defense-contracted manufacturers.
Pricing Analysis
Cost-plus contracts with germanium and rare-earth indexation dominate hardware security module procurement. Three-tier pricing structure across FIPS 140-3 Level 4, Level 3, and uncertified tiers separates defense-grade premiums from commercial mid-market offerings. Price differentiation hinges on certification tier and volume scale, with annual enterprise commitments commanding 15-30 point discounts against spot procurement. Pricing pressure stems from cloud-native SaaS alternatives displacing capital-intensive hardware refresh cycles. Mid-market financial institutions in India and Brazil exhibit highest price sensitivity, while US defense agencies and German automotive OEMs demonstrate lowest elasticity due to sovereign assurance mandates.
Supply Chain Analysis
Contract manufacturing concentrates with TSMC foundry capacity for secure element fabrication and Foxconn EMS for token assembly. Geographic supply concentration centers on Taiwan, Germany, and South Korea for cryptographic silicon, with secondary packaging capacity in Vietnam and Mexico. Raw material dependencies draw from gallium arsenide substrates, tamper-responsive mesh materials, and quantum-resistant substrate formulations. Single-source vulnerability runs through TSMC's 5nm secure enclave production lines, where capacity allocation prioritizes smartphone and payment card clients. Distribution runs through tier-one systems integrators—Accenture, Deloitte, IBM Services—for enterprise deployment, with direct OEM relationships dominating government and defense channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced authentication markets exhibit defensive moat characteristics rooted in regulatory entrenchment. FIPS 140-3 and EU AI Act certification requirements create multi-year approval timelines that lock out unqualified competitors and cement incumbent positioning.
For Market Incumbents: Pre-empt platform consolidation by acquiring behavioral biometrics specialists before cloud-native entrants capture mid-market share. Thales Group and Microsoft should accelerate ISO/IEC 30107-3 certification pipelines for facial liveness detection to outpace NIST post-quantum migration deadlines. Vertical integration into edge compute infrastructure—specifically sub-100ms latency nodes for emerging market deployment—defends against SaaS-native challengers. For New Entrants and Emerging Players: Indonesian digital banking licensing creates immediate white-space opportunity, with central bank biometric onboarding mandates outpacing local vendor capacity. Target healthcare identity convergence in US hospital systems where FDA guidelines for clinical data access merge with enterprise authentication specifications. Go-to-market angle: continuous authentication protocols integrating keystroke dynamics with facial liveness detection for remote workforce zero-trust contracts. For Investors and Strategic Acquirers: The market sits at a standardization phase that favors platform-native providers with multi-year identity fabric contracts. Long-term viability across the analysis window favors vendors with FIDO2/WebAuthn protocol depth and sovereign-hosted deployment capability. Acquisition target archetype: pure-play behavioral biometrics SaaS with ISO/IEC 30107-3 certification and existing channel partnerships with system integrators. Signal to watch: RBI mandate expansion beyond UPI into insurance and securities authentication, which would compress procurement cycles for risk-based behavioral models.| Strategic Initiative | Industry Significance |
|---|---|
| FIDO2/WebAuthn Protocol Certification | Microsoft and Okta leverage Entra integration to anchor Fortune 500 passwordless migrations ahead of NIST deadlines. |
| ISO/IEC 30107-3 Liveness Detection Investment | Thales Group and NEC Corporation capture EU AI Act-mandated procurement in Frankfurt and Paris financial clusters. |
| Edge Compute Infrastructure Expansion | IBM and Dell Technologies deploy sub-100ms latency nodes for India's UPI real-time risk scoring requirements. |
| Healthcare Identity Convergence Partnership | Okta and RSA Security merge clinical authentication with enterprise fabrics under FDA healthcare data access guidelines. |
| Post-Quantum Cryptography Migration | Broadcom and Fujitsu refresh certificate-based infrastructure for defense and government clients per NIST algorithm finalization. |
Research Approach
The analysis maps biometric authentication, token-based systems, risk-based behavioral models, and certificate-based PKI credentialing, each validated through chief information security officers, identity platform engineers, financial services procurement leads, and healthcare IT directors. Primary interviews with these stakeholders combined with secondary validation from SEC 10-K filings, NIST cybersecurity framework updates, EU AI Act regulatory texts, and RBI circulars on digital payment authentication. Bottom-up deployment sizing across authentication technology segments triangulated against top-down enterprise IT security spending benchmarks.
Forecast assumptions held regulatory compliance timelines and NIST post-quantum cryptography standardization fixed, while varying cloud adoption rates and behavioral biometrics algorithmic improvement curves. The analytical framework models authentication technology, deployment mode, application sector, and end user organization type across the projection horizon. CAGRs derive from segment-level deployment trajectories weighted by procurement cycle length and compliance mandate effective dates. Industry-specific forecast inputs include UPI transaction volume elasticity and EU AI Act biometric surveillance restriction implementation pace.
Practitioners should monitor NIST post-quantum algorithm finalization dates and EU AI Act enforcement precedence for early signals of certificate infrastructure refresh demand. Forecasts reflect assumptions about sovereign data residency requirement proliferation and hardware security module foundry capacity allocation. Cross-checking against Gartner identity and access management spending benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Anti-Fraud Management System Market
Security Software
Global Data Loss Prevention Software Market
Security Software
Privacy Management Software Market
Security Software
Global Electronic Offender Monitoring Solutions Market
Security Software
VPN Software Market
Security Software
Network Camera Market
Security Software
Public Cloud Management and Security Services Market
Security Software
Automotive Over-the-Air Cybersecurity Hardening Test Equipment Market
Security Software
DC and PKI Market
Security Software
Wi-Fi Based Home Camera Market
Security Software
Global Digital Vehicle Forensics Market
Security Software
Security Testing Market
Security Software
Global Mobile Identification Market
Security Software
Phone Antivirus Software Market
Security Software
Private Virtual Communications for Police Network Market
Security Software
Privileged Access Management (PAM) Market