
 United States Lawful Interception Market | 2026-2036
United States Lawful Interception Market Size, Share, and Industry Trends Forecast 2026-2036
United States Lawful Interception Market Intelligence
The Communications Assistance for Law Enforcement Act (CALEA) is shifting compliance burdens onto cloud-native architectures and encrypted traffic handling. Verint Systems Inc. leverages decades of voice analytics heritage to sustain federal agency relationships. SS8 Networks Inc. specializes in real-time data intercept across 5G and IP multimedia subsystems. Utimaco GmbH anchors its position through hardware security module integration with lawful interception gateways.
Lawful interception encompasses the legally sanctioned acquisition of communications content and metadata by authorized agencies, typically requiring deep packet inspection capabilities that operate at line rates exceeding 100 Gbps while preserving chain-of-custody integrity. The technology segment splits between mature packet filtering deployments and rapidly expanding deep packet inspection demand driven by encrypted traffic proliferation. Service type dynamics favor managed services as agencies outsource complex 5G intercept architecture, while professional services retain margin pools in courtroom-ready evidence formatting. Deployment patterns show cloud-based solutions gaining traction among telecommunication providers seeking elastic scaling for sporadic warrant volumes.
The Federal Communications Commission (FCC) mandates technical standards for carrier compliance, while the Department of Justice (DOJ) and Federal Bureau of Investigation (FBI) shape procurement specifications through classified capability requirements. National Institute of Standards and Technology (NIST) guidelines increasingly influence encryption bypass methodologies and audit trail architectures. Stakeholders must weigh the accelerating technical arms race between privacy-preserving protocols and intercept capability investments.
Market Dynamics
The CALEA modernization mandate is forcing telecommunications carriers to rebuild intercept architectures around cloud-native packet cores, compressing vendor qualification timelines and fragmenting procurement authority between carrier engineering teams and federal security offices.
Growth Catalysts
- 5G Standalone Core Deployment:Carriers are installing lawful interception functions directly into cloud-native 5G cores, creating mandatory upgrade cycles for intercept gateway vendors.
- FBI Technical Collection Specifications:Classified capability requirements for real-time metadata correlation are expanding federal agency procurement budgets for deep packet inspection platforms.
- Encrypted Traffic Volume Surge:Proliferation of end-to-end encryption protocols is driving demand for lawful access solutions that operate at line rates exceeding 100 Gbps without traffic degradation.
Market Restraints
- Semiconductor Supply Concentration:Specialized packet processing ASICs rely on Taiwan-based foundry capacity, creating lead time volatility for high-throughput intercept hardware.
- NIST Post-Quantum Cryptography Timeline:Uncertainty around federal encryption standards is freezing long-term architecture investments among risk-averse carrier procurement teams.
- Qualified Security Personnel Scarcity:Deep expertise in both telecommunications signaling protocols and federal security clearance requirements concentrates in Northern Virginia and San Diego metro areas.
Strategic Opportunities
- Managed Security Service Provider Channel:Regional carriers are outsourcing intercept compliance to specialized MSSPs, opening distribution partnerships outside traditional direct vendor relationships.
- State Fusion Center Expansion:California, Texas, and Virginia are funding local law enforcement intercept capabilities, creating procurement opportunities below federal contract thresholds.
- Artificial Intelligence-Assisted Traffic Classification:Machine learning models trained on encrypted traffic patterns are converging with hardware acceleration to enable faster warrant execution.
Industry Challenges
- Chain-of-Custody Documentation Automation:Federal courts are rejecting evidence where automated logging gaps create authentication vulnerabilities, forcing vendors to rebuild audit trail architectures.
- Legacy TDM Circuit Integration:Hybrid networks requiring simultaneous intercept across packet-switched 5G cores and remaining time-division multiplexing infrastructure are extending deployment timelines.
- Cross-Agency Coordination Friction:DEA, FBI, and DHS maintain incompatible technical standards for intercept data formats, multiplying integration costs for multi-agency jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Lawful Interception Market |
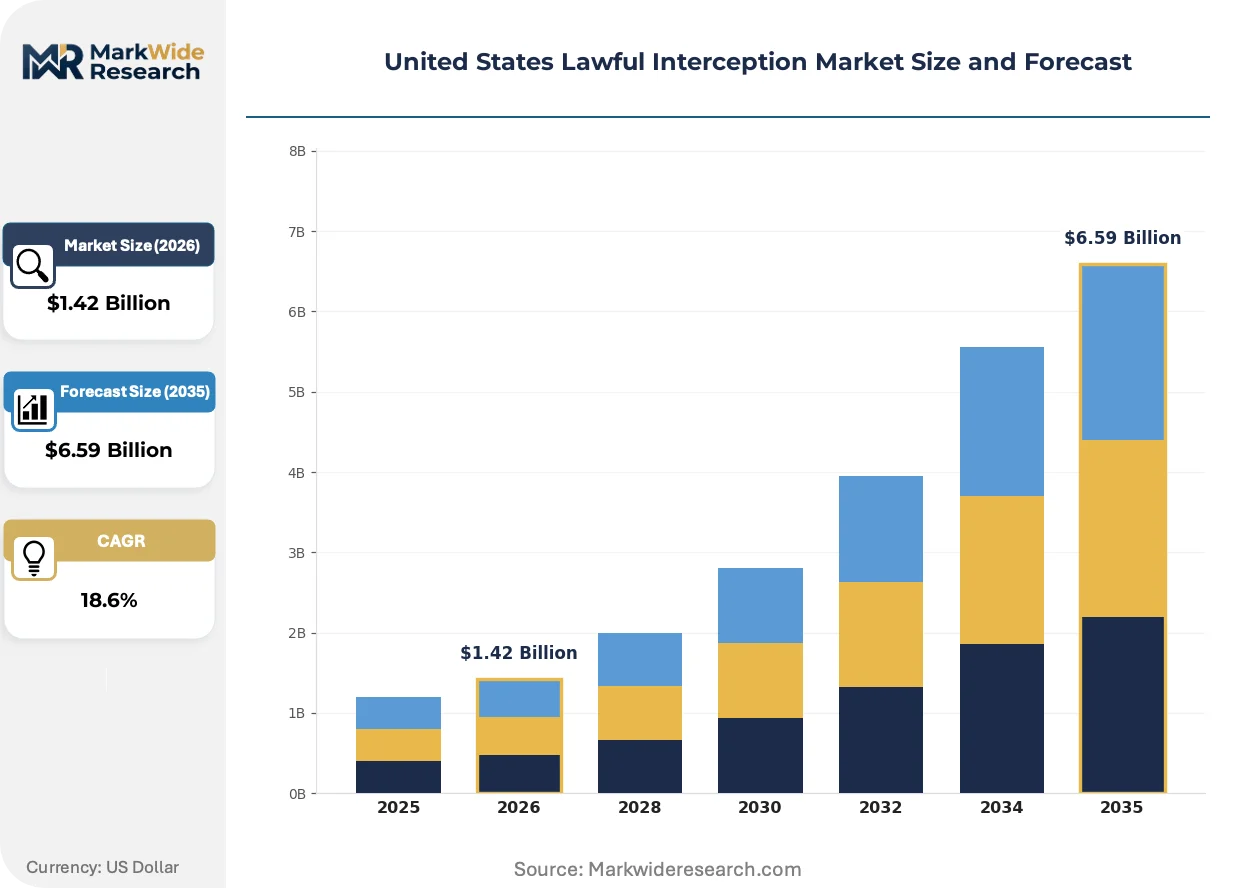
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $6.59 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Packet Filtering, Deep Packet Inspection, Lawful Interception Gateways, Monitoring Centers Service Type: Managed Services, Professional Services, Software Solutions, Compliance Solutions End User: Telecommunication Providers, Law Enforcement Agencies, Government Bodies, ISPs Deployment: Cloud-based, On-premises, Hybrid, Edge Computing |
| Companies Covered | Vocal Technologies Ltd., Utimaco GmbH, Verint Systems Inc., NICE Ltd., Cisco Systems Inc., SS8 Networks Inc., BAE Systems plc, NetScout Systems Inc., AQSACOM Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Lawful Interception Market Strategic Shifts & Innovations
Deep packet inspection hardware is absorbing artificial intelligence acceleration while federal procurement specifications harden around quantum-resistant encryption bypass capabilities, compressing vendor development cycles.
Deep packet inspection platforms are integrating neural network inference engines directly into line-rate processing pipelines. Federal agencies are deploying these systems for encrypted traffic metadata extraction without full decryption. This convergence is integrating machine learning capabilities into hardware that previously relied solely on signature-based pattern matching, compressing the performance gap between classified and commercial intercept technologies.
The FCC's 2023 CALEA compliance guidance is mandating carrier-provided intercept access points for cloud-native voice over IP services. This regulatory pressure is forcing traditional lawful interception vendors to rebuild software architectures around containerized deployment models. Smaller regional carriers in the Midwest and Southeast are responding fastest, lacking legacy infrastructure entanglements that slow Tier-1 carrier transitions.
Agency buyers are consolidating intercept procurement under enterprise-wide indefinite delivery contracts, displacing project-specific purchasing. This behavioral shift is compressing vendor sales cycles while elevating importance of past performance ratings in federal procurement databases. The pattern is most visible in Department of Homeland Security component agencies, where standardized technical specifications are reducing vendor qualification overhead.
United States Lawful Interception Market Segmentation
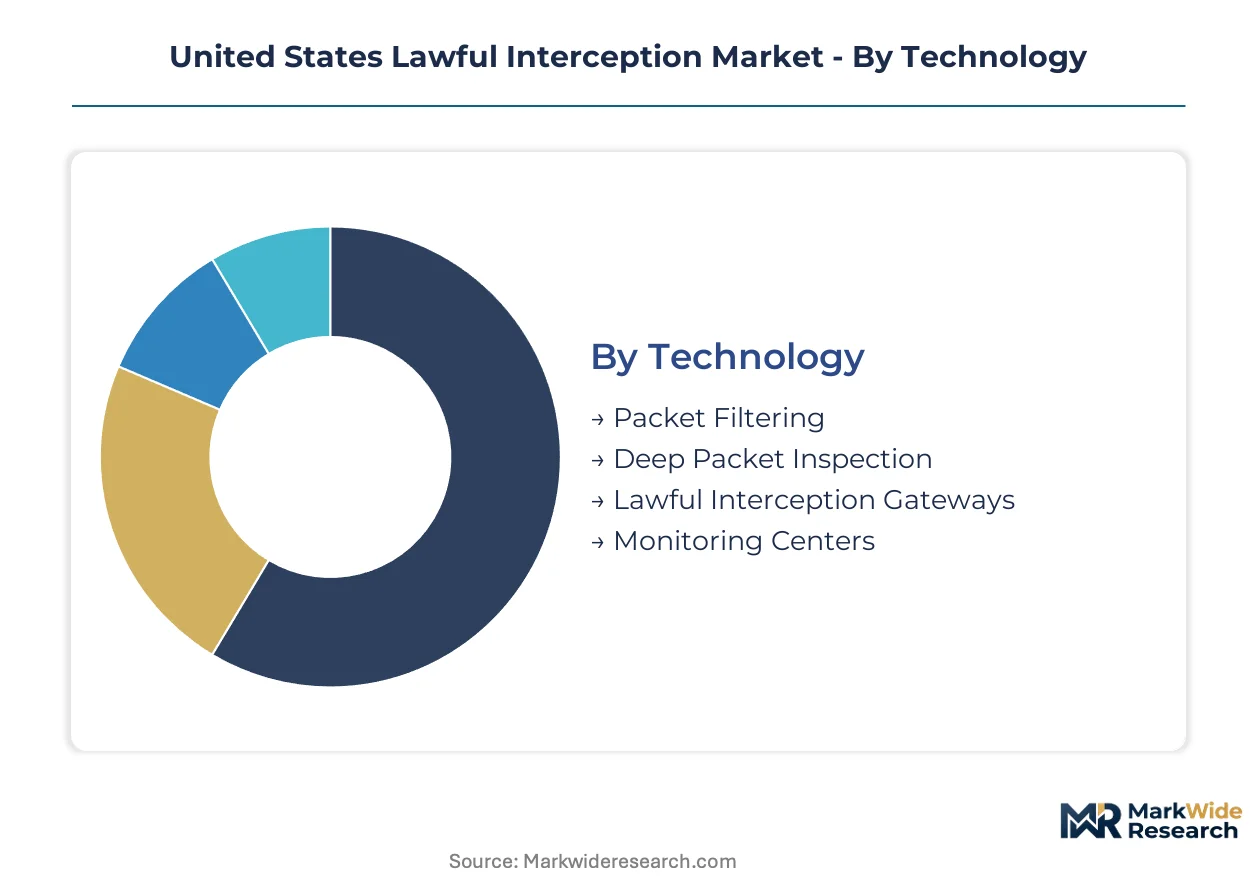
Segmentation in the United States lawful interception market reveals how procurement authority fragments between carrier engineering teams and federal security offices. Buyers prioritize line-rate performance, chain-of-custody integrity, and CALEA compliance architecture differently across technology, service, and deployment dimensions.
Technology:
Carrier engineering teams evaluate throughput scalability and encrypted traffic handling as primary selection criteria.
- Deep Packet Inspection:Neural network inference engines now integrate directly into line-rate processing pipelines for encrypted traffic metadata extraction. FBI technical collection specifications are expanding federal procurement budgets for these platforms as agencies deploy them without full decryption. Demand concentrates in Virginia and California where intelligence community facilities cluster.
- Lawful Interception Gateways:Hardware security module integration anchors vendor positioning for these cloud-native packet core interfaces. NIST guidelines increasingly influence encryption bypass methodologies built into gateway architectures. Texas carrier switching centers are driving deployment volume.
- Packet Filtering:Mature signature-based deployments handle unencrypted legacy traffic at lower cost tiers.
- Monitoring Centers:Centralized evidence formatting and courtroom-ready audit trail generation serve multi-agency coordination requirements.
Volume sits with Lawful Interception Gateways; growth tilts toward Deep Packet Inspection.
Service Type:
Budget authority splits between capital-constrained regional carriers and federal agencies with classified capability mandates.
- Managed Services:Regional carriers in the Midwest and Southeast are outsourcing intercept compliance to specialized MSSPs, opening distribution partnerships outside traditional direct vendor relationships. Elastic scaling for sporadic warrant volumes drives this preference among cloud-native architecture adopters.
- Professional Services:Courtroom-ready evidence formatting and chain-of-custody documentation automation retain margin pools. Federal courts are rejecting evidence where automated logging gaps create authentication vulnerabilities, forcing vendor investment in audit trail architectures.
- Software Solutions:Containerized deployment models respond to FCC CALEA compliance guidance for cloud-native voice over IP services.
- Compliance Solutions:CALEA modernization mandates compress vendor qualification timelines for carrier procurement teams.
Professional Services commands the largest contract values; Managed Services climbs the fastest as regional carriers outsource complexity.
End User:
Technical standards fragmentation between DEA, FBI, and DHS multiplies integration costs for multi-agency jurisdictions.
- Telecommunication Providers:Tier-1 carriers face legacy infrastructure entanglements slowing cloud-native transitions, while regional carriers respond faster. FCC mandates force rebuilds of intercept architectures around containerized deployment models.
- Law Enforcement Agencies:State fusion centers in California, Texas, and Virginia are funding local capabilities below federal contract thresholds. Real-time metadata correlation requirements expand procurement budgets.
- Government Bodies:Department of Homeland Security component agencies are consolidating intercept procurement under enterprise-wide indefinite delivery contracts.
- ISPs:Smaller internet service providers lack internal security clearance expertise, creating dependency on vendor-managed solutions.
Telecommunication Providers anchor current installations; Law Enforcement Agencies show the steepest expansion trajectory as state fusion centers multiply.
Deployment:
Supply concentration in specialized packet processing ASICs creates lead time volatility that shapes architecture decisions.
- Cloud-based:Containerized deployment models gain traction among telecommunication providers seeking elastic scaling for sporadic warrant volumes. FCC guidance is mandating carrier-provided intercept access points for cloud-native voice over IP services.
- Hybrid:Simultaneous intercept across packet-switched 5G cores and remaining TDM infrastructure extends deployment timelines. Legacy circuit integration requirements favor this architecture for Tier-1 carriers.
- On-premises:Classified facility requirements and air-gapped security protocols sustain demand in intelligence community installations.
- Edge Computing:Low-latency warrant execution for 5G standalone core deployments drives pilot programs at carrier switching centers.
Hybrid deployments dominate current carrier infrastructure; Cloud-based solutions gain share fastest as regional carriers skip legacy entanglements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
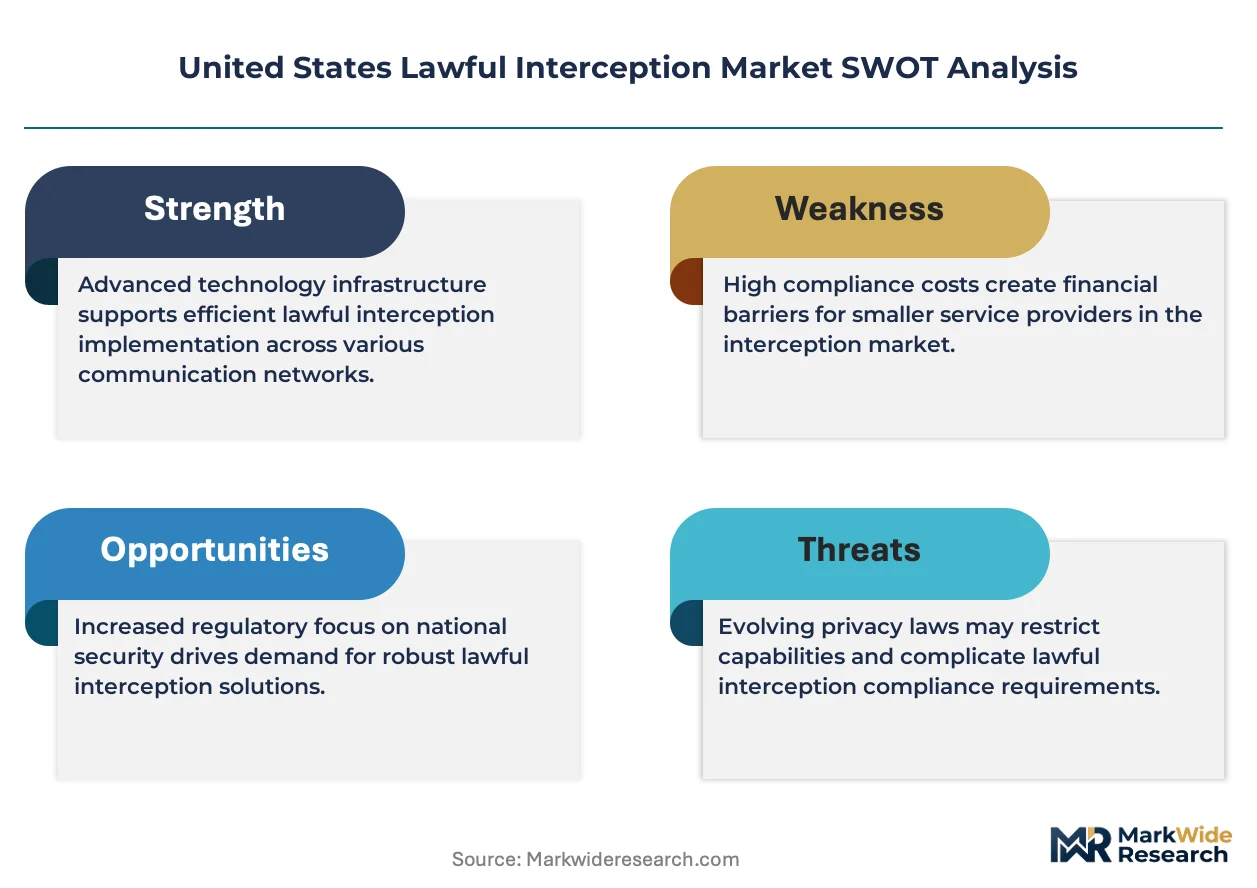
Federal procurement hubs and carrier switching centers concentrate demand in tax-advantaged zones across Virginia, California, and Texas. State fusion center funding is expanding local law enforcement capabilities below federal contract thresholds.
Virginia
Northern Virginia hosts the intelligence community's classified intercept facilities and FBI technical collection operations. NIST guidelines originating from Gaithersburg influence encryption bypass methodologies adopted by vendors serving federal agencies. The Dulles technology corridor concentrates cleared personnel with dual expertise in telecommunications signaling and security protocols.
California
Silicon Valley cloud providers and Los Angeles carrier switching centers drive cloud-native intercept architecture demand. FCC CALEA compliance mandates force containerized deployment models for voice over IP services. San Diego's defense contractor ecosystem supplies deep packet inspection hardware to federal agencies.
Texas
Dallas-Fort Worth carrier switching centers anchor lawful interception gateway deployments for regional telecommunications providers. State-funded fusion centers in Houston and Austin are procuring real-time metadata correlation capabilities below federal contract thresholds. The Texas National Guard's cyber operations unit influences technical specifications for state-level intercept platforms.
Florida
Miami's international telecommunications landing points create intercept requirements for cross-border traffic monitoring. State law enforcement agencies are consolidating procurement under enterprise-wide contracts modeled on DHS standardized specifications. Tampa's cybersecurity training programs are addressing qualified security personnel scarcity affecting regional carrier compliance teams.
Illinois
Chicago's financial sector data centers are driving demand for encrypted traffic handling at line rates exceeding 100 Gbps. The Illinois State Police fusion center coordinates intercept capabilities across Midwestern jurisdictions with incompatible federal agency technical standards. Regional carriers in the state are outsourcing compliance to managed security service providers.
United States Lawful Interception Market Key Industry Players
Israeli and American producers anchor one tier; German specialists hold differentiated positions in hardware security modules. The vendor base clusters around three strategic archetypes: voice analytics heritage players, real-time data intercept specialists, and telecommunications equipment incumbents with integrated lawful interception portfolios. Competitive moves center on CALEA modernization qualification timelines and cloud-native architecture certifications.
Within the federal agency tier, Verint Systems Inc. and SS8 Networks Inc. exemplify contrasting specialization models. Verint occupies a position anchored in decades of voice analytics heritage sustaining relationships with classified procurement offices. SS8 represents the real-time intercept specialist archetype with focus on 5G and IP multimedia subsystem deployments. Utimaco GmbH anchors the hardware security module integration segment serving gateway architectures. BAE Systems plc sits within the defense contractor tier leveraging cleared facility access for intelligence community installations.
| Leading Market Players |
|---|
| Vocal Technologies Ltd. |
| Utimaco GmbH |
| Verint Systems Inc. |
| NICE Ltd. |
| Cisco Systems Inc. |
| SS8 Networks Inc. |
| BAE Systems plc |
| NetScout Systems Inc. |
| AQSACOM Inc. |
| Others |
Cost & Logistics Intelligence
Specialized packet processing ASICs manufactured through Taiwan-based foundry capacity cascade through three pricing tiers before reaching carrier procurement teams. Long lead times for high-throughput intercept hardware compress margins at the gateway integration stage while federal security clearance requirements inflate labor costs for installation services.
Pricing Analysis
Premium pricing attaches to short lead-time delivery of deep packet inspection platforms certified for FBI technical collection specifications. Three-tier pricing structure across premium, standard, and economy levels separates classified-capability systems from carrier-grade gateways and legacy packet filtering deployments. Price differentiation hinges on NIST compliance tier and encrypted traffic throughput rating. Pricing pressure stems from semiconductor supply concentration as carriers absorb foundry margin expansion. Regional carriers in the Midwest exhibit highest price sensitivity; intelligence community facilities show least sensitivity due to classified mandate requirements.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan for advanced ASIC fabrication and with South Korea for high-bandwidth memory modules feeding neural network inference engines. Raw material dependencies span silicon wafers, specialized photonics components, and hardware security modules sourced from Germany. Supply chain risk centers on tariff exposure for telecommunications equipment imports under shifting trade policy. Distribution runs through direct vendor relationships with Tier-1 carriers and emerging MSSP channels for regional providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry capacity constraints for specialized intercept silicon prop pricing power upstream, constraining downstream vendor margin expansion across the analysis window.
For Market Incumbents: Deepen hardware security module integration partnerships with Utimaco GmbH and similar specialists to lock in encryption bypass capability roadmaps. Expand cleared facility presence in Northern Virginia beyond current Dulles corridor concentration to capture scarce personnel pools. Counter emerging cloud-native entrants by accelerating CALEA modernization qualification timelines. For New Entrants and Emerging Players: Enter via managed security service provider partnerships serving regional carriers in the Southeast lacking internal intercept architecture expertise. Target state fusion center procurement in Texas and California where funding flows below federal contract thresholds demand standardized but affordable platforms. Lead with containerized deployment models that bypass legacy TDM integration burdens slowing Tier-1 carrier transitions. For Investors and Strategic Acquirers: FBI technical collection specification revisions are the leading indicator that federal procurement budgets for deep packet inspection platforms are expanding. Five-to-ten year viability favors vendors with dual capability in voice analytics heritage and real-time 5G intercept. Acquisition target archetype: mid-cap specialists with NIST-influenced encryption bypass methodologies and existing carrier gateway certifications.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Architecture Certification | FCC CALEA compliance guidance mandates containerized deployment models for VoIP intercept. |
| AI-Assisted Traffic Classification Partnership | Machine learning convergence with hardware acceleration compresses warrant execution timelines. |
| State Fusion Center Distribution Agreement | California, Texas, and Virginia funding expands procurement below federal contract thresholds. |
| Hardware Security Module Integration | NIST guidelines increasingly influence encryption bypass methodologies in gateway architectures. |
| Cleared Personnel Pipeline Investment | Dual expertise in telecommunications signaling and security protocols concentrates in Northern Virginia. |
Research Approach
SEC filings, FCC enforcement records, and federal procurement databases formed the secondary backbone of data collection. Primary interviews with carrier network engineering directors, federal security clearance officers, lawful interception vendor product managers, and state fusion center procurement leads validated demand-side assumptions. Bottom-up and top-down triangulation cross-checked vendor shipment estimates against carrier infrastructure deployment timelines and agency budget authorization patterns.
Bottom-up modeling aggregated individual carrier intercept gateway deployments and federal agency deep packet inspection procurements across technology, service, and deployment segmentation dimensions. Top-down analysis calibrated aggregate market expansion against telecommunications infrastructure investment cycles and classified budget trend indicators. CAGRs derived from weighted scenario analysis incorporating 5G standalone core deployment velocity and CALEA modernization mandate compliance deadlines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NIST post-quantum cryptography timeline acceleration or sustained semiconductor supply disruption. Forecasts reflect assumptions about carrier cloud-native transition pacing and federal technical collection specification stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Application Control Software Market
Security Software
Video Intercom Devices Market
Security Software
Global User Provisioning Market
Security Software
Secure Web Gateway Market
Security Software
Mobile Data Protection Solutions and Services Market
Security Software
Door Phone Market
Security Software
Anomaly Detection Tools Market
Security Software
Security Information and Event Management Software Market
Security Software
Global Secure Mobile Communications Software Market
Security Software
Security Testing Market
Security Software
Battery-Powered Doorbell Camera Market
Security Software
Online Background Check Market
Security Software
Mobile Antivirus Software Market
Security Software
Private Virtual Communications for Police Network Market
Security Software
Parental Monitoring Software Market
Security Software
Security Software Market