
 Vsaas Market | 2026-2036
Vsaas Market Size, Share, and Industry Trends Forecast 2026-2036
Vsaas Market Outlook
The EU AI Act is broadening compliance obligations for biometric identification systems, forcing Vsaas providers to redesign analytics pipelines around explainable AI thresholds. Axis Communications AB leverages its Nordic engineering heritage to sustain leadership in edge-computing camera architectures. Johnson Controls International plc anchors its position through deep building-automation integration, while Genetec Inc. differentiates via open-platform cybersecurity certifications for critical infrastructure deployments.
Video Surveillance as a Service delivers remotely managed video capture, storage, and analytics through cloud or hybrid architectures, typically encoding H.265 streams at 1080p to 4K resolution for real-time threat detection and forensic retrieval. Public cloud deployments dominate mid-market adoption due to elastic capacity and zero capital expenditure, though hybrid cloud configurations are capturing regulated enterprises requiring local retention with centralized management. AI analytics represents the fastest-expanding service type, with video analytics and access control converging into unified physical security platforms.
The US FCC governs spectrum allocation for wireless camera backhaul, while the EU GDPR and AI Act jointly constrain facial recognition deployments and mandate algorithmic transparency in public spaces. India's TRAI cloud-service frameworks and BIS cybersecurity standards are shaping how foreign Vsaas vendors structure data residency and encryption protocols. Stakeholders must monitor whether emerging national AI safety institutes will extend licensing requirements to behavior-recognition algorithms in commercial surveillance.
Market Dynamics
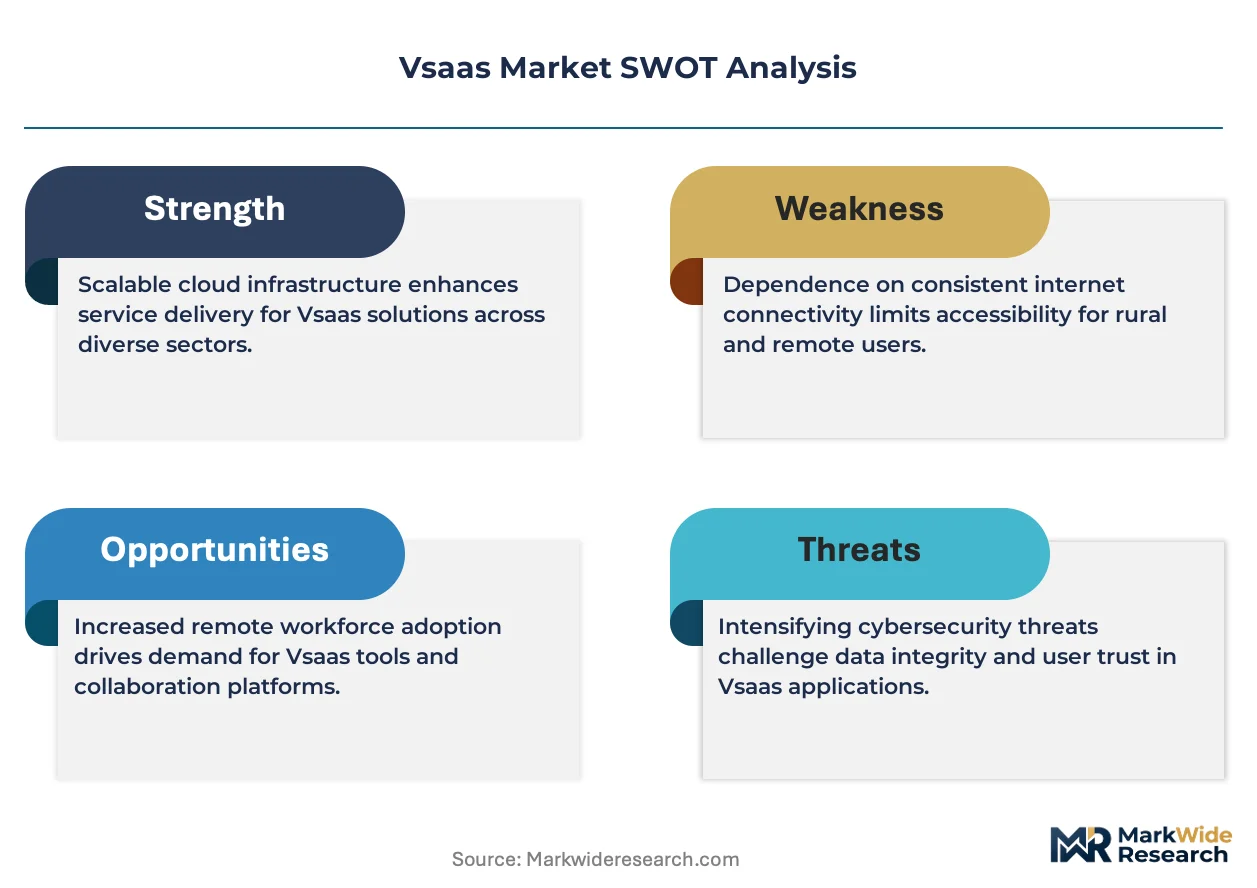
The Vsaas market is undergoing a fundamental restructuring as cloud-native architectures displace on-premise NVR systems, with enterprise buyers prioritizing subscription-based operational expenditure over capital-intensive infrastructure ownership. This shift is compressing traditional hardware margins while elevating software and analytics monetization.
Growth Catalysts
- EU AI Act compliance mandates:High-risk classification of biometric analytics is forcing facility operators toward certified Vsaas platforms that embed algorithmic transparency and audit trails by design.
- Industrial IoT convergence:Factory automation in Germany's Ruhr corridor is integrating video analytics with predictive maintenance systems, creating unified physical-digital security architectures.
- Elastic cloud capacity:Mid-market commercial real estate operators across North America are abandoning fixed storage arrays for consumption-based models that scale with occupancy fluctuations.
Market Restraints
- Bandwidth infrastructure gaps:Rural and secondary urban markets lack symmetric fiber backhaul sufficient for 4K H.265 stream aggregation, limiting addressable geography.
- Semiconductor supply concentration:Edge AI chip fabrication concentrates in Taiwan and South Korea, exposing camera OEMs to geopolitical disruption and allocation rationing.
- GDPR data-residency friction:Cross-border video storage triggers Article 44 transfer mechanism complexity, lengthening enterprise sales cycles and legal review.
Strategic Opportunities
- India's smart city mandates:Municipal surveillance tenders under the Ministry of Housing and Urban Affairs are specifying cloud-native architectures with BIS-certified encryption, opening public-sector verticals.
- Behavioral analytics white space:Retail loss-prevention and warehouse safety applications remain underpenetrated for AI-driven anomaly detection beyond perimeter security.
- 5G private network integration:Ultra-reliable low-latency communication is enabling wireless camera deployments in mining, ports, and energy infrastructure previously unreachable by fiber.
Industry Challenges
- Edge-AI firmware engineering scarcity:The intersection of embedded systems, computer vision, and cybersecurity expertise remains concentrated among a narrow talent pool, inflating R&D compensation.
- Legacy analog migration complexity:Brownfield installations with coaxial infrastructure require hybrid encoder bridges that degrade analytics performance and expand integration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vsaas Market |
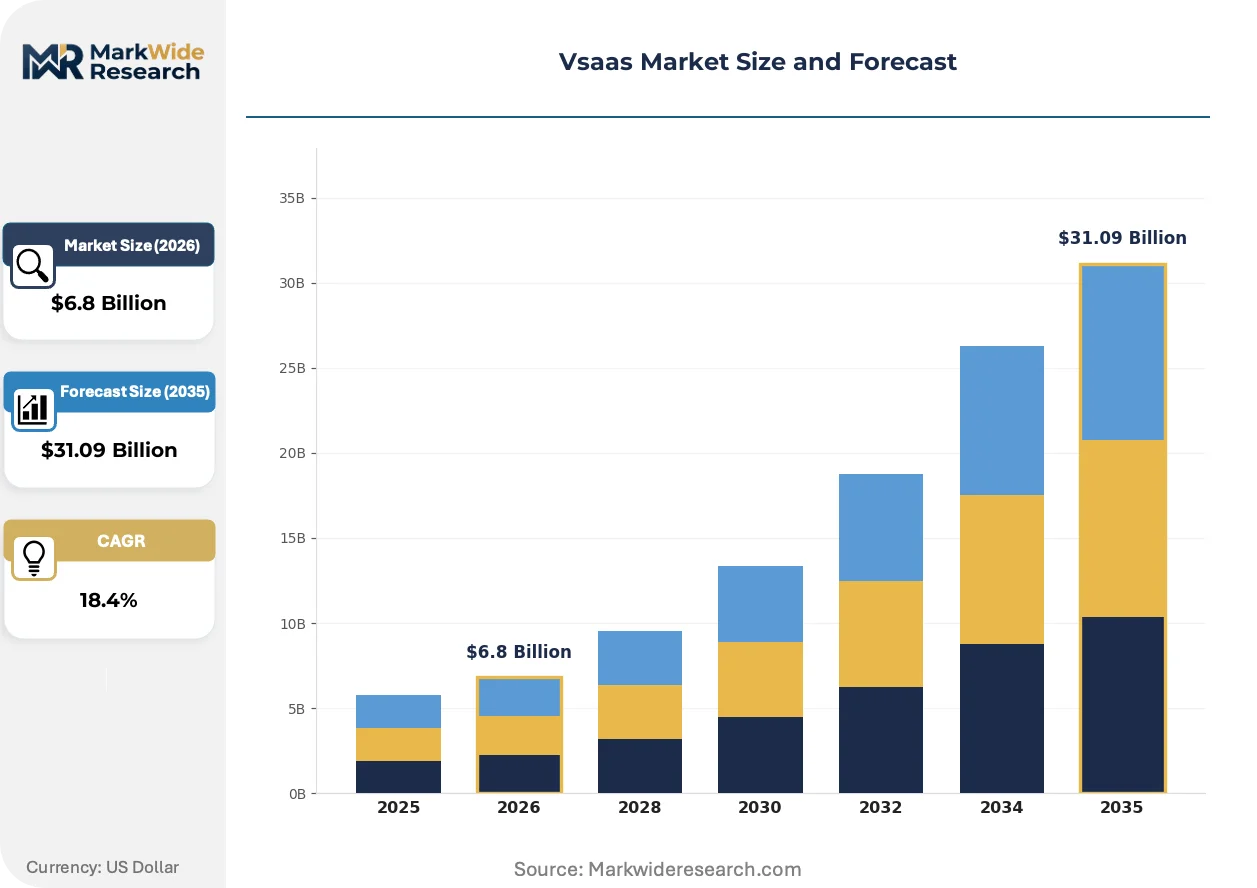
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Residential Users, Small Businesses, Enterprises, Government Agencies Service Type: Monitoring Services, Video Analytics, Storage Solutions, Access Control Technology: IP Cameras, Cloud Storage, Mobile Apps, AI Analytics |
| Companies Covered | ADT Inc., Johnson Controls International plc, Axis Communications AB, Honeywell International Inc., Motorola Solutions, Inc., Robert Bosch GmbH, Alarm.com, Genetec Inc., Eagle Eye Networks Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vsaas Market Strategic Shifts
Edge-computing camera architectures are redefining where intelligence resides in the video pipeline, shifting processing from centralized servers to device-level inference engines. This topological inversion is compressing latency, reducing backhaul costs, and enabling offline operation during connectivity outages.
Neural processing units embedded directly into camera SoCs are electrifying real-time threat detection capabilities. Large logistics operators in the United States are deploying these devices at warehouse perimeters to identify PPE violations and unauthorized zone intrusions without cloud round-trips. The architecture is compressing response times from seconds to milliseconds while reducing recurring bandwidth expenditure.
The EU AI Act's algorithmic transparency requirements are mandating explainable decision trails for biometric identification systems. Vsaas providers must now document training data provenance, model performance metrics, and human oversight protocols to achieve CE marking for high-risk applications. Critical infrastructure deployments in France and Germany are prioritizing vendors with pre-certified compliance documentation, creating procurement preference segmentation.
Subscription-based consumption models are displacing perpetual licensing in enterprise procurement. Facility management firms are unbundling hardware acquisition from software and analytics services, treating video infrastructure as an operational utility rather than capital asset. This pattern is most pronounced in United Kingdom commercial real estate, where REITs favor opex-aligned contracts that synchronize surveillance spending with lease revenue cycles.
Vsaas Market Segmentation
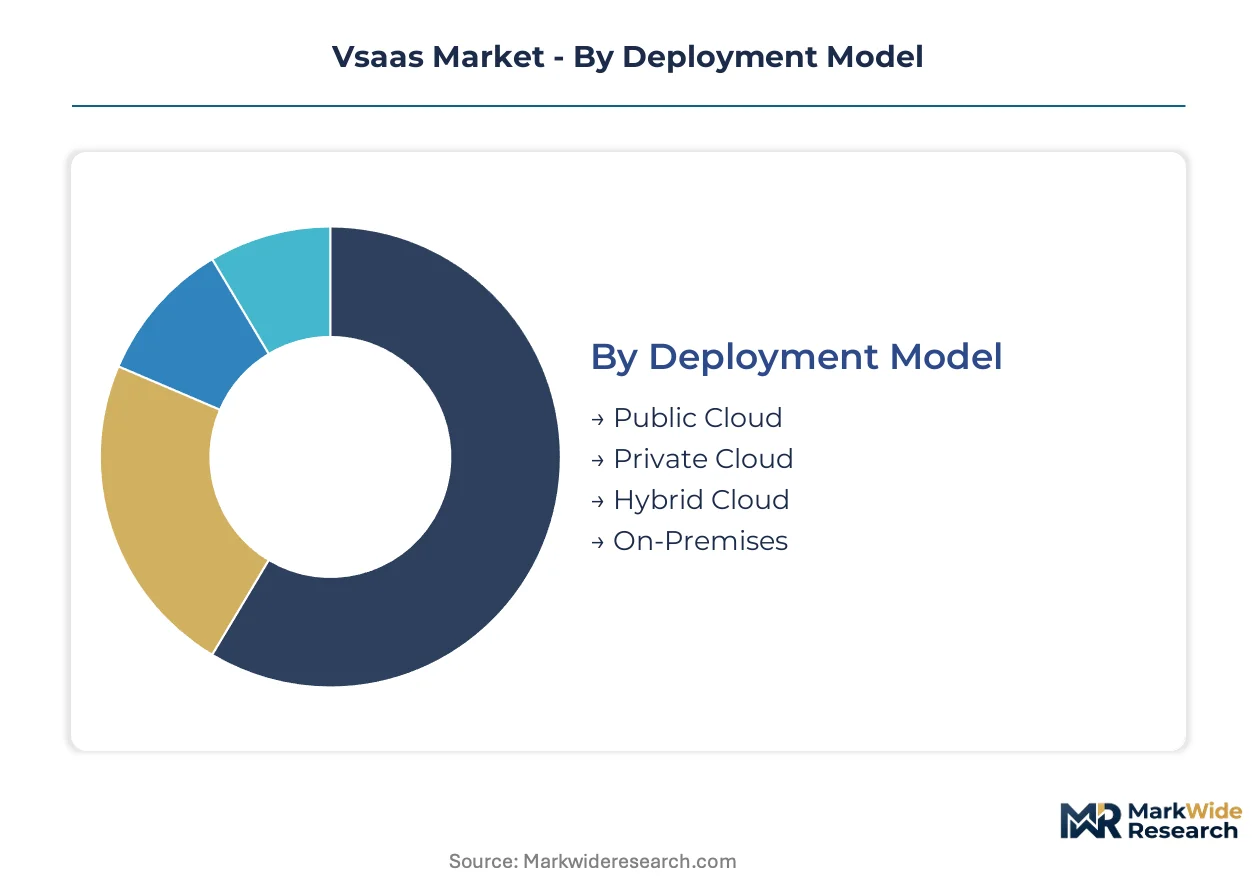
Vsaas architectures fragment across deployment sovereignty levels and intelligence depth, with procurement patterns diverging sharply between capital-constrained residential adopters and compliance-bound institutional buyers. Segment boundaries blur as edge-AI capabilities migrate downward from enterprise tiers and subscription economics reshape ownership models across every vertical.
Deployment Model:
Standardization dominates at the infrastructure layer while customization intensifies at the policy and data-residency layers, creating a paradox where identical hardware serves radically different governance requirements.
- Public Cloud:Multi-tenant architectures deliver elastic H.265 stream processing through hyperscale data centers, eliminating local server footprint. Demand concentrates among United States mid-market commercial real estate operators prioritizing zero-capex onboarding and consumption-aligned billing cycles.
- Private Cloud:Single-tenant dedicated infrastructure isolates video repositories within sovereign boundaries, mandatory for France's critical infrastructure operators under CNIL guidelines and Germany's industrial firms navigating GDPR Article 44 transfer restrictions.
- Hybrid Cloud:Tiered architectures retain high-resolution archival locally while pushing metadata and alerts to centralized dashboards, bridging bandwidth constraints in India's tier-2 smart city deployments where fiber backhaul remains uneven.
- On-Premises:Legacy NVR-centric configurations persist where air-gapped security mandates override cloud economics, notably within United States defense contractors and certain European nuclear facilities.
Leading the category by volume: Public Cloud. Growing fastest: Hybrid Cloud.
End User:
Customer sophistication cascades from institutional procurement teams with dedicated security operations centers to residential buyers selecting from app store interfaces, with service bundling and pricing granularity scaling inversely.
- Enterprises:Multi-site facility operators demand API-first platforms integrating video with building automation, identity management, and occupancy analytics. United States logistics campuses and Germany's automotive manufacturing complexes drive specification complexity around edge-AI inference and SOC-2 compliance documentation.
- Government Agencies:Municipal and federal buyers mandate certified encryption, domestic data residency, and algorithmic transparency under procurement frameworks like India's BIS standards or the EU AI Act's high-risk system registry.
- Small Businesses:Retail proprietors and professional service firms prioritize smartphone-managed systems with straightforward per-camera pricing, often bundling video with point-of-sale or access control through vertical SaaS partnerships.
- Residential Users:Homeowners select from mass-market doorbell cameras and standalone WiFi devices, with subscription attachment rates determining vendor profitability in this price-sensitive tier.
Commanding premium pricing: Enterprises. Expanding most quickly: Small Businesses.
Service Type:
Margin structures invert from commodity storage toward predictive intelligence, with vendors racing to embed differentiated analytics before infrastructure-layer pricing collapses toward utility levels.
- Video Analytics:Real-time inference engines detect perimeter breaches, PPE violations, and behavioral anomalies through neural processing units at the edge or cloud. United States warehouse operators and Germany's factory automation corridors deploy these capabilities for predictive safety intervention.
- Access Control:Unified physical identity platforms converge video verification with credential management, biometric enrollment, and audit logging. Demand clusters among United Kingdom financial services firms consolidating vendor relationships under single-pane governance.
- Monitoring Services:Human-in-the-loop alarm verification and dispatch coordination provide liability insulation for small business and residential segments lacking internal security operations capacity.
- Storage Solutions:Tiered retention policies balancing immediate accessibility against archival cost optimization, with regulatory minimums varying by jurisdiction and incident type.
Highest attach rate: Video Analytics. Steepest expansion trajectory: Access Control.
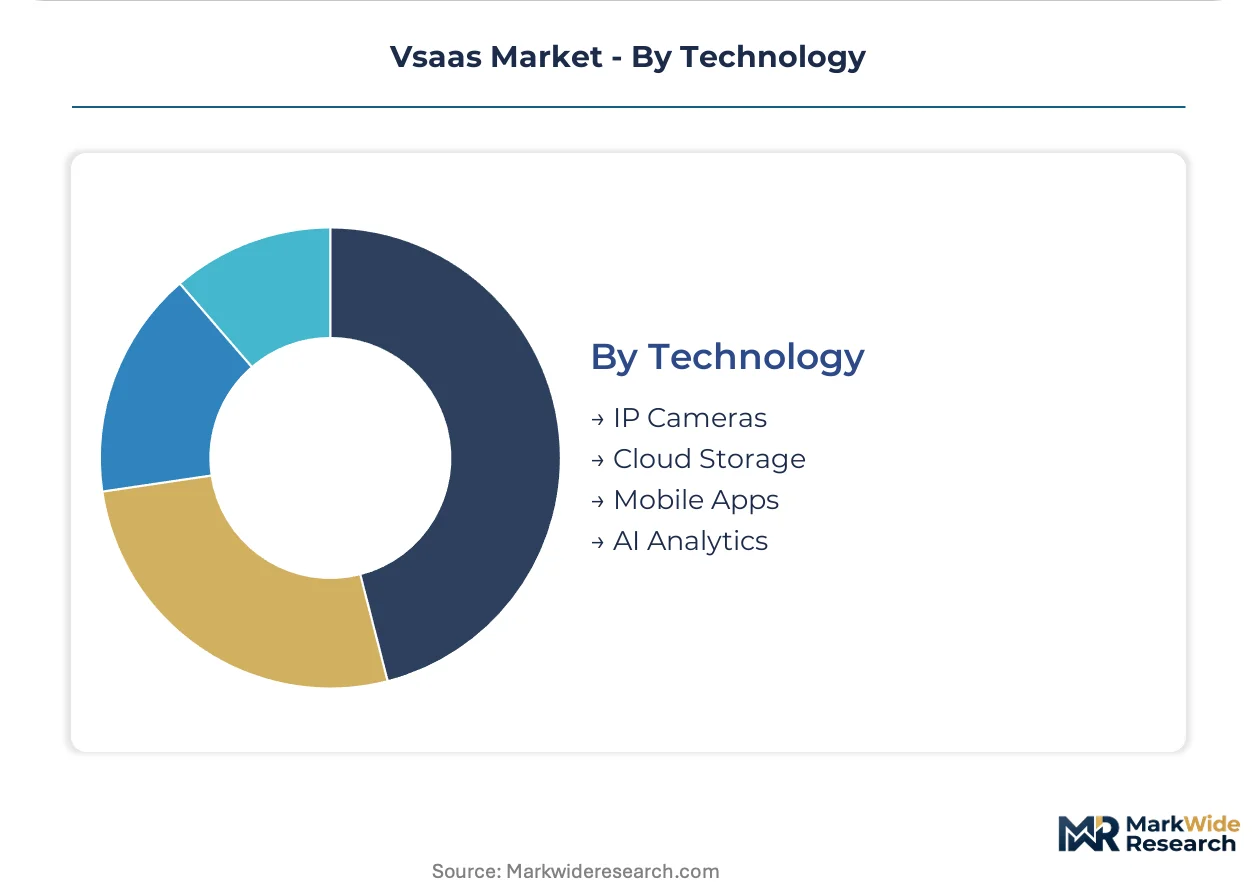
Technology:
Component commoditization accelerates at the camera layer while proprietary differentiation concentrates in software-defined analytics and seamless mobile experience orchestration.
- AI Analytics:Computer vision pipelines for object classification, facial recognition, and anomaly detection require continuous model retraining and edge-cloud orchestration. United States logistics operators and India's emerging smart city deployments represent primary demand centers.
- IP Cameras:H.265-encoded 4K sensors with embedded neural processing units deliver on-device inference, reducing backhaul costs and enabling offline operation during connectivity interruptions.
- Cloud Storage:Object-tiered repositories with automated lifecycle policies manage petabyte-scale video archives across hot, warm, and cold access patterns.
- Mobile Apps:Native iOS and Android interfaces for live viewing, playback scrubbing, and alert acknowledgment serve as the primary touchpoint for residential and small business segments.
Capturing R&D investment concentration: AI Analytics. Gaining share fastest: IP Cameras.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr industrial corridor anchors European Vsaas demand, where factory automation converges video analytics with predictive maintenance systems. Facility operators across the corridor prioritize edge-AI inference engines that integrate with IoT platforms for unified physical-digital security architectures.
United States
Logistics campuses in Illinois and Michigan drive specification complexity around SOC-2 compliance documentation and API-first platform integration. The FCC governs spectrum allocation for wireless camera backhaul while enterprise buyers prioritize subscription-based operational expenditure over capital-intensive infrastructure ownership. Mid-market commercial real estate operators in Texas and Florida favor consumption-based models that scale with occupancy fluctuations.
Germany
Automotive manufacturing complexes in Bavaria and Baden-Württemberg demand edge-AI inference capabilities embedded directly into camera SoCs. The EU AI Act and GDPR jointly constrain facial recognition deployments while mandating algorithmic transparency in public spaces. Factory automation in the Ruhr corridor integrates video-as-a-service with predictive maintenance systems for unified security architectures.
India
Municipal surveillance tenders under the Ministry of Housing and Urban Affairs specify cloud-native architectures with BIS-certified encryption for smart city deployments. The TRAI cloud-service frameworks shape how foreign vendors structure data residency and encryption protocols. Tier-2 urban centers in Maharashtra and Karnataka deploy hybrid cloud configurations bridging uneven fiber backhaul with centralized management dashboards.
United Kingdom
REITs favor opex-aligned contracts that synchronize surveillance spending with lease revenue cycles across London and Southeast commercial portfolios. Financial services firms consolidate vendor relationships under single-pane governance for unified physical identity platforms. The UK Information Commissioner's Office enforces GDPR-aligned video retention policies that lengthen enterprise sales cycles and legal review.
France
Critical infrastructure operators under CNIL guidelines mandate single-tenant dedicated infrastructure isolating video repositories within sovereign boundaries. The EU AI Act's high-risk system registry requires pre-certified compliance documentation for biometric identification deployments. Nuclear facilities and defense contractors in Provence-Alpes-Côte d'Azur maintain air-gapped security mandates that override cloud economics.
Vsaas Market Competitive Environment
The competitive structure tilts toward integrated building-automation specialists with deep cybersecurity certifications. Market concentration remains moderate, with diversified industrial conglomerates competing against pure-play video analytics specialists. Two strategic archetypes dominate: Nordic engineering heritage firms emphasizing edge-computing camera architectures, and North American platform vendors prioritizing open-architecture cybersecurity for critical infrastructure. Dominant competitive moves include strategic partnerships for 5G private network integration and portfolio diversification into behavioral analytics for retail and warehouse safety applications.
Within the integrated building-automation tier, Johnson Controls International plc and Honeywell International plc exemplify diversified industrial conglomerates that anchor market position through deep facility management integration. Among pure-play video platform specialists, Genetec Inc. occupies a position emphasizing open-platform cybersecurity certifications, while Axis Communications AB represents Nordic engineering heritage in edge-computing camera architectures. Alarm.com and Eagle Eye Networks Inc. sit within the cloud-native subscription tier, targeting mid-market commercial real estate with consumption-based operational models.
| Leading Market Players |
|---|
| ADT Inc. |
| Johnson Controls International plc |
| Axis Communications AB |
| Honeywell International Inc. |
| Motorola Solutions, Inc. |
| Robert Bosch GmbH |
| Alarm.com |
| Genetec Inc. |
| Eagle Eye Networks Inc. |
| Others |
Value Chain & Pricing Dynamics
CMOS sensor wafer pricing from Taiwan's foundry complexes cascades through camera OEM cost structures into three-tier subscription tiers, compressing hardware margins while elevating software-analytics premiums for enterprise buyers.
Pricing Analysis
Per-camera uptime guarantees anchor value-based pricing for industrial deployments, with subscription tiers separating SOC-2 certified platforms from standard encryption offerings. Price differentiation hinges on AI inference depth and GDPR compliance documentation, with cost compression in the mid-market intensifying due to hyperscaler cloud storage commoditization. Residential buyers exhibit highest price sensitivity, while German automotive manufacturers accept premium positioning for edge-AI latency specifications.
Supply Chain Analysis
Ocean freight rates from Taiwan and South Korea to North American distribution hubs directly impact landed costs for neural processing units and 4K imaging sensors. Camera assembly draws from Taiwanese chip fabrication, Korean memory modules, and Chinese lens optics, exposing OEMs to single-source vulnerability in edge-AI semiconductor supply. Distribution runs through certified systems integrators for enterprise deployments and direct-to-consumer e-commerce for residential tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native video architectures are displacing on-premise NVR infrastructure, with edge-AI inference engines replacing centralized server processing across enterprise procurement cycles.
For Market Incumbents: Acquire edge-AI firmware engineering teams to counter talent scarcity inflating R&D compensation. Consolidate cybersecurity certification portfolios against pure-play analytics specialists. Deepen building-automation integration to defend against open-platform challengers targeting API-first procurement specifications.
For New Entrants and Emerging Players: Managed service providers represent the fastest channel to scale, bypassing direct enterprise sales cycle complexity. Target India's tier-2 smart city tenders where BIS-certified encryption requirements filter out unqualified foreign vendors. Lead with hybrid cloud configurations addressing uneven fiber backhaul in Maharashtra and Karnataka urban corridors.
For Investors and Strategic Acquirers: The window for entry favors pure-play video analytics specialists with pre-certified EU AI Act documentation. Long-term viability centers on algorithmic transparency capabilities becoming mandatory procurement filters. Monitor CNIL enforcement patterns in France as the inflection signal for compliance-premium pricing expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Chip Supply Agreement | Long-term foundry contracts with TSMC or Samsung insulate against geopolitical allocation rationing. |
| EU AI Act Pre-Certification | CE marking for high-risk biometric systems creates procurement preference segmentation in France and Germany. |
| 5G Private Network Partnership | Ultra-reliable low-latency communication enables wireless deployments in mining and port infrastructure. |
| Behavioral Analytics Acquisition | Retail loss-prevention algorithms address underpenetrated warehouse safety applications beyond perimeter security. |
| Hybrid Cloud Platform Launch | Tiered architectures bridge bandwidth constraints in India's tier-2 municipal surveillance tenders. |
Study Parameters
SEC 10-K filings, EU AI Act regulatory databases, and hyperscaler capex disclosures formed the secondary backbone, supplemented by primary interviews with facility security directors, cloud platform engineers, and municipal procurement officers across Germany, the United States, and India. Bottom-up camera shipment analysis triangulated against top-down enterprise IT spending surveys to validate segment sizing.
Historical trendline analysis of cloud storage pricing and edge-AI chip shipment volumes informed the projection framework across the analysis window. Segmentation modeling incorporated deployment sovereignty levels, end-user sophistication tiers, and service type margin structures. CAGRs derived from elasticity-adjusted adoption curves for video analytics and access control convergence patterns.
Several conditions sit outside the modeled scope, including potential FCC spectrum reallocation, Taiwan semiconductor supply disruption, and EU AI Act enforcement intensity variations. Stakeholders should weight assumptions against their own operating context and regulatory exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Doorbell Camera Market
Security Software
US Evidence Management Market
Security Software
Global Digital Vehicle Forensics Market
Security Software
Source Code Escrow Market
Security Software
Risk-Based Authentication (RBA) Market
Security Software
Asia-Pacific Fraud Detection & Prevention Market
Security Software
Mobile Data Protection Solutions and Services Market
Security Software
Cloud Encryption Software Market
Security Software
Automotive Over-the-Air Cybersecurity Hardening Test Equipment Market
Security Software
Public Cloud Management and Security Services Market
Security Software
Europe User Provisioning Market
Security Software
Geofencing Market
Security Software
US and Latin America Identity and Access Management (IAM) Market
Security Software
Global Privileged Access Management (PAM) Solutions Market
Security Software
Global Email Verification Tools Market
Security Software
AD-Blocking Software Market