
 Latin America Ransomware Protection Market | 2026-2036
Latin America Ransomware Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Ransomware Protection Market Insights
The gap between premium managed detection services and commodity antivirus bundles is broadening across Latin American enterprise procurement. Palo Alto Networks leverages its next-generation firewall integration to anchor high-margin accounts in São Paulo and Mexico City. Fortinet competes through consolidated security fabric licensing that sustains mid-market penetration across Brazilian manufacturing conglomerates.
Ransomware protection encompasses technical systems that detect, contain, and recover from cryptographic malware attacks through behavioral analysis, immutable backup architectures, and zero-trust network segmentation. These solutions operate at throughput thresholds exceeding 10 Gbps in enterprise data centers while maintaining sub-100-millisecond threat response latency. Cloud-based deployment leads adoption curves as Brazilian healthcare providers migrate patient records off legacy on-premises infrastructure. Endpoint protection commands the deepest margin pools where CrowdStrike's agent architecture specializes in kernel-level visibility without signature dependency.
ANPD in Brazil and INAI in Mexico enforce data breach notification timelines that compress incident response windows to 72 hours, directly elevating demand for managed detection retainers. The EU AI Act's extraterritorial reach into Latin American subsidiaries of European multinationals further tightens algorithmic transparency requirements for automated threat classification. Stakeholders must weigh sovereign data residency mandates against cloud provider consolidation when selecting backup architecture.
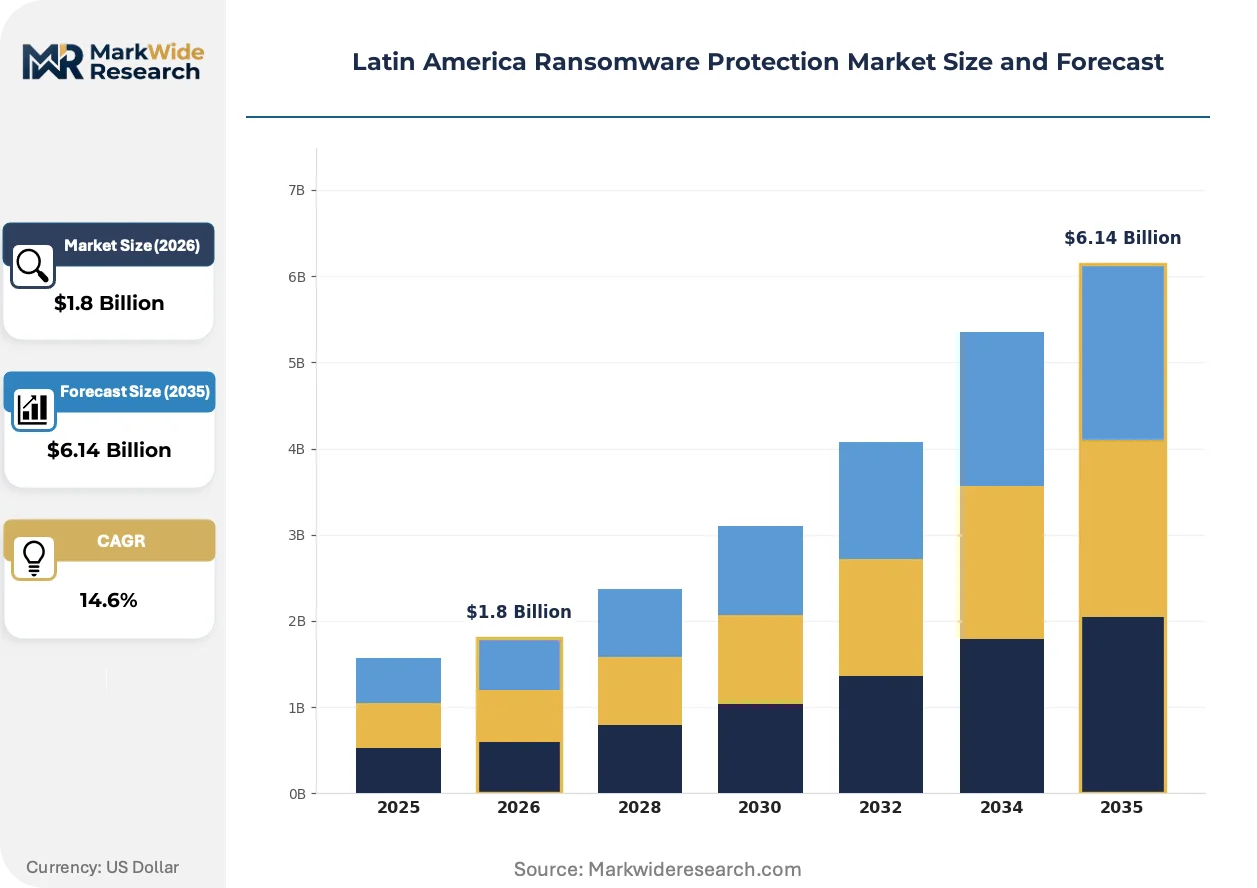
Market Dynamics
The migration of Brazilian healthcare and financial records to cloud infrastructure compresses incident response windows and elevates demand for managed detection retainers across the region.
Growth Catalysts
- ANPD Breach Notification Mandates:Brazil's 72-hour disclosure deadline forces financial institutions to deploy automated threat classification systems with sub-100-millisecond latency.
- Cloud Migration in Colombian Healthcare:Patient record digitization off legacy on-premises systems drives demand for immutable backup architectures and zero-trust segmentation.
- EU AI Act Extraterritorial Reach:Latin American subsidiaries of European multinationals face algorithmic transparency requirements that tighten procurement standards for automated security tools.
Market Restraints
- Specialized Talent Scarcity:Kernel-level security engineering expertise concentrates in São Paulo and Mexico City, inflating managed service retainer costs for regional enterprises.
- Sovereign Data Residency Requirements:Mexican and Colombian regulations mandate local backup storage, fragmenting cloud provider consolidation and complicating architecture selection.
- Commodity Antivirus Substitution:Mid-market manufacturers in Brazil continue deploying signature-dependent endpoint protection, delaying behavioral analysis adoption.
Strategic Opportunities
- Peruvian and Chilean Enterprise Sectors:Underpenetrated mid-market manufacturing and mining operations present whitespace for consolidated security fabric licensing models.
- Behavioral Analysis Convergence:Integration of kernel-level endpoint visibility with next-generation firewall telemetry enables unified threat response platforms.
- INAI Compliance Tailwinds:Mexico's tightening data protection framework under INAI oversight creates mandatory upgrade cycles for legacy detection systems.
Industry Challenges
- Integration Complexity with Legacy Infrastructure:Brazilian manufacturing conglomerates operate heterogeneous on-premises systems that resist seamless cloud-based deployment.
- Certification Timeline Compression:ANPD and INAI disclosure windows leave insufficient time for manual threat verification, forcing premature automated response activation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Ransomware Protection Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Healthcare, Education, BFSI, Government Solution: Backup Solutions, Endpoint Protection, Network Security, Threat Intelligence Service Type: Consulting, Incident Response, Managed Detection, Training |
| Companies Covered | Palo Alto Networks, Fortinet, Microsoft, IBM, Check Point Software Technologies Ltd, Cisco Systems Inc., Symantec Corporation, McAfee, LLC, CrowdStrike Holdings Inc, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Ransomware Protection Market Trends and Innovations
Behavioral detection architectures and regulatory compliance automation are actively restructuring how Latin American enterprises procure and deploy ransomware protection capabilities.
Kernel-level endpoint protection is converging with cloud-native security fabric orchestration. Brazilian healthcare providers migrating patient records to distributed cloud environments adopt agent architectures that bypass signature dependency entirely. This convergence is compressing procurement cycles that previously separated endpoint, network, and backup decisions into unified platform evaluations.
INAI oversight in Mexico tightens data breach notification timelines that directly elevate demand for automated incident response. The regulator's 72-hour disclosure mandate forces enterprises to abandon manual verification workflows. Financial institutions in Mexico City now prioritize detection systems with embedded compliance documentation.
Enterprise buyers across Colombian manufacturing sectors unbundle after-sales service from perpetual license agreements. Procurement teams negotiate separate managed detection retainers that specify response latency guarantees rather than product feature checklists. This behavioral shift is most visible in Medellín and Bogotá industrial corridors where conglomerates consolidate vendor relationships.
Latin America Ransomware Protection Market Segmentation
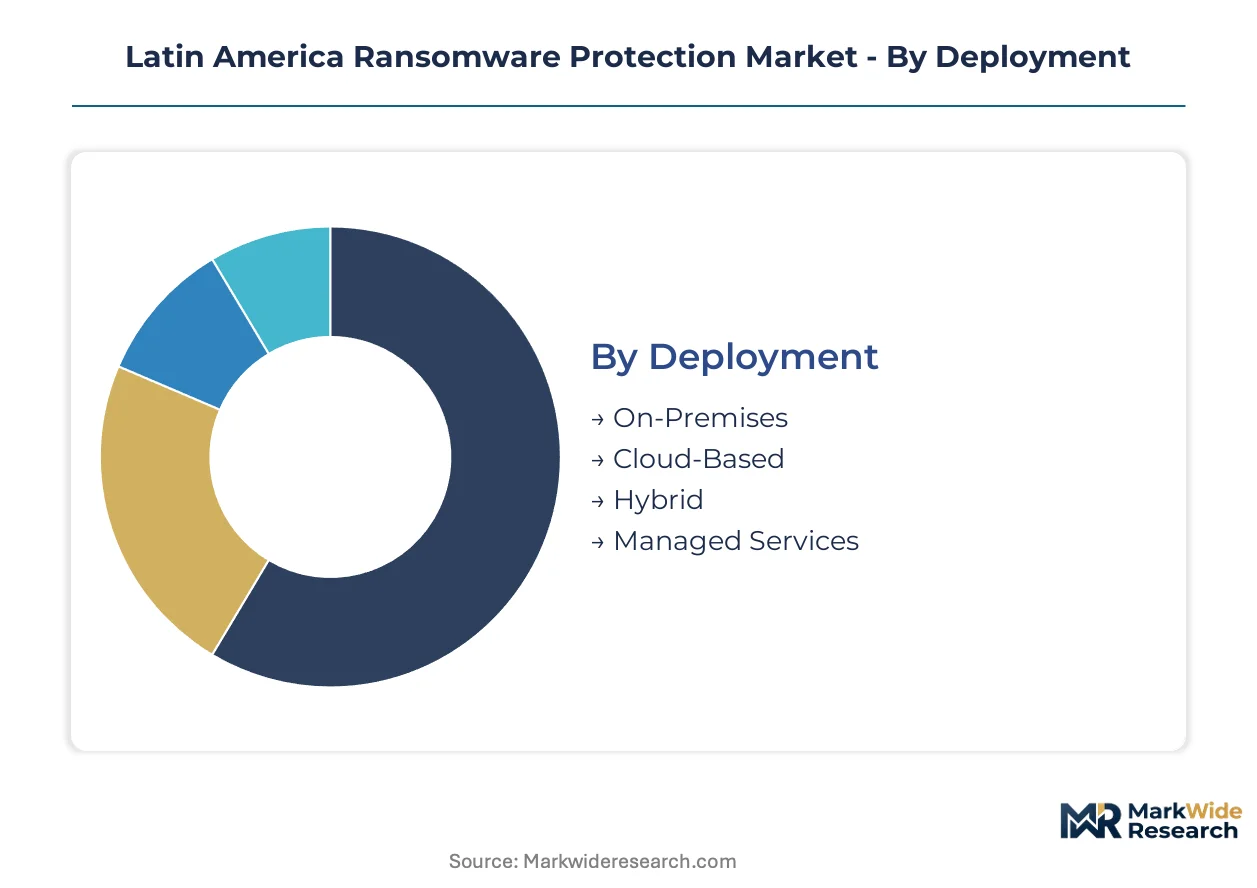
Ransomware protection procurement across Latin America fragments across deployment architectures, regulatory verticals, and service delivery models. Understanding these divisions reveals where compliance burdens concentrate and where margin pools shift between product and service revenue.
Deployment:
ANPD and INAI disclosure mandates impose distinct certification burdens: cloud-based deployments require sovereign data residency attestations, while managed services demand SOC 2 Type II or equivalent audit trails for incident response documentation.
- Cloud-Based:Distributed architectures with immutable backup replication across availability zones. Brazilian healthcare providers in São Paulo and Rio de Janeiro drive concentration as patient record digitization accelerates under ANPD pressure. Compliance automation for 72-hour breach notification elevates procurement priority.
- Managed Services:Outsourced detection and response with contractual latency guarantees for threat containment. Colombian financial institutions in Bogotá favor this model to compensate for kernel-level security talent scarcity. Retainer structures separate from perpetual licensing reshape vendor relationships.
- On-Premises:Legacy air-gapped systems in Mexican government facilities resisting cloud migration.
- Hybrid:Segmented architectures with critical workloads on-premises and non-sensitive data in cloud.
Cloud-based sits at the top of the volume ranking, with managed services climbing the fastest.
End User:
Vertical-specific risk profiles determine solution sophistication: BFSI faces systemic attack volumes, while healthcare confronts life-safety consequences from encrypted patient records.
- BFSI:Banking, financial services, and insurance operations with real-time transaction processing requirements. Brazilian institutions deploy sub-100-millisecond threat response systems to meet ANPD disclosure windows. Ransomware cartels systematically target payment infrastructure.
- Healthcare:Hospitals and clinic networks with electronic health record dependencies. Mexican providers under INAI oversight migrate off legacy infrastructure toward immutable backup architectures. Patient safety liability amplifies recovery time objective pressures.
- Government:Federal and state agencies with classified data retention mandates.
- Education:Universities and research institutions with dispersed endpoint populations.
BFSI commands the deepest security spending per employee, with healthcare expanding most quickly as digitization deadlines approach.
Solution:
Technical component selection tracks infrastructure maturity: organizations with modernized endpoints prioritize behavioral detection, while those with heterogeneous legacy stacks emphasize network segmentation.
- Endpoint Protection:Kernel-level agent architectures delivering visibility without signature dependency. Brazilian manufacturing conglomerates in São Paulo industrial corridors adopt these systems to replace commodity antivirus. CrowdStrike and similar vendors anchor high-margin accounts through telemetry consolidation.
- Network Security:Next-generation firewall integration with zero-trust segmentation policies. Colombian enterprises deploy these at 10+ Gbps throughput thresholds to maintain operational continuity. Palo Alto Networks leverages this category for platform anchoring.
- Backup Solutions:Immutable snapshot architectures with air-gapped replication.
- Threat Intelligence:Feeds and analytics for indicator-of-compromise enrichment.
Endpoint protection generates the highest margin contribution, with network security gaining share fastest as firewall refresh cycles accelerate.
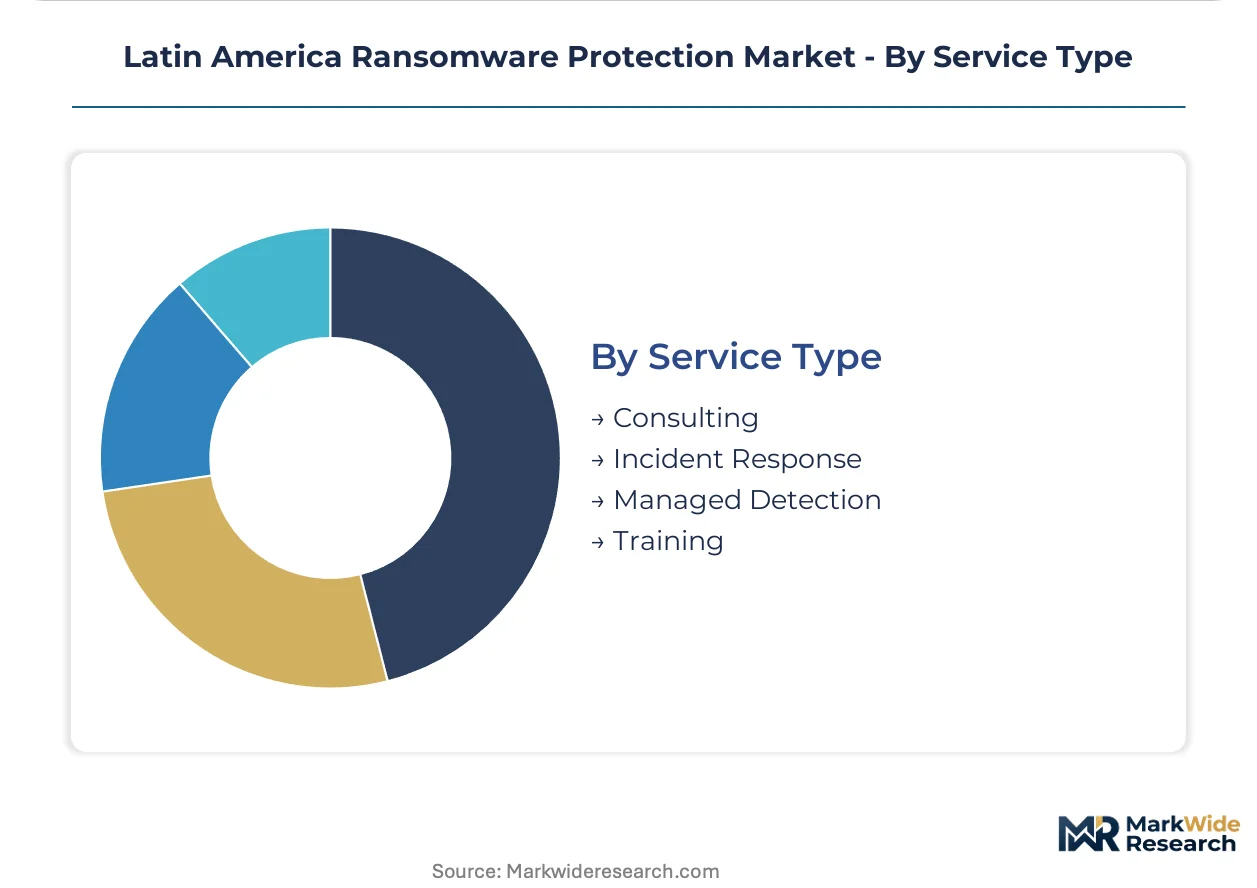
Service Type:
Procurement unbundling separates product from service revenue: enterprises now negotiate standalone retainers specifying response metrics rather than accepting bundled maintenance.
- Managed Detection:Continuous monitoring with automated threat classification and human escalation protocols. Mexican City financial institutions prioritize embedded compliance documentation for INAI disclosure readiness. 72-hour notification windows eliminate manual verification workflows.
- Incident Response:Retained breach containment teams with guaranteed mobilization timelines. Brazilian healthcare networks contract these services given patient safety exposure. Forensic preservation for regulatory evidence dominates scope.
- Consulting:Architecture design and zero-trust migration planning.
- Training:Phishing simulation and security awareness programs.
Managed detection sits at the top of the volume ranking, with incident response climbing the fastest as attack volumes escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kernel-level security engineering expertise concentrates in São Paulo and Mexico City, creating talent gravity that shapes procurement patterns across the region. This workforce distribution elevates managed service retainer costs for enterprises outside these metros while compressing incident response capabilities where density is highest.
Brazil
ANPD's 72-hour breach notification deadline forces financial institutions in São Paulo and Rio de Janeiro to deploy automated threat classification systems with sub-100-millisecond latency. The national data protection authority enforces disclosure timelines that eliminate manual verification workflows. Manufacturing conglomerates in São Paulo industrial corridors replace commodity antivirus with kernel-level endpoint architectures.
Mexico
INAI oversight tightens data protection frameworks and compresses incident response windows for Mexico City financial institutions. The regulator mandates algorithmic transparency requirements that affect Latin American subsidiaries of European multinationals under EU AI Act reach. Healthcare providers migrate patient records toward immutable backup architectures with sovereign data residency compliance.
Colombia
Cloud migration across Bogotá and Medellín industrial corridors drives demand for zero-trust network segmentation and distributed backup replication. Colombian enterprises unbundle after-sales service from perpetual licenses, negotiating standalone managed detection retainers with response latency guarantees. Procurement teams prioritize consolidated security fabric licensing over point-product accumulation.
Chile
Mid-market mining and manufacturing operations in Santiago present whitespace for behavioral analysis adoption beyond signature-dependent protection. The country's data protection authority enforces breach notification requirements that elevate automated incident response procurement. Enterprise buyers in Chilean industrial sectors show accelerating preference for cloud-native deployment over legacy on-premises infrastructure.
Peru
Lima-based enterprises in underpenetrated manufacturing and extractive industries represent expansion targets for consolidated security platform vendors. Local data residency regulations complicate cloud provider selection while creating openings for hybrid deployment specialists. Peruvian procurement teams demonstrate rising sophistication in separating product licensing from managed service retainers.
Latin America Ransomware Protection Market Competitive Landscape
Capital-heavy integrated platform vendors compete with asset-light endpoint specialists across Latin American enterprise procurement cycles. The vendor base organizes around three strategic archetypes: next-generation firewall anchoring platforms, consolidated security fabric licensors, and kernel-level endpoint visibility specialists. Palo Alto Networks leverages firewall integration for high-margin account anchoring in São Paulo and Mexico City. Fortinet sustains mid-market penetration through consolidated licensing across Brazilian manufacturing conglomerates. CrowdStrike anchors premium accounts via agent architectures that bypass signature dependency entirely. Competitive moves concentrate on M&A for behavioral analysis capabilities and strategic partnerships for sovereign cloud compliance.
Within the integrated platform tier, Palo Alto Networks and Fortinet exemplify contrasting geographic strategies for Latin American market development. Palo Alto Networks occupies a position emphasizing next-generation firewall anchoring in premium financial services accounts across São Paulo and Mexico City metros. Fortinet sits within the consolidated fabric licensing archetype, targeting mid-market manufacturing penetration through bundled security service delivery. CrowdStrike Holdings Inc represents the kernel-level endpoint specialist archetype, commanding margin pools where behavioral detection displaces signature-dependent alternatives. These three anchors demonstrate how vendor positioning fragments across deployment complexity, regulatory vertical, and service unbundling trends reshaping procurement patterns.
| Leading Market Players |
|---|
| Palo Alto Networks |
| Fortinet |
| Microsoft |
| IBM |
| Check Point Software Technologies Ltd |
| Cisco Systems Inc. |
| Symantec Corporation |
| McAfee, LLC |
| CrowdStrike Holdings Inc |
| Others |
Pricing and Supply Chain Analysis
Colombian financial institutions in Bogotá and Medellín anchor regional procurement volumes, driving unbundled service contracts that separate managed detection retainers from perpetual software licensing. This buyer concentration elevates pricing power for vendors offering SOC 2 Type II audit trails and sub-100-millisecond response guarantees.
Pricing Analysis
Bundled security fabric licensing competes against unbundled managed detection retainers across Latin American enterprise procurement. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth and response latency guarantees. Pricing pressure stems from commodity antivirus substitution in Brazilian mid-market manufacturing, where signature-dependent alternatives delay behavioral analysis adoption. Healthcare networks in São Paulo show least price sensitivity due to patient safety liability exposure.
Supply Chain Analysis
Kernel-level security engineering talent concentrates in São Paulo, Mexico City, and Santiago, creating input dependency for managed service delivery. Cloud infrastructure draws from US hyperscaler availability zones, with sovereign data residency mandates forcing Colombian and Mexican local replication. Single-source vulnerability sits with concentrated endpoint agent development in North American headquarters. Distribution runs through value-added resellers with ANPD and INAI compliance certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in managed detection retainers, where automation of compliance documentation compresses delivery costs while premium-tier buyers absorb latency-guarantee pricing.
For Market Incumbents: Hedge against kernel-level talent scarcity by building SOC 2 Type II-certified delivery centers in Santiago and Lima, reducing dependency on São Paulo and Mexico City wage premiums. Anchor high-margin accounts through next-generation firewall integration that locks in telemetry consolidation. Defend against CrowdStrike's agent-architecture displacement by accelerating behavioral analysis R&D. For New Entrants and Emerging Players: Begin with underpenetrated Peruvian mining operations and Chilean mid-market manufacturing, where signature-dependent endpoint protection still dominates. Target hybrid deployment architectures that navigate Mexican and Colombian sovereign data residency requirements without full cloud migration. Lead with managed detection retainers priced below incumbent benchmarks. For Investors and Strategic Acquirers: Consolidated security platform vendors are the most active acquirer in this space, seeking behavioral analysis capabilities to complete unified threat response portfolios. Acquisition targets include kernel-level endpoint specialists with INAI compliance automation and regional managed service providers with ANPD-certified delivery infrastructure. Watch for ANPD enforcement intensity as inflection indicator for Brazilian healthcare and financial upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Behavioral Analysis Capability Acquisition | Kernel-level endpoint visibility displaces signature-dependent alternatives in São Paulo manufacturing corridors. |
| Sovereign Cloud Compliance Partnership | Mexican data residency mandates force local backup replication away from consolidated hyperscaler architectures. |
| Managed Detection Retainer Unbundling | Colombian procurement teams now negotiate standalone response-latency contracts separate from perpetual licensing. |
| Zero-Trust Network Segmentation Deployment | Brazilian healthcare providers migrating patient records require 10+ Gbps throughput with sub-100-millisecond threat response. |
| INAI Compliance Automation Integration | Mexico City financial institutions prioritize embedded documentation for 72-hour breach notification readiness. |
Research Methodology
Coverage spans Brazil, Mexico, Colombia, Chile, and Peru, with primary inputs from each national market. Interviews with CISOs at Brazilian financial institutions, Mexican healthcare network IT directors, Colombian manufacturing conglomerate procurement leads, and kernel-level security engineering specialists in São Paulo and Mexico City inform demand-side dynamics. Secondary validation draws from ANPD enforcement disclosures, INAI regulatory filings, hyperscaler capex announcements, and SOC 2 Type II audit registries. Bottom-up deployment model sizing triangulates against top-down cybersecurity spending estimates from national statistical agencies.
Granularity extends to deployment architecture, regulatory vertical, solution component, and service delivery model across the projection horizon. Cloud-based, managed services, on-premises, and hybrid deployment modes were modeled separately with distinct compliance burden weightings. BFSI, healthcare, government, and education verticals incorporate vertical-specific risk profiles and notification timeline pressures. CAGRs derive from regression against attack volume trajectories, regulatory enforcement intensity indices, and cloud migration penetration curves. Sovereign data residency mandate evolution and EU AI Act extraterritorial reach inform cross-border procurement pattern shifts.
Several conditions sit outside the modeled scope, including specific ransomware cartel tactical evolution, individual vendor security breach events, and abrupt sovereign data localization requirement changes. Forecasts assume continued ANPD and INAI enforcement capacity building without regulatory rollback. A small set of named triggers warrants ongoing watch: ANPD fine issuance velocity, INAI disclosure window compression, and hyperscaler regional availability zone expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Smart Grid Cyber Security Market
Cybersecurity
Dark Web Intelligence Market
Cybersecurity
Internet of Things (IoT) Security Market
Cybersecurity
Network Sandboxing Market
Cybersecurity
Cyber Security As a Service Market
Cybersecurity
Cybersecurity in Gaming Market
Cybersecurity
Denmark Cybersecurity Market
Cybersecurity
LAMEA Deception Technology Market
Cybersecurity
Singapore Cybersecurity Market
Cybersecurity
ASEAN Cyber Security Market
Cybersecurity
Austria Cybersecurity Market
Cybersecurity
North America Cyber Security Market
Cybersecurity
Digital Security Market
Cybersecurity
Cyber Security Consulting Market
Cybersecurity
Open RAN Security Market
Cybersecurity
Germany Endpoint Detection and Response Market