
 North America Cleanroom Technology Market | 2026-2036
North America Cleanroom Technology Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cleanroom Technology Market Analytics
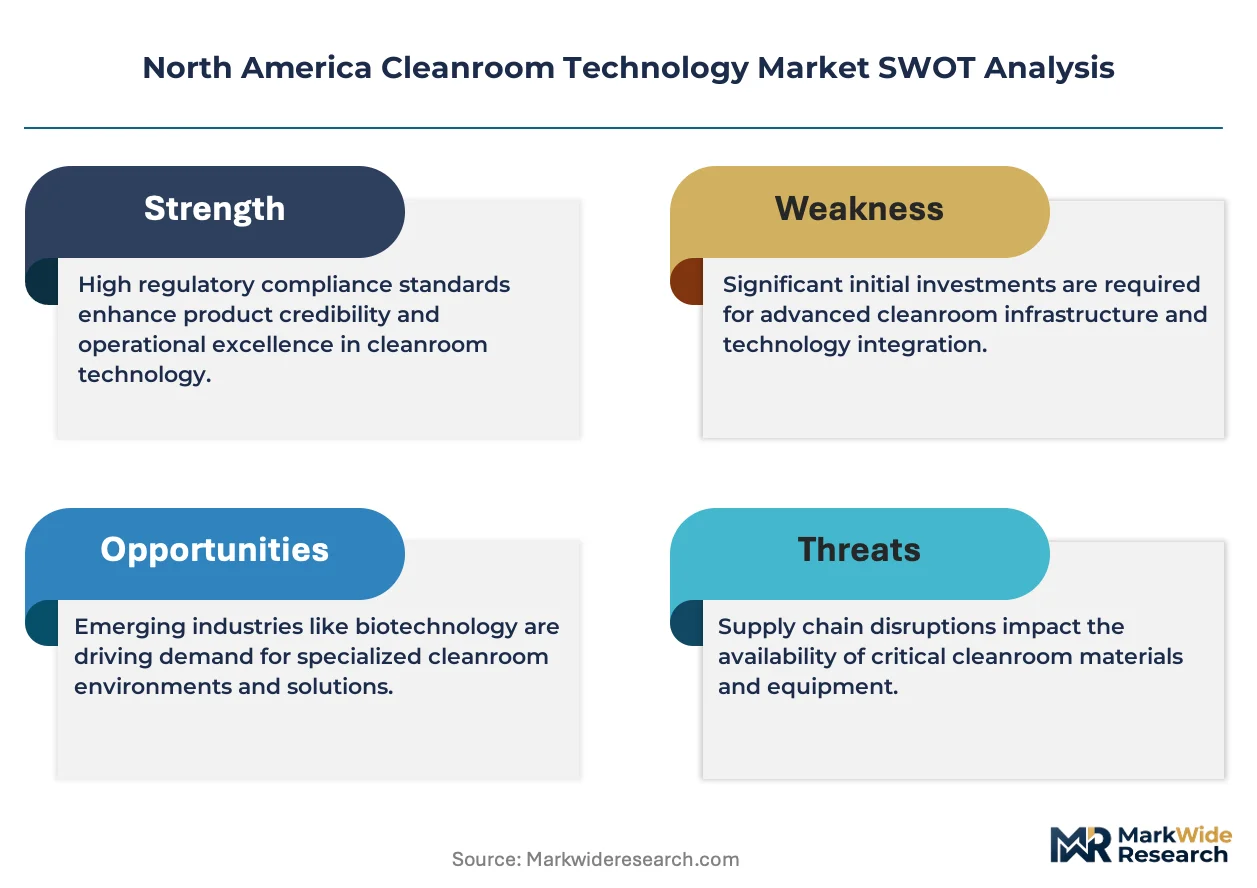
Aftermarket service revenue for filtration system validation and recertification is reshaping margin distribution across the North America cleanroom technology landscape. DuPont de Nemours, Inc. leverages its materials science portfolio to dominate high-performance barrier fabric supply for pharmaceutical apparel. Kimberly-Clark Corporation sustains broad channel control through hospital and laboratory distribution networks. Illinois Tool Works Inc. anchors its position via specialized HVAC and filtration components for controlled environment infrastructure.
Cleanroom technology encompasses engineered enclosures, filtration systems, garments, and monitoring equipment designed to maintain specified airborne particulate concentrations, typically achieving ISO Class 5 to Class 8 cleanliness levels through laminar airflow and HEPA or ULPA filtration. This technology serves the essential function of eliminating contamination risks during sterile drug manufacturing, microelectronics fabrication, and sensitive research procedures. HEPA Filters command the largest product-type margin pool due to recurring replacement cycles and stringent validation protocols, while Cleanroom Apparel experiences accelerated demand from biotechnology expansion. Pharmaceutical applications lead absolute spending, though Medical Devices represents the fastest-growing application segment as OEMs reshore sterile assembly capacity.
FDA enforcement of current Good Manufacturing Practice standards and USP <797>/<800> sterile compounding requirements directly shapes equipment specification and facility validation schedules across the region. EPA energy efficiency mandates and OSHA workplace exposure limits further constrain system design, pushing buyers toward integrated monitoring and lower-energy filtration architectures. Stakeholders must monitor evolving MDR harmonization pressures from Health Canada and potential convergence with EU GMP Annex 1 revisions to anticipate cross-border facility standardization demands.
Market Dynamics
Biopharmaceutical manufacturing expansion across the US Northeast corridor and Mid-Atlantic states is compressing facility build timelines while tightening contamination control specifications, forcing equipment vendors to accelerate modular cleanroom deployment cycles and integrate real-time monitoring architectures from project inception.
Growth Catalysts
- USP <797>/<800> Enforcement:FDA and state pharmacy boards are intensifying sterile compounding inspections, compelling hospital systems and 503B outsourcing facilities to upgrade HVAC and barrier systems to meet revised environmental monitoring requirements.
- Cell and Gene Therapy Manufacturing:Commercial-scale production of CAR-T therapies and viral vectors requires ISO Class 5-7 suites with unidirectional airflow, driving demand for flexible ballroom configurations and isolator-integrated filling lines.
- Boston-Cambridge Cluster Density:Concentrated biotech R&D and manufacturing investment across Massachusetts and New Jersey is sustaining multi-year facility construction pipelines and recurring validation service contracts.
Market Restraints
- High-Purity Aluminum and Specialty Steel Input Volatility:Cleanroom panel and framing systems depend on aerospace-grade aluminum alloys and electropolished stainless steel subject to energy-intensive production constraints and tariff exposure.
- HEPA Media Supply Concentration:Borosilicate microfiber and PTFE membrane supply for ULPA-grade filtration concentrates among a limited set of North American and European substrate manufacturers, creating lead time vulnerability.
- Legacy Facility Retrofit Complexity:Existing pharmaceutical plants built to 1990s cGMP standards face structural limitations integrating modern continuous monitoring systems without full HVAC reconstruction.
Strategic Opportunities
- Canadian Biologics Manufacturing Expansion:Health Canada MDR harmonization with EU Annex 1 is attracting multinational sponsors to Toronto-Montreal corridor facilities requiring ISO-compliant infrastructure and cross-border validation protocols.
- Modular Cleanroom-as-a-Service Models:Equipment vendors are deploying lease-based flexible suites with embedded validation and maintenance, reducing upfront capex barriers for emerging biotechs and contract manufacturers.
- Energy Recovery Ventilation Integration:EPA efficiency mandates and IRA clean energy incentives are accelerating heat recovery wheel and enthalpy wheel adoption in new pharmaceutical HVAC specifications.
Industry Challenges
- Qualified Cleanroom Commissioning Talent Scarcity:ISO 14644-1 certification and FDA validation protocol expertise concentrates among aging specialist engineers, constraining project throughput across the region.
- Multi-Standard Convergence Complexity:Simultaneous compliance with USP <797>, EU GMP Annex 1 revisions, and Health Canada MDR is extending facility qualification timelines and documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cleanroom Technology Market |
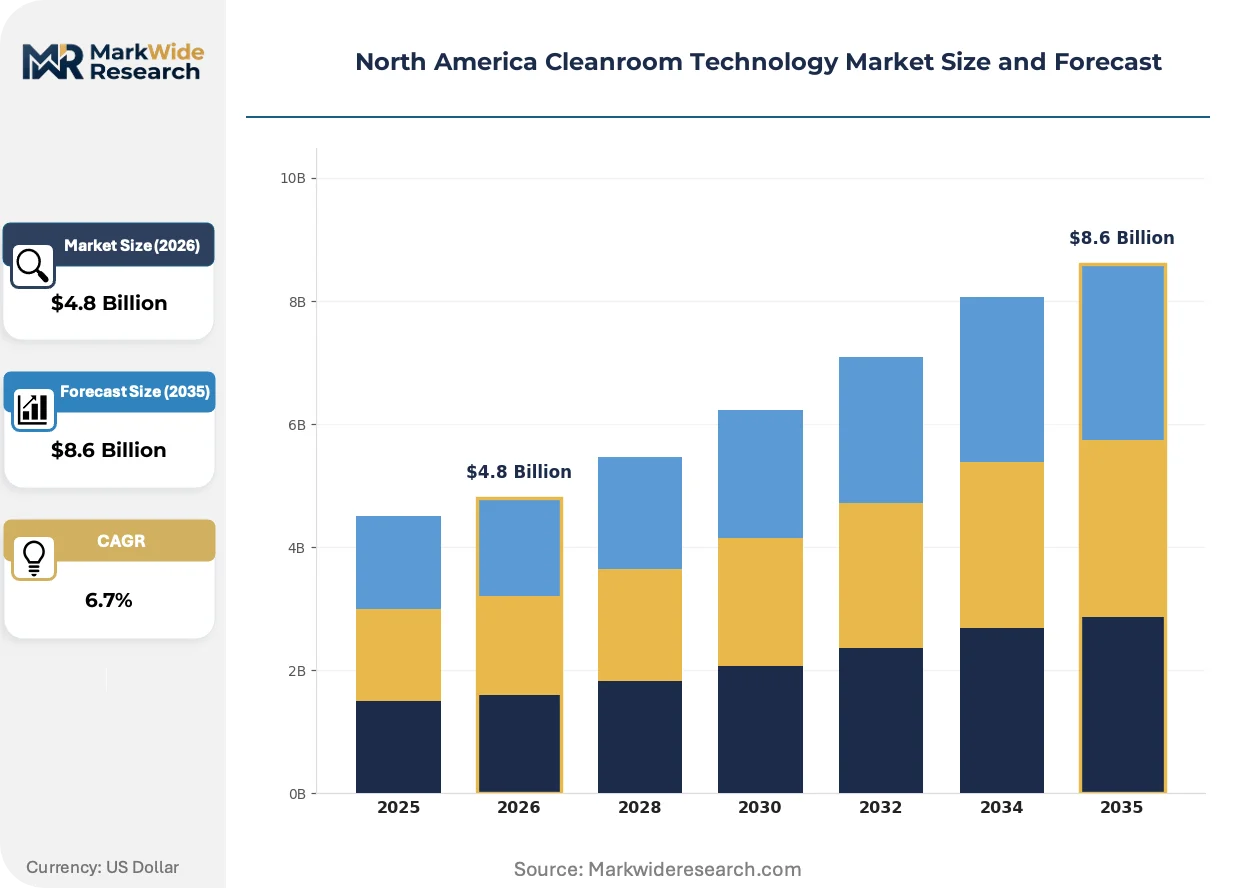
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Showers, Cleanroom Apparel, HEPA Filters, Cleanroom Furniture Application: Pharmaceutical, Biotechnology, Medical Devices, Electronics End User: Hospitals, Research Laboratories, Manufacturing Units, Educational Institutions Delivery Mode: In-house, Outsourced, Hybrid, On-demand |
| Companies Covered | Kimberly-Clark Corporation, DuPont de Nemours, Inc., Illinois Tool Works Inc., Labconco Corporation, Clean Air Products Inc., Taikisha Ltd, Azbil Corporation, Exyte GmbH, Terra Universal Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cleanroom Technology Market Evolving Landscape
Digital twin architectures and AI-driven environmental monitoring are compressing commissioning cycles while enabling predictive contamination control, fundamentally altering how pharmaceutical and medical device manufacturers validate and operate controlled environments.
Computational fluid dynamics (CFD) modeling combined with IoT sensor networks is virtualizing cleanroom design validation before physical construction, allowing biopharma engineering teams to simulate particle dispersion patterns and airflow turbulence across proposed suite layouts. Large molecule manufacturers in the Boston-Cambridge corridor are adopting these tools to de-risk facility investments and accelerate regulatory submission timelines. This virtualization is compressing traditional design-build-validate cycles and reducing costly post-construction remediation.
EPA energy efficiency mandates and evolving OSHA workplace exposure limits are forcing HVAC specification shifts toward lower-pressure-drop filtration media and demand-controlled ventilation systems in pharmaceutical manufacturing environments. Equipment buyers now prioritize integrated monitoring platforms that correlate energy consumption with particulate and microbial load data for regulatory reporting. The US Northeast pharmaceutical corridor shows the most aggressive adoption, driven by state-level clean energy incentives and corporate sustainability commitments.
Service unbundling is fragmenting traditional cleanroom equipment procurement, with biopharma operators separating capital equipment purchases from validation, recertification, and aftermarket monitoring contracts. Contract manufacturers and emerging biotechs increasingly source modular suites through third-party lessors while retaining specialized commissioning agents for FDA-facing documentation. This pattern concentrates in New Jersey and Pennsylvania, where outsourced pharmaceutical manufacturing capacity expansion is fastest.
North America Cleanroom Technology Market Segmentation
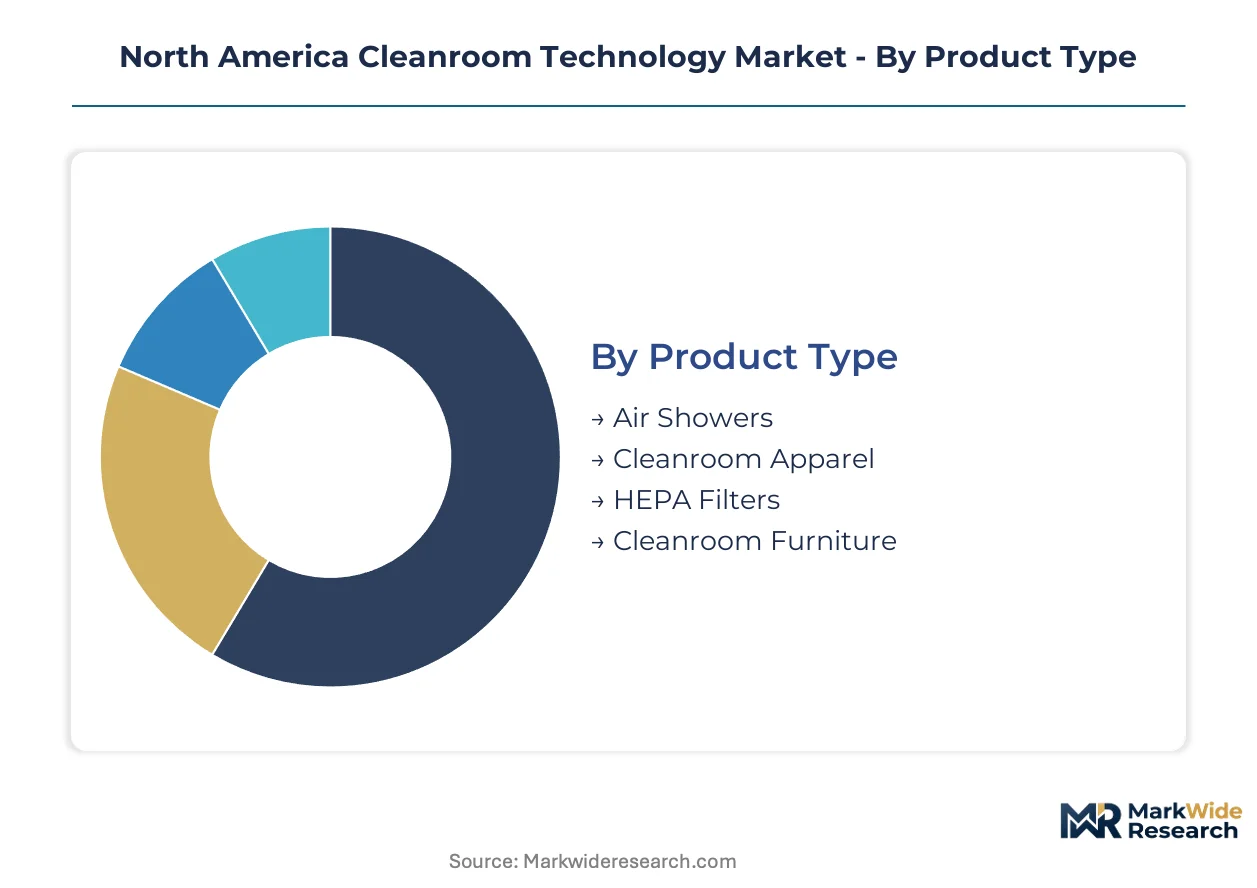
Cleanroom technology procurement patterns diverge sharply across product categories, with contamination control specifications varying by end-use criticality. Segmentation reveals how ISO classification requirements and regulatory compliance burdens reshape vendor selection and facility investment priorities across North American pharmaceutical and medical device corridors.
Product Type:
Mature filtration technologies anchor procurement budgets while emerging contamination control formats reshape facility architecture across the region.
- HEPA Filters:Borosilicate microfiber and PTFE membrane assemblies achieve 99.97% particle retention at 0.3 microns for ISO Class 5-8 environments. Pharmaceutical sterile suites in the Boston-Cambridge corridor drive replacement demand through FDA-mandated validation cycles and continuous monitoring integration.
- Cleanroom Apparel:Non-woven polypropylene and DuPont Tyvek barrier fabrics prevent human-borne contamination in aseptic processing. Biotechnology expansion across New Jersey and Pennsylvania accelerates demand for sterile gowns, hoods, and coveralls with integrated breathable moisture barriers.
- Air Showers:High-velocity HEPA-filtered air jets remove surface particles from personnel and equipment before cleanroom entry.
- Cleanroom Furniture:Electropolished stainless steel workbenches and storage systems meet cGMP surface finish requirements for pharmaceutical manufacturing.
HEPA Filters handles the majority of throughput; Cleanroom Apparel is the fastest mover on share.
Application:
Cost tier stratification separates capital-intensive sterile drug manufacturing from precision electronics assembly with divergent contamination thresholds.
- Pharmaceutical:Aseptic filling lines and sterile compounding suites require ISO Class 5-7 laminar airflow with continuous viable and non-viable particle monitoring. USP <797> enforcement across hospital systems and 503B outsourcing facilities sustains multi-year HVAC upgrade cycles in the US Northeast.
- Medical Devices:Sterile implantable and invasive device assembly demands ISO 14644-1 compliant environments with validated cleaning protocols. OEM reshoring initiatives across Minnesota and California medical device corridors accelerate ballroom and isolator deployment for orthopedic and cardiovascular product lines.
- Biotechnology:Cell and gene therapy manufacturing requires flexible suite configurations for viral vector and CAR-T production.
- Electronics:Semiconductor and microelectronics fabrication operates at ISO Class 1-4 with unidirectional airflow and ionization control.
Pharmaceutical commands the largest absolute spend; Medical Devices is climbing the fastest on application share.
End User:
Customer type determines procurement sophistication, with regulated manufacturers demanding integrated validation services that hospitals and academic labs rarely specify.
- Manufacturing Units:Pharmaceutical and biotech production facilities deploy permanent modular cleanrooms with embedded HVAC, monitoring, and documentation systems for FDA submission. Massachusetts and New Jersey manufacturing clusters sustain the highest per-facility investment in continuous environmental monitoring platforms.
- Hospitals:Sterile compounding pharmacies and operating suites upgrade barrier systems to meet revised USP <797> and USP <800> hazardous drug handling requirements. State pharmacy board inspections across California, Texas, and Florida drive episodic HVAC and containment investments.
- Research Laboratories:Academic and government research facilities require flexible cleanroom configurations for multi-protocol use.
- Educational Institutions:University engineering and life science programs deploy teaching cleanrooms for workforce training.
Manufacturing Units absorb the dominant share of capital deployment; Hospitals are expanding most quickly on end user mix.
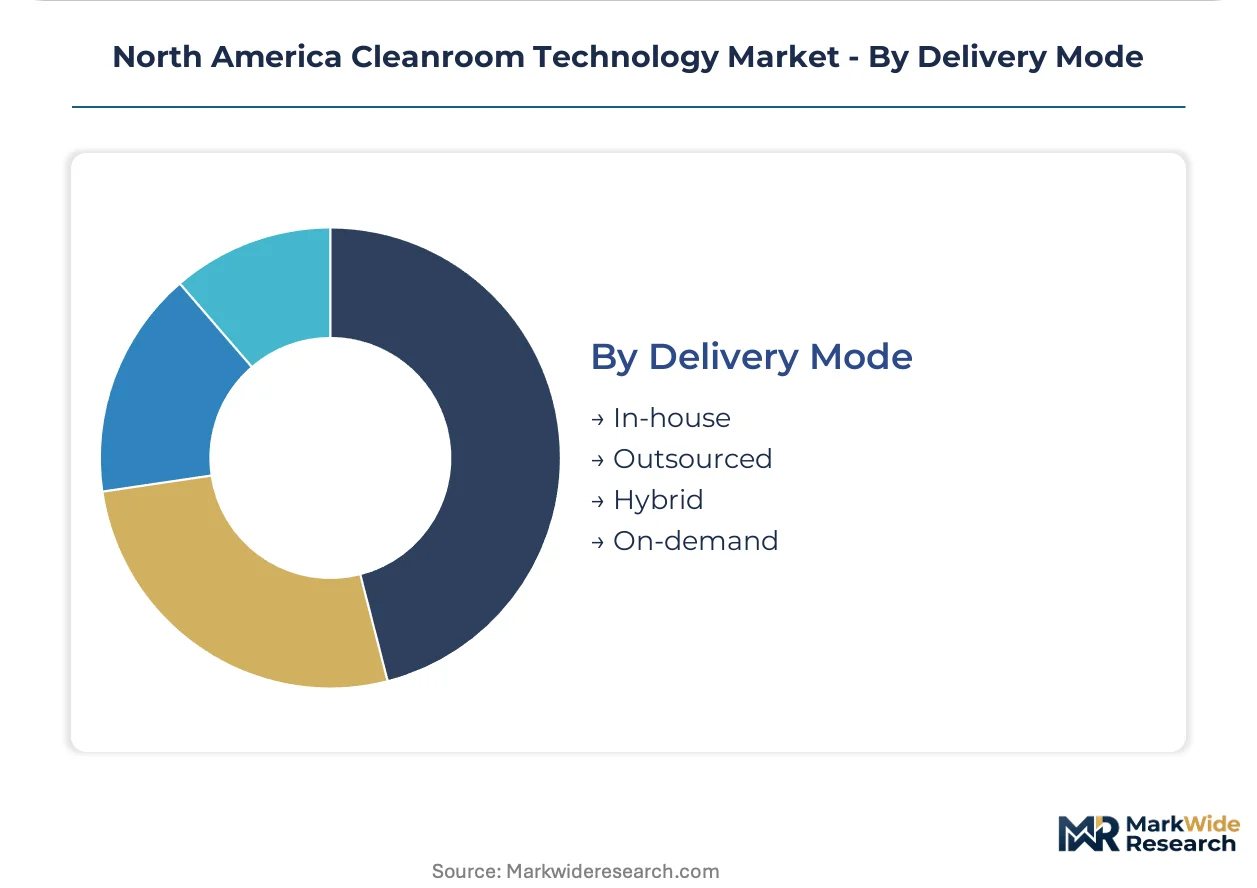
Delivery Mode:
Supply concentration among specialized commissioning agents creates procurement friction for complex facility integrations.
- In-house:Large pharmaceutical operators maintain captive engineering teams for cleanroom design, construction, and FDA validation protocol execution. Pfizer, Merck, and Johnson & Johnson facilities across the US Northeast corridor retain specialized ISO 14644-1 certified engineers for recurring recertification cycles.
- Outsourced:Emerging biotechs and contract manufacturers lease modular suites with embedded validation and maintenance from third-party lessors. Toronto-Montreal corridor expansion attracts outsourced facility providers serving Health Canada MDR compliance requirements.
- Hybrid:Mixed procurement combines capital equipment purchase with contracted commissioning and ongoing monitoring services.
- On-demand:Flexible cleanroom-as-a-service models reduce upfront capex for clinical-stage manufacturers.
In-house delivery retains the largest project volume; Outsourced is gaining share fastest among emerging biotechs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems in Florida and Texas exhibit acute price sensitivity for USP <797> compliance upgrades, while Massachusetts biotech clusters absorb premium pricing for ISO Class 5 modular suites without volume elasticity.
United States
FDA enforcement of revised USP <797> and USP <800> standards drives HVAC replacement cycles across hospital sterile compounding pharmacies. The Inflation Reduction Act's clean energy incentives accelerate heat recovery ventilation adoption in pharmaceutical manufacturing specifications. The Boston-Cambridge corridor sustains concentrated demand for flexible ballroom configurations serving cell and gene therapy commercialization.
Canada
Health Canada MDR harmonization with EU GMP Annex 1 attracts multinational biologics sponsors to Toronto-Montreal corridor facilities. Federal clean technology investment tax credits reduce capital barriers for energy-efficient cleanroom infrastructure deployment. The Toronto metropolitan area anchors cross-border validation service demand as US sponsors establish Health Canada-compliant manufacturing capacity.
Mexico
Nearshoring of medical device sterile assembly accelerates ISO 14644-1 compliant facility construction across Baja California and Chihuahua border states. COFEPRIS regulatory alignment initiatives with FDA standards streamline facility qualification timelines for export-oriented manufacturers. Tijuana and Ciudad Juárez industrial corridors concentrate contract manufacturing investment requiring contamination control infrastructure.
North America Cleanroom Technology Market Competitive Landscape
Integrated materials conglomerates and specialized HVAC fabricators split the market between barrier material supply and controlled environment infrastructure deployment. The vendor base concentrates around three strategic archetypes: diversified industrial conglomerates with materials science portfolios, specialized cleanroom engineering contractors with commissioning expertise, and filtration component specialists with recurring service revenue models. Dominant competitive moves include backward integration into high-performance fabric manufacturing and geographic expansion through modular cleanroom-as-a-service leasing platforms.
Within the materials-centric tier, DuPont de Nemours, Inc. and Kimberly-Clark Corporation exemplify divergent positioning strategies. DuPont occupies a position anchored in barrier fabric technology derived from its broader materials science portfolio. Kimberly-Clark represents channel-control archetype execution through established hospital and laboratory distribution networks. Illinois Tool Works Inc. sits within the specialized component tier, anchoring its market presence via HVAC and filtration subsystem supply for integrated facility builds.
| Leading Market Players |
|---|
| Kimberly-Clark Corporation |
| DuPont de Nemours, Inc. |
| Illinois Tool Works Inc. |
| Labconco Corporation |
| Clean Air Products Inc. |
| Taikisha Ltd |
| Azbil Corporation |
| Exyte GmbH |
| Terra Universal Inc |
| Others |
Value Network & Pricing Analysis
Tariff exposure on aerospace-grade aluminum alloys and electropolished stainless steel simultaneously compresses margin structures for cleanroom panel fabricators and widens pricing tier spreads between premium ISO Class 5 suites and standard hospital pharmacy retrofits. This input cost volatility forces buyers toward modular lease structures that externalize capex risk while concentrating supply chain leverage among integrated materials conglomerates with captive metal sourcing.
Pricing Analysis
Aftermarket validation and recertification service contracts drive lifetime value for cleanroom equipment vendors, with multi-year maintenance agreements often exceeding initial hardware revenue. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical suites from hospital USP compliance upgrades and educational training facilities. Cost compression in standard-tier hospital retrofits is intensifying because state pharmacy boards mandate episodic compliance investments without recurring revenue attachment. Contract manufacturers and emerging biotechs in the Boston-Cambridge corridor show lowest price sensitivity, absorbing premium modular ballroom configurations without volume elasticity.
Supply Chain Analysis
Borosilicate microfiber and PTFE membrane feedstock for HEPA and ULPA filtration draws from concentrated North American and European substrate manufacturers, with limited qualified suppliers creating lead time vulnerability for pharmaceutical-grade media. Electropolished stainless steel work surfaces and aluminum framing systems rest on aerospace and semiconductor industry supply chains in the United States, Germany, and Japan. Single-source vulnerability for ULPA-grade membrane production exposes cleanroom builders to qualification delays when switching substrate vendors. Distribution runs through specialized HVAC contractors and third-party commissioning agents rather than direct manufacturer-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cleanroom technology procurement is shifting toward platform-based service models where embedded monitoring, validation, and energy management interoperability determine vendor selection. This ecosystem inflection rewards suppliers that integrate IoT sensor networks with predictive contamination control software.
For Market Incumbents: Entrench position through backward integration into high-performance barrier fabric production and captive validation engineering capacity. DuPont's materials science portfolio and Illinois Tool Works' HVAC component dominance illustrate how upstream control over critical inputs defends margin structures against modular-as-a-service entrants. Certification investment in ISO 14644-1 commissioning expertise addresses the specialist engineer scarcity constraining regional project throughput.
For New Entrants and Emerging Players: Establish a beachhead in outsourced modular cleanroom leasing for Toronto-Montreal corridor biologics manufacturers navigating Health Canada MDR harmonization. Canadian facilities require cross-border validation protocols that incumbent US vendors underserve. Target hospital systems in Florida and Texas facing acute USP 797 compliance deadlines with standardized retrofit packages priced below premium pharmaceutical tiers.
For Investors and Strategic Acquirers: FDA modernization initiatives and USP 800 hazardous drug handling requirements reshape the acquisition landscape toward commissioning agents with FDA-facing documentation expertise and recurring service revenue models. Long-term viability centers on vendors capturing aftermarket validation contracts rather than pure equipment manufacturing. Watch Health Canada-EU GMP Annex 1 convergence timeline as signal for cross-border facility standardization investment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barrier Fabric Production | Captive supply of DuPont Tyvek-equivalent materials reduces input cost volatility for pharmaceutical apparel vendors. |
| Modular Cleanroom-as-a-Service Launch | Lease-based flexible suites with embedded validation reduce upfront capex barriers for emerging Boston-Cambridge biotechs. |
| Energy Recovery Ventilation Partnership | Heat recovery wheel integration addresses EPA efficiency mandates and IRA clean energy incentives in pharmaceutical HVAC specifications. |
| Cross-Border Validation Service Expansion | Toronto-Montreal corridor facilities require Health Canada-EU GMP Annex 1 compliant documentation protocols for multinational sponsors. |
| Digital Twin Platform Development | CFD modeling and IoT sensor networks compress commissioning cycles for cell and gene therapy manufacturing suites. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 483 inspection observations, USP compounding pharmacy compliance databases, and ISO 14644-1 certification records. Primary interviews with cleanroom engineering directors, pharmaceutical facility validation leads, hospital pharmacy compliance officers, and HVAC contractor procurement managers informed demand-side assumptions. Secondary validation drew from SEC 10-K filings of diversified materials conglomerates, Health Canada MDR guidance documents, and EPA energy efficiency mandate disclosures. Bottom-up project pipeline analysis across Massachusetts, New Jersey, and Pennsylvania manufacturing corridors triangulated against top-down market sizing from filtration media replacement cycle data.
Forecast inputs include facility construction permit tracking, biopharma venture financing velocity, and regulatory inspection frequency trends across the projection horizon. Segmentation modeling incorporates product type, application criticality, end-user procurement sophistication, and delivery mode preference. CAGRs derive from regression analysis of historical replacement cycles against projected biopharma manufacturing capacity expansion. Industry-specific inputs include USP 797 enforcement intensity by state pharmacy board and IRA clean energy incentive uptake rates in pharmaceutical HVAC specifications.
Sensitivities concentrate around borosilicate microfiber supply disruptions, Health Canada-EU GMP Annex 1 harmonization timeline acceleration, and qualified commissioning engineer availability constraints. Cross-checking against FDA sterile compounding inspection backlog data and state-level pharmacy board enforcement calendars is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Global Next Generation Computing Market
Emerging and Next Generation Technologies
Nanoparticle Technology Market
Emerging and Next Generation Technologies
Graphene Nanoplatelets Market
Emerging and Next Generation Technologies
Chipless RFID Market
Emerging and Next Generation Technologies
Transparent Solar Cells Market
Emerging and Next Generation Technologies
Next Gen TV (ATSC TV) Market
Emerging and Next Generation Technologies
Global WI SUN Technology Market
Emerging and Next Generation Technologies
Stretchable Electronics Market
Emerging and Next Generation Technologies
Asia Pacific Wigig Market
Emerging and Next Generation Technologies
Next-Generation Organic Solar Cell Market
Emerging and Next Generation Technologies
Nanodiamond Market
Emerging and Next Generation Technologies
In-Mold Electronics (IME) Market
Emerging and Next Generation Technologies
Laser Technology Market
Emerging and Next Generation Technologies
Spintronics Market
Emerging and Next Generation Technologies
Internet of Nano Things Market
Emerging and Next Generation Technologies
Global Hybrid Intelligence Market