
 Multi-Touch Technology Market | 2026-2036
Multi-Touch Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Touch Technology Market Foresight
Project finance for display-grade semiconductor foundries is tilting competitive advantage toward capital-rich participants. Samsung Electronics leverages captive OLED fabrication to dominate premium smartphone touch stacks. Apple sustains proprietary in-cell integration that compresses module thickness and narrows supplier lists. TPK Holding anchors industrial-grade projected capacitive supply for automotive tier-1s across East Asia.
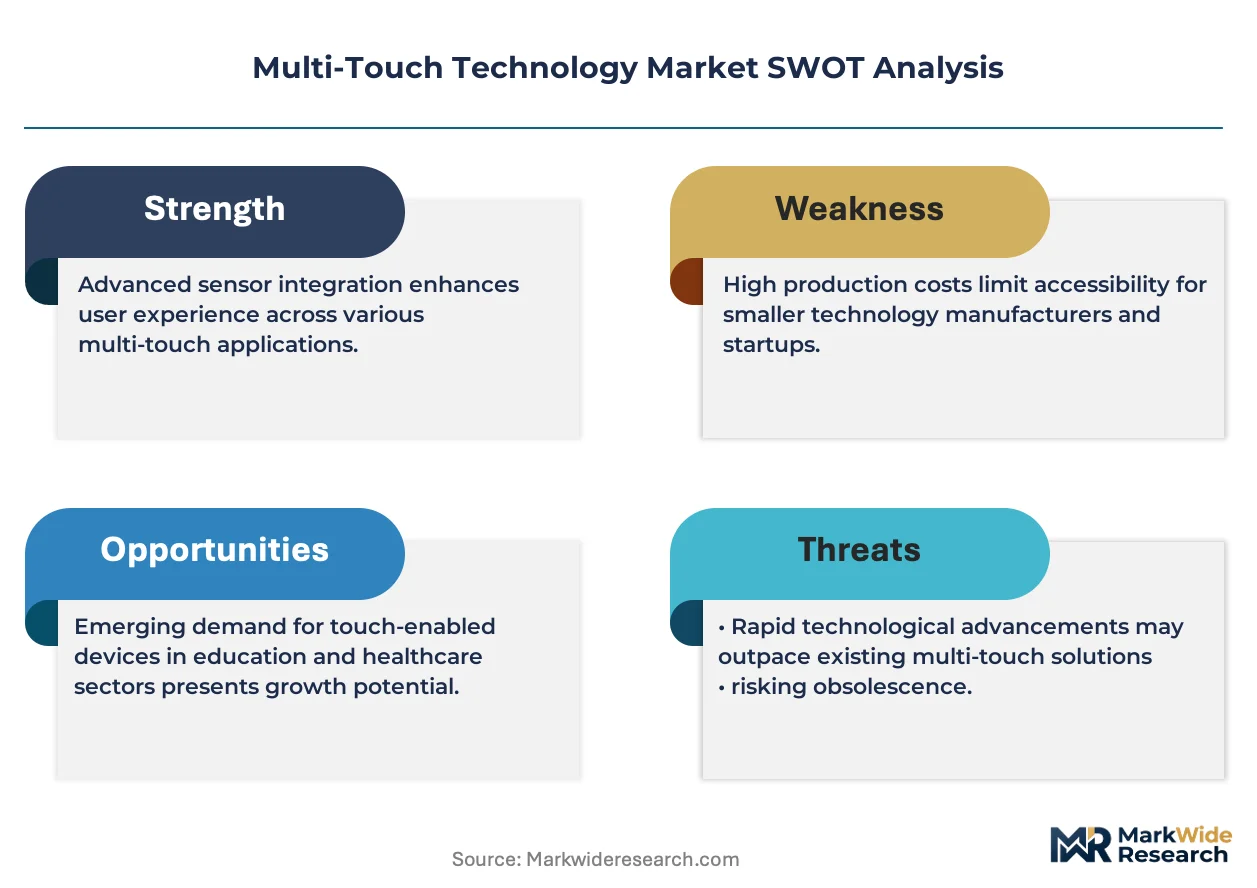
Multi-touch technology registers simultaneous contact points through capacitive, resistive, optical, or acoustic sensing layers bonded to glass or polymer substrates, with projected capacitive variants detecting finger position via inductive coupling at electrode intersections to enable gesture-driven human-machine interfaces. Capacitive technology leads in value terms due to its dominance in smartphones and tablets where multi-point precision and optical clarity command premium positioning. Kiosks and displays in retail and hospitality settings represent the fastest structural expansion as self-service terminals replace staffed counters. Optical and acoustic segments occupy narrower verticals where environmental durability or large-format scalability outweighs unit cost sensitivity.
FCC electromagnetic interference standards in the United States, CE marking under the EU's Radio Equipment Directive, and China's GB/T national standards for information technology equipment collectively dictate emission thresholds, safety testing protocols, and market access prerequisites for touch-enabled devices. Ecodesign regulations in Europe and evolving energy efficiency benchmarks from China's MIIT shape controller IC specifications and power budget requirements. Stakeholders must monitor divergence between regional certification regimes as modular platform strategies face escalating compliance fragmentation.
Market Dynamics
The automotive sector's pivot toward curved, multi-display cockpits is compressing touch module supply chains into fewer qualified suppliers capable of bonding flexible sensor films to non-planar glass.
Growth Catalysts
- Automotive Display Integration:OEM specifications for haptic feedback and glove-compatible operation in premium vehicle lines are expanding projected capacitive orders beyond consumer electronics.
- REACH RoHS Compliance:European material restrictions on heavy metals in indium tin oxide alternatives are accelerating adoption of silver nanowire and metal mesh conductive layers.
- Retail Self-Service Terminals:Quick-service restaurants and grocery chains in North America are replacing staffed checkout lanes with weatherized outdoor kiosks requiring optical bonding and anti-vandal glass.
Market Restraints
- Indium Supply Concentration:Over seventy percent of refined indium originates from Chinese zinc smelter byproduct recovery, exposing ITO sputtering targets to export quota volatility.
- Controller IC Lead Times:Fabless touch semiconductor vendors face allocation constraints at mature-node foundries serving automotive qualification requirements.
- Acoustic Pulse Recognition:Piezoelectric alternatives in large-format digital signage eliminate the need for conductive coatings on substrates exceeding eighty-five inches diagonal.
Strategic Opportunities
- Medical Device Interfaces:Sterilizable glass touch surfaces for surgical navigation systems remain underpenetrated relative to membrane switch legacy installations.
- India PLI Scheme:Production-linked incentives for electronic components manufacturing are attracting module assembly investments to Gujarat and Tamil Nadu clusters.
- Haptic-Display Convergence:Integration of localized vibration actuators directly beneath LCD layers enables programmable texture feedback without separate mechanical buttons.
Industry Challenges
- Automotive Qualification Cycles:AEC-Q100 stress testing and OEM-specific validation protocols extend touch controller development timelines to thirty-six months minimum.
- Cleanroom Capacity Bottlenecks:Class 1000 fabrication space for optical bonding operations concentrates in Taiwan and South Korea, constraining geographic diversification of module supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Touch Technology Market |
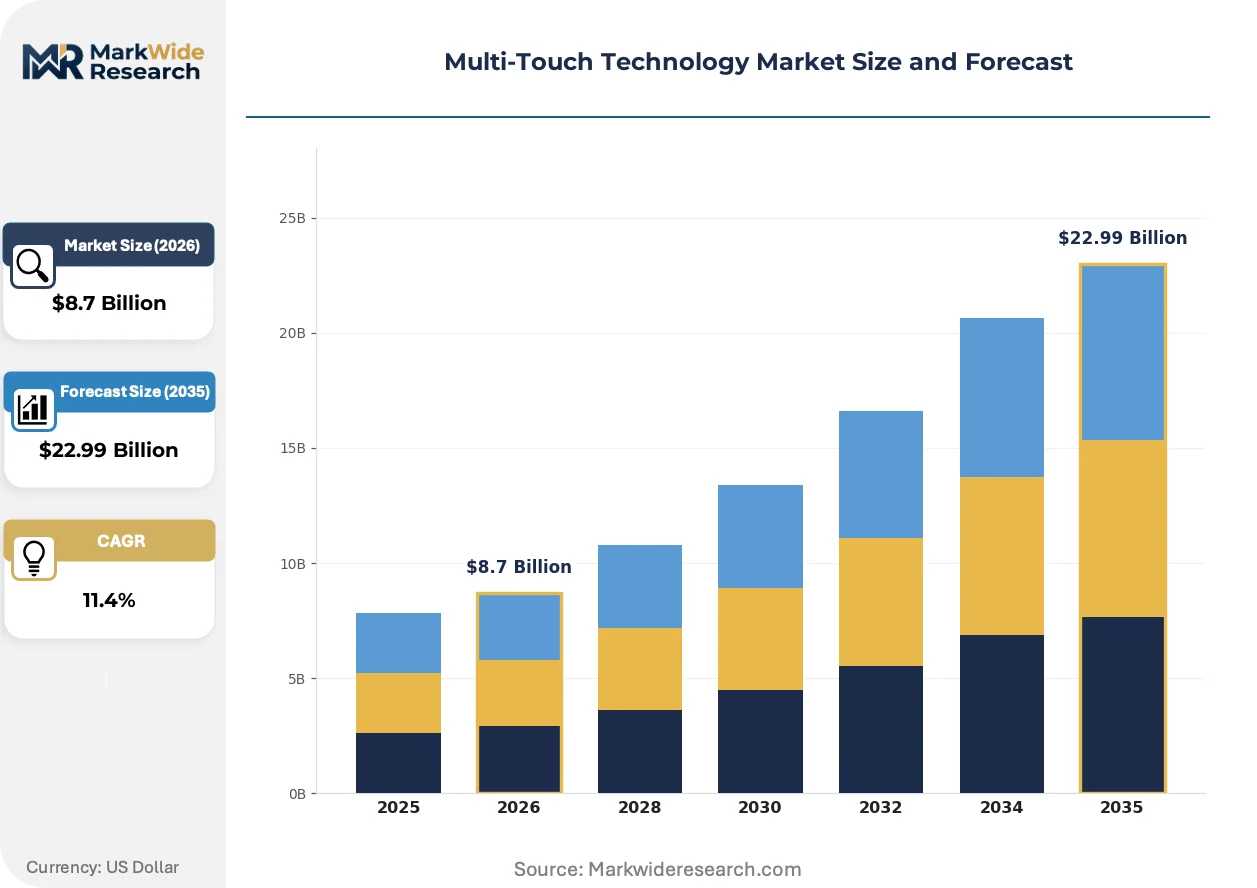
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Capacitive, Resistive, Optical, Acoustic Application: Consumer Electronics, Automotive, Gaming, Healthcare End User: Retail, Education, Hospitality, Industrial Product Type: Tablets, Smartphones, Kiosks, Displays |
| Companies Covered | Apple Inc., Samsung Electronics, Microsoft Corporation, TPK Holding Co., Ltd., LG Electronics Inc., 3M Company, Elo Touch Solutions Inc., Synaptics Incorporated, Fujitsu Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Touch Technology Market Shifts & Advancements
Touch interface architectures are fragmenting along application-specific performance vectors rather than converging on universal capacitive dominance, with each vertical demanding customized stack optimizations.
Metal mesh conductive films are virtualizing the traditional ITO monopoly in medium-format displays by enabling lower sheet resistance at equivalent optical transmission. Automotive tier-1s in Germany and Japan are qualifying hybrid silver-copper mesh patterns for curved instrument clusters. This substrate transition is virtualizing the procurement power of legacy sputtering equipment suppliers and compressing capital requirements for new conductive layer entrants.
The EU Ecodesign for Energy-related Products directive is mandating active power consumption ceilings for touch controllers in battery-operated equipment. Controller IC vendors must now demonstrate sub-milliwatt sleep states to maintain CE marking eligibility. Consumer tablet and laptop segments face the steepest redesign timelines as existing standby budgets exceed the 2027 phased thresholds.
Industrial buyers in factory automation are consolidating touch panel procurement through system integrators rather than direct module sourcing. Machine builder purchasing departments now specify complete HMI assemblies with pre-certified environmental ratings. This channel consolidation is most pronounced in German and Japanese manufacturing equipment markets where liability exposure drives bundled subsystem accountability.
Multi-Touch Technology Market Segmentation
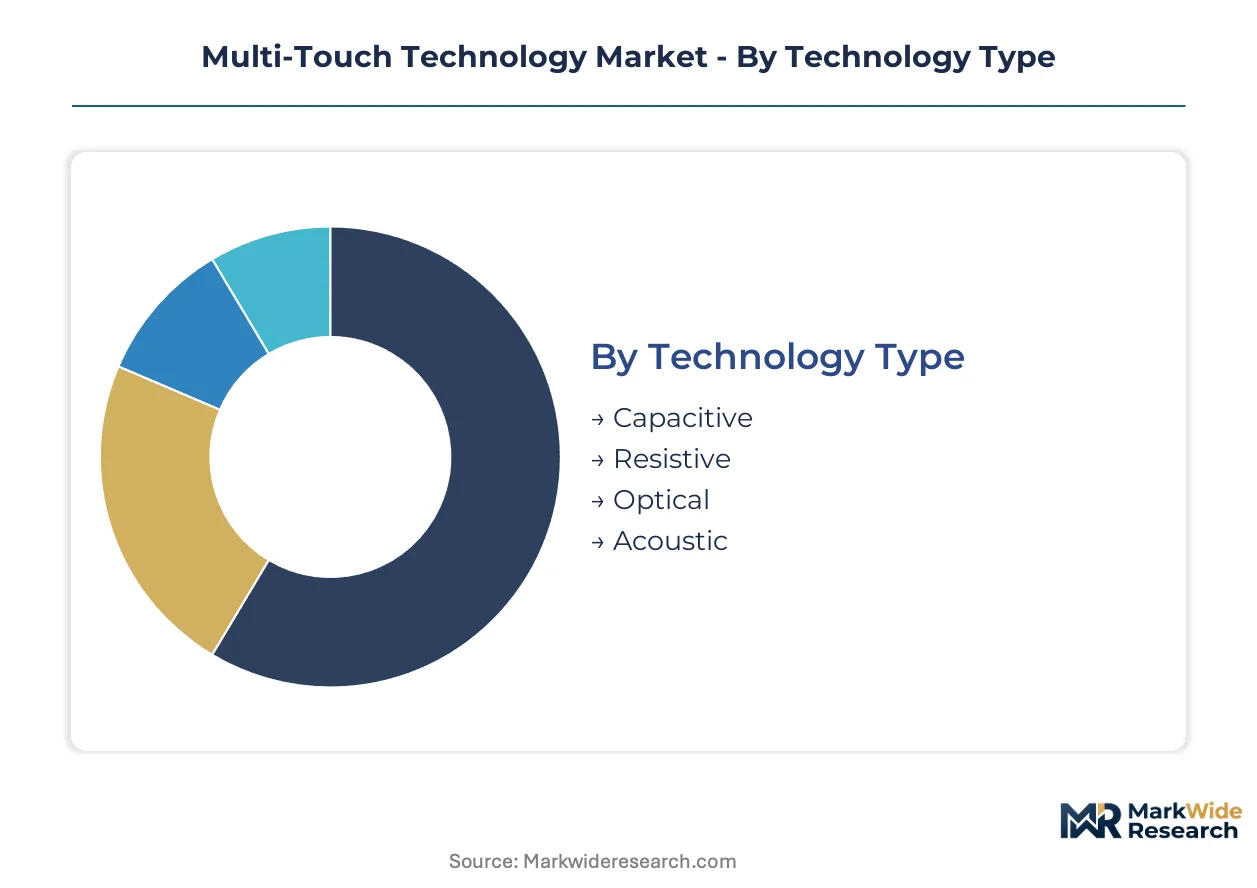
Multi-touch technology fragments across four distinct category axes, each commanding different procurement cycles and margin structures. Technology type determines controller IC architecture and qualification timelines, while application verticals dictate environmental durability requirements and certification pathways.
Technology Type:
Capacitive variants refresh on 18-month consumer electronics cycles, whereas acoustic and optical technologies persist for 7-10 years in industrial deployments.
- Capacitive:Projected capacitive variants detect finger position through inductive coupling at indium tin oxide electrode intersections, enabling multi-point precision in smartphones and tablets. Automotive OEMs in Germany and Japan are now qualifying silver nanowire alternatives to reduce indium dependency for curved instrument clusters.
- Resistive:Pressure-sensitive layers separated by air gaps or microdots respond to stylus and gloved input in legacy industrial panels. Demand concentrates in factory automation HMI systems across the US Midwest and Japan's Kansai manufacturing belt where electromagnetic immunity outweighs optical clarity requirements.
- Optical:Infrared grid arrays enable scale-agnostic sensing for digital signage exceeding eighty-five inches diagonal without conductive coatings.
- Acoustic:Surface acoustic wave and bending wave technologies leverage piezoelectric transducers for vandal-resistant outdoor kiosks.
Capacitive dominates installed base. Optical is where expansion concentrates for large-format retail and transportation infrastructure.
Application:
Consumer electronics commands the steepest volume concentration, while automotive and healthcare segments extract premium pricing through extended qualification protocols.
- Consumer Electronics:Smartphones, tablets, and wearable devices absorb the majority of projected capacitive controller IC output, with OEMs specifying sub-milliwatt sleep states to meet EU Ecodesign thresholds. Samsung Electronics and Apple compress supplier lists through captive OLED fabrication and in-cell integration respectively.
- Automotive:Curved multi-display cockpits require flexible sensor films bonded to non-planar glass with AEC-Q100 qualification cycles extending to thirty-six months minimum. Tier-1 suppliers in Germany and Japan are consolidating procurement through qualified module vendors capable of optical bonding in Class 1000 cleanrooms.
- Gaming:Arcade machines and casino terminals demand vandal-resistant glass and haptic feedback integration.
- Healthcare:Sterilizable glass touch surfaces for surgical navigation systems remain underpenetrated relative to membrane switch legacy installations in US hospital networks.
Consumer electronics commands volume scale. Healthcare offers the steepest expansion trajectory for specialized sterilizable interfaces.
End User:
Retail and hospitality procurement runs through system integrators, while industrial buyers specify complete HMI assemblies with pre-certified environmental ratings.
- Retail:Quick-service restaurants and grocery chains across North America are replacing staffed checkout lanes with weatherized outdoor kiosks requiring optical bonding and anti-vandal glass specifications.
- Education:Interactive whiteboards and collaborative learning panels concentrate demand in South Korean and Chinese procurement cycles tied to school infrastructure budgets.
- Hospitality:Self-service check-in terminals and in-room control panels prioritize aesthetic integration over technical performance.
- Industrial:Machine builder purchasing departments in Germany and Japan now bundle touch panel accountability with complete subsystem liability exposure.
Industrial anchors replacement demand. Retail is expanding most quickly through self-service terminal deployment.
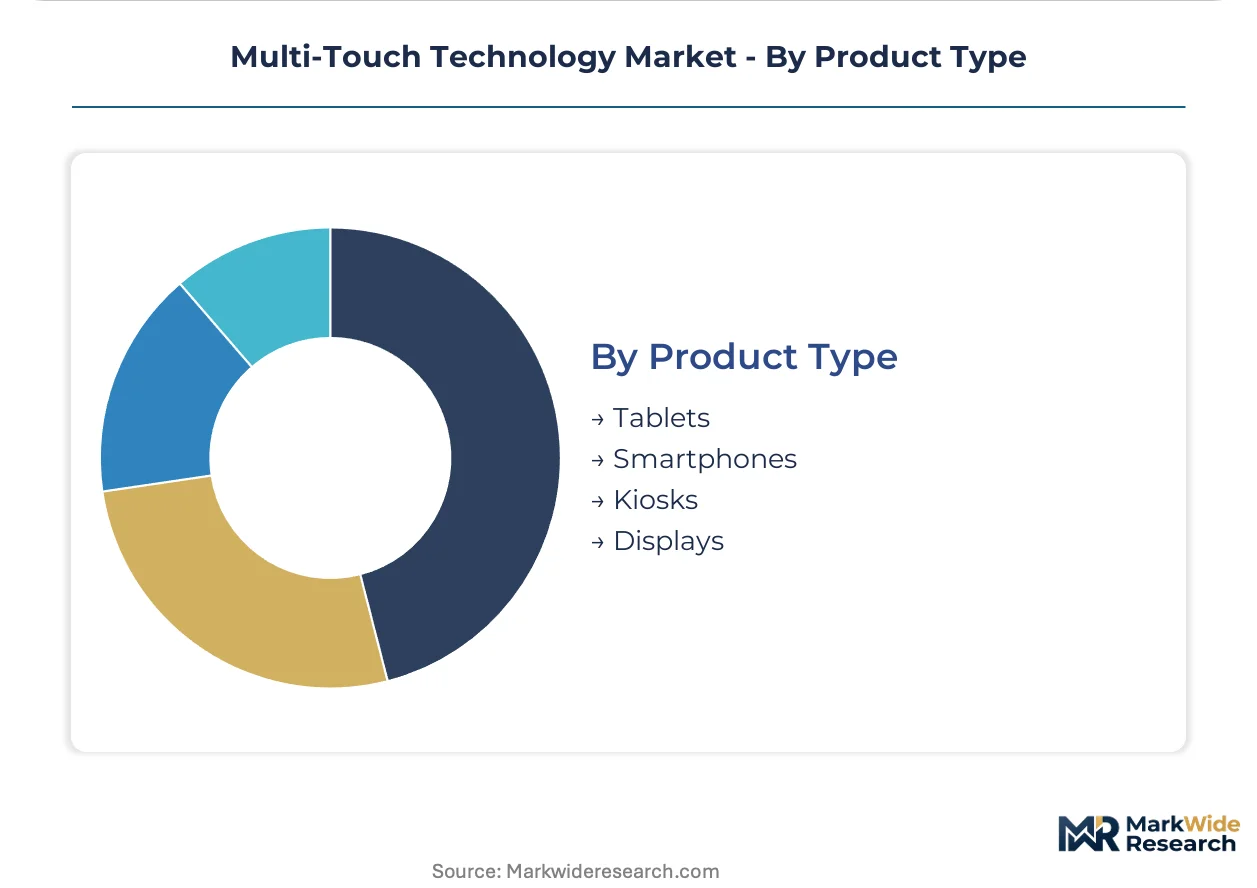
Product Type:
Smartphones and tablets concentrate controller IC innovation, while kiosks and specialized displays fragment across application-specific durability requirements.
- Smartphones:In-cell and on-cell integration compresses module thickness to sub-millimeter specifications, with Apple sustaining proprietary processes that narrow supplier participation. FCC electromagnetic interference standards and CE marking under the EU's Radio Equipment Directive govern emission thresholds.
- Tablets:Enterprise and education deployments face the steepest redesign timelines as EU Ecodesign phased thresholds force sub-milliwatt standby consumption compliance.
- Kiosks:Outdoor quick-service restaurant terminals in North America specify IP65 ingress protection and heater elements for cold-climate operation.
- Displays:Large-format digital signage exceeding eighty-five inches diagonal increasingly adopts acoustic pulse recognition to eliminate conductive coating requirements.
Smartphones dominate controller IC volume. Kiosks represent the fastest-climbing product category through retail automation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China runs a substantial trade surplus in capacitive touch sensor components, while the United States and Germany remain net importers of display-grade controller ICs. Korea and Taiwan balance specialized exports of optical bonding equipment against raw material dependencies.
China
MIIT's GB/T standards for information technology equipment govern emission thresholds for touch-enabled devices, while the country's dual carbon goals pressure manufacturers toward lower-power controller specifications. Guangdong and Jiangsu provinces concentrate the heaviest procurement volume for capacitive touch sensor production, with Shenzhen-based module assemblers feeding global smartphone supply chains.
United States
FCC electromagnetic interference standards dictate market access prerequisites for consumer electronics, while quick-service restaurant chains across Texas and California drive weatherized outdoor kiosk specifications. The Pacific Northwest anchors cleanroom-dependent optical bonding operations serving aerospace and medical device contracts.
Germany
REACH and RoHS compliance mandates accelerate silver nanowire adoption as indium tin oxide alternatives, with KBA oversight extending to automotive HMI safety certifications. Bavaria's automotive tier-1 suppliers consolidate procurement through qualified module vendors capable of curved display bonding for premium vehicle lines.
South Korea
METI-coordinated standards alignment supports export competitiveness, though domestic demand concentrates in Seoul Capital Area display fabs. Samsung Electronics leverages captive OLED fabrication to dominate premium smartphone touch stacks, compressing supplier lists for in-cell integration processes.
Japan
JIS standards for industrial equipment shape factory automation HMI durability requirements, with METI oversight of semiconductor material flows. Kansai manufacturing belt machine builders now bundle touch panel accountability with complete subsystem procurement, channeling demand through system integrators rather than direct module sourcing.
Multi-Touch Technology Market Competitive Landscape
On the supply side, the industry is consolidating around capital-rich participants capable of financing display-grade semiconductor foundries and captive OLED fabrication. Three strategic archetypes dominate: vertically integrated electronics conglomerates controlling upstream sensor production, specialized touch module vendors with cleanroom bonding capabilities, and fabless controller IC designers reliant on mature-node foundry allocation. Competitive moves center on AEC-Q100 automotive qualification investments and geographic diversification of optical bonding capacity beyond Taiwan and South Korea.
Among Asia-Pacific-based fabricators, TPK Holding Co., Ltd. anchors industrial-grade projected capacitive supply for automotive tier-1s, while Samsung Electronics exemplifies the captive-integration archetype through in-house OLED and touch stack production. Apple Inc. occupies a proprietary position through sustained in-cell integration that compresses module thickness and narrows external supplier participation.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| Microsoft Corporation |
| TPK Holding Co., Ltd. |
| LG Electronics Inc. |
| 3M Company |
| Elo Touch Solutions Inc. |
| Synaptics Incorporated |
| Fujitsu Limited |
| Others |
Supply & Pricing Matrix
Indium supply concentration from Chinese zinc smelter byproduct recovery determines both the spread between premium automotive-grade touch stacks and economy tablet modules and the geographic clustering of ITO sputtering capacity. This single-source dependency compresses margins for mid-tier module vendors while rewarding backward integration into silver nanowire alternatives.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on AEC-Q100 certification grade and volume scale, with automotive tier-1s paying substantial premiums for thirty-six-month qualification cycles. Cost compression in consumer electronics tiers is intensifying because of fabless controller IC allocation constraints at mature-node foundries. Quick-service restaurant chains in North America demonstrate highest price sensitivity, while German automotive OEMs prioritize liability bundling over unit cost.
Supply Chain Analysis
Export controls on semiconductor manufacturing equipment limit flows of advanced lithography tools to Chinese display-grade foundries, reshaping regional competitive dynamics. Manufacturing concentrates in China, Taiwan, and South Korea, with Guangdong and Jiangsu provinces hosting the heaviest capacitive sensor assembly. Raw material flows draw from refined indium, silver nanowire conductive films, and projected capacitive controller ICs. Single-source vulnerability in ITO sputtering targets exposes procurement to export quota volatility. Distribution runs through automotive tier-1 suppliers in Germany and Japan and direct module sourcing for consumer electronics OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The multi-touch technology market sits at an inflection where EU Ecodesign power ceilings and automotive curved-display specifications are simultaneously rewriting controller IC architectures and module bonding requirements.
For Market Incumbents: Pre-empt displacement from acoustic pulse recognition in large-format signage by accelerating silver nanowire qualification for curved automotive clusters. Lock in Class 1000 cleanroom capacity expansion beyond Taiwan and South Korea before geographic diversification becomes a tier-1 procurement mandate. Prioritize AEC-Q100 certification pipelines to defend automotive revenue pools against emerging module vendors.
For New Entrants and Emerging Players: Pursue the underpenetrated surgical navigation interface segment where sterilizable glass touch surfaces remain minority share against membrane switch legacy. Establish beachheads in Gujarat and Tamil Nadu module assembly clusters under India's PLI scheme for electronic components. Lead with haptic-display convergence as a differentiated value proposition for gaming and industrial HMI applications.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors capital-rich participants with captive OLED fabrication or cleanroom bonding capabilities. Five-to-ten-year viability hinges on automotive qualification moats and regulatory compliance infrastructure rather than consumer electronics volume scale. Watch for MIIT energy efficiency benchmarks tightening beyond current GB/T standards as the signal for controller IC vendor shakeout timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Silver Nanowire Qualification | Reduces indium dependency for curved automotive instrument clusters under REACH compliance. |
| Class 1000 Cleanroom Expansion | Enables optical bonding capacity diversification beyond Taiwan and South Korea for tier-1 procurement. |
| AEC-Q100 Certification Pipeline | Extends automotive controller IC development timelines to thirty-six months minimum, creating qualification moats. |
| Haptic-Display Convergence | Integrates localized vibration actuators beneath LCD layers for programmable texture feedback in gaming terminals. |
| India PLI Module Assembly | Attracts production-linked incentive investments to Gujarat and Tamil Nadu clusters for geographic risk distribution. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with touch controller IC designers, automotive tier-1 procurement officers, display module bonding engineers, and retail kiosk system integrators; and secondary validation against SEC filings from fabless semiconductor vendors, MIIT energy efficiency disclosures, EU Ecodesign directive implementation documents, and customs trade data for indium and silver nanowire flows. Bottom-up and top-down triangulation cross-checked unit volume assumptions against foundry capacity utilization and OEM display procurement disclosures.
Forecast inputs span technology type, application vertical, end-user segment, and product category dimensions across the analysis window. CAGRs derive from segment-level growth trajectory blending rather than aggregate market extrapolation. Automotive display integration intensity, EU Ecodesign compliance timelines, and indium price volatility indices feed directly into the projection framework.
Sensitivities concentrate around export quota volatility for refined indium, AEC-Q100 qualification timeline extensions, and divergence between regional certification regimes. Forecasts reflect documented assumptions on foundry allocation constraints and tier-1 supplier consolidation patterns. Material shifts in Chinese semiconductor equipment access or EU active power consumption ceiling enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Switchable Smart Film Market
Emerging and Next Generation Technologies
Microfluidics Prototype Market
Emerging and Next Generation Technologies
Ultra-Fine Ath Market
Emerging and Next Generation Technologies
Global Electronic Design Automation (EDA) Market
Emerging and Next Generation Technologies
Transparent Electronics Market
Emerging and Next Generation Technologies
3D Xpoint Technology Market
Emerging and Next Generation Technologies
Global Ultrafast Lasers Market
Emerging and Next Generation Technologies
Global Digital Twin Technology Market
Emerging and Next Generation Technologies
North America Cleanroom Technology Market
Emerging and Next Generation Technologies
Third-Generation Solar Cells Market
Emerging and Next Generation Technologies
Nanoelectronics Market
Emerging and Next Generation Technologies
AI Edge Computing Market
Emerging and Next Generation Technologies
Programmable Semiconductor Technologies Market
Emerging and Next Generation Technologies
Global Metamaterial Market
Emerging and Next Generation Technologies
Global Nano Batteries Market
Emerging and Next Generation Technologies
Asia Pacific Wigig Market