
 North America Quantum Computing Market | 2026-2036
North America Quantum Computing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Quantum Computing Market Insights
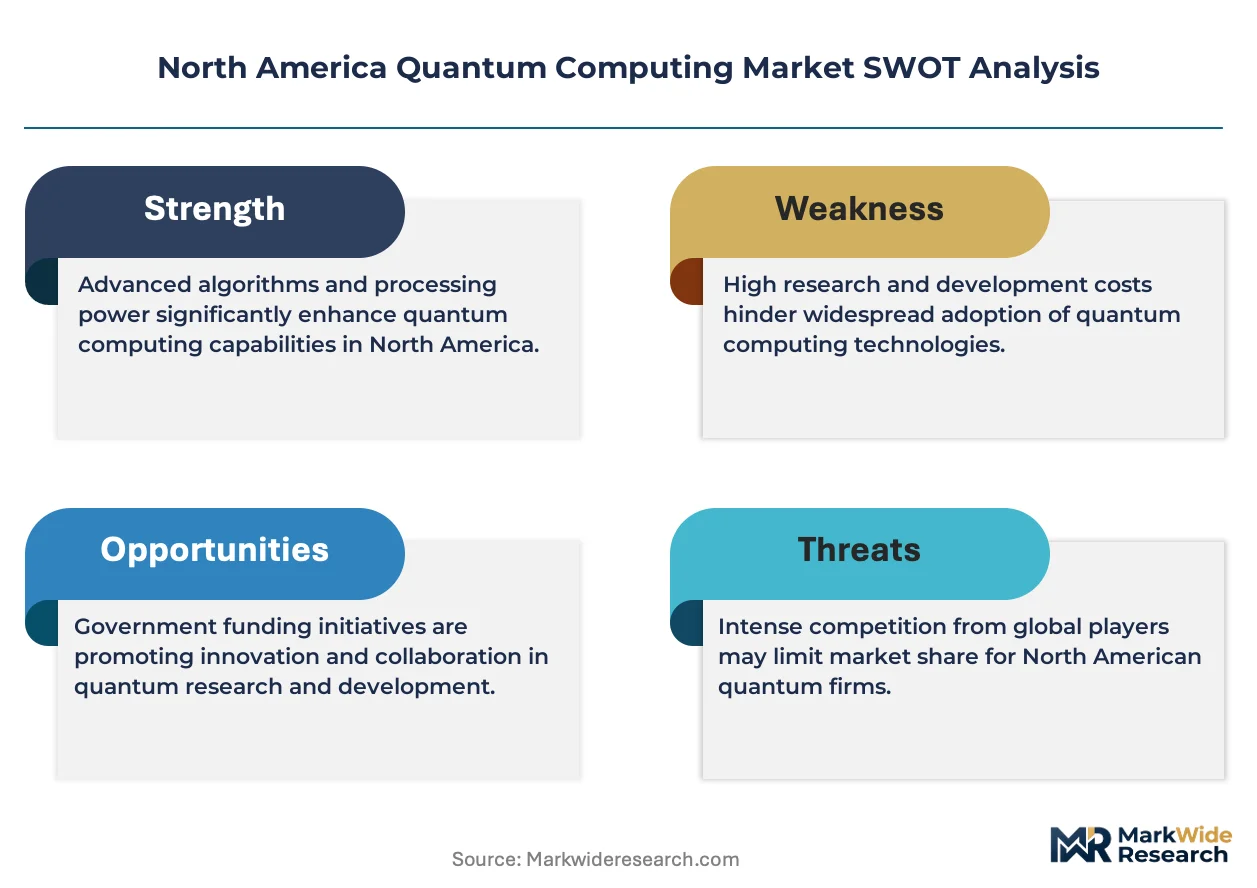
Pharmaceutical demand is pivoting toward quantum-accelerated drug discovery pipelines as molecular complexity outstrips classical simulation limits. IBM leverages its superconducting qubit roadmap to anchor enterprise adoption across government and BFSI clients. Quantinuum specializes in trapped-ion systems for high-fidelity cryptographic applications. D-Wave Quantum dominates annealing-based optimization for logistics and financial modeling workloads.
North America quantum computing encompasses hardware, software, and cloud-based platforms that manipulate quantum mechanical phenomena—superposition, entanglement, and interference—to process information at scales inaccessible to classical transistor-based systems. Superconducting qubits currently lead hardware deployments due to mature fabrication compatibility with existing semiconductor foundries, while trapped-ion architectures capture premium segments requiring longer coherence times and lower error rates. Cloud-based solutions are expanding fastest among mid-sized enterprises seeking pay-per-use access without capital-intensive infrastructure commitments.
The National Quantum Initiative Act and NIST post-quantum cryptography standards shape federal procurement timelines and security compliance requirements across BFSI and government end users. FDA engagement with quantum-enhanced drug discovery tools signals emerging regulatory frameworks for computational validation in pharmaceutical submissions. Stakeholders must monitor NIST standardization milestones and federal grant disbursement rhythms to time platform investments and partnership strategies effectively.
Market Dynamics
Federal procurement timelines under the National Quantum Initiative Act are compressing vendor qualification cycles while NIST post-quantum cryptography standards reshape security compliance requirements across BFSI and defense contractors.
Growth Catalysts
- Pharmaceutical molecular simulation:Drug developers are deploying quantum-accelerated pipelines as classical supercomputing hits computational limits on protein folding complexity.
- National Quantum Initiative Act:Federal R&D disbursements are expanding domestic fabrication capacity for superconducting qubit foundries.
- Silicon Valley cluster density:California's venture concentration is attracting trapped-ion engineering talent from academic physics departments.
Market Restraints
- Dilution refrigerator supply concentration:Cryogenic cooling hardware depends on a limited set of specialized European and Japanese component suppliers.
- Error correction overhead:Logical qubit requirements demand physical qubit counts that strain current fabrication yields.
- NIST compliance friction:Post-quantum cryptography migration timelines create procurement hesitation among risk-averse government buyers.
Strategic Opportunities
- Boston Route 128 corridor:Massachusetts-based biotech clusters represent underpenetrated demand for quantum-chemistry simulation services.
- Cloud access models:Pay-per-use platforms are opening mid-sized enterprise adoption without capital-intensive infrastructure commitments.
- AI-quantum convergence:Hybrid machine-learning optimization workloads are creating new algorithmic service categories.
Industry Challenges
- Cryogenic engineering talent scarcity:PhD-level quantum physicists with systems integration experience command compensation premiums that strain startup burn rates.
- Legacy security architecture retrofit:Financial institutions face multi-year integration timelines to embed quantum-resistant encryption without disrupting transaction processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Quantum Computing Market |
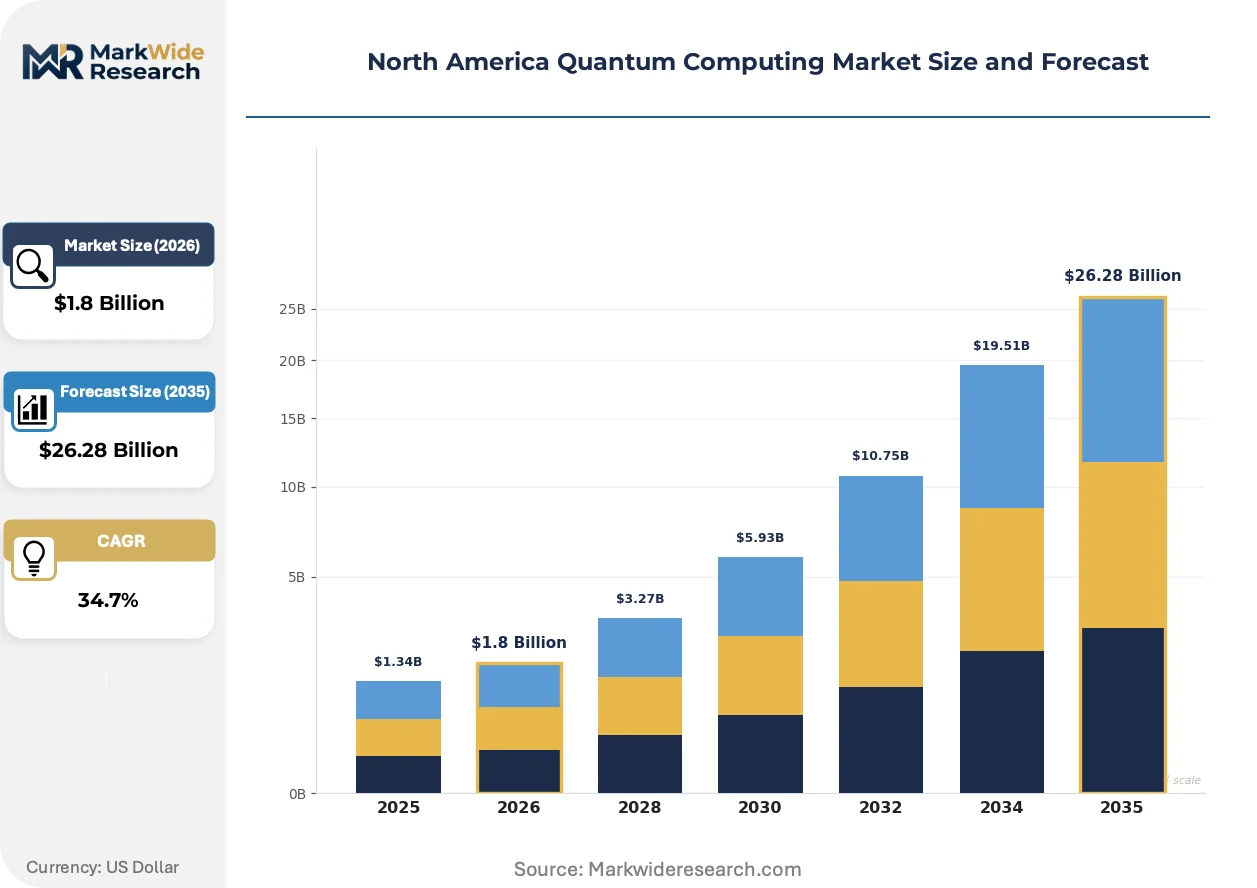
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $26.28 Billion |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Cloud-Based Solutions, Quantum Accelerators End User: Government, BFSI, Healthcare, Aerospace Technology: Superconducting Qubits, Trapped Ions, Topological Qubits, Photonic Quantum Computing Application: Cryptography, Optimization, Drug Discovery, Financial Modeling |
| Companies Covered | IBM, Microsoft, Amazon Web Services, D-Wave Quantum, Rigetti Computing, IonQ, Google, Intel, Quantinuum, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Quantum Computing Market Trends and Innovations
Superconducting qubit roadmaps are accelerating while trapped-ion architectures capture premium fidelity segments, and cloud-based delivery models are democratizing access beyond national laboratory and hyperscaler incumbents.
Superconducting transmon qubits leverage mature semiconductor foundry processes to achieve 1000+ qubit densities. Pharmaceutical firms and government laboratories are adopting these systems for near-term optimization workloads. This fabrication compatibility is rewriting capital efficiency assumptions for hardware scaling.
The FDA has initiated engagement protocols for quantum-enhanced computational chemistry in drug discovery submissions. This regulatory attention is forcing submission templates to accommodate algorithmic validation methodologies. Early-stage biotech developers in California and Massachusetts are restructuring their IND packages to preempt review friction.
Enterprise buyers are unbundling quantum computing from traditional HPC procurement contracts. Mid-sized financial services firms are accessing trapped-ion systems through specialized cloud brokers rather than building captive infrastructure. This channel innovation is most visible in Chicago's derivatives trading community and Toronto's quantitative asset management sector.
North America Quantum Computing Market Segmentation
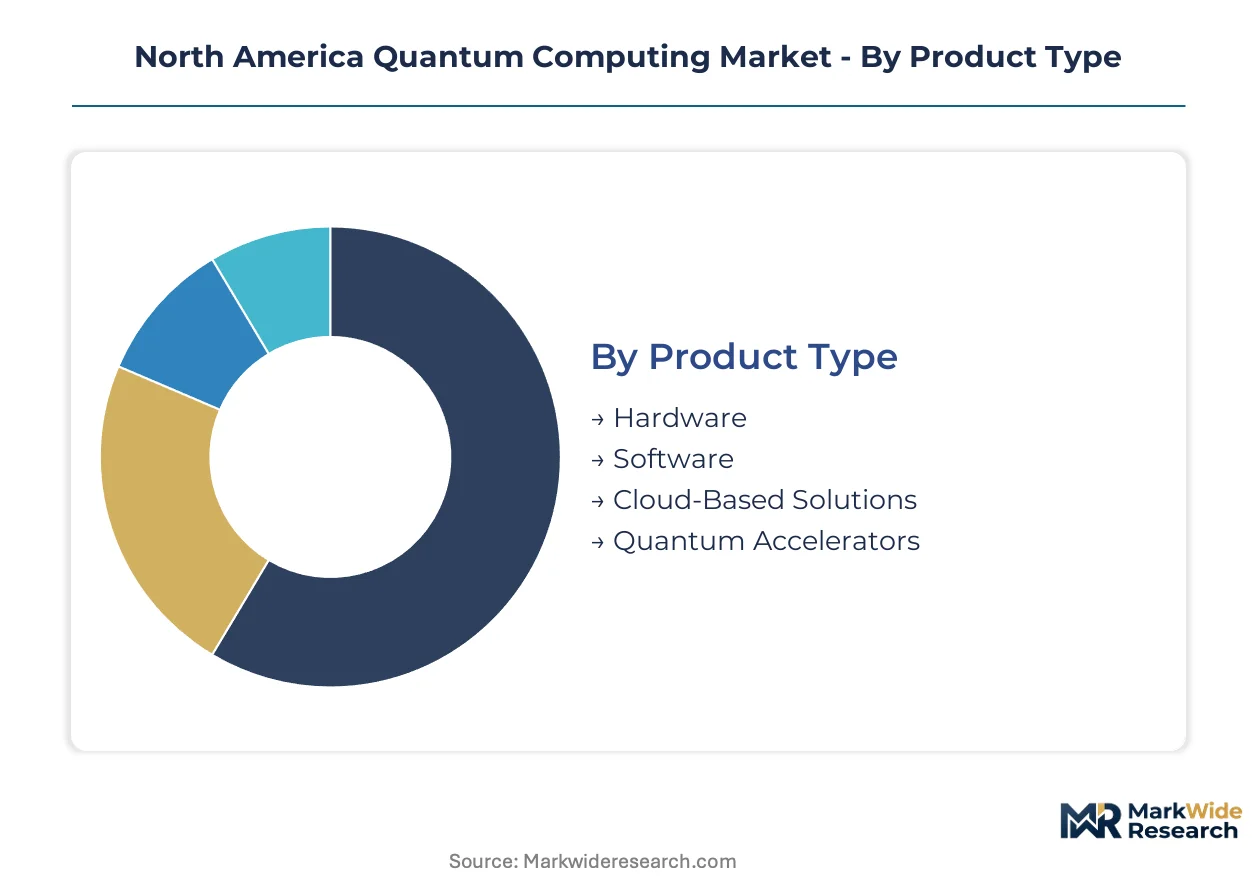
Segmentation reveals how quantum computing value flows across distinct technology maturity curves and buyer risk profiles. Hardware and government procurement anchor near-term revenue, while cloud delivery and pharmaceutical applications are capturing growth-oriented investment.
Product Type:
Hardware commands premium pricing through cryogenic infrastructure requirements, while cloud-based solutions are scaling fastest through pay-per-use accessibility.
- Hardware:Dilution refrigerators, control electronics, and qubit processor assemblies form the capital-intensive foundation. Demand concentrates in Department of Energy national laboratories and IBM's Yorktown Heights research campus, constrained by European and Japanese cryogenic component supply bottlenecks.
- Cloud-Based Solutions:API-accessible quantum processing units allow enterprises to execute circuits without captive infrastructure. Mid-sized financial services firms in Chicago and Toronto are adopting these platforms fastest, driven by derivatives pricing workloads that outstrip classical Monte Carlo simulation speeds.
- Software:Circuit compilers, error mitigation algorithms, and quantum-classical hybrid orchestration tools. IBM Qiskit and open-source alternatives dominate development environments across academic physics departments.
- Quantum Accelerators:Specialized coprocessors for specific algorithmic classes including quantum annealing units. D-Wave systems serve logistics optimization contracts from Vancouver to Los Angeles port authorities.
Mature deployment sits with Hardware. Newer deployment is concentrated in Cloud-Based Solutions.
End User:
Government contracts provide revenue stability through multi-year R&D programs, while healthcare applications are expanding most quickly through FDA engagement with computational chemistry validation.
- Government:National laboratories, defense agencies, and intelligence community procurement under the National Quantum Initiative Act. Sandia National Laboratories and Oak Ridge National Laboratory operate the largest superconducting qubit installations, constrained by NIST post-quantum cryptography compliance timelines.
- Healthcare:Pharmaceutical molecular simulation and computational biology workloads. Biotech clusters in Boston's Route 128 corridor and South San Francisco are restructuring IND submission packages to incorporate quantum-enhanced protein folding data.
- BFSI:Portfolio optimization, risk modeling, and fraud detection across investment banks and quantitative hedge funds. JPMorgan Chase and Goldman Sachs maintain dedicated quantum research groups.
- Aerospace:Materials science simulation and flight path optimization. Boeing's quantum research unit collaborates with academic partners on corrosion-resistant alloy discovery.
Procurement stability centers on Government. Steepest expansion trajectory is visible in Healthcare.
Technology:
Superconducting qubits leverage semiconductor foundry compatibility for volume manufacturing, while trapped-ion architectures command fidelity premiums in cryptographic applications.
- Superconducting Qubits:Transmon and fluxonium designs fabricated on silicon substrates using modified CMOS processes. IBM and Google have exceeded 1000-qubit processor densities, with foundry partnerships concentrated in upstate New York and Santa Barbara.
- Trapped Ions:Ytterbium and calcium ion chains manipulated by laser pulses in ultra-high vacuum chambers. Quantinuum's Boulder and Seattle facilities serve government clients requiring gate fidelities above 99.9% for cryptographic key distribution.
- Topological Qubits:Microsoft Azure Quantum pursues Majorana zero-mode-based designs for intrinsic error protection. Research concentrates in Redmond and Copenhagen partnerships, with no commercial systems yet deployed.
- Photonic Quantum Computing:Linear optical quantum computing using squeezed light states and beam splitter networks. PsiQuantum's Palo Alto operations target fault-tolerant systems through silicon photonics manufacturing.
Commercial maturity sits with Superconducting Qubits. Emerging deployment concentrates in Photonic Quantum Computing.
Application:
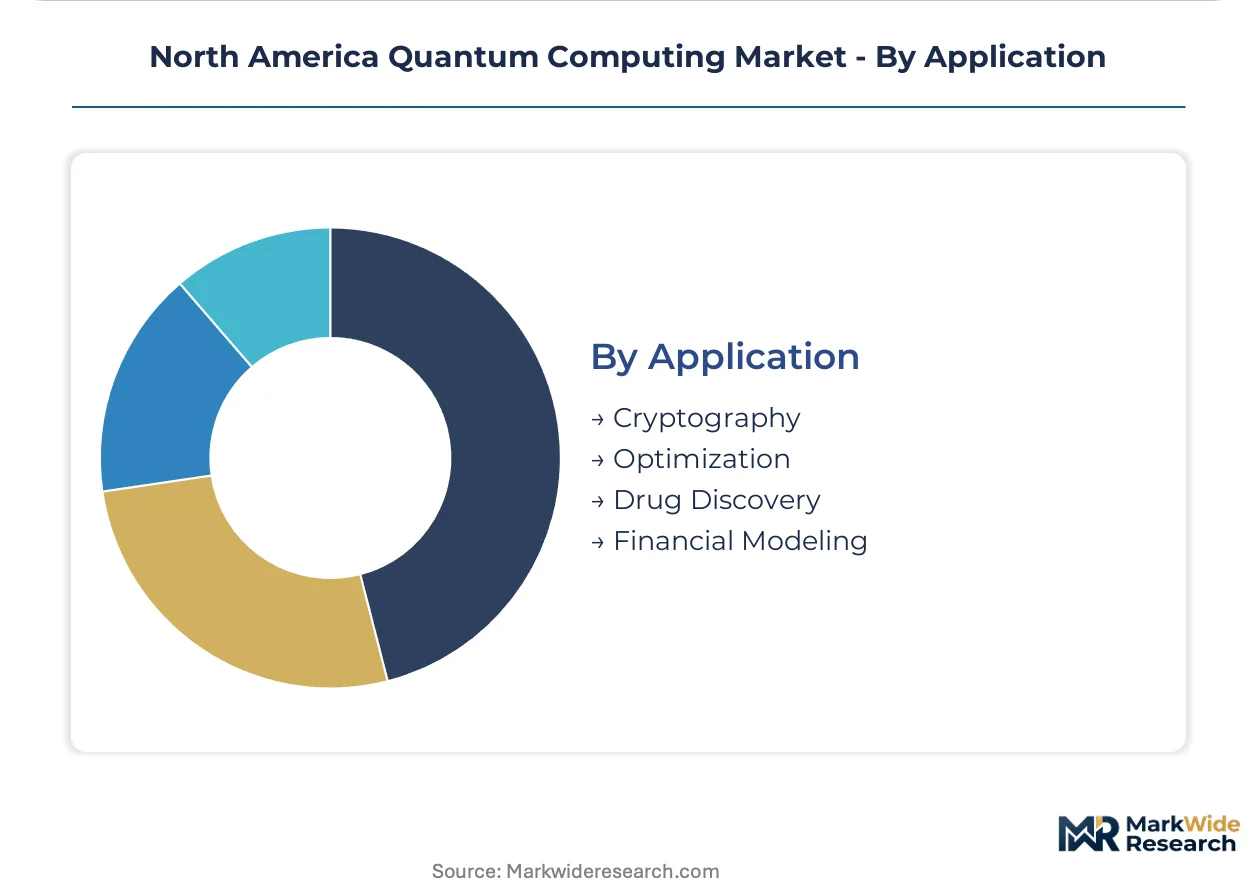
Optimization workloads deliver near-term utility on noisy intermediate-scale quantum devices, while drug discovery applications are climbing fastest through FDA regulatory pathway development.
- Optimization:Combinatorial problems including supply chain routing, portfolio allocation, and manufacturing scheduling. D-Wave annealers process thousands of variables for Volkswagen's traffic flow management and ExxonMobil's maritime routing.
- Drug Discovery:Molecular dynamics simulation for protein-ligand binding affinity prediction. Roche and Biogen are piloting quantum-classical hybrid algorithms for Alzheimer's target identification, constrained by classical verification requirements for regulatory submission.
- Cryptography:Quantum key distribution and post-quantum cryptographic protocol testing. Financial clearinghouses in New York and Chicago are evaluating quantum-resistant signature schemes against NIST standardization timelines.
- Financial Modeling:Monte Carlo acceleration for derivatives pricing and credit risk simulation. Chicago Mercantile Exchange members access trapped-ion systems through specialized cloud brokers for overnight risk recalculation.
Operational maturity sits with Optimization. Gaining share fastest is Drug Discovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research Triangle Park and similar innovation zones across North America concentrate quantum R&D through targeted federal tax incentives and state-level matching funds. These designated districts anchor the continent's hardware fabrication and algorithm development pipelines.
United States
National laboratories at Oak Ridge and Sandia drive superconducting qubit procurement under Department of Energy contracts. The National Quantum Initiative Act channels federal disbursements toward domestic foundry capacity in New York and Arizona. Silicon Valley clusters in Santa Clara County attract trapped-ion engineering talent from Stanford and Berkeley physics departments.
Canada
Waterloo's quantum valley anchors photonics research through the Perimeter Institute and University of Waterloo partnerships. The country's national research council funds quantum-safe cryptography pilots for financial clearinghouses. Toronto's quantitative asset management sector accesses cloud-based annealing systems through specialized brokers.
Mexico
Monterrey's engineering institutes supply cryogenic technician training for cross-border hardware maintenance contracts. The central bank monitors NIST post-quantum cryptography timelines to align domestic financial infrastructure migration. Guadalajara's software development clusters contribute quantum-classical hybrid algorithm talent to North American service providers.
North America Quantum Computing Market Competitive Landscape
Top-tier vendors anchor government and hyperscaler procurement, while mid-scale specialists capture cloud delivery and niche application segments. The vendor base stratifies across three tiers: integrated hardware-software stacks, pure-play cloud platforms, and component subsystem suppliers. Strategic archetypes include superconducting foundry operators, trapped-ion fidelity specialists, and quantum-annealing optimization providers. Competitive moves concentrate on strategic partnerships with national laboratories and technology licensing for cloud access models.
Within the integrated hardware-software tier, IBM and Google exemplify superconducting roadmap execution through foundry partnerships and enterprise cloud integration. Quantinuum occupies a position in the trapped-ion fidelity segment, serving cryptographic applications requiring gate precision above 99.9%. D-Wave Quantum anchors the quantum-annealing archetype for combinatorial optimization workloads across logistics and financial modeling.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| Amazon Web Services |
| D-Wave Quantum |
| Rigetti Computing |
| IonQ |
| Intel |
| Quantinuum |
| Others |
Pricing and Supply Chain Analysis
PhD-level cryogenic engineering talent concentrated in Boulder and Waterloo commands compensation premiums that widen spreads between premium-tier trapped-ion systems and standard superconducting qubit offerings. Labor-cost differentials between these specialized physics clusters and emerging training programs in Monterrey directly shape three-tier pricing structures across hardware procurement contracts.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent national laboratory procurements from scheduled enterprise cloud deployments. Premium pricing attaches to sub-90-day cryogenic component delivery for Department of Energy facilities, while spot-access cloud credits trade at discounts for pre-scheduled batch workloads. Price differentiation rests on gate fidelity certification tiers and geographic proximity to dilution refrigerator maintenance hubs. Cost compression in mid-tier superconducting systems intensifies as IBM and Google expand foundry partnerships. Government buyers demonstrate lowest price sensitivity given NIST compliance mandates, while mid-sized financial services firms in Chicago exhibit highest elasticity to per-qubit-minute rates.
Supply Chain Analysis
Dual-sourcing requirements from Sandia and Oak Ridge national laboratories mandate qualified suppliers for both European dilution refrigerator components and Japanese cryogenic control electronics. Hardware fabrication draws from specialized foundries in upstate New York, Santa Barbara, and Arizona for superconducting qubit wafers. Supply chain vulnerability centers on single-source dependencies for helium-3 isotope refinement and ultra-high vacuum chamber assemblies. Distribution runs through direct national laboratory contracts, specialized cloud broker platforms, and systems integrators serving defense contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America quantum computing market operates as a cost-of-compliance story where NIST post-quantum cryptography standardization timelines erect substantial barrier-to-entry moats for vendors lacking federal security clearance infrastructure.
For Market Incumbents: To counter trapped-ion fidelity advances from Quantinuum, IBM should deepen backward integration into cryogenic control electronics manufacturing and expand Yorktown Heights certification capacity for NIST-compliant cryptographic validation. Foundry partnerships in Arizona and New York provide capacity leverage against emerging photonics competitors. For New Entrants and Emerging Players: Cloud-native API platforms represent the most penetrable entry vector for mid-sized biotech firms along Boston's Route 128 corridor lacking captive quantum infrastructure. Target computational chemistry simulation services for IND submission support, leveraging pay-per-use pricing to bypass capital-intensive hardware procurement barriers. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid quantum-classical software orchestration specialists given FDA engagement with computational validation frameworks for drug discovery submissions. Long-term viability hinges on algorithmic IP moats rather than hardware commoditization. Watch NIST standardization milestone announcements as inflection indicators for federal procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| NIST Post-Quantum Cryptography Certification | Federal procurement eligibility under National Quantum Initiative Act disbursement timelines. |
| Cloud-Native API Platform Launch | Mid-sized enterprise access without dilution refrigerator capital commitments. |
| FDA Computational Chemistry Validation Partnership | Regulatory pathway for quantum-enhanced IND submission packages. |
| Foundry Capacity Expansion | Domestic superconducting qubit fabrication scaling under federal R&D directives. |
| Trapped-Ion Fidelity Roadmap Advancement | Premium positioning for cryptographic applications requiring 99.9% gate precision. |
Research Methodology
Multi-period observation of federal grant disbursement rhythms, national laboratory procurement timelines, and venture deployment patterns anchored the trend analysis, supplemented by interviews with quantum hardware engineering directors, cloud platform product managers, pharmaceutical computational chemistry leads, and cryogenic systems procurement officers at Department of Energy facilities. Secondary validation drew from National Quantum Initiative Act appropriation records, NIST post-quantum cryptography standardization documentation, FDA engagement protocols for computational drug discovery, and hyperscaler quantum computing capex disclosures. Bottom-up vendor revenue triangulation against top-down federal R&D allocation estimates ensured cross-check integrity.
Input-output matrices modeled qubit processor shipments, cloud access credit consumption, and software licensing flows across hardware type, deployment model, end-user industry, and geographic cluster dimensions. CAGRs were derived from slope-consistency checks against historical federal procurement cycles and pharmaceutical R&D intensity trends. Industry-specific forecast inputs included trapped-ion coherence time improvement trajectories and superconducting qubit error rate reduction curves.
Inputs from national laboratory procurement databases and venture capital transaction records were available through the study window; gaps in classified defense agency quantum spending introduce uncertainty bands around government segment projections. Deviation in NIST post-quantum cryptography standardization acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Roll to Roll Flexible Electronics Market
Emerging and Next Generation Technologies
Global Next Generation Computing Market
Emerging and Next Generation Technologies
Laser Technology Market
Emerging and Next Generation Technologies
Transparent Electronics Market
Emerging and Next Generation Technologies
Global Metamaterial Market
Emerging and Next Generation Technologies
Global Ultrafast Lasers Market
Emerging and Next Generation Technologies
Mexico Cleanroom Technology Market
Emerging and Next Generation Technologies
Swarm Computing Market
Emerging and Next Generation Technologies
Global Metamaterials Technologies Market
Emerging and Next Generation Technologies
1550nm LiDAR Pulsed Fiber Laser Market
Emerging and Next Generation Technologies
Global Terahertz Technology Market
Emerging and Next Generation Technologies
Global High-Performance Computing (HPC) Market
Emerging and Next Generation Technologies
Nanoparticle Technology Market
Emerging and Next Generation Technologies
3D Electronics Market
Emerging and Next Generation Technologies
AI Edge Computing Market
Emerging and Next Generation Technologies
Piezoelectric Nanogenerator Market