
 Global Digital Twin Technology Market | 2026-2036
Global Digital Twin Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Twin Technology Market Foresight
ISO 23247, the digital twin manufacturing framework standard, is bifurcating vendor eligibility between certified platform providers and uncertified aspirants. Siemens leverages its industrial automation heritage to anchor digital twin deployments in European manufacturing. GE Vernova sustains leadership through deep integration with power generation asset performance management. PTC differentiates via its ThingWorx IoT backbone and closed-loop PLM connectivity.
A digital twin constitutes a virtual representation of a physical entity, continuously synchronized through real-time sensor data feeds and physics-based simulation models operating at millisecond update intervals. Its primary commercial purpose centers on optimizing asset lifecycle performance, reducing unplanned downtime, and enabling scenario testing without physical intervention. Cloud-based deployment captures the dominant revenue share as enterprises prioritize scalable compute for complex multiphysics simulations, while predictive maintenance applications within the application dimension command premium pricing due to measurable ROI from avoided failure costs. The energy and utilities vertical demonstrates the steepest adoption trajectory, driven by grid modernization mandates and renewable asset complexity.
The U.S. FDA regulates digital twin implementations in medical device development through its premarket submission pathways for computational modeling, while the EU AI Act imposes conformity requirements on autonomous decision-making components within twin architectures. China's MIIT enforces GB standards for industrial internet platforms that embed twin functionality, creating divergent compliance obligations for multinational software vendors. Stakeholders must monitor how jurisdictional fragmentation in AI governance and data residency rules reshapes platform architecture decisions and partnership strategies.
Market Dynamics
ISO 23247 certification requirements are bifurcating the vendor base, forcing platform providers to choose between costly standardization investments and retreat to uncertified niche applications. This structural filter is reshaping competitive positioning across manufacturing, energy, and healthcare deployments.
Growth Catalysts
- EU AI Act Conformity Mandates:The EU AI Act imposes algorithmic transparency requirements on autonomous decision-making components within twin architectures, compelling enterprises to upgrade legacy simulation platforms and creating replacement demand for compliant infrastructure.
- Grid Modernization Imperatives:Renewable asset complexity in Germany and Japan is accelerating digital twin deployments for predictive maintenance of offshore wind and distributed solar installations, with utilities prioritizing physics-based models over statistical approximations.
- FDA Computational Modeling Pathway:The FDA's premarket submission framework for software-as-medical-device applications is legitimizing digital twins in cardiovascular and orthopedic device development, expanding addressable market into regulated healthcare verticals.
Market Restraints
- Specialized Talent Scarcity:The intersection of physics simulation, IoT engineering, and domain expertise in power systems or aerostructures commands premium compensation, constraining deployment velocity for mid-market manufacturers lacking captive technical workforces.
- Cloud Compute Cost Volatility:Multiphysics simulations requiring millisecond synchronization intervals consume GPU-intensive resources, exposing operators to unpredictable operational expenditure swings that compress project margins and deter long-term commitments.
- Data Residency Fragmentation:China's MIIT enforcement of GB standards for industrial internet platforms creates architectural incompatibilities with Western cloud infrastructure, forcing multinational vendors to maintain parallel codebases and compliance documentation.
Strategic Opportunities
- India Manufacturing Digitization:The country's PLI scheme incentives for semiconductor and pharmaceutical production are creating first-mover openings for twin platforms in greenfield fabs, where absence of legacy automation reduces integration friction.
- Convergence with Generative AI:Large language models trained on equipment manuals and failure databases are enabling natural language interfaces for scenario testing, lowering technical barriers for maintenance engineers and expanding user bases beyond simulation specialists.
- Outcome-Based Performance Contracts:Equipment OEMs in aerospace and power generation are restructuring commercial relationships around guaranteed uptime metrics, requiring embedded twin infrastructure to validate performance claims and manage contractual risk.
Industry Challenges
- Interoperability Certification Timelines:ISO 23247 compliance validation cycles extend 18-24 months, delaying revenue recognition for platform providers and freezing procurement decisions for risk-averse manufacturing buyers awaiting vendor certification status.
- Multiphysics Model Calibration:Synchronizing thermal, mechanical, and electrical simulation domains with physical sensor streams demands specialized integration engineering that exceeds the capabilities of conventional IT system integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Twin Technology Market |
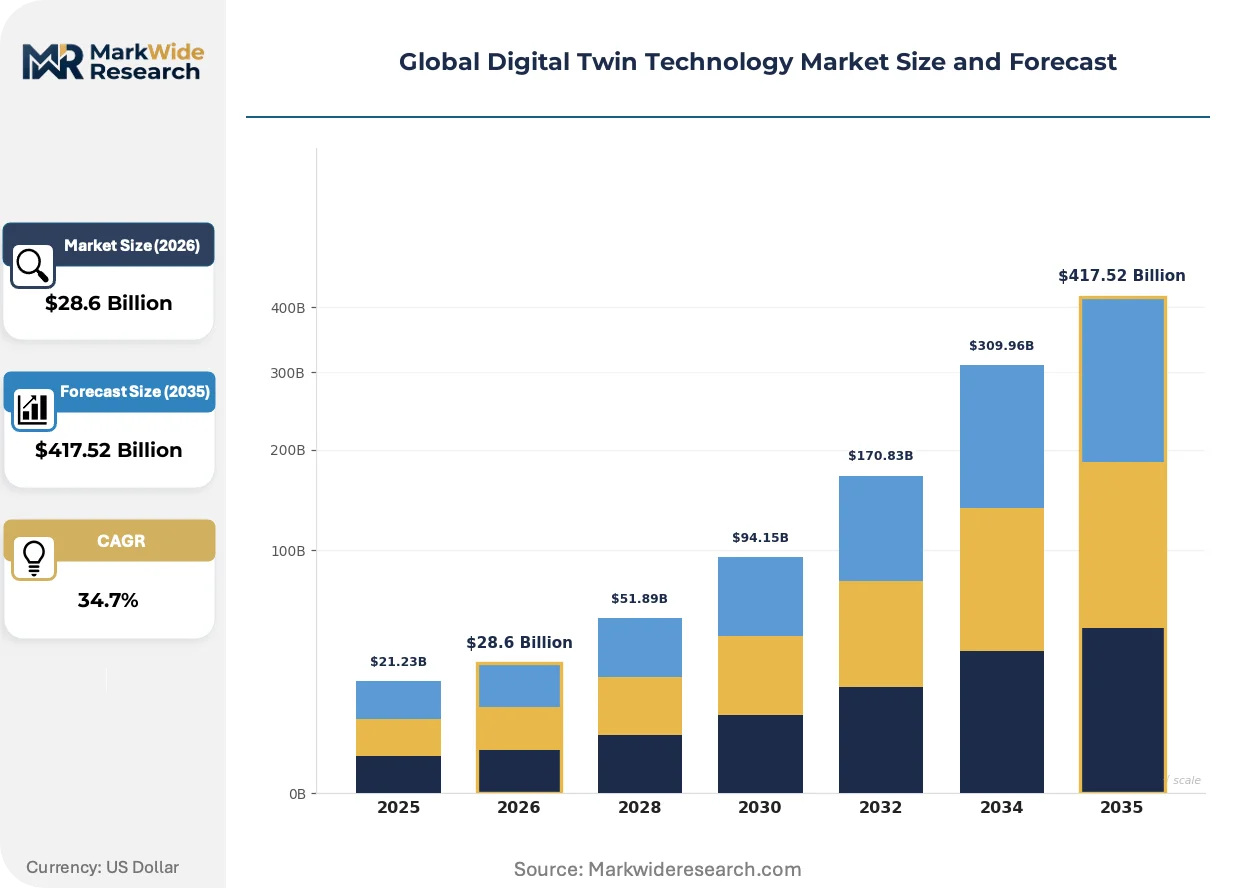
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $417.52 Billion |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Edge Computing, Hybrid Application: Smart Manufacturing, Urban Planning, Aerospace Simulation, Predictive Maintenance Industry Vertical: Energy & Utilities, Transportation, Telecommunication, Agriculture Solution Type: Visualization & Modeling, Analytics & Optimization, Monitoring & Control, Simulation Software, Integration Platforms |
| Companies Covered | Siemens, GE Vernova, PTC, Dassault Systèmes, Microsoft, IBM, ANSYS, General Electric, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Twin Technology Market Shifts & Advancements
Real-time edge inference is compressing the latency gap between physical assets and their virtual counterparts, enabling closed-loop control applications that were previously confined to offline simulation environments.
Physics-informed neural networks are fragmenting the traditional divide between first-principles simulation and machine learning approximation. Automotive OEMs in Stuttgart and Toyota City are deploying hybrid models that embed Navier-Stokes and Maxwell equations within deep learning architectures, achieving 40x speedup in aerodynamic and electromagnetic simulations without sacrificing deterministic accuracy. This convergence is compressing the competitive advantage of specialized CAE incumbents.
The EU AI Act's risk classification framework for autonomous systems is mandating explainability documentation for digital twin decision layers. Medical device manufacturers submitting to EMA and national competent authorities must now provide algorithmic impact assessments alongside traditional clinical evidence, forcing platform vendors to retrofit audit trails and bias detection modules into operational deployments. German automotive suppliers are responding by segregating AI-driven optimization loops from safety-critical control paths.
Buyers in energy and utilities are consolidating vendor relationships around integrated platform stacks rather than point solutions for isolated asset classes. Procurement functions at European grid operators and Texas independent power producers are prioritizing single-source accountability for hardware, software, and implementation services, displacing the previous multi-vendor integration model. This concentration is most visible in offshore wind, where turbine OEMs now bundle lifetime digital twin subscriptions with equipment supply contracts.
Global Digital Twin Technology Market Segmentation
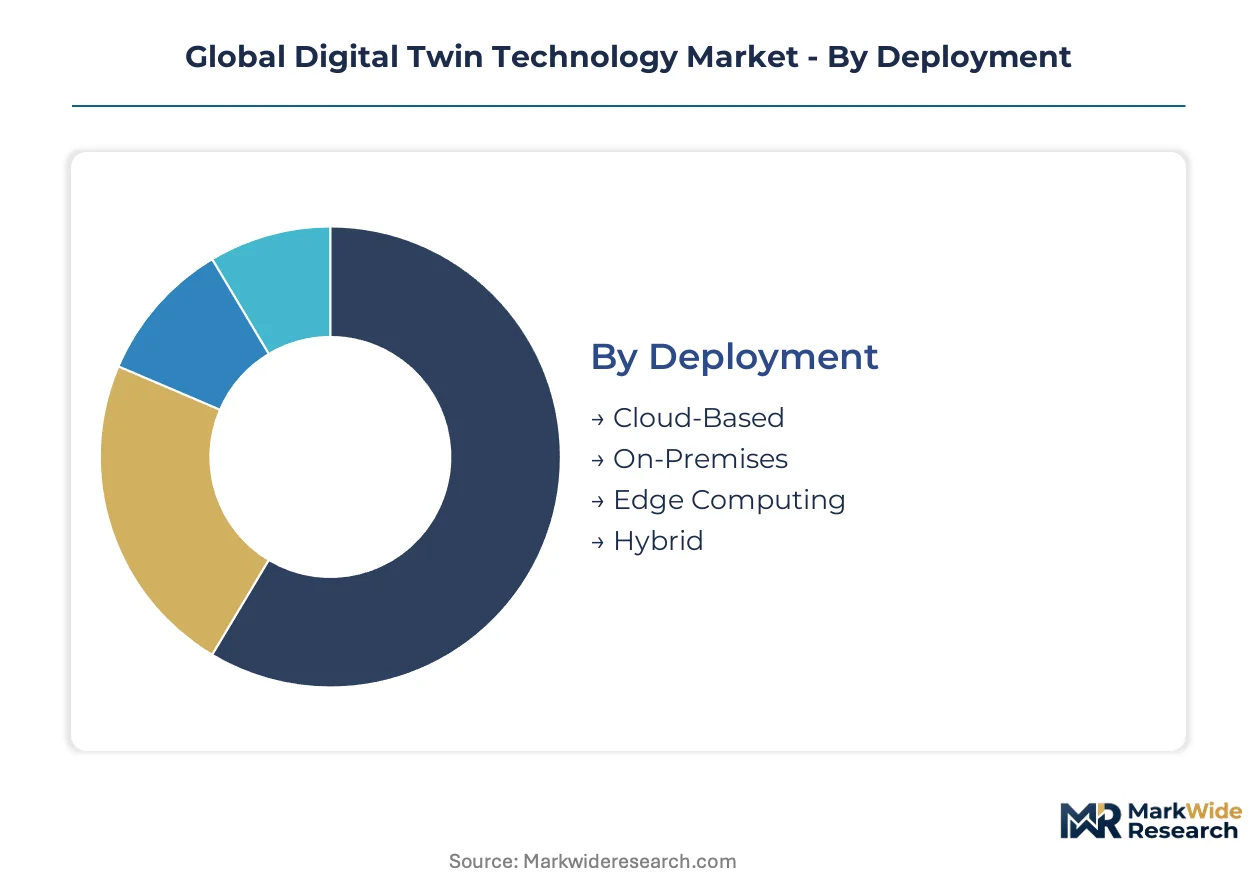
Deployment architecture and application specificity determine compliance obligations and pricing tiers across the digital twin landscape. Segmentation reveals where regulatory fragmentation creates vendor qualification barriers and where standardization accelerates procurement cycles.
Deployment:
Cloud infrastructure faces divergent data residency mandates across jurisdictions, forcing architectural tradeoffs between scalability and sovereignty compliance.
- Cloud-Based:Scalable compute clusters enable complex multiphysics simulations with millisecond synchronization intervals. Demand concentrates in Texas defense manufacturing corridors and Seattle aerospace clusters, driven by GPU-intensive renewable asset modeling requirements. Cloud deployments handle the majority of throughput; Edge Computing is the fastest mover on share.
- On-Premises:Air-gapped installations satisfy China's MIIT GB standards for industrial internet platforms and FDA 21 CFR Part 11 requirements in pharmaceutical manufacturing. German automotive OEMs prefer captive infrastructure for proprietary aerodynamic datasets.
- Edge Computing:Real-time inference at the asset level compresses latency for closed-loop control. Offshore wind installations in the North Sea and distributed solar arrays in Japan deploy edge nodes to reduce bandwidth dependency.
- Hybrid:Tiered architectures partition sensitive control loops on-premises while offloading training workloads to cloud instances. European grid operators adopt hybrid models to satisfy GDPR data localization while accessing scalable analytics.
Cloud deployments capture the dominant revenue position; Edge Computing is climbing the fastest on adoption curves.
Application:
Functional use cases stratify by measurable ROI transparency and regulatory documentation burden.
- Smart Manufacturing:ISO 23247-certified platforms synchronize production lines with virtual counterparts for quality prediction. Stuttgart automotive suppliers and Toyota City OEMs deploy these systems for virtual commissioning of new assembly cells.
- Urban Planning:City-scale digital twins integrate building information models with traffic and utility sensor networks. Singapore and Barcelona municipalities lead implementation for flood prediction and energy demand forecasting.
- Aerospace Simulation:FAA and EASA certification requirements mandate deterministic physics models for flight control validation. Boeing and Airbus supplier networks in Seattle and Toulouse drive specialized demand.
- Predictive Maintenance:Physics-based degradation models forecast equipment failure before sensor threshold breaches. Offshore wind operators in Germany and Texas independent power producers command premium pricing for avoided downtime.
Predictive Maintenance commands the steepest pricing premium; Smart Manufacturing is expanding most quickly on deployment volume.
Industry Vertical:
Vertical-specific compliance frameworks and asset complexity determine platform customization depth.
- Energy & Utilities:FERC Order 2222 and EU Green Deal grid modernization mandates accelerate renewable asset twin deployment. German transmission operators and Texas ERCOT market participants prioritize physics-based models over statistical approximations.
- Transportation:NHTSA autonomous vehicle testing protocols and EU AI Act risk classifications shape simulation requirements. Detroit automakers and Stuttgart suppliers invest in hybrid physics-ML architectures for crash prediction.
- Telecommunication:FCC spectrum auction rules and 5G network densification drive radio frequency twin adoption for interference modeling.
- Agriculture:USDA precision agriculture incentives and EU Common Agricultural Policy digitization funds support farm-level sensor integration for irrigation optimization.
Energy & Utilities dominates current procurement volume; Transportation is gaining share fastest on regulatory deadline pressure.
Solution Type:
Component layer specialization determines vendor integration burden and customer technical staffing requirements.
- Visualization & Modeling:3D rendering engines and CAD geometry processing form the user interface layer. Architecture and engineering firms in London and New York drive demand for immersive design review.
- Analytics & Optimization:Machine learning pipelines trained on equipment failure databases enable scenario testing. Maintenance engineers at Japanese power utilities leverage natural language interfaces to query degradation predictions.
- Monitoring & Control:Real-time SCADA integration and alarm management satisfy operational technology security standards.
- Simulation Software:Multiphysics solvers embedding Navier-Stokes and Maxwell equations execute on GPU clusters. Automotive aerodynamic teams achieve 40x speedup through physics-informed neural network architectures.
- Integration Platforms:API middleware and data lakes unify heterogeneous sensor streams and enterprise systems. Mid-market manufacturers lacking captive integration expertise outsource to platform vendors.
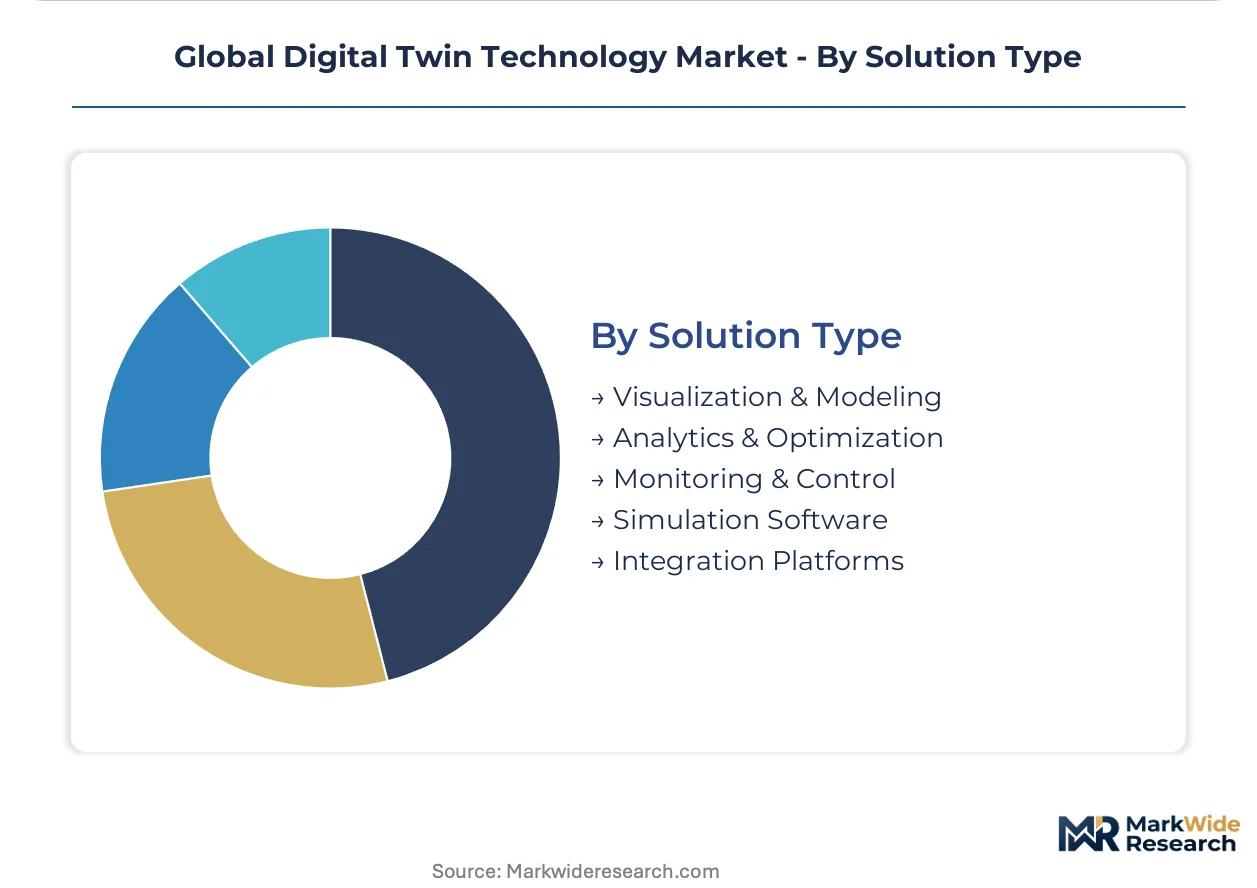
Integration Platforms absorb the largest implementation budgets; Simulation Software is the fastest climber on performance differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government procurement incentives and industrial modernization mandates are concentrating digital twin deployments in manufacturing corridors with pre-existing automation infrastructure and clear regulatory pathways for computational modeling.
United States
Defense manufacturing corridors in Texas and aerospace clusters in Seattle drive concentrated demand for physics-based simulation platforms. The FDA's premarket submission framework for software-as-medical-device applications legitimizes twin deployments in cardiovascular device development. Boeing supplier networks in Washington state integrate virtual prototyping systems for flight control validation.
Germany
Automotive OEMs in Stuttgart and transmission operators managing offshore wind assets in the North Sea anchor European deployment volume. The EU AI Act imposes algorithmic transparency requirements on autonomous decision-making components within twin architectures, compelling platform upgrades. Bavarian automotive suppliers segregate AI-driven optimization loops from safety-critical control paths to satisfy conformity mandates.
China
MIIT enforcement of GB standards for industrial internet platforms creates architectural requirements that diverge from Western cloud infrastructure. State-led grid modernization investments accelerate renewable asset twin deployment for distributed solar and offshore wind. Yangtze River Delta manufacturing hubs adopt captive on-premises infrastructure to satisfy data residency obligations while accessing scalable analytics.
Japan
Toyota City OEMs and METI-backed smart factory initiatives propel hybrid physics-ML architectures for aerodynamic simulation. The country's precision manufacturing base demands millisecond synchronization intervals for closed-loop quality prediction. Power utilities in the Kanto region deploy edge computing nodes for predictive maintenance of thermal generation assets.
India
PLI scheme incentives for semiconductor and pharmaceutical production create first-mover openings in greenfield fabs lacking legacy automation. Karnataka and Gujarat manufacturing zones attract platform providers seeking reduced integration friction. The country's central electricity regulator encourages grid modernization investments that embed twin functionality for renewable asset management.
Global Digital Twin Technology Market Competitive Landscape
Listed leaders compete with private specialists across certification status and domain depth, creating a tiered structure where ISO 23247 compliance separates qualified platform providers from aspirants. The vendor base clusters around industrial automation heritage, IoT backbone integration, and multiphysics simulation expertise. Three archetypes dominate: diversified conglomerates with captive manufacturing relationships, pure-play software vendors with cloud-native architectures, and specialized engineering firms with physics solver depth. Competitive moves concentrate on strategic partnerships for edge computing deployment and portfolio diversification into generative AI interfaces.
Within the diversified conglomerate tier, Siemens and General Electric exemplify players leveraging industrial automation heritage to anchor manufacturing deployments. PTC occupies a position among pure-play software specialists, differentiated through IoT platform integration and closed-loop PLM connectivity. These three represent distinct strategic postures: European industrial depth, American power generation asset management, and specialized software architecture.
| Leading Market Players |
|---|
| Siemens |
| GE Vernova |
| PTC |
| Dassault Systèmes |
| Microsoft |
| IBM |
| ANSYS |
| General Electric |
| Oracle |
| Others |
Supply & Pricing Matrix
Eighteen-to-twenty-four-month ISO 23247 certification cycles compress vendor pricing power while amplifying procurement delays, as manufacturers withhold commitments until compliance status clarifies. Cloud GPU instances for multiphysics simulations now constitute the dominant variable cost layer, forcing tiered service packaging that separates certified platform premiums from uncertified alternatives.
Pricing Analysis
Certification level creates the primary spread between ISO 23247-compliant platforms and uncertified alternatives, with subscription SaaS tiers dominating revenue models across manufacturing and energy verticals. Price differentiation hinges on millisecond synchronization guarantees and FDA premarket pathway documentation for healthcare deployments. Pricing pressure intensifies in the mid-market segment as cloud compute volatility erodes project margins. Defense manufacturers in Texas exhibit lowest price sensitivity due to mission-critical uptime requirements, while Indian pharmaceutical greenfield sites command aggressive volume discounts.
Supply Chain Analysis
Strategic stockpiling of GPU compute capacity supersedes just-in-time preferences as cloud providers buffer against demand surges from renewable asset modeling. Software development concentrates in Germany, the United States, and Japan, with physics solver libraries drawing from specialized academic licensing pools. Supply chain risk centers on single-source vulnerability for NVIDIA GPU architectures tethered to Taiwan Semiconductor manufacturing. Distribution runs through direct enterprise sales teams for certified platforms, supplemented by systems integrator channels for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of engineers fluent in both Navier-Stokes simulation and industrial IoT integration constrains deployment velocity, elevating acquisition premiums for teams with hybrid physics-ML capabilities.
For Market Incumbents: Compound certification moats by accelerating ISO 23247 compliance investments before validation timelines freeze procurement decisions. Acquire specialized multiphysics calibration boutiques in Stuttgart and Toyota City to defend against physics-informed neural network disruptors. Prioritize backward integration into edge hardware to capture latency-sensitive closed-loop control applications. For New Entrants and Emerging Players: Anchor in India's PLI-backed semiconductor fabs, where absence of legacy automation minimizes integration friction for greenfield digital twin deployments. Target predictive maintenance for distributed solar arrays as the most penetrable application, leveraging natural language interfaces to bypass simulation specialist scarcity. Pursue outcome-based performance contracting with Texas independent power producers to validate platform efficacy without upfront capital burden. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-software convergence play because physical asset digitization becomes non-discretionary under grid modernization mandates and EU AI Act conformity deadlines. Prioritize targets with captive physics solver IP and established FDA submission track records. Watch for inflection when physics-informed neural network adoption crosses 50% share in automotive aerodynamic simulation, signaling commoditization pressure on traditional CAE incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 23247 Certification Acceleration | Separates qualified platform providers from uncertified aspirants in European manufacturing procurement. |
| Physics-Informed Neural Network Integration | Delivers 40x simulation speedup for Stuttgart automotive aerodynamic teams without deterministic accuracy loss. |
| Edge Computing Node Deployment | Compresses latency for North Sea offshore wind closed-loop control independent of bandwidth constraints. |
| Outcome-Based Performance Contracting | Restructures aerospace OEM relationships around guaranteed uptime metrics validated through embedded twin infrastructure. |
| Generative AI Interface Development | Enables natural language scenario testing for Japanese power utility maintenance engineers beyond simulation specialist pools. |
Research Methodology
Operator-level perspectives from digital twin platform engineers, predictive maintenance directors at German utilities, FDA regulatory affairs specialists, and Texas defense manufacturing procurement officers anchored the qualitative base. Secondary validation drew from SEC filings of industrial automation conglomerates, EMA algorithmic impact assessment guidance, MIIT GB standard enforcement notices, and hyperscaler cloud infrastructure capex disclosures. Bottom-up deployment estimates triangulated against top-down market sizing across certification tiers.
Sensitivity analysis tested forecast robustness across GPU cost volatility scenarios and ISO 23247 compliance timeline variations throughout the projection horizon. Segmentation dimensions modeled encompass deployment architecture, application specificity, industry vertical, and solution type, with regional adoption patterns calibrated to jurisdictional regulatory fragmentation. CAGRs derived from multivariate regression against industrial automation investment cycles and renewable asset deployment pipelines.
Decision-makers should treat outputs as directional under sustained cloud compute demand growth and stable FDA premarket pathway timelines; material deviation would warrant model refresh. Specific risk factors include MIIT data localization enforcement intensification and EU AI Act risk classification expansion. Revision becomes warranted when physics-informed neural network adoption crosses critical thresholds in automotive simulation workflows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Triboelectric Nano-Generator Market
Emerging and Next Generation Technologies
Internet of Nano Things Market
Emerging and Next Generation Technologies
Global Metamaterials Technologies Market
Emerging and Next Generation Technologies
Haptic Technology Market
Emerging and Next Generation Technologies
Swarm Intelligence Market
Emerging and Next Generation Technologies
Hyperscale Computing Market
Emerging and Next Generation Technologies
Flexible Hybrid Electronics (FHE) Market
Emerging and Next Generation Technologies
Graphene Nanoplatelets Market
Emerging and Next Generation Technologies
Global Broad Ion Beam Technology Market
Emerging and Next Generation Technologies
AI PC Market
Emerging and Next Generation Technologies
Third-Generation Solar Cells Market
Emerging and Next Generation Technologies
Global Ultrafast Lasers Market
Emerging and Next Generation Technologies
Global WI SUN Technology Market
Emerging and Next Generation Technologies
Global High-Performance Computing (HPC) Market
Emerging and Next Generation Technologies
North America Quantum Computing Market
Emerging and Next Generation Technologies
Mexico Cleanroom Technology Market