
 Printed Antenna Market | 2026-2036
Printed Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
Printed Antenna Market Intelligence
Demand from high-volume automotive and consumer electronics sectors is reorganizing the competitive landscape, previously dominated by specialized industrial applications. This shift prioritizes cost-effective, scalable production methods. Galtronics Corporation leverages its established expertise in RF systems to serve diverse end-users. Meanwhile, Optomec Inc. specializes in aerosol jet printing technologies, enabling the creation of complex 3D antennas for advanced applications.
A printed antenna is a radio frequency component created by depositing conductive materials, such as silver-based inks, onto a non-conductive substrate. These antennas are manufactured using processes like screen, inkjet, or aerosol jet printing. Their primary purpose is to transmit and receive electromagnetic signals for wireless communication in a compact and often flexible form factor. Flex Antennas currently command significant volume, driven by their integration into smartphones and wearable devices, while advancements in Conductive Inks are critical for improving performance and reducing manufacturing costs.
Regulatory frameworks significantly influence product design and market entry. In the United States, the FCC sets stringent limits on radio frequency interference, while in Europe, CE marking and the RoHS directive restrict hazardous substances in electronic equipment. Compliance with these standards is mandatory for manufacturers. The selection of substrate materials and printing technologies will therefore be a crucial decision point for vendors aiming to compete in next-generation wireless device markets.
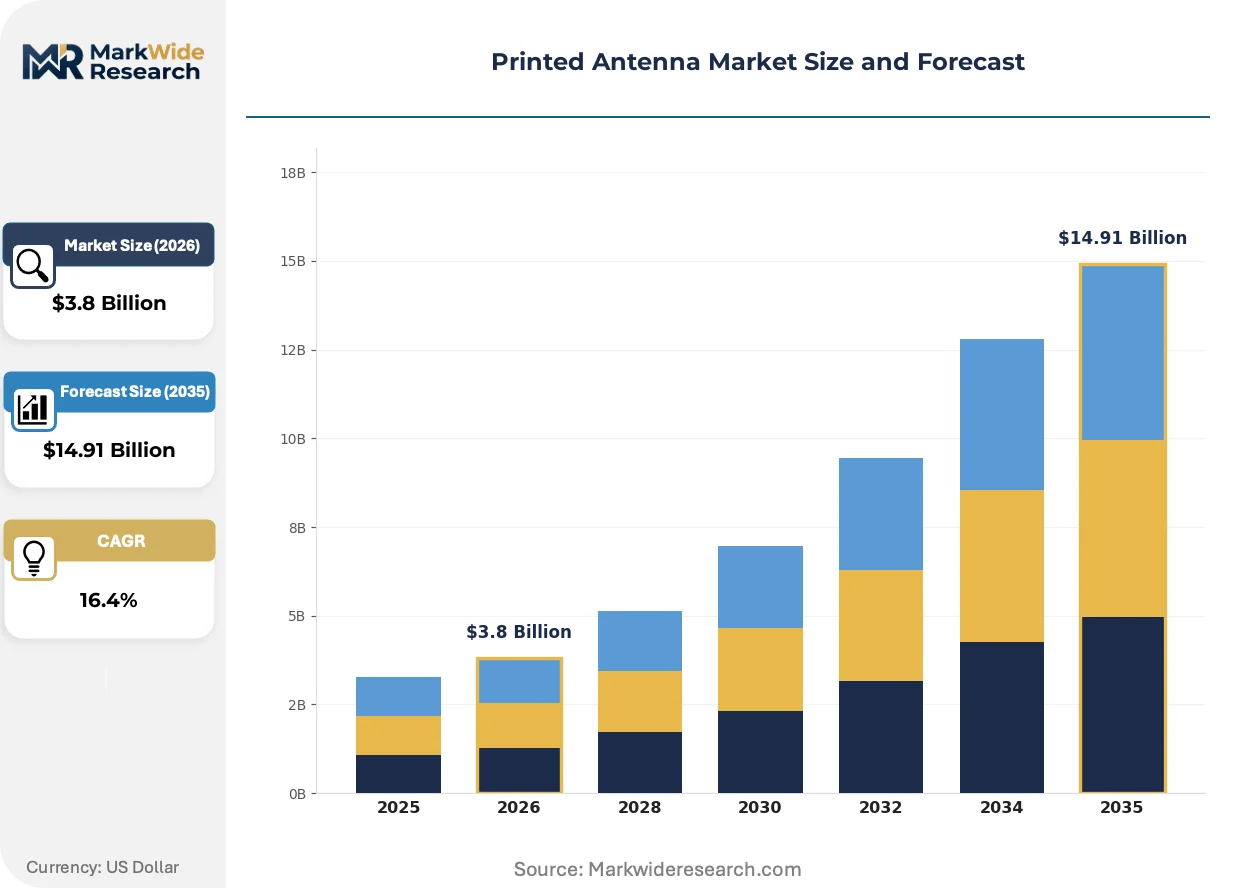
Market Dynamics
The convergence of 5G and 6G network deployments with mass-market IoT and automotive applications is reshaping the printed antenna market. This pivot prioritizes cost-effective, scalable production over the prior focus on specialized, high-margin industrial components.
Growth Catalysts
- Proliferation of IoT Devices:The expansion of connected devices in smart home, industrial automation, and wearable technology sectors creates a continuous need for compact, low-cost antennas for wireless data transmission.
- 5G and 6G Network Rollout:Government-led spectrum allocation and infrastructure initiatives, such as those guided by the FCC in the United States, necessitate novel antenna designs capable of operating at higher frequencies.
- Automotive Sector Integration:Demand for advanced driver-assistance systems (ADAS) and vehicle-to-everything (V2X) communication is driving the adoption of printed antennas for telematics, navigation, and onboard connectivity.
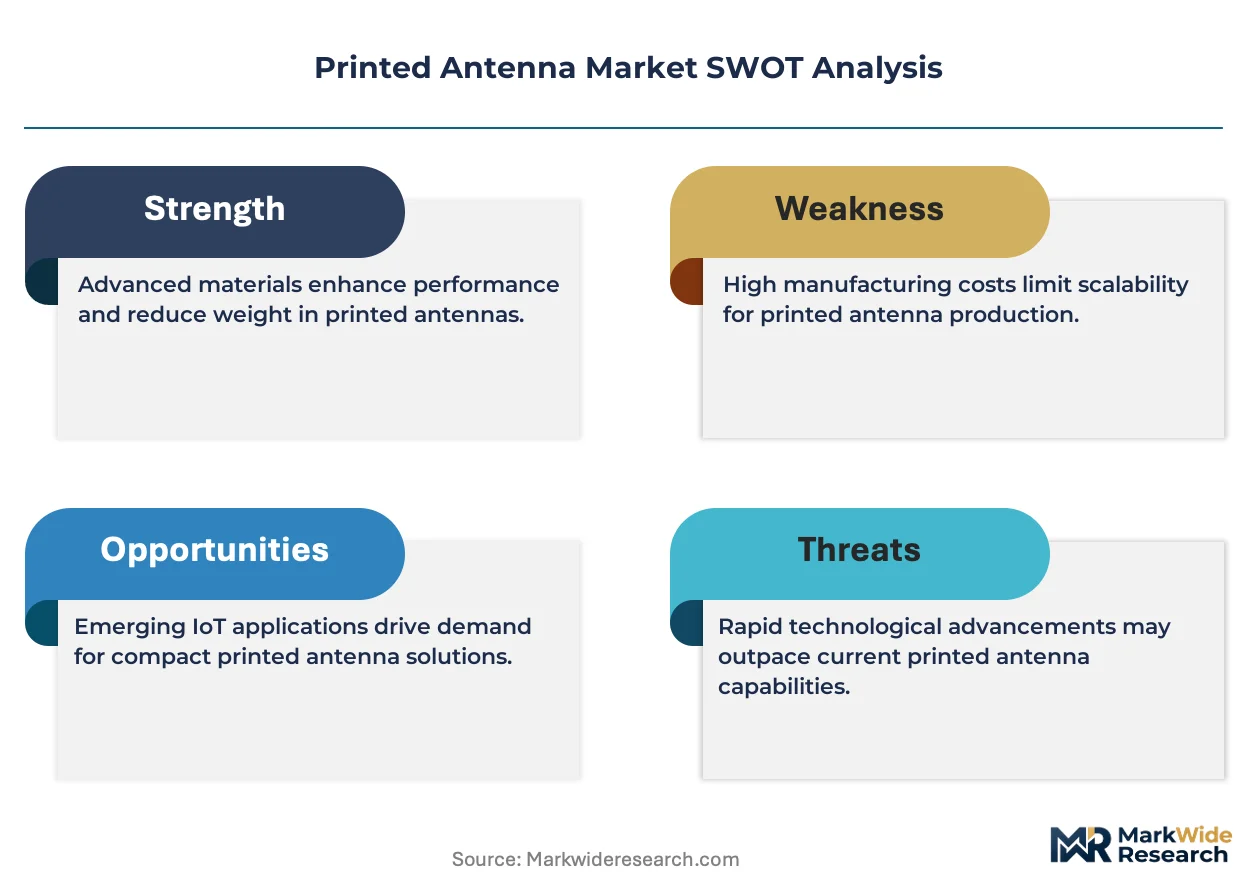
Market Restraints
- Performance Limitations:Compared to conventional antennas, printed variants can exhibit lower gain and bandwidth, a technical constraint that limits their use in certain high-performance or long-range communication applications.
- Conductive Ink Cost:Production cost is heavily influenced by the price of conductive materials, especially silver-based inks, creating margin pressure and price volatility for manufacturers.
- Material Restrictions:Europe's RoHS directive and similar environmental regulations restrict the use of certain hazardous substances, which can complicate material selection and exclude some high-performance but non-compliant conductive formulations.
Strategic Opportunities
- Flexible and Wearable Electronics:The development of antennas on flexible or stretchable substrates opens significant opportunities in medical biosensors, smart textiles, and next-generation consumer wearables requiring body-conformable designs.
- Antenna-in-Package (AiP) Integration:Miniaturization trends in consumer electronics create a white space for integrating printed antennas directly onto semiconductor packages, reducing device size and improving signal integrity for 5G mmWave applications.
- Targeted Manufacturing Incentives:India's Production Linked Incentive (PLI) scheme for electronics manufacturing offers a strategic opportunity for vendors to establish local production facilities to serve the country's rapidly growing domestic market.
Industry Challenges
- Standardization Gaps:A lack of universally accepted standards for testing the performance and reliability of 3D and flexible printed antennas complicates design validation and can hinder interoperability between components.
- Complex Compliance Pathways:Manufacturers face long and costly certification processes to meet divergent international standards for electromagnetic interference, such as FCC Part 15 in the US and CE marking directives in Europe.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printed Antenna Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flex Antennas, Planar Antennas, 3D Antennas, Array Antennas Technology: Substrate Materials, Conductive Inks, Printing Techniques, Hybrid Approaches End User: Consumer Electronics, Automotive Applications, Healthcare Devices, IoT Solutions Application: RFID Systems, Wireless Communication, Satellite Communication, Sensor Networks |
| Companies Covered | Texas Instruments Incorporated, Galtronics Corporation, Cobham Plc, GSI Technologies, Mars Antennas and RF Systems Ltd, Optomec Inc, TIL-TEK Antenna Inc, Optisys Inc, Gamma NU Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printed Antenna Market Strategic Shifts & Innovations
A fundamental shift from discrete antenna components to fully integrated and multifunctional surfaces is defining the market's trajectory. Material science advancements and novel manufacturing processes are enabling antennas to become an intrinsic part of a device's structure.
Aerosol jet printing enables the direct deposition of conductive materials onto non-planar and 3D surfaces, creating conformal antennas. Adoption is accelerating in the aerospace and medical device sectors for highly customized components. This advanced manufacturing capability is fragmenting the market away from standardized flat antennas, enabling bespoke designs that are optimized for the unique geometry of each product.
European Union regulations, including the RoHS directive and the broader EU Green Deal's focus on circularity, are intensifying scrutiny on electronic waste. This pressure is spurring R&D into biodegradable substrates and less hazardous, recyclable conductive inks. Consequently, the consumer electronics segment is beginning to prioritize antenna materials based on their end-of-life environmental impact alongside traditional performance metrics.
Buyer behavior is shifting from the procurement of standard, off-the-shelf antennas to collaborative design partnerships with antenna specialists. This model displaces traditional component distributors in favor of direct engineering engagements to optimize RF performance early in the product lifecycle. This co-design approach is most prominent within the hyper-competitive smartphone and automotive industries in China and South Korea.
Printed Antenna Market Segmentation
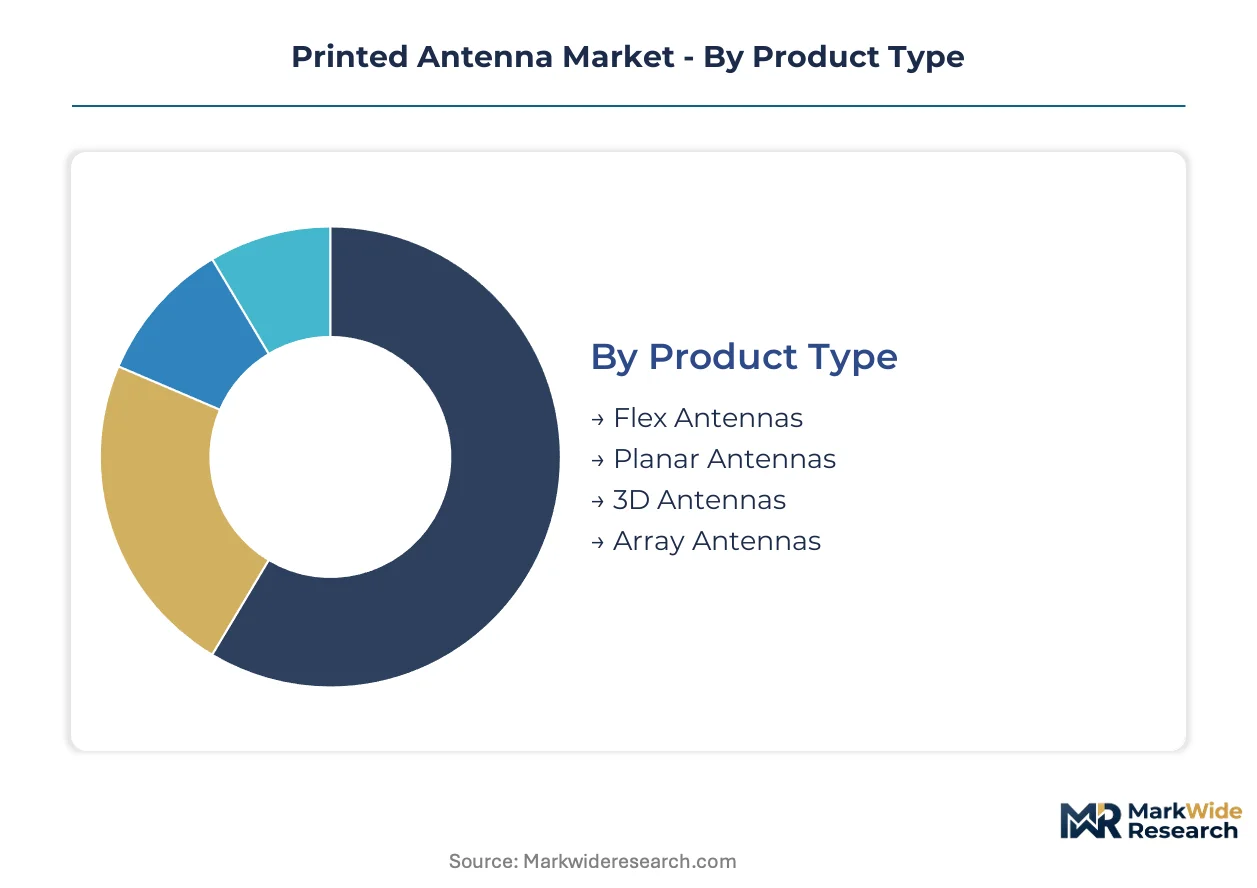
Understanding the segmentation of the printed antenna market reveals the diverse technological pathways and end-user demands shaping its evolution. This granular analysis highlights specific product types, underlying technologies, key end-user industries, and critical applications driving market expansion.
Product Type:
The geographic distribution of printed antenna product types often reflects regional manufacturing capabilities and specific market demands.
- Flex Antennas:These antennas are fabricated on flexible substrates, such as polyimide or PET, allowing for bending and conformal integration into devices. Demand concentrates heavily in Asia, particularly China, driven by high-volume smartphone and wearable device manufacturing.
- Planar Antennas:Planar antennas are designed on flat, rigid substrates, typically PCB materials, and are characterized by their low profile and ease of integration into existing electronic systems. These are widely used in consumer electronics and networking equipment globally.
- 3D Antennas:Created using advanced techniques like aerosol jet printing on non-planar surfaces, 3D antennas offer superior spatial efficiency and integration into complex device geometries. Adoption is accelerating in European aerospace and medical device sectors for highly customized components.
- Array Antennas:Comprising multiple individual antenna elements arranged in a specific pattern, array antennas enhance gain and beamforming capabilities for directional communication. These are critical for 5G mmWave applications in North America and East Asia.
Flex Antennas commands the established base. The steepest expansion runs through 3D Antennas.
Technology:
The cost structure of printed antenna technologies varies significantly, influencing material selection and process adoption across different markets.
- Substrate Materials:These include various non-conductive films and rigid boards like PET, polyimide, FR4, and LCP, providing the foundational support for the conductive antenna patterns. Material choice impacts flexibility, cost, and high-frequency performance.
- Conductive Inks:Formulated with metallic nanoparticles, primarily silver or copper, these inks are deposited onto substrates to create the antenna's conductive elements. Advancements in conductive inks are critical for improving antenna performance and reducing manufacturing costs, especially in China's high-volume production.
- Printing Techniques:This category encompasses diverse manufacturing methods such as screen printing, inkjet printing, and aerosol jet printing, each offering different levels of resolution, material compatibility, and throughput. Aerosol jet printing enables complex 3D antenna creation for advanced applications in Germany.
- Hybrid Approaches:Combining printed antenna elements with traditional circuit board components or semiconductor integration, these methods optimize performance and miniaturization. They are particularly relevant for Antenna-in-Package (AiP) solutions in South Korea.
Conductive Inks form the foundational element. Printing Techniques are gaining share fastest due to innovation.
End User:
End-user segments for printed antennas are differentiated by their application volume requirements and integration complexity.
- Consumer Electronics:This segment includes smartphones, smartwatches, laptops, and other portable devices where compact size, low cost, and aesthetic integration are paramount. Demand is concentrated in Asia for mass production.
- Automotive Applications:Printed antennas are integrated into vehicles for advanced driver-assistance systems (ADAS), infotainment, GPS, and vehicle-to-everything (V2X) communication. European automotive manufacturers are driving demand for robust and reliable solutions.
- Healthcare Devices:This segment utilizes printed antennas for medical biosensors, wearable health monitors, and compact diagnostic equipment, prioritizing flexibility, biocompatibility, and small form factors. North American medical device companies are key adopters.
- IoT Solutions:Covering a broad range of connected devices in smart homes, industrial automation, and smart cities, this segment requires cost-effective, compact antennas for widespread wireless data transmission. IoT proliferation globally drives continuous demand.
Consumer Electronics represents the largest volume. IoT Solutions are expanding most quickly.
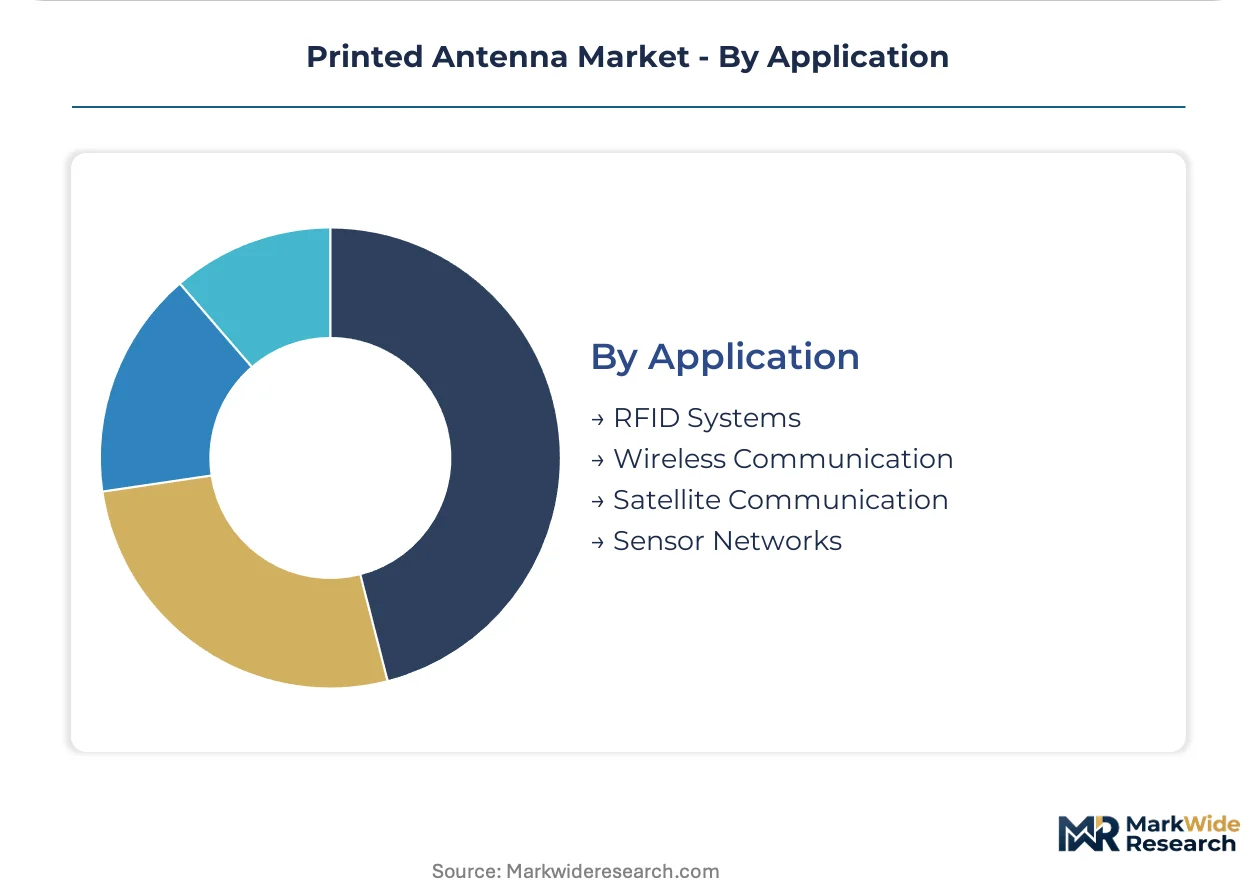
Application:
The maturity of printed antenna applications ranges from established communication protocols to nascent sensor networks.
- RFID Systems:Printed antennas are a core component in RFID tags and readers for inventory management, access control, and asset tracking across retail and logistics. These systems are widely deployed in commercial and industrial sectors.
- Wireless Communication:This broad application area includes Wi-Fi, Bluetooth, cellular (4G/5G/6G), and other short to medium-range wireless data transmission. It forms the largest application segment, supporting virtually all connected devices.
- Satellite Communication:Specialized printed array antennas are used in satellite terminals and ground stations for high-bandwidth data transfer and global connectivity. These applications often require high precision and durability.
- Sensor Networks:Printed antennas enable wireless connectivity for distributed sensor nodes in environmental monitoring, smart agriculture, and structural health monitoring. These networks require low-power, compact solutions for widespread deployment.
Wireless Communication maintains a broad presence. Sensor Networks are climbing the fastest, driven by IoT proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's robust manufacturing ecosystem drives significant supply-side concentration for printed antennas. This country's vast consumer electronics sector and high-volume production capabilities establish it as a critical hub. The global market relies heavily on its established infrastructure for cost-effective manufacturing.
China
China's vast consumer electronics ecosystem drives immense demand for flex antennas. The Ministry of Industry and Information Technology (MIIT) supports local component production. Shenzhen, a major electronics hub, specializes in high-volume, cost-effective printed antenna fabrication.
United States
The United States drives demand for advanced array antennas, especially for 5G mmWave applications. The Federal Communications Commission (FCC) regulates device performance, influencing design. Silicon Valley and Boston concentrate research into Antenna-in-Package (AiP) solutions.
Germany
Germany's automotive sector demands robust printed antennas for ADAS and V2X communication. European Union regulations, including CE marking, mandate strict compliance. Industrial clusters in Bavaria foster innovation in aerosol jet printing for complex 3D antenna geometries.
South Korea
South Korea's consumer electronics sector fuels demand for highly integrated antenna solutions in smartphones. Government initiatives support R&D in advanced semiconductor packaging. Major tech conglomerates in Seoul drive co-design partnerships for Antenna-in-Package (AiP) integration.
India
India's expanding domestic market for IoT devices and consumer electronics generates significant antenna demand. The Production Linked Incentive (PLI) scheme encourages local electronics manufacturing. Bengaluru and Chennai emerge as key centers for new production facilities.
Printed Antenna Market Key Industry Players
Concentration sits with specialized industrial component suppliers, but the market is becoming increasingly fragmented by new entrants focusing on cost-effective, scalable production methods. This shift prioritizes mass-market applications over traditional high-margin industrial uses. Three archetypes emerge: established RF system providers, advanced manufacturing technology specialists, and high-volume component fabricators. Strategic partnerships, capacity expansion, and portfolio diversification are dominant competitive moves.
Specialists in advanced manufacturing technologies, such as Optomec Inc., exemplify the shift towards complex 3D antenna creation and conformal designs for advanced applications. Meanwhile, Galtronics Corporation occupies a position among established RF system providers, leveraging extensive expertise in RF systems to serve diverse end-users across multiple sectors. GSI Technologies represents a segment of component fabricators, crucial for supplying foundational materials and processes to the broader market. These entities collectively highlight the market's evolving demand for both niche innovation and scalable, cost-effective production, particularly in high-volume segments.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Galtronics Corporation |
| Cobham Plc |
| GSI Technologies |
| Mars Antennas and RF Systems Ltd |
| Optomec Inc |
| TIL-TEK Antenna Inc |
| Optisys Inc |
| Gamma NU Inc |
| Others |
Cost & Logistics Intelligence
European Union regulations, including the RoHS directive, gate both material qualification and price differentiation for printed antenna components. Compliance with these environmental standards impacts material sourcing and manufacturing costs across the value chain.
Pricing Analysis
Europe's RoHS directive dictates the pricing tier structure for printed antennas, influencing material selection costs. The dominant pricing model is per-unit transactional, with differentiation driven by customization level for 3D antennas and certification level for automotive-grade components. Pricing softness reflects intense competition in the high-volume consumer electronics segment, particularly in Asia. Automotive manufacturers exhibit lower price sensitivity compared to mass-market IoT solution providers.
Supply Chain Analysis
Just-in-time inventory strategies are common for high-volume consumer electronics components, while strategic stockpiling secures specialized materials. Geographic supply concentration centers on China for flex antennas and conductive inks, with Germany leading in aerosol jet printing technology. Raw material dependencies include silver-based conductive inks and flexible polyimide substrates. Commodity price volatility for silver creates a structural risk, impacting cost stability. Distribution runs through direct manufacturer-to-OEM channels, especially for co-designed solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting as large consumer electronics OEMs consolidate their procurement, demanding co-design partnerships for printed antennas. This dynamic forces suppliers to adapt their engagement models.
For Market Incumbents:Shield core market share by deepening vertical integration into advanced conductive ink formulation and expanding capacity in strategic regions like India. The threat of low-cost Asian manufacturers necessitates R&D investment in novel 3D printing technologies for high-value applications. Consolidate smaller specialized players to gain access to niche printing expertise. Focus on intellectual property protection for proprietary antenna designs.
For New Entrants and Emerging Players:FCC certification fast-tracks enable market entry for novel 5G mmWave antenna solutions in North America. Target the underpenetrated medical biosensor market with flexible, biocompatible designs. Leverage aerosol jet printing capabilities to offer customized 3D antennas for aerospace and defense sectors. A direct engineering engagement model with early-stage product developers provides a strong go-to-market angle.
For Investors and Strategic Acquirers:Carve-out targets emerge from large electronics conglomerates seeking to divest non-core antenna fabrication units. The long-term viability favors specialists in advanced manufacturing technologies and material science. Focus on acquiring firms with strong intellectual property in 3D antenna design or next-generation conductive inks. A signal to watch is the increasing adoption rate of Antenna-in-Package (AiP) solutions in new smartphone models.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in India | Addresses rapidly growing domestic IoT and consumer electronics demand. |
| Advanced Conductive Ink R&D | Improves performance and reduces manufacturing costs for printed antennas. |
| Strategic Partnership for AiP | Accelerates integration of printed antennas into semiconductor packages. |
| Vertical Integration into Substrate Production | Secures supply of critical polyimide and PET materials. |
| European CE Marking Certification | Facilitates market entry for electronic equipment in the EU. |
Research Approach
Initial hypotheses were tested against primary input from R&D directors, OEM procurement leads, and specialized antenna engineers. Expert interviews combined with rigorous secondary validation informed the analysis. Secondary data sources included FCC filings, EU RoHS directives, and consumer electronics industry reports. A bottom-up approach to market sizing was triangulated with top-down validation.
Variance decomposition identified key drivers impacting market growth across the analysis window, including product type, technology, end-user, and application. The analytical framework modeled segment-specific growth trajectories, accounting for material cost fluctuations. Compound Annual Growth Rates were derived from historical data analysis and projected demand shifts. Key forecast inputs included 5G/6G deployment schedules and IoT device proliferation rates.
Underlying assumptions cover technological advancements and regulatory stability, with deviation risk concentrated in raw material price volatility. Global trade policy shifts also pose a significant revision risk. Revision becomes warranted when 5G/6G deployment rates diverge significantly from projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Middle East and Africa Temperature Sensors Market
Sensors and Controls
Global Battery Free RFID Sensor Market
Sensors and Controls
Doppler Lidar Market
Sensors and Controls
Global Actuator Sensor Interface Market
Sensors and Controls
Microseismic Monitoring Technology Market
Sensors and Controls
On-Board Magnetic Sensors Market
Sensors and Controls
North America Fingerprint Sensor Market
Sensors and Controls
Industrial Sensors Market
Sensors and Controls
PM2.5 Sensors Market
Sensors and Controls
Earthquake Sensor Market
Sensors and Controls
Middle East and Africa Wearable Sensors Market
Sensors and Controls
Ambient Light Sensor Market
Sensors and Controls
Global Hazardous Location Thermostats Market
Sensors and Controls
North America Temperature Sensor Market
Sensors and Controls
Asia-Pacific Touch Sensor Market
Sensors and Controls
Digital Automation Temperature Regulator Market