
 GCC Ceramic Tiles Market | 2026-2036
GCC Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Ceramic Tiles Market Intelligence
Modular large-format panel systems is pivoting buyer preference away from traditional small-tile specifications across GCC specification channels. RAK Ceramics leverages integrated manufacturing from frit to finished slab to sustain cost leadership in porcelain gres. Saudi Ceramic Company anchors domestic supply security through captive raw material sourcing in the kingdom's central region. Al Anwar Ceramic Tile Co. differentiates via specialized glaze chemistry adapted to Gulf climate extremes of thermal cycling and salinity.
Ceramic tiles are sintered clay-based surfacing materials fired at temperatures exceeding 1,000°C, engineered with controlled porosity, modulus of rupture, and dimensional stability for architectural envelope and interior finish applications. Porcelain and vitrified categories command premium positioning due to near-zero water absorption rates below 0.5% that satisfy exterior cladding and heavy-traffic flooring specifications in Gulf commercial developments. Flooring and wall cladding applications together absorb the dominant share of volume, with institutional end-user procurement—hospitals, airports, educational facilities—driving specification-grade margin pools through performance-certification requirements. Distribution runs through direct sales channels for project developers while retail stores and online platforms capture renovation and residential replacement cycles.
Gulf Standardization Organization harmonization protocols, Saudi Standards, Metrology and Quality Organization technical regulations, and UAE Ministry of Industry and Advanced Technology product registration requirements collectively govern market access and quality benchmarking across the six member states. These frameworks enforce slip resistance, chemical resistance, and lead-content thresholds that filter import supply and elevate local manufacturing competitiveness. Stakeholders must monitor evolving carbon-footprint disclosure obligations under GCC environmental cooperation frameworks and their projected impact on kiln-fuel sourcing and export eligibility.
Market Dynamics
Modular large-format panel systems are compressing traditional small-tile specifications across GCC specification channels, forcing manufacturers to retool kiln configurations and glaze chemistry for thinner, larger slabs. Saudi Arabia's SABER conformity program and UAE's ECAS certification are simultaneously elevating quality thresholds and filtering import supply.
Growth Catalysts
- SABER Technical Regulations:Saudi Standards, Metrology and Quality Organization mandates are accelerating specification-grade procurement by disqualifying non-conforming imports from giga-project supply chains.
- Hospital and Airport Construction:Institutional end-users in Riyadh and Jeddah corridors are driving certified porcelain volumes through performance-grade slip-resistance and chemical-resistance requirements.
- Captive Raw Material Bases:Domestic clay and feldspar deposits in Saudi Arabia's central region are insulating local manufacturers from freight cost volatility affecting import-dependent competitors.
Market Restraints
- Natural Gas Price Volatility:Kiln fuel represents 35-40% of production cost structure; Gulf spot market fluctuations compress margin predictability for continuous-firing operations.
- Import Concentration in Glaze Chemistry:Specialized zircon and rutile formulations remain concentrated among Italian and Spanish suppliers, creating input bottlenecks for premium finish tiers.
- Water Absorption Floor for Exterior Cladding:Porcelain gres below 0.5% absorption satisfies only 60% of GCC facade specifications; remaining applications require alternative envelope materials.
Strategic Opportunities
- Underpenetrated Qatar Hospitality Pipeline:Lusail City and Msheireb Downtown buildouts are specifying imported large-format panels where local supply gaps create white space for Saudi and UAE manufacturers.
- Carbon-Footprint Disclosure Mandates:GCC environmental cooperation frameworks are projected to impose kiln-fuel sourcing documentation, rewarding early adopters of renewable thermal energy with preferential procurement status.
- Digital Specification Platforms:BIM-integrated tile libraries are compressing architect decision cycles, enabling direct-to-designer channels that bypass traditional distributor markups.
Industry Challenges
- Glaze Chemist Talent Scarcity:Formulation expertise for Gulf climate extremes of thermal cycling and salinity remains concentrated among retiring European specialists, constraining R&D velocity.
- Continuous Kiln Capex Intensity:Large-format panel production requires roller-hearth kiln investments exceeding $15 million per line, limiting mid-scale manufacturer upgrade paths.
- Multi-Jurisdiction Certification Timelines:Parallel SABER, ECAS, and GSO harmonization approvals extend product launch cycles by 8-14 months for pan-GCC distribution strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Ceramic Tiles Market |
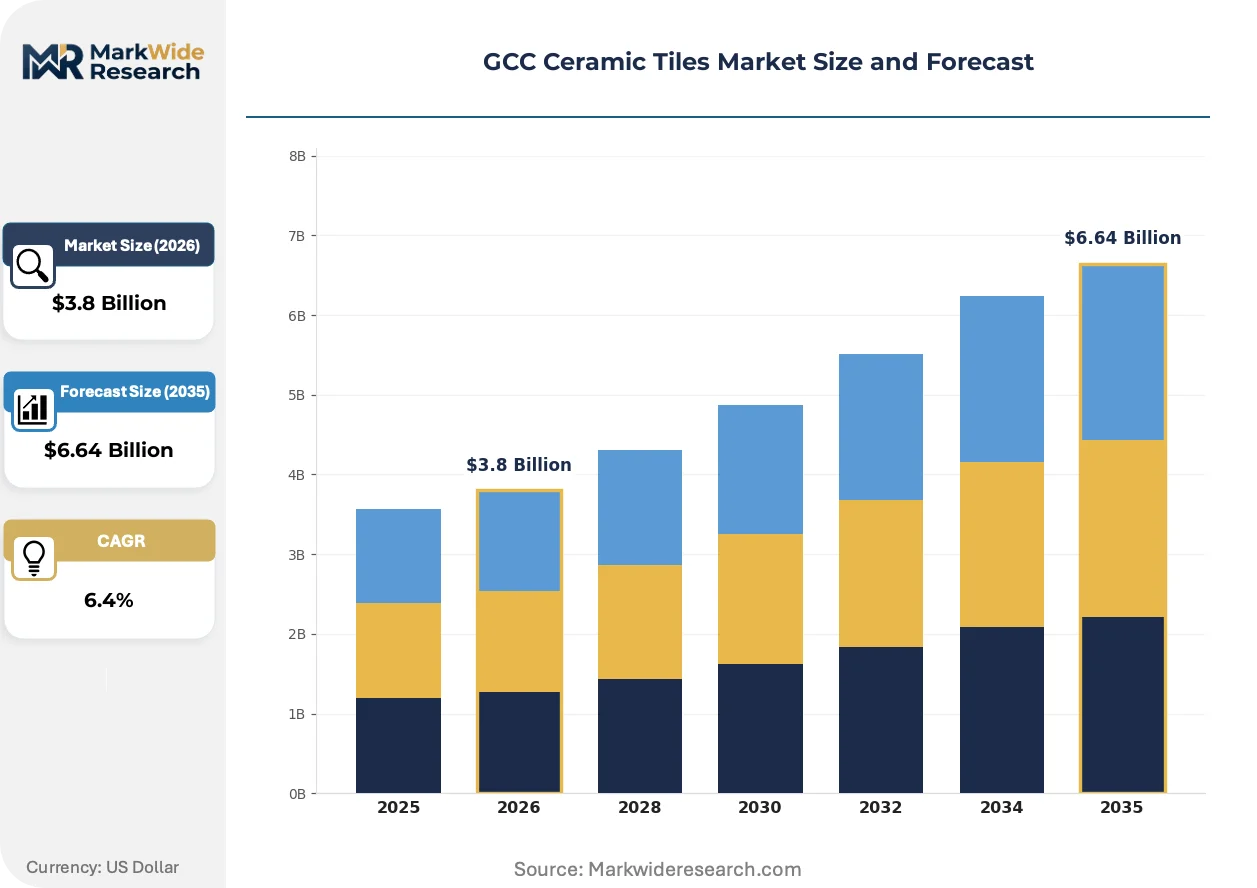
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitrified, Glazed, Porcelain, Rustic Application: Flooring, Wall Cladding, Countertops, Backsplashes End User: Residential, Commercial, Industrial, Institutional Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Wholesalers |
| Companies Covered | Porcelanosa Dubai, Al Khaleej Ceramics Co., RAK Ceramics, Riyadh Ceramics, Arabian Tile Company Limited, Saudi Ceramic Company, Kajaria Ceramics, Future Ceramics, Al Anwar Ceramic Tile Co., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Ceramic Tiles Market Strategic Shifts & Innovations
Digital inkjet decoration and thin-body porcelain technologies are converging to redefine surface aesthetics and installation economics across GCC commercial developments. These shifts are compressing traditional supply chain margins while opening specification access for domestic manufacturers.
Thin-body porcelain slabs measuring 3-6mm thickness are integrating large-format architectural envelope applications previously reserved for stone or composite panels. Hospital and airport developers in Riyadh are specifying these systems for weight-reduced cladding retrofits. The technology is integrating vertically with structural adhesive systems, eliminating traditional mortar-bed labor and compressing project timelines by 30-40%.
Gulf Standardization Organization harmonization protocols are mandating unified slip-resistance and lead-content thresholds across all six member states. This regulatory convergence is eliminating redundant testing burdens for manufacturers holding multiple national certifications. Saudi Arabia and UAE are responding fastest, with SABER and ECAS databases now cross-referencing GSO technical regulations to accelerate mutual recognition.
Architects and project developers are consolidating specification decisions around BIM-integrated material libraries that embed performance certification data directly into design workflows. Retail and renovation channels are losing influence over commercial project procurement as direct manufacturer-designer relationships disintermediate traditional distributor networks. This pattern is most visible in Jeddah's hospitality buildouts, where international hotel operators mandate digital specification trails for warranty compliance.
GCC Ceramic Tiles Market Segmentation
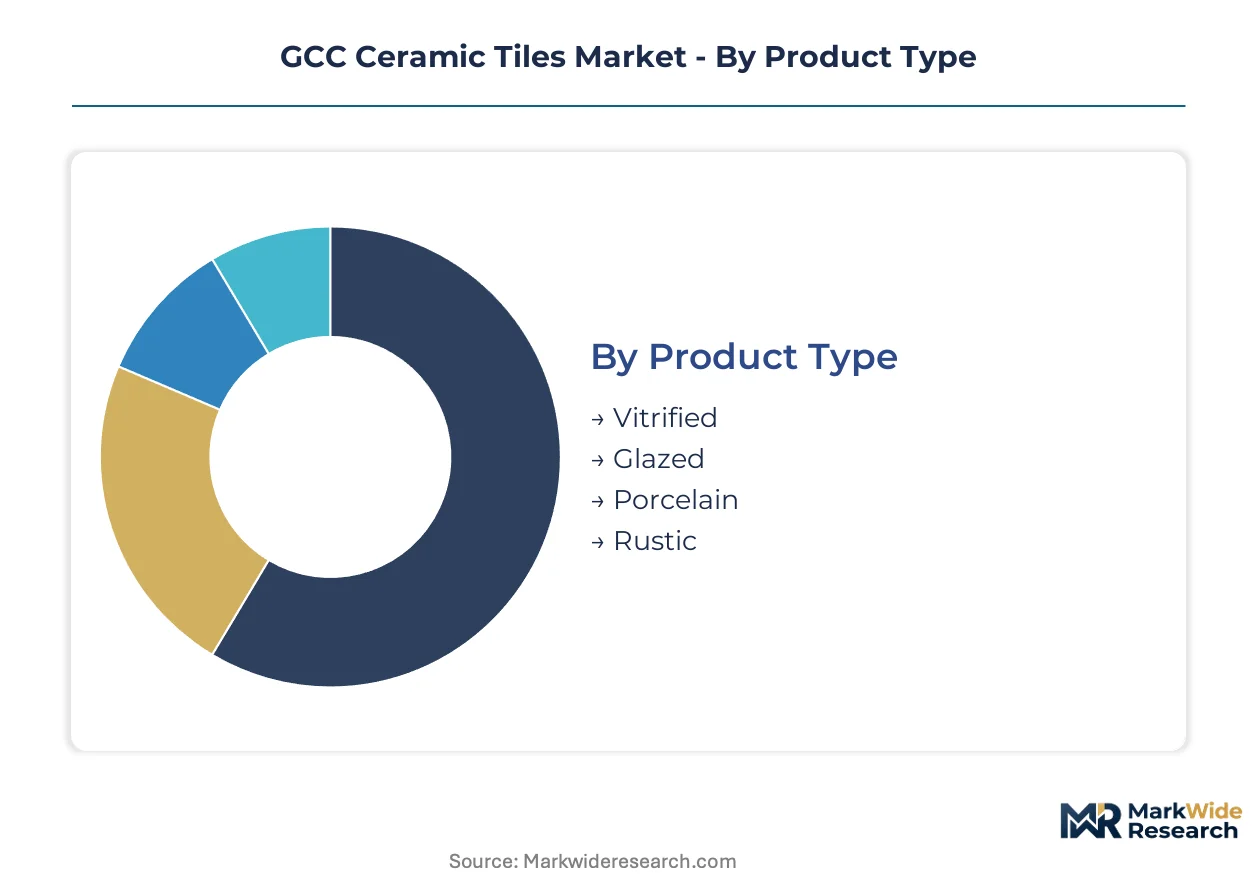
Segmentation in the GCC ceramic tiles market reveals how specification-grade procurement diverges across construction verticals. Product chemistry, application environment, and channel access each create distinct margin pools that manufacturers must navigate simultaneously.
Product Type:
Upgrade cycles in Saudi Arabia's giga-developments are compressing replacement timelines from traditional 15-20 year intervals toward 10-12 year refresh schedules.
- Vitrified:Fired at temperatures exceeding 1,200°C with near-zero porosity below 0.5% water absorption, these tiles satisfy heavy-traffic flooring specifications in Riyadh's airport terminals and hospital complexes. Demand concentrates in institutional corridors where slip-resistance certification under SABER technical regulations is mandatory.
- Porcelain:Engineered with controlled mineral composition for dimensional stability across thermal cycling extremes, porcelain commands specification priority in Jeddah's hospitality buildouts. Coastal salinity exposure drives procurement toward through-body color consistency rather than surface-glaze alternatives.
- Glazed:Surface-applied glass coatings enable aesthetic differentiation at moderate cost tiers, capturing residential renovation cycles in Dubai's villa districts.
- Rustic:Textured finishes with higher water absorption rates serve interior accent applications where performance certification requirements are relaxed.
Volume placements concentrate in vitrified; the faster expansion belongs to porcelain as facade specifications tighten.
Application:
Cost tier stratification across GCC project budgets is fragmenting procurement patterns between premium specification channels and economy replacement markets.
- Flooring:Dominant volume category absorbing institutional wear-resistance requirements. Riyadh hospital procurement mandates dynamic coefficient of friction testing that filters out substandard imports.
- Wall Cladding:Thin-body porcelain panels measuring 3-6mm are displacing traditional stone in Jeddah commercial retrofits, cutting installed weight by 60%.
- Countertops:Compact sintered surfaces with stain-resistant nano-coatings serve high-end residential kitchens in Doha's Pearl-Qatar developments.
- Backsplashes:Decorative inkjet-printed tiles capture renovation spend with shorter decision cycles and lower certification burdens.
Margin pools concentrate in wall cladding; flooring retains volume dominance across the six member states.
End User:
Customer type differentiation separates project developers with direct manufacturer relationships from retail-dependent residential buyers.
- Institutional:Hospitals, airports, and educational facilities drive certified porcelain volumes through performance-grade specifications. SABER conformity documentation is non-negotiable for Saudi Ministry of Health procurement.
- Commercial:Hospitality and retail developers in Lusail City specify large-format panels where local supply gaps create import dependency.
- Residential:Villa and apartment construction in Dubai's suburban corridors favors mid-tier glazed products through retail distributor networks.
- Industrial:Warehousing and logistics facilities prioritize chemical resistance over aesthetic finish, accepting higher water absorption rates.
Procurement authority concentrates in institutional buyers; commercial segments are climbing the fastest as Qatar's hospitality pipeline accelerates.
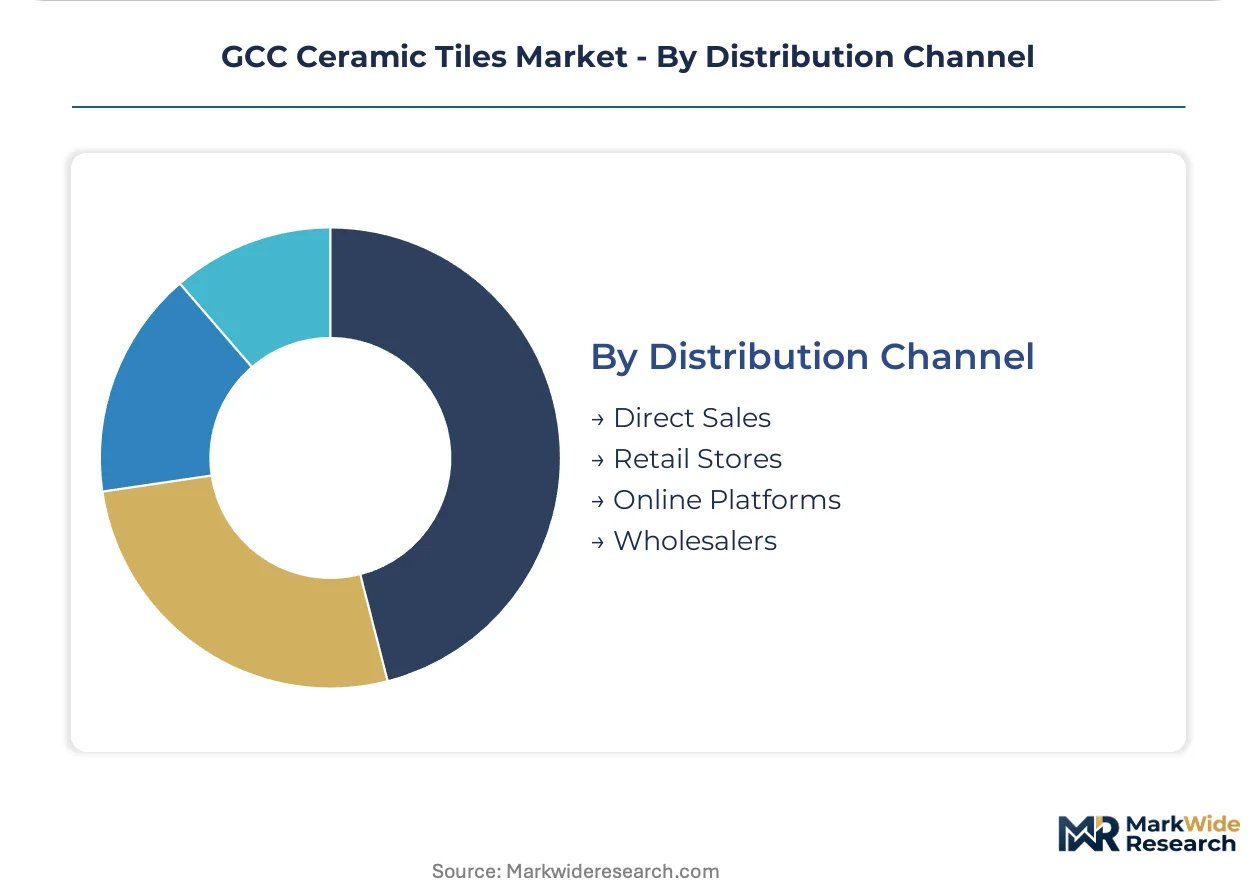
Distribution Channel:
Supply concentration among project-direct channels is marginalizing traditional wholesaler roles in specification-grade segments.
- Direct Sales:Manufacturer-to-developer relationships dominate giga-project procurement in Saudi Arabia's NEOM and Red Sea Global developments. BIM-integrated specification libraries are compressing architect decision cycles.
- Retail Stores:Showroom networks capture renovation and residential replacement demand across UAE's emirate-level distributor footprints.
- Online Platforms:Digital procurement is gaining traction in standardized product categories where physical inspection is less critical.
- Wholesalers:Bulk intermediaries serve smaller contractors in Bahrain and Oman where project scale does not justify direct manufacturer engagement.
Revenue concentration sits with direct sales; online platforms are expanding most quickly as digital specification tools mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Saudi Arabia's central region while consumption pulls toward coastal urban corridors. Domestic manufacturers leverage captive clay deposits to serve Riyadh's giga-developments. Import dependency persists in Qatar and Kuwait where local supply gaps remain acute.
Saudi Arabia
Riyadh's NEOM and Red Sea Global developments are absorbing specification-grade porcelain volumes through direct manufacturer contracts. SABER technical regulations under the Saudi Standards, Metrology and Quality Organization disqualify non-conforming imports from Ministry of Health procurement. Jeddah's hospitality buildouts along the western corridor specify through-body porcelain for coastal salinity resistance.
United Arab Emirates
Dubai's villa renovation cycles sustain mid-tier glazed product demand through retail distributor networks. The Emirates Conformity Assessment Scheme mandates product registration under the Ministry of Industry and Advanced Technology for all construction material imports. Abu Dhabi's institutional projects specify large-format panels where BIM-integrated specification libraries compress architect decision cycles.
Qatar
Lusail City and Msheireb Downtown hospitality buildouts are specifying imported large-format panels where local manufacturing gaps create supply bottlenecks. The Qatar General Organization for Standard and Metrology enforces Gulf Standardization Organization harmonization protocols for slip-resistance certification. Doha's Pearl-Qatar developments anchor premium countertop demand for compact sintered surfaces.
Kuwait
Residential construction in Kuwait City's southern corridor favors economy-tier glazed tiles through wholesale import channels. The Public Authority for Industry administers mandatory conformity marking for ceramic products entering customs. Salmiya's retail showroom clusters serve renovation demand from expatriate housing stock.
Oman
Muscat's airport and hospital expansions are driving certified porcelain procurement through performance-grade specifications. The Ministry of Commerce, Industry and Investment Promotion aligns national standards with Gulf Standardization Organization technical regulations. Sohar's industrial zone hosts warehousing and logistics facilities prioritizing chemical-resistant flooring over aesthetic finish tiers.
GCC Ceramic Tiles Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across specification-grade and economy-tier segments. Market structure shows moderate consolidation around integrated manufacturers with captive raw material bases. Three archetypes dominate: vertically integrated domestic producers with kiln-to-quarry control, import-dependent distributors serving retail renovation cycles, and specialized glaze chemistry houses targeting institutional certification requirements. Competitive moves center on capacity expansion for large-format panel production and strategic partnerships with project developers for giga-development supply chain integration.
Among integrated manufacturers, RAK Ceramics, Saudi Ceramic Company, and Al Anwar Ceramic Tile Co. occupy positions spanning production scale and technical specialization. RAK Ceramics exemplifies the scale-driven archetype with manufacturing breadth across the product spectrum. Saudi Ceramic Company represents domestic supply security through captive raw material sourcing in the kingdom's central region. Al Anwar Ceramic Tile Co. anchors the specialized tier with differentiated glaze chemistry adapted to Gulf climate extremes.
| Leading Market Players |
|---|
| Porcelanosa Dubai |
| Al Khaleej Ceramics Co. |
| RAK Ceramics |
| Riyadh Ceramics |
| Arabian Tile Company Limited |
| Saudi Ceramic Company |
| Kajaria Ceramics |
| Future Ceramics |
| Al Anwar Ceramic Tile Co. |
| Others |
Cost & Logistics Intelligence
Backward integration into captive clay and feldspar deposits anchors Saudi manufacturers' cost position against import-dependent competitors while insulating their pricing power from freight volatility. This upstream control over mineral inputs compresses delivered cost structures for domestic producers serving Riyadh's giga-developments, even as natural gas kiln fuel exposes margins to Gulf spot market swings.
Pricing Analysis
Margin tightening in specification-grade porcelain traces to SABER and ECAS certification burdens that filter substandard imports and concentrate procurement among compliant domestic manufacturers. Three-tier pricing structure across premium certified, standard commercial, and economy residential levels separates institutional buyers from renovation retail channels. Cost-down pressure on mid-tier glazed products accelerates as Dubai's villa districts shift volume toward direct-import alternatives. Hospital and airport developers show least price sensitivity due to warranty compliance mandates, while residential replacement buyers negotiate aggressively on per-square-meter rates.
Supply Chain Analysis
Single-source vulnerability sits with Italian and Spanish suppliers for specialized zircon and rutile glaze formulations that Gulf manufacturers cannot replicate domestically. Raw material sourcing draws from Saudi Arabia's central region clay deposits, UAE's processed feldspar imports, and Oman's limestone reserves for body composition. Supply chain risk centers on regulatory restriction as SABER and ECAS timelines extend product launch cycles. Distribution runs through direct manufacturer-developer channels for NEOM-scale projects alongside retail showroom networks capturing Dubai's renovation cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC ceramic tiles market sits in a technology-transition phase as thin-body porcelain panels displace traditional stone and composite cladding systems across commercial envelope specifications.
For Market Incumbents: Cement specification-grade positioning through SABER pre-certification investments that disqualify import competitors from Ministry of Health procurement. Deepen captive raw material bases beyond current central Saudi deposits to offset glaze chemistry import dependency threatening margin stability. Prioritize roller-hearth kiln capacity additions for large-format panel production as architect specifications shift toward 3-6mm thickness categories. For New Entrants and Emerging Players: BIM-integrated digital specification platforms offer direct-to-designer channel access that bypasses established distributor markups in Jeddah hospitality buildouts. Target Qatar's underpenetrated hospitality pipeline where Lusail City and Msheireb Downtown create supply gaps for Saudi and UAE manufacturers with ECAS-compliant large-format inventory. Lead with carbon-footprint documentation capabilities to capture early preferential procurement status under projected GCC environmental cooperation frameworks. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated manufacturers with kiln-to-quarry control and established SABER certification databases. Long-term viability favors archetypes with demonstrated glaze chemistry adaptation to Gulf thermal cycling and salinity extremes. Watch for inflection signals in renewable thermal energy adoption rates as kiln-fuel sourcing documentation mandates reshape procurement eligibility criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Large-Format Panel Capacity Expansion | Captures architect specification shifts away from traditional small-tile procurement in Saudi giga-developments. |
| Captive Glaze Chemistry Development | Reduces Italian and Spanish import dependency for zircon and rutile formulations serving premium finish tiers. |
| SABER Pre-Certification Investment | Secures Ministry of Health procurement eligibility before competitor products complete technical regulation compliance. |
| BIM-Integrated Specification Platform Launch | Compresses architect decision cycles and disintermediates traditional distributor markups in commercial channels. |
| Renewable Thermal Energy Transition | Positions for preferential procurement status under projected GCC carbon-footprint disclosure mandates. |
Research Approach
Document review covered trade customs data, Gulf Standardization Organization technical regulations, and Saudi Standards, Metrology and Quality Organization filings, complemented by interviews with plant operations directors at integrated manufacturers, procurement leads at hospital and airport developers, specification architects in Riyadh and Jeddah corridors, and distributor channel managers across UAE emirates. Secondary validation drew from SABER and ECAS certification databases, construction project tracking systems, and mineral import records. Bottom-up volume estimates triangulated against top-down construction spend allocations across the six member states.
Cross-referencing historical production capacity expansion patterns against panel-based forecast inputs anchored volume projections across the analysis window. Segmentation dimensions modeled include product chemistry tier, application environment, end-user procurement authority, and distribution channel access. CAGRs derived from weighted average of demand elasticity coefficients and supply-side capacity constraints. Industry-specific inputs incorporated kiln fuel cost volatility bands and certification timeline distributions for multi-jurisdiction product launches.
The model holds under stable regulatory harmonization trajectories; deviation in SABER-ECAS mutual recognition timelines or natural gas price spikes would shift volume and value outputs. Forecasts reflect assumptions around giga-development construction continuity and architect specification adoption rates for thin-body porcelain systems. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Education Building Design Market
Building & Construction Materials
Saudi Arabia Sanitaryware Market
Building & Construction Materials
Building Insulation Market
Building & Construction Materials
Dimension Stone Market
Building & Construction Materials
North America Particle Board Market
Building & Construction Materials
Residential Energy Efficient Windows Market
Building & Construction Materials
Geofoam Market
Building & Construction Materials
US Retractable Roofing System Market
Building & Construction Materials
Autoclaved Aerated Concrete (AAC) Blocks Market
Building & Construction Materials
Steel Wire Rope Products Market
Building & Construction Materials
Vinyl Windows Market
Building & Construction Materials
Global Steel Wire Rod Market
Building & Construction Materials
Door System Market
Building & Construction Materials
India Particle Board Market
Building & Construction Materials
Sliding Bearing Market
Building & Construction Materials
Egypt Prefab Wood Buildings Market