
 Indonesia Cement Market | 2026-2036
Indonesia Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Cement Market Insights
Residential construction is expanding as Indonesia's urban population shifts toward mid-rise housing and township developments. Semen Indonesia leverages integrated quarry-to-distribution networks across Java and Sulawesi. Indocement Tunggal Prakarsa sustains premium positioning through specialized mortar and ready-mix product lines. Holcim Indonesia anchors its position in sustainable building material solutions for commercial developments.
Cement is a hydraulic binder composed primarily of calcium silicates, produced by calcining limestone and clay at approximately 1,450°C, then grinding the resulting clinker with gypsum to control setting time. Its primary purpose is to bind sand and aggregate into concrete for structural load-bearing applications. Portland cement dominates volume due to universal building code acceptance, while blended cement variants are gaining share as fly ash and slag additives reduce clinker content and lower carbon intensity. White cement occupies a narrow premium tier serving architectural finishes and decorative precast segments where color consistency commands margin premiums.
The Ministry of Public Works and Housing enforces SNI standards that mandate compressive strength testing and chemical composition limits for all domestically produced cement. BIS-equivalent import certification requirements restrict non-compliant foreign supply from penetrating Indonesian project tenders. Stakeholders must monitor evolving green building regulations and alternative fuel substitution mandates that will reshape kiln economics and product certification pathways.
Market Dynamics
The Ministry of Public Works and Housing's SNI certification mandate is compressing supply-side flexibility while infrastructure corridors across Java and Sumatra absorb rising volumes. This regulatory anchoring reshapes competitive positioning around compliance infrastructure rather than pure scale economics.
Growth Catalysts
- Nusantara Capital Relocation:The new capital city project in East Kalimantan demands millions of tonnes of structural concrete for government buildings, residential districts, and transport links.
- SNI 7064:2014 Enforcement:Mandatory compressive strength testing and chemical composition limits create quality-tier differentiation that rewards certified domestic producers in public tenders.
- Geothermal Kiln Integration:Alternative fuel substitution using palm kernel shells and rice husks is lowering operational carbon intensity for producers with captive biomass supply.
Market Restraints
- Clinker Import Dependency:Domestic limestone quality variations force reliance on Vietnamese and Chinese clinker for high-grade Portland production, exposing margins to shipping cost volatility.
- Java-Locked Distribution:Seventy percent of grinding capacity sits within 200 kilometers of Jakarta, creating logistical bottlenecks for Eastern Indonesia projects.
- Blended Cement Performance Ceiling:Fly ash and slag additive ratios above 35 percent compromise early-age strength, limiting substitution in high-rise structural applications.
Strategic Opportunities
- Papua Infrastructure Gap:Trans-Papua highway segments and border post construction remain underserved by existing supply networks, rewarding mobile grinding plant investments.
- Green Building Certification:The government's GREENSHIP rating system creates premium positioning for low-carbon cement variants in commercial developments targeting ESG compliance.
- Ready-Mix Channel Expansion:Project-scale batching plant partnerships with state-owned contractors bypass bagged cement competition and lock in volume commitments.
Industry Challenges
- Alternative Fuel Handling Expertise:Biomass co-processing requires kiln operators trained in combustion chemistry and emissions control, a skill set scarce outside Semen Indonesia's Sulawesi operations.
- SNI Audit Timeline Compression:Certification renewal cycles now demand quarterly third-party testing, straining laboratory capacity and delaying product release schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Cement Market |
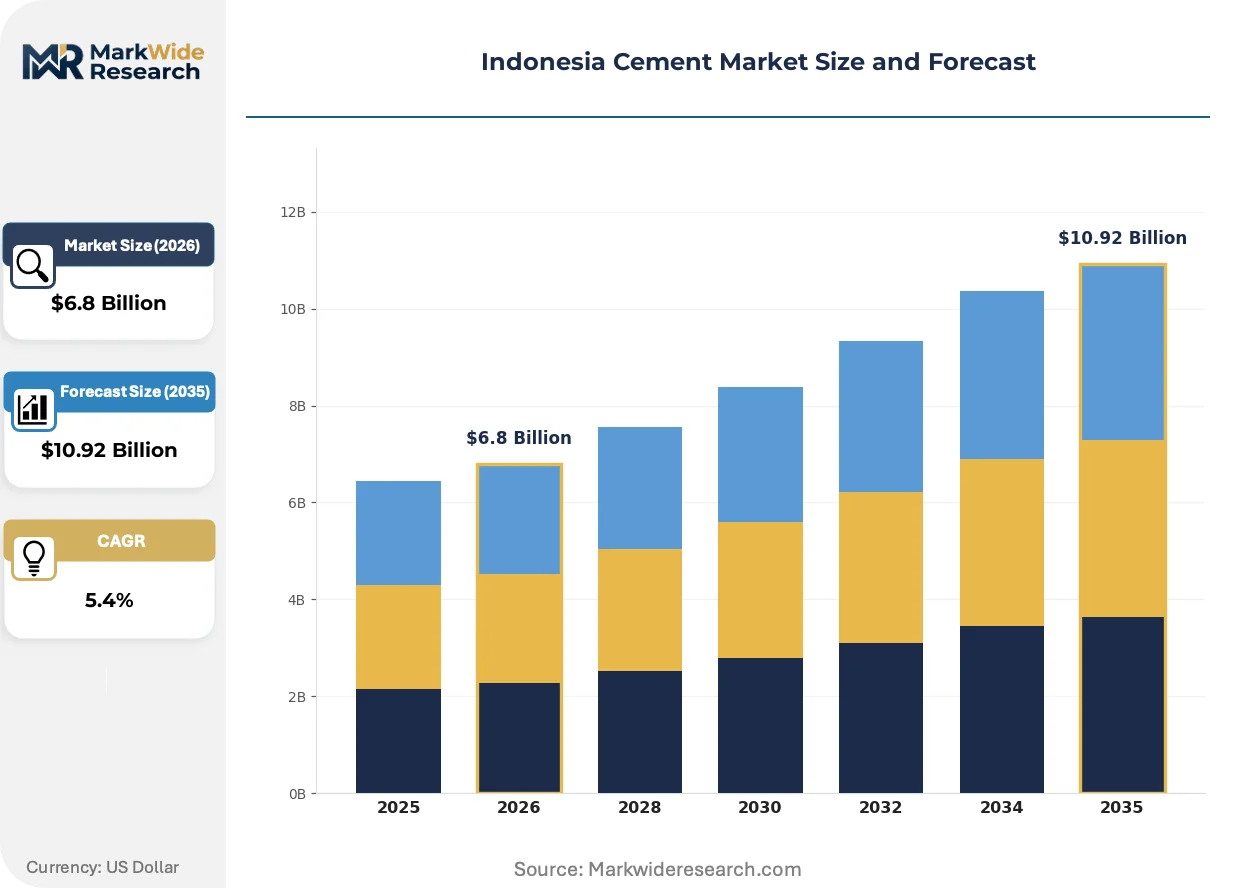
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portland Cement, Blended Cement, White Cement, Oil Well Cement End User: Residential Construction, Commercial Construction, Infrastructure Projects, Industrial Applications Distribution Channel: Direct Sales, Wholesale Distributors, Retail Outlets, Online Sales Packaging Type: Bags, Bulk, Pallets, Containers |
| Companies Covered | Semen Indonesia, Indocement Tunggal Prakarsa, Holcim Indonesia, Semen Padang, Semen Gresik, Bosowa Corporation, Semen Baturaja, Anhui Conch Cement Indonesia, Cemindo Gemilang, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Cement Market Trends and Innovations
Digital quality control systems and alternative fuel chemistry are converging to redefine production economics. Regulatory pressure on embodied carbon is accelerating technology adoption timelines.
Calcined clay activation is integrating into grinding circuits as a supplementary cementitious material that maintains strength performance while reducing clinker factors below 50 percent. State-owned contractors in the Nusantara corridor are specifying LC3 blends for foundation work, compressing the payback period for kiln retrofits from seven years to four.
The Ministry of Public Works and Housing is expanding SNI scope to cover imported bagged cement, requiring foreign suppliers to establish domestic testing partnerships. This friction is redirecting project procurement toward integrated domestic producers with captive laboratory networks, particularly affecting Sulawesi and Maluku island developments.
Project developers are consolidating purchase decisions through centralized procurement offices rather than site-level purchasing. Large township developers in Greater Jakarta now contract annual volume agreements directly with grinding plant operators, displacing the traditional distributor layer and compressing price negotiation cycles from quarterly to monthly intervals.
Indonesia Cement Market Segmentation
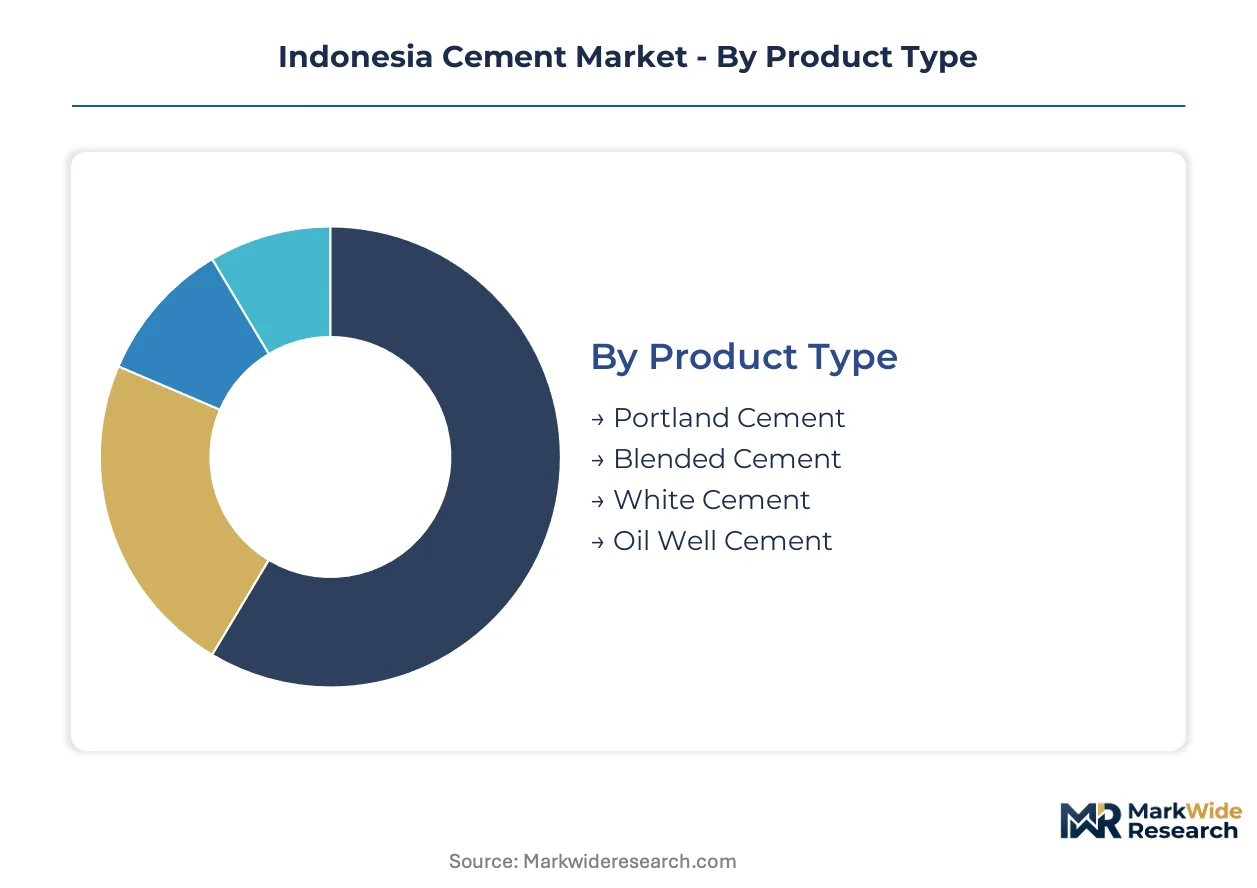
Segmentation in the Indonesia cement market reveals how product specifications, channel structures, and packaging formats align with distinct construction workflows across Java's metropolitan corridor and Eastern Indonesia's infrastructure frontier. Understanding these divisions exposes where margin capture concentrates and where logistical constraints reshape competitive access.
Product Type:
Portland cement functions as a standalone structural binder requiring no blending at site, while blended and specialty variants embed into pre-mixed formulations or architectural finishes demanding tighter quality control.
- Portland Cement:Composed of ground clinker with 3-5% gypsum addition, achieving compressive strength ratings of 32.5-52.5 MPa under SNI 7064:2014 testing protocols. Demand concentrates in high-rise structural frames across Jakarta's Sudirman Central Business District and Surabaya's industrial zones, where early-age strength development determines construction scheduling. Clinker import dependency from Vietnamese suppliers constrains margin stability for domestic producers.
- Blended Cement:Incorporates fly ash, slag, or volcanic pozzolan at 15-35% substitution rates, reducing embodied carbon intensity while maintaining SNI-compliant performance thresholds. State-owned contractors in the Nusantara capital corridor specify these variants for foundation work, compressing payback periods for kiln retrofits. Early-age strength limitations above 35% additive ratios restrict deployment in vertical structural elements.
- White Cement:Manufactured from low-iron kaolin clinker with controlled manganese and chromium content, delivering consistent coloration for architectural precast and decorative finishes. Boutique demand from luxury township developers in Greater Jakarta sustains premium positioning.
- Oil Well Cement:Formulated with strict sulfate resistance and thickening time controls for geothermal drilling applications in Sulawesi and Sumatra's energy corridors. Pertamina's upstream operations anchor procurement volumes.
Portland cement leads volumes today; blended cement is gaining share fastest.
End User:
Cost tier segmentation separates project-scale volume commitments from fragmented retail demand, with infrastructure tenders commanding lowest unit economics and industrial applications extracting premium specifications.
- Residential Construction:Mid-rise housing and township developments across Bekasi, Tangerang, and Sidoarjo absorb bagged cement through distributor networks. Developer consolidation into centralized procurement offices compresses price negotiation cycles from quarterly to monthly intervals.
- Commercial Construction:Office towers and retail complexes in Jakarta's CBD specify ready-mix concrete partnerships that bypass bagged distribution entirely. GREENSHIP certification requirements for low-carbon variants reshape material specifications.
- Infrastructure Projects:Trans-Java toll roads, Nusantara capital construction, and Trans-Papua highway segments demand bulk delivery contracts with penalty clauses for supply interruption. Ministry of Public Works and Housing mandates SNI certification for all structural applications.
- Industrial Applications:Manufacturing facility foundations, mining processing plants, and smelter construction in Morowali and Weda Bay require sulfate-resistant and rapid-hardening specialty formulations. Nickel processing investments in Central Sulawesi anchor regional demand.
Infrastructure projects command the largest single-contract volumes; residential construction contributes the broadest geographic dispersion.
Distribution Channel:
Channel selection determines working capital intensity and price transparency, with direct sales embedding producers into project cash flows while wholesale networks fragment margin capture across multiple intermediaries.
- Direct Sales:Annual volume agreements between grinding plant operators and state-owned contractors or large township developers eliminate distributor markups. Semen Indonesia and Indocement Tunggal Prakarsa deploy dedicated logistics fleets for Nusantara corridor commitments.
- Wholesale Distributors:Regional aggregators in Surabaya, Medan, and Makassar consolidate bagged cement from multiple producers for resale to smaller contractors. Java-locked grinding capacity creates logistical bottlenecks for Eastern Indonesia projects.
- Retail Outlets:Hardware stores and building material depots serve individual homeowners and micro-contractors with 50kg bagged units. Price competition intensifies in Greater Jakarta's saturated distribution network.
- Online Sales:E-commerce platforms and project procurement portals facilitate price comparison and bulk ordering for mid-tier contractors. Digital penetration remains constrained by cement's weight-to-value ratio and last-mile delivery complexity.
Direct sales channels deliver the highest margin realization; wholesale distributors retain the deepest geographic penetration.
Packaging Type:
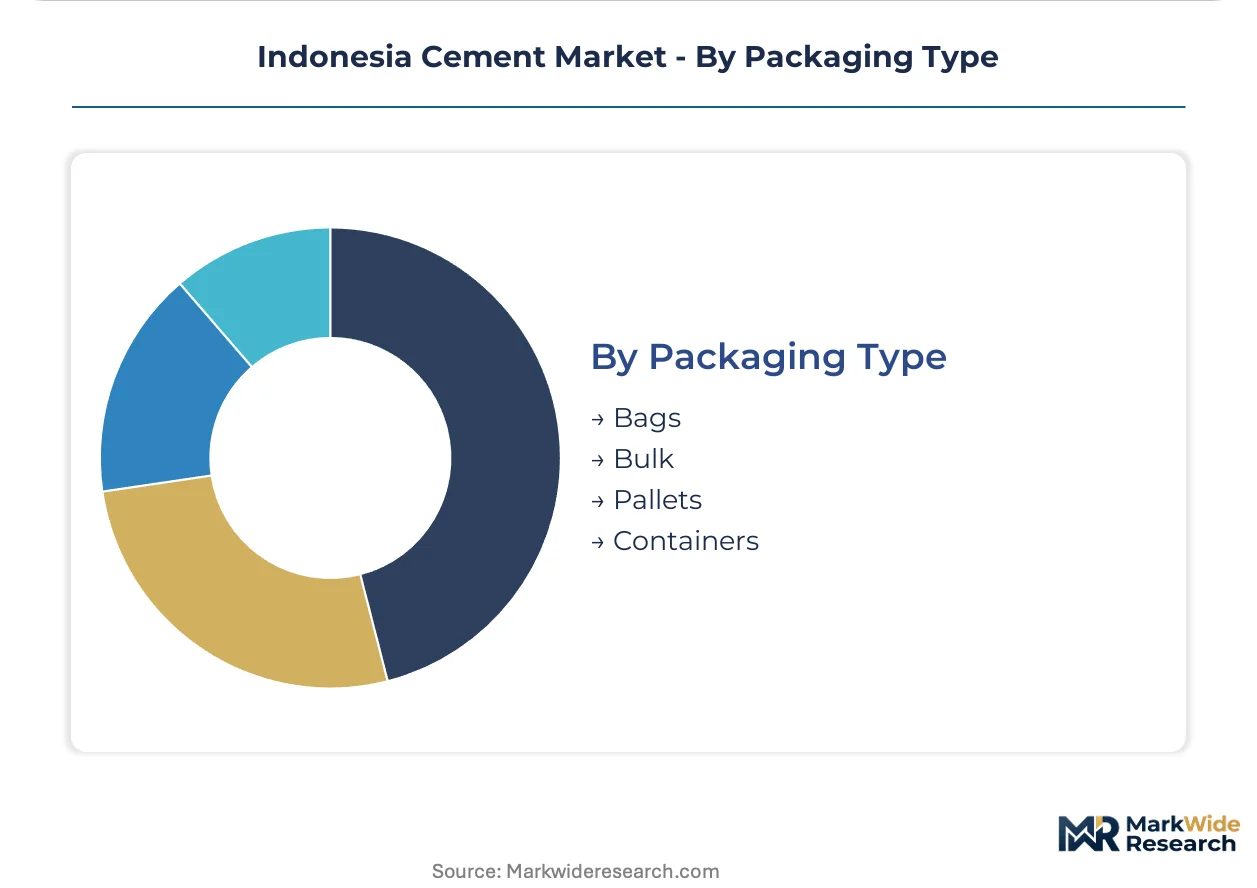
Packaging format correlates with customer scale and handling infrastructure, with bulk delivery requiring captive silo investment while bagged formats maximize flexibility for fragmented demand.
- Bags:50kg multi-layer paper or woven polypropylene sacks dominate residential and small commercial applications. Manual handling requirements limit efficiency but enable distribution to sites lacking pneumatic unloading equipment.
- Bulk:Pneumatic tanker delivery to project-site silos minimizes packaging cost and spillage for infrastructure and large commercial developments. Nusantara capital construction mandates bulk supply for government building contracts.
- Pallets:Unitized loads of 40-50 bags facilitate mechanical handling at ready-mix batching plants and large retail depots. Standardization around 1.2m x 1.0m pallet dimensions enables intermodal transfer.
- Containers:Maritime containerization supports clinker import logistics from Vietnamese and Chinese suppliers, with 20-foot dry containers holding approximately 25 tonnes of granular material.
Bagged cement dominates unit volume; bulk delivery is expanding most quickly in infrastructure corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Java's metropolitan corridor anchors national cement consumption through Jakarta's vertical construction density and Surabaya's industrial expansion. The Ministry of Public Works and Housing channels infrastructure investment across Sumatra and Kalimantan while SNI certification requirements reshape regional supply access.
Java
Jakarta's Sudirman Central Business District and Bekasi-Tangerang township corridors absorb bulk cement volumes for high-rise structural frames. The Ministry of Public Works and Housing mandates SNI 7064:2014 certification for all government building contracts. East Java industrial zones around Gresik and Sidoarjo concentrate grinding capacity within 200 kilometers of Surabaya's port infrastructure.
Sumatra
Trans-Sumatra toll road segments and Medan's commercial development drive bagged cement demand through distributor networks. The Ministry of Public Works and Housing enforces SNI standards for all structural applications in public tenders. North Sumatra's Deli Serdang regency hosts cement terminals serving Aceh border post construction and palm oil processing facility foundations.
Kalimantan
Nusantara capital relocation in East Kalimantan commands millions of tonnes for government buildings, residential districts, and transport links. State-owned contractors specify LC3 blended cement variants for foundation work to meet GREENSHIP rating requirements. Balikpapan and Samarinda anchor logistics networks for mobile grinding plant deployment into underserved interior highway segments.
Sulawesi
Nickel processing investments in Morowali and Weda Bay Industrial Park require sulfate-resistant specialty formulations for smelter construction. Pertamina's geothermal drilling operations in South Sulawesi anchor oil well cement procurement volumes. Semen Indonesia's captive biomass supply from palm kernel shells and rice husks lowers operational carbon intensity for kiln operations.
Papua
Trans-Papua highway segments and border post construction remain underserved by existing Java-locked distribution networks. Mobile grinding plant investments face logistical constraints from port infrastructure limitations in Jayapura and Merauke. Indonesian military and civilian administration construction programs generate concentrated demand bursts for rapid-hardening cement variants.
Indonesia Cement Market Competitive Landscape
Capacity expansion dominates the current landscape as producers retrofit kilns for calcined clay activation and alternative fuel integration. The market structure concentrates around three integrated domestic groups with captive quarry-to-distribution networks, supplemented by regional specialists and one foreign-backed entrant. Strategic archetypes separate vertically integrated national champions from Sulawesi-focused biomass innovators and Chinese-backed scale players. Competitive moves center on SNI certification infrastructure investment and direct sales channel development with state-owned contractors.
Within the integrated national champion tier, Semen Indonesia and Semen Gresik exemplify quarry-to-distribution control across Java and Sulawesi. Among premium-positioned specialists, Indocement Tunggal Prakarsa occupies a position serving ready-mix and specialized mortar segments. At the foreign-backed scale end, Anhui Conch Cement Indonesia represents Chinese clinker import integration into domestic grinding operations. These three anchors illustrate how SNI compliance infrastructure and biomass fuel access determine competitive positioning.
| Leading Market Players |
|---|
| Semen Indonesia |
| Indocement Tunggal Prakarsa |
| Holcim Indonesia |
| Semen Padang |
| Semen Gresik |
| Bosowa Corporation |
| Semen Baturaja |
| Anhui Conch Cement Indonesia |
| Cemindo Gemilang |
| Others |
Pricing and Supply Chain Analysis
Centralized procurement offices at large township developers in Greater Jakarta now contract annual volume agreements directly with grinding plant operators, eliminating distributor markups and compressing price negotiation cycles from quarterly to monthly intervals. This buyer consolidation forces supply-side restructuring around direct sales channel investment and captive logistics fleet deployment.
Pricing Analysis
Clinker import costs from Vietnamese and Chinese suppliers pass through into domestic Portland cement pricing, with shipping cost volatility exposing margin stability for producers lacking captive quarry resources. Three-tier pricing structure across SNI-certified premium grades, standard blended variants, and economy bagged products differentiates by certification level and volume scale. Cost compression in the economy tier intensifies as distributor networks fragment margin capture across multiple intermediaries. Small contractors and individual homeowners exhibit highest price sensitivity, while state-owned infrastructure contractors prioritize supply security over unit cost.
Supply Chain Analysis
Regional distribution centers in Surabaya, Medan, and Makassar operate as hub-and-spoke consolidation points for bagged cement moving into Eastern Indonesia, though Java-locked grinding capacity creates persistent logistical bottlenecks. Domestic production draws from limestone quarries across Java and Sulawesi, with rice husk and palm kernel shell biomass feeding alternative fuel substitution programs. Single-source vulnerability to Vietnamese clinker imports exposes margins to maritime freight volatility. Distribution runs through direct sales to state contractors, wholesale distributor networks, and retail hardware depots serving fragmented residential demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where SNI certification mandates and GREENSHIP rating requirements continuously reshape procurement specifications and quality-tier premiums.
For Market Incumbents: Cement SNI laboratory network expansion and quarterly third-party testing capacity as defensive moats against certification renewal timeline compression. Secure captive biomass supply contracts in Sulawesi to anchor alternative fuel cost advantages while retrofitting kilns for calcined clay activation to meet LC3 specification demand from Nusantara corridor contractors. For New Entrants and Emerging Players: Mobile grinding plant deployments into Papua's Trans-Papua highway segments offer white-space access where Java-locked distribution networks fail to reach. Target nickel processing facility construction in Morowali and Weda Bay for sulfate-resistant specialty cement procurement. Establish ready-mix batching plant partnerships with state-owned contractors to bypass saturated bagged cement competition in Greater Jakarta. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated domestic producers possessing captive quarry-to-distribution control and SNI-compliant laboratory infrastructure. Long-term viability favors asset-light grinding operators with biomass fuel access over clinker-import-dependent scale players. Monitor Nusantara capital construction contract awards as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Calcined Clay Kiln Retrofit | LC3 blend capability captures Nusantara foundation specifications and compresses retrofit payback periods. |
| Biomass Fuel Integration | Palm kernel shell and rice husk co-processing lowers carbon intensity for GREENSHIP-compliant commercial developments. |
| Mobile Grinding Plant Deployment | Papua and Eastern Indonesia infrastructure gaps reward flexible production assets near underserved project sites. |
| Direct Sales Channel Expansion | Annual volume agreements with state-owned contractors eliminate distributor markups and lock in committed offtake. |
| SNI Laboratory Network Investment | Captive testing infrastructure accelerates certification renewal cycles and blocks non-compliant foreign supply from tenders. |
Research Methodology
Multiple input streams — executive interviews with cement plant operations directors, procurement leads at state-owned contractors, and distribution channel partners; customs and trade data; Ministry of Public Works and Housing SNI certification records; and producer financial disclosures — were reconciled through bottom-up volume modeling and top-down market sizing triangulation. Secondary validation drew from industry association production statistics, infrastructure project development databases, and regional construction permit filings.
Data-stream reconciliation across product type, end-use sector, distribution channel, and regional demand cluster dimensions produced volume and value outputs over the projection horizon. CAGRs were derived from segment-level growth trajectory analysis incorporating Nusantara capital construction timelines, GREENSHIP certification adoption curves, and alternative fuel substitution rates in kiln operations.
Underlying measurement precision varies by segment; Portland cement and infrastructure end-use carry tighter precision than specialty formulations and industrial applications. Forecasts reflect assumptions around SNI enforcement continuity, clinker import cost trajectories, and biomass fuel supply stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Roofing Liners Market
Building & Construction Materials
Marble Market
Building & Construction Materials
Autoclaved Aerated Concrete (AAC) Blocks Market
Building & Construction Materials
Saudi Arabia Tiles Market
Building & Construction Materials
Household Mosaic Tiles Market
Building & Construction Materials
Concrete Waterproofing with Crystalline Technology Market
Building & Construction Materials
Precast Concrete Pile Market
Building & Construction Materials
Sandwich Panel System Market
Building & Construction Materials
Ball Iron Rods Market
Building & Construction Materials
North America Ceiling Tiles Market
Building & Construction Materials
North America Rainscreen Cladding Market
Building & Construction Materials
Europe I-Joist Market
Building & Construction Materials
North America Concrete Conditioner Market
Building & Construction Materials
Building Modules Market
Building & Construction Materials
Roofing Tiles Market
Building & Construction Materials
Manufactured Sand Market