
 PU Waterstops Market | 2026-2036
PU Waterstops Market Size, Share, and Industry Trends Forecast 2026-2036
PU Waterstops Market Insights
Polyurethane formulation chemistry is narrowing the performance gap between commodity waterstops and engineered hydrophilic systems. Sika AG leverages its European R&D footprint to sustain leadership in hydrophilic strip development. GCP Applied Technologies anchors North American supply through embedded installation expertise. Fosroc International specializes in vulcanized rubber hybrids for marine structures.
PU waterstops are elastomeric sealing devices manufactured from polyurethane resins, typically incorporating hydrophilic additives that expand upon water contact to seal concrete joints against hydrostatic pressure. These products serve primarily to prevent water ingress in structural joints across tunnels, dams, bridges, and water treatment facilities. Hydrophilic strip formats command premium positioning due to self-sealing activation under sustained moisture exposure. Tunnel lining and dam construction applications concentrate procurement volume, while surface-mounted methods remain cost-sensitive alternatives in retrofit projects.
ISO 9001 quality management and ASTM D412 tensile testing protocols govern material certification for PU waterstop suppliers entering public infrastructure tenders. The EPA's stormwater management requirements and China's GB standards for underground waterproofing shape product specification thresholds across major demand centers. Stakeholders must track evolving green building codes and polymer recyclability mandates as specification gatekeepers in municipal procurement.
Market Dynamics
Hydrophilic polyurethane chemistry is compressing the performance premium once commanded by vulcanized rubber and PVC alternatives, redistributing procurement power toward formulation specialists with in-house polymer R&D capabilities.
Growth Catalysts
- China's GB 50108 underground waterproofing standards:Updated hydrostatic pressure requirements in metro and high-speed rail tunnels are mandating hydrophilic strip formats over conventional passive seals.
- Tunnel lining specification intensity:Asia-Pacific infrastructure corridors are embedding waterstop procurement into design-build contracts, locking in multi-year supplier relationships.
- Reactive polymer chemistry advances:Controlled expansion rates in hydrophilic PU formulations now match concrete shrinkage profiles, reducing joint failure callbacks.
Market Restraints
- Polyether polyol feedstock volatility:Crude-linked input costs swing formulation economics unpredictably, squeezing margin stability for mid-tier compounders.
- Specialized applicator concentration:Certified installation expertise clusters in Germany and Japan, creating bottleneck risk for projects in emerging demand centers.
- PVC price anchoring in retrofit segments:Surface-mounted PVC waterstops retain specification inertia in cost-sensitive maintenance contracts, delaying PU penetration.
Strategic Opportunities
- India's PLI-linked infrastructure scale-up:Dedicated freight corridors and urban metro expansions are creating first-mover windows for hydrophilic strip suppliers with local compounding partnerships.
- Green building code convergence:LEED v4.1 and BREEAM waterproofing credits are elevating low-VOC polyurethane formulations in municipal tender scoring.
- Digital twin integration:Sensor-embedded waterstop prototypes enabling predictive leak detection are opening subscription service models for critical infrastructure operators.
Industry Challenges
- ISO 9001 audit timeline compression:Accelerated infrastructure tender cycles are compressing certification renewal windows, straining quality management bandwidth at smaller compounders.
- Legacy concrete substrate variability:Inconsistent surface preparation standards across regional contractor bases are elevating field failure rates and warranty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PU Waterstops Market |
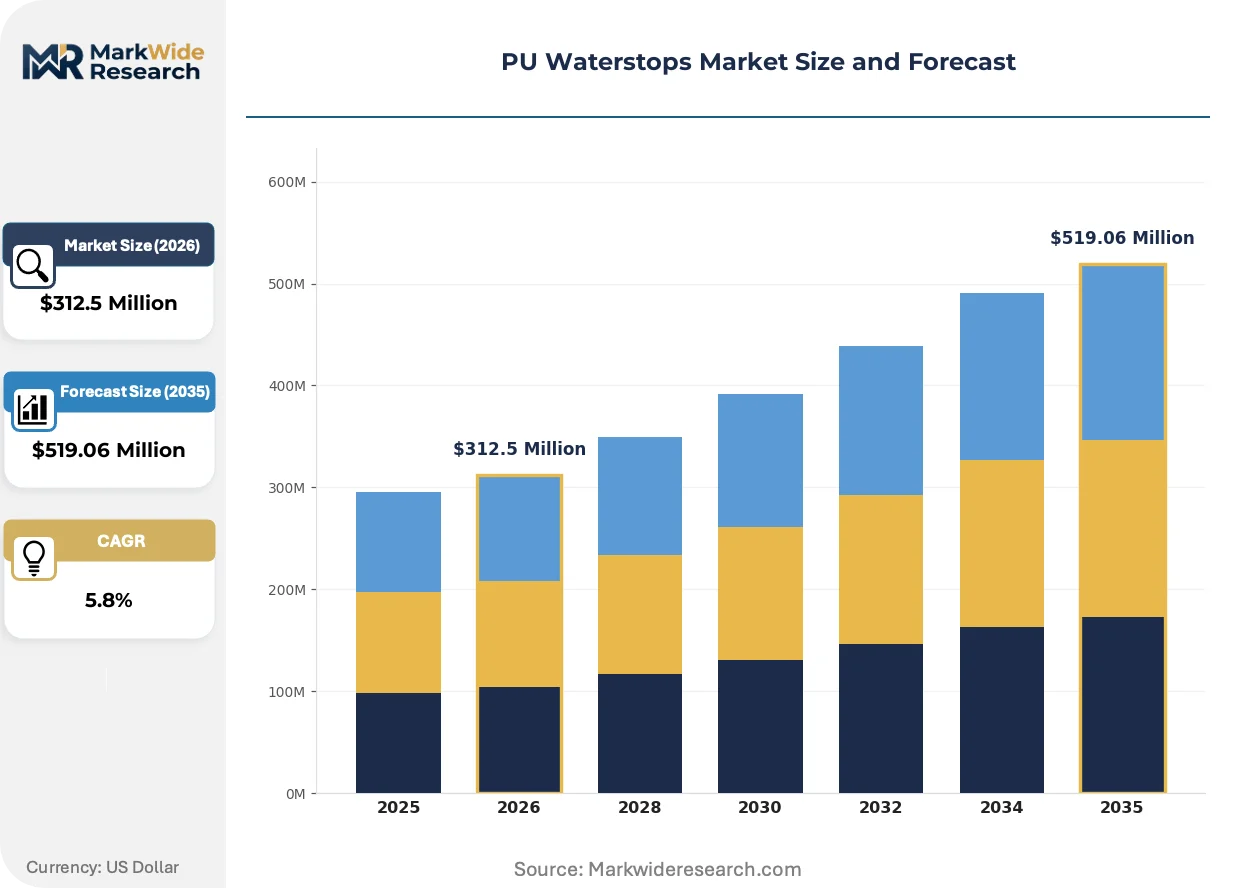
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homogeneous Strip, Hydrophilic, Vulcanized Rubber, Butt Joint, Bentonite, Preformed Application: Bridge Construction, Tunnel Lining, Water Retaining Structures, Concrete Joints, Dam Construction, Marine Structures Installation Method: Embedded, Surface Mounted, Mechanical Fastening, Adhesive Bonding, Slot Mounted End User: Construction Contractors, Infrastructure Developers, Civil Engineering Firms, Marine Engineers, Water Resource Managers |
| Companies Covered | Sika AG, GCP Applied Technologies, BASF SE, Trelleborg AB, SealBoss Corporation, Fosroc International, MAPEI S.p.A., Henry Company, RPM International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PU Waterstops Market Trends and Innovations
Formulation science and installation methodology are converging to redefine performance benchmarking, with digital tools and sustainability metrics now embedded in procurement evaluation frameworks.
Self-healing hydrophilic polyurethane matrices are virtualizing the traditional separation between active and passive waterstop categories. Tunnel operators in Switzerland and Austria are piloting these systems in high-pressure alpine environments. The technology is virtualizing supplier value propositions from commodity supply toward performance-guaranteed service contracts.
REACH Annex XVII restrictions on certain phthalate plasticizers are redirecting formulation R&D toward bio-based chain extenders in European supply chains. Compounders serving German and French public works must now demonstrate full material disclosure to maintain tender eligibility. Hydrophilic PU variants with certified bio-content are capturing specification share in Nordic green infrastructure programs.
Asset owner purchasing departments are consolidating waterstop procurement into multi-project framework agreements with embedded technical support clauses. Engineering-procurement-construction firms in Australia's tunnel sector are displacing spot purchasing with five-year supply partnerships. This concentration is most pronounced in Singapore's deep tunnel sewerage system expansions, where single-source accountability is reducing interface risk.
PU Waterstops Market Segmentation
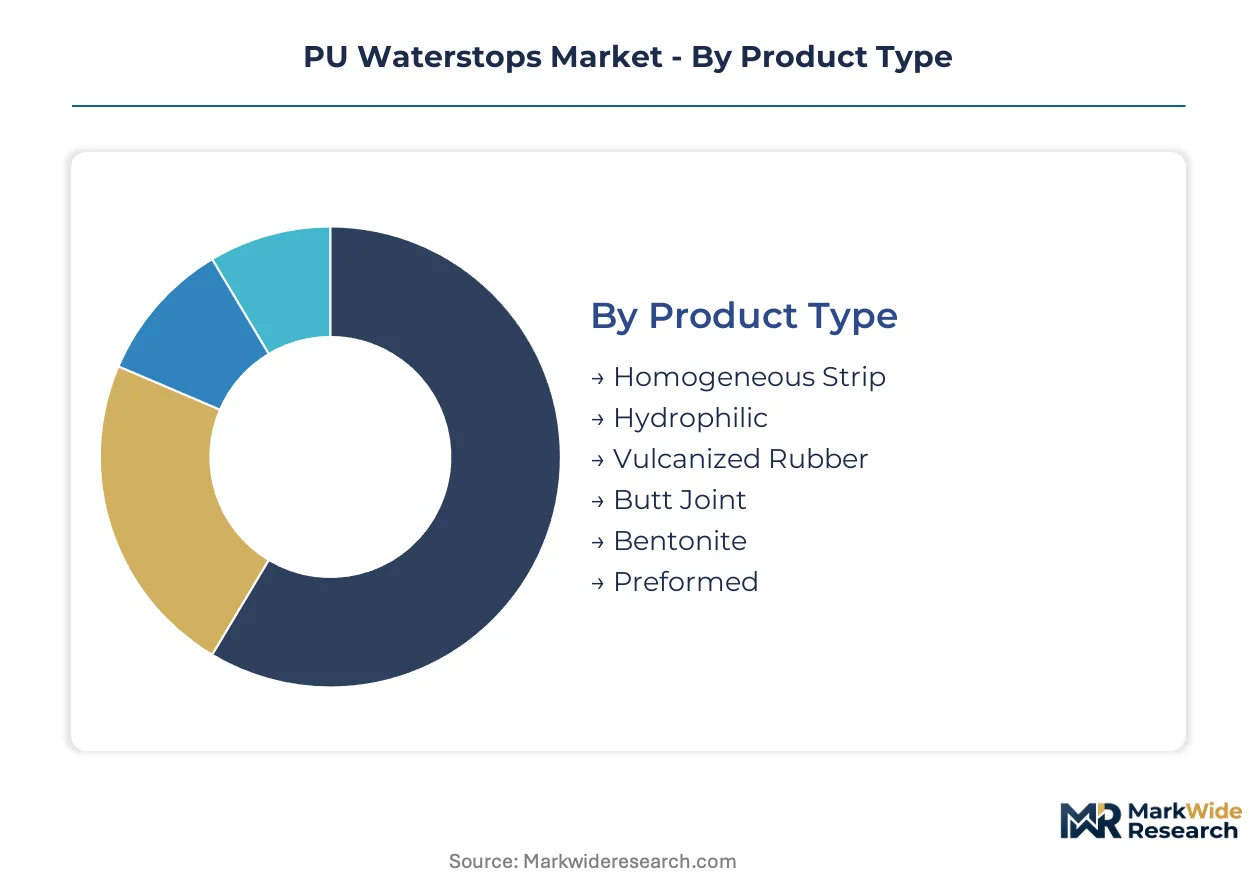
Segmentation in PU waterstops reveals how specification power flows through distinct technical, commercial, and operational channels. Product chemistry, installation complexity, and contractor certification requirements create divergent margin profiles across categories. Understanding these splits exposes where formulation R&D investment yields sustainable pricing power versus commodity exposure.
Product Type:
After-sales service intensity varies dramatically across product formats, with hydrophilic strips demanding embedded technical support through installation and activation monitoring while homogeneous strips require minimal field intervention.
- Hydrophilic:Reactive polyurethane matrices incorporate hydrophilic additives that expand upon moisture contact to create self-sealing barriers against hydrostatic pressure. Metro tunnel specifications in China and high-speed rail corridors across Asia-Pacific are mandating this format over passive alternatives under updated GB 50108 waterproofing standards.
- Homogeneous Strip:Uniform polyurethane composition without reactive additives provides baseline sealing through physical compression in concrete joints. Water treatment facility retrofits and cost-sensitive maintenance contracts in North America specify this format where hydrostatic pressure exposure remains moderate.
- Vulcanized Rubber:Cross-linked elastomer hybrids combine PU surface layers with rubber cores for extreme pressure tolerance.
- Butt Joint:Pre-fabricated connection pieces enabling continuous sealing across segmented concrete pours.
- Bentonite:Clay-polymer composite strips activated by groundwater absorption for below-grade applications.
- Preformed:Factory-molded profiles with integrated ribs or bulbs for specific joint geometries.
By volume, homogeneous strip leads due to retrofit market penetration. By growth pace, hydrophilic formats are gaining share fastest on infrastructure specification upgrades.
Application:
Application segmentation tracks how structural joint geometry and hydrostatic loading conditions dictate formulation requirements and contractor specialization.
- Tunnel Lining:Continuous circumferential and longitudinal joint sealing in bored and cut-and-cover tunnels faces extreme hydrostatic pressure cycling. Design-build contracts across China's Yangtze River Delta and India's Dedicated Freight Corridors are embedding multi-year waterstop supply agreements with embedded technical support clauses.
- Dam Construction:Mass concrete structures with expansion and contraction joints require waterstops tolerant of thermal cycling and alkali exposure. Swiss and Austrian alpine hydropower projects are piloting self-healing hydrophilic matrices in high-pressure environments.
- Bridge Construction:Deck and abutment joints exposed to traffic loading and de-icing chemical attack.
- Water Retaining Structures:Reservoirs, tanks, and basins with intermittent hydrostatic loading.
- Concrete Joints:General building and infrastructure applications with standard joint geometries.
- Marine Structures:Seawalls, quays, and offshore platforms requiring saltwater corrosion resistance.
By project value concentration, tunnel lining dominates. By specification intensity growth, dam construction is climbing the fastest on climate resilience infrastructure programs.
Installation Method:
Installation method segmentation exposes where certified applicator scarcity creates supply bottlenecks and where specification flexibility enables cost competition.
- Embedded:Waterstops cast directly into concrete during pour operations demand precise positioning and vibration-resistant fastening. Germany and Japan host concentrated certified installer bases, creating capacity constraints for emerging market projects in India and Southeast Asia.
- Surface Mounted:Retrofit application to existing joint faces using adhesive or mechanical anchoring. Maintenance contractors in North America favor this method for cost-sensitive bridge deck and building basement repairs where full concrete removal is prohibitive.
- Mechanical Fastening:Anchor bolts or clips securing preformed profiles to prepared substrates.
- Adhesive Bonding:Chemical anchoring systems for smooth concrete or coated surfaces.
- Slot Mounted:Post-installation insertion into saw-cut or pre-formed grooves.
By deployment volume, embedded methods lead on new construction share. By accessibility expansion, surface mounted is gaining traction fastest in retrofit market growth.
End User:
End user segmentation captures how procurement authority and technical evaluation capacity distribute across project delivery structures.
- Infrastructure Developers:State-owned and private entities with multi-project portfolios leverage framework agreements consolidating waterstop procurement across tunnel, dam, and rail programs. Singapore's Public Utilities Board exemplifies this concentration in deep tunnel sewerage system expansions.
- Construction Contractors:General and specialty contractors executing design-build and traditional bid-build contracts. Tier-one EPC firms in Australia's tunnel sector are displacing spot purchasing with five-year supply partnerships embedding technical support.
- Civil Engineering Firms:Design consultants specifying waterstop performance criteria in tender documents.
- Marine Engineers:Port and coastal infrastructure specialists with saltwater exposure expertise.
- Water Resource Managers:Utility operators prioritizing lifecycle cost over first-cost in asset procurement.
By contract value authority, infrastructure developers lead. By procurement process modernization, construction contractors are moving fastest toward partnership-based sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German compounders export hydrophilic strip formulations to tunnel contractors across Switzerland and Austria, establishing a north-south supply corridor into alpine infrastructure projects.
China
High-speed rail expansion along the Yangtze River Delta and metro construction in Chengdu and Xi'an concentrate procurement volume. GB 50108 underground waterproofing standards mandate hydrophilic formats over passive seals. State-owned developers in Guangdong Province lock in multi-year supply agreements for Pearl River Delta tunnel networks.
Germany
Certified embedded installation expertise clusters around Stuttgart and Munich, serving export demand into Swiss and Austrian hydropower. REACH Annex XVII phthalate restrictions redirect formulation R&D toward bio-based chain extenders. BASF SE and compounders in North Rhine-Westphalia supply hydrophilic matrices to Nordic green infrastructure programs.
India
Dedicated freight corridors and Mumbai-Ahmedabad high-speed rail create first-mover windows for hydrophilic strip suppliers. PLI-linked infrastructure scale-up accelerates tender issuance for underground waterproofing. Contractor certification gaps in Maharashtra and Gujarat create bottleneck risk for embedded installation deployment.
Switzerland
Alpine tunnel operators pilot self-healing hydrophilic polyurethane matrices in high-pressure environments. Gotthard Base Tunnel maintenance contracts specify performance-guaranteed service models over commodity supply. Swiss Federal Railways consolidate procurement through framework agreements embedding technical support clauses.
United States
EPA stormwater management requirements shape specification thresholds for water treatment facility retrofits. Surface-mounted methods dominate cost-sensitive bridge deck repairs in the Northeast and Midwest. GCP Applied Technologies anchors North American supply through embedded installation expertise in major metropolitan infrastructure.
PU Waterstops Market Competitive Landscape
Channel-controlling players compete with product-specialist players across formulation chemistry and installation certification vectors. The vendor base stratifies between European R&D-heavy compounders with hydrophilic strip leadership and North American applicator-anchored distributors serving retrofit segments. Three archetypes dominate: formulation specialists with captive polymer science, installation-integrated service providers, and regional compounders competing on feedstock proximity. Competitive moves concentrate on backward integration into polyether polyol supply and five-year framework agreements locking in tunnel sector procurement.
Within the European formulation tier, Sika AG exemplifies the R&D-anchored archetype, while Fosroc International occupies a position bridging vulcanized rubber heritage with polyurethane hybrid development. Among North American channel players, GCP Applied Technologies represents the installation-integrated model. These three entities anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Sika AG |
| GCP Applied Technologies |
| BASF SE |
| Trelleborg AB |
| SealBoss Corporation |
| Fosroc International |
| MAPEI S.p.A. |
| Henry Company |
| RPM International |
| Others |
Pricing and Supply Chain Analysis
German and Japanese polyether polyol suppliers anchor upstream feedstock pricing, concentrating margin capture in hydrophilic strip formulations where reactive chemistry commands premium positioning over homogeneous alternatives.
Pricing Analysis
Current-generation hydrophilic polyurethane strips price at multiples above prior-generation homogeneous formats, while next-generation self-healing matrices are piloting performance-guaranteed service contracts. Project-based pricing dominates tunnel and dam procurement, with price differentiation driven by ISO 9001 certification tier and embedded technical support intensity. Pricing pressure stems from polyether polyol feedstock volatility squeezing mid-tier compounders. Retrofit contractors in North America exhibit highest price sensitivity, while infrastructure developers in China and Switzerland prioritize lifecycle performance over first cost.
Supply Chain Analysis
Contract manufacturing concentrates among BASF SE compounding facilities in Germany, Sika AG production sites in Switzerland, and specialized PU formulators in Japan. Raw material flows draw from Saudi Arabian MDI producers, Chinese polyether polyol manufacturers, and European specialty additive suppliers. Single-source vulnerability runs through certified embedded installer networks clustered in Germany and Japan, creating bottleneck risk for Indian and Southeast Asian project deployment. Distribution feeds from formulation specialists through EPC contractor procurement desks and infrastructure developer framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical support and activation monitoring services are expanding faster than hardware supply, creating attach-rate opportunities for suppliers embedding field engineering into multi-year framework agreements.
For Market Incumbents: Pre-empt PVC displacement in retrofit segments by acquiring surface-mounted installation expertise and certifying applicator networks in India and Southeast Asia. Backward integration into polyether polyol supply buffers margin compression from crude-linked feedstock swings. Lock in five-year tunnel sector procurement through performance-guaranteed service models that virtualize commodity supply into subscription revenue. For New Entrants and Emerging Players: Build out local compounding partnerships in Maharashtra and Gujarat to serve India's PLI-linked infrastructure scale-up, where contractor certification gaps create first-mover windows. Target embedded installation deployment in dedicated freight corridors and urban metro expansions. Lead with green building code compliance—LEED v4.1 and BREEAM waterproofing credits—to differentiate in municipal tender scoring. For Investors and Strategic Acquirers: Capital is best deployed toward formulation specialists with captive polymer R&D and established hydrophilic strip portfolios, given the multi-year infrastructure procurement cycles locking in supplier relationships. The 5-10 year viability window favors compounders with demonstrated GB 50108 compliance and Swiss alpine project references. Monitor REACH Annex XVII bio-based formulation mandates as the inflection signal redirecting R&D investment toward certified chain extenders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyether Polyol Supply | BASF SE and German compounders secure captive feedstock against crude price volatility. |
| Certified Applicator Network Expansion | Sika AG extends embedded installation expertise from Germany into Indian infrastructure corridors. |
| Self-Healing Hydrophilic Matrix Development | Swiss and Austrian alpine operators pilot performance-guaranteed service contracts over commodity supply. |
| Green Formulation Certification Program | REACH Annex XVII compliance redirects R&D toward bio-based chain extenders for Nordic tenders. |
| Digital Twin Integration Partnership | Sensor-embedded prototypes enable predictive leak detection subscriptions for critical infrastructure. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC 10-K filings from listed chemical suppliers, GB standard documentation, and ECHA REACH registration databases. Interviews with tunnel project procurement managers, PU compounder R&D directors, certified embedded installation contractors, and infrastructure developer technical specifications teams informed demand-side validation. Bottom-up segment sizing triangulates against top-down infrastructure investment flow analysis.
Forecast inputs include hydrophilic versus homogeneous format adoption curves, tunnel lining specification intensity across Asia-Pacific corridors, and green building code penetration in municipal procurement. Modeled dimensions span product chemistry tier, installation method complexity, application pressure exposure, and regional regulatory cluster. CAGRs derive from segment-level volume build-ups calibrated to infrastructure tender issuance patterns and contractor certification expansion timelines.
Stress conditions across polyether polyol price bands, embedded installer capacity constraints, and GB standard revision timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on infrastructure investment continuity and formulation chemistry substitution rates. Quarterly review of tender issuance velocity in China's Yangtze River Delta and REACH Annex XVII amendment proposals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Plastic Fencing Market
Building & Construction Materials
Concrete Protective Liners Market
Building & Construction Materials
Insulated Wall Panels Market
Building & Construction Materials
Carbon Steel IBC Market
Building & Construction Materials
North America Wood Based Panel Market
Building & Construction Materials
North America Fabricated Metal Products Market
Building & Construction Materials
Residential and Commercial Smart Glass Market
Building & Construction Materials
Europe AAC Blocks and Panels Market
Building & Construction Materials
Global Concrete Surface Retarders Market
Building & Construction Materials
Plastic Formwork Market
Building & Construction Materials
Rebars Market
Building & Construction Materials
Decorative Concrete Market
Building & Construction Materials
Building and Construction Plastic Fasteners Market
Building & Construction Materials
US and Canada Corner Beads and Caps Market
Building & Construction Materials
Global Raised Access Floor Systems Market