
 Africa Construction Chemicals Market | 2026-2036
Africa Construction Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Construction Chemicals Market Outlook
Modular waterproofing kits bundled with application guidance is hardening as the default procurement format for mid-sized contractors across the continent. Sika South Africa leverages its regional blending network to supply these configurations at shorter lead times. Fosroc anchors its position through technical advisory services tied to every product shipment. BASF SE competes on polymer chemistry depth, particularly for high-performance admixtures specified in bridge and dam contracts.
Construction chemicals encompass formulated additives, binders, and protective systems engineered to modify cementitious matrices, enhance substrate durability, or control moisture ingress in built structures. These products typically incorporate acrylic or epoxy polymer backbones, active mineral fillers, and rheology modifiers blended to achieve specific performance parameters such as compressive strength gain, chloride permeability resistance, or elongation at break. Admixtures command the largest volume share due to their integration into nearly every ready-mix and precast operation. Waterproofing applications generate disproportionate margin pools as project owners extend defect-liability periods and specify certified membrane systems. Polymer-based technologies are displacing solvent-born alternatives as environmental compliance tightens and water-borne formulations achieve equivalent cure profiles.
Kenya's National Construction Authority enforces structural integrity standards that mandate third-party testing of admixtures used in public infrastructure. South Africa's National Regulator for Compulsory Specifications administers SANS certification for construction products, creating a compliance threshold that filters out uncertified imports. Nigeria's Federal Ministry of Works periodically updates highway design manuals that reference specific chemical treatment protocols for coastal exposure zones. Stakeholders must track which national standards bodies are harmonizing with ISO test methods versus maintaining idiosyncratic local protocols, as this divergence determines product registration costs and reformulation requirements.
Market Dynamics
Modular waterproofing kits bundled with application guidance are hardening as the default procurement format across Africa, compressing traditional specification cycles and forcing reformulation of legacy product lines for shorter lead times.
Growth Catalysts
- Kenya's National Construction Authority mandates:Revised building codes for high-rise durability require third-party testing of admixtures used in public infrastructure, pulling certified products into megaproject supply chains.
- Concrete admixtures:Infrastructure megaprojects across East Africa are absorbing larger volumes of these formulations as cement consumption per capita accelerates in the Lagos-Ibadan corridor.
- Polymer-based waterproofing:Water-borne formulations achieving equivalent cure profiles to solvent-born alternatives are displacing legacy systems as environmental compliance tightens across Nigerian coastal exposure zones.
Market Restraints
- Petrochemical feedstock volatility:Acrylic and epoxy polymer backbone costs fluctuate with crude oil benchmarks, compressing margin pools for formulated additives.
- Import concentration:Uncertified imports from Asian suppliers flood price-sensitive segments, undercutting SANS-certified domestic production in South Africa.
- ISO harmonization gaps:Divergence between national standards bodies maintaining idiosyncratic local protocols versus ISO test methods elevates product registration costs and reformulation requirements.
Strategic Opportunities
- Technical advisory services:Fosroc's model of tying expertise to every product shipment represents expandable white space for mid-sized contractors lacking in-house specification capability.
- Regional blending networks:Sika South Africa's distributed production model enables shorter lead times for modular kit configurations, replicable in underpenetrated East African markets.
- Bridge and dam specifications:High-performance admixtures with polymer chemistry depth command disproportionate margins as defect-liability periods extend.
Industry Challenges
- Rheology modifier formulation expertise:Scarce technical talent for optimizing active mineral filler blends limits domestic product development capacity.
- SANS certification timelines:South Africa's National Regulator for Compulsory Specifications administers extended approval cycles that delay market entry for reformulated lines.
- Ready-mix integration complexity:Admixture dosing systems require retrofitting legacy batching infrastructure across fragmented precast operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Construction Chemicals Market |
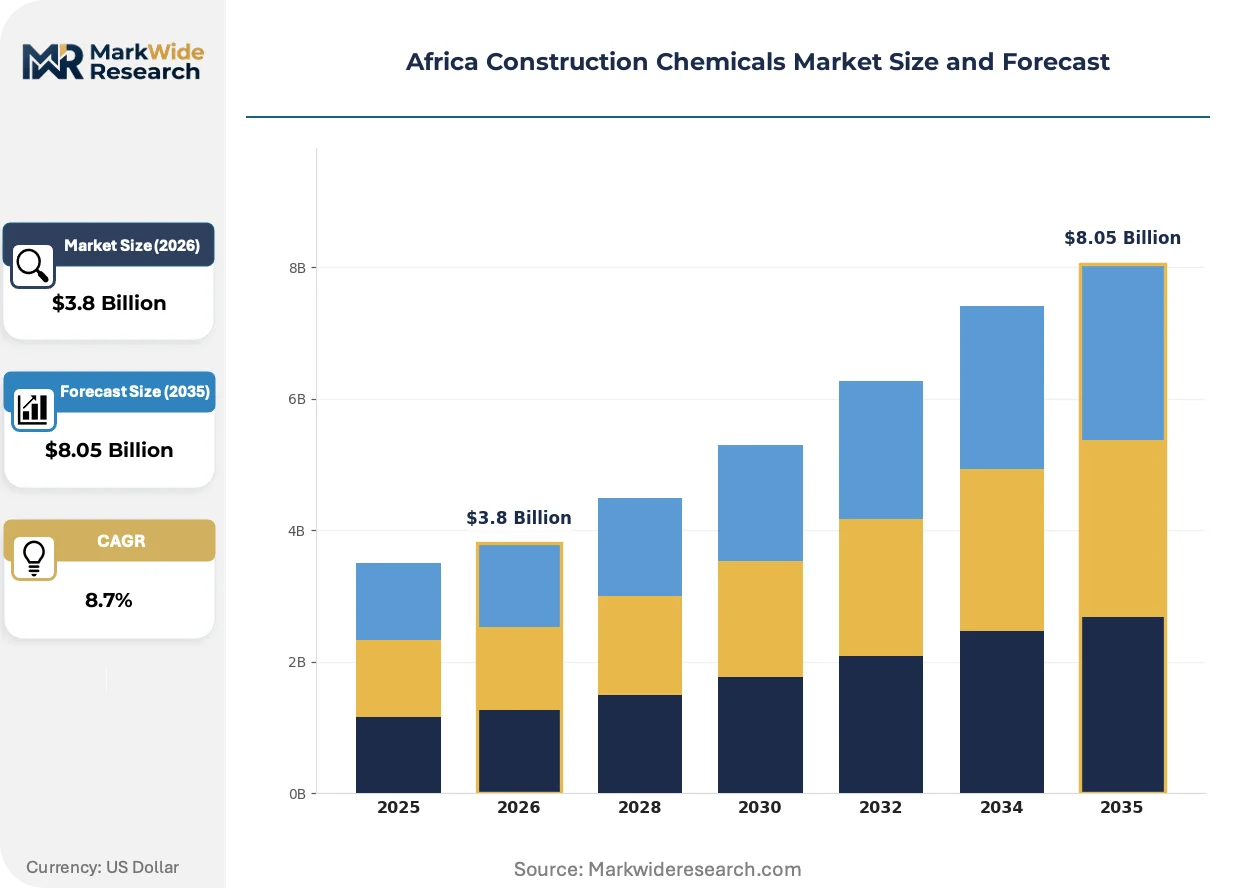
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Admixtures, Sealants, Adhesives, Coatings End User: Residential, Commercial, Industrial, Infrastructure Application: Waterproofing, Flooring, Repair, Surface Treatment Technology: Polymer-Based, Water-Based, Solvent-Based, Others |
| Companies Covered | Dow, Fosroc, BASF SE, Pidilite Industries, Mapei, Sika South Africa, SOCHEM, Arkema, Chryso, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Construction Chemicals Market Strategic Shifts
Polymer chemistry advances and procurement model compression are actively restructuring how construction chemicals reach African project sites, with water-borne systems and bundled service formats displacing legacy supply arrangements.
Water-borne epoxy and acrylic membrane systems is absorbing specification share from solvent-born alternatives as Nigeria's Federal Ministry of Works updates highway design manuals for coastal exposure zones. Ready-mix contractors in the Lagos-Ibadan corridor are specifying these formulations at accelerating pace. This absorption is compressing the viable shelf life of legacy inventory held by distributors serving price-sensitive segments.
South Africa's National Regulator for Compulsory Specifications tightened SANS certification requirements for construction products entering public infrastructure tenders. Industrial consequence: uncertified imports face systematic exclusion from megaproject supply chains. Waterproofing membrane suppliers with existing SANS approvals are capturing specification share in Durban-Cape Town corridor contracts.
Mid-sized contractors across Kenya and Nigeria are consolidating purchasing through bundled waterproofing kits with embedded application guidance. Traditional specification-by-specification procurement is yielding to pre-configured product-service combinations. This pattern concentrates most visibly in Nairobi's high-rise residential sector, where National Construction Authority compliance mandates accelerate adoption of certified, supported systems over commodity alternatives.
Africa Construction Chemicals Market Segmentation
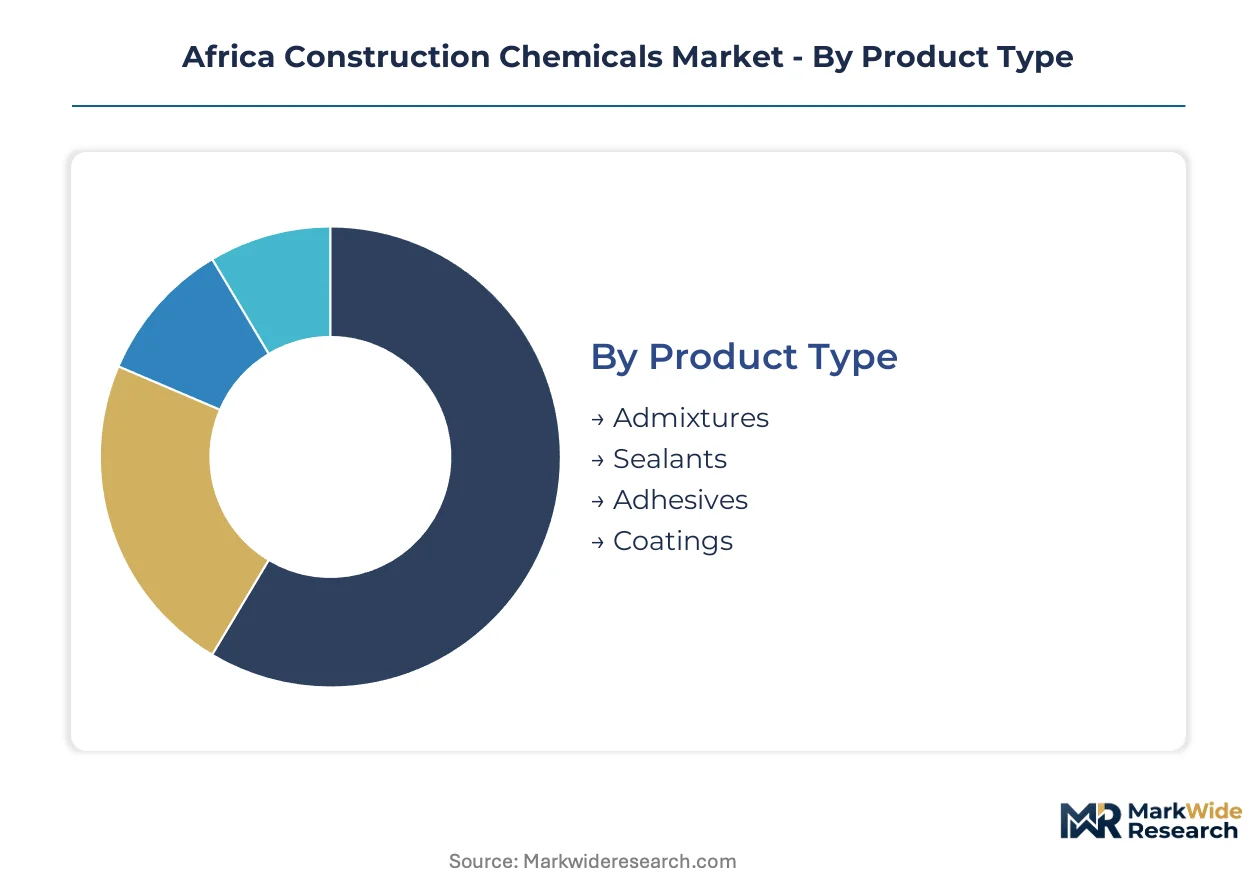
Construction chemicals in Africa fragment across four intersecting dimensions that determine specification authority and margin capture. Product type governs raw material exposure and formulation complexity. End-user concentration shapes volume contracts and technical service intensity.
Product Type:
Replacement cycles for legacy formulations accelerate as national building codes tighten certification requirements across Kenya, Nigeria, and South Africa.
- Admixtures:These cement-modifying formulations incorporate active mineral fillers and rheology modifiers to control set time, workability, and compressive strength gain. Infrastructure megaprojects across East Africa absorb larger volumes as cement consumption per capita accelerates in Nigeria's Lagos-Ibadan corridor. Kenya's National Construction Authority mandates third-party testing for public infrastructure use.
- Sealants:Elastomeric joint-sealing compounds formulated from silicone, polyurethane, or polysulfide backbones accommodate structural movement while blocking moisture ingress. Demand clusters in high-rise residential developments across Nairobi where defect-liability period extensions drive specification of certified membrane systems over commodity alternatives.
- Adhesives:Bonding agents engineered for tile, stone, and facade anchorage applications.
- Coatings:Protective surface films including anti-carbonation and decorative cementitious systems.
Admixtures sit at the top of the volume ranking, with sealants climbing the fastest as waterproofing specifications tighten.
End User:
Customer-type concentration determines pricing power and technical advisory bundling requirements across African construction markets.
- Infrastructure:Bridge, dam, highway, and port projects specify high-performance admixtures with extended defect-liability coverage. Nigeria's Federal Ministry of Works updates highway design manuals for coastal exposure zones, pulling certified polymer-based formulations into megaproject supply chains. SANS certification requirements in South Africa systematically exclude uncertified imports from public tenders.
- Residential:High-rise and mass housing developments in Nairobi's urban corridor consolidate procurement through modular waterproofing kits with embedded application guidance. Kenya's National Construction Authority compliance mandates accelerate adoption of supported systems over commodity alternatives for durability-critical structures.
- Commercial:Office, retail, and hospitality developments with shorter capital recovery timelines.
- Industrial:Manufacturing facilities and processing plants requiring chemical-resistant flooring and containment systems.
Infrastructure commands the largest contract values, with residential expanding most quickly as urbanization accelerates across East and West Africa.
Application:
Functional use-case segmentation tracks where polymer chemistry advances displace legacy solvent-born systems.
- Waterproofing:Membrane and coating systems engineered to control moisture ingress in below-grade and exposed structures. Water-borne epoxy and acrylic formulations achieve equivalent cure profiles to solvent-born alternatives as environmental compliance tightens across Nigerian coastal exposure zones. Modular kit configurations with application guidance harden as the default procurement format for mid-sized contractors.
- Repair:Structural rehabilitation mortars and injection grouts for deteriorated concrete infrastructure. South Africa's aging bridge stock and coastal exposure damage generate recurring demand for chloride-resistant repair systems with SANS certification.
- Flooring:Industrial and decorative screed systems including self-leveling compounds and epoxy finishes.
- Surface Treatment:Curing compounds, release agents, and anti-carbonation coatings for fresh concrete protection.
Waterproofing generates the highest margin pools, with repair gaining share fastest as infrastructure maintenance backlogs accumulate.
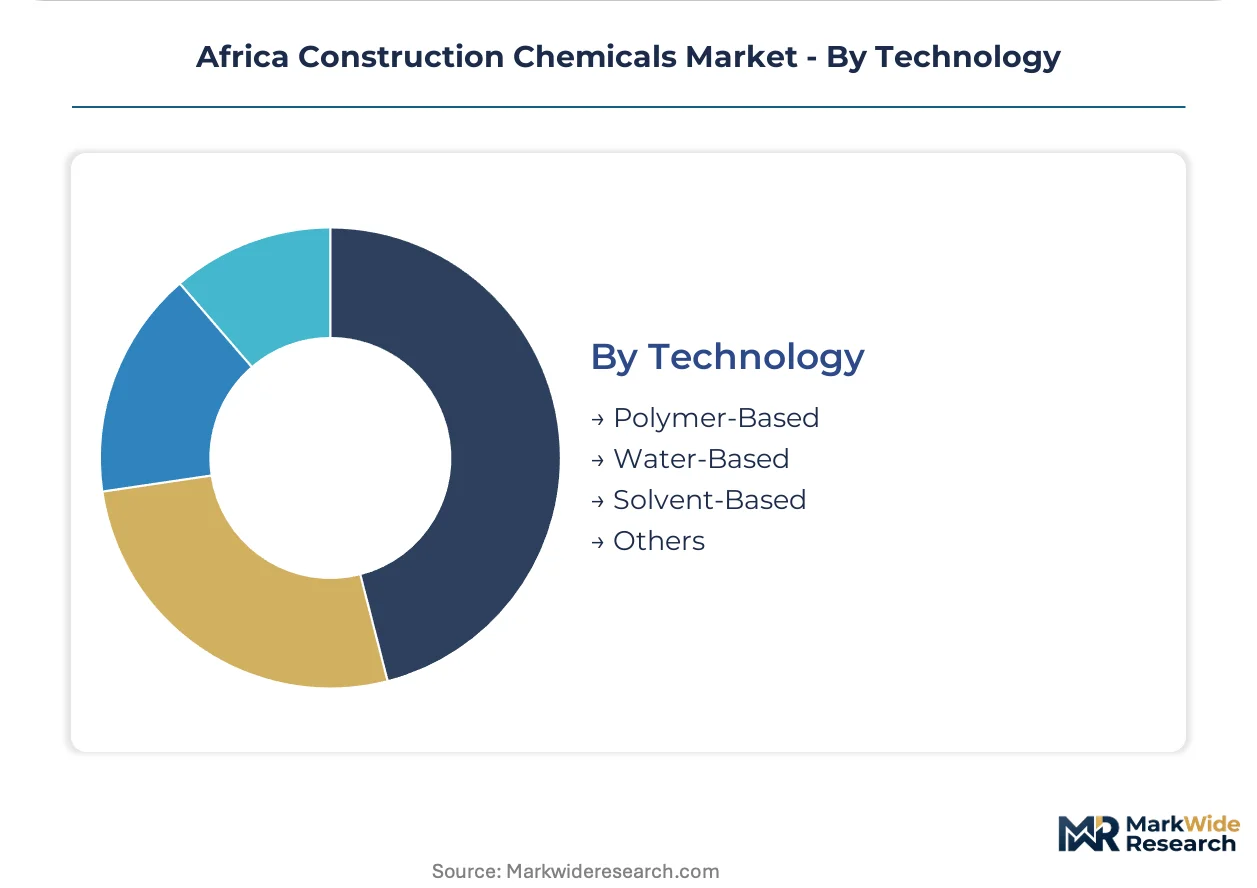
Technology:
Formulation chemistry determines environmental compliance positioning and raw material cost exposure across African supply chains.
- Polymer-Based:Acrylic, epoxy, and polyurethane backbone systems delivering high elongation, chemical resistance, and substrate adhesion. BASF SE competes on polymer chemistry depth for bridge and dam specifications where defect-liability periods extend. Petrochemical feedstock volatility compresses margin pools when crude oil benchmarks fluctuate.
- Water-Based:Low-VOC formulations displacing solvent-born alternatives as national environmental regulations tighten. Ready-mix contractors in the Lagos-Ibadan corridor specify these systems at accelerating pace, compressing viable shelf life of legacy distributor inventory.
- Solvent-Based:High-solids systems with faster cure profiles in temperature-variable conditions.
- Others:Cementitious and silicate-based technologies for specific substrate compatibility requirements.
Polymer-based formulations dominate high-specification applications, with water-based systems climbing fastest as regulatory pressure intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction chemicals manufacturing first scaled in South Africa during the 1970s mining boom, then spread northward as infrastructure investment accelerated across the continent. Today, demand clusters trace the path of cement consumption growth and regulatory tightening in East and West African urban corridors.
South Africa
SANS certification requirements from the National Regulator for Compulsory Specifications filter uncertified imports from public infrastructure tenders. The Durban-Cape Town corridor concentrates waterproofing membrane demand as coastal exposure damage accumulates on aging bridge stock. Regional blending networks supply modular kit configurations at compressed lead times for mid-sized contractors.
Nigeria
Cement consumption per capita accelerates fastest in the Lagos-Ibadan corridor, pulling concrete admixtures into megaproject supply chains. The Federal Ministry of Works periodically updates highway design manuals referencing specific chemical treatment protocols for coastal exposure zones. Ready-mix contractors specify water-borne polymer systems at accelerating pace, compressing viable shelf life of legacy distributor inventory.
Kenya
The National Construction Authority mandates third-party testing of admixtures used in public infrastructure, pulling certified products into high-rise durability specifications. Nairobi's urban corridor consolidates procurement through bundled waterproofing kits with embedded application guidance. Defect-liability period extensions drive specification of certified membrane systems over commodity alternatives in residential developments.
Egypt
Suez Canal expansion and new capital city construction absorb larger volumes of high-performance admixtures for bridge and dam specifications. National building code revisions align partially with ISO test methods, reducing reformulation costs for multinational suppliers entering public tenders. Cairo-Alexandria industrial zones concentrate demand for polymer-based waterproofing in below-grade foundation systems.
Ghana
Petrochemical feedstock access from Tema refinery operations supports domestic formulation capacity for acrylic and epoxy backbone systems. Building code harmonization with West African regional standards proceeds incrementally, creating transitional compliance windows for imported products. Accra-Tema metropolitan construction absorbs sealant volumes for high-rise residential joint-sealing applications.
Africa Construction Chemicals Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification depth and technical advisory bundling. The vendor base organizes into three tiers: multinational specialists with polymer chemistry depth, regional blenders with distributed production networks, and import-dependent distributors serving price-sensitive segments. Two dominant competitive moves define current positioning: technical service integration into product shipments, and regional blending capacity expansion to compress lead times for modular kit configurations.
Among European-headquartered specialists, BASF SE and Fosroc exemplify the premium-tier archetype through polymer chemistry depth and advisory bundling. Sika South Africa anchors the regional blender category with distributed production enabling shorter lead times. Dow and Arkema occupy positions bridging multinational scale with regional formulation adaptation. Pidilite Industries represents the import-specialist model concentrated in West African price-sensitive segments.
| Leading Market Players |
|---|
| Dow |
| Fosroc |
| BASF SE |
| Pidilite Industries |
| Mapei |
| Sika South Africa |
| SOCHEM |
| Arkema |
| Chryso |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between SANS-validated and uncertified imports manifests in both margin capture and procurement routing across African construction chemicals markets. Premium-tier suppliers command pricing power through bundled technical advisory services, while commodity channels absorb price-sensitive volume through Asian import flows that bypass domestic blending infrastructure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs the African construction chemicals market. Price differentiation rests on certification depth and technical service bundling, with SANS-certified formulations capturing substantial premiums over uncertified alternatives. Cost compression in economy-tier imports is intensifying because Asian suppliers flood price-sensitive segments with unvalidated polymer systems. Infrastructure contractors demonstrate least price sensitivity due to extended defect-liability mandates, while residential developers in peri-urban corridors exhibit highest elasticity.
Supply Chain Analysis
Returns and reformulation flows from expired distributor inventory compress working capital cycles for legacy solvent-based systems displaced by water-borne alternatives. Manufacturing concentrates in South Africa, Nigeria, and Egypt, with regional blending nodes serving East African corridors. Raw material dependencies draw from Saudi petrochemical feedstocks, Indian active mineral fillers, and European rheology modifiers. Single-source vulnerability in acrylic polymer supply creates exposure when crude benchmarks fluctuate. Distribution runs through project-site direct delivery for megaprojects and distributor networks for fragmented mid-sized contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in certification-tier upgrades and technical service bundling as defect-liability periods extend across African infrastructure procurement. Water-borne formulation transitions and modular kit configurations drive premium capture for suppliers with compliant product portfolios.
For Market Incumbents: Acquire regional blending capacity in underpenetrated East African corridors to compress lead times for modular waterproofing kits. SANS certification investments filter uncertified import competition from South African public tenders. Backward integration into active mineral filler supply secures formulation cost control against petrochemical volatility. For New Entrants and Emerging Players: Enter via technical advisory service bundling for mid-sized contractors lacking in-house specification capability in Kenya's high-rise residential sector. White-space concentration appears in water-borne polymer systems for Nigerian coastal exposure zones where environmental compliance tightens. Go-to-market positioning should emphasize application guidance embedded in procurement configurations rather than commodity product-only supply. For Investors and Strategic Acquirers: Consolidation pressure builds where SANS certification timelines and ISO harmonization gaps create barriers for subscale domestic formulators. Long-term viability favors vertically integrated specialists with polymer chemistry depth and distributed production footprints. Acquisition target archetypes include regional blenders with existing certification portfolios and technical service capabilities. Monitor Kenya's National Construction Authority enforcement patterns and Nigeria's Federal Ministry of Works manual updates as inflection indicators for certified product demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Mineral Fillers | Captive supply of rheology modifiers insulates margin pools from import cost volatility in South African formulations. |
| Regional Blending Network Expansion | Distributed production nodes in Nairobi and Lagos compress lead times for modular waterproofing kit configurations. |
| SANS Certification Investment | Systematic exclusion of uncertified imports from public infrastructure tenders secures specification share in Durban-Cape Town corridor. |
| Technical Advisory Service Bundling | Embedded application guidance with every product shipment replicates Fosroc's premium-tier positioning for mid-sized contractor segments. |
| Water-Borne Formulation Transition | Low-VOC polymer systems align with Nigeria's coastal exposure zone mandates and compress legacy solvent-based inventory viability. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct the African construction chemicals market analysis. Primary engagement captured perspectives from technical R&D directors at multinational suppliers, procurement leads at Nigerian ready-mix operators, distribution channel partners serving Kenya's residential sector, and plant managers at South African blending facilities. Secondary validation drew from customs and trade data, SANS certification registries, SEC 10-K disclosures from listed chemical majors, and infrastructure procurement databases tracking megaproject chemical specifications. Bottom-up volume modeling and top-down value triangulation cross-validated segment outputs.
Segment-weighting across product type, end-user concentration, application function, and technology chemistry anchored the analytical framework. Admixture volume shares, waterproofing margin pools, and infrastructure-residential-commercial splits were modeled across the projection horizon. CAGRs derived from historical cement consumption elasticity, regulatory tightening trajectories, and polymer substitution rates. Industry-specific forecast inputs included Kenya's National Construction Authority compliance mandate enforcement intensity and Nigeria's highway design manual revision cycles for coastal exposure protocols.
The model holds under steady regulatory enforcement and petrochemical price band stability; deviation in crude benchmark volatility or SANS certification timeline extensions would shift volume and value trajectories. Forecasts reflect documented assumptions on ISO harmonization progress and infrastructure megaproject completion rates. Practitioners should monitor Kenya's third-party testing mandate expansion and Nigeria's environmental compliance phase-in schedules for early signals of certified product demand acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Tile Backer Boards Market
Building & Construction Materials
Residential Energy Efficient Windows Market
Building & Construction Materials
United States I-Joist Market
Building & Construction Materials
Stone Veneer Market
Building & Construction Materials
Glass Railing System Market
Building & Construction Materials
Canada Asphalt Shingles Market
Building & Construction Materials
Steel Sandwich Panels Market
Building & Construction Materials
Global Drywall Textures Market
Building & Construction Materials
Pipe Hanger Market
Building & Construction Materials
US Retractable Roofing System Market
Building & Construction Materials
Thin Wall Mould Market
Building & Construction Materials
US Parking Deck Coatings Market
Building & Construction Materials
Global Screw Piles Market
Building & Construction Materials
Europe Construction Repair and Rehabilitation Chemicals Market
Building & Construction Materials
Global Steel Pipe Piles Market
Building & Construction Materials
North America Decks Market