
 Asia-Pacific Ready-Mix Concrete Market | 2026-2036
Asia-Pacific Ready-Mix Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Ready-Mix Concrete Market Outlook
Digital batching and IoT-enabled slump monitoring is narrowing quality variance between plant and pour site across the Asia-Pacific ready-mix concrete value chain. SCG leverages vertical integration across aggregates, cement, and logistics to sustain margin control in Thailand's competitive lowland basin. China National Building Material Group Corporation anchors national supply security through captive limestone reserves and provincial mixing networks spanning thirty-plus provinces.
Ready-mix concrete denotes factory-blended Portland cement, aggregates, water, and admixtures delivered in plastic state for immediate placement, typically specified by compressive strength at twenty-eight days and slump measured in millimeters for workability verification. Its primary commercial purpose eliminates on-site proportioning errors while compressing construction schedules for high-rise and horizontal infrastructure. High-strength grades dominate margin pools in premium commercial towers across Seoul and Singapore, while fiber-reinforced formulations capture fastest-growing share in seismic-zone infrastructure from Japan's Tohoku region to New Zealand's Wellington fault corridor. Lightweight mixes remain niche, constrained by higher per-cubic-meter cost and limited regional fly ash availability.
China's MEE enforces carbon intensity benchmarks on cement clinker production, directly elevating demand for blended and low-carbon ready-mix formulations. India's BIS mandates IS 4926 compliance for ready-mix concrete quality assurance, shaping procurement specifications for government infrastructure tenders under the CEA building code framework. South Korea's KOSHA workplace safety standards extend to mixing plant dust exposure limits, adding compliance cost layers for mid-tier operators. Stakeholders must track which national regulators tighten embodied-carbon disclosure first, as that jurisdiction will set the template for cross-border specification harmonization across Southeast Asian project finance.
Market Dynamics
China's MIIT dual carbon goals are compressing clinker-to-cement ratios across the region, forcing producers to reformulate with fly ash and slag substitutes while maintaining compressive strength specifications. This single regulatory vector is redrawing competitive advantage toward integrated suppliers with captive SCM access.
Growth Catalysts
- India's National Infrastructure Pipeline:Urban megaprojects in Mumbai and Delhi NCR absorb high-strength grades for metro viaducts and commercial towers, pulling volume from informal on-site mixing.
- CEA building code enforcement:Government tender mandates for IS 4926-compliant RMC are disqualifying unregistered batch plants from public works procurement.
- IoT-enabled slump monitoring:Real-time rheology sensors are reducing rejection rates at pour sites, compressing quality assurance cycles for high-rise contractors.
Market Restraints
- Limestone reserve concentration:Captive quarry access concentrates among state-affiliated groups in China and Thailand, elevating input costs for independent blenders.
- Fly ash supply volatility:Coal plant retirement schedules in South Korea and Japan are constraining regional SCM availability, forcing costlier slag imports.
- Seismic-grade technical floor:Japan's JIS standards for fiber-reinforced formulations impose minimum performance thresholds that exclude low-cost competitors from premium infrastructure bids.
Strategic Opportunities
- Vietnam's industrial corridor:Ho Chi Minh City peripheral zones lack integrated RMC capacity relative to accelerating electronics park construction, creating greenfield entry points.
- Low-carbon procurement mandates:Singapore's Building and Construction Authority green mark incentives reward embodied-carbon disclosure, favoring blended mix suppliers with verified EPDs.
- Digital twin convergence:Predictive curing algorithms paired with connected batch plants enable just-in-time delivery contracts for fast-track hospital and data center builds.
Industry Challenges
- Certification timeline compression:BIS laboratory accreditation for new admixture chemistries stretches 14-18 months, delaying product launches for mid-tier formulators.
- Mixer fleet reconfiguration:Transitioning drum fleets for low-slump and self-consolidating mixes requires capex outlays that strain operator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Ready-Mix Concrete Market |
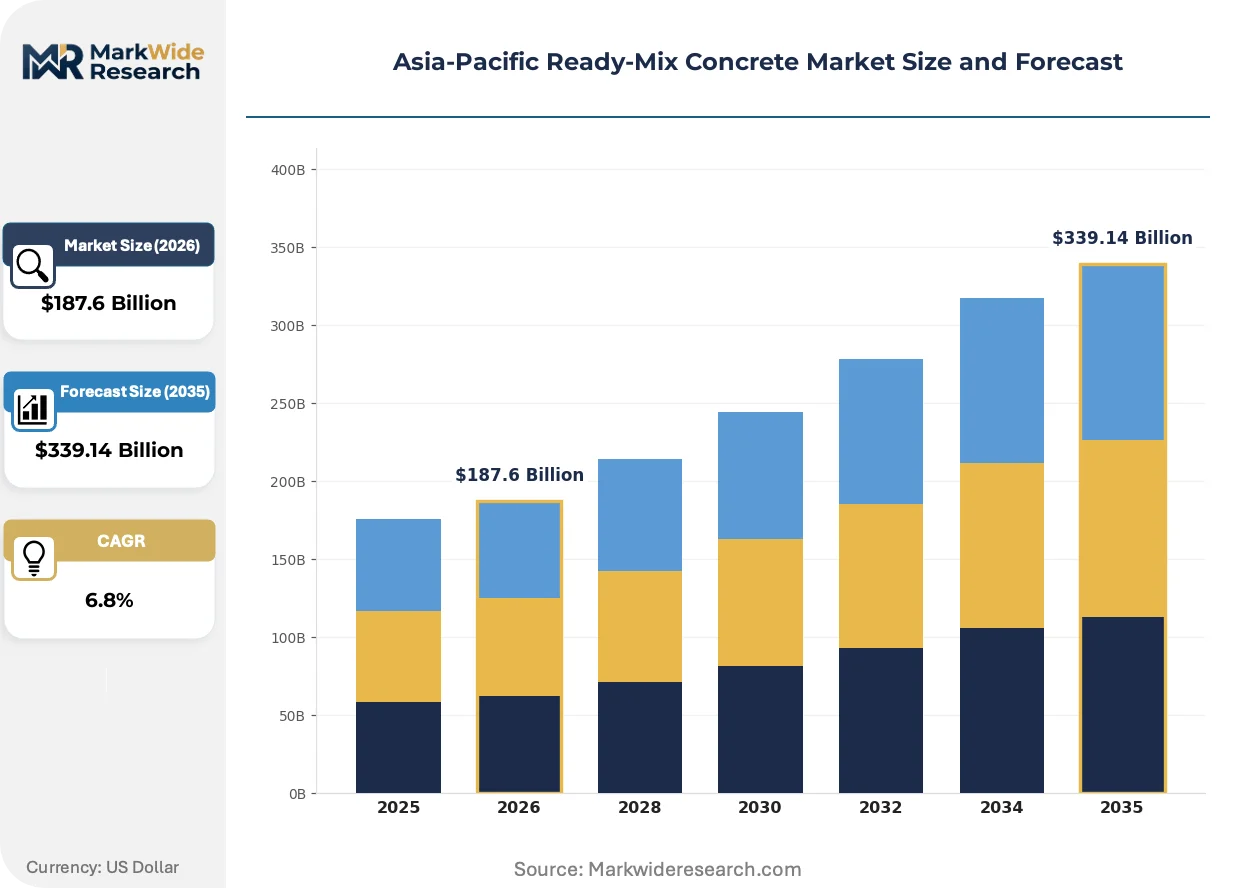
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $339.14 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, High-Strength, Lightweight, Fiber-Reinforced End User: Residential, Commercial, Infrastructure, Industrial Delivery Model: On-Site, Central Mix, Truck Mixer, Ready-Mix Application: Pavements, Foundations, Precast Structures, Bridges |
| Companies Covered | SCG, CSCEC, China National Building Material Group Corporation, SAMPYO GROUP, EUGENE GROUP, Foshan Huijiang Concrete Co., Ltd., BBMG Corporation, UltraTech Cement Ltd., Shanghai Construction Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Ready-Mix Concrete Market Strategic Shifts
Digital batching architectures and carbon accounting protocols are converging to redefine quality assurance and procurement specifications across the Asia-Pacific ready-mix value chain. These shifts favor integrated operators with data infrastructure over traditional volume-based competitors.
Self-consolidating concrete formulations incorporating viscosity-modifying admixtures are rendering obsolete conventional vibration-based placement crews for densely reinforced structural elements. High-rise contractors in Seoul and Singapore specify these grades for core wall pours to compress floor-cycle times. The technology is rendering obsolete established labor-intensive finishing workflows, compressing project margins for contractors slow to retool.
China's MEE carbon intensity benchmarks on clinker production are elevating demand for blended cement systems with GGBFS and pozzolanic substitutes. Provincial enforcement varies, but coastal provinces face binding 2025 targets that reshape procurement from pure Portland toward binary and ternary blends. Ready-mix producers with captive slag grinding capacity capture margin expansion unavailable to conventional blenders.
Buyers are consolidating purchase decisions through centralized procurement platforms for multi-site infrastructure programs, displacing project-level sourcing. State construction corporations in India and Indonesia now mandate pan-portfolio supplier certification, favoring national networks over regional batch plants. This concentration is most visible in India's Delhi-Mumbai Industrial Corridor, where single-source contracts cover 500+ kilometer construction zones.
Asia-Pacific Ready-Mix Concrete Market Segmentation
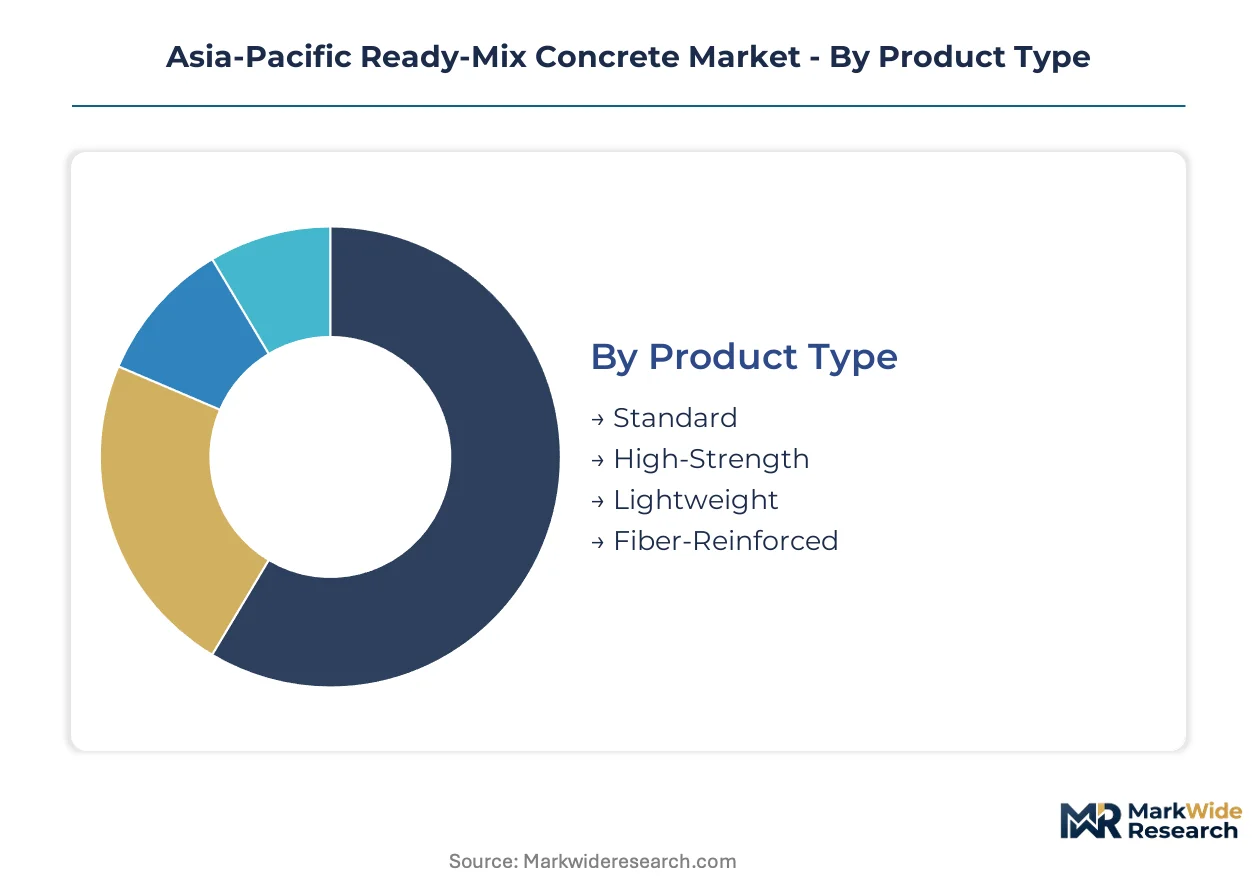
Segmentation in the Asia-Pacific ready-mix concrete market reveals how specification intensity and logistics complexity fragment procurement patterns. Contractors select grades based on structural load requirements, while delivery models trade off quality control against site flexibility.
Product Type:
High-strength grades command extended batch-to-pour windows due to admixture sensitivity, while standard mixes turn faster through simpler quality cycles.
- Standard:Factory-blended Portland cement with nominal compressive strength ratings serves mass housing foundations and horizontal pavements where specification tolerance is widest. Procurement concentrates in India's tier-two cities where cost-sensitive developers dominate residential construction.
- High-Strength:Binary and ternary cement systems achieve elevated compressive ratings through GGBFS and silica fume inclusion. Demand clusters in Seoul and Singapore commercial towers where structural engineers mandate grades exceeding standard specifications for core wall applications.
- Lightweight:Expanded clay or pumice aggregate replacement reduces dead load for high-rise slabs. Availability constraints in Vietnam and Indonesia limit adoption outside premium commercial segments.
- Fiber-Reinforced:Polypropylene or steel fiber dispersion enhances crack resistance for seismic-zone infrastructure. Japan's Tohoku region specifications drive procurement for public works resilience upgrades.
Standard grades anchor the volume base while fiber-reinforced formulations gain share at the steepest rate.
End User:
Cost tier differentiation separates specification-heavy infrastructure from price-sensitive residential procurement.
- Infrastructure:Government-mandated performance grades with extended curing documentation and third-party testing. India's National Infrastructure Pipeline tenders absorb volume across metro viaducts and highway corridors.
- Commercial:Fast-track schedules compress delivery windows for high-rise cores and basement structures. Singapore's green mark incentives reward suppliers with verified embodied-carbon disclosure.
- Residential:Volume-driven procurement with minimal admixture complexity and flexible timing. Informal on-site mixing still captures significant share in Indonesia's peripheral urban zones.
- Industrial:Heavy-duty formulations for manufacturing floors and warehouse slabs requiring abrasion resistance. Electronics park construction in Vietnam's Ho Chi Minh City corridor pulls specialized grades.
Infrastructure contracts concentrate procurement decisions through centralized platforms, while industrial end users expand most quickly as manufacturing investment accelerates.
Delivery Model:
Volume throughput varies dramatically: central mix plants achieve highest batch consistency but require dedicated fleet investment, while on-site systems sacrifice quality control for remote access.
- Central Mix:Stationary batching with rigorous slump monitoring before truck loading. China's provincial mixing networks leverage this model for quality assurance across thirty-plus provinces.
- Truck Mixer:Transit mixing with continuous drum rotation maintains plasticity for extended haul distances. Thailand's competitive lowland basin operators favor this flexibility for dispersed project sites.
- Ready-Mix:Factory-controlled proportioning with documented batch records for specification compliance. BIS IS 4926 mandates are elevating this model's share in Indian government tenders.
- On-Site:Portable batch plants for remote locations beyond economic haul radius. Limited to mining and hydroelectric projects in Papua New Guinea and Laos.
Truck mixer deployment dominates current fleet composition while central mix capacity expands most quickly as quality assurance requirements tighten.
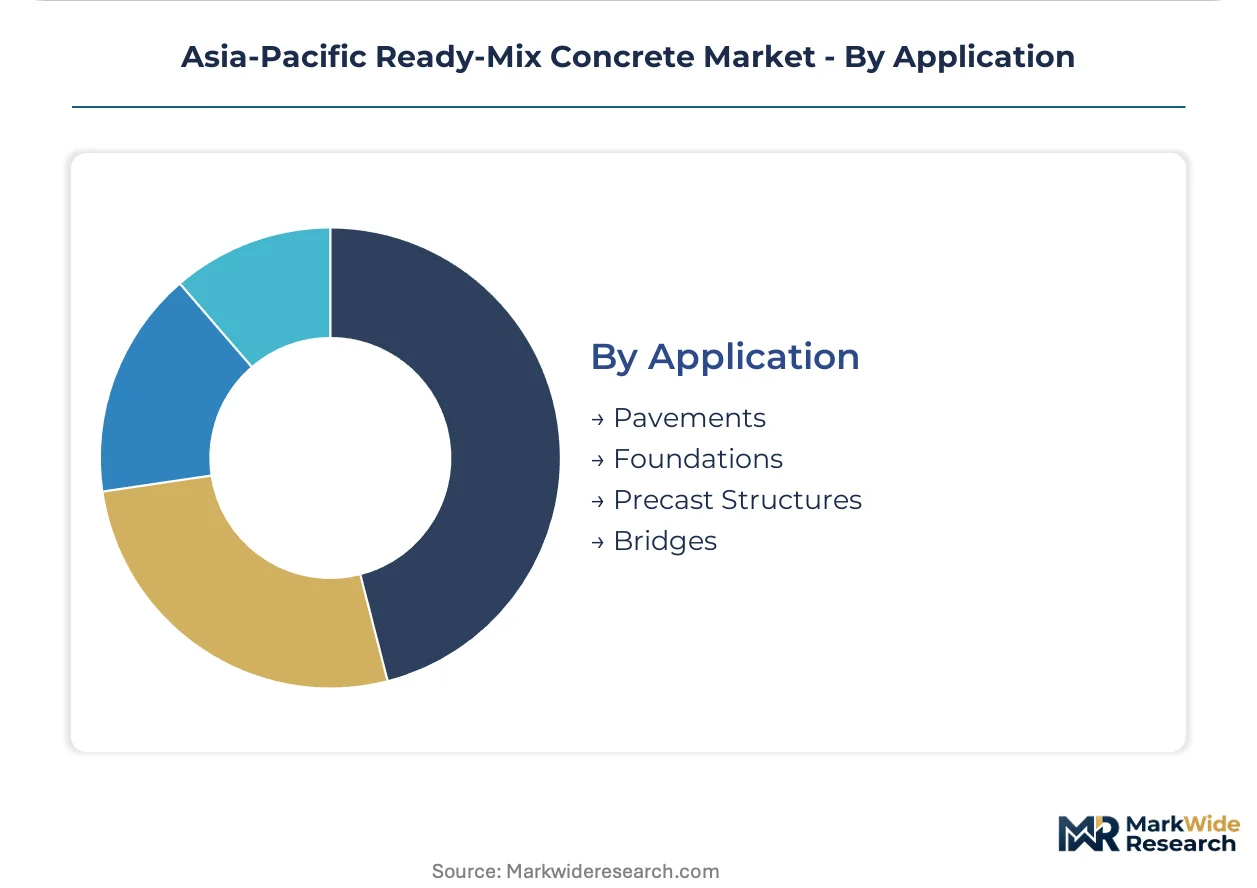
Application:
Structural performance requirements stratify by load-bearing intensity and exposure conditions.
- Foundations:Mass pours with extended set-time control for raft and pile cap construction. Mumbai's coastal high-rises specify sulfate-resistant formulations for marine exposure.
- Bridges:High-durability grades with air entrainment for freeze-thaw cycling and de-icing salt exposure. Japan's Honshu-Shikoku corridor maintenance programs sustain demand.
- Precast Structures:Accelerated curing cycles with controlled demolding strength for factory production. South Korea's modular housing initiatives pull specialized supply.
- Pavements:Surface durability focus with abrasion resistance and joint spacing optimization. India's Delhi-Mumbai Industrial Corridor road construction absorbs volume across 500-plus kilometer zones.
Foundation applications anchor the volume base while bridge specifications climb the fastest as aging infrastructure replacement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for supplementary cementitious materials shapes regional trade flows, with coastal provinces sourcing GGBFS from integrated steelworks while inland markets absorb higher logistics premiums. Export capacity concentrates among Chinese state-affiliated groups with captive limestone reserves.
China
Provincial mixing networks spanning thirty-plus provinces anchor national supply security under MEE carbon intensity benchmarks. MIIT dual carbon goals compress clinker-to-cement ratios, elevating demand for fly ash and slag substitutes. Yangtze River Delta megacities absorb reformulated low-carbon mixes for commercial tower construction.
India
Urban infrastructure megaprojects in Mumbai and Delhi NCR absorb high-strength grades for metro viaducts and commercial towers. BIS mandates IS 4926 compliance for government tenders under the CEA building code framework. The Delhi-Mumbai Industrial Corridor concentrates procurement across 500-plus kilometer construction zones.
Japan
Fiber-reinforced formulations for seismic-zone infrastructure sustain demand across the Tohoku region resilience upgrades. METI workplace safety standards extend to mixing plant dust exposure limits, adding compliance cost layers. Kanto corridor specifications drive premium-grade procurement for high-rise core applications.
Vietnam
Electronics park construction accelerates across Ho Chi Minh City peripheral zones, outpacing integrated RMC capacity. Industrial corridor demand concentrates in specialized grades for manufacturing floors and warehouse slabs. Greenfield entry points emerge where logistics infrastructure lags project timelines.
South Korea
KOSHA workplace safety standards govern mixing plant operations, elevating compliance thresholds for mid-tier operators. KOSHA dust exposure limits reshape facility investment patterns. Seoul commercial tower specifications pull high-strength binary and ternary cement systems for accelerated construction schedules.
Asia-Pacific Ready-Mix Concrete Market Competitive Environment
On the supply side, the industry is consolidating around integrated groups with captive raw material access and provincial distribution networks. State-affiliated cement conglomerates in China and Thailand leverage backward integration into limestone quarries and slag grinding capacity. Three archetypes dominate: vertically integrated national champions, regional batch-plant operators with logistics specialization, and technology-focused admixture formulators. Competitive moves center on fleet reconfiguration for low-slump mixes and digital twin deployment for just-in-time delivery contracts.
Within the national champion tier, China National Building Material Group Corporation and BBMG Corporation exemplify state-affiliated structures with multi-province coverage. SCG anchors Thai supply with integrated control across aggregates, cement, and logistics in the competitive lowland basin. UltraTech Cement Ltd. represents Indian capacity expansion toward government infrastructure pipelines under BIS compliance mandates.
| Leading Market Players |
|---|
| SCG |
| CSCEC |
| China National Building Material Group Corporation |
| SAMPYO GROUP |
| EUGENE GROUP |
| Foshan Huijiang Concrete Co., Ltd. |
| BBMG Corporation |
| UltraTech Cement Ltd. |
| Shanghai Construction Group |
| Others |
Value Chain & Pricing Dynamics
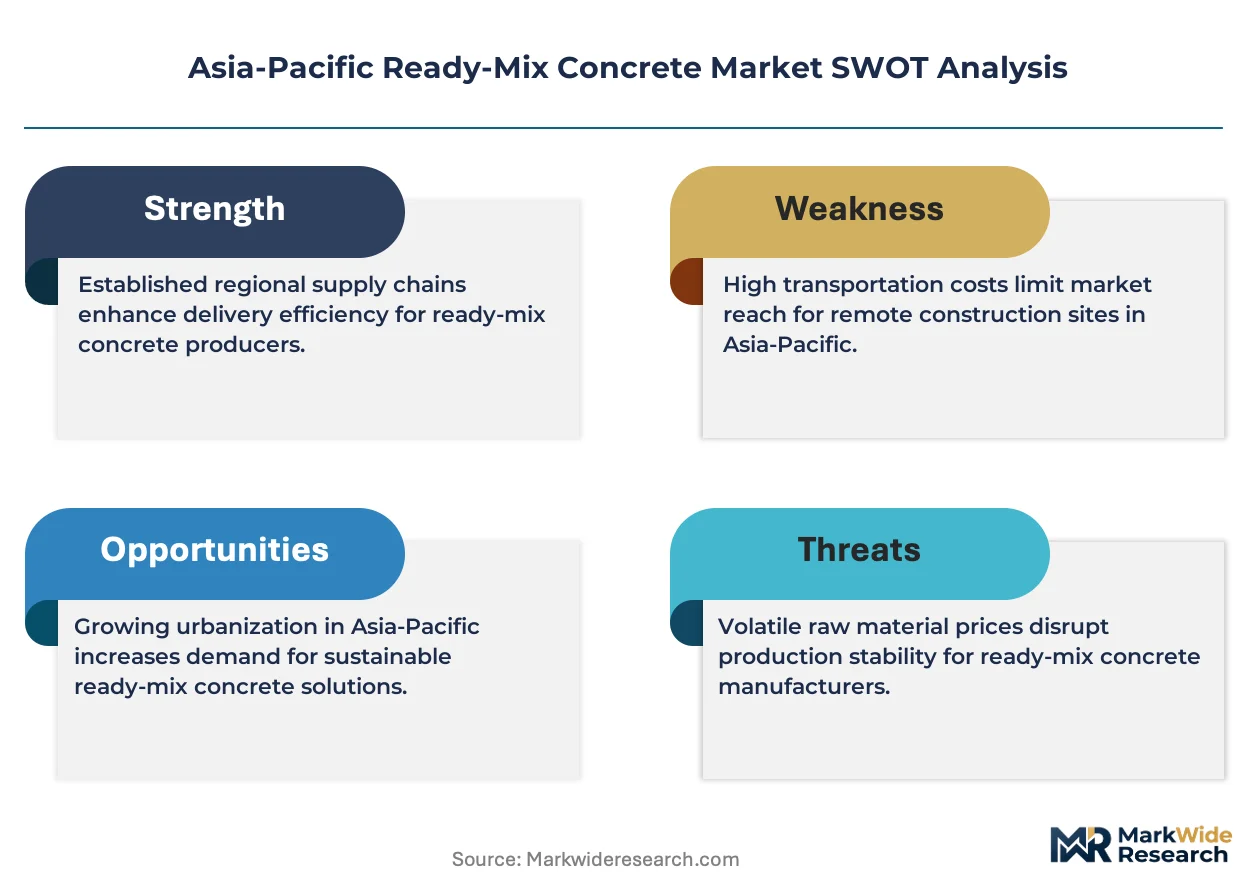
Yangtze River Delta clinker capacity concentration grants coastal Chinese producers outsized leverage over regional ready-mix pricing, compressing margins for inland blenders forced to absorb elevated logistics premiums or cede share to integrated state-affiliated competitors.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure where pricing stratifies across premium, standard, and economy tiers based on compressive strength certification and volume commitment scale. Price differentiation hinges on BIS IS 4926 compliance grade and captive SCM access, with government infrastructure tenders commanding premium rates for documented batch records. Cost compression in the standard grade tier is intensifying because informal on-site mixing still captures significant residential share in Indonesia's peripheral zones. Residential developers exhibit highest price sensitivity, while Singapore commercial contractors purchasing for green mark-certified towers demonstrate lowest sensitivity due to embodied-carbon disclosure requirements.
Supply Chain Analysis
Limestone quarry access in China, Thailand, and Vietnam anchors upstream feedstock security for integrated producers, while regional fly ash availability draws from coal plant retirement schedules in South Korea and Japan. Key inputs include Portland cement clinker, GGBFS from integrated steelworks, and viscosity-modifying admixtures for self-consolidating formulations. Single-source vulnerability concentrates around captive slag grinding capacity, where producers lacking in-house production face costlier imports. Distribution runs through provincial mixing networks with dedicated drum fleets, though central mix plant expansion is displacing transit-mixing for quality-sensitive infrastructure contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ready-mix concrete incumbents face substitution pressure from precast modular systems and on-site 3D printing technologies that compress structural construction timelines, requiring defensive positioning around quality assurance infrastructure and just-in-time delivery capabilities.
For Market Incumbents: Harden quality variance control through IoT-enabled slump monitoring deployment across fleet operations, and secure captive SCM access via backward integration into slag grinding capacity or long-term fly ash supply agreements. China's MIIT dual carbon benchmarks threaten margin compression for conventional Portland blenders, making certification investment for low-carbon mix documentation the priority defensive lever against state-affiliated competitors with provincial network scale.
For New Entrants and Emerging Players: Establish a beachhead in Vietnam's Ho Chi Minh City electronics park corridor where integrated RMC capacity lags accelerating industrial floor demand, and target specialized fiber-reinforced grades for seismic-zone infrastructure in Japan's Tohoku region where JIS standards exclude low-cost competitors. A go-to-market angle anchored around digital twin curing algorithms for fast-track data center contracts differentiates against legacy volume-based operators.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because national procurement platform mandates in India and Indonesia are displacing regional batch plants, creating acquisition targets among mid-tier operators with BIS laboratory accreditation and fleet reconfiguration capacity. The signal to watch is tightening embodied-carbon disclosure requirements in Singapore and coastal Chinese provinces, which will accelerate preference for blended mix suppliers with verified EPDs and captive SCM infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SCM Grinding | Captive GGBFS capacity insulates margin from coal plant retirement volatility across Northeast Asia. |
| Digital Twin Deployment | Predictive curing algorithms enable just-in-time contracts for Seoul and Singapore fast-track hospital builds. |
| Fleet Reconfiguration for Low-Slump Mixes | Drum fleet transition captures self-consolidating concrete demand in high-rise core wall applications. |
| EPD Certification Investment | Verified embodied-carbon disclosure qualifies suppliers for Singapore BCA green mark incentive programs. |
| Provincial Network Expansion | Multi-province batch plant coverage meets India's centralized procurement mandates for 500-plus kilometer corridors. |
Study Parameters
Initial hypotheses were tested against primary input from ready-mix plant operations managers, infrastructure procurement officers at state construction corporations, admixture technical sales directors, and logistics fleet supervisors, and refined through secondary validation against China MEE carbon intensity filings, India BIS laboratory accreditation records, Japan METI industrial production statistics, and customs data for GGBFS trade flows. Bottom-up volume estimates from batch plant capacity utilization were triangulated against top-down construction spending projections across the analysis window.
Demand-supply balance modeling anchored the forecast framework, with segmentation across product type, end user, delivery model, and application dimensions. CAGRs were derived from elasticity-adjusted construction volume projections and clinker-to-cement ratio compression trajectories under MIIT dual carbon enforcement. Key inputs included provincial infrastructure pipeline announcements, coal plant retirement schedules affecting fly ash availability, and green building certification adoption curves in commercial construction clusters.
Sensitivities concentrate around MEE enforcement variance across Chinese provinces, BIS accreditation timeline delays for new admixture chemistries, and SCM import disruption from geopolitical friction. Cross-checking against IEA cement sector decarbonization benchmarks and national construction spending databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Technical Insulation Market
Building & Construction Materials
Residential Elevator Market
Building & Construction Materials
Floor Screeds Market
Building & Construction Materials
North America Gutter Guards Market
Building & Construction Materials
TMT Steel Bar Market
Building & Construction Materials
United States Roofing Market
Building & Construction Materials
Nordic Solar Shades Market
Building & Construction Materials
Gypsum and Drywall Market
Building & Construction Materials
Dimension Stone Market
Building & Construction Materials
Black Bricks Market
Building & Construction Materials
North America Mineral Wool Ceiling Tiles Market
Building & Construction Materials
Asia-Pacific Construction Adhesives Market
Building & Construction Materials
Polished Concrete Market
Building & Construction Materials
US Windows Market
Building & Construction Materials
Europe Timber Construction Connectors Market
Building & Construction Materials
Italy Ceramic Tiles Market