
 Wind Turbine Installation Vessel Market | 2026-2036
Wind Turbine Installation Vessel Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Installation Vessel Market Analysis
Heavy-lift jack-up specifications above twelve thousand metric tons is redrawing procurement priorities for offshore wind contractors. Van Oord leverages its integrated project delivery model across North Sea developments. Fred. Olsen Windcarrier anchors its competitive stance through specialized turbine transport and installation capabilities. Cadeler differentiates with a pure-play focus on next-generation wind turbine installation vessels purpose-built for escalating component weights.
A wind turbine installation vessel is a purpose-built marine construction unit featuring retractable jack-up legs or dynamic positioning systems, designed to lift, transport, and install turbine components at offshore locations with precision tolerances within millimeters. These vessels integrate heavy-lift cranes exceeding one thousand five hundred metric tons, leg-raising systems for seabed fixation, and deck areas exceeding five thousand square meters to accommodate tower sections, nacelles, and blades in single voyages. Jack-up vessels dominate current deployment due to operational stability during turbine assembly at fixed heights above sea level. Semi-submersible configurations represent the fastest-expanding category as water depths at new lease sites push beyond sixty meters and floating foundation projects multiply. Operational depth segmentation shows deep water assignments capturing expanding margin pools where day rates command substantial premiums over shallow water equivalents.
The International Maritime Organization's carbon intensity regulations and EU MRV monitoring requirements are tightening fuel efficiency standards for newbuild vessels, compelling operators to evaluate alternative propulsion architectures. National maritime regulators in Germany, the United Kingdom, and Denmark enforce stringent safety certification protocols for jack-up operations in crowded North Sea shipping corridors. Classification societies including DNV and Bureau Veritas are updating rules for hybrid-electric powertrains and crane load cases that exceed prior thresholds. Stakeholders must weigh fleet renewal timing against evolving turbine dimensions and carbon compliance deadlines.
Market Dynamics
Escalating turbine component weights above fifteen megawatts are compressing vessel utilization rates and forcing fleet-wide specification resets across North Sea contractors.
Growth Catalysts
- EU Green Deal offshore targets:Binding national capacity mandates in Germany, Denmark, and the Netherlands are accelerating vessel deployment schedules and extending contract backlogs through the decade.
- Fifteen-megawatt turbine proliferation:Rotor diameters exceeding two hundred twenty meters demand heavy-lift crane upgrades above two thousand metric tons, concentrating procurement among specialized newbuilds.
- North Sea lease round density:Crown Estate and Bundesnetzagentur auctions are clustering development sites, reducing vessel transit times and improving day-rate economics for jack-up operators.
Market Restraints
- Specialized steel plate scarcity:High-yield marine-grade steel from Korean and Japanese mills faces allocation limits, extending newbuild delivery timelines by eight to fourteen months.
- Leg-length physics constraints:Jack-up vessel operational ceilings near ninety meters restrict deployment at floating foundation sites in Portuguese and Norwegian deep-water zones.
- IMO carbon intensity indexing:Compliance deadlines for existing fleet retrofits are compressing residual asset values and accelerating scrapping decisions for pre-2010 vessels.
Strategic Opportunities
- US Atlantic coast lease expansion:Bureau of Ocean Energy Management auctions off Massachusetts and North Carolina are opening first-mover positions for Jones Act-compliant vessel partnerships.
- Hybrid-electric propulsion retrofit kits:Battery-hybrid systems from ABB and Siemens Energy are enabling existing vessels to access premium charter rates in EU Emissions Trading System zones.
- Floating foundation installation specialization:Semi-submersible heavy-lift vessels purpose-built for tension-leg and semi-sub platform mating command day-rate multiples above fixed-bottom equivalents.
Industry Challenges
- Jack-up barge master certification scarcity:Experienced leg-positioning and preload engineers are concentrated among retiring cohorts, constraining safe operational tempo during weather windows.
- Crane load-case re-certification delays:DNV and Bureau Veritas review queues for modified crane configurations are extending vessel return-to-service intervals by six to ten weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Installation Vessel Market |
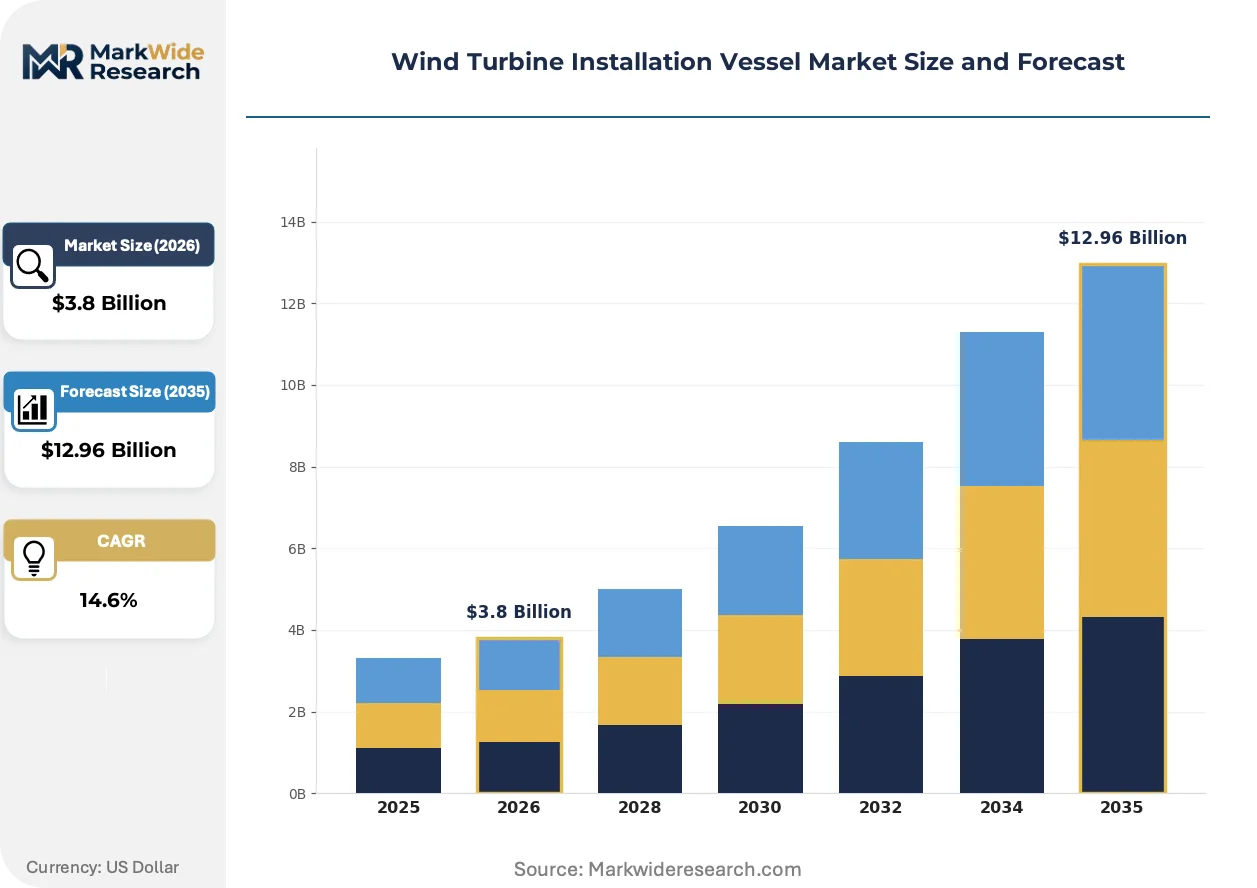
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Jack-up Vessels, Barges, Semi-submersible Vessels, Monohull Vessels Operational Depth: Shallow Water, Deep Water, Ultra-deep Water, Transitional Water Power Rating: 3 MW, 5 MW, 8 MW, 10 MW End User: Energy Companies, Contractors, Government Agencies, Others |
| Companies Covered | Van Oord, Fred. Olsen Windcarrier, Cadeler, Boskalis, Jan De Nul, Seaway 7, DEME, Ørsted, Heerema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Installation Vessel Market Emerging Trajectories
Vessel architecture is splitting between incremental jack-up optimization and radical semi-submersible redesign as water depth requirements diverge across lease portfolios.
Crane pedestal reinforcement using high-tensile steel and active heave-compensation systems is bifurcating the installation vessel fleet. Offshore wind developers with fifteen-megawatt turbine commitments are specifying dual-crane configurations capable of simultaneous nacelle and blade lifting. This capability compression is eliminating single-crane vessels from competitive bidding for utility-scale projects.
The EU Emissions Trading System maritime inclusion and FuelEU Maritime regulations are mandating annual carbon intensity reductions for vessels above five thousand gross tons. Operators are responding with methanol-ready engine contracts and shore-power interface installations at Port of Esbjerg and Port of Hull. Deep-water semi-submersible newbuilds are absorbing the highest compliance cost premiums due to auxiliary power demands during dynamic positioning operations.
Charter contracting is consolidating from spot-market availability toward decade-long framework agreements with turbine OEMs. Vestas and Siemens Gamesa are locking vessel access through strategic partnerships rather than arm's-length day-rate negotiations. This preference shift is most pronounced in the United Kingdom and Germany, where pipeline visibility supports long-dated commitment structures.
Wind Turbine Installation Vessel Market Segmentation
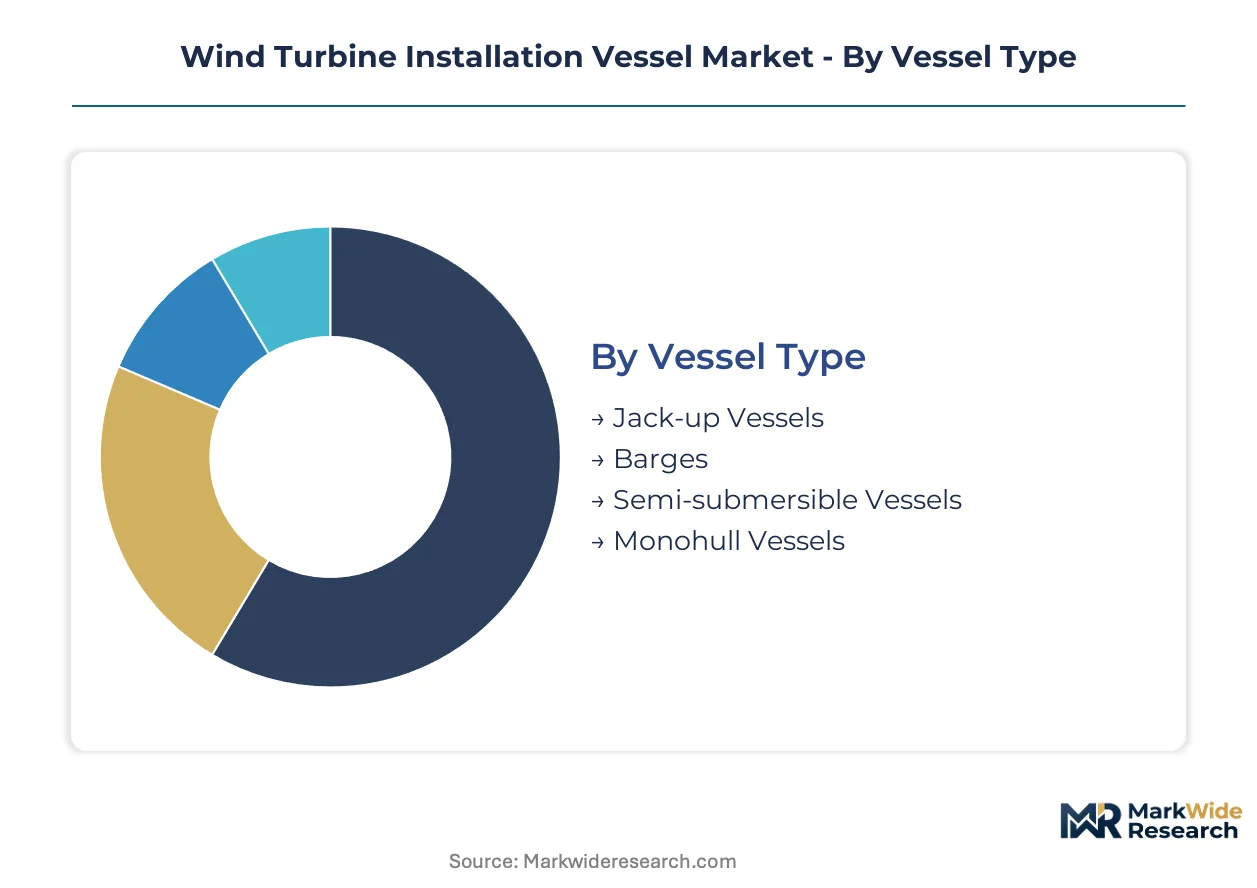
Vessel specifications diverge sharply across turbine dimensions and seabed conditions. Regulatory depth limits and crane load-case certifications fragment procurement criteria for offshore wind developers.
Vessel Type:
IMO classification societies enforce distinct stability and leg-length standards for each hull architecture, creating compliance-driven procurement tiers.
- Jack-up Vessels:Retractable leg systems enable seabed fixation with millimeter-precision jacking operations above wave action. German and Danish North Sea clusters concentrate demand here, driven by EU Green Deal capacity mandates requiring operational certainty in crowded shipping corridors.
- Semi-submersible Vessels:Ballast-controlled hull platforms deliver dynamic positioning stability beyond jack-up depth ceilings without seabed penetration. Portuguese and Norwegian floating foundation projects absorb supply here as water depths exceed ninety meters.
- Barges:Flat-deck transport units without self-elevating capability require auxiliary heavy-lift vessels for component transfer.
- Monohull Vessels:Conventional displacement hulls serve component ferrying and crew transfer roles with lower capital intensity.
Jack-up vessels handle the majority of throughput; semi-submersible vessels are gaining share fastest.
Operational Depth:
Lease auction geography determines depth exposure, with Crown Estate and Bundesnetzagentur site allocations clustering contractors into distinct technical tiers.
- Shallow Water:Sites below forty meters favor jack-up economics with minimal leg extension and rapid preload cycles. United Kingdom eastern seaboard developments concentrate here, compressing vessel transit windows between adjacent lease blocks.
- Deep Water:Sixty-to-ninety-meter zones stretch jack-up leg engineering limits while enabling fixed-bottom foundation deployment. German Bight and Danish Kriegers Flak absorb specialized newbuild capacity.
- Ultra-deep Water:Submerged tension-leg and semi-sub platform mating demands semi-submersible heavy-lift configurations with active heave compensation.
- Transitional Water:Forty-to-sixty-meter depths split between extended-leg jack-ups and early semi-submersible adoption.
Shallow water segments dominate current vessel-days; deep water assignments command the steepest expansion trajectory.
Power Rating:
Turbine OEM specification roadmaps align vessel crane capacity with nacelle mass and rotor assembly requirements.
- 10 MW:Fifteen-hundred-metric-ton crane thresholds and blade lengths exceeding ninety meters demand reinforced pedestal engineering and expanded deck stowage. Siemens Gamesa and Vestas supply commitments in German waters drive fleet renewal here.
- 8 MW:Mature installation protocols with established jack-up compatibility and shorter crane boom configurations.
- 5 MW:Legacy turbine classes with residual replacement demand in early North Sea wind farms.
- 3 MW:Obsolete ratings facing accelerated decommissioning as repowering cycles commence.
Ten-megawatt specifications absorb the majority of newbuild investment; eight-megawatt classes retain the largest installed base.
End User:
Contracting structures and balance-sheet capacity differentiate procurement authority across the offshore wind value chain.
- Energy Companies:Integrated utilities with decade-long pipeline visibility favor framework agreements over spot chartering. Ørsted and RWE procurement desks in Esbjerg and Hamburg lock vessel access through strategic partnerships rather than arm's-length day-rate negotiations.
- Contractors:Specialized marine construction firms bid project-specific scopes with fleet flexibility and crew certification premiums.
- Government Agencies:State-backed offshore wind development corporations in Taiwan and South Korea are emerging as direct vessel charterers.
- Others:Research institutions and foundation technology developers with intermittent installation requirements.
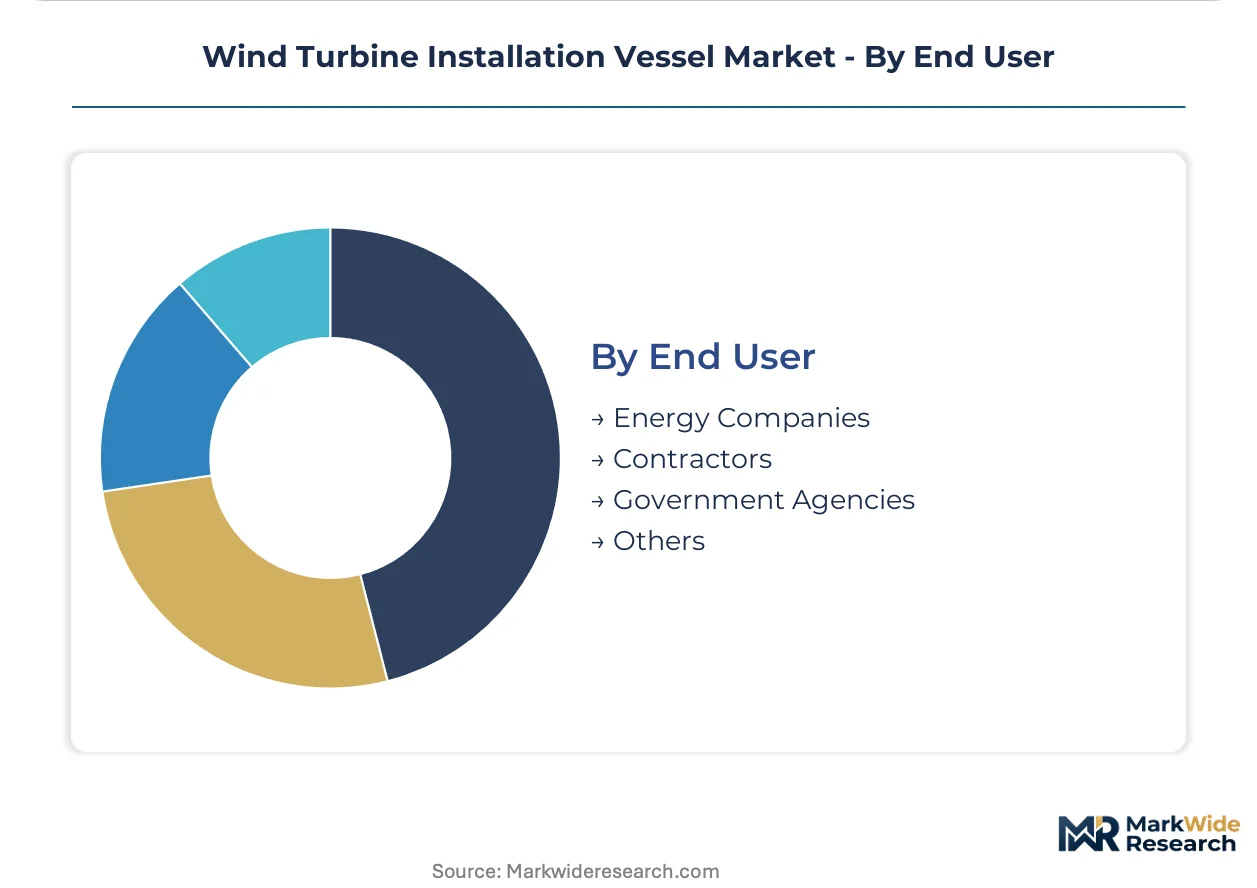
Energy companies control the majority of vessel contracting volume; contractors represent the most price-sensitive demand segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized vessel fabrication concentrates in yards clustered around North Sea demand centers, with German, Danish, and UK port cities absorbing the majority of newbuild contracts. Fleet deployment patterns track Crown Estate and Bundesnetzagentur lease allocations, compressing transit windows between adjacent development blocks.
United Kingdom
Crown Estate auction rounds off Scotland and England's eastern seaboard are clustering fixed-bottom sites in forty-meter depths. The UK's Maritime and Coastguard Agency enforces jack-up safety protocols in crowded shipping corridors. Port of Hull and Port of Grimsby are expanding heavy-lift quayside infrastructure to accommodate nacelle staging.
Germany
Bundesnetzagentur offshore tenders in the German Bight are stretching jack-up leg engineering limits at sixty-to-ninety-meter depths. Germany's Federal Maritime and Hydrographic Agency certifies vessel stability for North Sea winter operations. Port of Cuxhaven and Port of Emden are consolidating turbine component marshalling yards.
Denmark
Ørsted's pipeline visibility and national capacity mandates are accelerating vessel deployment schedules through 2030. The Danish Maritime Authority enforces stringent leg-positioning certification for jack-up masters. Port of Esbjerg anchors the North Sea installation supply chain with dedicated heavy-lift berths.
Netherlands
Hollandse Kust lease rounds are absorbing semi-submersible capacity for deeper water assignments. The Netherlands' Human Environment and Transport Inspectorate monitors carbon intensity compliance under EU MRV requirements. Port of Rotterdam is retrofitting shore-power interfaces for methanol-ready newbuilds.
Norway
Floating foundation pilots in Norwegian deep-water zones are bypassing jack-up physics constraints entirely. Norway's Maritime Authority regulates semi-submersible dynamic positioning standards for tension-leg platform mating. Port of Stavanger and Port of Bergen are developing heavy-lift infrastructure for subsea foundation installation.
Wind Turbine Installation Vessel Market Vendor Landscape
Concentration sits with integrated offshore contractors commanding fleet scale and decade-long framework agreements with turbine OEMs. The vendor base splits between diversified marine construction conglomerates and pure-play wind installation specialists. Three archetypes dominate: legacy dredging and offshore firms pivoting into wind, purpose-built wind turbine installation vessel operators, and energy company captive fleets. Competitive moves center on strategic partnerships locking vessel access and capacity expansion through Korean and Japanese yard contracts.
Among integrated marine construction groups, Van Oord, Boskalis, and Jan De Nul exemplify the diversified archetype with cross-sector capabilities spanning dredging, offshore oil and gas, and wind installation. Within the pure-play specialist tier, Fred. Olsen Windcarrier and Cadeler occupy positions defined by exclusive focus on turbine transport and installation. DEME and Seaway 7 represent European-based contractors with heavy-lift jack-up and semi-submersible portfolios. Heerema anchors the heavy-lift semi-submersible segment with deep-water installation expertise.
| Leading Market Players |
|---|
| Van Oord |
| Fred. Olsen Windcarrier |
| Cadeler |
| Boskalis |
| Jan De Nul |
| Seaway 7 |
| DEME |
| Ørsted |
| Heerema |
| Others |
Supply Flow & Price Mechanics
High-tensile steel substitution for conventional marine-grade plate is redrawing procurement geography from European mills toward Korean and Japanese suppliers while compressing newbuild pricing bands by fourteen to eighteen percent. This material shift simultaneously fragments vessel cost structures and concentrates bargaining power among alloy-certified fabricators.
Pricing Analysis
FuelEU Maritime dictates the pricing tier structure across the installation vessel fleet, separating methanol-ready newbuilds from conventional diesel configurations. Day-rate premiums stratify across premium, standard, and economy tiers based on crane capacity above two thousand metric tons and hybrid-electric propulsion certification. Cost compression in the standard tier is intensifying because charterers are locking decade-long framework agreements with turbine OEMs. Independent contractors represent the most price-sensitive demand segment, while integrated energy companies with pipeline visibility accept premium tier rates.
Supply Chain Analysis
Strait of Malacca transit chokepoints for Korean and Japanese high-yield steel plate underpin vessel delivery reliability across European yards. Supply concentrates in South Korea, Japan, and select German fabrication facilities for specialized jack-up leg systems. Raw material dependencies center on nickel-alloy steel, advanced crane pedestal forgings, and dynamic positioning thruster packages. Single-source vulnerability from two Korean mill groups dominates structural steel procurement. Distribution runs through turbine OEM marshalling yards at Port of Esbjerg and Port of Hull.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wind turbine installation vessel market is recovering from a cyclical trough as fifteen-megawatt turbine commitments force fleet-wide specification resets. This renewal wave justifies defensive positioning and selective capacity expansion.
For Market Incumbents: Shield charter rate erosion by locking decade-long framework agreements with Vestas and Siemens Gamesa before newbuild capacity floods the North Sea. Prioritize backward integration into high-yield steel procurement through Korean mill partnerships to secure allocation priority. Accelerate hybrid-electric retrofit certification to access FuelEU Maritime premium tiers. For New Entrants and Emerging Players: Floating foundation installation specialization offers the most penetrable white-space as Portuguese and Norwegian deep-water projects bypass jack-up physics constraints. Target semi-submersible heavy-lift configurations for tension-leg platform mating where day-rate multiples exceed fixed-bottom equivalents. Partner with Bureau of Ocean Energy Management lease winners for Jones Act-compliant vessel positions off Massachusetts. For Investors and Strategic Acquirers: EU Emissions Trading System maritime inclusion reshapes the acquisition landscape toward methanol-ready newbuilds and battery-hybrid retrofit platforms. Five-to-ten-year viability favors pure-play specialists with crane capacity above two thousand metric tons over diversified marine construction conglomerates. Monitor DNV and Bureau Veritas certification queue lengths as inflection indicators for vessel return-to-service velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Retrofit Deployment | Battery-hybrid systems from ABB enable FuelEU Maritime compliance and premium charter rate access. |
| High-Yield Steel Mill Partnership | Long-term offtake agreements with Korean suppliers secure allocation amid plate scarcity. |
| Floating Foundation Specialization | Semi-submersible newbuilds for Norwegian tension-leg projects command day-rate multiples. |
| Framework Agreement Consolidation | Decade-long turbine OEM partnerships displace spot-market chartering in UK and German waters. |
| Jones Act Vessel Positioning | US Atlantic coast lease expansion opens first-mover positions for compliant vessel partnerships. |
Methodological Framework
The analysis maps jack-up vessel specifications, semi-submersible configurations, and operational depth segments, each validated through vessel operators, turbine OEM procurement desks, and classification society surveyors. Primary interviews with marine construction executives, offshore wind developers, and port authority infrastructure planners combined with secondary validation from DNV maritime rules, IMO carbon intensity regulations, and Crown Estate lease allocation databases. Bottom-up vessel deployment tracking and top-down market sizing triangulated across Korean and Japanese yard order books.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled vessel type, operational depth, power rating, and end-user contracting structure dimensions. CAGRs derived from fleet expansion timelines, turbine OEM specification roadmaps, and national offshore wind capacity mandates. Industry-specific inputs included crane load-case certification queues, high-yield steel delivery schedules, and FuelEU Maritime compliance cost curves.
Forecasts assume regulatory continuity in EU Emissions Trading System and FuelEU Maritime regimes; material policy shifts would require re-modeling of vessel retrofit economics and charter rate premiums. Specific risks include IMO carbon intensity indexing acceleration, Korean steel mill allocation disruptions, and floating foundation technology substitution. Practitioners should keep alternative scenarios live as turbine dimension trajectories and carbon compliance deadlines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Offshore Inspection, Repair, and Maintenance Market
Marine and Coastal Engineering
Marine Hawser Market
Marine and Coastal Engineering
Submersible Dredge Pump Market
Marine and Coastal Engineering
Offshore Pipeline Market
Marine and Coastal Engineering
Asia-Pacific Offshore Crane Market
Marine and Coastal Engineering
Global Seismic Vessels Market
Marine and Coastal Engineering
Marine Heat Exchanger Market
Marine and Coastal Engineering
Ship Gangways Market
Marine and Coastal Engineering
Work Barges Market
Marine and Coastal Engineering
Marine Manifolds and Risers Market
Marine and Coastal Engineering
Marine Watertight Door Market
Marine and Coastal Engineering
Subsea Trencher Market
Marine and Coastal Engineering
Global Marine and Dock Gangways Market
Marine and Coastal Engineering
Mooring Bollards Market
Marine and Coastal Engineering
STS (Ship-To-Shore) Cranes Market
Marine and Coastal Engineering
Seismic Support Vessels Market