
 Philippines Building System Components Market | 2026-2036
Philippines Building System Components Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Building System Components Market Analytics
Preventive maintenance contracts and lifecycle service agreements is rebalancing how building system components are monetized beyond the initial sale. USG Boral Building Products leverages its gypsum board specialization to anchor supply relationships with large-scale commercial contractors. United Steel Technology Int'l Corporation sustains fabrication capacity that dominates structural steel deliveries across Luzon-based projects. SMC Builders competes through integrated construction services that bundle material procurement with installation labor.
Building system components encompass prefabricated and site-installed assemblies including windows, doors, roofing, and insulation, manufactured from wood, steel, concrete, or PVC to provide structural enclosure, thermal performance, and weather protection in buildings. Steel-framed roofing systems typically employ galvanized coils with zinc coating weights between Z120 and Z275 to achieve corrosion resistance in tropical marine environments. The residential application segment leads volume absorption as housing backlog drives repetitive standard designs, while modular installation methods capture expanding share by compressing construction schedules and reducing on-site labor dependency.
The Department of Public Works and Highways enforces National Building Code compliance that mandates structural load calculations and fire-resistance ratings for all commercial and institutional submissions. BIS-equivalent material standards administered by the Bureau of Product Standards shape import clearance protocols for PVC and steel component categories. The Climate Change Commission adaptation frameworks are pressuring envelope performance specifications upward, particularly for insulation R-values in new public building procurement. Stakeholders must monitor how pending green building mandate expansions could disqualify conventional material grades from government-funded project eligibility.
Market Dynamics
Pre-fabrication adoption is compressing traditional construction timelines across Philippine residential and industrial projects, forcing material suppliers to reconfigure fulfillment models around just-in-time structural assembly delivery.
Growth Catalysts
- Industrial Park Expansion:Central Luzon industrial zones are absorbing steel and concrete system components at unprecedented scale, creating sustained demand for standardized structural assemblies.
- National Building Code Enforcement:The Department of Public Works and Highways tightened material certification requirements, mandating structural load calculations that favor certified pre-engineered systems over conventional site-built alternatives.
- Housing Backlog Pressure:Metro Manila residential developers are expanding procurement of pre-fabricated structural assemblies to address persistent housing shortages through faster project completion.
Market Restraints
- Galvanized Steel Input Volatility:Zinc coating specifications between Z120 and Z275 for tropical marine corrosion resistance expose roofing system manufacturers to commodity price swings in global metal markets.
- Import Clearance Friction:Bureau of Product Standards protocols for PVC and steel component categories create processing delays that disadvantage foreign suppliers against domestic fabricators.
- Skilled Installation Bottleneck:Modular assembly methods require certified erection crews that remain concentrated in Metro Manila and Cebu, limiting deployment speed in secondary cities.
Strategic Opportunities
- Visayas and Mindanao Undersupply:Construction activity in Davao and Iloilo outpaces local component manufacturing capacity, creating white space for regional distribution hubs.
- Climate Adaptation Procurement:The Climate Change Commission adaptation frameworks are pressuring envelope performance specifications upward, particularly for insulation R-values in new public building tenders.
- Lifecycle Service Monetization:Preventive maintenance contracts and lifecycle service agreements are rebalancing revenue streams beyond initial component sales for integrated suppliers.
Industry Challenges
- Certification Timeline Compression:Fire-resistance rating approvals for commercial and institutional submissions require extended testing cycles that delay project mobilization.
- Legacy Labor Dependency:Traditional construction crews resist modular installation training, slowing workforce transition despite schedule advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Building System Components Market |
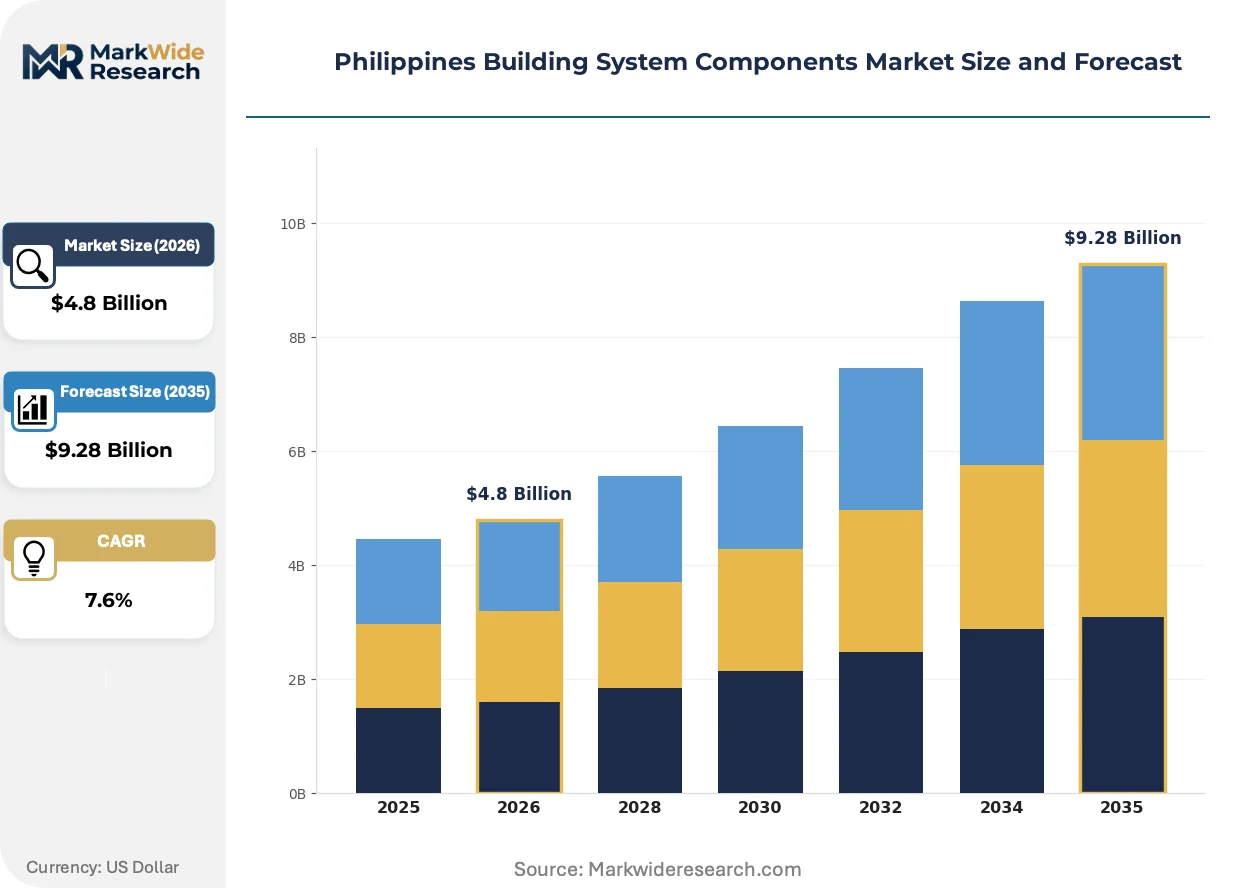
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Windows, Doors, Roofing, Insulation Material: Wood, Steel, Concrete, PVC Application: Residential, Commercial, Industrial, Institutional Installation Method: Pre-fabricated, On-site Assembly, Modular, Custom-built |
| Companies Covered | USG Boral Building Products, United Steel Technology Int'l Corporation, SMC Builders, Metro Pacific Investments Corporation, iSteel Inc., Union Galvasteel Corporation, Eterna Industries, DuraSteel, Power Steel Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Building System Components Market Evolving Landscape
Digital fabrication and regulatory pressure on building performance are converging to transform how structural assemblies are specified, manufactured, and delivered across Philippine construction markets.
Building information modeling is integrating with pre-fabrication workflows to enable precise off-site cutting and assembly of steel-framed roofing systems. Large-scale commercial contractors in Metro Manila are adopting BIM-coordinated structural packages to reduce field-fit errors and compress erection schedules. This technology convergence is integrating design, manufacturing, and installation phases into unified digital threads that eliminate traditional handoff friction.
The Climate Change Commission adaptation frameworks are mandating higher thermal performance standards for public building envelopes. Bureau of Product Standards is aligning testing protocols with these requirements, forcing insulation and glazing suppliers to recertify product lines. Government-funded projects in Central Luzon and CALABARZON are responding by specifying high-R-value envelope assemblies that exceed legacy code minimums.
Large residential developers are consolidating supplier relationships around integrated structural package providers. Single-source procurement of pre-fabricated wall, roof, and floor assemblies is displacing fragmented material bidding in volume housing projects. This concentration is most visible in Cavite and Bulacan industrialized housing zones where repetitive standard designs favor systematized component supply over conventional build methods.
Philippines Building System Components Market Segmentation
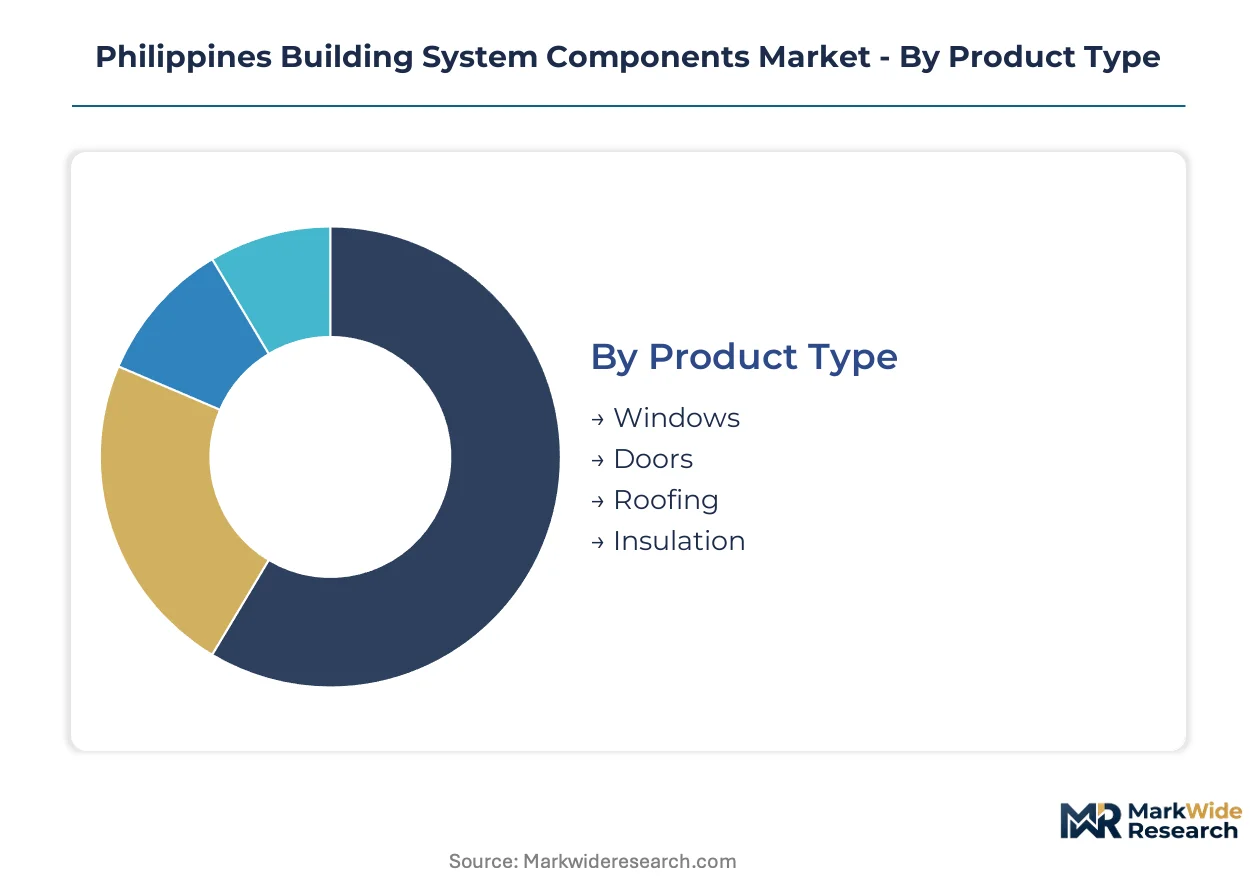
Philippine building system components fragment across four dimensions that determine procurement patterns, margin structures, and supplier relationships. Product type and material composition define the technical specifications required by tropical marine environments, while application and installation method shape fulfillment models and project economics.
Product Type:
Standalone envelope elements dominate initial procurement, though integrated façade systems are gaining traction in large-scale developments where thermal performance certification drives specification.
- Windows:Aluminum-framed and uPVC profiles with double-glazed configurations address rising envelope performance mandates from the Climate Change Commission. Cavite and Bulacan industrialized housing zones absorb volume shipments of standardized window packages.
- Doors:Fire-rated steel and timber-core assemblies carry certification requirements from the Bureau of Product Standards that extend lead times for commercial and institutional submissions. Metro Manila commercial contractors consolidate procurement around pre-hung door systems to compress installation schedules.
- Roofing:Galvanized steel coils with Z120 to Z275 zinc coating specifications provide corrosion resistance.
- Insulation:R-value upgrades are pressuring specification shifts in public building tenders.
Volume placements concentrate in Roofing; the faster expansion belongs to Insulation.
Material:
Cost tier positioning separates commodity-grade inputs from performance-certified alternatives, with import friction and domestic fabrication capacity shaping competitive dynamics.
- Steel:Galvanized coil and structural section fabrication dominates Central Luzon industrial park deliveries, with United Steel Technology Int'l Corporation sustaining capacity that controls Luzon-based project supply. Bureau of Product Standards protocols create clearance advantages for domestic mills over imported alternatives.
- Concrete:Precast wall and floor assemblies absorb capital deployment from SMC Builders and integrated construction service providers bundling material with installation labor. Standardized repetitive designs in volume housing enable systematized component supply over site-cast methods.
- Wood:Tropical hardwood and engineered timber products face sustainability scrutiny.
- PVC:Window profiles and piping systems encounter import processing delays.
Steel captures the dominant volume share; PVC is climbing the fastest as uPVC window adoption accelerates.
Application:
Customer type and project scale determine specification rigor, with government-funded developments enforcing stricter certification than private residential construction.
- Residential:Housing backlog pressure in Metro Manila drives repetitive standard designs that favor pre-fabricated wall, roof, and floor assemblies. Large developers consolidate supplier relationships around integrated structural package providers to accelerate project completion.
- Industrial:Central Luzon industrial zones absorb steel and concrete system components at unprecedented scale, with standardized structural assemblies meeting accelerated construction timelines for manufacturing facility envelopes.
- Commercial:Fire-resistance rating approvals extend testing cycles.
- Institutional:Public building procurement responds to Climate Change Commission adaptation frameworks.
Residential commands the largest placement volumes; Industrial is gaining share fastest.
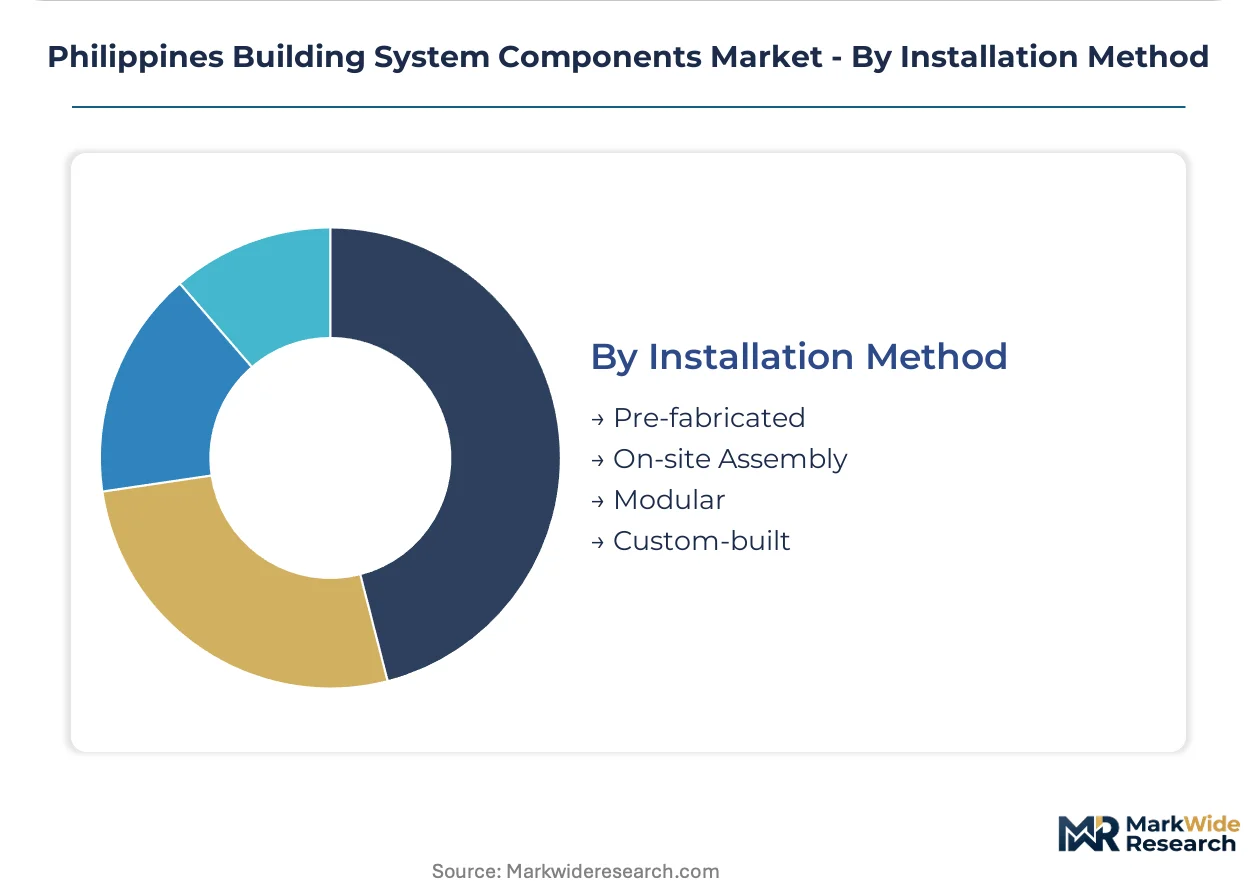
Installation Method:
Maturity and supply concentration separate established on-site practices from emerging modular approaches that compress schedules but require certified erection crews.
- Pre-fabricated:Off-site cutting and assembly of steel-framed roofing systems integrates with building information modeling to reduce field-fit errors. Metro Manila large-scale commercial contractors adopt BIM-coordinated structural packages to compress erection schedules.
- Modular:Complete volumetric units require certified erection crews concentrated in Metro Manila and Cebu, limiting deployment speed in Davao and Iloilo where construction activity outpaces local capacity. Visayas and Mindanao undersupply creates white space for regional distribution hubs.
- On-site Assembly:Traditional construction crews resist modular installation training.
- Custom-built:Bespoke fabrication serves high-specification institutional projects.
Pre-fabricated methods hold the volume concentration; Modular approaches show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic fabrication capacity concentrates in Central Luzon and Metro Manila, while construction demand spreads across the archipelago's emerging growth corridors. This geographic mismatch creates fulfillment challenges for standardized structural assemblies.
Metro Manila
Large-scale commercial contractors dominate pre-fabricated structural procurement to compress erection schedules. The Department of Public Works and Highways enforces National Building Code compliance that mandates fire-resistance ratings for institutional submissions. Cavite and Bulacan industrialized housing zones absorb volume shipments of standardized window and door packages.
Central Luzon
Industrial park construction absorbs steel and concrete system components at unprecedented scale. Bureau of Product Standards protocols create clearance advantages for domestic mills over imported alternatives. Subic-Clark corridor manufacturing facilities drive repetitive demand for galvanized roofing systems with Z120 to Z275 zinc coating specifications.
CALABARZON
Residential developers consolidate supplier relationships around integrated structural package providers. Climate Change Commission adaptation frameworks pressure envelope performance specifications upward in public building tenders. Batangas and Laguna industrial zones sustain precast concrete assembly demand from integrated construction service providers.
Visayas
Construction activity in Iloilo outpaces local component manufacturing capacity. Skilled installation crews for modular assembly methods remain concentrated in Metro Manila and Cebu, limiting deployment speed. White space exists for regional distribution hubs serving secondary city construction markets.
Mindanao
Davao construction markets absorb building system components faster than regional supply chains can fulfill. Import clearance friction through Bureau of Product Standards disadvantages foreign suppliers against domestic fabricators. Local capacity expansion lags behind industrial and residential project pipelines.
Philippines Building System Components Market Competitive Landscape
Top-tier vendors anchor Luzon-based fabrication capacity, while mid-tier specialists compete on installation bundling and regional reach. Three structural archetypes define the competitive terrain: integrated construction service providers, specialized material fabricators, and diversified industrial conglomerates with captive construction arms. Capacity expansion and strategic partnerships represent the dominant competitive moves as players position for pre-fabrication adoption curves.
Among steel-focused fabricators, United Steel Technology Int'l Corporation and Union Galvasteel Corporation exemplify the specialized material archetype with sustained structural section production. SMC Builders occupies a position within the integrated construction service tier, bundling material procurement with installation labor. USG Boral Building Products anchors the building envelope specialization vector through gypsum board and interior system focus. These three represent distinct strategic postures without overlapping core competencies.
| Leading Market Players |
|---|
| USG Boral Building Products |
| United Steel Technology Int'l Corporation |
| SMC Builders |
| Metro Pacific Investments Corporation |
| iSteel Inc. |
| Union Galvasteel Corporation |
| Eterna Industries |
| DuraSteel |
| Power Steel Corporation |
| Others |
Value Network & Pricing Analysis
Pre-fabrication adoption across Philippine construction is compressing cost economics while redistributing supply concentration toward integrated structural package providers. Building information modeling integration with off-site manufacturing tightens coordination between design and production, squeezing traditional material-only suppliers while rewarding bundled service providers with pricing power anchored in schedule certainty.
Pricing Analysis
Margin tightening in standard-grade structural steel traces to galvanized coil input volatility and Bureau of Product Standards certification overhead. Three-tier pricing structure across premium certified, standard compliant, and economy grades separates suppliers by fire-resistance rating and thermal performance tier. Cost-down pressure on economy-grade concrete components accelerates because housing developers prioritize volume throughput over specification upgrades. Industrial park contractors show least price sensitivity, absorbing premium grades to meet accelerated construction timelines.
Supply Chain Analysis
Bureau of Product Standards protocols for PVC and steel component categories are reshaping sourcing toward domestic mills with clearance advantages over imported alternatives. Philippine fabrication capacity concentrates in Central Luzon and Metro Manila, drawing from galvanized coil feedstock and precast concrete inputs. Single-source vulnerability runs through concentrated structural steel supply from Luzon-based mills serving Visayas and Mindanao projects. Distribution runs through project-direct fulfillment from fabrication yards to construction sites, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Building system components procurement is transitioning from fragmented material bidding toward integrated structural packages, with building information modeling coordination displacing conventional specification workflows.
For Market Incumbents: Hedge against pre-fabrication margin compression by deepening captive installation capabilities in Davao and Iloilo where certified erection crews remain scarce. Defend position by securing Bureau of Product Standards pre-approval for standardized assemblies, reducing client procurement friction. Prioritize lifecycle service agreements over transactional component sales to lock recurring revenue streams as initial construction volumes plateau. For New Entrants and Emerging Players: The premium-economy price gap in modular envelope systems creates entry space for mid-tier specialists bundling certified installation with regional distribution hubs. Target Visayas and Mindanao construction markets where local manufacturing capacity lags project pipelines. Pursue joint venture structures with domestic fabricators to navigate import clearance friction and accelerate market access. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated construction service providers seeking captive material supply. Long-term viability favors specialists with Bureau of Product Standards certification infrastructure and regional installation networks spanning secondary cities. Watch Climate Change Commission green building mandate expansion as the signal for envelope performance tier repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Distribution Hub Establishment | Visayas and Mindanao project pipelines outpace local supply, rewarding early hub positioning in Iloilo and Davao. |
| Certification Pre-Approval Investment | Bureau of Product Standards fire-resistance and thermal performance testing reduces client procurement cycles. |
| Lifecycle Service Agreement Expansion | Preventive maintenance contracts rebalance revenue toward recurring streams beyond initial component sales. |
| Backward Integration into Galvanized Coil | Captive supply of Z120 to Z275 zinc-coated steel insulates roofing system margins from commodity volatility. |
| BIM-Coordinated Structural Package Development | Digital fabrication integration compresses field-fit errors and accelerates erection schedules for large contractors. |
Research Methodology
Document review covered Bureau of Product Standards certification protocols, Department of Public Works and Highways building code submissions, and Climate Change Commission adaptation frameworks, complemented by interviews with procurement directors at residential developers, plant managers at Central Luzon steel fabricators, project engineers at industrial park contractors, and distribution channel partners. Secondary validation drew from customs clearance records, construction project databases, and regional industrial zone development plans. Bottom-up volume estimates triangulated against top-down construction spending allocations.
Segment-level projections across product type, material composition, application, and installation method were generated through the analysis window. The analytical framework incorporated housing backlog absorption rates, industrial park construction pipelines, and regulatory compliance timeline compression. CAGRs were derived from fitted growth curves calibrated to historical pre-fabrication adoption patterns and projected certification requirement tightening.
Inputs from Bureau of Product Standards and Department of Public Works and Highways were available through the study window; gaps in real-time project pipeline data from Mindanao introduce uncertainty bands around regional forecasts. Forecasts reflect assumptions regarding green building mandate expansion pace and skilled crew training program scaling. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Glue-Laminated Timber Market
Building & Construction Materials
GCC Ceramic Tiles Market
Building & Construction Materials
Tar Paper Market
Building & Construction Materials
Prefabricated Building System Market
Building & Construction Materials
Asia-Pacific Oriented Strand Board Market
Building & Construction Materials
Manufactured Sand Market
Building & Construction Materials
Precast Concrete Market
Building & Construction Materials
Soil Stabilization Market
Building & Construction Materials
North America Steel Rebar Market
Building & Construction Materials
Liquid Applied Roofing Market
Building & Construction Materials
North America Fabricated Metal Products Market
Building & Construction Materials
Middle-East and Africa Construction Adhesives Market
Building & Construction Materials
Slimline Aluminum Window System Market
Building & Construction Materials
Corrugated Steel Panels Market
Building & Construction Materials
Russia Cross Laminated Timber Market
Building & Construction Materials
Architectural Acoustic Panels Market