
 Fiberboard Ceiling Market | 2026-2036
Fiberboard Ceiling Market Size, Share, and Industry Trends Forecast 2026-2036
Fiberboard Ceiling Market Analytics
A capital-intensity divergence between integrated resin producers and commodity panel converters is bifurcating competitive returns in fiberboard ceiling supply. Kronospan Limited leverages captive forestry assets and particleboard co-generation to sustain margin compression better than non-integrated rivals. Armstrong World Industries anchors its specification channel through architectural rep networks and LEED-compliant product libraries. Georgia-Pacific competes on scale, operating multiple high-volume continuous press lines serving big-box distribution.
Fiberboard ceiling denotes a rigid, low-density panel manufactured from mechanically refined wood fibers bound with synthetic resin and pressed under heat, typically achieving densities of 400–800 kg/m³ and Noise Reduction Coefficients up to 0.70 for acoustic grades. These panels suspend in T-bar grid systems or direct-mount to conceal mechanical infrastructure while delivering sound absorption, thermal resistance, or decorative finish. The acoustic segment leads specification value owing to open-plan office and education retrofit cycles, while moisture-resistant grades command premium positioning in healthcare and food-processing applications where ASTM E84 Class A flame spread ratings are mandatory. Decorative fiberboard ceiling panels occupy a mature, price-sensitive tier serving residential and light commercial contractors through distributor stock programs.
The US EPA regulates formaldehyde emissions from composite wood products under TSCA Title VI, directly limiting resin chemistry choices and factory certification burdens for domestic manufacturers. ASTM E84 and UL 723 fire-performance testing governs commercial building code acceptance, with California's Department of Housing and Community Development enforcing additional seismic bracing requirements for suspended ceiling assemblies. The EU Ecodesign Framework and REACH chemical restrictions shape export product configurations for North American suppliers serving European project channels. Stakeholders must monitor evolving embodied-carbon disclosure rules in procurement mandates, as environmental product declarations increasingly filter specification eligibility in public-sector construction.
Market Dynamics
Acoustic performance mandates in commercial retrofit specifications are compressing product development cycles and forcing resin chemistry pivots among fiberboard ceiling manufacturers seeking code compliance across multiple jurisdictions.
Growth Catalysts
- California Title 24 thermal upgrades:Ceiling assembly R-value requirements are accelerating specification of insulated fiberboard systems in commercial retrofits throughout the state.
- Passivhaus construction:Germany's certified building program is concentrating demand for high-performance fiberboard ceiling panels with integrated thermal breaks.
- Open-plan office acoustics:Noise Reduction Coefficient ratings above 0.60 are becoming mandatory in North American workplace redesigns, favoring perforated fiberboard installations.
Market Restraints
- Formaldehyde resin cost volatility:Urea-formaldehyde binder chemistry faces input price swings tied to natural gas feedstocks, squeezing converter margins.
- European supply concentration:Decorative-grade fiberboard production clusters in Central European continuous press corridors, creating logistics vulnerability for North American distributors.
- Mineral fiber substitution:Wet-felted mineral wool panels with equivalent NRC performance are capturing healthcare specification share where moisture resistance is paramount.
Strategic Opportunities
- India commercial construction:Bureau of Indian Standards certification gaps in acoustic ceiling systems create first-mover positioning for fiberboard suppliers establishing local testing protocols.
- Mass timber hybrid buildings:Cross-laminated timber structures require compatible ceiling systems where low-density fiberboard offers weight-matched fire-rated assemblies.
- EU Ecodesign embodied-carbon mandates:Environmental Product Declaration requirements in public procurement are favoring wood-based ceiling materials over mineral alternatives in Nordic markets.
Industry Challenges
- Continuous press technician scarcity:Operating high-volume fiberboard lines requires specialized heat-transfer and resin-cure expertise that vocational programs have not scaled to meet.
- TSCA Title VI certification lag:EPA third-party certifier queue times extend factory qualification periods, delaying product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiberboard Ceiling Market |
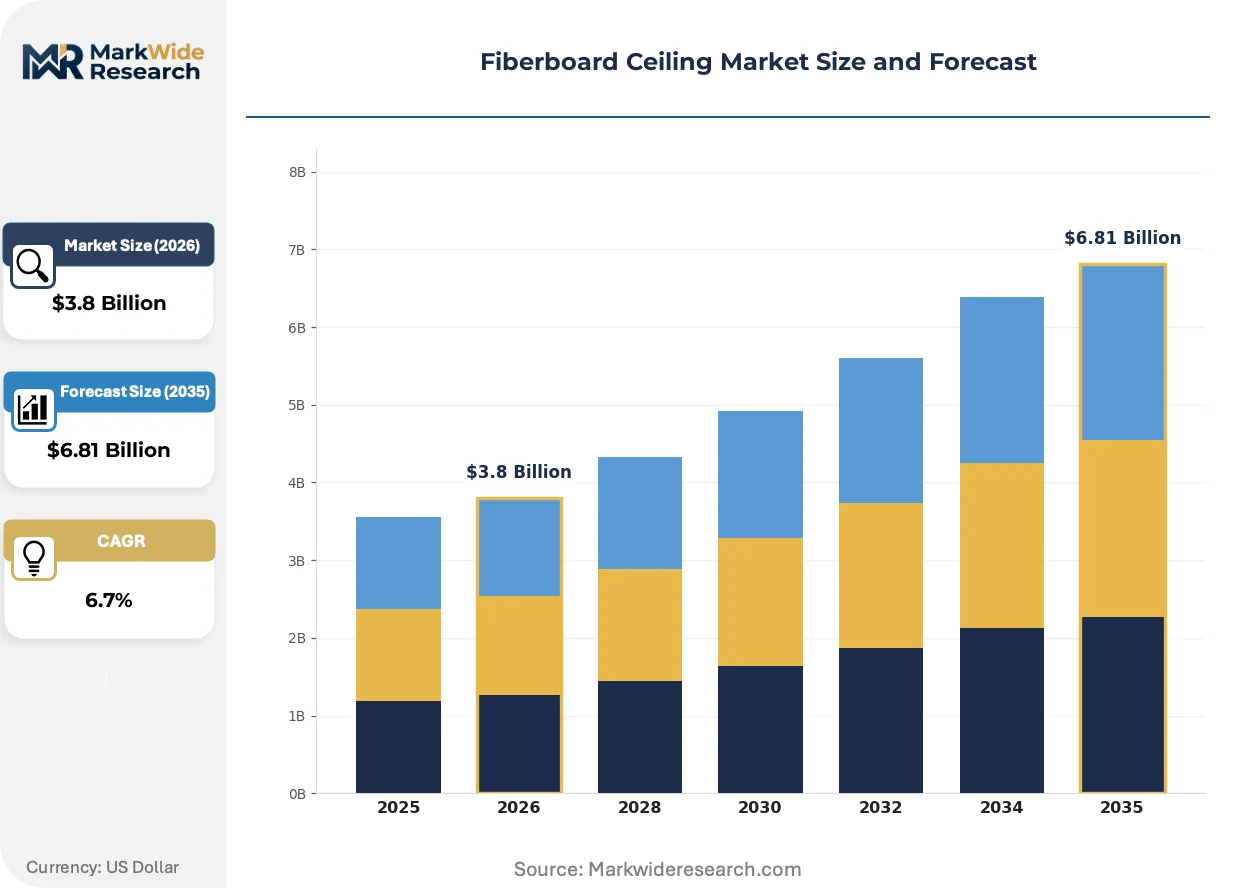
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acoustic, Decorative, Insulated, Moisture-Resistant Application: Commercial Buildings, Residential Interiors, Industrial Facilities, Hospitality Material: Wood, Gypsum, Plastic, Mineral Fiber End User: Architects, Contractors, Property Developers, Homeowners |
| Companies Covered | Arauco Corporation, Kronospan Limited, Egger Group, Dare Panel Group, Kastamonu Entegre Corporation, Georgia-Pacific, Armstrong World Industries, USG Corporation, Daiken Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiberboard Ceiling Market Evolving Landscape
Digital specification tools and bio-based resin platforms are compressing traditional product development timelines while fragmenting procurement authority across architect, contractor, and facility manager constituencies.
Micro-perforated fiberboard facing technology is miniaturizing acoustic pore geometries below 0.5mm diameter, enabling tuned absorption across broader frequency ranges without additional backing materials. Healthcare and performing arts venues are specifying these systems at accelerating rates. The technology is miniaturizing the physical footprint of high-NRC ceiling assemblies, reducing plenum depth requirements in constrained retrofit structures.
REACH chemical restriction amendments are forcing reformulation of melamine-urea resin systems used in moisture-resistant grades, with ECHA substance evaluation driving substitution toward pMDI binders in export-oriented production. German and French manufacturers face the steepest compliance curves. Acoustic-grade fiberboard destined for EU public works must now carry updated safety data sheets reflecting the 2023-2025 evaluation window substance restrictions.
Architects are consolidating ceiling specification authority through proprietary digital product libraries that bypass traditional rep networks, with large commercial practices in California and Texas building in-house databases of pre-vetted assemblies. Distributor stock-and-defer programs are losing share to direct-to-jobsite fulfillment coordinated by master specification writers. This concentration is most visible in education and municipal verticals where repeat building types enable templated ceiling selections.
Fiberboard Ceiling Market Segmentation
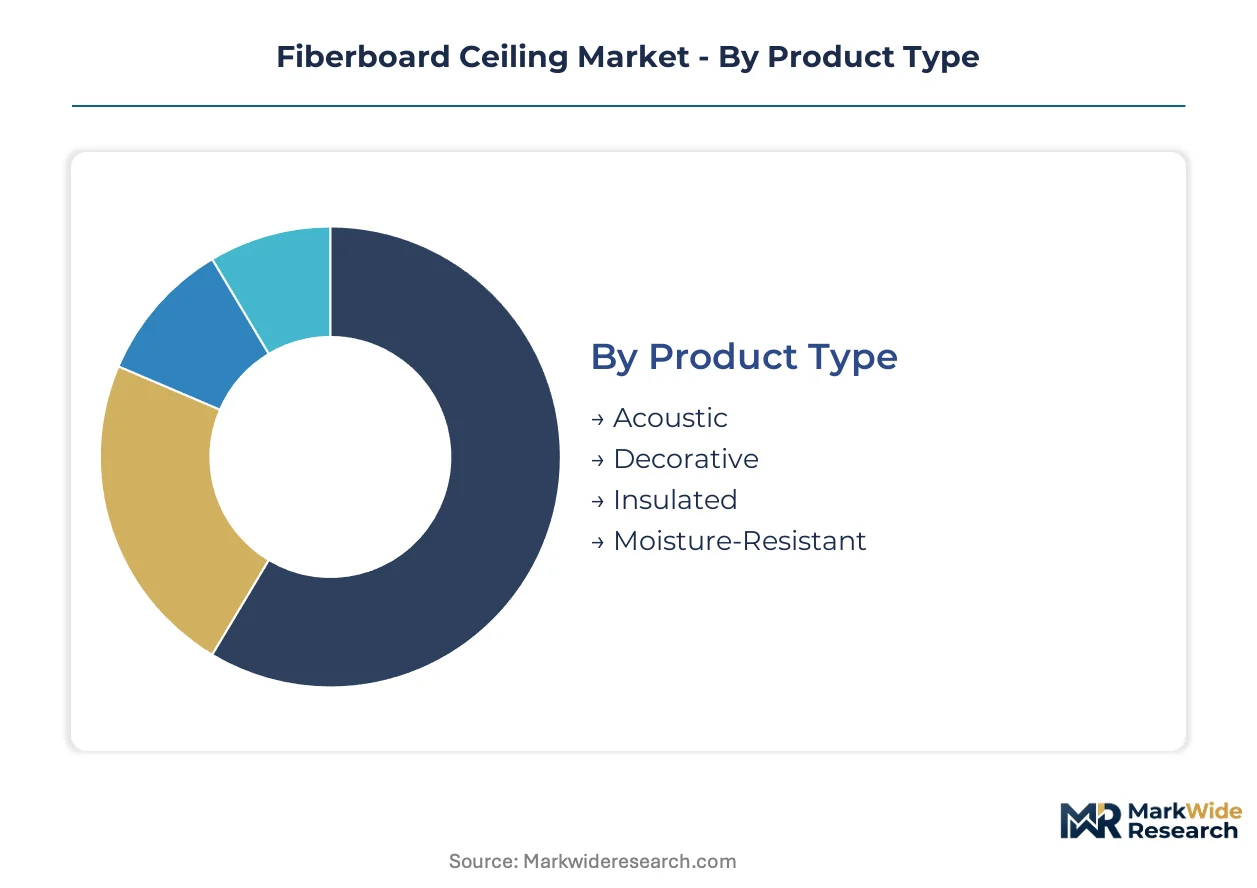
Fiberboard ceiling specification fragments across performance tiers, end-use verticals, and procurement channels. Each segment carries distinct regulatory burdens and substitution exposure that reshape competitive positioning.
Product Type:
Substitution pressure from mineral fiber and metal alternatives concentrates in decorative and standard acoustic grades, forcing fiberboard suppliers to defend share through performance differentiation.
- Acoustic:Perforated or fissured surfaces achieve Noise Reduction Coefficients of 0.60–0.70, engineered with tuned cavity depths for open-plan offices and education retrofits. North American workplace redesign mandates are compressing specification cycles for NRC-rated assemblies.
- Decorative:Smooth or textured facings serve residential and light commercial finish requirements through distributor stock programs. Wet-felted mineral wool and PVC-laminated gypsum panels are capturing price-sensitive volume in this tier.
- Insulated:Factory-laminated thermal layers integrate with Passivhaus-certified assemblies in Germany. California Title 24 R-value upgrades are accelerating commercial retrofit specification.
- Moisture-Resistant:Melamine-urea or pMDI resin systems achieve ASTM E84 Class A ratings for healthcare and food-processing environments. REACH amendments are forcing resin reformulation in EU-bound production.
Acoustic retains volume leadership; insulated holds the steepest expansion curve.
Application:
Cost tier stratification separates specification-grade commercial projects from residential stock-and-defer procurement, with margin compression deepest in contractor-driven segments.
- Commercial Buildings:Corporate headquarters, healthcare facilities, and municipal structures demand certified fire performance and acoustic control. LEED-compliant product libraries and master specification templates dominate procurement authority.
- Residential Interiors:Single-family and multi-family finish work relies on distributor availability and contractor familiarity. Big-box retail channels and regional lumberyards stock standard decorative grades.
- Industrial Facilities:Manufacturing plants and warehouses prioritize durability and chemical resistance over aesthetic finish. Wash-down requirements favor moisture-resistant or non-fiber alternatives.
- Hospitality:Hotels and restaurants balance acoustic comfort with decorative impact. Franchise specification programs and brand-standard design guides constrain supplier selection.
Commercial Buildings anchor revenue concentration; Hospitality climbs the fastest.
Material:
Supply concentration in continuous press corridors and raw material sourcing patterns determine regional cost competitiveness across substrate alternatives.
- Wood:Mechanically refined softwood fibers bound with synthetic resin achieve densities of 400–800 kg/m³. Captive forestry assets and particleboard co-generation sustain margin positions for integrated producers.
- Gypsum:Wet-cast or laminated gypsum core panels compete on fire resistance and dimensional stability. Plasterboard manufacturers leverage existing wallboard distribution infrastructure.
- Plastic:PVC or PET-based ceiling systems offer moisture immunity and cleanability for hygiene-critical environments. Healthcare specification is shifting toward these alternatives where steam sterilization protocols apply.
- Mineral Fiber:Wet-felted slag wool or rock wool delivers equivalent NRC performance with superior moisture resistance. Wet-felted mineral wool is displacing fiberboard in hospital and laboratory specifications.
Wood dominates installed base; plastic gains share fastest in healthcare verticals.
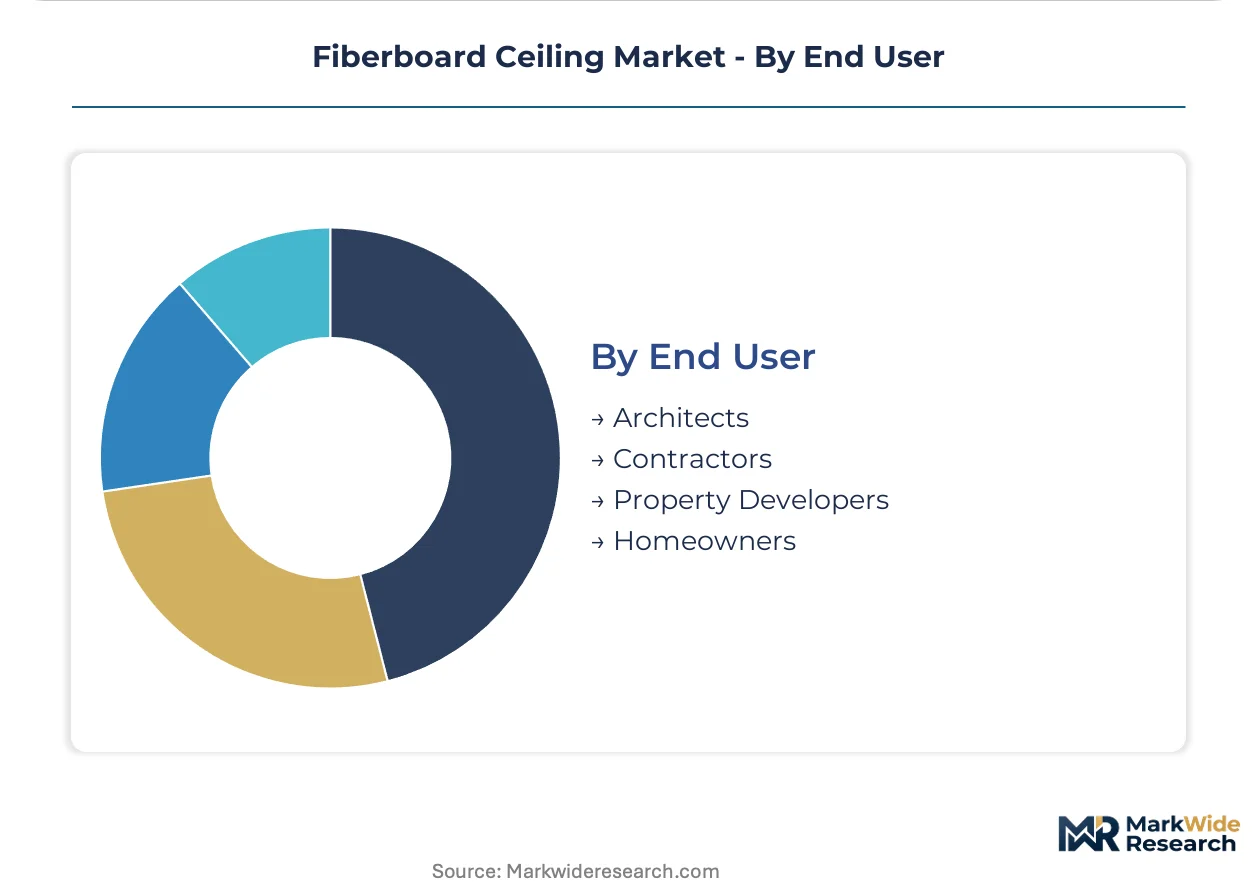
End User:
Procurement authority fragmentation across design, construction, and ownership phases reshapes channel strategy and technical support requirements.
- Architects:Specification authority consolidates through proprietary digital product libraries and pre-vetted assembly databases. Large California and Texas practices are building in-house databases that bypass traditional rep networks.
- Contractors:Value engineering pressure and schedule constraints drive substitution toward readily available alternatives. Stock-and-defer programs are losing share to direct-to-jobsite fulfillment.
- Property Developers:Pro forma cost targets and repeat building types enable templated ceiling selections. Multi-tenant commercial and student housing projects standardize across portfolios.
- Homeowners:Retail selection and contractor recommendation dominate residential decision-making. Big-box availability and visual samples outweigh technical performance claims.
Architects control specification gatekeeping; property developers are expanding most quickly as a procurement segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. German buyers prioritize Passivhaus-certified thermal performance over cost, while Indian contractors select on availability and contractor familiarity.
Germany
Passivhaus-certified construction concentrates demand for insulated fiberboard ceiling panels with integrated thermal breaks. The EU Ecodesign Framework mandates embodied-carbon disclosure for public procurement. Production clusters in Bavaria and North Rhine-Westphalia supply high-performance grades to certified building projects across the Rhine-Ruhr metropolitan region.
United States
California's Title 24 energy code revisions tighten thermal performance requirements for commercial ceiling assemblies. The EPA regulates formaldehyde emissions under TSCA Title VI, limiting resin chemistry choices. Manufacturing concentrates in the Southeast and Pacific Northwest, serving retrofit cycles in Los Angeles and San Francisco Bay Area office markets.
China
Commercial construction in first-tier cities drives specification of acoustic-rated systems for open-plan offices. The country's national building code enforces fire-performance testing equivalent to ASTM standards. Production gravity centers on the Yangtze River Delta, where continuous press corridors serve Shanghai and Hangzhou development pipelines.
India
Bureau of Indian Standards certification gaps in acoustic ceiling systems create positioning opportunities for suppliers establishing local testing protocols. The national building code lacks harmonized NRC rating requirements. Demand concentrates in Maharashtra and Karnataka, where Mumbai and Bangalore commercial towers specify imported fiberboard for premium finishes.
United Kingdom
LEED-equivalent BREEAM certification drives specification of low-embodied-carbon ceiling materials in London commercial retrofits. The Building Safety Regulator enforces fire-performance testing for high-rise assemblies. Specification authority clusters in London and the Southeast, where architectural practices build proprietary digital product libraries.
Fiberboard Ceiling Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in fiberboard ceiling supply. Captive forestry assets and particleboard co-generation distinguish the upper tier from non-integrated converters. Two strategic archetypes dominate: integrated resin-to-panel producers leveraging backward control over wood fiber supply, and specification-channel specialists anchoring architectural rep networks. Capacity expansion and portfolio diversification toward moisture-resistant and acoustic grades constitute the primary competitive moves.
Among integrated producers, Kronospan Limited exemplifies the captive-asset archetype through its forestry and co-generation model. Armstrong World Industries occupies a position as a specification-channel anchor with architectural network penetration. Georgia-Pacific represents scale-driven manufacturing serving high-volume distribution channels.
| Leading Market Players |
|---|
| Arauco Corporation |
| Kronospan Limited |
| Egger Group |
| Dare Panel Group |
| Kastamonu Entegre Corporation |
| Georgia-Pacific |
| Armstrong World Industries |
| USG Corporation |
| Daiken Corporation |
| Others |
Value Network & Pricing Analysis
Mineral fiber substitution in healthcare specifications simultaneously redraws supply geography toward wet-felted mineral wool corridors and compresses pricing power in moisture-resistant fiberboard tiers. This displacement dynamic forces fiberboard manufacturers to defend acoustic-grade premiums while absorbing resin cost volatility in commoditized decorative segments.
Pricing Analysis
Specification support contracts and extended warranty bundles drive lifetime value capture in commercial-grade fiberboard ceiling systems. Three-tier pricing structure across premium acoustic, standard decorative, and economy retrofit levels separates NRC-certified assemblies from distributor stock programs. Price differentiation hinges on LEED-compliant certification libraries and captive forestry integration. Cost compression in decorative grades is intensifying because wet-felted mineral wool and PVC-laminated gypsum panels capture price-sensitive volume. Contractor-driven residential segments exhibit highest price sensitivity, while Passivhaus-certified commercial projects in Germany show lowest.
Supply Chain Analysis
Germany and Austria anchor high-performance insulated fiberboard production for Passivhaus-certified assemblies, while the United States concentrates acoustic and moisture-resistant grades serving California Title 24 retrofits. Raw material flows draw from softwood fiber plantations, urea-formaldehyde resin feedstocks, and pMDI binder chemicals. Single-source vulnerability clusters in Central European continuous press corridors serving North American decorative-grade demand. Distribution runs through architectural specification networks for commercial projects and big-box retail channels for residential stock programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital specification platforms are reconstituting fiberboard ceiling procurement as a platform-economics inflection, with proprietary architect databases displacing traditional rep networks and fragmenting authority across design, construction, and ownership phases.
For Market Incumbents: Compound specification-channel control through LEED-compliant product library expansion and captive forestry asset deepening to offset mineral fiber substitution in healthcare verticals. Prioritize backward integration into particleboard co-generation and resin chemistry to defend margin compression from urea-formaldehyde feedstock volatility. For New Entrants and Emerging Players: Anchor in Bureau of Indian Standards certification gaps for acoustic ceiling systems, establishing local testing protocols ahead of harmonized NRC requirements. Target Maharashtra and Karnataka commercial tower pipelines where imported fiberboard commands premium positioning for premium finishes. Pursue direct-to-jobsite fulfillment partnerships with master specification writers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated resin-to-panel producers with captive forestry assets and specification-channel penetration. Long-term viability over the next decade rests on environmental product declaration compliance and embodied-carbon disclosure readiness. Watch for REACH amendment implementation as the inflection signal reshaping EU-bound production economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Chemistry | Captive urea-formaldehyde production insulates margin compression from natural gas feedstock swings. |
| Environmental Product Declaration Certification | EU Ecodesign mandates in Nordic public procurement favor wood-based ceiling materials over mineral alternatives. |
| Digital Specification Platform Development | Proprietary architect databases in California and Texas practices bypass traditional rep network intermediation. |
| Regional Testing Protocol Establishment | Bureau of Indian Standards certification gaps create first-mover positioning in Maharashtra commercial construction. |
| Micro-Perforated Facing Technology Investment | Tuned absorption across broader frequency ranges reduces plenum depth requirements in constrained retrofits. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA TSCA Title VI filings, ASTM E84 test reports, and EU Ecodesign Framework documentation. Interviews with specification sales directors, architectural practice technology officers, continuous press operations managers, and distributor procurement leads informed demand-side validation. Customs trade data, SEC 10-K disclosures from building materials manufacturers, and continuous press capacity registries provided supply-side triangulation. Bottom-up volume builds and top-down macroeconomic cross-checks converged on segment-level estimates.
Product type, application vertical, material substrate, and end-user procurement authority dimensions structured the analytical framework. CAGRs were derived from regression analysis against construction spending indices, energy code adoption curves, and retrofit cycle timing. Forecast inputs incorporated Passivhaus certification penetration rates in Germany, California Title 24 compliance deadlines, and REACH amendment implementation timelines across the analysis window.
Underlying assumptions cover resin chemistry stability, continuous press technician availability, and third-party certifier queue durations, with deviation risk concentrated in EPA certification lag periods and ECHA substance evaluation outcomes. Recalibration cycles align with material shifts in energy code revisions, chemical restriction amendments, and specification platform adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Concrete Repair Product Market
Building & Construction Materials
Building Acoustic Insulation Market
Building & Construction Materials
Steep Slope Roofing Materials Market
Building & Construction Materials
Global Anchors and Grouts Market
Building & Construction Materials
North America Freestanding Canopy Market
Building & Construction Materials
Drywall Compound and Drywall Mud Market
Building & Construction Materials
Global Floor and Wall Glazed Tiles Market
Building & Construction Materials
Roofing Underlay Market
Building & Construction Materials
Russia Cross Laminated Timber Market
Building & Construction Materials
Ready-Mix Concrete Market
Building & Construction Materials
Global Cool Roofs Market
Building & Construction Materials
Roof Coating Market
Building & Construction Materials
Industrial Flooring Market
Building & Construction Materials
North America Residential Water Heater Market
Building & Construction Materials
Indonesia Cement Market
Building & Construction Materials
Sliding Bearing Market