
 Precast Concrete Members Market | 2026-2036
Precast Concrete Members Market Size, Share, and Industry Trends Forecast 2026-2036
Precast Concrete Members Market Insights
Modular bundling of wall panels with pre-integrated MEP routing is realigning procurement patterns for commercial developers. Holcim leverages its integrated cement-to-precast chain to control material cost volatility across project timelines. CEMEX anchors its position through digital fabrication platforms that shorten design-to-delivery cycles for complex geometries. CRH competes via regional manufacturing density that reduces transport-driven breakage and scheduling risk for just-in-site delivery.
Precast concrete members are factory-cast structural elements produced under controlled curing conditions with specified compressive strengths, typically using Portland cement with steel or fiber reinforcement, then transported for assembly into buildings, bridges, and utility systems. Floor slabs lead volume contribution due to repetitive span requirements in multi-story construction, while polymer-modified concrete commands margin premiums for corrosion-exposed infrastructure. Wall panels represent the fastest-growing configuration as tilt-up and modular methods displace cast-in-place envelopes in warehouse and logistics facilities.
EU Green Deal carbon benchmarks, EPA construction-material emission guidelines, and BIS structural concrete certification standards collectively tighten compliance thresholds for cross-border project participation. REACH chemical restrictions and evolving EN 206 concrete performance standards further differentiate product-grade access between premium-certified and uncertified suppliers. Stakeholders must monitor regulatory convergence between embodied-carbon accounting and structural performance mandates to avoid stranded capacity in non-compliant production lines.
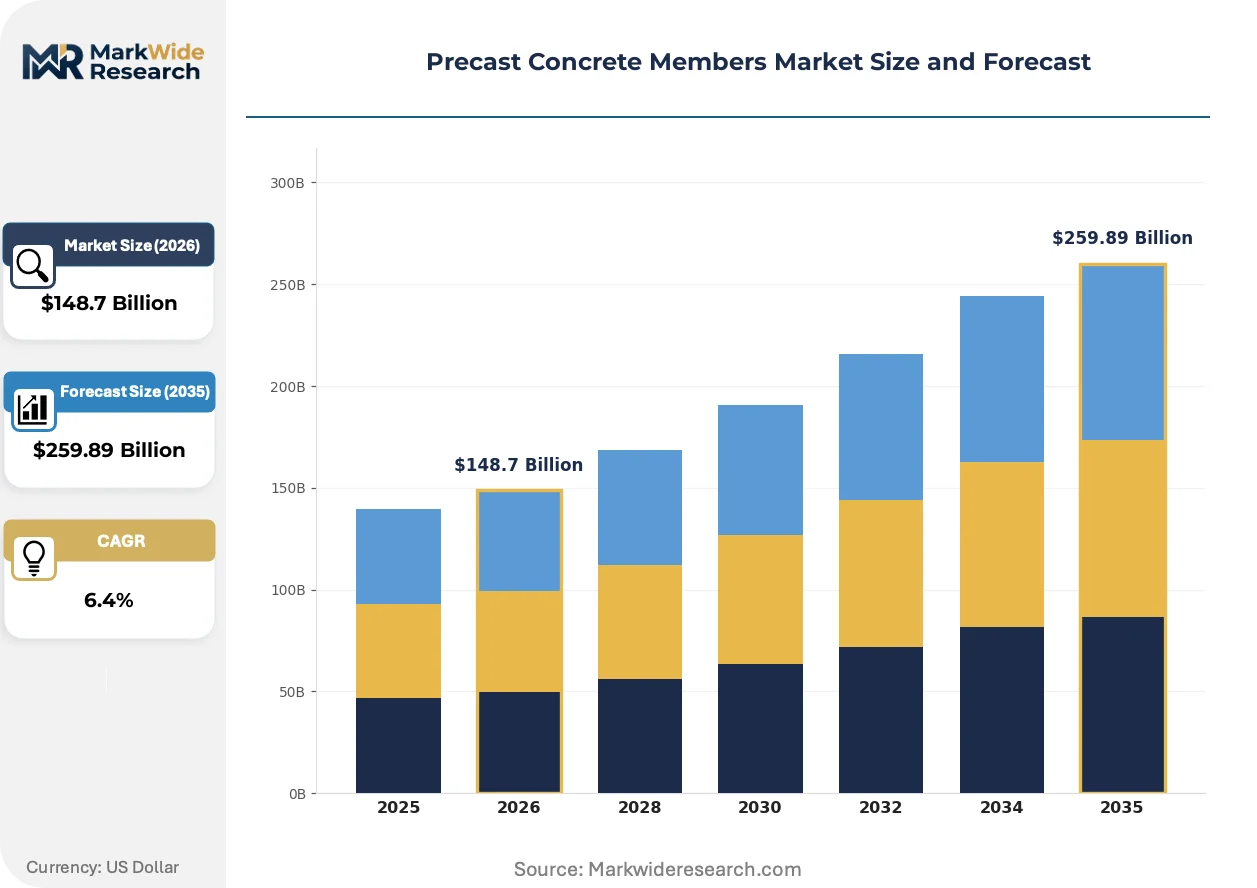
Market Dynamics
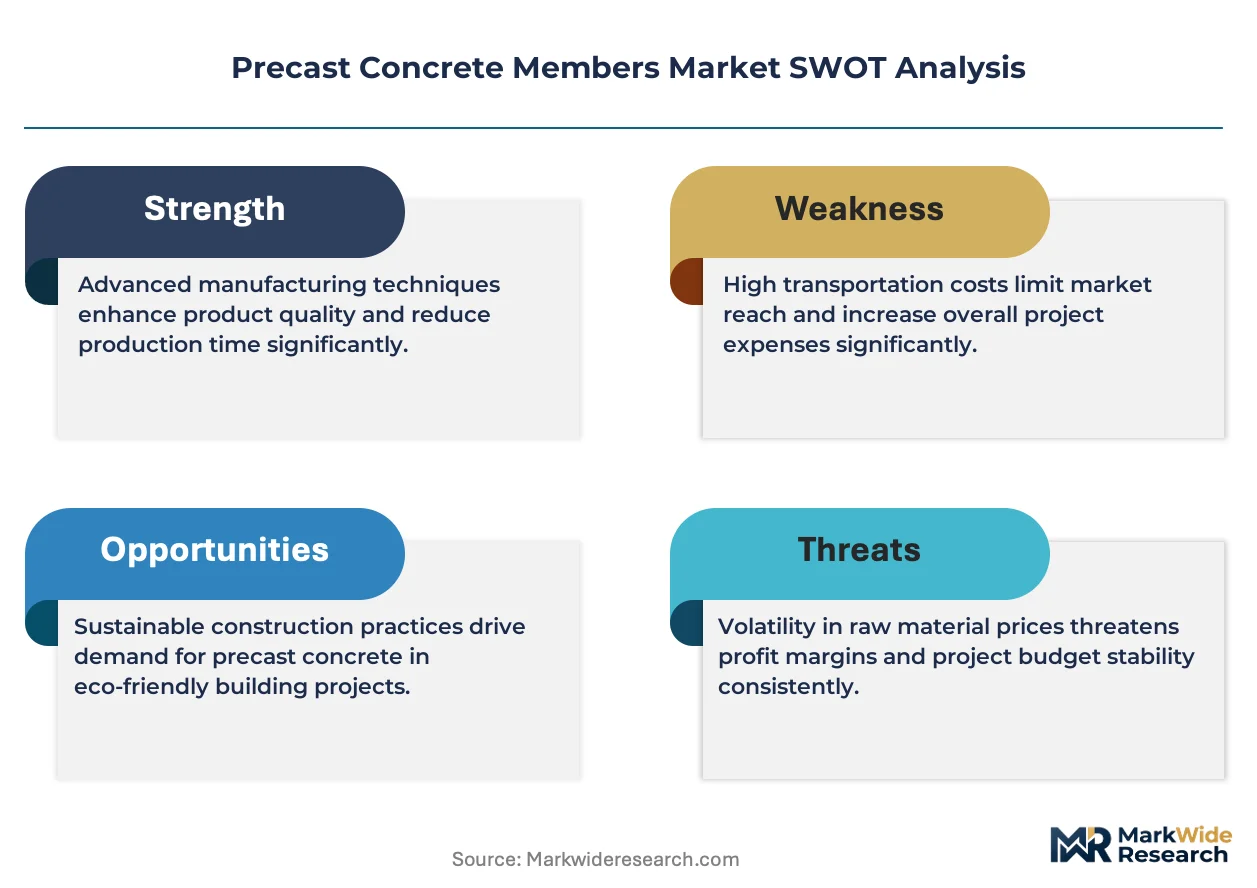
Carbon-accounting mandates from the EU Green Deal and parallel EPA guidelines are forcing manufacturers to reconfigure mix designs and supply chains simultaneously, compressing margins for uncertified producers while rewarding low-carbon formulation leaders.
Growth Catalysts
- EU Green Deal embodied-carbon benchmarks:Builders in Germany, France, and the Netherlands now specify Environmental Product Declarations for structural elements, redirecting procurement toward verified low-carbon precast suppliers.
- Multi-story residential construction:Housing shortages in India and China are accelerating factory-cast floor slab deployment to compress project timelines by 30-40% versus cast-in-place methods.
- Geopolymer and alkali-activated binders:These cement alternatives cut process emissions by 60-80% and are gaining traction in Scandinavian markets with strict national carbon budgets.
Market Restraints
- Portland cement price volatility:Energy costs and clinker supply disruptions in key producing regions transmit directly to precast margin pressure, with limited near-term substitution at scale.
- Heavy transport radius constraints:Precast elements face economic shipping limits of 200-300 kilometers, fragmenting effective market territories and protecting regional incumbents from distant competition.
- Steel reinforcement corrosion in marine environments:Standard carbon steel rebar limits service life in coastal infrastructure, requiring expensive stainless or fiber alternatives that compress project economics.
Strategic Opportunities
- India's Smart Cities Mission and PMAY-Urban:Central government mandates for affordable housing delivery timelines favor industrialized construction methods with precast wall panel systems.
- Carbon capture and utilization in concrete curing:Mineralization technologies that sequester CO2 during production are creating premium product tiers for public infrastructure tenders with green procurement rules.
- Direct-to-developer digital platforms:Bypassing traditional distributor networks, manufacturers are configuring design-to-delivery portals that compress quoting cycles and capture margin from specification through installation.
Industry Challenges
- Finite element modeling and BIM integration:Shortages of technicians capable of translating architectural designs into fabrication-ready precast shop drawings are extending project onboarding timelines.
- EN 206 and BIS certification concurrency:Cross-border suppliers must maintain parallel testing protocols for European and Indian structural concrete standards, duplicating quality assurance overhead.
- Just-in-time delivery coordination:Crane availability and site sequencing precision requirements expose precast schedules to weather and labor disruption risks that factory control cannot eliminate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precast Concrete Members Market |
| Market Size in 2026 | $148.7 Billion |
| Market Size in 2035 | $259.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Panels, Floor Slabs, Beams, Columns Installation Method: Pre-Assembly, On-Site Assembly, Modular Construction, Tilt-Up End User: Commercial Buildings, Residential Structures, Infrastructure Projects, Industrial Facilities Material: Cement, Reinforced Concrete, Polymer-Modified Concrete, Lightweight Aggregate |
| Companies Covered | Holcim, CEMEX, CRH, Boral Limited, Forterra, Oldcastle Infrastructure, Bouygues Construction, HeidelbergCement, Taisei Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precast Concrete Members Market Trends and Innovations
Digital fabrication and material science advances are compressing design-to-installation cycles while regulatory carbon thresholds are redefining product-grade hierarchies across residential, commercial, and infrastructure verticals.
Self-compacting concrete with fiber-reinforced polymer rebar is rewriting structural design assumptions for seismic zones. Japanese and Turkish developers are specifying these hybrid systems for mid-rise residential towers, enabling thinner wall sections and reduced foundation loads that cut overall material volumes by 15-20%.
REACH chemical restrictions and evolving EN 206 performance standards are tightening admixture approval pathways across European member states. Manufacturers serving cross-border projects must now maintain substance inventories compliant with both ECHA candidate lists and national derogation timelines, favoring larger formulators with dedicated regulatory affairs capacity.
Specification authority is migrating from general contractors to design-build consortia and developer-procurement teams. Warehouse and logistics facility builders in the United States are bypassing traditional specification channels, instead contracting directly with precast fabricators for tilt-up envelope packages that bundle structural and architectural finish responsibilities.
Precast Concrete Members Market Segmentation
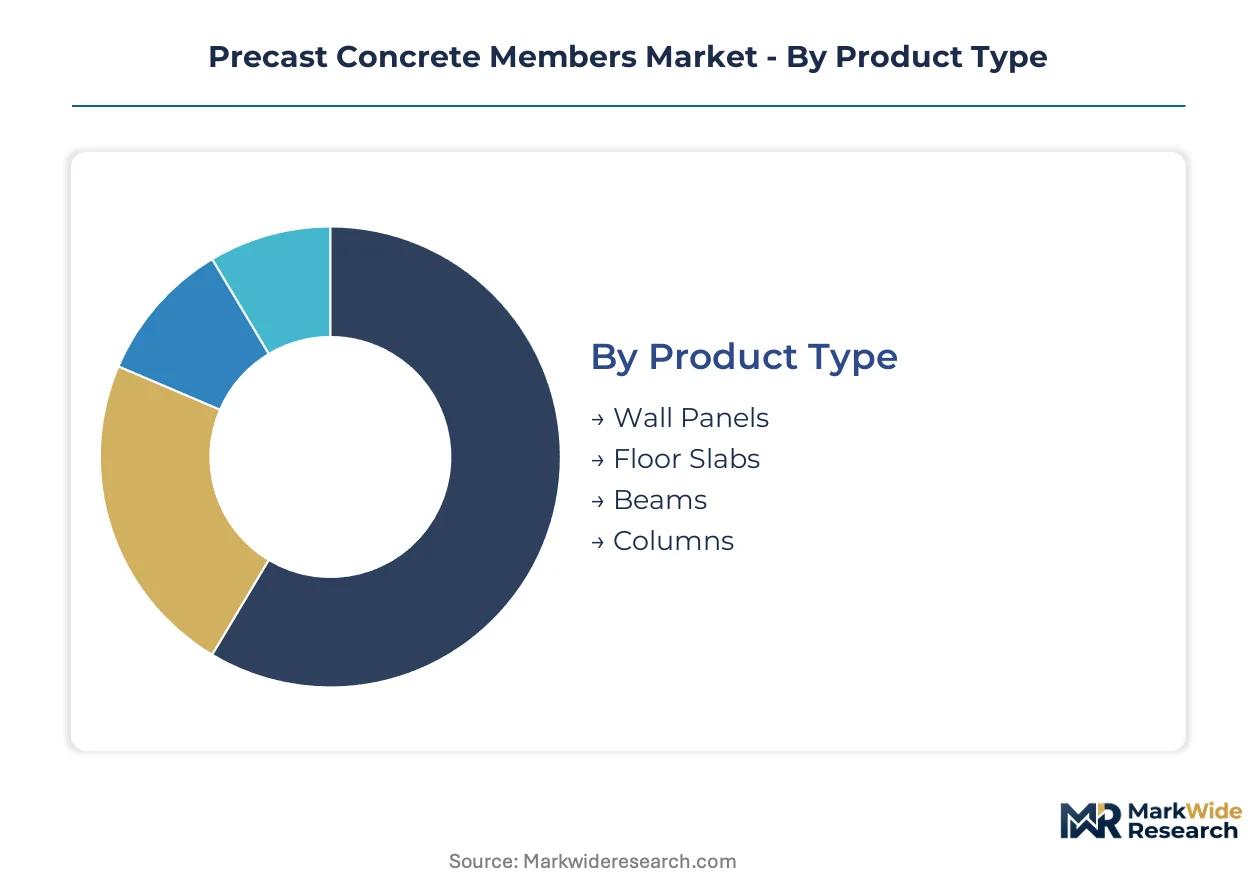
Precast concrete manufacturers configure production lines around element geometry and curing specifications that dictate mold inventory, transport logistics, and crane scheduling. Segmentation reveals where capital deployment concentrates and which technical capabilities unlock premium pricing tiers.
Product Type:
Structural function and repetition frequency differentiate procurement economics across precast categories.
- Wall Panels:Factory-cast vertical envelopes integrate insulation layers and window openings under controlled conditions. Warehouse and logistics facility builders in the United States specify tilt-up panel packages that compress envelope construction schedules by 50% versus masonry alternatives.
- Floor Slabs:Hollow-core and double-tee configurations dominate multi-story residential construction in India and China where housing delivery mandates favor repetitive span solutions. Standardized depths from 150mm to 400mm cover most commercial and residential load requirements without custom engineering.
- Beams:Prestressed I-sections and L-sections transfer vertical loads in parking structures and industrial frames. German and Dutch infrastructure contractors specify carbon-optimized profiles that reduce embodied carbon for EU Green Deal compliance.
- Columns:Square, round, and rectangular cross-sections serve as primary vertical supports in moment-resisting frames. High-rise residential towers in Turkey and Japan increasingly specify hybrid columns with fiber-reinforced polymer rebar for seismic performance.
Floor slabs lead volumes today; wall panels are gaining share fastest.
Installation Method:
Site labor availability and crane capacity constraints determine which assembly approaches dominate regional markets.
- Pre-Assembly:Factory integration of MEP routing and architectural finishes reduces field labor requirements. Scandinavian contractors specify fully outfitted bathroom and utility pods that ship complete to compressed urban sites.
- On-Site Assembly:Individual elements arrive sequenced for crane placement and immediate connection. Indian affordable housing projects under PMAY-Urban rely on this method where factory density remains insufficient for full modular delivery.
- Modular Construction:Volumetric units stack into complete building sections with minimal field finishing. British and Australian developers specify modular hotel and student housing configurations that cut construction programs by 40%.
- Tilt-Up:Site-cast panels lifted into vertical position eliminate transport radius constraints for large envelope areas. US distribution center builders favor this method for single-story footprints exceeding 10,000 square meters.
On-site assembly dominates current project counts; modular construction is climbing the fastest as factory capacity expands.
End User:
Project scale and specification authority concentration create divergent margin profiles across buyer categories.
- Commercial Buildings:Office and retail developers specify architectural precast with exposed aggregate and form liner finishes. French and German procurement teams now require Environmental Product Declarations for structural elements under national carbon budgets.
- Residential Structures:Multi-story housing shortages in India and China drive repetitive floor slab demand with compressed design cycles. Chinese developers under dual carbon goals increasingly specify geopolymer precast for mid-rise towers.
- Infrastructure Projects:Bridge girders, culverts, and tunnel segments demand high-durability formulations for 100-year service life. US state DOTs specify polymer-modified concrete for marine exposure zones under EPA corrosion guidelines.
- Industrial Facilities:Manufacturing plants and data centers require heavy-load floor slabs with abrasion-resistant surfaces. German automotive facilities specify steel fiber-reinforced slabs that eliminate traditional rebar congestion.
Residential structures anchor volume today; infrastructure projects show the steepest expansion trajectory as public procurement rules tighten.
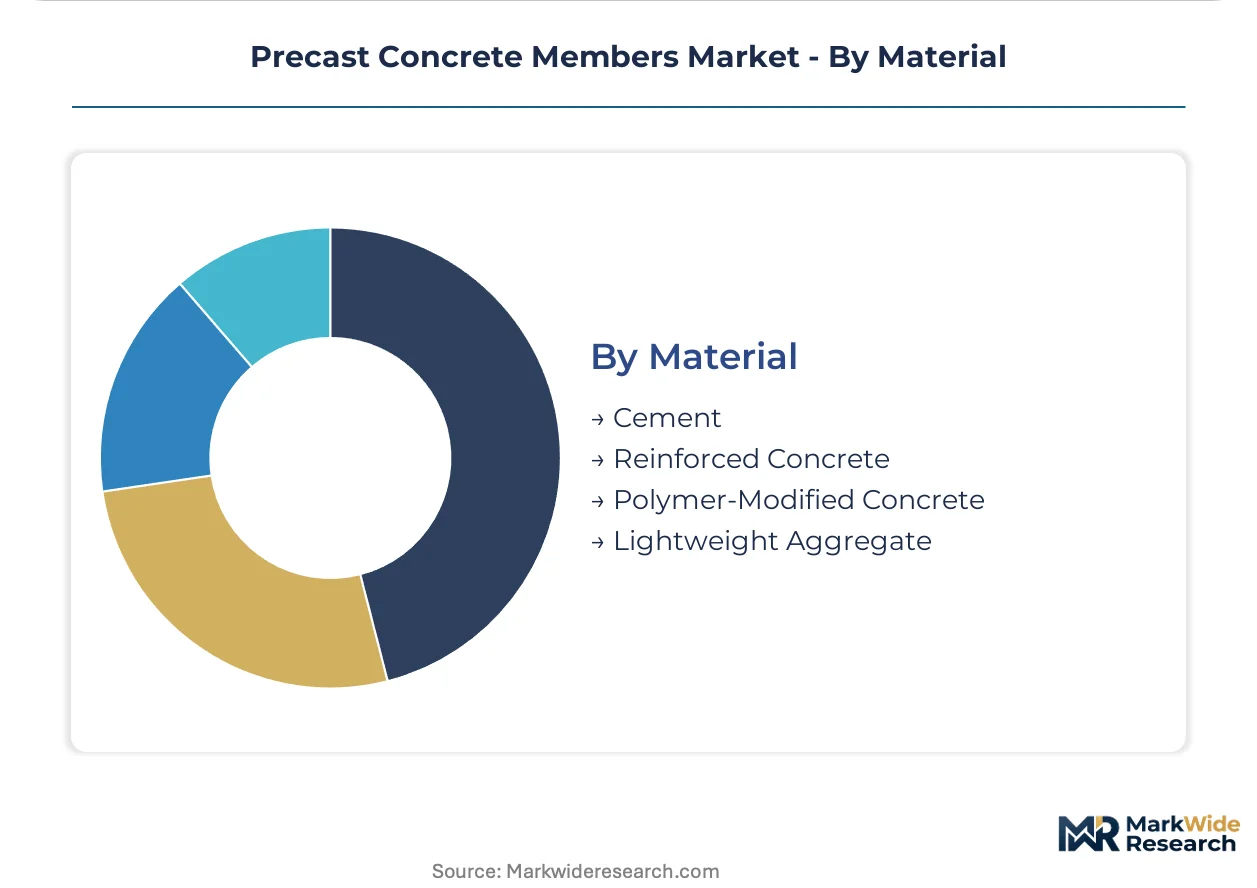
Material:
Binders and reinforcement selection determine compliance eligibility for carbon-accounting tenders and exposure classifications.
- Cement:Portland cement remains the baseline binder for standard structural grades despite clinker price volatility. Indian manufacturers under BIS certification maintain parallel testing protocols for domestic and export-grade concrete.
- Reinforced Concrete:Steel rebar and prestressing strand provide tensile capacity for spanning elements. Coastal infrastructure in the United States faces service life limitations from carbon steel corrosion, driving specification of stainless alternatives.
- Polymer-Modified Concrete:Latex and epoxy additions enhance bond strength and chemical resistance for aggressive environments. Scandinavian bridge tenders specify these formulations for de-icing salt exposure under strict national durability standards.
- Lightweight Aggregate:Expanded clay and shale reduce dead loads for long-span applications and seismic zones. Japanese high-rise construction specifies these aggregates to minimize foundation demands on dense urban sites.
Reinforced concrete dominates installed base today; polymer-modified concrete is expanding most quickly in corrosion-critical infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precast concrete manufacturing originated in Nordic countries during the 1950s as a response to labor shortages and harsh construction seasons, then scaled through post-war European reconstruction before diffusing to North American and Asian markets. The industry's geographic footprint now tracks urbanization velocity, infrastructure renewal cycles, and industrialized construction policy adoption.
China
Multi-story residential towers and high-speed rail corridors absorb the majority of domestic precast capacity. The Ministry of Ecology and Environment enforces dual carbon goals that tighten clinker-to-cement ratios in structural concrete. Yangtze River Delta manufacturers around Shanghai supply geopolymer precast to mid-rise developments under municipal green building mandates.
United States
Warehouse and logistics facility construction drives tilt-up panel demand as e-commerce fulfillment networks expand. EPA construction-material emission guidelines pressure state DOTs to specify lower-carbon bridge girders. Texas and Florida fabricators cluster along interstate corridors to serve distribution center builds within economic transport radii.
Germany
Carbon-optimized beam profiles and modular residential systems dominate procurement as builders chase EU Green Deal compliance. The national building energy code requires Environmental Product Declarations for structural elements in public tenders. Bavarian and North Rhine-Westphalian plants supply prefabricated floor slabs to dense urban infill projects in Munich and Cologne.
India
Housing shortages under PMAY-Urban and Smart Cities Mission timelines favor factory-cast wall panels for affordable unit delivery. BIS certification standards for structural concrete mandate parallel testing protocols for domestic and export-grade production. Gujarat and Maharashtra fabricators near Ahmedabad and Mumbai serve rapid-transit and residential tower contracts.
Japan
Seismic-resistant hybrid columns with fiber-reinforced polymer rebar address building code requirements for high-rise resilience. METI industrial policy supports prefabrication adoption to offset construction labor decline. Kanto region plants around Tokyo supply self-compacting concrete systems for residential towers and commercial retrofits.
Precast Concrete Members Market Competitive Landscape
Premium-margin players sit above commodity-margin players across carbon-certification and digital-fabrication capabilities, creating a tiered structure where low-carbon formulation leaders capture public infrastructure tenders while undifferentiated regional fabricators compete on transport-radius convenience. The vendor base spans integrated cement-to-precast conglomerates, standalone element specialists, and contractor-captive fabrication units. Three archetypes dominate: multinational materials groups with captive supply chains, regional density players optimizing logistics networks, and technology-forward specialists commercializing digital design-to-delivery platforms. Competitive moves concentrate on backward integration into cement and aggregate supply, plus capacity expansion into high-growth urban corridors.
Among integrated materials groups, Holcim, CEMEX, and CRH occupy positions spanning multiple continents and product categories. Holcim exemplifies the captive-supply archetype through cement-to-precast chain control. CEMEX represents technology-forward positioning with digital fabrication platforms compressing design-to-delivery cycles. CRH anchors the regional-density strategy through manufacturing footprint optimization. These three structures illustrate how scale, technology, and logistics each carve defensible margin positions.
| Leading Market Players |
|---|
| Holcim |
| CEMEX |
| CRH |
| Boral Limited |
| Forterra |
| Oldcastle Infrastructure |
| Bouygues Construction |
| HeidelbergCement |
| Taisei Corporation |
| Others |
Pricing and Supply Chain Analysis
Clinker price indices from key producing regions transmit volatility directly through precast concrete supply chains, compressing margins for uncertified producers while rewarding integrated manufacturers with captive cement supply. This cost cascade stratifies pricing tiers around carbon-certification status and transport-radius convenience.
Pricing Analysis
Project-based contract pricing dominates precast procurement, with three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on Environmental Product Declaration certification and geographic delivery radius, with EU Green Deal compliance commanding substantial premiums. Cost compression in standard-grade segments is intensifying because Portland cement price volatility transmits directly to uncertified producers. Affordable housing developers under India's PMAY-Urban exhibit highest price sensitivity, while German infrastructure contractors under national carbon budgets show lowest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with Chinese clinker production and Indian steel rebar supply, exposing downstream fabricators to energy-cost shocks and trade-policy shifts. Manufacturing draws from cement kilns in China, India, and Germany, with reinforcement steel sourced from India, Turkey, and South Korea. Tariff exposure on steel imports threatens margin stability for coastal fabricators serving marine infrastructure. Distribution runs through direct-to-developer digital platforms and traditional contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precast concrete offers margin-expansion potential as low-carbon formulation premiums widen and digital fabrication compresses design-to-delivery overhead. Geopolymer binder adoption and carbon-capture curing technologies unlock new pricing tiers.
For Market Incumbents: Deepen backward integration into cement and aggregate supply to insulate margins from clinker price volatility. Expand manufacturing density in India's Gujarat and Maharashtra corridors to capture Smart Cities Mission demand. Invest in EN 206 and BIS certification concurrency to defend cross-border project access against emerging regional specialists. For New Entrants and Emerging Players: EU Green Deal embodied-carbon benchmarks in Germany, France, and the Netherlands open a window for geopolymer precast specialists to capture public infrastructure tenders. Target Scandinavian markets with strict national carbon budgets where alkali-activated binder expertise commands premium positioning. Deploy direct-to-developer digital platforms to bypass entrenched distributor networks and compress quoting cycles. For Investors and Strategic Acquirers: Consolidation pressure builds where regional fabricators lack carbon-certification capabilities and face stranded capacity under tightening procurement rules. Five-to-ten-year viability favors technology-forward specialists with digital fabrication platforms and low-carbon formulation pipelines. Watch for mineralization technology commercialization as inflection indicator for premium-tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cement Supply | Captive clinker access insulates Holcim and CEMEX from energy-cost volatility across project timelines. |
| Carbon-Capture Curing Deployment | Mineralization technologies sequester CO2 during production for EU Green Deal-compliant infrastructure tenders. |
| Digital Fabrication Platform Launch | CEMEX's design-to-delivery portals compress quoting cycles for complex geometries in commercial development. |
| Geopolymer Formulation Scale-Up | Alkali-activated binders cut process emissions by 60-80% for Scandinavian markets with strict carbon budgets. |
| Regional Manufacturing Expansion | CRH's density strategy reduces transport-driven breakage for just-in-site delivery within 200-kilometer radii. |
Research Methodology
Coverage spans China, India, Germany, the United States, and Japan, with primary inputs from each market cluster. The analysis combines interviews with precast plant managers, cement procurement leads at integrated manufacturers, construction project developers, and structural engineering consultants with secondary validation from BIS certification records, EN 206 compliance databases, EPA construction-material guidelines, and EU Green Deal implementation reports. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Rate-of-change decomposition across the analysis window isolates volume drivers by product type, installation method, end-user vertical, and material formulation. The framework models hollow-core floor slab penetration in multi-story residential construction, tilt-up panel adoption in US logistics facilities, and geopolymer precast share in EU public infrastructure. CAGRs derive from segment-level growth rate blending and cross-validation against cement consumption trends and construction output indices.
Revisions become necessary when clinker supply disruptions, regulatory convergence between embodied-carbon accounting and structural standards, or breakthroughs in alternative binder chemistry materialize. Forecasts reflect documented assumptions about policy enforcement timelines and technology adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Roof Cladding Market
Building & Construction Materials
Vegetal Concrete Market
Building & Construction Materials
India Pipe Fabrication Market
Building & Construction Materials
Building and Construction Plastic Fasteners Market
Building & Construction Materials
Plastic Decking Market
Building & Construction Materials
North America Rainscreen Cladding Market
Building & Construction Materials
Residential and Commercial Smart Glass Market
Building & Construction Materials
Europe Gypsum Board Market
Building & Construction Materials
Architectural Membrane Market
Building & Construction Materials
Thin Wall Mould Market
Building & Construction Materials
Global Fiber Cement Board Market
Building & Construction Materials
Autoclave Aerated Concrete Market
Building & Construction Materials
Liquid Applied Roofing Market
Building & Construction Materials
Global Aluminum Cladding Panels Market
Building & Construction Materials
US Plywood Market
Building & Construction Materials
Europe Timber Construction Connectors Market