
 Prestressed Concrete Market | 2026-2036
Prestressed Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Prestressed Concrete Market Analysis
ASTM C823 inspection qualification cycles is collapsing the vendor pool for critical infrastructure contracts, pushing smaller precasters out of contention for state-funded bridge work. CRH leverages its vertically integrated cement-to-precast network across North America to sustain bid competitiveness on large DOT projects. Holcim anchors European supply through its certified precast subsidiary network, while CEMEX competes aggressively in Latin American infrastructure tenders with regionally manufactured post-tensioned girders.
Prestressed concrete is concrete into which internal compressive stresses have been introduced by tensioned steel tendons before or after casting, typically achieving concrete strengths of 4,000 to 6,000 psi to counteract service load tensile stresses. Its primary purpose is to span longer distances with thinner sections while reducing material volume in bridges, buildings, and parking structures. Post-tensioned systems dominate bridge applications due to their adaptability to curved alignments and longer span capabilities, while pre-tensioned products occupy standardized highway girder manufacturing where economies of scale concentrate margin pools. Infrastructure end-use is pulling the fastest growth as federal and state replacement programs accelerate procurement timelines.
FHWA bridge inspection standards, AASHTO LRFD specifications, and OSHA fall protection mandates collectively shape product certification requirements and contractor eligibility for public sector work. The EU Construction Products Regulation and EN 13369 precast concrete standards govern market access across European member states, with CE marking enforcement intensifying for structural elements. Stakeholders must monitor evolving DOT asset management plans and tightening embodied carbon regulations to align capacity investments with procurement windows.
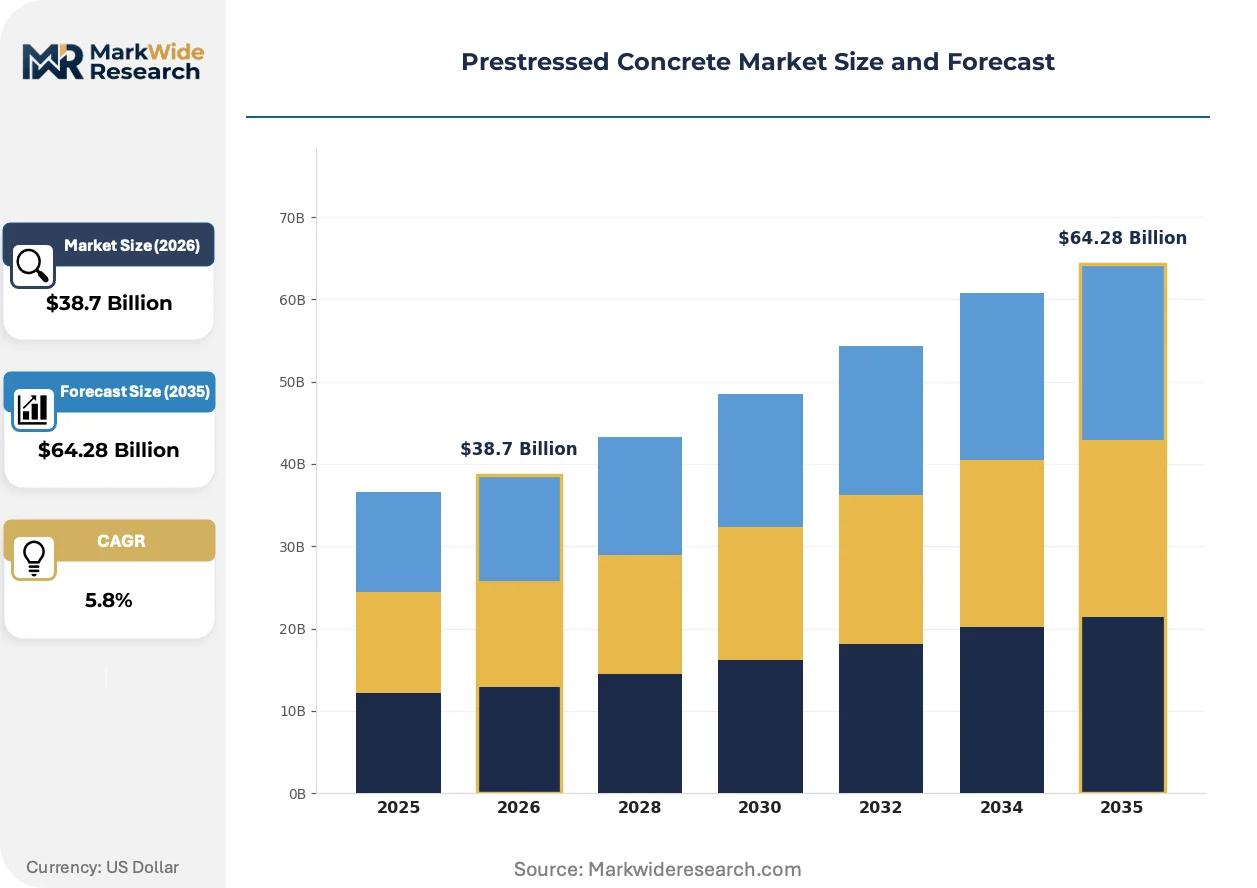
Market Dynamics
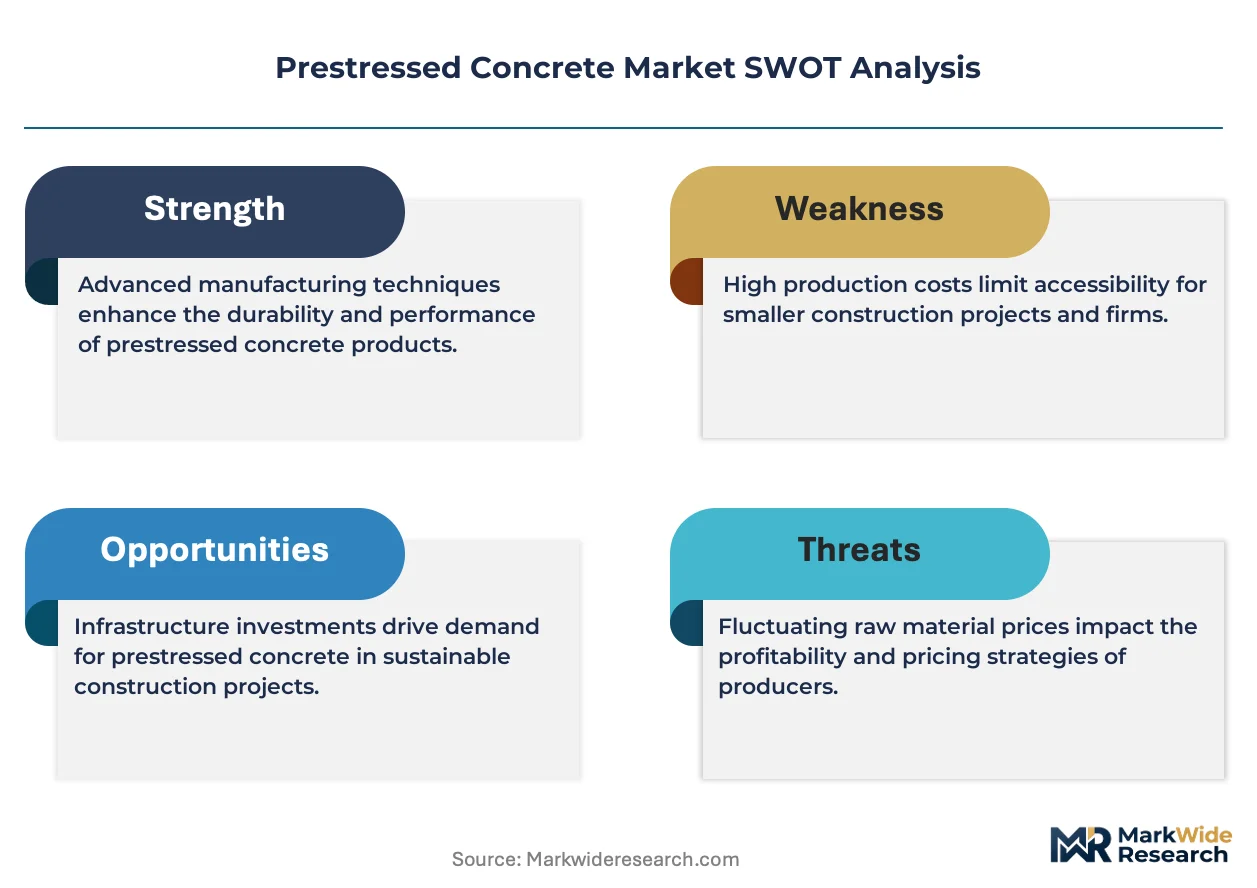
FHWA bridge inspection standards and tightening CE marking requirements under the EU Construction Products Regulation are compressing the qualified vendor pool for public infrastructure contracts, forcing capacity consolidation among precasters capable of meeting multi-jurisdictional certification demands.
Growth Catalysts
- US federal bridge replacement programs:State DOTs are accelerating procurement timelines for post-tensioned systems as aging structure inventories trigger mandatory replacement schedules under federal asset management mandates.
- REACH-compliant low-carbon cement formulations:European precasters adopting alternative binder systems are securing preferential positioning on public tenders with embodied carbon scoring criteria.
- High-speed rail expansion in China:Multi-billion-yuan procurement programs for urban transit viaducts are concentrating demand for pre-tensioned box girders with standardized span configurations.
Market Restraints
- High-strength steel tendon volatility:Post-tensioning strand costs fluctuate with scrap metal indices and electric arc furnace capacity, compressing margin predictability for fixed-price DOT contracts.
- Regional supply concentration:North American precast girder manufacturing clusters in the Gulf Coast and Midwest create logistics cost penalties for coastal infrastructure projects.
- Carbon fiber composite substitution:Bridge designers in corrosive environments increasingly specify CFRP prestressing for lifecycle durability, threatening conventional steel tendon volumes in marine applications.
Strategic Opportunities
- India National Infrastructure Pipeline:Greenfield expressway construction and dedicated freight corridors offer first-mover positioning for precasters establishing domestic girder fabrication capacity.
- OSHA-compliant modular formwork systems:Automated self-climbing platforms reduce fall exposure during bridge deck construction, opening premium pricing tiers for safety-integrated post-tensioning packages.
- EU Taxonomy-aligned green bonds:Sustainable finance eligibility criteria for low-carbon concrete are channeling institutional capital toward certified precast producers with verified Environmental Product Declarations.
Industry Challenges
- Post-tensioning specialist certification gaps:AASHTO and PTIB qualification requirements for tendon installation supervision exceed available trained inspector capacity, delaying project mobilization.
- Multi-jurisdictional CE marking complexity:Precasters serving both EU and UK markets face diverging conformity assessment procedures following Brexit regulatory divergence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prestressed Concrete Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-Tensioned, Post-Tensioned, Hybrid, High-Strength End User: Residential, Commercial, Industrial, Infrastructure Application: Bridges, Buildings, Parking Structures, Stadiums Material: Cement, Steel, Fibers, Admixtures |
| Companies Covered | CRH, Oldcastle Infrastructure, Holcim, Forterra, Spancrete, CEMEX, Tindall Corporation, Boral Precast, HeidelbergCement, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prestressed Concrete Market Emerging Trajectories
Digital fabrication and low-carbon material science are restructuring competitive advantage in prestressed concrete, rewarding precasters with integrated design-to-production capabilities and verified sustainability credentials.
Ultra-high performance concrete (UHPC) is displacing conventional precast elements in bridge joint and connection details. State DOTs in Texas and Virginia are specifying UHPC closure pours for accelerated bridge construction, exploiting its 18,000-plus psi compressive strength to eliminate field-casting delays. The material is displacing epoxy-coated rebar and grouted sleeve systems in high-seismic zones where ductility demands exceed standard concrete capacity.
The EU Construction Products Regulation's intensified CE marking enforcement for structural precast elements is forcing third-party certification upgrades. Notified body assessment timelines have extended from 12 to 24 weeks for new product lines, compressing launch windows for innovative girder profiles. German and Dutch precasters are responding by consolidating testing portfolios across product families to amortize compliance costs.
Design-build and public-private partnership delivery models are concentrating procurement authority among fewer buyers with consolidated technical specifications. Turnkey bridge contractors in Florida and California now bundle post-tensioning design, supply, and installation into single-source packages, displacing traditional bid-item separation between precast supply and specialty subcontracting. This concentration is most visible in urban viaduct projects where alignment complexity demands integrated design liability.
Prestressed Concrete Market Segmentation
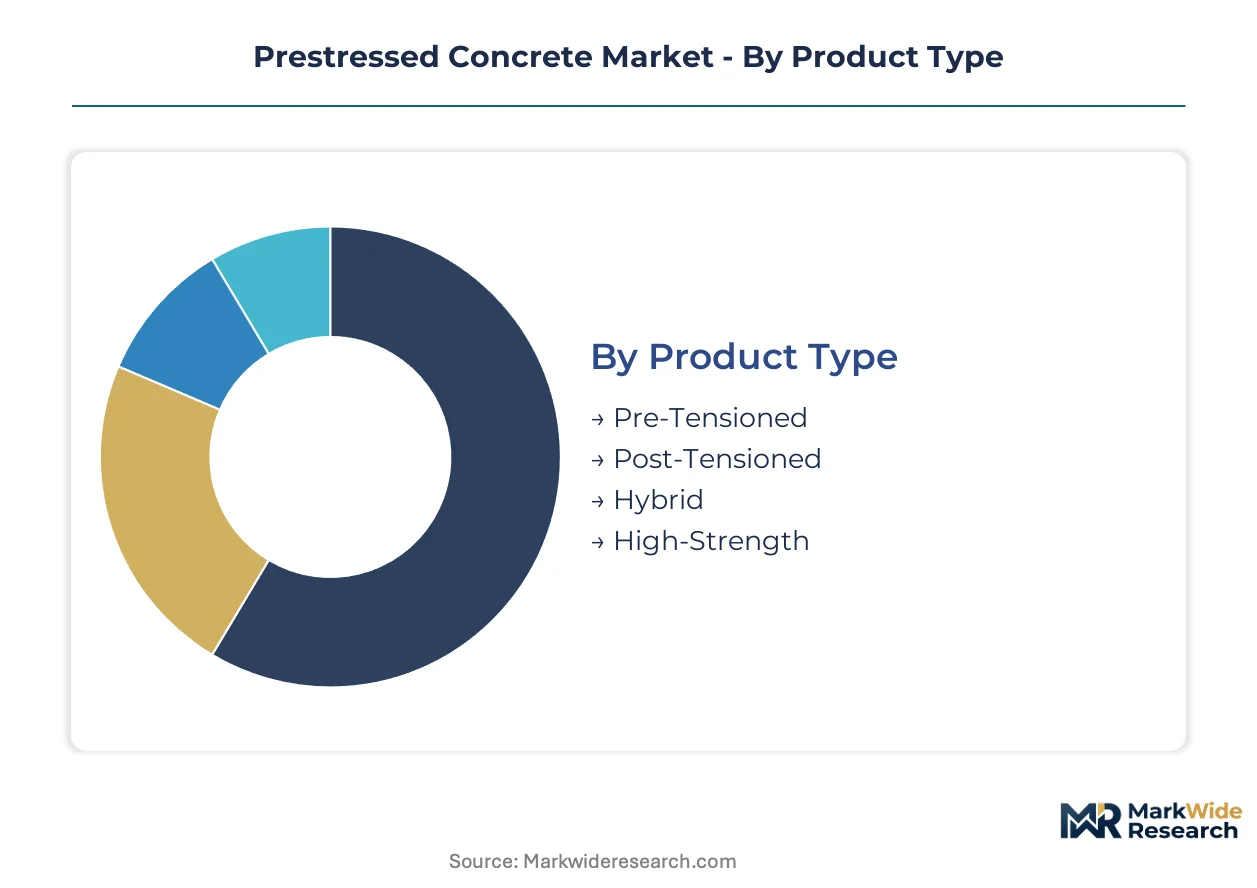
Prestressed concrete procurement splits across technical specifications that determine certification requirements and installation protocols. Regulatory frameworks from FHWA, AASHTO, and EU Construction Products Regulation enforce distinct compliance pathways for each segment category.
Product Type:
CE marking intensity and PTIB qualification tiers separate segments by installation complexity and inspector certification demands.
- Post-Tensioned:Tendons are tensioned after concrete curing using hydraulic jacks, enabling curved bridge alignments and span lengths exceeding 150 feet. State DOTs in Texas and California specify post-tensioned box girders for urban viaduct replacement programs where geometric constraints preclude standard shapes. FHWA mandates specialized inspection protocols that compress the qualified contractor pool.
- Pre-Tensioned:Steel strands are tensioned against fixed abutments before concrete placement, then released to transfer compressive stress. Standardized highway girder plants in the US Midwest and Gulf Coast exploit economies of scale for repetitive span configurations on interstate widening projects. AASHTO LRFD specifications govern strand pattern and release strength requirements.
- Hybrid:Combines pre-tensioned plant production with field post-tensioning for complex span arrangements.
- High-Strength:Achieves compressive strengths above 8,000 psi through optimized mix designs and steam curing protocols.
Post-Tensioned handles the majority of throughput; High-Strength is expanding most quickly on share.
End User:
Project scale and procurement authority concentration determine margin structure and contract terms across customer categories.
- Infrastructure:Federal and state-funded bridge, highway, and rail projects with multi-year procurement cycles and bonded contract requirements. US DOTs command 80% of North American prestressed concrete volume through design-build and public-private partnership vehicles. OSHA fall protection mandates and FHWA inspection standards shape contractor eligibility.
- Commercial:Office towers, retail centers, and mixed-use developments specifying post-tensioned floor plates for column-free spans. Developers in Miami and Los Angeles prioritize rapid construction cycles where post-tensioned slabs reduce formwork duration by 30% versus conventional reinforced concrete.
- Industrial:Manufacturing facilities and warehouses requiring heavy-load floor systems with minimal maintenance downtime.
- Residential:Mid-rise apartment buildings and condominiums using precast plank systems for repetitive bay configurations.
Infrastructure commands absolute volume leadership; Commercial is climbing the fastest as urban density intensifies.
Application:
Structural performance requirements and exposure conditions dictate material specification and durability design life.
- Bridges:Decks, girders, and segmental box sections subjected to cyclic loading and de-icing chemical exposure. State DOTs in Virginia and Florida specify UHPC closure pours for accelerated bridge construction, exploiting 18,000-plus psi compressive strength to eliminate field-casting delays. AASHTO load rating protocols govern design life assumptions.
- Buildings:Floor systems, transfer beams, and structural frames where span-to-depth ratios determine rentable efficiency. High-rise developers in Chicago and Seattle specify post-tensioned flat plates to maximize ceiling heights within zoning envelope constraints.
- Parking Structures:Long-span ramp and deck systems with carbonation and chloride exposure concerns.
- Stadiums:Cantilevered roof and seating bowl elements requiring dynamic load resistance.
Bridges absorb the dominant share of specialized capacity; Buildings is gaining share fastest as urban core construction accelerates.
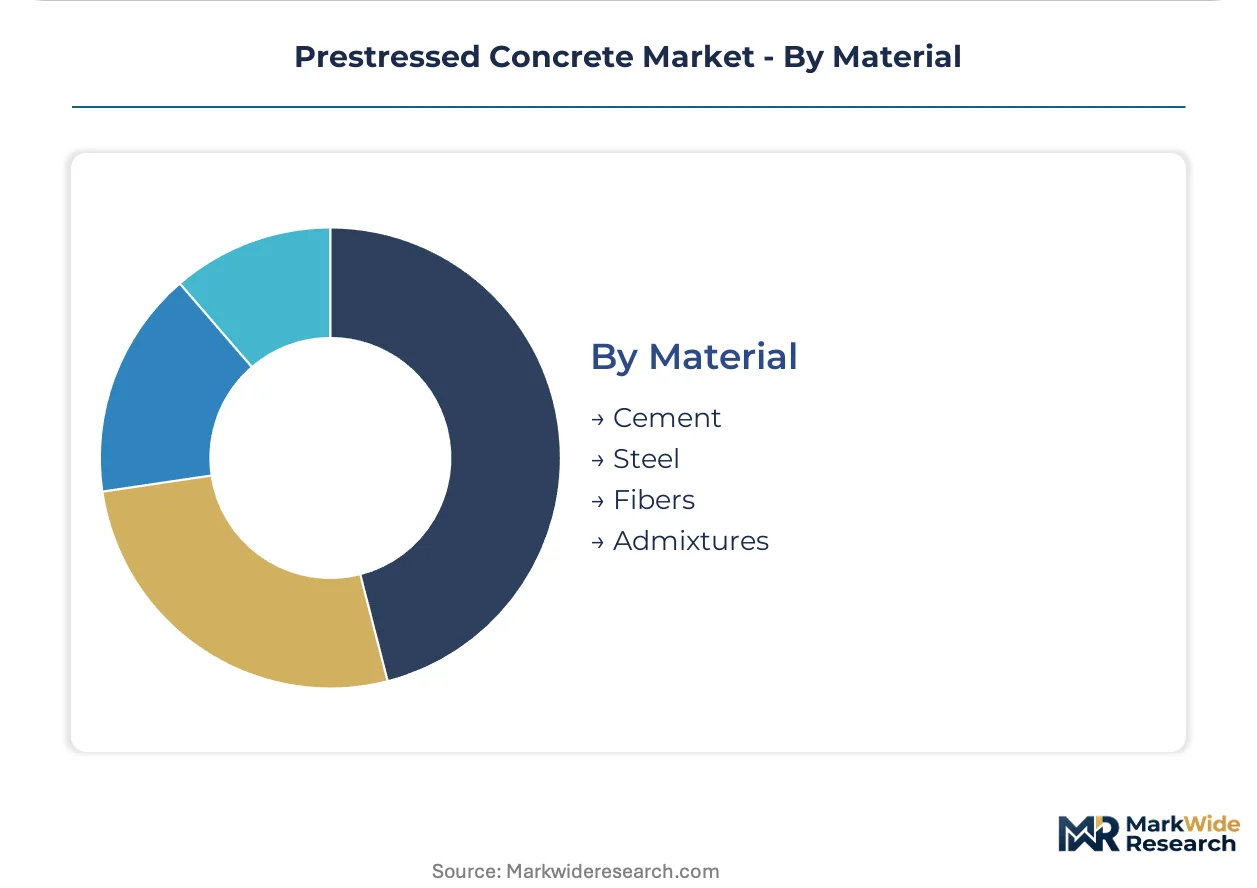
Material:
Embodied carbon scoring and REACH compliance are restructuring sourcing priorities across constituent materials.
- Cement:Portland and blended hydraulic cements comprising 60-70% of concrete mass by volume. European precasters adopting alternative binder systems with calcined clays and ground granulated blast furnace slag are securing preferential positioning on public tenders with carbon scoring criteria under EU Taxonomy alignment.
- Steel:Prestressing strand, wire, and bar reinforcement providing tensile capacity. High-strength steel tendon costs fluctuate with scrap metal indices and electric arc furnace capacity, compressing margin predictability for fixed-price DOT contracts.
- Fibers:Steel and synthetic microfibers controlling plastic shrinkage and macrofibers replacing nominal reinforcement.
- Admixtures:High-range water reducers, corrosion inhibitors, and air-entraining agents modifying fresh and hardened properties.
Cement dominates mass and cost exposure; Steel faces the steepest price volatility pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State transportation departments and national infrastructure agencies concentrate procurement authority for prestressed concrete, with bridge replacement programs and high-speed rail corridors driving geographic demand patterns across four major markets.
United States
State DOTs in Texas and California dominate post-tensioned girder procurement for urban viaduct replacement programs. FHWA bridge inspection standards compress the qualified contractor pool for federal-aid projects. Manufacturing clusters in the Gulf Coast and Midwest supply standardized pre-tensioned highway girders for interstate widening.
China
Multi-billion-yuan procurement programs for high-speed rail viaducts concentrate demand for pre-tensioned box girders with standardized span configurations. MIIT industrial standards govern structural precast certification for transportation infrastructure. Manufacturing capacity clusters in the Yangtze River Delta and Pearl River Delta serve national rail expansion timelines.
Germany
Federal transport infrastructure programs drive demand for certified precast bridge elements on autobahn and rail corridor upgrades. EU Construction Products Regulation CE marking requirements intensify third-party certification demands for structural elements. Notified body assessment timelines extend compliance lead times for new product launches.
India
National Infrastructure Pipeline expressway construction and dedicated freight corridors create procurement windows for precast girder fabrication capacity. BIS structural concrete standards and highway authority specifications govern product certification. Industrial corridors in Gujarat and Maharashtra attract greenfield precasting investments.
United Arab Emirates
Mega-project developments and transportation corridor expansions specify post-tensioned structural systems for long-span applications. UAE construction regulators enforce structural product conformity assessment for public infrastructure tenders. Manufacturing facilities in Dubai Industrial City and Abu Dhabi supply domestic and regional export markets.
Prestressed Concrete Market Vendor Landscape
Player mix skews toward vertically integrated building materials conglomerates with captive cement-to-precast networks, compressing margin pools for standalone fabricators on large public contracts. Three strategic archetypes dominate: multinational cement-precast integrators leveraging backward integration into raw materials, regional specialists commanding local DOT relationships, and diversified infrastructure contractors bundling design-build post-tensioning packages. Capacity consolidation and sustainability certification investments represent the dominant competitive moves.
Within the multinational integrator tier, CRH and Holcim occupy positions defined by geographically distributed certified precast subsidiary networks, while CEMEX anchors Latin American market presence. These conglomerates exemplify the scale-driven archetype where captive cement supply and multi-jurisdictional certification portfolios sustain bid competitiveness on state-funded infrastructure programs. Regional specialists including Tindall Corporation and Spancrete represent the relationship-driven tier, concentrating manufacturing assets near major DOT procurement clusters and cultivating long-term agency partnerships. The competitive dynamic favors players with verified Environmental Product Declarations and CE marking capabilities as public tenders embed embodied carbon scoring and multi-standard compliance requirements.
| Leading Market Players |
|---|
| CRH |
| Oldcastle Infrastructure |
| Holcim |
| Forterra |
| Spancrete |
| CEMEX |
| Tindall Corporation |
| Boral Precast |
| HeidelbergCement |
| Others |
Supply Flow & Price Mechanics
Carbon fiber composite substitution for steel tendons in marine bridge applications is simultaneously redrawing supplier geography toward specialized CFRP manufacturers and compressing pricing power for conventional post-tensioning strand producers on corrosion-critical contracts.
Pricing Analysis
Cost-plus contracts with scrap metal indexation dominate fixed-price DOT agreements, exposing precaster margins to electric arc furnace capacity swings and ferrous scrap volatility. Price differentiation separates PTIB-certified installation packages from standard supply-only bids, with turnkey design-build premiums widening as project complexity increases. Pricing pressure intensifies in standardized pre-tensioned highway girders where Gulf Coast and Midwest manufacturing clusters face coastal logistics penalties. State transportation departments exhibit highest price sensitivity on repetitive span configurations, while urban viaduct projects with geometric constraints accept post-tensioning premiums for curved alignment capability.
Supply Chain Analysis
Just-in-time delivery preferences for post-tensioning strand clash with strategic stockpiling of high-strength steel by major precasters hedging against scrap index volatility. Manufacturing concentration in the United States, China, and Germany anchors global prestressed concrete supply, with the Yangtze River Delta and Pearl River Delta serving China's rail expansion timelines. Raw material dependencies center on Portland cement, prestressing strand, and corrosion inhibitors, with REACH-compliant low-carbon binder systems gaining procurement preference in European tenders. Single-source vulnerability in electric arc furnace capacity for specialty strand grades creates supply risk during infrastructure procurement surges. Distribution runs through design-build contractors bundling post-tensioning design, supply, and installation into consolidated procurement packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prestressed concrete sits in early-cycle expansion as federal bridge replacement programs and high-speed rail procurement waves accelerate adoption beyond historical infrastructure replacement rates.
For Market Incumbents: Consolidate certified precast capacity in DOT procurement clusters to defend against vertically integrated cement-to-precast competitors. Anchor backward integration into low-carbon cement formulations to capture EU Taxonomy-aligned green bond eligibility, while deepening PTIB-qualified inspector training pipelines to overcome specialist certification gaps delaying project mobilization. For New Entrants and Emerging Players: CE marking fast-track investments unlock European public infrastructure access where notified body assessment timelines have extended compliance lead times for established competitors. Target India's National Infrastructure Pipeline expressway construction as the most penetrable geography, leveraging BIS certification pathways and greenfield fabrication partnerships with Gujarat and Maharashtra industrial corridor developers. For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors precasters with verified Environmental Product Declarations and multi-jurisdictional certification portfolios. Long-term viability hinges on sustainability credentialing as embodied carbon scoring embeds in public tender evaluation. Watch DOT asset management plan acceleration as the signal indicating procurement window expansion or contraction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Carbon Cement | Captures EU Taxonomy green bond eligibility and REACH-compliant tender positioning. |
| PTIB Inspector Certification Pipeline Expansion | Resolves specialist qualification gaps delaying post-tensioning project mobilization. |
| CE Marking Consolidation Across Product Families | Amortizes notified body assessment costs as EU enforcement intensifies. |
| Design-Build Bundle Packaging | Aligns with Florida and California turnkey procurement concentration for urban viaducts. |
| UHPC Joint Detail Specification Capture | Secures accelerated bridge construction preference in Texas and Virginia DOT programs. |
Methodological Framework
A standing panel of bridge design engineers, state DOT procurement officers, precast plant managers, and post-tensioning specialty contractors provided ongoing calibration across primary interview cycles. Secondary validation drew from FHWA bridge inventory databases, AASHTO LRFD specification updates, EU Construction Products Regulation guidance documents, and MIIT industrial standards filings. Bottom-up project pipeline tracking and top-down infrastructure budget appropriation analysis were triangulated to reconcile volume estimates.
Consistency checks against external benchmarks validated segment-level outputs across the projection horizon. The analytical framework modeled product type, end user category, application, and material composition dimensions alongside regional regulatory cluster variations. CAGRs were derived from infrastructure spending trajectory alignment with precast capacity expansion announcements. Forecast inputs incorporated DOT asset management plan replacement schedules and high-speed rail procurement timeline disclosures.
Underlying assumptions cover sustained federal funding authorization, stable scrap metal index ranges, and CE marking enforcement continuity, with deviation risk concentrated in steel tendon cost volatility and multi-jurisdictional certification divergence post-Brexit. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Metal Structural Insulation Panels Market
Structural Engineering
Europe Facade Market
Structural Engineering
Bridge Expansion Joint Market
Structural Engineering
Cold-Formed Steel Market
Structural Engineering
North America Anchors and Grouts Market
Structural Engineering
High Damping Rubber Bearing (HDRB) Market
Structural Engineering
Translucent Concrete Market
Structural Engineering
Fabricated Structural Steel Market
Structural Engineering
Europe Bridge Bearings Market
Structural Engineering
FRP Bridge Market
Structural Engineering
Europe Insulated Concrete Form (ICF) Market
Structural Engineering
Americas Structural Insulated Panel Market
Structural Engineering
Self-Healing Concrete Market
Structural Engineering
Self-Compacting Concrete Market
Structural Engineering
Prestressed High Strength Concrete Pipe Pile Market
Structural Engineering
India Structural Steel Fabrication Market