
 Opening Trim Weatherstrips Market | 2026-2036
Opening Trim Weatherstrips Market Size, Share, and Industry Trends Forecast 2026-2036
Opening Trim Weatherstrips Market Outlook
Aftermarket replacement revenue is rewriting margin economics across the value chain. Toyoda Gosei leverages its polymer compounding expertise to dominate OE supply contracts for Asian automakers. Steele Rubber Products sustains a specialized position in vintage and restoration channels where exact-profile reproduction commands premium positioning. Cooper Standard Automotive anchors North American production through backward integration into extrusion tooling and compound development.
Opening trim weatherstrips are compressible sealing profiles installed along door frames, trunk openings, and hood perimeters, typically manufactured from EPDM rubber, silicone, or thermoplastic elastomer via continuous extrusion with bonded metal carriers for structural retention. Their primary function is to exclude moisture, wind, and airborne particulates while maintaining acoustic isolation between movable and fixed body panels. Rubber formulations occupy the largest material share due to cost-performance balance across temperature extremes, while silicone segments command premium positioning in aerospace and high-performance automotive applications where thermal stability exceeds 200°C. Snap-in and slide-on installation types are gaining share in professional channels as vehicle designs prioritize modular assembly and reduced warranty exposure from adhesive degradation.
EPA fuel economy standards and NHTSA safety regulations in the United States mandate aerodynamic sealing efficiency, directly tightening tolerance requirements for weatherstrip compression set and permanent deformation. ECHA REACH restrictions on phthalate plasticizers and heavy metal stabilizers are forcing compound reformulation across European supply chains, elevating compliance costs for vinyl-dominant producers. Stakeholders must monitor divergence between regional chemical safety frameworks and OEM platform globalization strategies, as misalignment between EPA, ECHA, and MIIT certification timelines risks fragmenting product portfolios and inflating development overhead.
Market Dynamics
EPDM rubber formulations with enhanced UV stabilization are compressing the competitive window for PVC-dominant suppliers as OEMs tighten compression-set tolerances under NHTSA aerodynamic mandates.
Growth Catalysts
- EPA Fuel Economy Standards:Aerodynamic sealing requirements for 2026-2032 model years force automakers to specify lower-permanent-deformation weatherstrips, expanding EPDM adoption at PVC's expense.
- Automotive NVH Engineering:Cabin acoustic isolation targets in electric vehicle platforms demand multi-durometer sealing profiles with bonded metal carriers, creating specification upgrades across door and trunk openings.
- China MIIT Platform Development:New vehicle architecture cycles from domestic OEMs concentrate demand for modular snap-in weatherstrip designs that reduce assembly-line touch time.
Market Restraints
- Petrochemical Feedstock Volatility:Ethylene-propylene diene monomer pricing tracks naphtha and natural gas liquid markets, compressing compounder margins during upstream energy shocks.
- ECHA REACH Compliance Burden:Phthalate plasticizer restrictions and heavy metal stabilizer bans force vinyl-profile producers into costly reformulation cycles, disadvantaging European manufacturing relative to Asian competitors.
- Silicone Substitution Ceiling:Perfluorinated elastomer seals in aerospace thermal management applications above 200°C capture premium positioning that rubber formulations cannot technically match.
Strategic Opportunities
- Indian Automotive Localization:PLI scheme incentives for component manufacturing attract extrusion tooling investment to serve Maruti Suzuki and Hyundai Motor India expansion.
- Aftermarket Digital Channels:VIN-matched weatherstrip configurators on Amazon and RockAuto disintermediate traditional jobber distribution, capturing restoration and collision repair demand.
- EU Green Deal Circular Mandates:End-of-life vehicle recycling targets create pull for thermoplastic elastomer formulations that enable material recovery versus thermoset rubber incineration.
Industry Challenges
- Extrusion Die Engineering Scarcity:Compound flow simulation expertise for multi-cavity profiles with co-extruded metal carriers concentrates among aging toolmakers in Germany and Japan.
- OEM Platform Synchronization:Misaligned EPA, ECHA, and MIIT certification timelines fragment product portfolios, inflating development overhead for global supply contracts.
- Adhesive Bonding Reliability:Warranty exposure from tape-applied weatherstrip detachment in extreme climate zones pushes automakers toward mechanical retention designs requiring retooling investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Opening Trim Weatherstrips Market |
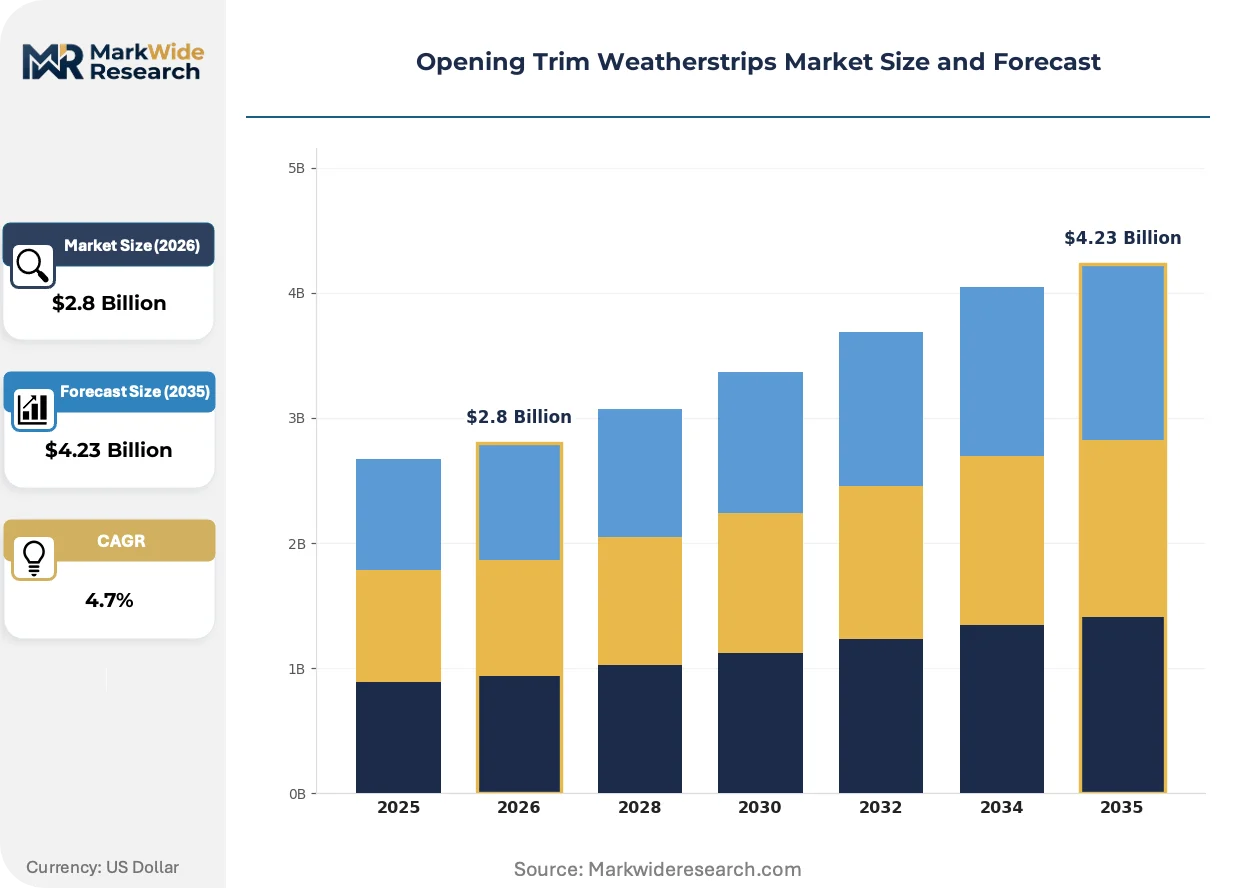
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Rubber, Foam, Silicone, Vinyl Use Case: Residential, Automotive, Commercial, Industrial Type: Adhesive Backed, Snap-In, Slide-On, Pressure Fit Installation Method: DIY, Professional, Pre-Applied, Peel and Stick |
| Companies Covered | Precision, Fairchild Industries, Steele Rubber Products, Toyoda Gosei, Hebei Shida Seal Group, Trim Parts, Cooper Standard Automotive, Hutchinson, Schlegel Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Opening Trim Weatherstrips Market Strategic Shifts
Continuous extrusion processes with in-line laser measurement are tightening dimensional tolerances while digital thread technologies compress new product introduction cycles from concept to production validation.
Co-extruded thermoplastic vulcanizate skins over EPDM sponge cores are migrating from luxury vehicle programs to mass-market electric platforms as automakers seek weight reduction without sacrificing compression-set performance. Hyundai Motor and BYD specify these constructions for door primary seals to offset battery pack mass. The technology is migrating from premium segment exclusivity toward standard equipment on vehicles priced below thirty thousand dollars.
REACH restrictions on phthalate plasticizers and heavy metal stabilizers are forcing compound reformulation across European supply chains, elevating compliance costs for vinyl-dominant producers. ECHA substance of very high concern listings now cover four critical weatherstrip additives previously grandfathered under transitional arrangements. German and French compounders accelerate bio-based plasticizer testing to maintain OEM supply qualifications ahead of 2027 authorization deadlines.
Fleet procurement departments now specify outcome-based sealing performance contracts rather than per-part pricing, transferring compression-set degradation risk to suppliers over seven-year vehicle lifecycles. General Motors and Stellantis pilot these arrangements for high-volume platforms, replacing traditional piece-price negotiations with warranty-cost-sharing mechanisms. North American contract manufacturing organizations invest in accelerated aging test cells to underwrite performance guarantees demanded by these agreements.
Opening Trim Weatherstrips Market Segmentation
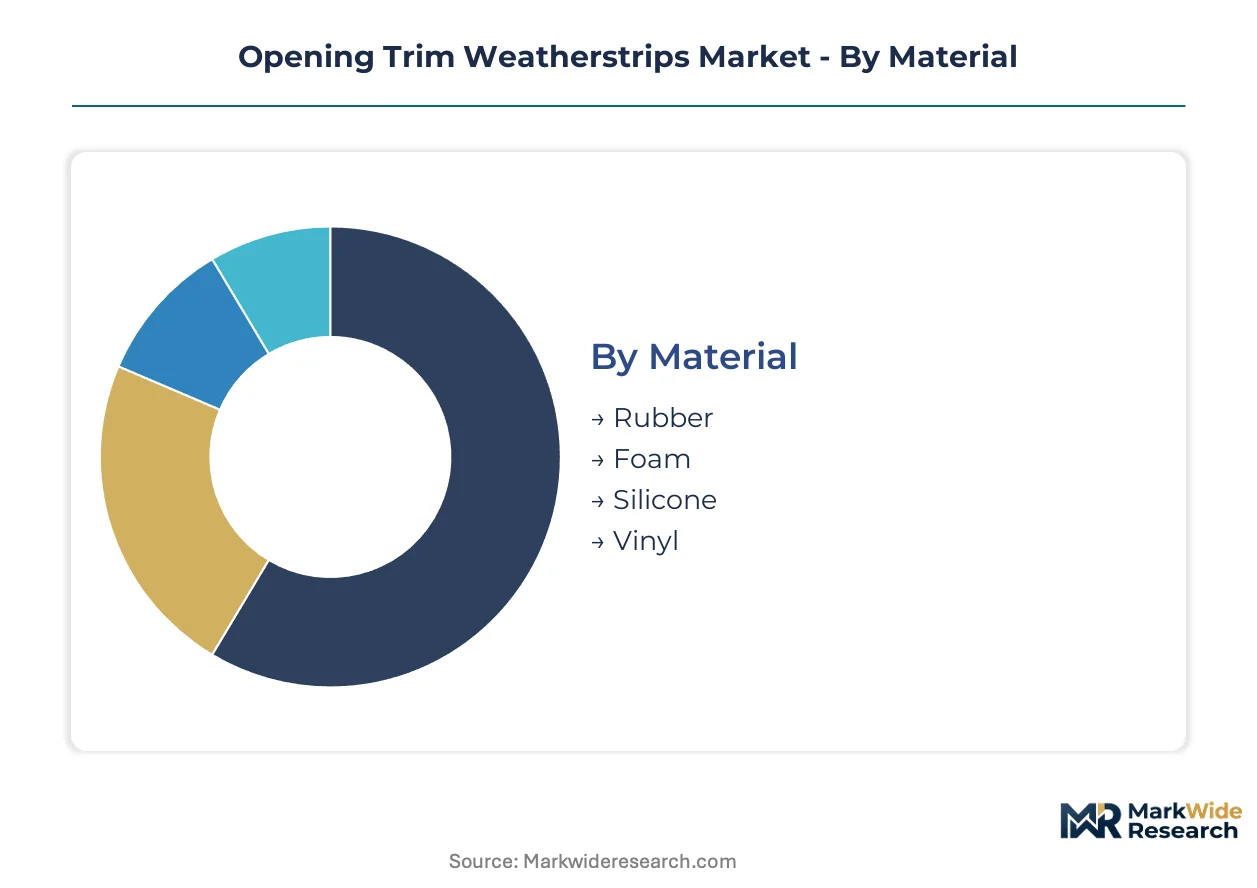
Segmentation in opening trim weatherstrips determines replacement frequency, margin structure, and channel strategy. Material composition dictates thermal performance and regulatory compliance, while installation complexity shapes whether demand flows through retail or professional service networks.
Material:
After-sales service intensity varies dramatically by material chemistry, with rubber formulations requiring the most frequent replacement cycles in exterior automotive exposure.
- Rubber:EPDM compounds dominate exterior automotive sealing with compression-set resistance across temperature extremes from -40°C to 150°C. United States EPA aerodynamic mandates tighten tolerance requirements, forcing automakers toward low-permanent-deformation formulations that exclude moisture and wind while maintaining acoustic isolation.
- Silicone:Perfluorinated elastomer constructions serve aerospace thermal management above 200°C where rubber formulations fail. Germany's ECHA REACH restrictions on phthalate plasticizers accelerate silicone substitution in premium European automotive programs seeking extended service intervals.
- Foam:Open-cell polyurethane cores provide cost-effective sealing in residential window retrofits where compression recovery requirements are modest.
- Vinyl:PVC profiles retain share in budget residential applications despite UV degradation susceptibility and regulatory pressure from heavy metal stabilizer bans.
By volume, rubber leads. By growth pace, silicone is ahead.
Use Case:
Cost tier stratification separates specification-grade automotive contracts from commoditized residential retrofits, with commercial building codes creating mid-tier compliance demand.
- Automotive:OEM primary seals for door frames, trunk openings, and hood perimeters command multi-durometer constructions with bonded metal carriers. China's MIIT platform development concentrates demand for modular snap-in designs that reduce assembly-line touch time at BYD and Hyundai Motor facilities.
- Residential:Window and door retrofits drive aftermarket volume through hardware retail and digital channels where VIN-matched configurators disintermediate traditional distribution.
- Commercial:Building envelope specifications under ASHRAE energy codes mandate air infiltration limits that elevate thermoplastic elastomer adoption over conventional vinyl.
- Industrial:Equipment panel sealing tolerates wider compression-set variance, prioritizing cost over longevity in manufacturing facility applications.
Automotive generates highest revenue per unit. Residential delivers largest absolute volume.
Type:
Volume concentration favors mechanical retention designs as automakers shift warranty exposure away from adhesive degradation in extreme climate zones.
- Snap-In:Modular profiles with co-extruded metal carriers enable rapid assembly-line installation without cure time. United States NHTSA safety regulations and EPA fuel economy standards tighten compression-set tolerances, favoring these constructions for 2026-2032 model year platforms.
- Slide-On:Continuous extrusion with in-line laser measurement ensures dimensional precision for trunk and hood perimeter sealing where gap variance exceeds door frame tolerances.
- Adhesive Backed:Tape-applied formulations face warranty exposure from detachment in thermal cycling, limiting share to interior applications and aftermarket replacement.
- Pressure Fit:Compression-only retention serves temporary or low-cycle applications where installation speed outweighs longevity requirements.
Snap-in dominates new vehicle platforms. Adhesive backed retains aftermarket restoration share.
Installation Method:
Customer type bifurcation separates professional channel specifications from DIY retail, with pre-applied formulations capturing collision repair demand.
- Professional:Certified installer networks specify outcome-based performance contracts with warranty-cost-sharing mechanisms. General Motors and Stellantis pilot these arrangements, transferring compression-set degradation risk to suppliers over seven-year vehicle lifecycles.
- DIY:Consumer retail through Amazon and RockAuto captures restoration demand where exact-profile reproduction commands premium positioning in vintage vehicle channels.
- Pre-Applied:OEM-applied formulations at Tier 1 suppliers reduce dealer installation variance and warranty claims.
- Peel and Stick:Simplified application targets residential retrofit markets where labor cost sensitivity favors minimal tool requirements.
Professional installation commands highest margin per job. DIY delivers broadest geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aftermarket buyers in India and Brazil exhibit acute price elasticity, squeezing margins on commodity EPDM formulations, while German and Japanese OEM procurement teams prioritize compression-set performance over unit cost, insulating premium compounders from margin compression.
United States
Domestic automakers accelerate platform redesigns for 2026-2032 EPA fuel economy compliance, specifying low-permanent-deformation EPDM primary seals. NHTSA safety regulations tighten dimensional tolerances for door and trunk openings. Detroit-area Tier 1 suppliers invest in continuous extrusion lines with in-line laser measurement to underwrite outcome-based performance contracts with General Motors and Stellantis.
Germany
Premium OEMs specify multi-durometer sealing profiles with bonded metal carriers for electric vehicle NVH targets. ECHA REACH restrictions on phthalate plasticizers force compound reformulation ahead of 2027 authorization deadlines. Stuttgart and Munich industrial clusters concentrate extrusion die engineering expertise for co-extruded thermoplastic vulcanizate constructions migrating to mass-market platforms.
China
Domestic OEM platform development under MIIT direction concentrates demand for modular snap-in designs at BYD and Hyundai Motor joint venture facilities. GB standards for vehicle sealing performance elevate specifications for trunk and hood perimeter applications. Yangtze River Delta extrusion houses scale thermoplastic elastomer capacity to serve battery-electric vehicle weight reduction mandates.
Japan
Automotive polymer compounding expertise anchors OE supply relationships with Asian OEMs seeking extended service intervals. METI industrial standards for material recycling create pull for thermoplastic elastomer formulations compatible with end-of-life vehicle recovery. Nagoya-area toolmakers concentrate flow simulation capability for multi-cavity profiles with co-extruded metal carriers.
India
Maruti Suzuki and Hyundai Motor India expansion drives localization demand for extrusion tooling under PLI scheme incentives. BIS certification requirements for automotive sealing components elevate entry barriers for imported profiles. Tamil Nadu and Gujarat manufacturing corridors attract compounder investment to serve replacement cycle growth in passenger vehicle parc expansion.
Opening Trim Weatherstrips Market Competitive Environment
Capability concentration sits with specialized extrusion die engineers and polymer compounders; scale advantage sits with integrated automotive suppliers with captive OEM relationships. The vendor base stratifies across three tiers: multinational Tier 1s with backward integration into compound development, regional specialists dominating aftermarket restoration channels, and emerging Asian fabricators capturing localization contracts. Dominant competitive moves include geographic expansion through joint venture structures and portfolio diversification into thermoplastic elastomer formulations.
Within the multinational Tier 1 tier, Toyoda Gosei and Cooper Standard Automotive exemplify scale-advantaged positions anchored in polymer compounding expertise and extrusion tooling integration. Among restoration channel specialists, Steele Rubber Products occupies a position defined by exact-profile reproduction capability for vintage vehicle applications. Hebei Shida Seal Group represents the emerging Asian fabricator archetype, positioned to capture PLI scheme-driven localization demand in Indian automotive expansion.
| Leading Market Players |
|---|
| Precision |
| Fairchild Industries |
| Steele Rubber Products |
| Toyoda Gosei |
| Hebei Shida Seal Group |
| Trim Parts |
| Cooper Standard Automotive |
| Hutchinson |
| Schlegel Automotive |
| Others |
Value Chain & Pricing Dynamics
Petrochemical feedstock volatility compresses compounder margins during upstream energy shocks, determining both three-tier pricing stratification across premium EPDM formulations and commodity vinyl alternatives and the geographic shape of supply chain concentration in naphtha-adjacent production clusters.
Pricing Analysis
Aftermarket replacement revenue drives lifetime value through seven-year performance contracts that transfer compression-set degradation risk to suppliers. Pricing stratifies across OEM specification-grade, professional installer, and DIY retail tiers, with EPDM formulations commanding premiums for low-permanent-deformation characteristics under EPA aerodynamic mandates. Cost compression in vinyl-dominant segments intensifies because ECHA REACH compliance burdens elevate European manufacturing overhead relative to Asian competitors. Fleet procurement departments exhibit lowest price sensitivity, while restoration channel buyers in India and Brazil demonstrate acute elasticity on commodity formulations.
Supply Chain Analysis
Export-control restrictions on extrusion die engineering software limit flow simulation capability transfers, concentrating precision tooling design among aging specialists in Germany and Japan. Manufacturing draws from China, the United States, and Germany for continuous extrusion capacity, with EPDM sponge cores and co-extruded thermoplastic vulcanizate skins as critical inputs. Single-source vulnerability sits with multi-cavity die engineering expertise concentrated in Nagoya and Stuttgart industrial clusters. Distribution runs through Tier 1 automotive supplier networks, aftermarket digital channels, and hardware retail jobbers serving collision repair and restoration demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive replacement cycles and electric vehicle platform proliferation position this market for cyclical recovery, with battery-electric vehicle weight reduction mandates accelerating specification upgrades across door and trunk sealing applications.
For Market Incumbents: Harden supply chain resilience through backward integration into EPDM compound development and captive extrusion tooling production to offset petrochemical feedstock volatility. Lock in OEM platform engineering relationships ahead of divergent EPA, ECHA, and MIIT certification timelines that threaten to fragment global product portfolios and inflate development overhead for non-integrated competitors. For New Entrants and Emerging Players: Indian automotive localization under PLI scheme incentives represents the most penetrable entry point, with Maruti Suzuki and Hyundai Motor India expansion driving demand for extrusion tooling investment in Tamil Nadu and Gujarat manufacturing corridors. Target thermoplastic elastomer formulations compatible with EU Green Deal circular mandates to capture end-of-life vehicle recycling pull ahead of incumbents locked in thermoset rubber incineration pathways. For Investors and Strategic Acquirers: The market sits at a specification-upgrade phase that favors compounders with polymer formulation expertise and die engineering integration. Long-term viability over a five-to-ten year window rests on positioning for electric vehicle NVH engineering demands and aftermarket digital channel disintermediation. Watch for accelerated fleet procurement adoption of outcome-based performance contracts as the inflection signal compressing traditional piece-price negotiation models.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compound Development | Captive EPDM formulation control insulates margins from naphtha price volatility and secures OEM qualification lock-in. |
| Thermoplastic Elastomer Capacity Expansion | EU Green Deal recycling targets create pull for material recovery-compatible formulations versus thermoset incineration. |
| Extrusion Tooling Joint Venture | Flow simulation expertise scarcity in Germany and Japan demands partnership structures to access multi-cavity die engineering. |
| Aftermarket Digital Channel Launch | VIN-matched configurators on Amazon and RockAuto disintermediate traditional jobber distribution in restoration and collision repair. |
| Modular Snap-In Design Platform | MIIT-directed Chinese OEM architecture cycles prioritize reduced assembly-line touch time at BYD and Hyundai Motor facilities. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and extrusion tooling specialists; and secondary validation through vehicle production databases, customs and trade flow records, SEC 10-K filings of listed automotive suppliers, and regulatory filings with EPA, ECHA, and MIIT. Bottom-up segment sizing triangulated against top-down market consolidation estimates.
Forecast inputs considered material substitution dynamics, regulatory compliance cost trajectories, and platform standardization trends across the projection horizon. Segmentation dimensions modeled include material chemistry, installation type, use case intensity, and regional production cluster. CAGRs derived from elasticity-adjusted volume projections and value-per-unit evolution across specification tiers. Electric vehicle content-per-vehicle shifts and aftermarket replacement frequency assumptions anchored the analytical framework.
Macroeconomic conditions sit as an overlay; deviation in naphtha pricing, automotive production volumes, or currency volatility in Asian manufacturing corridors would shift the trajectory. Forecasts reflect documented assumptions on OEM platform cadence and regulatory harmonization timelines. Material shifts in ECHA authorization deadlines or EPA fuel economy standard stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Europe Timber Construction Connectors Market
Building & Construction Materials
Calcium Sulphate Board Raised Access Floor Market
Building & Construction Materials
Fire Rated Glass Market
Building & Construction Materials
Russia Ceramic Tiles Market
Building & Construction Materials
North America Decks Market
Building & Construction Materials
North America Steel Roofing Market
Building & Construction Materials
Ceiling Tiles Market
Building & Construction Materials
Cement Sacks Market
Building & Construction Materials
Global Fire-Rated Medium Density Fiberboard Market
Building & Construction Materials
Waterstop Market
Building & Construction Materials
Limestone Aggregates Market
Building & Construction Materials
Global Sandwich Panels Market
Building & Construction Materials
Sound Barriers Market
Building & Construction Materials
Warm Mix Asphalt Market
Building & Construction Materials
Global Steel Service Centers Market
Building & Construction Materials
Traffic Road Marking Coatings Market