
 Smart Sensor Market | 2026-2036
Smart Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Sensor Market Analysis
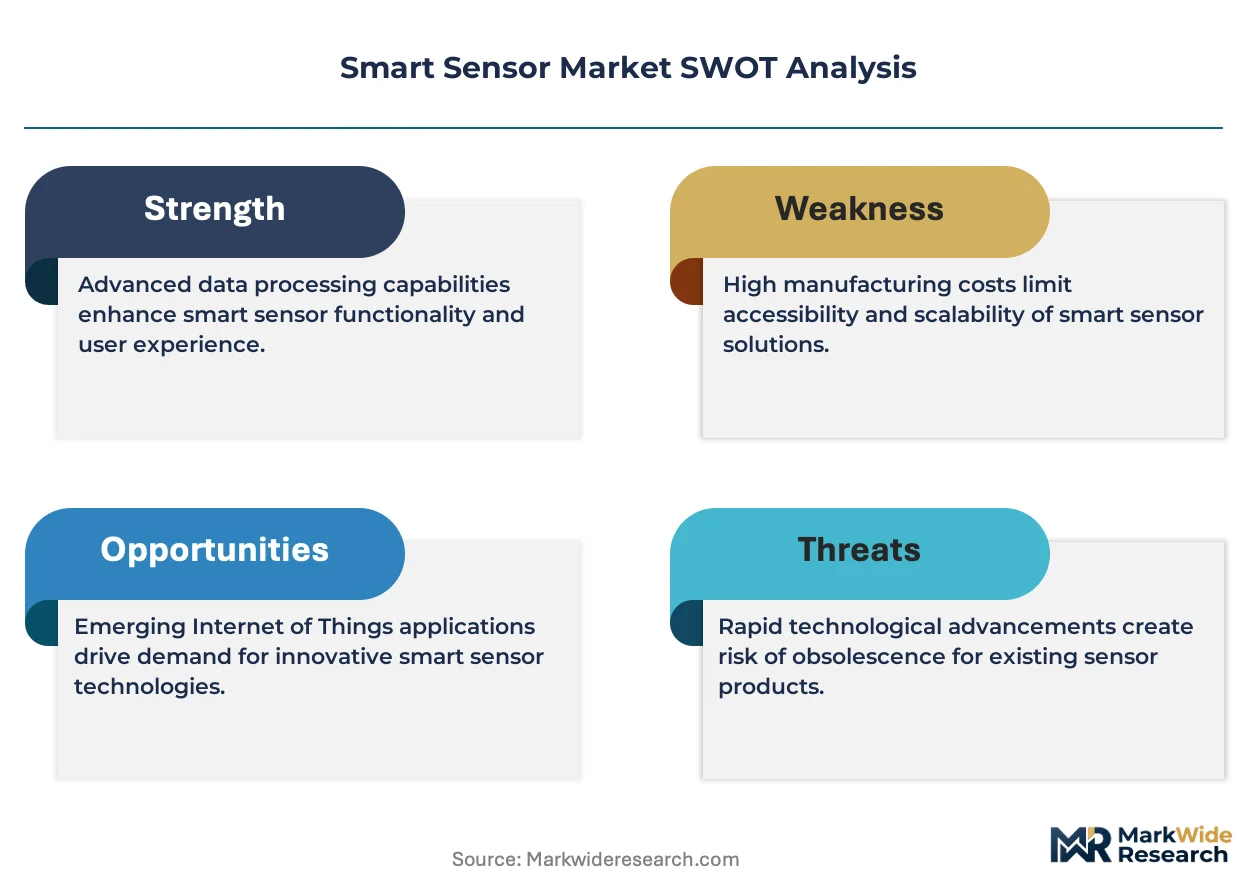
Sensor-as-a-service leasing models is reconfiguring capital deployment across the competitive landscape, allowing mid-tier manufacturers to access calibrated sensing arrays without heavy upfront investment. Honeywell International Inc. leverages its industrial automation heritage to dominate process-control sensor deployments. Infineon Technologies AG anchors its position through captive MEMS fabrication facilities. STMicroelectronics differentiates via integrated signal-conditioning architectures that reduce downstream design complexity.
Smart sensors are transducer devices incorporating embedded microprocessors, communication interfaces, and self-diagnostic algorithms to convert physical stimuli into actionable digital outputs with local preprocessing capabilities; they typically operate across temperature ranges from minus 40 to 125 degrees Celsius and communicate via I2C, SPI, or wireless protocols to enable real-time decision-making without host-processor dependency. Temperature sensors occupy the largest installed base due to universal applicability across HVAC, battery management, and process industries, while wireless sensors represent the fastest-expanding technology category as industrial mesh networks displace wired fieldbus architectures. Pressure sensors command premium margin pools in aerospace and medical-grade applications where calibration traceability requirements elevate switching costs.
The U.S. Food and Drug Administration and the European Medicines Agency impose stringent validation protocols on sensors deployed in patient-monitoring systems, effectively raising barriers for uncertified entrants. The Federal Communications Commission governs radio-frequency emissions from wireless sensor nodes, directly constraining transmission-power budgets and antenna-design choices. Stakeholders must monitor evolving cybersecurity mandates from the EU AI Act as edge-device authentication becomes a procurement gate.
Market Dynamics
Industrial mesh networks are collapsing the traditional wired fieldbus architecture, forcing sensor vendors to reengineer power budgets and security stacks for battery-operated edge nodes.
Growth Catalysts
- EU Green Deal energy-efficiency mandates:CE marking requirements for connected devices are accelerating replacement cycles in building automation and process industries.
- Predictive maintenance networks:Factory digitization programs in automotive and heavy machinery sectors are pulling calibrated sensor arrays into brownfield installations.
- MEMS fabrication scale:Captive 8-inch wafer capacity in Germany and Taiwan is reducing unit economics for pressure and inertial sensing modules.
Market Restraints
- Neodymium and palladium input volatility:Rare earth magnet costs for position sensors fluctuate with Chinese export quota policies.
- Calibration equipment concentration:Primary standards traceability depends on a narrow base of NIST- and PTB-accredited laboratories in the US and Germany.
- Wireless coexistence limitations:FCC Part 15 and ETSI EN 300 328 spectral density rules constrain multi-protocol node density in industrial environments.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Component-level incentives are attracting sensor packaging and testing investments away from traditional East Asian hubs.
- Sensor-as-a-service leasing:Mid-tier manufacturers are accessing calibrated arrays through operational expenditure models rather than capital deployment.
- EU AI Act edge-device authentication:Mandatory cybersecurity certification for autonomous decision-making nodes creates premium tiers for hardened hardware.
Industry Challenges
- Multi-physics simulation expertise:Packaging teams lack coupled thermal-electro-mechanical modeling capabilities for harsh-environment reliability.
- ISO/IEC 17025 audit timelines:Third-party laboratory accreditation for medical-grade pressure sensors extends time-to-revenue by 14-18 months.
- Legacy 4-20mA integration friction:Brownfield process plants resist full digital retrofits, forcing hybrid signal-conditioning architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Sensor Market |
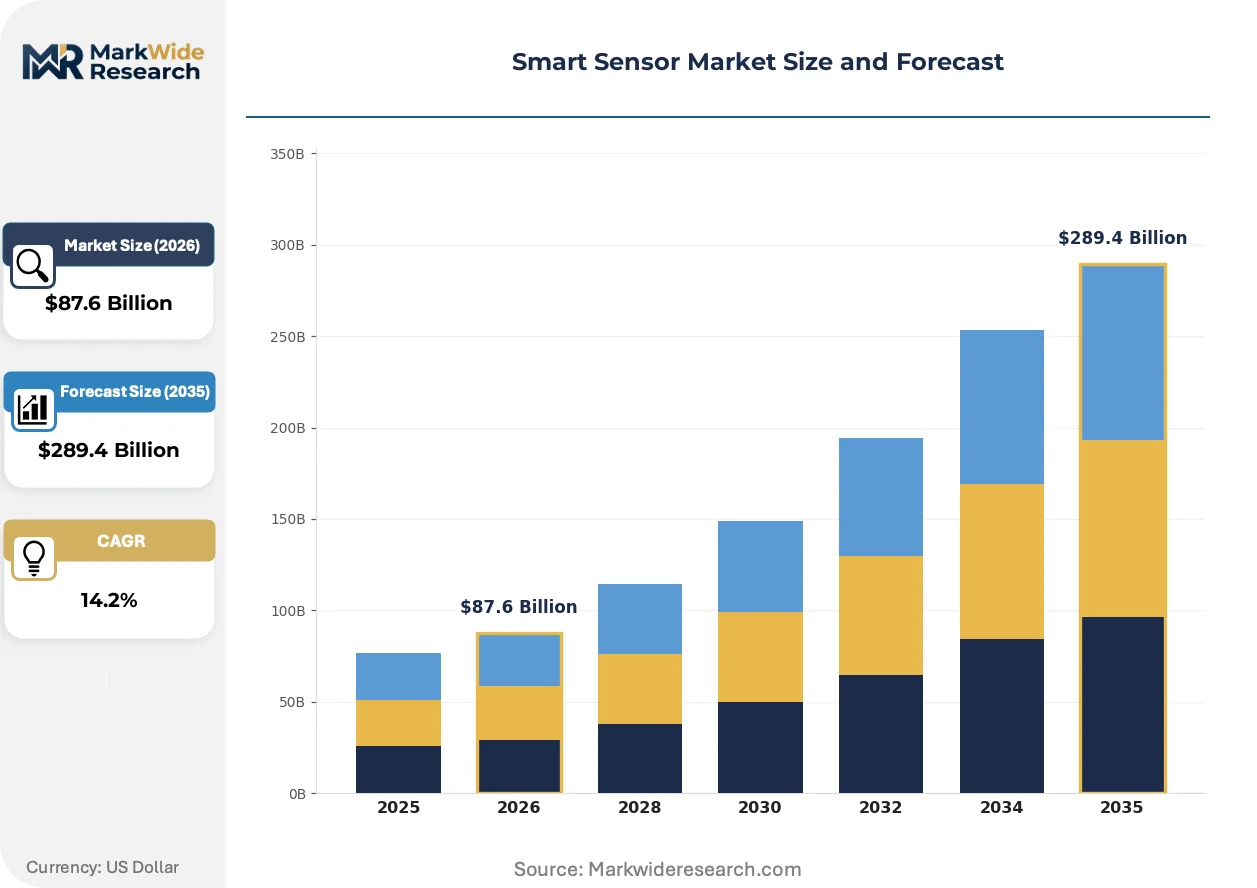
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $289.4 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Proximity Sensors, Pressure Sensors, Accelerometers Technology: Microelectromechanical Systems, Analog Sensors, Digital Sensors, Wireless Sensors Application: Smart Homes, Industrial Automation, Healthcare Monitoring, Automotive Systems End User: Consumer Electronics, Manufacturing, Healthcare, Energy Management |
| Companies Covered | Analog Devices, Inc., Honeywell International Inc., Siemens AG, Robert Bosch GmbH, STMicroelectronics, Infineon Technologies AG, NXP Semiconductors, TE Connectivity, Omron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Sensor Market Emerging Trajectories
Edge intelligence is redistributing computational load from cloud gateways to sensor nodes, compressing response latency for safety-critical loops while complicating firmware update logistics.
Time-sensitive networking over IEEE 802.1AS is collapsing the determinism gap between Ethernet-based sensor buses and legacy fieldbus protocols. Automotive OEMs in Germany and Japan are adopting TSN-enabled camera and lidar modules for synchronized perception stacks. This convergence is collapsing the historical separation between IT and OT network engineering teams in plant environments.
REACH substance restrictions on per- and polyfluoroalkyl substances are forcing MEMS foundries to reformulate wafer-release chemistries and packaging adhesives. The European Chemicals Agency's 2023 PFAS restriction proposal targets fluorinated polymers used in moisture barriers. Sensor vendors with German automotive qualifications face the steepest reformulation timelines given existing PPAP lock-ins.
Asset-light procurement is displacing outright ownership in industrial sensor deployments. German automotive tier-1 suppliers are leasing vibration-monitoring arrays with bundled calibration and cloud analytics from component vendors. This shift concentrates vendor selection criteria on service-level agreements and cybersecurity liability rather than hardware specifications alone.
Smart Sensor Market Segmentation
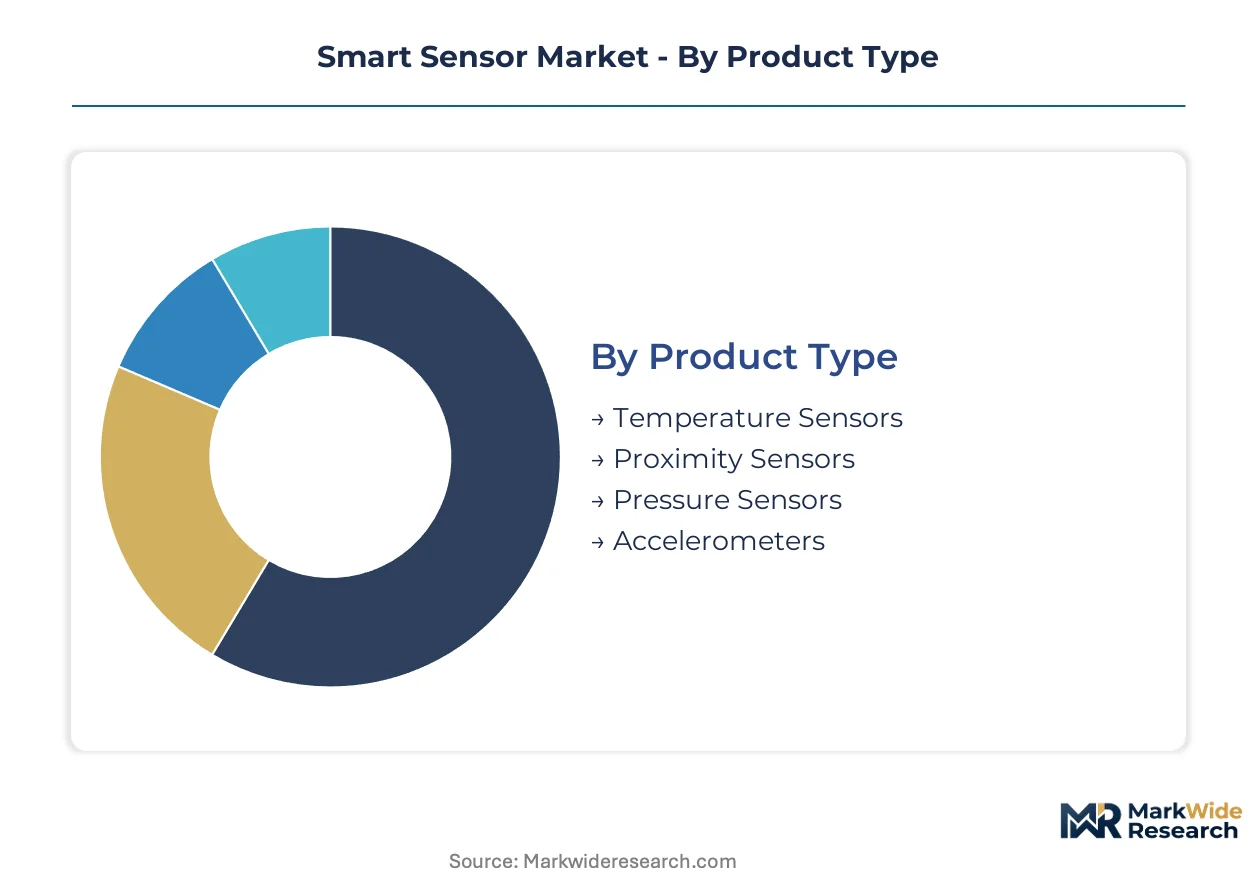
Smart sensor procurement varies sharply by deployment environment, from precision calibration requirements in medical settings to ruggedized packaging for factory floors. Segmentation reveals how technical specifications, connectivity protocols, and regulatory compliance tiers reshape vendor selection criteria across verticals.
Product Type:
Use cases span thermal monitoring in battery systems to vibration sensing in rotating machinery, with each transducer type commanding distinct margin pools based on calibration traceability requirements.
- Temperature Sensors:Thermocouple, RTD, and semiconductor junction devices dominate HVAC, electric vehicle battery management, and process control installations. Universal applicability across building automation and industrial process loops sustains the largest installed base, though price compression in consumer-grade silicon thermistors erodes margins at the low end.
- Pressure Sensors:Piezoresistive MEMS and capacitive ceramic transducers serve aerospace, medical infusion pumps, and hydraulic systems where NIST-traceable calibration certificates elevate switching costs. German automotive OEMs and medical device manufacturers in Switzerland anchor premium procurement for safety-critical applications.
- Proximity Sensors:Inductive, capacitive, and photoelectric variants detect object presence without physical contact in packaging lines and robotics cells.
- Accelerometers:Capacitive MEMS and piezoelectric devices measure vibration and shock in predictive maintenance networks and automotive crash detection systems.
Established volume favors temperature sensing; emerging adoption favors pressure sensing in medical-grade deployments.
Technology:
Cost tiers separate legacy analog architectures from digitally integrated and wirelessly connected nodes, with fabrication scale determining competitive positioning.
- Microelectromechanical Systems:Silicon micromachining enables batch-fabricated pressure, inertial, and acoustic transducers at unit economics unreachable with discrete component assembly. Captive 8-inch wafer capacity in Germany and Taiwan anchors supply concentration for automotive-qualified devices.
- Wireless Sensors:Battery-operated mesh nodes communicating via LoRa, Zigbee, or proprietary industrial protocols are displacing wired fieldbus architectures in brownfield retrofits. FCC Part 15 and ETSI EN 300 328 spectral density rules constrain transmission power budgets and node density in multi-protocol environments.
- Digital Sensors:Integrated ADC and preprocessing capabilities reduce host-processor dependency while complicating firmware update logistics for edge intelligence deployments.
- Analog Sensors:Continuous voltage or current outputs persist in legacy 4-20mA process control loops where full digital retrofits face capital constraints.
Legacy analog maintains share in process industries; wireless architectures are climbing the fastest in industrial automation.
Application:
Customer maturity separates consumer-facing convenience features from industrial safety-critical systems with stringent validation protocols.
- Industrial Automation:Predictive maintenance networks, robotic positioning, and process control loops demand calibrated sensing arrays with ISO/IEC 17025 traceability. Factory digitization programs in German automotive and heavy machinery sectors pull sensor procurement into brownfield installations.
- Healthcare Monitoring:Patient-worn and bedside devices require FDA and EMA validation protocols that extend time-to-revenue by 14-18 months for uncertified entrants. Blood pressure cuffs, pulse oximeters, and infusion pumps represent concentrated demand from hospital systems and home care providers.
- Smart Homes:Thermostats, occupancy detectors, and air quality monitors serve residential and commercial building automation with lower certification barriers but higher price sensitivity.
- Automotive Systems:Engine management, chassis control, and advanced driver-assistance systems require AEC-Q100 qualified devices with PPAP documentation lock-ins.
Industrial automation commands premium pricing; healthcare monitoring faces the steepest regulatory filtration.
End User:
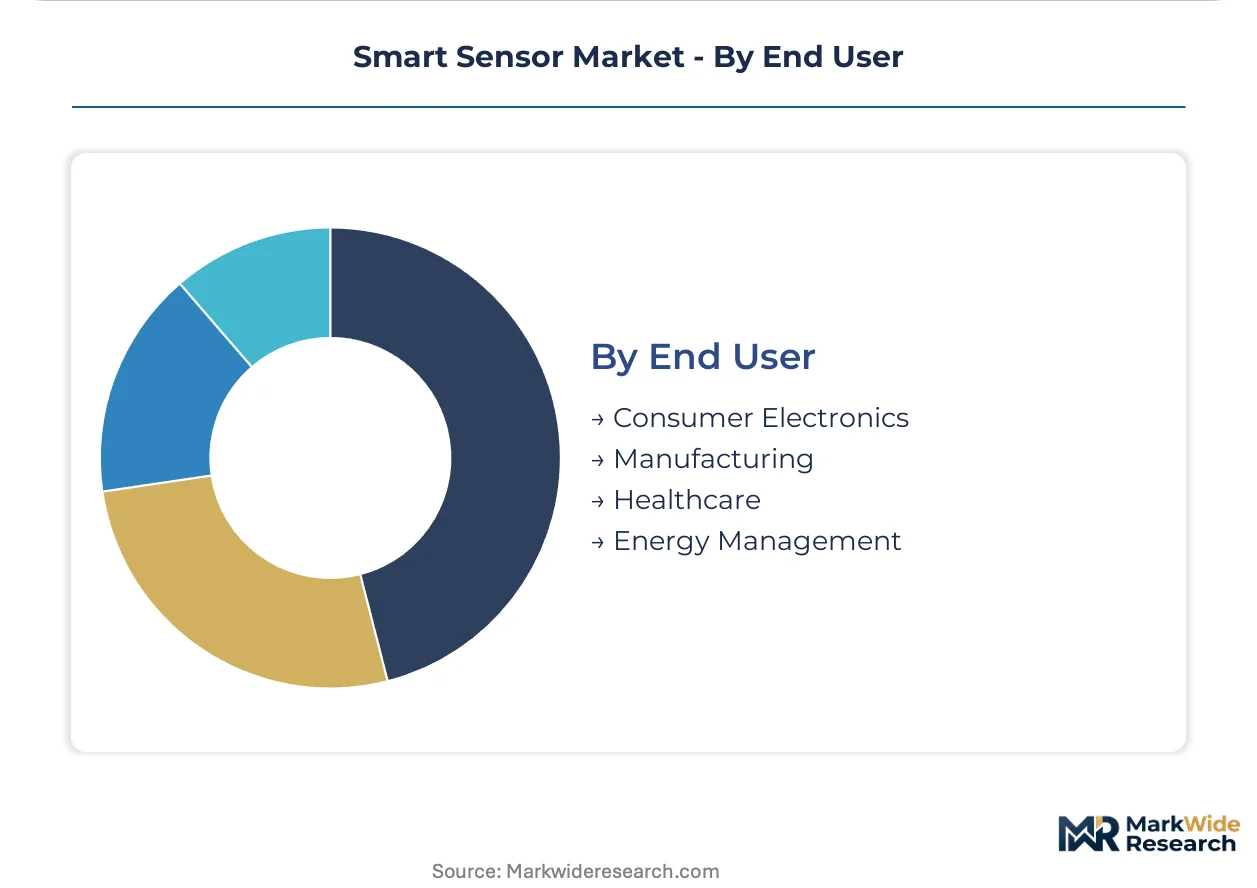
Procurement patterns diverge between high-volume consumer electronics with compressed design cycles and industrial sectors with decade-long equipment lifecycles.
- Manufacturing:Discrete and process industries deploy vibration, temperature, and pressure monitoring for asset health optimization. German industrial equipment makers anchor sensor procurement with bundled calibration and cloud analytics service agreements.
- Healthcare:Hospital systems, diagnostic imaging OEMs, and home care device manufacturers prioritize cybersecurity certification under the EU AI Act for autonomous decision-making nodes.
- Consumer Electronics:Smartphones, wearables, and white goods integrate motion, environmental, and biometric sensors at massive scale with aggressive cost-down targets.
- Energy Management:Grid monitoring, renewable generation asset tracking, and building energy optimization drive demand for power-quality and environmental sensors.
Manufacturing sustains the deepest integration partnerships; energy management is gaining share fastest from decarbonization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal energy-efficiency mandates and national semiconductor subsidy programs are redrawing procurement patterns across major economies. Factory digitization initiatives in automotive and heavy machinery sectors pull sensor deployment into brownfield installations. Regulatory divergence on cybersecurity certification and rare earth export controls fragments vendor qualification requirements.
Germany
Automotive OEMs in Stuttgart and Munich anchor premium demand for AEC-Q100 qualified pressure and inertial sensors. The KBA enforces PPAP documentation lock-ins that extend qualification timelines for safety-critical chassis applications. Bavarian industrial equipment makers bundle vibration-monitoring arrays with cloud analytics service agreements.
United States
FDA validation protocols for patient-monitoring systems create 14-18 month barriers for uncertified entrants in healthcare. The FCC governs radio-frequency emissions from wireless sensor nodes, constraining transmission-power budgets for industrial mesh networks. Michigan automotive suppliers and Texas oilfield service companies drive divergent demand for ruggedized versus precision-calibrated devices.
China
MIIT dual carbon goals accelerate building automation sensor replacement cycles in commercial real estate. GB standards on electromagnetic compatibility filter uncertified vendors from state-owned enterprise procurement. Yangtze River Delta MEMS foundries expand 8-inch wafer capacity for pressure and acoustic transducers serving domestic automotive brands.
Japan
METI subsidies for predictive maintenance networks pull calibrated sensing arrays into aging steel and chemical plant infrastructure. JIS standards on industrial communication protocols constrain interoperability with foreign wireless architectures. Nagoya automotive tier-1 suppliers lease vibration-monitoring equipment with bundled calibration services.
India
PLI scheme incentives for electronics manufacturing attract sensor packaging and testing investments from East Asian contract manufacturers. CEA mandates on grid monitoring equipment create demand for power-quality sensors in renewable generation asset tracking. Tamil Nadu and Karnataka industrial corridors host expanding calibration laboratory capacity for automotive qualification.
Smart Sensor Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. Industrial automation heritage confers procurement access in process-control deployments. MEMS fabrication scale and integrated signal-conditioning architectures represent distinct strategic archetypes. Capacity expansion in captive wafer facilities and sensor-as-a-service leasing models constitute dominant competitive moves.
Among diversified industrial conglomerates, Honeywell International Inc., Siemens AG, and Robert Bosch GmbH occupy positions spanning process automation, building technologies, and automotive systems. These entities leverage established distribution channels and service infrastructure to bundle hardware with predictive analytics subscriptions. STMicroelectronics and Infineon Technologies AG exemplify the captive-fabrication archetype, anchoring supply security through in-house MEMS production. NXP Semiconductors represents the automotive-specialist positioning with AEC-Q100 qualification depth.
| Leading Market Players |
|---|
| Analog Devices, Inc. |
| Honeywell International Inc. |
| Siemens AG |
| Robert Bosch GmbH |
| STMicroelectronics |
| Infineon Technologies AG |
| NXP Semiconductors |
| TE Connectivity |
| Omron Corporation |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Taiwan's 8-inch MEMS foundries is forcing automotive sensor buyers into longer-term contract commitments and elevating spot-market premiums for AEC-Q100 qualified devices. This utilization squeeze transmits directly into pricing power for captive-fabrication specialists while squeezing margins for fabless design houses dependent on outsourced wafer supply.
Pricing Analysis
Certification level creates the primary spread between premium and economy tiers in smart sensor procurement. AEC-Q100 automotive qualification and ISO/IEC 17025 calibration traceability command substantial premiums over consumer-grade silicon thermistors. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade pressure sensors with FDA validation from industrial process sensors with CE marking and basic HVAC thermistors. Cost compression in consumer-grade temperature sensing is intensifying because smartphone and white goods manufacturers enforce aggressive annual cost-down targets. Healthcare monitoring applications show the lowest price sensitivity due to switching costs and liability exposure, while smart home device makers exhibit extreme elasticity to component pricing.
Supply Chain Analysis
Contract manufacturing concentration rests with Taiwan Semiconductor Manufacturing Company and United Microelectronics Corporation for MEMS wafer fabrication, alongside Foxconn and Jabil for sensor module assembly and testing. Geographic supply concentration centers on Taiwan for captive 8-inch MEMS foundry capacity, Germany for automotive qualification and calibration laboratories, and China for rare earth magnet processing in position sensing applications. Raw material dependencies draw from neodymium and palladium for magnetic position sensors, silicon wafers for MEMS transducers, and fluorinated polymers for moisture barrier packaging. Single-source vulnerability in NIST- and PTB-accredited calibration standards creates chokepoint risk for medical-grade sensor certification. Distribution runs through direct OEM relationships for automotive and industrial tiers, with electronics distributors serving mid-volume manufacturing and building automation segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart sensor penetration remains in early-cycle expansion as factory digitization programs accelerate predictive maintenance network deployment across brownfield industrial infrastructure.
For Market Incumbents: Harden cybersecurity certification capabilities under the EU AI Act to capture premium pricing for autonomous edge-device authentication. Expand captive 8-inch MEMS wafer capacity in Germany or Taiwan to secure supply continuity against foundry undercapacity. Defensive positioning against fabless entrants requires deepening calibration laboratory accreditation and PPAP documentation lock-ins with Stuttgart and Munich automotive OEMs. For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme corridors for sensor packaging and testing services, leveraging component-level incentives away from saturated East Asian hubs. Target power-quality sensor procurement for renewable generation asset tracking under CEA mandates, where qualification barriers remain lower than automotive or medical tiers. Go-to-market traction requires bundling hardware with cloud analytics subscriptions to match German industrial equipment maker service-level expectations. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mid-cap specialists with captive MEMS fabrication and existing AEC-Q100 qualification depth. Long-term viability favors entities with backward integration into wafer supply and forward integration into sensor-as-a-service leasing models. The signal to monitor is India PLI scheme disbursement velocity and Tamil Nadu calibration laboratory accreditation timelines as inflection indicators for supply chain migration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive MEMS Foundry Expansion | Secures wafer supply continuity for automotive-qualified pressure and inertial sensors against Taiwan capacity constraints. |
| EU AI Act Cybersecurity Certification | Creates premium tier access for edge-device authentication in autonomous decision-making nodes across German manufacturing. |
| Sensor-as-a-Service Leasing Launch | Transforms capital expenditure models for mid-tier manufacturers through bundled calibration and cloud analytics subscriptions. |
| India PLI Scheme Manufacturing Migration | Captures component-level incentives for sensor packaging and testing in Tamil Nadu and Karnataka industrial corridors. |
| ISO/IEC 17025 Calibration Laboratory Accreditation | Extends medical-grade pressure sensor market access through NIST-traceable certification reducing time-to-revenue barriers. |
Methodological Framework
A standing panel of MEMS fabrication engineers, automotive Tier 1 procurement directors, industrial automation system integrators, and FDA regulatory affairs specialists provided ongoing calibration throughout the research process. Primary interview insights were cross-validated against secondary sources including SEC 10-K filings from diversified industrial conglomerates, ECHA PFAS restriction proposals, FCC Part 15 spectral density rulings, and EU AI Act cybersecurity draft provisions. Bottom-up sensor shipment estimates by product type and application were triangulated with top-down market sizing derived from semiconductor capital expenditure disclosures and industrial automation software revenue proxies.
Scenario-bracketing around EU Green Deal implementation velocity and India PLI scheme disbursement timelines framed the projection envelope across the analysis window. Segmentation modeling incorporated product type, technology architecture, application vertical, and end-user industry dimensions alongside regional regulatory cluster differentiation. CAGRs were derived from fitted adoption curves calibrated to historical MEMS unit economics and wireless sensor node deployment trajectories. Forecast inputs included automotive production schedules for Stuttgart and Munich OEMs, MIIT dual carbon building automation mandates, and METI predictive maintenance subsidy allocations.
Sensitivities concentrate around neodymium export quota volatility from Chinese rare earth policies and REACH substance restriction timelines for PFAS reformulation in MEMS packaging. Forecasts embed assumptions regarding 8-inch wafer capacity expansion trajectories and ISO/IEC 17025 audit timeline normalization. Quarterly review of Taiwan foundry utilization rates, India electronics manufacturing incentive disbursements, and EU AI Act certification requirement finalization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Connected Sensors Market
Sensors and Controls
Thermo Hygrometer Market
Sensors and Controls
Thermistor Temperature Sensor Market
Sensors and Controls
Europe Machine Control System Market
Sensors and Controls
Doppler Wind Lidar System Market
Sensors and Controls
Odor Detection Equipment Market
Sensors and Controls
Magnetic Sensor Market
Sensors and Controls
Light Detection and Ranging (Lidar) Market
Sensors and Controls
Europe Temperature Sensors Market
Sensors and Controls
Middle East and Africa Vibration Sensors Market
Sensors and Controls
Digital Flow Meter Market
Sensors and Controls
Global Nanosensors Market
Sensors and Controls
Water and Wastewater Sensors Market
Sensors and Controls
MEMS Market
Sensors and Controls
United States Scintillator Market
Sensors and Controls
DCT Mechatronic Control Unit Market