
 Radar Level Transmitter Market | 2026-2036
Radar Level Transmitter Market Size, Share, and Industry Trends Forecast 2026-2036
Radar Level Transmitter Market Analysis
IEC 61508 functional safety certification is redrawing competitive boundaries among radar level transmitter suppliers. Emerson leverages its global instrumentation footprint to sustain project engineering relationships across major refinery operators. Endress+Hauser anchors its position through deep calibration service networks in European process industries. Siemens competes by integrating radar level data into its distributed control system architectures.
A radar level transmitter measures liquid or solid material height in storage vessels and process tanks by emitting electromagnetic waves and calculating distance from the reflected signal, typically operating at frequencies between 6 GHz and 80 GHz depending on the technology variant. Its primary industrial purpose centers on inventory management, overflow prevention, and continuous process control in hazardous or high-pressure environments. Frequency modulated continuous wave technology leads in accuracy-critical chemical applications where millimeter-level precision justifies premium positioning, while non-contact pulsed radar dominates bulk solids measurement in mining and cement operations where build-up resistance determines equipment survival. Contact-guided wave radar occupies a specialized niche in liquefied natural gas and cryogenic storage where probe-based measurement penetrates vapor layers that defeat free-space propagation.
The EPA enforces leak detection and repair standards that mandate reliable level monitoring in petroleum storage, while IEC 61508 and ATEX directives in Europe shape product certification requirements for explosive atmosphere deployment. China's SAMR implements GB standards for measuring instruments used in hazardous chemical facilities, creating parallel compliance pathways for multinational suppliers. Buyers must evaluate whether supplier certification portfolios align with their specific geographic operating jurisdictions before committing to platform-standardization strategies.
Market Dynamics
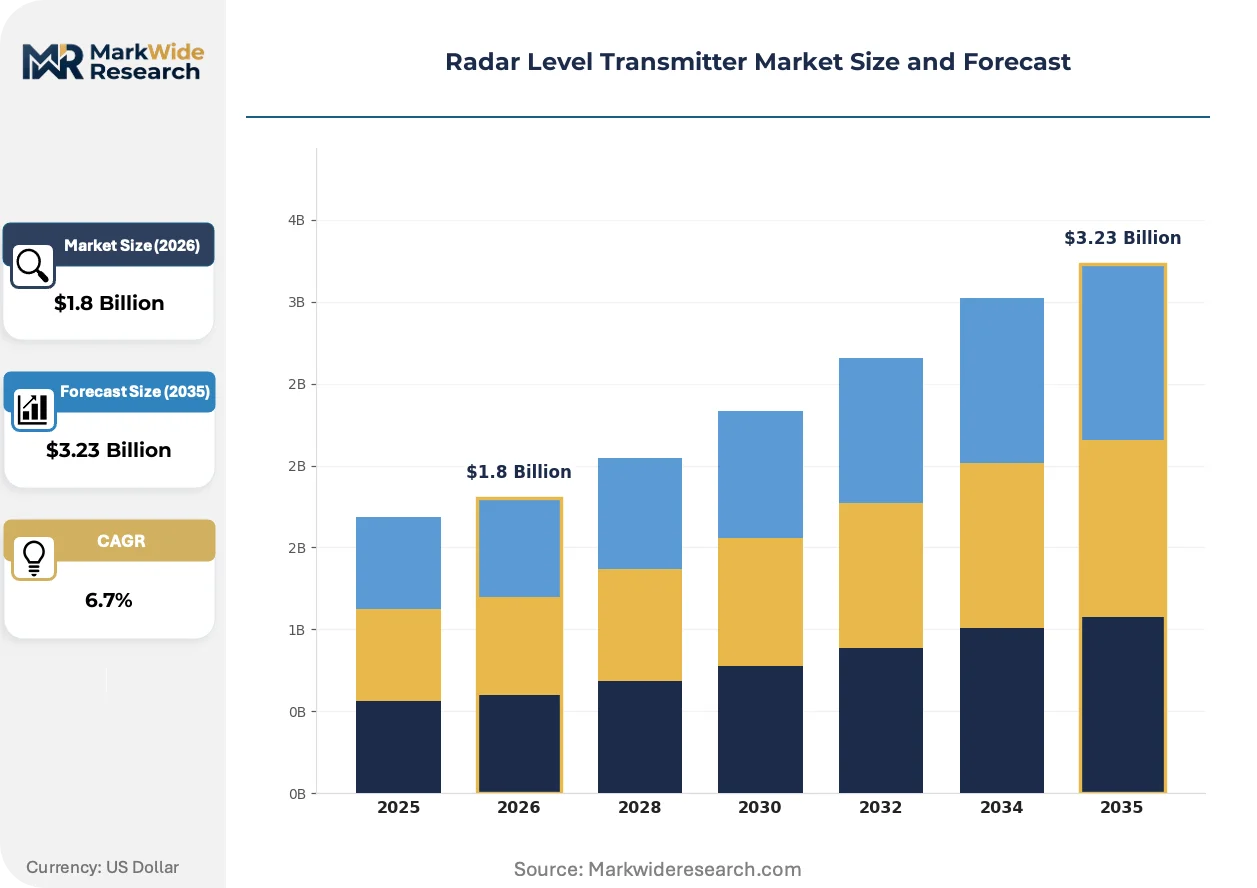
Frequency modulated continuous wave technology is compressing price premiums across chemical processing applications while IEC 61508 certification requirements fragment supplier qualification pools. Procurement teams now weight calibration service density equally with hardware specifications.
Growth Catalysts
- IEC 61508 functional safety mandates:Chemical facilities in Germany and the United States face mandatory SIL certification for overfill protection systems. Non-contact FMCW units capture preference where millimeter precision prevents catastrophic tank failures.
- EPA leak detection enforcement:Petroleum storage operators on the US Gulf Coast must deploy continuous level monitoring to satisfy LDAR inspection protocols. Radar instruments displace mechanical floats where vapor recovery integration matters.
- Yangtze River Delta manufacturing expansion:China's hazardous chemical facility upgrades under SAMR GB standards drive instrument replacement cycles. Multinational suppliers localize production to capture procurement tenders.
Market Restraints
- Semiconductor input volatility:Gallium arsenide and silicon germanium wafer costs fluctuate with RF component demand from telecommunications. Transmitter manufacturers absorb margin compression or pass through to project budgets.
- Specialized calibration labor scarcity:Certified technicians for 80 GHz FMCW verification concentrate in Western Europe and coastal China. Field service coverage gaps delay commissioning in peripheral industrial zones.
- Guided wave radar substitution:Probe-based contact instruments penetrate LNG cryogenic storage where vapor layers defeat free-space propagation. Contactless suppliers forfeit share in liquefied natural gas infrastructure.
Strategic Opportunities
- India hazardous chemical facility buildup:BIS certification requirements for measuring instruments create first-mover advantage for certified suppliers. Domestic refinery expansions along the Gujarat coast require SIL-rated level systems.
- Digital twin integration:Radar level data streams into predictive maintenance platforms through OPC UA protocols. Asset-intensive operators in petrochemical corridors pay premium for connected instrument packages.
- EU F-Gas Regulation phase-down:Refrigerated storage operators abandon hydrofluorocarbon-based level detection. Radar instruments capture share in cold chain logistics and pharmaceutical warehousing.
Industry Challenges
- Multi-protocol integration complexity:Legacy DCS architectures from the 1990s lack native 80 GHz signal processing capability. Upgrade projects require middleware development that extends commissioning timelines.
- ATEX and IECEx parallel certification burden:Suppliers maintain separate testing documentation for European and international explosive atmosphere standards. Certification timeline duplication strains engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radar Level Transmitter Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Guided Wave Radar, Microwaves, Frequency Modulated Continuous Wave, Pulsed Radar Technology: Non-Contact, Contact, Differential Pressure, Ultrasonic End User: Oil & Gas, Water Treatment, Chemicals, Food & Beverage Installation: Fixed, Portable, Submerged, Top-Mounted |
| Companies Covered | Emerson, ABB, Endress+Hauser, Rosemount, Honeywell, VEGA Grieshaber, KROHNE, Magnetrol, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radar Level Transmitter Market Emerging Trajectories
Electromagnetic wave processing hardware and signal interpretation software are diverging into separate competitive arenas. Suppliers must now excel at both RF engineering and edge computing to sustain premium positioning.
Frequency modulated continuous wave architecture is bifurcating the accuracy-sensitive chemical tier from bulk solids applications. Chemical processors in the US Gulf Coast and Germany's Ruhr basin specify 80 GHz units for reactor level control. Pulsed radar suppliers retreat toward mining and cement where build-up tolerance outweighs precision requirements.
REACH substance restrictions and ATEX directive updates are compelling material changes in transmitter housings. Manufacturers substitute glass-reinforced polymers for aluminum in corrosive atmosphere deployments. European process industries face the tightest compliance windows, accelerating qualification cycles for housing suppliers.
Service unbundling is fragmenting traditional project pricing. End-users in China's Yangtze Delta now procure hardware through EPC contractors while negotiating calibration contracts directly with instrument vendors. This bifurcation compresses upfront equipment margins while extending recurring revenue relationships.
Radar Level Transmitter Market Segmentation
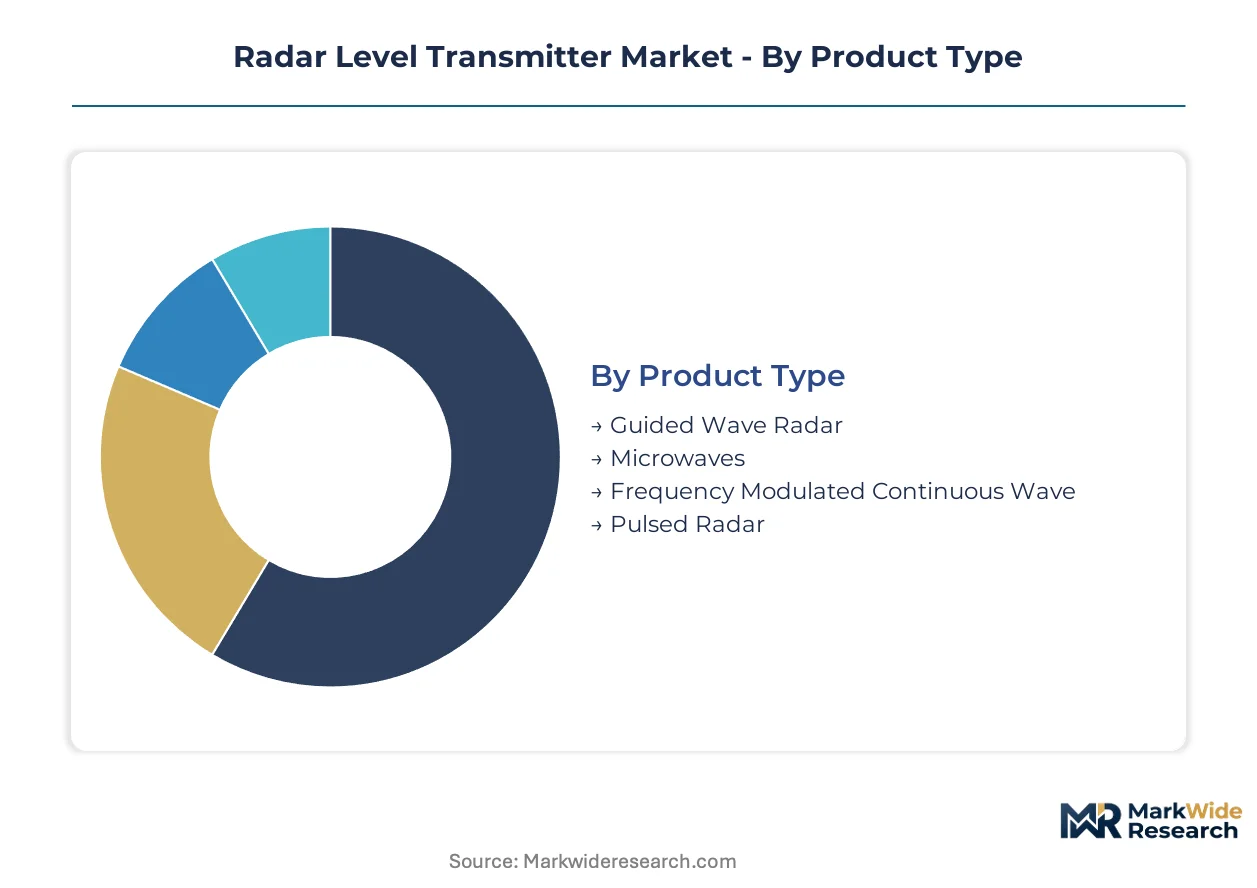
Radar level transmitter procurement patterns diverge sharply across technology platforms and deployment contexts. End-users segment their sourcing strategies by measurement precision requirements, hazardous area classifications, and integration complexity with legacy control systems.
Product Type:
Domestic production concentrates frequency modulated continuous wave units in Germany and the United States for chemical sector export, while pulsed radar manufacturing localizes in China for mining and cement applications serving Asian markets.
- Frequency Modulated Continuous Wave:These units transmit continuous frequency sweeps and measure phase shift to achieve millimeter-level accuracy in reactor level control. US Gulf Coast petrochemical operators specify 80 GHz FMCW variants for SIL-rated overfill protection under EPA enforcement protocols.
- Pulsed Radar:Time-of-flight measurement using discrete microwave pulses dominates bulk solids applications where build-up resistance outweighs precision demands. China's Yangtze River Delta cement producers favor pulsed units for clinker silo monitoring under SAMR GB compliance requirements.
- Guided Wave Radar:Probe-based contact instruments penetrate vapor layers in cryogenic LNG storage where free-space propagation fails.
- Microwaves:Lower-frequency 6 GHz units serve legacy tank farms with simpler signal processing requirements and reduced semiconductor content.
Frequency modulated continuous wave holds the largest share; momentum sits with pulsed radar in emerging market bulk applications.
Technology:
Cost tiers separate certification-intensive non-contact platforms from commodity contact alternatives, with ultrasonic occupying a price-sensitive niche below radar technologies.
- Non-Contact:Free-space electromagnetic transmission eliminates probe fouling in corrosive chemical environments. German process industries mandate non-contact FMCW units for IEC 61508 SIL certification compliance in hazardous reactor vessels.
- Contact:Probe-based measurement penetrates vapor layers and foam that defeat non-contact propagation. Guided wave contact instruments capture liquefied natural gas storage contracts where cryogenic vapor suppression is critical.
- Differential Pressure:Hydrostatic measurement using pressure transmitters competes on installed cost in non-hazardous liquid storage.
- Ultrasonic:Acoustic pulse-echo technology serves water treatment and food applications where electromagnetic compatibility constraints limit radar deployment.
Non-contact commands premium positioning; contact technology is climbing the fastest in LNG infrastructure investment cycles.
End User:
Application maturity varies dramatically, with oil and gas representing established replacement demand while food and beverage offers greenfield automation potential.
- Oil & Gas:Petroleum storage and refining operations require continuous level monitoring for leak detection and vapor recovery integration. US Gulf Coast operators face EPA LDAR mandates that displace mechanical floats with radar instruments in above-ground storage tanks.
- Chemicals:Reactor level control and hazardous material storage demand SIL-certified precision measurement. German chemical processors in the Ruhr basin specify 80 GHz FMCW units under ATEX and IEC 61508 functional safety requirements.
- Water Treatment:Municipal and industrial wastewater facilities deploy radar for sludge level and clarifier monitoring.
- Food & Beverage:Hygienic process connections and CIP-cleanable designs distinguish radar specifications in dairy and brewing applications.
Oil and gas retains the largest installed base; food and beverage presents the steepest expansion trajectory as automation penetrates batch processing.
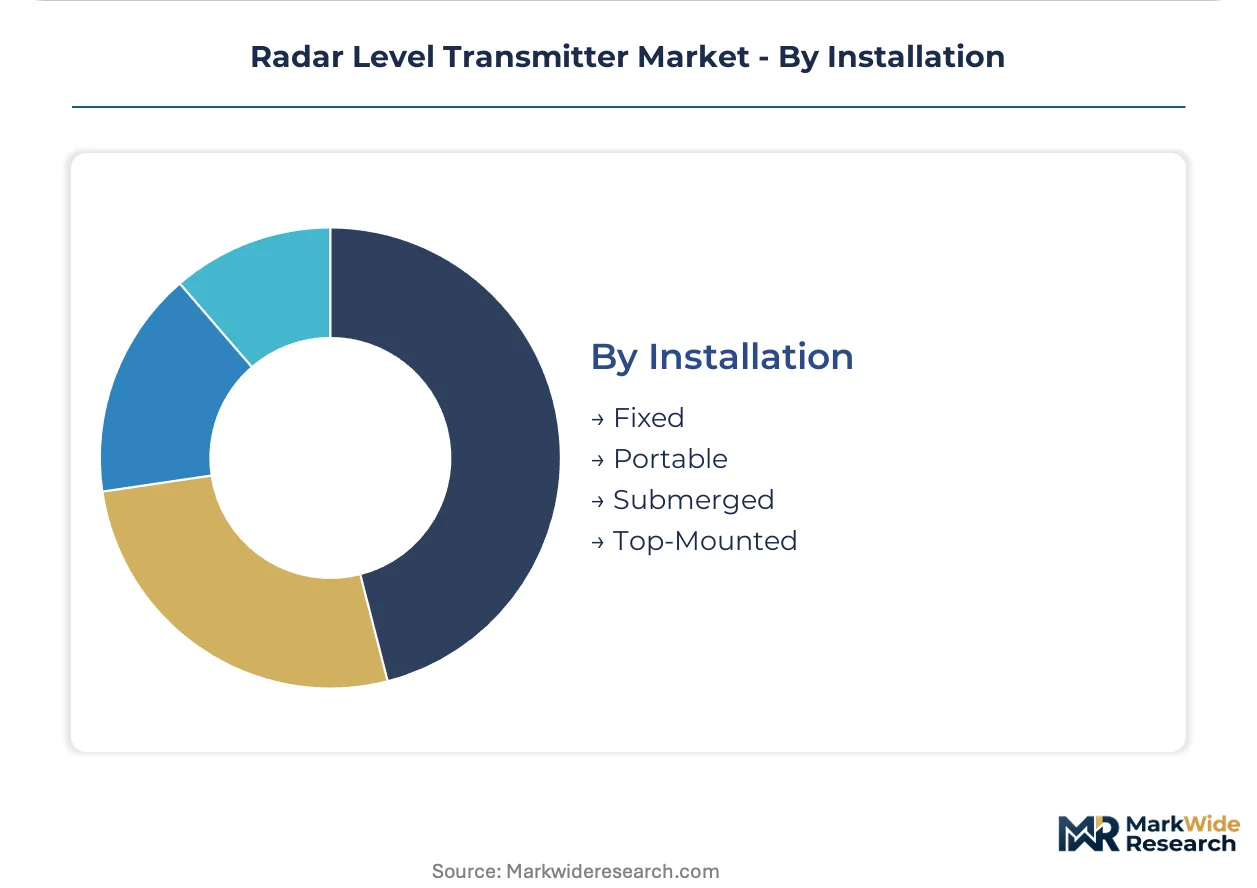
Installation:
Volume concentration favors fixed permanent mounting, though portable configurations serve maintenance and calibration service providers.
- Fixed:Permanent vessel-mounted transmitters dominate process industry automation with hardwired 4-20 mA or digital protocol outputs. China's Yangtze River Delta hazardous chemical facility upgrades under SAMR standards drive fixed installation replacement cycles.
- Top-Mounted:Nozzle-positioned instruments simplify retrofit in existing tank farms without internal vessel access. US refinery operators favor top-mounted radar for LDAR compliance upgrades to minimize shutdown requirements.
- Portable:Battery-powered handheld units support field verification and temporary measurement campaigns.
- Submerged:Pressure-compensated designs serve deep tank and sump applications where surface measurement is impractical.
Fixed installation captures the dominant revenue position; top-mounted configurations are gaining share fastest in retrofit-intensive developed markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA enforcement of leak detection and repair standards is reshaping procurement patterns across petroleum storage corridors. IEC 61508 functional safety mandates in Europe and SAMR hazardous chemical regulations in China are accelerating instrument replacement cycles in process industries.
United States
Petrochemical operators along the Gulf Coast face EPA LDAR inspection protocols that mandate continuous level monitoring in above-ground storage tanks. Refinery expansions in Texas and Louisiana are displacing mechanical floats with radar instruments to satisfy vapor recovery integration requirements. Houston anchors the densest concentration of procurement activity for SIL-rated overfill protection systems.
Germany
Chemical processors in the Ruhr basin specify 80 GHz FMCW units under ATEX and IEC 61508 functional safety requirements for reactor level control. REACH substance restrictions are compelling material changes in transmitter housings for corrosive atmosphere deployments. BASF and Bayer facility upgrades in Ludwigshafen and Leverkusen drive premium-tier instrument demand.
China
SAMR GB standards for measuring instruments in hazardous chemical facilities are triggering replacement cycles across the Yangtze River Delta manufacturing belt. Domestic refinery and petrochemical expansions in Shanghai and Ningbo require localized production capabilities from multinational suppliers. State-owned enterprise procurement tenders favor vendors with in-country calibration service networks.
India
BIS certification requirements for measuring instruments create qualification barriers for imported radar level transmitters. Refinery expansions along the Gujarat coast in Jamnagar and Vadodara require SIL-rated level systems for new crude processing units. Reliance Industries and Indian Oil facility upgrades are concentrating demand in the western industrial corridor.
Saudi Arabia
Saudi Aramco downstream expansions in Jubail and Yanbu are specifying radar instruments for crude storage and refining operations. The kingdom's national industrial regulator mandates hazardous area certifications aligned with IECEx standards for petrochemical infrastructure. SABIC affiliate facilities are driving procurement volume for high-temperature process vessel applications.
Radar Level Transmitter Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with established instrumentation divisions. Market structure exhibits moderate consolidation around suppliers with integrated calibration service networks and functional safety certification portfolios. Two strategic archetypes dominate: full-line process automation vendors leveraging distributed control system integration, and specialized level measurement firms competing on application engineering depth. Competitive moves center on geographic expansion of field service coverage and technology licensing partnerships for 80 GHz signal processing.
Among diversified automation suppliers, Emerson Electric Co. and Siemens AG exemplify the full-line archetype through their instrumentation-to-control-system integration capabilities. Endress+Hauser AG occupies a position within the specialized tier, anchoring premium positioning through calibration service density in European process industries. VEGA Grieshaber KG represents the mid-market specialist segment, while ABB Ltd. sits within the conglomerate tier with broad industrial electrification portfolios. Honeywell International Inc. and KROHNE Messtechnik GmbH exemplify regional strength archetypes with concentrated presence in North American and European petrochemical corridors respectively.
| Leading Market Players |
|---|
| Emerson |
| ABB |
| Endress+Hauser |
| Rosemount |
| Honeywell |
| VEGA Grieshaber |
| KROHNE |
| Magnetrol |
| Siemens |
| Others |
Supply Flow & Price Mechanics
IEC 61508 SIL certification gates supplier qualification and price differentiation simultaneously in radar level transmitter procurement. German chemical processors and US Gulf Coast refiners pay premiums for certified 80 GHz FMCW units while non-certified pulsed radar suppliers compete on hardware margins in Asian bulk solids applications.
Pricing Analysis
Certification level creates the primary spread between premium and commodity tiers in this market. Three-tier pricing structure across SIL-certified premium, ATEX-compliant standard, and non-certified economy levels dominates project contracting. Pricing pressure stems from semiconductor input volatility in RF components, with gallium arsenide wafer costs compressing margins on 80 GHz units. EPC contractors in China's Yangtze Delta exhibit highest price sensitivity, demanding unbundled hardware procurement separate from calibration services.
Supply Chain Analysis
Inventory lead times for 80 GHz signal processing chips stretch procurement cycles beyond mechanical instrument alternatives. Manufacturing concentrates in Germany, the United States, and China, with domestic production aligning to regional certification requirements. Gallium arsenide and silicon germanium wafers draw from telecommunications RF component supply chains, creating cross-industry demand competition. Single-source vulnerability sits with specialized 80 GHz semiconductor foundries. Distribution runs through EPC contractors and direct instrument vendor relationships in developed markets, with state-owned enterprise tenders dominating Chinese procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among EPC contractors and state-owned petrochemical enterprises, fragmenting traditional supplier-direct relationships. Consolidation among Gulf Coast refinery operators and Yangtze Delta chemical groups enables volume aggregation and unbundled service procurement.
For Market Incumbents: Fortify calibration service density as the primary retention mechanism against emerging low-cost hardware suppliers. Expand in-country certification laboratory footprints to match SAMR and BIS localization requirements. Vertical integration into 80 GHz semiconductor sourcing reduces exposure to telecommunications demand cycles. Defensive R&D investment should target edge computing integration for digital twin compatibility. For New Entrants and Emerging Players: Differentiate on application-specific engineering depth rather than competing head-to-head with full-line automation vendors. Target India's Gujarat coast refinery corridor where BIS certification creates first-mover windows for qualified suppliers. Penetrate food and beverage automation as the fastest-expanding greenfield segment with less entrenched incumbent relationships. Pursue direct calibration service contracts with EPC contractors as the primary go-to-market channel. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across 80 GHz FMCW manufacturing as cleanroom fabrication requirements deepen. Long-term viability favors suppliers with captive calibration networks and multi-regional certification portfolios. Acquisition target archetype: mid-market specialists with dense European service footprints and pending IECEx qualification for Middle East expansion. Monitor semiconductor foundry capacity allocation to RF components as the critical inflection signal for margin trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Expansion | Dense service coverage in Germany and coastal China locks in chemical processor loyalty against hardware-only competitors. |
| 80 GHz Signal Processing Licensing | Technology partnerships with RF semiconductor specialists accelerate FMCW product development without captive fab investment. |
| Digital Twin Platform Integration | OPC UA protocol compatibility captures premium positioning among petrochemical operators deploying predictive maintenance. |
| Multi-Regional Certification Investment | Parallel ATEX, IECEx, and SAMR qualification opens procurement access to European, Middle Eastern, and Chinese tenders simultaneously. |
| Backward Integration into RF Components | In-house gallium arsenide sourcing insulates margin structure from telecommunications demand volatility. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC instrument division filings, and hazardous chemical facility regulatory databases. Primary interviews engaged plant engineers at German Ruhr basin chemical processors, procurement leads at US Gulf Coast refineries, and calibration service technicians across China's Yangtze Delta manufacturing belt. Secondary validation drew from EPA LDAR enforcement records, SAMR GB standard implementation notices, and IEC 61508 certification registries. Bottom-up project pipeline tracking triangulates against top-down instrumentation market sizing.
Segmentation dimensions modeled include technology platform, end-use industry vertical, installation configuration, and regional regulatory cluster across the projection horizon. CAGRs derive from unit shipment trajectories by technology tier and average selling price evolution by certification level. Industry-specific forecast inputs incorporate petrochemical capacity expansion timelines and hazardous chemical facility upgrade cycles under SAMR and EPA mandates.
The analysis sits within stated boundaries; outcomes outside sustained EPA enforcement intensity or accelerated SAMR implementation would require recalibration. Forecasts reflect documented assumptions regarding semiconductor supply availability and calibration technician labor pool expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Wireless IoT Sensors Market
Sensors and Controls
Europe Acoustic Sensors Market
Sensors and Controls
Hydrogen Monitor Market
Sensors and Controls
Inertial Sensors Market
Sensors and Controls
Sensor Based Sorting System Market
Sensors and Controls
Pressure Transducer Market
Sensors and Controls
Differential Pressure Sensor Market
Sensors and Controls
Thermography Condition Monitoring Equipment Market
Sensors and Controls
Global Refrigeration Leak Detector Market
Sensors and Controls
Air Quality Monitoring System Market
Sensors and Controls
Rain Sensors Market
Sensors and Controls
Pressure Transmitter and Transducer Market
Sensors and Controls
Connected Sensors Market
Sensors and Controls
Fluid Sensors Market
Sensors and Controls
Global PH Sensor Market
Sensors and Controls
Smart Control Socket Market