
 Magnetometer Market | 2026-2036
Magnetometer Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetometer Market Intelligence
The strategic imperative for securing critical raw materials, as outlined in frameworks like the EU Green Deal, is restructuring demand for advanced geophysical survey equipment. Honeywell International Inc. leverages its extensive aerospace portfolio to integrate magnetometers into sophisticated avionics and guidance systems. Lockheed Martin Corporation dominates the defense segment with specialized sensor arrays for maritime and aerial surveillance platforms. In a different niche, Geometrics, Inc. specializes in high-resolution instruments for archaeological and unexploded ordnance (UXO) detection.
A magnetometer is an instrument designed to measure the vector or scalar properties of magnetic fields, with sensitivity often specified in picoteslas (pT) for high-precision models. These devices are critical for applications ranging from compassing and navigation to detecting subtle magnetic anomalies in geophysical surveys and medical diagnostics. Fluxgate magnetometers maintain a significant share due to their robustness in navigation and subsea exploration. Concurrently, MEMS-based Hall effect sensors are expanding rapidly, driven by their cost-effectiveness and scalability for integration into automotive systems and consumer electronics.
Product qualification is governed by stringent standards, including FAA airworthiness directives for avionics systems in the United States and CE marking requirements in Europe for electronic components. International standards such as ISO 9001 influence manufacturing quality, while export controls on dual-use quantum technologies also shape market access. Stakeholder success depends on navigating the technology transition from traditional electromagnetic sensors toward emerging quantum-based systems with superior sensitivity.
Market Dynamics
The central force shaping the magnetometer market is the bifurcation of technology paths. Miniaturization driven by MEMS technology enables mass-market adoption in consumer goods, while parallel development of quantum sensors pushes performance boundaries for niche scientific and defense applications.
Growth Catalysts
- Strategic Resource Initiatives:Frameworks like the EU Green Deal, aimed at securing critical raw materials, are stimulating demand for advanced magnetometers used in large-scale geophysical exploration and mineral prospecting.
- MEMS Proliferation:The widespread integration of Micro-Electro-Mechanical Systems (MEMS) technology allows for the cost-effective, high-volume production of compact magnetometers for automotive and consumer electronics.
- Space Exploration Investment:National space programs, particularly in the United States and China, require ultra-reliable, high-precision magnetometers for satellite attitude control, navigation, and planetary science missions.
Market Restraints
- Input Material Volatility:Manufacturing of high-performance magnetometers often relies on specific rare-earth elements, creating vulnerability to supply chain disruptions and price fluctuations concentrated in specific geographies.
- High-Temperature Performance Limits:Certain magnetometer technologies, including some Hall effect sensors, exhibit performance degradation and accuracy drift when subjected to the extreme temperatures common in automotive and industrial environments.
- Cost of Advanced Systems:The substantial initial investment required for quantum magnetometers and their associated cryogenic cooling systems restricts their use to well-funded government research and specialized defense applications.
Strategic Opportunities
- Medical Imaging Expansion:There is a significant opportunity for integrating highly sensitive magnetometers into medical devices, particularly for magnetoencephalography (MEG) systems used in non-invasive neurological diagnostics.
- Precision Agriculture:Underpenetrated applications in precision agriculture, such as using magnetometers for detailed soil mapping to optimize irrigation and fertilization, present a new growth vector in countries like Brazil.
- Autonomous Systems Navigation:The convergence of magnetometers with inertial measurement units (IMUs) provides a pathway for creating robust navigation solutions for drones and autonomous vehicles in GPS-denied areas.
Industry Challenges
- Signal Integrity and Integration:Integrating sensitive magnetic sensors into electronically noisy platforms like electric vehicles or industrial machinery without significant electromagnetic interference (EMI) requires complex shielding and design expertise.
- Stringent Certification Cycles:Product qualification for safety-critical sectors, especially aerospace, involves navigating long and costly certification processes such as FAA airworthiness directives in the United States.
- Specialized Talent Scarcity:A shortage of physicists and engineers with deep expertise in quantum sensing, magnetic materials science, and advanced signal processing algorithms constrains new product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetometer Market |
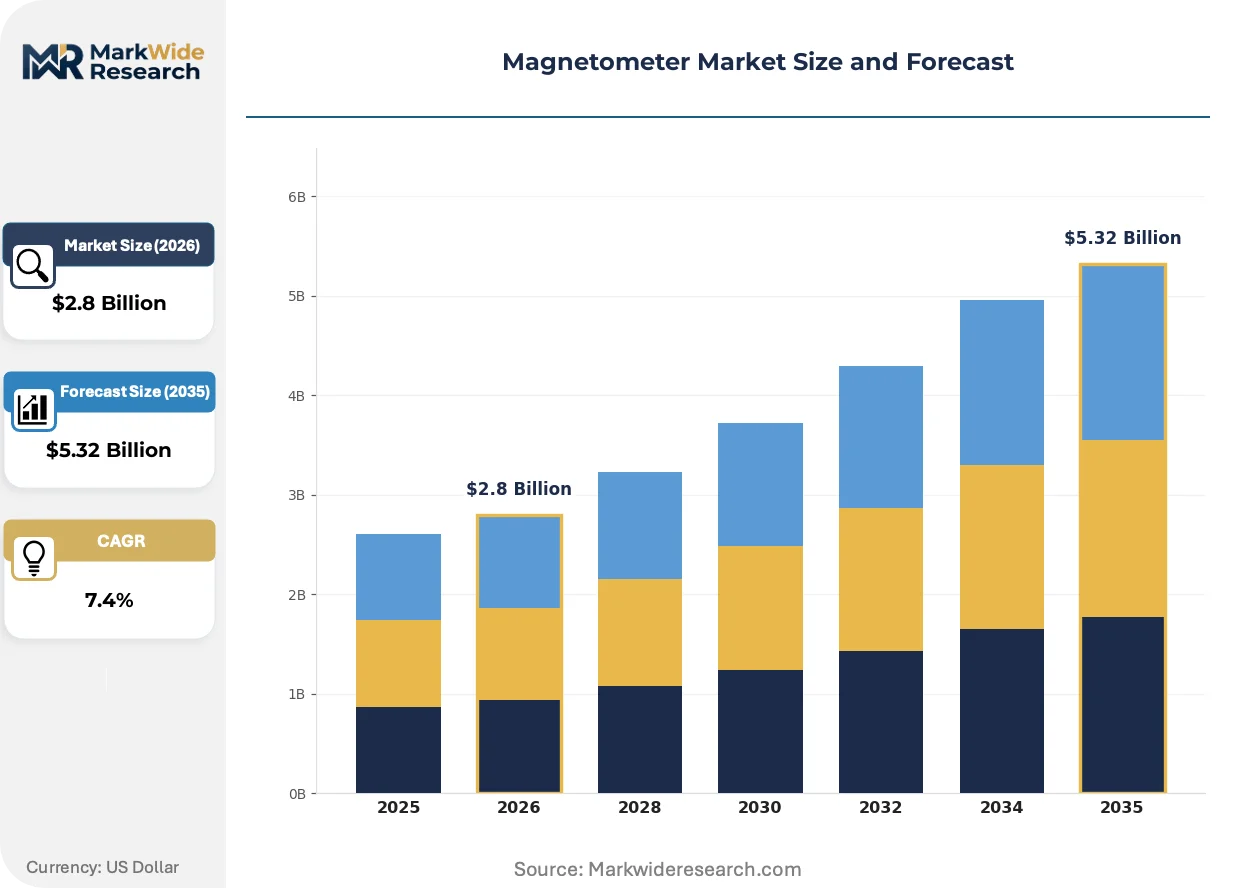
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.32 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Magnetometers, Atomic Magnetometers, Fluxgate Magnetometers, Hall Effect Sensors End User: Aerospace, Automotive, Healthcare, Energy Technology: Quantum Technology, MEMS, Semiconductor, Electromagnetic Application: Geophysical Surveys, Navigation, Subsea Exploration, Magnetic Field Mapping |
| Companies Covered | Robert Bosch GmbH, Lockheed Martin Corporation, Honeywell International Inc., Lake Shore Cryotronics, Inc., FOERSTER Holding GmbH, Geometrics, Inc., Infineon Technologies AG, Marine Magnetics Corp., Bartington Instruments Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetometer Market Strategic Shifts & Innovations
Miniaturization and extreme sensitivity define the two opposing poles of innovation. The market is reshaping around the split between high-volume, cost-optimized sensors for ubiquitous applications and ultra-high-performance systems for scientific and strategic intelligence gathering.
Quantum magnetometers, which measure the spin properties of atoms, provide unprecedented sensitivity for detecting minute magnetic field variations. Adoption is currently focused within geophysical research institutes and defense organizations for applications like unexploded ordnance (UXO) detection and anti-submarine warfare. This advanced technology is overtaking traditional proton precession sensors in high-end applications where ultimate detection capability is the primary requirement.
Export control regimes, particularly from the United States and within the European Union, are increasingly applied to dual-use quantum technologies that include high-sensitivity magnetometers. These regulations restrict the sale of advanced sensors to certain state and non-state actors, impacting international academic research and commercial sales channels. Aerospace and defense manufacturers are most affected, forcing them to implement stricter compliance and re-evaluate global partnerships.
A demand-side shift is occurring where large-volume buyers in the automotive sector prioritize sensor fusion capabilities over the performance of a standalone magnetometer. This disrupts the traditional component sales model, favoring suppliers who offer integrated inertial measurement units (IMUs) that combine magnetometers with accelerometers and gyroscopes on a single chip. This trend is most apparent in the supply chains for advanced driver-assistance systems (ADAS) in Germany and South Korea.
Magnetometer Market Segmentation
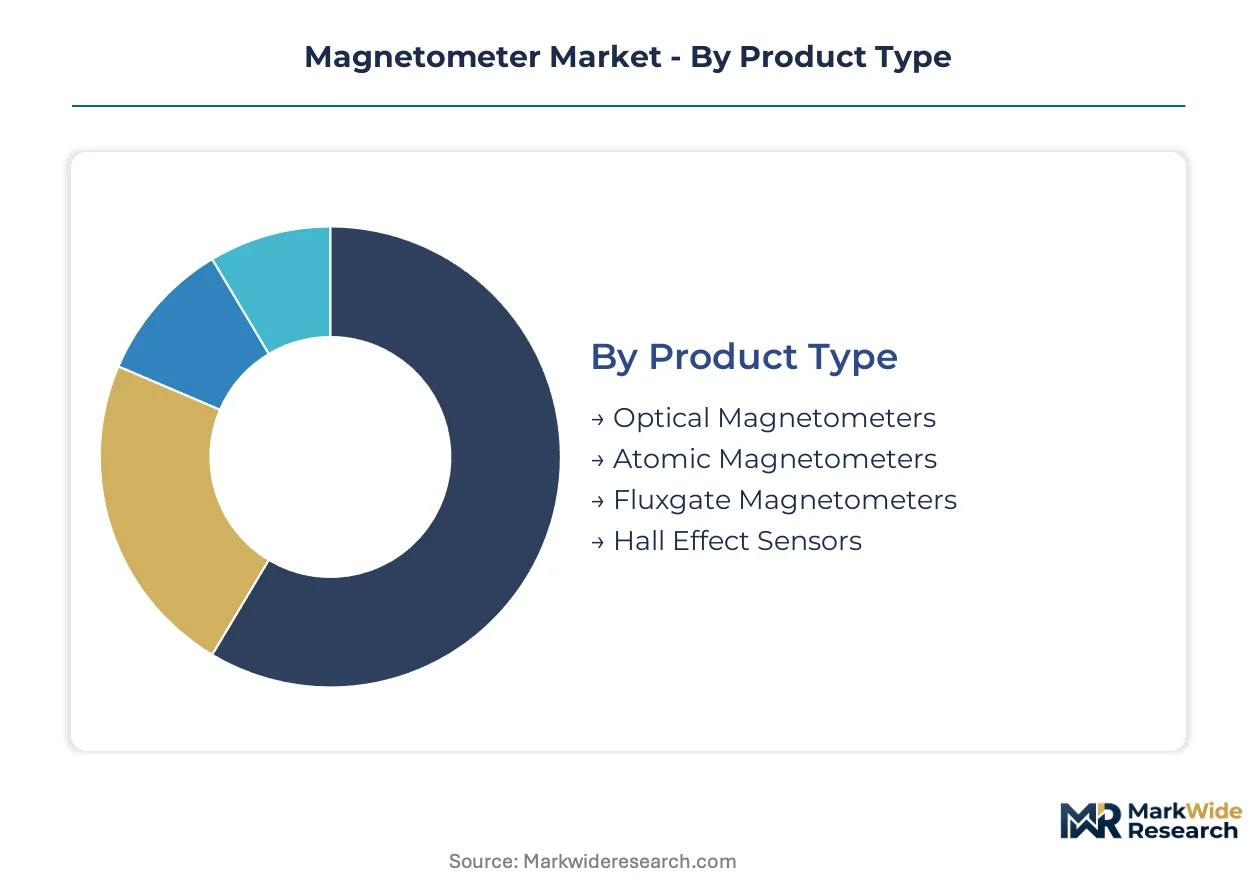
The magnetometer market segments reflect diverse operational demands and technological specifications driving product adoption. Understanding these distinct categories provides clarity on where innovation is concentrating and how various end-user requirements shape product development. This granular view helps stakeholders identify specific growth vectors and competitive landscapes within the broader market.
Product Type:
Buyer-decision drivers such as sensitivity, cost, and form factor significantly influence the selection of magnetometer product types across various industries.
- Optical Magnetometers:These devices leverage light-atom interaction for high sensitivity, finding use in advanced scientific research.
- Atomic Magnetometers:Offering unparalleled precision through quantum properties, these are critical for high-end medical diagnostics.
- Fluxgate Magnetometers:These sensors measure magnetic field strength via a ferromagnetic core, delivering robust performance suitable for demanding environments. Demand is strong in navigation systems and subsea exploration, where reliability in harsh conditions is paramount.
- Hall Effect Sensors:Solid-state devices generating voltage proportional to magnetic fields, known for their compact size and cost-efficiency. Their widespread integration into automotive systems and consumer electronics is a primary growth driver.
Fluxgate Magnetometers lead on scale within industrial applications; Hall Effect Sensors represent the fastest-growing trajectory in consumer and automotive segments.
End User:
Application requirements dictate the specific type and performance characteristics of magnetometers adopted by different end-user sectors.
- Aerospace:This sector requires ultra-reliable, high-precision magnetometers for satellite attitude control, navigation, and avionics systems. The United States space programs are significant consumers of these advanced sensors.
- Automotive:Magnetometers are integrated into advanced driver-assistance systems (ADAS) and electric vehicles for navigation and current sensing. Demand is concentrating in Germany and South Korea for sensor fusion capabilities.
- Healthcare:Medical diagnostics utilize magnetometers, particularly for magnetoencephalography (MEG) systems, enabling non-invasive neurological assessments.
- Energy:Geophysical surveys in the energy sector employ magnetometers for oil and gas exploration, mapping subsurface geological structures.
Specific operational demands define the usage profile for each end-user segment, with safety and reliability paramount in Aerospace and Automotive.
Technology:
Performance benchmarks differentiate technology choices, influencing adoption rates across various applications requiring magnetic field measurement.
- Quantum Technology:These advanced systems measure the spin properties of atoms, providing unprecedented sensitivity for minute magnetic field variations. Adoption is concentrated in defense organizations and geophysical research institutes for unexploded ordnance (UXO) detection.
- MEMS:Micro-Electro-Mechanical Systems (MEMS) technology enables the miniaturization and cost-effective production of compact magnetometers. Its widespread integration facilitates mass-market adoption in consumer goods and automotive applications.
- Semiconductor:Magnetometers based on semiconductor technology offer a balance of performance and cost, suitable for various industrial controls.
- Electromagnetic:Traditional electromagnetic sensors provide foundational magnetic field detection, often used in less demanding industrial settings.
Technological advancements continue to redefine capabilities within each segment, pushing boundaries for sensitivity and miniaturization.
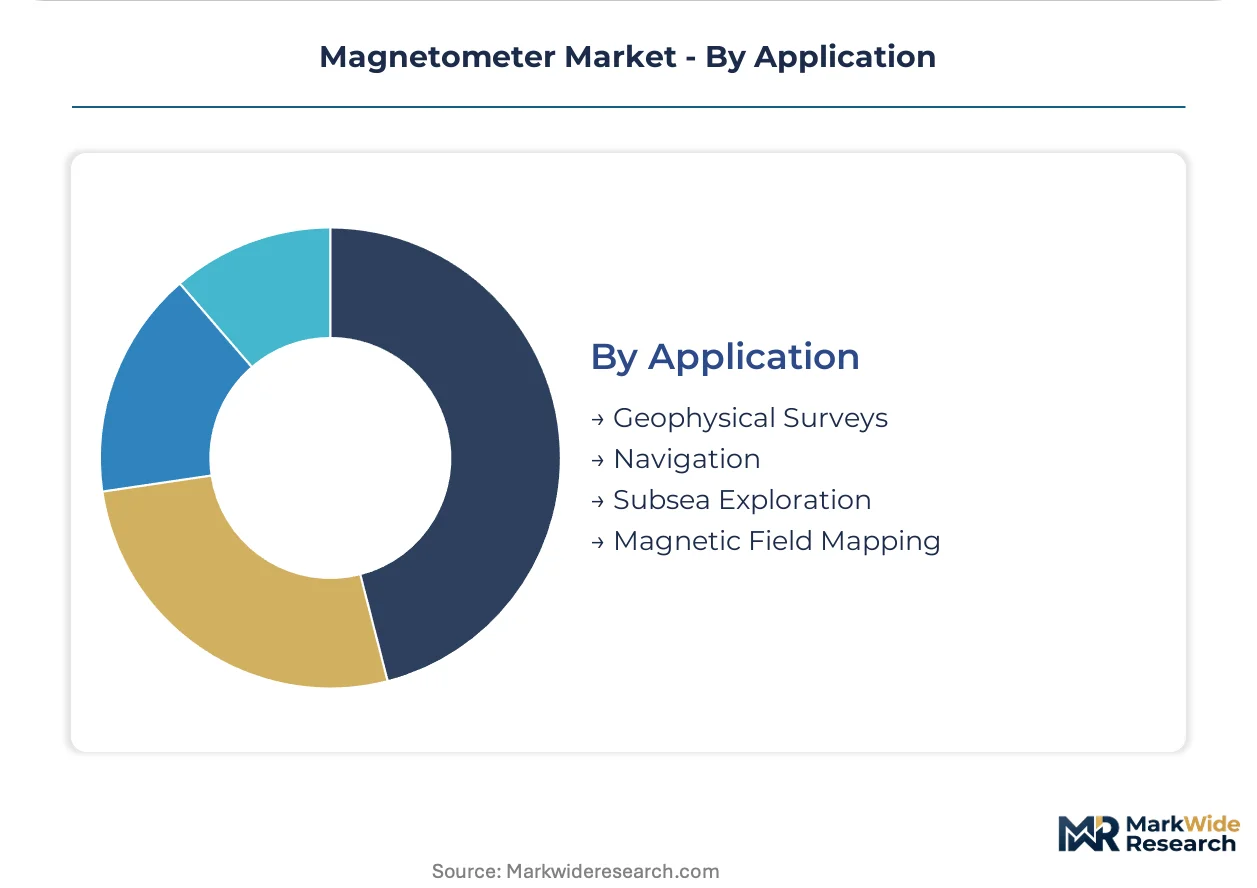
Application:
The specific task environment shapes the selection of magnetometer applications, driving demand for tailored solutions with precise performance characteristics.
- Geophysical Surveys:Magnetometers detect subtle magnetic anomalies in the Earth's crust, critical for mineral prospecting and archaeological investigations. The EU Green Deal initiatives are stimulating demand for advanced geophysical survey equipment.
- Navigation:These devices provide essential directional information and attitude control for aircraft, ships, and autonomous systems, especially in GPS-denied environments. The aerospace sector extensively utilizes magnetometers for precise positioning.
- Subsea Exploration:Magnetometers assist in underwater mapping, detecting submerged objects, and surveying pipelines in challenging marine conditions.
- Magnetic Field Mapping:This application involves creating detailed maps of magnetic fields for various purposes, including quality control and material characterization.
Diverse operational needs create distinct demand patterns across these applications, with Navigation and Geophysical Surveys exhibiting critical strategic importance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The magnetometer market's foundational development and widespread adoption trace back to military and scientific applications, notably in the United States and Europe. Innovation has consistently pushed performance boundaries, driving both miniaturization for mass markets and extreme sensitivity for specialized uses. Demand for these sensors now extends across diverse sectors, including automotive, consumer electronics, and space exploration, with several countries demonstrating concentrated growth.
United States
Aerospace and defense applications drive significant demand for high-precision magnetometers in the United States. FAA airworthiness directives mandate rigorous qualification for avionics systems integrating these sensors. Major aerospace hubs like Seattle and Wichita concentrate manufacturing and R&D for advanced navigation and attitude control systems.
Germany
Germany's robust automotive industry fuels demand for MEMS-based Hall effect sensors in ADAS and electric vehicles. CE marking requirements ensure product safety and performance for electronic components sold within the European Union. Munich and Stuttgart serve as key centers for automotive electronics innovation and sensor integration.
China
National space programs in China require ultra-reliable, high-precision magnetometers for satellite attitude control and planetary science missions. Dual-use quantum technologies face export controls, shaping domestic development and supply chains. Beijing and Shanghai host significant government-backed research institutes and manufacturing facilities for advanced sensors.
South Korea
South Korea exhibits strong demand for magnetometers in its advanced automotive and consumer electronics sectors. Integration into ADAS systems for sensor fusion capabilities is a primary driver for local manufacturers. Seoul and Ulsan are major industrial centers for automotive production and advanced electronics manufacturing.
Brazil
Precision agriculture applications, such as detailed soil mapping, represent an emerging growth vector for magnetometers in Brazil. ANVISA regulations govern the approval of medical devices, including those potentially incorporating magnetometers for diagnostic purposes. São Paulo and Minas Gerais are agricultural powerhouses exploring advanced farming technologies.
Magnetometer Market Key Industry Players
Premium-margin players sit above commodity-margin players across the performance and application spectrum for magnetometers. The market structure is tiered, with specialized high-performance providers at one end and mass-market component suppliers at the other. Strategic archetypes include diversified industrial conglomerates, defense contractors, and niche sensor specialists. Dominant competitive moves involve technology licensing and strategic partnerships to integrate sensor fusion capabilities.
On the premium-tier vector, Lockheed Martin Corporation exemplifies a defense contractor archetype, focusing on specialized sensor arrays for surveillance platforms. Honeywell International Inc. represents a diversified industrial conglomerate, integrating magnetometers into sophisticated avionics and guidance systems. Infineon Technologies AG occupies a position within the semiconductor and automotive segments, focusing on cost-effective, scalable Hall effect sensors for mass-market integration.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Lockheed Martin Corporation |
| Honeywell International Inc. |
| Lake Shore Cryotronics, Inc. |
| FOERSTER Holding GmbH |
| Geometrics, Inc. |
| Infineon Technologies AG |
| Marine Magnetics Corp. |
| Bartington Instruments Ltd. |
| Others |
Cost & Logistics Intelligence
Rare-earth elements, critical for high-performance magnetometers, influence upstream component manufacturing costs and subsequently impact downstream pricing for specialized defense and scientific instruments. This material dependency creates vulnerability to supply chain disruptions and price fluctuations across the market.
Pricing Analysis
Value-based pricing differentiates magnetometer offerings, with premium tiers commanding higher prices for superior sensitivity and certified performance. Certification levels, such as FAA airworthiness directives for aerospace applications, act as significant price differentiation drivers. Volume scale for automotive integration also impacts unit costs. Pricing pressure stems from the mass-market proliferation of cost-effective MEMS-based sensors. Consumer electronics and automotive segments exhibit the highest price sensitivity, while defense and space exploration prioritize performance over cost.
Supply Chain Analysis
Domestic content mandates in defense and aerospace sectors reshape sourcing for high-precision magnetometers, particularly in the United States. The supply chain draws heavily on rare-earth elements, often concentrated in China, and specialized MEMS fabrication capabilities from countries like Germany and South Korea. Vulnerability to supply chain disruptions, particularly for rare-earth elements, poses a structural risk. Distribution runs through direct-to-OEM channels for aerospace and automotive, with specialized distributors serving scientific and geophysical exploration segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The magnetometer market presents a late-cycle quality story, driven by a demand-shift toward premium specifications in quantum sensing and highly integrated solutions for autonomous systems.
For Market Incumbents:
Acquire quantum sensing IP and specialized talent to maintain a competitive edge against emerging technologies. Deepen vertical integration into critical raw material sourcing to mitigate input material volatility. Invest heavily in certification processes for next-generation avionics systems, safeguarding market access against stringent FAA airworthiness directives. Strategic partnerships with automotive Tier 1 suppliers can accelerate integrated sensor fusion development.
For New Entrants and Emerging Players:
Online technical support platforms and developer kits can lower barriers to entry for niche applications. Target underpenetrated applications like precision agriculture in Brazil, offering integrated soil mapping solutions. Focus on developing cost-effective, easily integratable MEMS-based solutions for industrial IoT and emerging autonomous systems. A go-to-market angle emphasizing rapid prototyping and customization for specific industrial controls can attract early adopters.
For Investors and Strategic Acquirers:
Consolidation pressure builds where specialized quantum expertise remains fragmented among research institutes and smaller firms. Long-term viability hinges on companies that can bridge the gap between high-performance quantum sensors and scalable manufacturing. Acquisition targets should include firms with proprietary quantum technology, robust MEMS fabrication capabilities, or strong positions in critical end-user certification pathways. A signal to watch is the broader commercialization rate of quantum magnetometers beyond defense and research.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Quantum Sensing R&D | Advances detection capabilities for defense and medical diagnostics, securing future high-margin segments. |
| Secure Rare-Earth Supply Agreements | Mitigates input material volatility and ensures stable production for high-performance magnetometers. |
| Expand MEMS Production Capacity | Addresses growing demand from automotive and consumer electronics sectors with cost-effective sensors. |
| Form Sensor Fusion Partnerships | Integrates magnetometers with IMUs for robust navigation solutions in autonomous systems. |
| Obtain Aerospace Certifications | Ensures compliance with FAA airworthiness directives, maintaining market access in critical avionics. |
Research Approach
Direct dialogue with aerospace engineers, automotive ADAS developers, geophysical survey operators, and quantum physicists provided qualitative grounding for the market analysis. This primary research was complemented by secondary validation from FAA directives, CE marking guidelines, ISO standards, and national space program reports. Bottom-up and top-down triangulation ensured comprehensive data coverage and accuracy.
The quantitative model projects market volume and value across the analysis window, utilizing an analytical framework that integrates historical trends with future growth drivers. Segmentation dimensions modeled included product type, end-user, technology, application, and geographic region. Compound annual growth rates were derived from a multi-factor analysis considering MEMS integration rates and space exploration budgets.
The model assumes a particular technology adoption path; alternative pathways for quantum magnetometers would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and the continued availability of critical raw materials. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
NB-IoT Smart Meter Market
Sensors and Controls
China Digital Thermometer Market
Sensors and Controls
Absolute Encoders Market
Sensors and Controls
Force Sensor Market
Sensors and Controls
HVAC Sensor Market
Sensors and Controls
Light Detection and Ranging (Lidar) Market
Sensors and Controls
Asia Pacific Lidar Market
Sensors and Controls
Infrared Sensors Market
Sensors and Controls
Global Multi-Turn Potentiometer Market
Sensors and Controls
Meteorological Devices Market
Sensors and Controls
Europe Digital Thermometer Market
Sensors and Controls
Temperature Monitoring Devices Market
Sensors and Controls
Motorcycle Sensors Market
Sensors and Controls
Pressure Transducer Market
Sensors and Controls
Asia Pacific Safety I/O Modules Market
Sensors and Controls
Instrumented Load Shackle Market