
 Digital Automation Temperature Regulator Market | 2026-2036
Digital Automation Temperature Regulator Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Automation Temperature Regulator Market Insights
Software-defined calibration services is expanding the recurring revenue base for temperature control vendors. Siemens AG leverages its industrial automation platform to bundle predictive maintenance subscriptions with hardware deployments. Honeywell International Inc. sustains competitive positioning through deep integration of building management software across commercial portfolios. Emerson Electric Co. anchors its presence in process industries with specialized thermal management algorithms for refining applications.
A digital automation temperature regulator is an electromechanical or solid-state device that measures thermal conditions through RTD, thermocouple, or semiconductor sensors and modulates heating or cooling output to maintain setpoint accuracy within 0.1°C to 2°C tolerance bands. Its primary purpose is to replace manual thermostat adjustment with closed-loop digital control, reducing energy waste and preventing thermal damage in sensitive manufacturing, storage, and occupied environments. Smart thermostats command the largest installed base among product types, though industrial monitors capture disproportionate margin pools due to certification requirements and integration complexity. Wi-Fi-enabled units lead residential and light commercial penetration, while wired architectures dominate pharmaceutical and food processing facilities where electromagnetic interference resilience and deterministic response times override wireless convenience.
The EPA regulates refrigerant management and energy efficiency standards for HVAC-controlling devices in the United States, while the EU F-Gas Regulation and Ecodesign Directive collectively mandate lower-global-warming-potential systems and minimum performance thresholds across European deployments. These frameworks elevate compliance costs for basic regulator models while creating certified-product premiums for manufacturers with in-house testing and documentation capabilities. Stakeholders must monitor evolving refrigerant phase-down schedules and sensor accuracy mandates to anticipate which product configurations will retain market access.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant options and forcing manufacturers to redesign sensor-calibration architectures for lower-global-warming-potential compatibility, reshaping R&D allocation across the supplier base.
Growth Catalysts
- Pharmaceutical Cold Chain Expansion:Biologics manufacturing clusters in Germany and Switzerland are mandating precision temperature control for batch consistency, pulling demand for certified industrial monitors with deterministic response protocols.
- REACH and RoHS Compliance Premiums:European material restrictions are disqualifying basic regulator models from tender eligibility, creating certified-product price tiers that reward in-house testing capabilities.
- Sensor Fusion Architectures:RTD-thermocouple hybrid designs are enabling single-device coverage across wider temperature bands, reducing hardware count in multi-zone food processing facilities.
Market Restraints
- Semiconductor Input Volatility:MEMS temperature sensor foundry capacity concentrates in Taiwan, exposing lead times to geopolitical friction and foundry allocation decisions.
- Calibration Labor Bottleneck:ISO 17025-accredited technician scarcity extends deployment timelines for pharmaceutical installations requiring documented traceability chains.
- Wireless Substitution Ceiling:Electromagnetic interference resilience requirements in refining and steel processing prevent Wi-Fi-enabled units from displacing wired architectures in high-margin industrial segments.
Strategic Opportunities
- India Cold Storage Modernization:FSSAI enforcement of temperature logging for perishable distribution is creating first-time demand for digital regulators in fragmented agricultural supply chains.
- Software-Defined Calibration Subscriptions:Cloud-based drift correction and predictive maintenance bundling is opening recurring revenue streams previously captured by third-party service providers.
- CE Marking Fast-Track Services:In-house notified body relationships and pre-certified modular designs are compressing time-to-market for mid-cap manufacturers lacking dedicated compliance teams.
Industry Challenges
- Legacy System Integration Complexity:Brownfield pharmaceutical facilities running 4-20mA analog loops require protocol gateway investments that inflate project scope and commissioning timelines.
- Cross-Border Certification Fragmentation:Divergent electromagnetic compatibility test suites between FDA, EMA, and PMDA jurisdictions force redundant validation cycles for multi-region suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Automation Temperature Regulator Market |
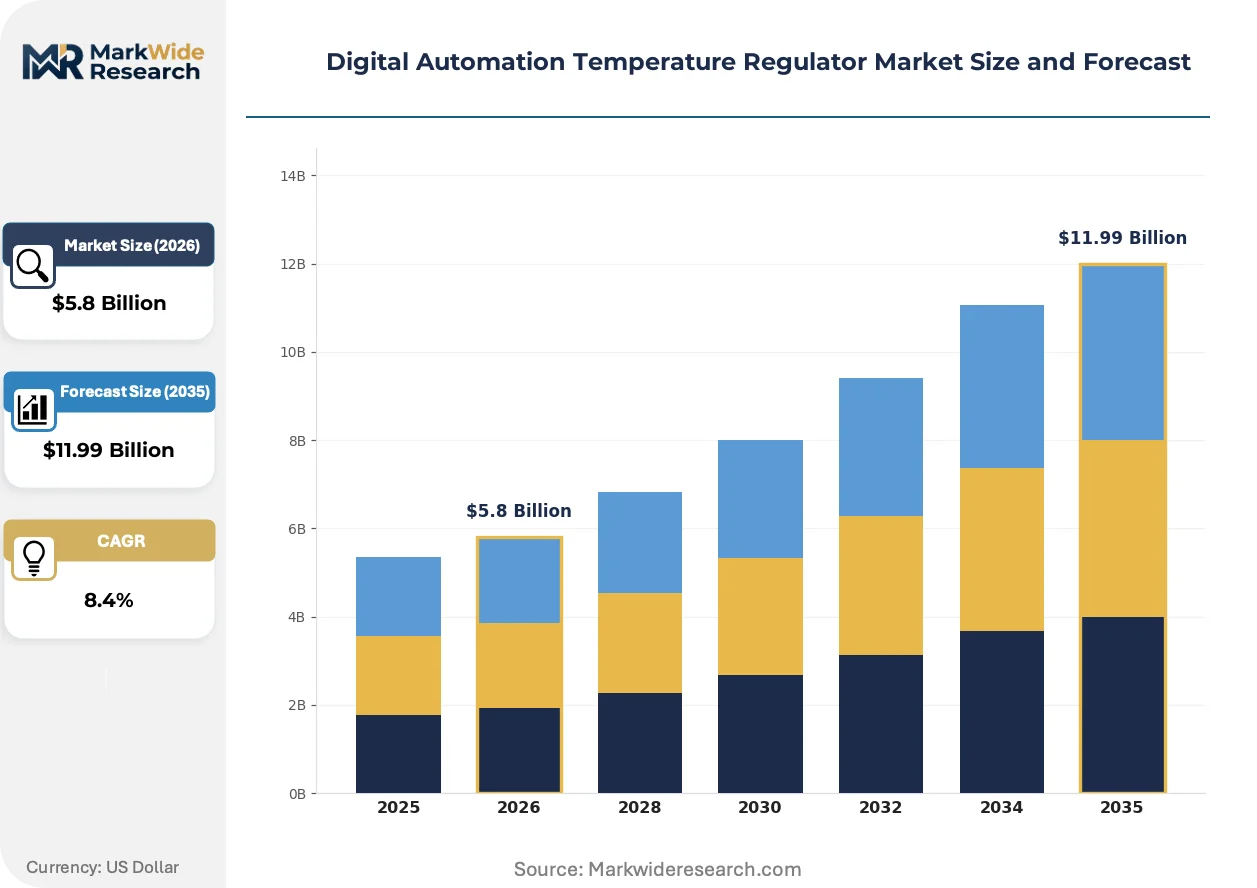
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Thermostats, Programmable Regulators, Commercial Controllers, Industrial Monitors Technology: Wi-Fi, Zigbee, Bluetooth, Wired Application: HVAC Systems, Industrial Processes, Home Automation, Cold Chain Management End User: Manufacturers, Retail Stores, Residential Users, Healthcare Facilities |
| Companies Covered | Honeywell International Inc., Siemens AG, TE Connectivity, Analog Devices, Inc., Emerson Electric Co., ABB Ltd., Schneider Electric SE, Texas Instruments Incorporated, Danfoss A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Automation Temperature Regulator Market Trends and Innovations
Edge computing architectures are redistributing control intelligence from centralized building management systems to device-level decision loops, compressing latency and enabling autonomous setpoint adjustments without cloud dependency.
Multi-sensor fusion platforms combining RTD accuracy with thermocouple range are decentralizing thermal monitoring from dedicated control rooms to distributed process nodes. Pharmaceutical lyophilization equipment manufacturers are adopting these architectures to eliminate single points of failure in batch-critical temperature zones. The shift is compressing wiring infrastructure costs while elevating firmware complexity as the primary competitive differentiator.
The EU F-Gas Regulation's hydrofluorocarbon phase-down schedule is mandating refrigerant sensor recalibration protocols for all new HVAC-controlling devices. Equipment manufacturers must now document compatibility with lower-global-warming-potential alternatives to retain CE marking eligibility. Commercial refrigeration OEMs in Germany and France are responding by pre-integrating digital regulators with refrigerant-agnostic pressure-temperature lookup tables.
Buyer consolidation among contract research organizations is compressing vendor qualification timelines and unbundling after-sales service from hardware procurement. Large CROs in Massachusetts and North Carolina are mandating API-accessible temperature logs for direct integration into laboratory information management systems. This pattern is most visible in gene therapy storage applications where audit trail automation overrides upfront hardware cost considerations.
Digital Automation Temperature Regulator Market Segmentation
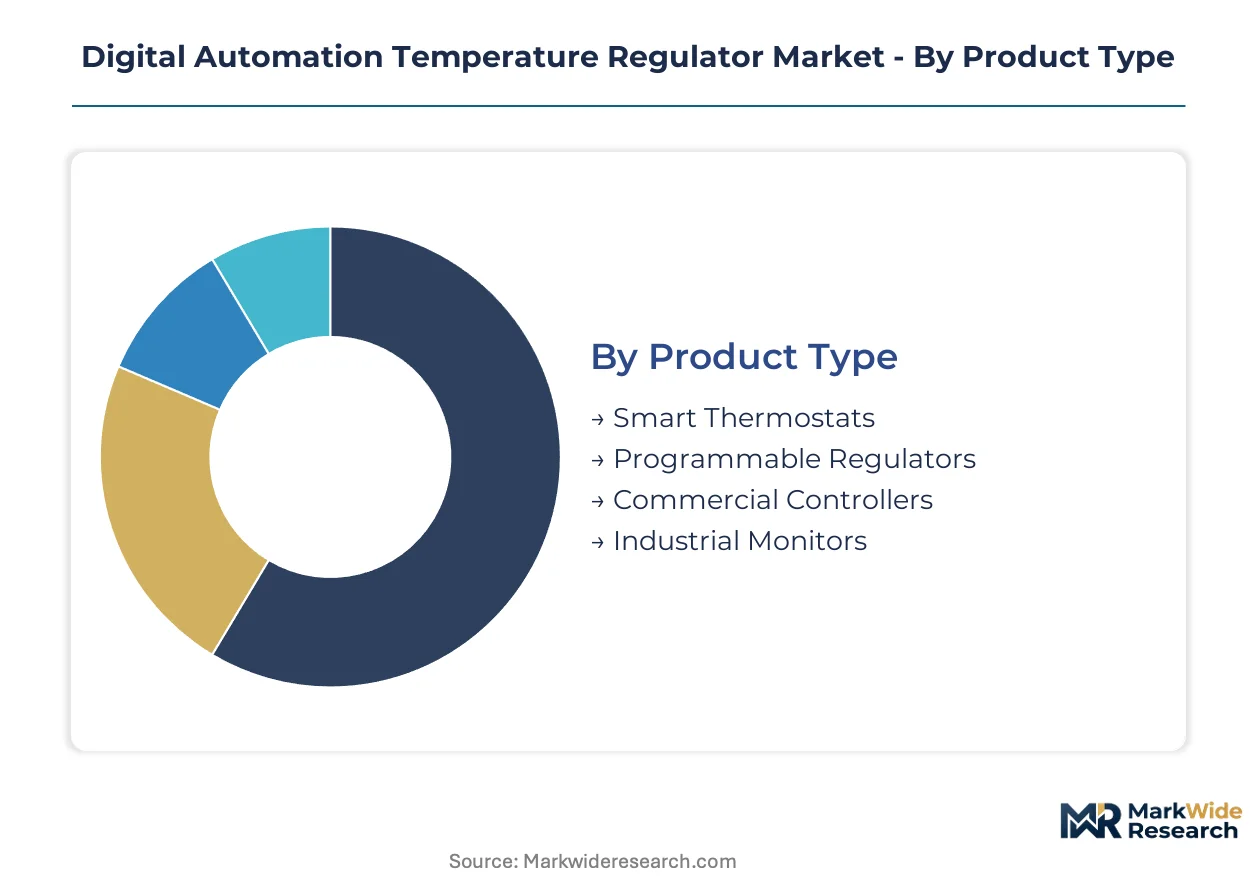
Temperature regulator architectures diverge sharply between mass-market convenience and mission-critical precision. Product configurations, connectivity protocols, deployment contexts, and buyer categories each create distinct margin profiles and compliance obligations.
Product Type:
Volume concentrates in residential-grade devices with slim hardware margins, while premium pools concentrate in certified industrial systems requiring documented calibration chains.
- Smart Thermostats:Wi-Fi-enabled units with touchscreen interfaces and occupancy-sensing algorithms dominate residential replacement cycles. Demand clusters in North American utility rebate programs and European building renovation subsidies, where smartphone integration overrides hardware durability concerns.
- Industrial Monitors:RTD-thermocouple hybrid architectures deliver 0.1°C accuracy with deterministic response protocols for batch-critical pharmaceutical manufacturing. German biologics clusters and Swiss vaccine production facilities mandate these units despite three-year qualification timelines.
- Programmable Regulators:Microcontroller-based units with seven-day scheduling and setback algorithms serve light commercial retrofit markets.
- Commercial Controllers:BACnet-integrated systems manage multi-zone HVAC in office and retail portfolios.
Today's leader: Smart Thermostats. Tomorrow's challenger: Industrial Monitors.
Technology:
Wireless protocols capture consumer mindshare through installation simplicity, yet wired architectures retain industrial dominance where electromagnetic resilience governs specification.
- Wired:4-20mA and Modbus RTU architectures deliver noise immunity and deterministic latency for refining and steel processing applications. Japanese automotive paint shops and German chemical plants specify these exclusively despite 40% higher installed cost.
- Wi-Fi:TCP/IP stacks enable cloud dashboard integration and over-the-air firmware updates for residential and light commercial deployments. Indian smart city initiatives and Brazilian retail chains are expanding first-time penetration through smartphone-centric procurement.
- Zigbee:Mesh networking protocols support battery-powered sensor networks in commercial building retrofits.
- Bluetooth:Low-energy stacks serve point-to-point commissioning and temporary monitoring applications.
Wired architectures command the steepest expansion trajectory in pharmaceutical and food safety certifications.
Application:
Cold chain integrity requirements are elevating sensor density and documentation standards beyond traditional HVAC comfort control.
- Cold Chain Management:Continuous temperature logging with blockchain-anchored audit trails protects perishable pharmaceuticals and gene therapies. US FDA enforcement of distribution documentation and EU Good Distribution Practice mandates are pulling multi-sensor deployments into last-mile logistics.
- Industrial Processes:Lyophilization, polymer extrusion, and semiconductor wafer processing demand cascade control architectures with sub-degree stability. Taiwanese foundries and South Korean battery manufacturers specify redundant sensor loops to eliminate batch scrap.
- HVAC Systems:Comfort control in occupied spaces drives replacement volume through efficiency regulations.
- Home Automation:Voice assistant integration and geofencing features differentiate consumer-grade offerings.
Procurement is shifting toward application-specific compliance bundles rather than generic hardware specifications.
End User:
Buyer sophistication spans from price-sensitive residential consumers to healthcare procurement teams with mandatory quality agreements.
- Healthcare Facilities:Hospital pharmacies and blood banks require ISO 17025-traceable calibration with 21 CFR Part 11 electronic signature compliance. US health system consolidation is compressing vendor qualification to pre-approved lists with multi-year service contracts.
- Manufacturers:Process industries prioritize mean-time-between-failure metrics and spare parts commonality across plant networks. German automotive suppliers and Japanese electronics assemblers standardize on single-vendor platforms to reduce training overhead.
- Residential Users:DIY installation and utility rebate eligibility drive purchase decisions.
- Retail Stores:Multi-site operators balance upfront hardware cost against centralized energy management visibility.
Healthcare procurement is concentrating demand among vendors with dedicated regulatory affairs teams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates pharmaceutical-grade regulator procurement under EU F-Gas mandates, while the United States channels demand through FDA-enforced cold chain documentation requirements for biologics distribution.
Germany
Biologics manufacturing clusters in Bavaria and North Rhine-Westphalia mandate precision temperature control for batch consistency. The EU F-Gas Regulation's hydrofluorocarbon phase-down compresses refrigerant options and forces sensor-recalibration protocol redesigns. Stuttgart-area automotive paint shops specify wired architectures exclusively for electromagnetic interference resilience.
United States
Gene therapy storage applications in Massachusetts and North Carolina pull multi-sensor deployments with API-accessible temperature logs. FDA enforcement of distribution documentation mandates blockchain-anchored audit trails for perishable pharmaceuticals. Contract research organization consolidation in the Research Triangle compresses vendor qualification timelines.
Switzerland
Vaccine production facilities near Basel require ISO 17025-traceable calibration with deterministic response protocols. Swissmedic oversight elevates certification requirements beyond standard CE marking thresholds. The Lake Geneva biotech corridor concentrates demand for redundant sensor loops in lyophilization equipment.
India
FSSAI enforcement of temperature logging for perishable distribution creates first-time demand in fragmented agricultural supply chains. The PLI scheme for cold chain infrastructure accelerates regulator deployment in Maharashtra and Gujarat dairy networks. Bangalore pharmaceutical packaging hubs adopt certified industrial monitors for export compliance.
Japan
Automotive paint shops in Toyota City and semiconductor foundries in Kumamoto specify wired Modbus RTU architectures for deterministic latency. METI energy efficiency standards drive replacement cycles in commercial building portfolios. Yokohama-area battery manufacturers mandate cascade control architectures with sub-degree stability.
Digital Automation Temperature Regulator Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated procurement in pharmaceutical verticals contrasting fragmented residential distribution. Industrial automation conglomerates anchor premium-tier positioning through bundled software subscriptions, while component specialists capture margin pools in sensor-calibration services. Two strategic archetypes dominate: full-stack platform vendors integrating predictive maintenance offerings, and modular hardware suppliers enabling fast-track CE marking. Competitive moves concentrate on M&A for regulatory affairs capabilities and capacity expansion in ISO 17025-accredited calibration laboratories.
Among diversified industrial technology conglomerates, Honeywell International Inc., Siemens AG, and Emerson Electric Co. exemplify platform-centric positioning. Honeywell leverages building management software integration across commercial portfolios. Siemens anchors its presence through industrial automation platform bundling. Emerson sustains process industry relationships through specialized thermal management algorithm deployment. Each occupies a distinct vector within the premium-mid-economy tiering structure.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Siemens AG |
| TE Connectivity |
| Analog Devices, Inc. |
| Emerson Electric Co. |
| ABB Ltd. |
| Schneider Electric SE |
| Texas Instruments Incorporated |
| Danfoss A/S |
| Others |
Pricing and Supply Chain Analysis
Captive sensor-calibration capabilities in Germany and Switzerland anchor premium pricing power for industrial-grade regulators, as in-house ISO 17025-accredited laboratories eliminate third-party service dependencies and compress buyer qualification timelines for pharmaceutical cold chain deployments.
Pricing Analysis
Capacity additions in Taiwan and South Korea for MEMS temperature sensors are reshaping price floors for mid-tier programmable regulators, though pharmaceutical-grade industrial monitors retain steep premiums through deterministic response certification. Pricing stratifies across premium-certified, standard-compliant, and economy unbranded tiers, with EU F-Gas Regulation compliance costs driving the widest spreads. Cost compression in residential smart thermostats intensifies as Chinese contract manufacturers scale Wi-Fi module production. Residential utility rebate programs exhibit highest price sensitivity, while German biologics manufacturers prioritize calibration traceability over unit cost.
Supply Chain Analysis
India's PLI scheme for cold chain infrastructure and domestic-content preferences in Maharashtra dairy networks are reshaping sourcing patterns for entry-level commercial controllers. Semiconductor foundry output concentrates in Taiwan, South Korea, and Japan, while precision RTD element fabrication centers on Germany and Switzerland. Raw material dependencies span silicon wafers, platinum-rhodium thermocouple wire, and refrigerant-agnostic pressure sensors. Single-source vulnerability in Taiwanese MEMS foundry capacity exposes lead times to geopolitical friction. Distribution runs through industrial automation distributors for pharmaceutical verticals and big-box retail for residential replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Digital Automation Temperature Regulator Market compounds steadily as regulatory mandates for cold chain documentation harden into permanent compliance infrastructure across pharmaceutical distribution networks.
For Market Incumbents: Anticipate margin compression in residential Wi-Fi thermostats from Chinese contract manufacturer vertical integration into module production. Defend position by deepening captive calibration laboratory capacity in Basel and Stuttgart corridors, and by bundling predictive maintenance subscriptions that lock in multi-year pharmaceutical service contracts against hardware commoditization. For New Entrants and Emerging Players: Fragmented agricultural cold storage operators in India's Gujarat and Maharashtra dairy networks represent the most penetrable buyer archetype, as FSSAI enforcement creates first-time digital regulator demand without entrenched vendor relationships. Pursue white-label partnerships with established industrial automation distributors rather than direct field sales, and emphasize cloud-based temperature logging with smartphone dashboard integration to bypass legacy building management system integration complexity. For Investors and Strategic Acquirers: Roll-up economics work for regional calibration service specialists because pharmaceutical buyer consolidation is compressing vendor qualification to pre-approved lists with mandatory ISO 17025 traceability. Target mid-cap laboratories with existing notified body relationships and accreditations in multiple jurisdictions. Watch FDA enforcement intensity for gene therapy distribution documentation as the inflection signal for premium-tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Acquisition | ISO 17025-accredited facilities in Germany and Switzerland command pharmaceutical procurement pre-approval status. |
| Refrigerant-Agnostic Firmware Development | EU F-Gas Regulation compliance requires pressure-temperature lookup tables for lower-global-warming-potential alternatives. |
| API-Accessible Temperature Logging | Massachusetts and North Carolina contract research organizations mandate direct laboratory information management system integration. |
| Edge Computing Architecture Deployment | Device-level control intelligence eliminates cloud dependency for lyophilization batch-critical temperature zones. |
| Multi-Sensor Fusion Platform Launch | RTD-thermocouple hybrid designs reduce hardware count in multi-zone food processing facilities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers at German automotive paint shops, regulatory affairs leads at Swiss vaccine manufacturers, procurement directors at North Carolina contract research organizations, and aftermarket service heads at Japanese semiconductor foundries with secondary validation through SEC filings of industrial automation conglomerates, EU F-Gas Regulation implementation progress reports, FDA distribution guidance documents, and customs trade data for temperature sensor module flows. Bottom-up unit economics triangulated against top-down market sizing across product type, connectivity protocol, application vertical, and end-user sophistication tiers.
Historical reference periods anchored the projection horizon through comparable-period growth rate patterning and regulatory phase-down schedule alignment. Segmentation dimensions modeled include product architecture grade, wired versus wireless connectivity, cold chain versus industrial process versus HVAC application, and healthcare versus manufacturing versus residential end-user category. CAGRs derived from segment-level penetration curves and replacement cycle analysis, with specific inputs from pharmaceutical batch consistency requirements and refrigerant sensor recalibration protocol mandates.
Underlying measurement precision varies by segment; pharmaceutical-grade industrial monitors carry tighter precision than residential smart thermostats due to documented calibration chain requirements. Forecasts reflect assumptions about regulatory enforcement continuity, foundry capacity allocation stability, and buyer consolidation trajectories that could revise if semiconductor supply disruptions deepen or cold chain mandates soften. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Motion Sensor Market
Sensors and Controls
Light Detection and Ranging (Lidar) Market
Sensors and Controls
Global Internet of Things Sensors Market
Sensors and Controls
Thermal Anemometer Market
Sensors and Controls
Digital Angle Gauge Market
Sensors and Controls
Spectral Sensor Market
Sensors and Controls
United States Scintillator Market
Sensors and Controls
United States Gas Sensors Market
Sensors and Controls
Millimeter Wave Sensors and Modules Market
Sensors and Controls
Thermometer Market
Sensors and Controls
Industrial Combustion Control Components and Systems Market
Sensors and Controls
Global Mid-And-High-Level Precision GPS Receiver Market
Sensors and Controls
Frictionless Remote Monitoring Devices Market
Sensors and Controls
Meteorological Devices Market
Sensors and Controls
Distance Measurement Sensor Market
Sensors and Controls
MEMS Gyroscope Market