
 MEMS Inertial Sensors Market | 2026-2036
MEMS Inertial Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
MEMS Inertial Sensors Market Outlook
Asset-light foundry partnerships and fabless licensing arrangements is fragmenting capital requirements across the MEMS inertial sensor value chain. Bosch Sensortec leverages captive wafer capacity to sustain cost leadership in high-volume accelerometer production. STMicroelectronics anchors European supply through vertically integrated MEMS fabrication in Italy and France. TDK InvenSense competes via specialized foundry relationships that reduce fixed-asset intensity for niche gyroscope designs.
MEMS inertial sensors integrate micromachined mechanical structures with transduction electronics to detect acceleration, angular rate, or tilt, typically fabricated on silicon substrates using deep reactive ion etching and wafer-level packaging to achieve milligram-scale precision in millimeter-scale envelopes. These devices serve as orientation and motion feedback elements in navigation systems, platform stabilization, and consumer device interfaces. Combo sensors now command the most attractive margin pools by merging accelerometer and gyroscope functions in single packages for smartphone and wearable OEMs. Automotive end users represent the fastest-expanding demand segment as electrified powertrains and chassis control systems multiply sensor count per vehicle. Industrial automation applications remain comparatively mature, with optical technique alternatives displacing MEMS in highest-precision metrology roles.
FDA scrutiny of MEMS-based surgical navigation tools in the United States is elevating validation documentation burdens for manufacturers targeting medical device integration. The EU AI Act and CE marking under MDR framework in Europe are imposing algorithmic transparency requirements on sensor-fusion systems that incorporate machine learning for predictive maintenance. China's GB standards and MIIT certification protocols govern electromagnetic compatibility and reliability testing for domestically deployed industrial sensors. Stakeholders must monitor how divergent national conformity pathways reshape product architecture decisions and regional sourcing strategies.
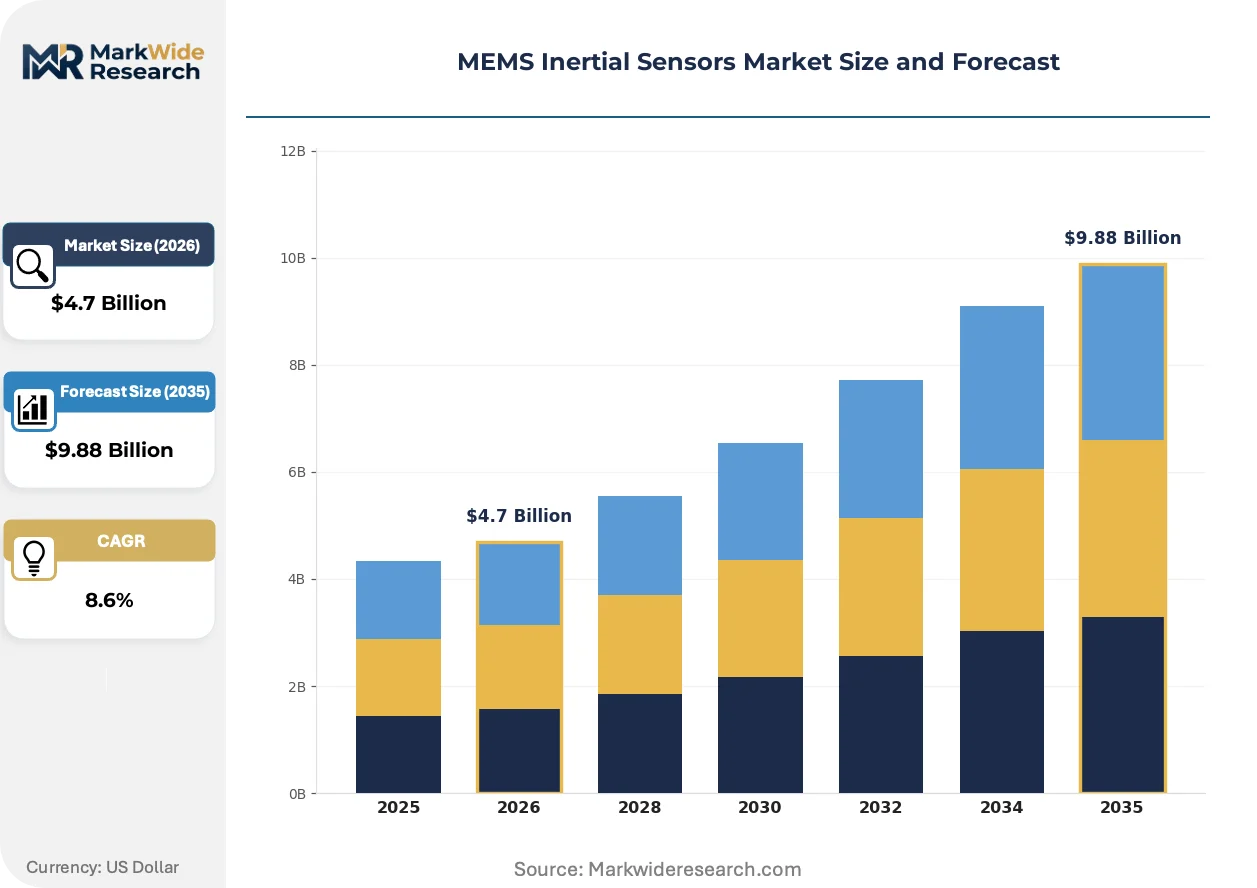
Market Dynamics
Automotive electrification and chassis digitization are multiplying sensor count per vehicle while foundry partnerships fragment capital requirements across the MEMS inertial sensor value chain.
Growth Catalysts
- EU F-Gas Regulation:Tightening material standards for sensor packages is accelerating migration to hermetic wafer-level sealing technologies that extend operational lifespan in harsh environments.
- Industrial automation corridors:Demand concentration in Shenzhen and Shanghai is pulling specialized gyroscope production toward China-based foundry relationships with reduced fixed-asset intensity.
- Deep reactive ion etching:Advances in DRIE process control are enabling thinner silicon structures that improve shock tolerance for automotive safety applications.
Market Restraints
- Optical interferometry:Highest-precision metrology roles in semiconductor manufacturing are seeing MEMS displacement by fiber-optic gyroscopes and ring laser systems with superior drift stability.
- Wafer supply concentration:Captive silicon capacity at integrated IDMs limits foundry access for fabless designers, creating allocation bottlenecks during demand spikes.
- CE marking under MDR:Algorithmic transparency requirements for sensor-fusion systems with machine learning are extending validation timelines for predictive maintenance deployments.
Strategic Opportunities
- Surgical navigation:FDA scrutiny of MEMS-based tools is elevating documentation burdens that favor established suppliers with quality management infrastructure over new entrants.
- Combo sensor architectures:Merging accelerometer and gyroscope functions in single packages is creating margin expansion for smartphone and wearable OEMs seeking footprint reduction.
- MIIT certification protocols:China's GB standards for electromagnetic compatibility are creating compliance moats for domestic manufacturers serving industrial automation deployments.
Industry Challenges
- MEMS-specific design automation:Shortage of engineers fluent in multi-physics simulation for micromachined structures is constraining development velocity at fabless firms.
- Wafer-level packaging qualification:Extended reliability testing for milligram-scale precision devices is compressing product launch windows against customer timing requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MEMS Inertial Sensors Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Accelerometers, Gyroscopes, Inclinometers, Combo Sensors End User: Consumer Electronics, Automotive, Aerospace, Industrial Automation Technology: Microfabrication, Optical Techniques, Electronic Integration, Wireless Connectivity Application: Navigation, Motion Tracking, Stabilization, Gaming |
| Companies Covered | Bosch Sensortec, Silicon Sensing Systems, Honeywell International Inc., Sensornor AS, Murata Manufacturing, Analog Devices Inc., STMicroelectronics, Xsens, TDK InvenSense, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MEMS Inertial Sensors Market Strategic Shifts
Sensor-fusion algorithms and packaging miniaturization are compressing form factors while regulatory fragmentation across major economies is forcing parallel certification tracks.
Silicon-on-insulator substrates with embedded piezoelectric thin films are hybridizing traditional capacitive sensing with resonant operation modes. Automotive tier-1 suppliers are adopting these structures for next-generation electronic stability control modules. The technology is hybridizing cost structures by merging high-volume MEMS economics with precision resonator performance in single process flows.
REACH substance restrictions and RoHS amendments are tightening material declarations for sensor packages containing lead-based solders and certain flame retardants. Manufacturers are reformulating underfill compounds and redistribution layers to maintain EU market access. Medical device integrators face the steepest compliance burden as MDR documentation requirements layer onto existing CE marking obligations.
Platform stabilization contracts for advanced driver assistance systems are consolidating procurement around multi-year sensor fusion partnerships rather than discrete component purchasing. Tier-1 automotive suppliers are absorbing integration risk that previously sat with OEMs. Germany and Japan anchor this shift, with KBA and METI type-approval processes favoring suppliers with end-to-end validation capabilities.
MEMS Inertial Sensors Market Segmentation
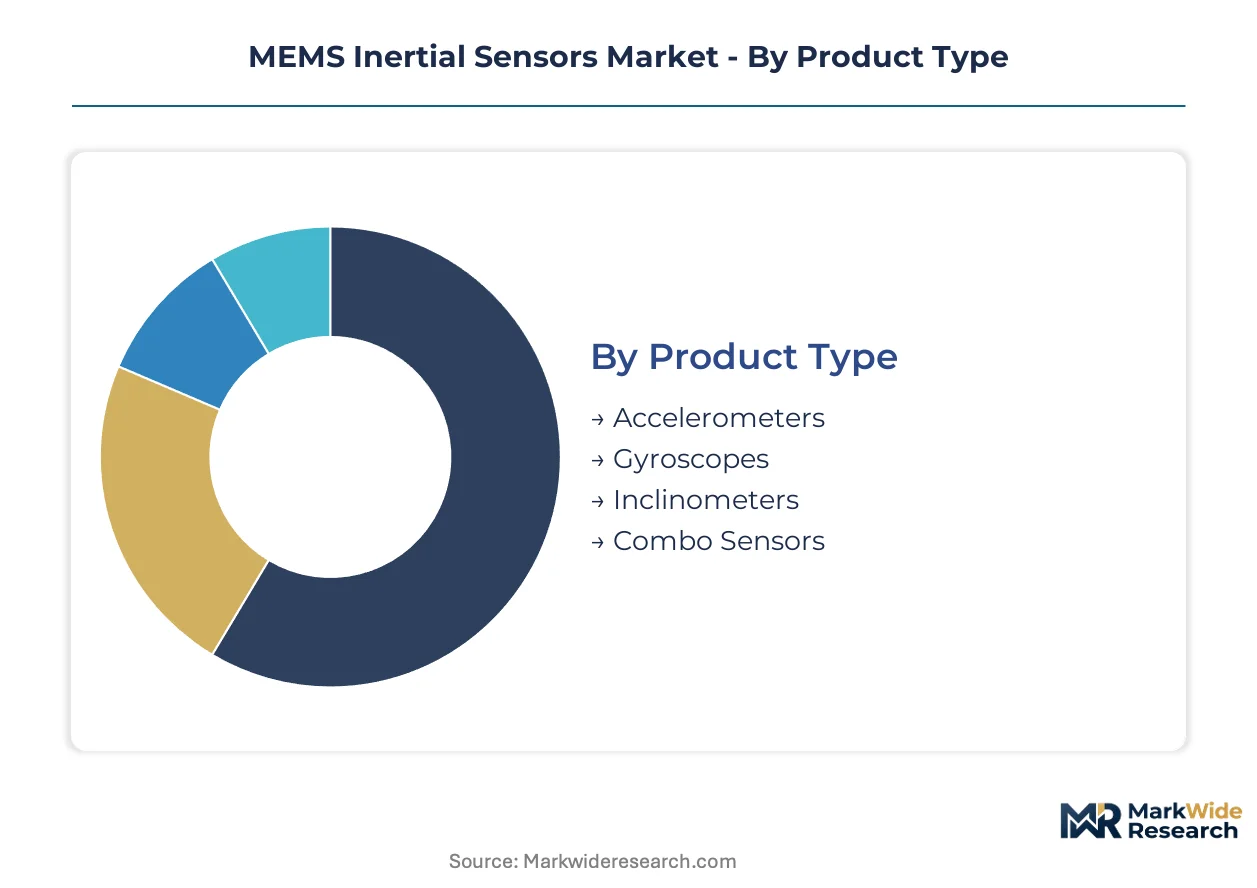
Segmentation in MEMS inertial sensors separates devices by precision grade, environmental tolerance, and integration complexity. Each category carries distinct margin profiles and aftermarket service requirements that reshape supplier economics.
Product Type:
After-sales calibration and recertification intensity varies sharply across product categories, with high-precision gyroscopes demanding periodic drift correction that combo sensors rarely require.
- Combo Sensors:Single-package integration of accelerometer and gyroscope functions reduces board space and power draw for smartphone OEMs. Shenzhen-based wearable manufacturers are pulling production toward fabless partnerships with reduced fixed-asset intensity. By volume, combo sensors lead. By growth pace, gyroscopes are climbing fastest.
- Accelerometers:Capacitive transduction structures detect linear acceleration across milli-g to hundreds-of-g ranges for automotive airbag deployment and consumer device orientation. German and Japanese automotive manufacturers are expanding stabilization system procurement around multi-year sensor fusion partnerships.
- Gyroscopes:Coriolis-force detection enables angular rate measurement for platform stabilization and navigation aiding.
- Inclinometers:Tilt-sensing variants serve construction equipment leveling and solar panel tracking with lower bandwidth requirements than full inertial units.
Cost tier separation runs deepest in this category: combo sensors and accelerometers compete on die-size economics, while gyroscopes and inclinometers command premiums through calibration labor.
End User:
Automotive qualification cycles stretch 18-24 months versus 6-9 months for consumer electronics, concentrating revenue recognition timing and inventory risk with tier-1 suppliers.
- Automotive:Electrified powertrains and chassis digitization multiply sensor count per vehicle for electronic stability control and battery thermal management. KBA type-approval processes in Germany favor suppliers with end-to-end validation capabilities spanning vibration, temperature, and electromagnetic stress testing.
- Consumer Electronics:Smartphone and wearable OEMs drive the steepest volume ramps but squeeze margins through consolidated procurement of combo sensor packages. Demand concentration in Shenzhen and Shanghai is pulling specialized foundry relationships toward China-based manufacturing.
- Industrial Automation:Predictive maintenance deployments face extended validation timelines under EU AI Act algorithmic transparency requirements for sensor-fusion systems with machine learning.
- Aerospace:Fiber-optic and ring laser alternatives displace MEMS in highest-precision navigation roles where drift stability dominates cost considerations.
Application maturity separates these end users: industrial automation and aerospace rely on established specifications, while automotive and consumer electronics face accelerating specification churn.
Technology:
Process technology choices lock in depreciation schedules and yield learning curves that persist across product generations.
- Microfabrication:Deep reactive ion etching and wafer-level packaging achieve milligram-scale precision in millimeter-scale envelopes through silicon-on-insulator substrates with embedded piezoelectric thin films.
- Electronic Integration:ASIC co-design with MEMS structures reduces noise floors and enables digital output interfaces for system-on-chip integration.
- Optical Techniques:Fiber-optic gyroscopes and interferometric methods serve metrology applications where MEMS drift rates prove insufficient.
- Wireless Connectivity:Bluetooth Low Energy and UWB integration enables distributed sensor networks for asset tracking and condition monitoring.
Supply concentration clusters around microfabrication and electronic integration, while optical techniques and wireless connectivity draw from distinct supplier bases with different capital intensity profiles.
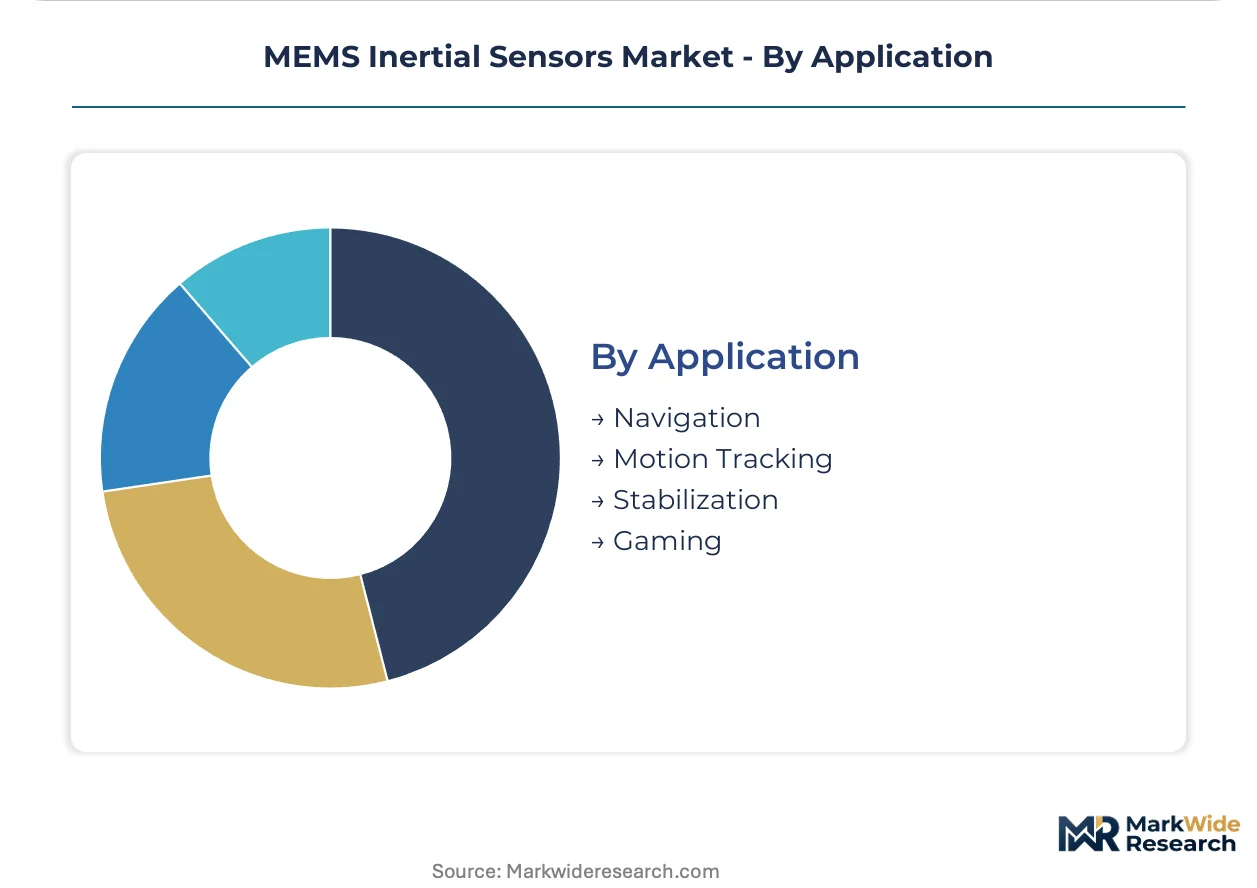
Application:
Functional requirements span open-loop orientation sensing to closed-loop stabilization with feedback bandwidths differing by orders of magnitude.
- Navigation:Sensor fusion with GNSS aiding demands tight bias stability and scale factor accuracy for dead reckoning during signal outages. FDA scrutiny of MEMS-based surgical navigation tools elevates documentation burdens for medical device integration in the United States.
- Stabilization:Platform control for advanced driver assistance systems requires shock tolerance and temperature compensation across automotive operating ranges.
- Motion Tracking:Gesture recognition and fitness quantification prioritize low power consumption over absolute accuracy.
- Gaming:Haptic feedback and controller orientation sensing represent the most price-sensitive application with minimal calibration requirements.
Precision requirements stratify these applications: navigation and stabilization demand traceable calibration chains, while motion tracking and gaming tolerate wider performance distributions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive tier-1 suppliers and smartphone OEMs concentrate procurement power across three manufacturing corridors. Germany and Japan anchor electrified vehicle sensor demand. China's industrial automation clusters pull foundry partnerships eastward. The United States sustains medical device and aerospace qualification requirements.
Germany
KBA type-approval processes favor suppliers with end-to-end validation spanning vibration, temperature, and electromagnetic stress testing. The EU F-Gas Regulation accelerates migration to hermetic wafer-level sealing for extended operational lifespan. Bavaria-based automotive manufacturers expand stabilization system procurement for advanced driver assistance platforms.
China
MIIT certification protocols and GB standards govern electromagnetic compatibility for domestically deployed industrial sensors. Shenzhen and Shanghai industrial automation corridors pull specialized gyroscope production toward China-based foundry relationships. Pearl River Delta wearable manufacturers drive combo sensor volume through consolidated procurement.
United States
FDA scrutiny elevates validation documentation burdens for MEMS-based surgical navigation tools targeting medical device integration. NHTSA safety standards shape automotive sensor qualification timelines for electronic stability control modules. Michigan and California anchor tier-1 supplier engineering centers for sensor fusion development.
Japan
METI type-approval processes favor suppliers with captive fabrication and end-to-end validation capabilities. Automotive electrification multiplies sensor count per vehicle for chassis digitization and battery thermal management. Nagoya and Tokyo metropolitan areas concentrate tier-1 supplier procurement offices.
MEMS Inertial Sensors Market Competitive Environment
Channel-controlling players compete with product-specialist players across a tiered structure. Integrated device manufacturers with captive wafer capacity anchor the premium tier through cost leadership in high-volume production. Fabless designers occupy the specialist tier via foundry partnerships that reduce fixed-asset intensity for niche architectures. Strategic moves concentrate on multi-year sensor fusion partnerships and hermetic packaging technology licensing.
Among European-integrated fabricators, STMicroelectronics anchors supply through vertically integrated MEMS fabrication in Italy and France. Bosch Sensortec and TDK InvenSense occupy distinct competitive positions: the former leverages captive wafer capacity for cost leadership, while the latter competes via specialized foundry relationships for niche gyroscope designs.
| Leading Market Players |
|---|
| Bosch Sensortec |
| Silicon Sensing Systems |
| Honeywell International Inc. |
| Sensornor AS |
| Murata Manufacturing |
| Analog Devices Inc. |
| STMicroelectronics |
| Xsens |
| TDK InvenSense |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in 200mm MEMS-dedicated foundry lines across Taiwan and China is compressing wafer pricing while accelerating supplier migration toward 300mm automotive-qualified capacity. This utilization imbalance concentrates pricing power with IDMs holding captive fabrication, forcing fabless designers into longer-term foundry commitments to secure allocation.
Pricing Analysis
Certification level creates the primary spread between automotive-grade units carrying KBA/METI validation and consumer-tier alternatives. Three-tier pricing structure across automotive, industrial, and consumer levels reflects die-size economics and calibration labor intensity. Pricing pressure stems from Shenzhen-based wearable OEMs consolidating combo sensor procurement into annual volume tenders. Consumer electronics buyers exhibit highest price sensitivity, while surgical navigation integrators tolerate premiums for FDA-validated supply chains.
Supply Chain Analysis
TSMC specialty MEMS foundry services, X-Fab silicon processing, and SMIC domestic lines anchor contract manufacturing concentration for fabless designers. Silicon wafer supply concentrates in Japan, Taiwan, and Germany; specialized gyroscope-grade substrates draw from South Korean and Japanese suppliers. Single-source vulnerability persists for deep reactive ion etching equipment and piezoelectric thin-film deposition tools. Distribution runs through tier-1 automotive supplier engineering centers and Shenzhen electronics component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MEMS inertial sensor incumbents face substitution defense against fiber-optic gyroscopes and ring laser systems capturing highest-precision navigation roles. Optical interferometry alternatives threaten margin pools in semiconductor metrology and aerospace guidance.
For Market Incumbents: Pre-empt displacement by fiber-optic alternatives through silicon-on-insulator substrate investments that narrow performance gaps. Captive 300mm wafer capacity in Germany or Japan anchors cost leadership against foundry-dependent competitors. Accelerate hermetic packaging technology licensing to monetize F-Gas Regulation compliance requirements. For New Entrants and Emerging Players: Underpenetrated surgical navigation tooling in the United States offers white-space expansion behind FDA validation barriers that deter commodity competitors. Target industrial automation corridors around Shenzhen with MIIT-certified gyroscope designs for predictive maintenance deployments. Lead with algorithmic transparency documentation that satisfies EU AI Act requirements ahead of established suppliers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among combo sensor suppliers with multi-year smartphone OEM contracts and automotive sensor fusion partnerships. Long-term viability hinges on backward integration into wafer-level packaging rather than pure fabless design. Monitor FDA 510(k) clearance velocity for MEMS-based surgical tools as inflection signal for medical device integration momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Hermetic Wafer-Level Packaging Scale-Up | EU F-Gas Regulation compliance extends operational lifespan in automotive thermal environments. |
| Sensor Fusion Partnership Expansion | German KBA type-approval processes favor suppliers with end-to-end validation capabilities. |
| Silicon-on-Insulator Substrate Adoption | Piezoelectric thin-film hybridization merges MEMS economics with precision resonator performance. |
| MIIT Certification Pathway Investment | GB standards compliance creates moats for domestic manufacturers serving China industrial automation. |
| FDA Quality Management Infrastructure Buildout | 510(k) documentation burdens favor established suppliers over new entrants in surgical navigation. |
Study Parameters
A spread of perspectives from MEMS process engineers, tier-1 automotive procurement managers, fabless design house executives, and medical device regulatory affairs leads converged on the working assumptions. Primary interviews combined with secondary validation against SEC 10-K filings, MIIT certification databases, and EU MDR technical documentation. Bottom-up die-size economics and top-down automotive content-per-vehicle estimates were triangulated for segmentation sizing.
Demand-supply balance modeling across the projection horizon incorporated electrified vehicle production ramps, smartphone unit forecasts, and industrial automation capital expenditure cycles. Segmentation dimensions included precision grade, environmental tolerance, and integration complexity alongside end-user qualification cycle length. CAGRs were derived from installed base growth and replacement dynamics rather than extrapolated point estimates. Forecast inputs encompassed foundry capacity utilization surveys and KBA/METI type-approval timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic suppliers or accelerated fiber-optic gyroscope cost reduction would shift outcomes. Quarterly review of FDA 510(k) submission trends, EU AI Act implementation guidance, and automotive platform sensor count specifications is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Internet of Things Sensors Market
Sensors and Controls
Sound Sensor Market
Sensors and Controls
Europe Sensors Market
Sensors and Controls
60GHz Radar Evaluation Kit Market
Sensors and Controls
Magnetic Proximity Sensor Market
Sensors and Controls
Europe Optical Sensors Market
Sensors and Controls
Canada Digital Thermometer Market
Sensors and Controls
Wireless Sensor Tags Market
Sensors and Controls
Chest Sensors Market
Sensors and Controls
Global Accelerometers Market
Sensors and Controls
Condition Monitoring System Market
Sensors and Controls
Capacitive Pressure Sensor Market
Sensors and Controls
Bioacoustics Sensing Market
Sensors and Controls
Parking Sensors Market
Sensors and Controls
GPS Tracking Device Market
Sensors and Controls
Thin Film Sensor Market