
 Fiber Bragg Grating Sensor Market | 2026-2036
Fiber Bragg Grating Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Bragg Grating Sensor Market Foresight
Wavelength-multiplexed interrogation is reconfiguring how distributed sensing architectures are deployed across industrial asset bases. Luna Innovations leverages its integrated photonics platform to dominate aerospace qualification programs. HBK FiberSensing anchors its position through deep vertical integration into strain sensor manufacturing. Proximion AB specializes in high-channel-count systems for energy sector clients.
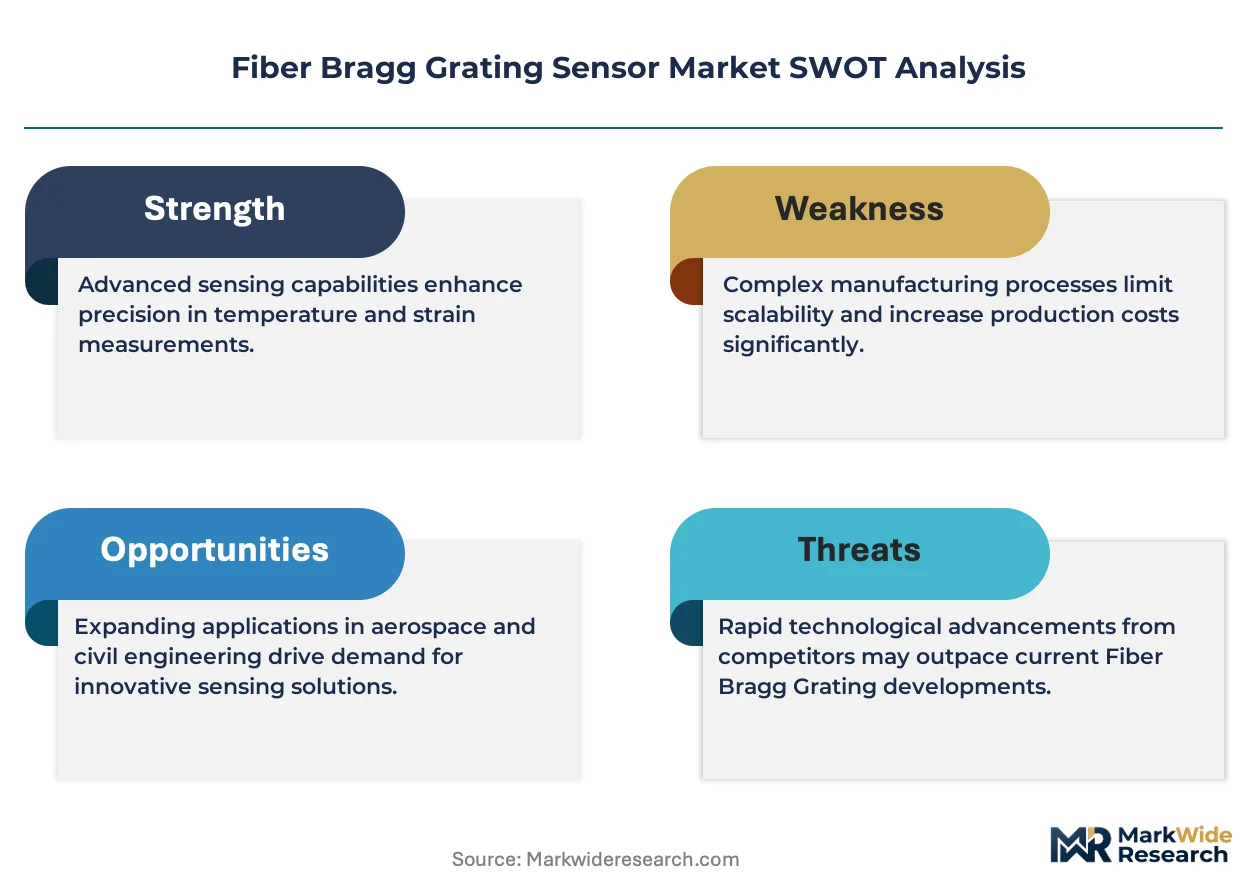
A Fiber Bragg Grating Sensor consists of a periodic refractive index modulation inscribed into optical fiber core using ultraviolet laser exposure, typically operating in the C-band near 1550 nm with reflectivity bandwidths below 0.5 nm. The device transduces mechanical strain or thermal variation into precise wavelength shifts, enabling distributed measurement of structural deformation, temperature gradients, and pressure differentials across kilometers of single fiber. Temperature sensors lead the product type landscape due to their penetration in power transformer and pipeline monitoring, while structural monitoring applications command premium pricing in civil engineering deployments. Specialty fiber technology is capturing share from quartz fiber in harsh-environment oil and gas installations where hydrogen darkening resistance proves critical.
The US Federal Highway Administration mandates structural health monitoring for critical bridge inventory, while Germany's KBA enforces rail infrastructure sensor standards under EU safety directives. China's MEE incorporates optical sensing into dam and reservoir safety regulations under national water security frameworks. Stakeholders must monitor how evolving infrastructure resilience codes in North America and Europe reshape procurement specifications for multi-parameter FBG systems.
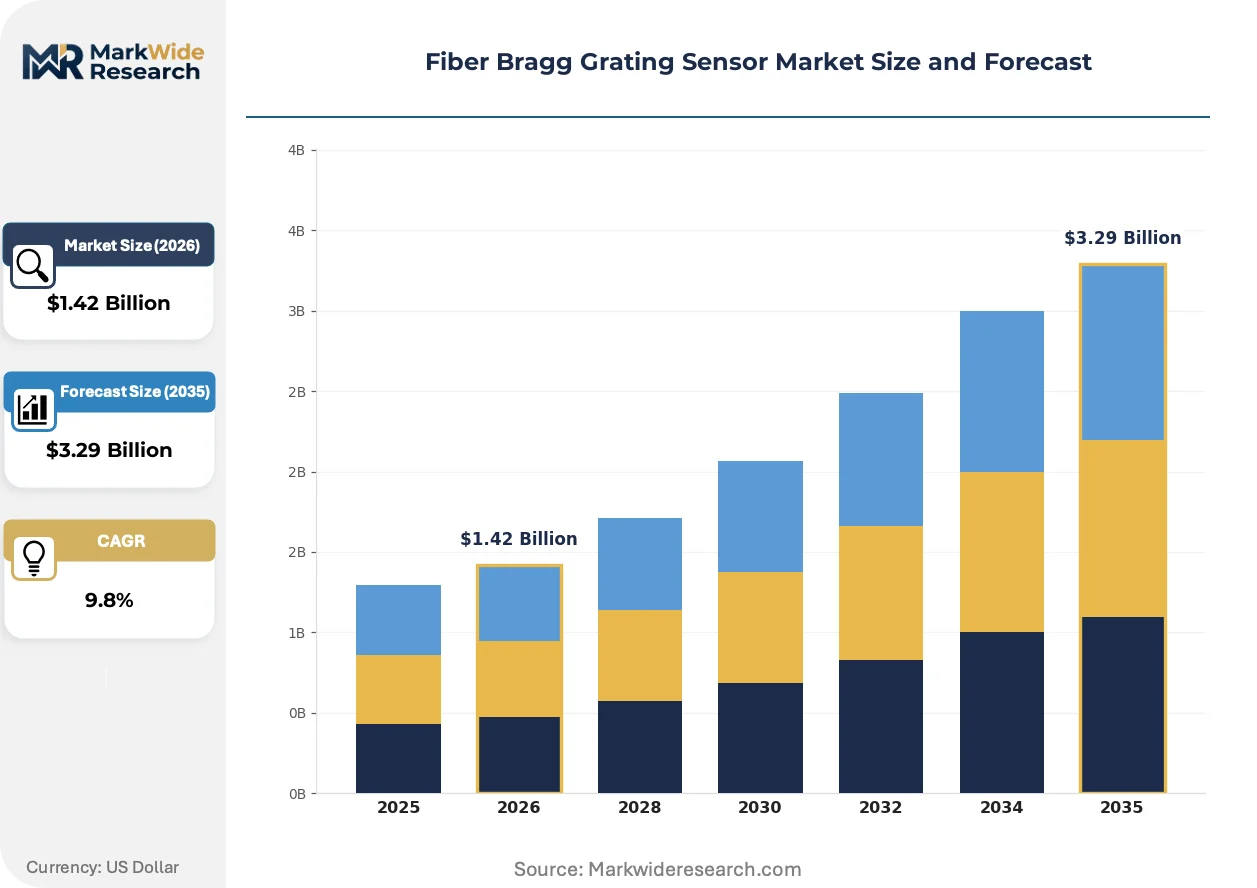
Market Dynamics
Wavelength-multiplexed interrogation systems are compressing installation costs per sensing point, enabling utility operators to blanket bridge networks with dense FBG arrays rather than sparse sampling. This density imperative is restructuring competitive advantage toward integrated photonics platforms.
Growth Catalysts
- FHWA Bridge Mandates:The US Federal Highway Administration requires structural health monitoring for critical bridge inventory, forcing state departments of transportation into multi-year sensor deployment programs.
- Hydrogen-Resistant Specialty Fiber:Fluorine-doped fiber designs withstand hydrogen darkening in downhole environments, unlocking permanent installation in sour gas wells where quartz degrades within months.
- German Rail Standardization:KBA enforcement of EU safety directives mandates sensor coverage across high-speed tunnel and viaduct infrastructure, creating predictable procurement pipelines for multi-channel systems.
Market Restraints
- UV Laser Inscription Bottleneck:Phase mask fabrication for FBG writing concentrates among specialized photonics equipment suppliers in Germany and Japan, creating single-source vulnerability.
- Interrogator Cost Floor:Precision wavelength detection electronics using tunable laser diodes or optical spectrum analyzers resist cost reduction below five-figure unit pricing.
- Silicon Photonic Substitution:Integrated silicon nitride strain sensors on SOI wafers threaten displacement in consumer electronics and automotive crash-testing applications.
Strategic Opportunities
- China Dam Safety Expansion:MEE regulations under national water security frameworks mandate optical sensing for hydroelectric reservoir structural monitoring, creating installation demand across provincial infrastructure.
- Wind Blade Embedded Sensing:Blade manufacturers seek FBG integration during composite layup for real-time load monitoring, replacing accelerometer arrays with fiber-integrated solutions.
- Data Center Thermal Mapping:Hyperscale operators deploy distributed temperature sensing across server rows, using FBG arrays to replace discrete thermocouple networks and enable liquid cooling optimization.
Industry Challenges
- Fiber Handling Expertise Gap:Installation crews lack training in bare fiber splicing and strain relief for harsh-environment deployments, causing field failure rates above acceptable thresholds.
- Multi-Parameter Certification Lag:Simultaneous strain-temperature-pressure calibration protocols lack unified IEC standards, forcing redundant testing cycles for each jurisdiction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Bragg Grating Sensor Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.29 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spectral Sensors, Temperature Sensors, Strain Sensors, Pressure Sensors End User: Aerospace, Civil Engineering, Oil & Gas, Healthcare Technology: Quartz Fiber, Specialty Fiber, Plastic Fiber, Hybrid Fiber Application: Structural Monitoring, Environmental Monitoring, Industrial Sensing, Automotive Testing |
| Companies Covered | FBGS International, Technica Optical Components, Luna Innovations, Advanced Optics Solutions GmbH, ITF Technologies, HBK FiberSensing, Proximion AB, Wuhan Ligong Guangke, Smart Fibres Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Bragg Grating Sensor Market Shifts & Advancements
Photonic integration is collapsing the boundary between sensor fabrication and signal processing, eliminating discrete component assembly in favor of monolithic chip-scale systems. This convergence is redrawing competitive boundaries across the value chain.
Femtosecond laser inscription is collapsing the equipment barrier for FBG manufacturing, enabling point-by-point grating writing without phase masks. Regional sensor shops in France and Switzerland now produce custom gratings for aerospace qualification programs. The technology is collapsing lead times from weeks to days for prototype development.
REACH chemical restrictions on halogenated flame retardants are forcing recertification of cable jacketing materials used in tunnel installations. German rail operators now specify low-smoke zero-halogen sheathing for all optical sensing cables in underground infrastructure. Material suppliers in the Benelux region are scaling phosphorous-nitrogen intumescent alternatives.
Asset operators now unbundle sensor hardware from analytics software, treating interrogators as commodity infrastructure while purchasing predictive maintenance algorithms on subscription. European utility consortiums lead this shift, sourcing FBG arrays through construction contractors while contracting specialized vendors for cloud-based strain analysis. The separation is compressing hardware margins while expanding recurring revenue pools for data interpretation services.
Fiber Bragg Grating Sensor Market Segmentation
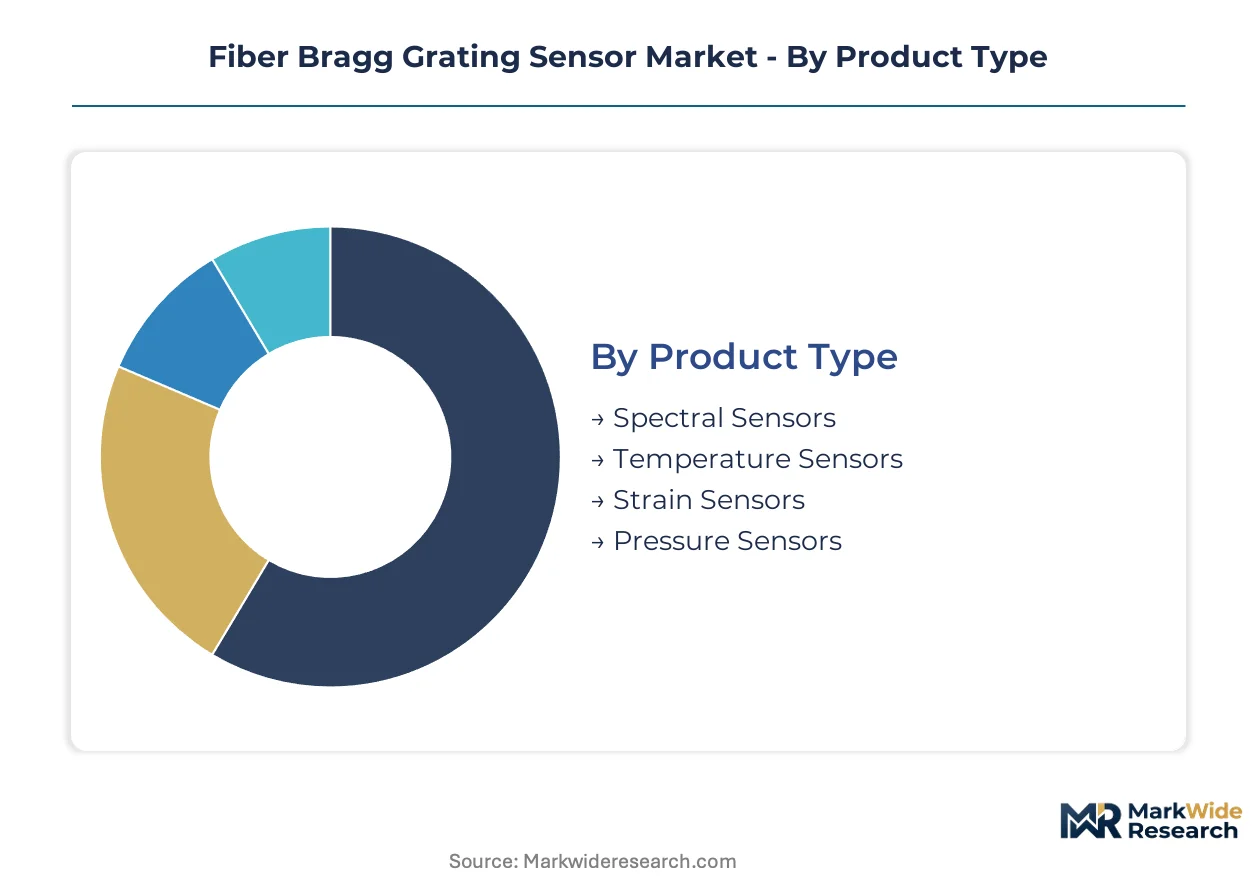
Segmentation in the Fiber Bragg Grating Sensor Market reveals how technical specifications, environmental demands, and end-use requirements fragment procurement patterns. Engineers select sensor architectures based on thermal tolerance, chemical exposure, and measurement precision rather than cost alone.
Product Type:
Cost tier differentiation separates commodity temperature probes from premium multi-parameter spectral systems deployed in safety-critical infrastructure.
- Temperature Sensors:These devices dominate transformer monitoring and pipeline surveillance through simple thermal-wavelength transduction. German utility operators deploy dense arrays across substation equipment, driven by grid reliability mandates under EU energy security frameworks.
- Strain Sensors:Precision measurement of mechanical deformation commands premium pricing in civil engineering applications. US state transportation departments embed these in bridge deck installations following FHWA structural health monitoring requirements.
- Pressure Sensors:Downhole oil and gas applications utilize hydrogen-resistant packaging for sour well environments.
- Spectral Sensors:Multi-wavelength interrogation enables simultaneous parameter extraction in aerospace qualification programs.
Temperature Sensors hold installed capacity. Strain Sensors is rotating up the share rankings.
End User:
Application maturity varies sharply across sectors, with civil engineering standardizing fastest while healthcare remains experimental.
- Civil Engineering:Bridge, tunnel, and dam monitoring represents the most codified demand segment. China's MEE mandates optical sensing for hydroelectric reservoir safety, creating predictable procurement volume across provincial infrastructure authorities.
- Oil & Gas:Downhole permanence requirements favor specialty fiber designs resistant to hydrogen darkening. Permian Basin operators now specify fluorine-doped fiber for sour gas well installations where quartz degrades within operational timeframes.
- Aerospace:Qualification protocols for flight-critical sensing limit supplier pools to pre-certified vendors.
- Healthcare:Biocompatible catheter-integrated FBGs remain in clinical validation for minimally invasive pressure monitoring.
Civil Engineering commands volume concentration. Oil & Gas is climbing the fastest on specialty fiber conversion.
Technology:
Supply concentration in fiber drawing and grating inscription equipment shapes competitive access across material platforms.
- Specialty Fiber:Fluorine-doped and hydrogen-resistant designs displace conventional quartz in harsh environments. German rail operators specify these for tunnel installations where long-term chemical stability proves mandatory under KBA safety directives.
- Quartz Fiber:Standard telecom-grade fiber retains cost advantage in benign laboratory and data center applications. European hyperscale operators deploy quartz-based temperature arrays for server rack thermal mapping where hydrogen exposure is absent.
- Plastic Fiber:Polymer waveguides enable low-cost disposable sensing in consumer health applications.
- Hybrid Fiber:Multi-material constructions combine thermal and mechanical resilience for composite wind blade integration.
Quartz Fiber holds installed capacity. Specialty Fiber is gaining share fastest on energy sector conversion.
Application:
Customer type fragmentation separates asset-owner direct procurement from contractor-mediated installation across project scales.
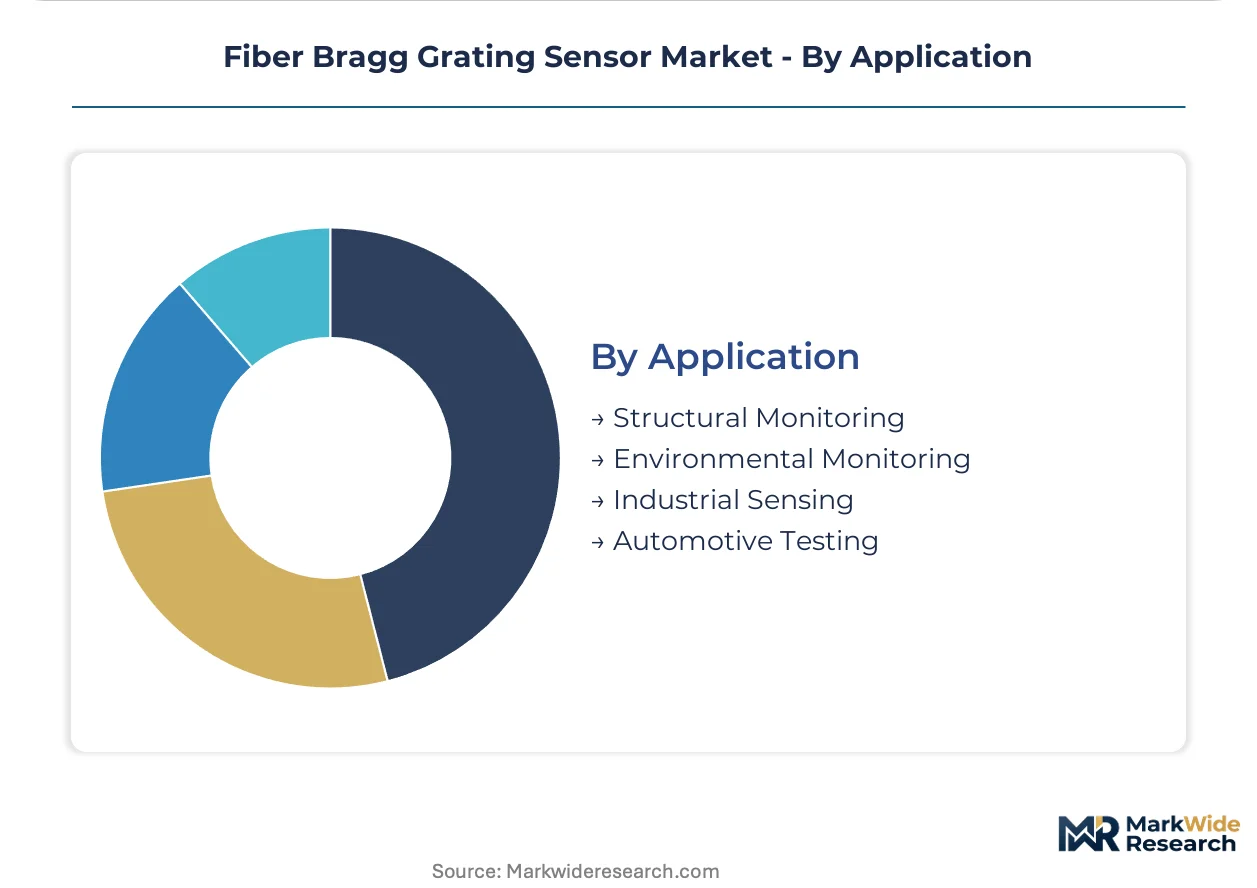
- Structural Monitoring:Bridge, building, and geotechnical deformation measurement carries the highest per-channel pricing. Japanese construction consortia embed FBG arrays in seismic-resistant high-rise foundations under METI building code amendments.
- Industrial Sensing:Manufacturing process control and equipment condition monitoring standardizes fastest. South Korean automotive test facilities deploy strain sensor networks for crash-structure validation under KATRI certification protocols.
- Environmental Monitoring:Distributed temperature and pressure sensing for groundwater and atmospheric applications.
- Automotive Testing:Crash-test dummy instrumentation and vehicle structural validation utilize disposable fiber configurations.
Structural Monitoring anchors premium pricing. Industrial Sensing is expanding most quickly on manufacturing automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German FBG interrogator manufacturers export dense wavelength-multiplexed systems to utility operators across Scandinavia and Central Europe. This trade corridor channels specialty fiber technology toward infrastructure monitoring programs mandated under EU safety frameworks.
United States
State transportation departments deploy FBG arrays across critical bridge inventory following FHWA structural health monitoring mandates. The Infrastructure Investment and Jobs Act channels federal funding toward sensor procurement for aging span rehabilitation. Texas and California DOTs lead installation volume, embedding strain sensors in seismic retrofit projects across the I-35 and I-80 corridors.
Germany
KBA rail safety directives force sensor coverage across high-speed tunnel and viaduct networks connecting Frankfurt to Munich. Deutsche Bahn's multi-year capital program specifies multi-channel interrogation systems for Rhine-Main and Rhine-Ruhr corridor monitoring. Bavarian infrastructure authorities concentrate procurement through Munich-based system integrators.
China
MEE dam safety regulations mandate optical sensing for hydroelectric reservoirs under national water security frameworks. Provincial infrastructure authorities in Sichuan and Yunnan install distributed temperature arrays across Three Gorges tributary systems. Yangtze River Delta construction consortia embed FBG networks in Shanghai-Ningbo high-speed rail tunnels.
Japan
METI building code amendments require seismic-resistant foundation monitoring in Tokyo and Osaka high-rise construction. Japanese rail operators deploy specialty fiber arrays along Shinkansen routes crossing tectonically active zones. Nagoya-based photonics equipment suppliers dominate domestic grating inscription capacity.
South Korea
KATRI certification protocols standardize FBG strain networks for automotive crash-structure validation at test facilities near Seoul. Korean automotive OEMs specify fiber-integrated sensing for electric vehicle battery pack thermal monitoring. Busan-Ulsan manufacturing clusters source interrogation systems through domestic system integrators.
Fiber Bragg Grating Sensor Market Competitive Landscape
On the supply side, the industry is bifurcated between integrated photonics platform specialists and component-centric sensor fabricators. Tier-one interrogator manufacturers compete through wavelength-multiplexing density and software analytics bundling. Three archetypes dominate: aerospace qualification specialists, energy-sector system integrators, and regional custom grating shops. Competitive moves concentrate on femtosecond laser inscription capability acquisition and predictive maintenance software unbundling from hardware sales.
Among North American platform specialists, Luna Innovations exemplifies the integrated photonics archetype through its aerospace-focused qualification positioning. HBK FiberSensing anchors the European tier through in-house strain sensor manufacturing and deep construction sector relationships. Proximion AB occupies the high-channel-count systems niche for energy infrastructure clients. Wuhan Ligong Guangke represents Chinese regional fabrication capacity serving domestic dam safety and rail monitoring procurement.
| Leading Market Players |
|---|
| FBGS International |
| Technica Optical Components |
| Luna Innovations |
| Advanced Optics Solutions GmbH |
| ITF Technologies |
| HBK FiberSensing |
| Proximion AB |
| Wuhan Ligong Guangke |
| Smart Fibres Ltd |
| Others |
Supply & Pricing Matrix
Overcapacity in femtosecond laser inscription equipment across France and Switzerland is compressing prototype grating pricing while simultaneously eroding margins for traditional phase-mask manufacturers in Germany and Japan, forcing suppliers toward bundled interrogator-analytics packages to recover value.
Pricing Analysis
Prior-generation quartz-based temperature arrays trade at commodity levels against current-generation specialty fiber systems commanding premiums for hydrogen resistance, while next-generation photonic-integrated interrogators threaten further compression through chip-scale integration. Three-tier pricing structure across aerospace-qualified, industrial-grade, and laboratory-economy levels separates procurement pools. Pricing pressure stems from silicon photonic substitution in consumer and automotive testing applications. State transportation departments exhibit highest price sensitivity due to federal funding constraints, whereas oil and gas operators prioritize operational longevity over unit cost.
Supply Chain Analysis
Upstream germanium tetrachloride and high-purity silicon feedstock draws from suppliers in the United States, Germany, and Japan before fiber drawing concentration in China, the United States, and Germany. Phase mask fabrication and femtosecond laser systems represent critical equipment dependencies. Single-source vulnerability in ultraviolet laser inscription tools creates structural risk. Distribution runs through construction contractors for civil infrastructure, system integrators for energy applications, and direct OEM supply for aerospace qualification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: certification protocols for flight-critical and infrastructure-monitoring applications create years-long supplier lock-in that resists displacement.
For Market Incumbents: Build switching-cost moats through predictive maintenance software unbundling that embeds customer workflows. Pursue backward integration into femtosecond laser inscription capacity to collapse prototype lead times. Accelerate certification investment for simultaneous strain-temperature-pressure protocols ahead of unified IEC standardization. Silicon photonic substitution in automotive crash-testing represents the most acute near-term threat.
For New Entrants and Emerging Players: China's provincial dam safety procurement under MEE frameworks offers the most penetrable white-space target given mandated installation volume and limited domestic photonics platform competition. Data center thermal mapping for hyperscale liquid cooling optimization presents a second entry vector with lower certification barriers. Partner with European utility consortiums as software-only analytics vendors to bypass hardware margin compression.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated photonics platform specialists with aerospace qualification positioning and unbundled SaaS analytics offerings. Long-term viability favors vendors controlling both grating inscription capability and interrogator manufacturing. Monitor femtosecond laser equipment acquisition activity as the inflection signal for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Femtosecond Laser Inscription Acquisition | Collapses prototype lead times from weeks to days for aerospace qualification programs. |
| Predictive Maintenance Software Unbundling | Converts hardware margins into recurring revenue pools with European utility consortiums. |
| Specialty Fiber Capacity Expansion | Captures hydrogen-resistant demand from Permian Basin sour gas well operators. |
| Multi-Parameter Certification Investment | Anticipates unified IEC standards for simultaneous strain-temperature-pressure systems. |
| Data Center Thermal Mapping Partnership | Replaces discrete thermocouple networks for hyperscale liquid cooling optimization. |
Research Methodology
A standing panel of fiber sensor design engineers, utility procurement directors, oil and gas reliability managers, and aerospace qualification specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from FHWA infrastructure databases, MEE dam safety filings, KBA rail directive documentation, and EU energy security framework publications. Bottom-up installation volume estimates triangulated against top-down market sizing from interrogator manufacturer capacity disclosures.
Scenario-bracketing framed low, baseline, and high cases across the projection horizon using technology adoption curves for photonic integration and regulatory enforcement intensity. Segmentation dimensions modeled included product type, end-user industry, fiber material platform, and application maturity. CAGRs derived from installation pipeline analysis by infrastructure authority procurement schedules and energy sector capital expenditure tracking. Forecast inputs incorporated femtosecond laser equipment deployment rates and REACH chemical restriction implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by silicon photonic sensor developers or accelerated EU safety directive harmonization would shift outcomes beyond modeled ranges. Cross-checking against FHWA bridge inventory rehabilitation schedules and Deutsche Bahn capital program disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
United States Proximity Sensor Market
Sensors and Controls
Infrared Gas Sensor Market
Sensors and Controls
Tunnel Sensor Market
Sensors and Controls
Asia-Pacific Machine Control System Market
Sensors and Controls
Frictionless Remote Monitoring Devices Market
Sensors and Controls
Global Pressure Calibrators Market
Sensors and Controls
PM2.5 Sensors Market
Sensors and Controls
Global Proximity and Displacement Sensors Market
Sensors and Controls
US Wireless Sensors Market
Sensors and Controls
Global Pyrometer Market
Sensors and Controls
Ceramic Transducers Market
Sensors and Controls
Automation Control Components and Devices Market
Sensors and Controls
Europe Wireless Sensors Market
Sensors and Controls
MEMS Pressure Sensors Market
Sensors and Controls
Marine Sensors Market
Sensors and Controls
VOC Sensors and Monitors Market