
 Thermistor Temperature Sensor Market | 2026-2036
Thermistor Temperature Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Thermistor Temperature Sensor Market Analytics
The direct-to-OEM channel is narrowing as tier-one automotive suppliers consolidate vendor lists for electrification programs. Honeywell International Inc. leverages its aerospace and industrial heritage to anchor premium thermistor contracts in North America. Vishay Intertechnology, Inc. competes through vertical integration in ceramic formulation and thin-film deposition. Murata Manufacturing Co., Ltd. dominates ceramic-based NTC production with manufacturing scale across multiple Asian facilities.
A thermistor temperature sensor is a resistive thermal detection device whose electrical resistance varies predictably with temperature, typically manufactured from metal oxide ceramics such as manganese, nickel, and cobalt oxides sintered at temperatures exceeding 1000°C. These sensors provide precision thermal feedback for circuit protection, battery management, process control, and patient monitoring systems where accuracy within ±0.1°C is required. NTC thermistors lead volume shipments due to their sensitivity in sub-100°C ranges, while digital thermistors capture expanding margin pools in IoT-connected industrial and medical platforms. Automotive systems represent the fastest-growing application dimension as electric vehicle thermal management architectures multiply sensor counts per vehicle.
The US NHTSA and EPA jointly shape automotive thermistor specifications through battery safety and emissions testing protocols, while the EU Green Deal and F-Gas Regulation mandate precision temperature monitoring in heat pump and refrigeration transitions. Japan's METI drives standardization through JIS specifications that govern medical and industrial sensor interchangeability. Stakeholders must monitor how regional certification divergence between FDA medical device requirements and automotive functional safety standards affects platform design costs and market access timelines.
Market Dynamics
The automotive electrification wave is compressing thermistor qualification cycles as OEMs demand ±0.05°C accuracy for lithium-ion cell monitoring, forcing suppliers to recalibrate ceramic formulations and validation protocols simultaneously.
Growth Catalysts
- EU F-Gas Regulation:Heat pump refrigerant transitions in Germany, France, and Italy mandate precision temperature monitoring for flammable coolant systems, expanding NTC sensor deployments in residential and commercial HVAC retrofits.
- Automotive Battery Management:Electric powertrain architectures now integrate 15-30 thermistors per battery pack for thermal runaway prevention, with tier-one suppliers consolidating vendor lists around qualified ceramic sensor sources.
- Medical Device Interoperability:Japan's METI JIS standards for patient monitoring equipment create specification harmonization that reduces redesign costs for multi-market thermistor deployments.
Market Restraints
- Raw Material Concentration:Manganese and cobalt oxide supply chains concentrate in southern African mining operations and Chinese refining facilities, exposing ceramic thermistor producers to geopolitical disruption and input cost volatility.
- Technical Ceiling in High-Temperature Ranges:NTC thermistors experience resistance drift above 150°C, forcing automotive exhaust and industrial furnace applications toward RTD alternatives that command 3-4x unit pricing.
- REACH Compliance Friction:EU substance restrictions on nickel compounds complicate formulation choices for medical-grade sensors, extending certification timelines by 8-14 months for non-European manufacturers.
Strategic Opportunities
- India Industrial Automation:PLI scheme incentives for electronics manufacturing are attracting thermistor assembly investments to serve domestic process control and white goods demand with reduced import dependency.
- Digital Thermistor Convergence:Integration of MEMS fabrication techniques with traditional ceramic NTC elements is enabling IoT-connected sensors with onboard calibration, opening industrial predictive maintenance contracts.
- US IRA Clean Energy Credits:Domestic content requirements for heat pump and battery manufacturing are creating localized demand for North American-assembled thermistor modules with traceable supply chains.
Industry Challenges
- Functional Safety Certification:Automotive ISO 26262 ASIL-C and ASIL-D ratings for battery management thermistors demand fault-tolerant designs that extend development cycles and require specialized failure-mode analysis expertise.
- Legacy System Integration:Industrial automation retrofits in Japan and Germany must bridge analog 4-20mA thermistor outputs with digital Industry 4.0 architectures, complicating signal conditioning and middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermistor Temperature Sensor Market |
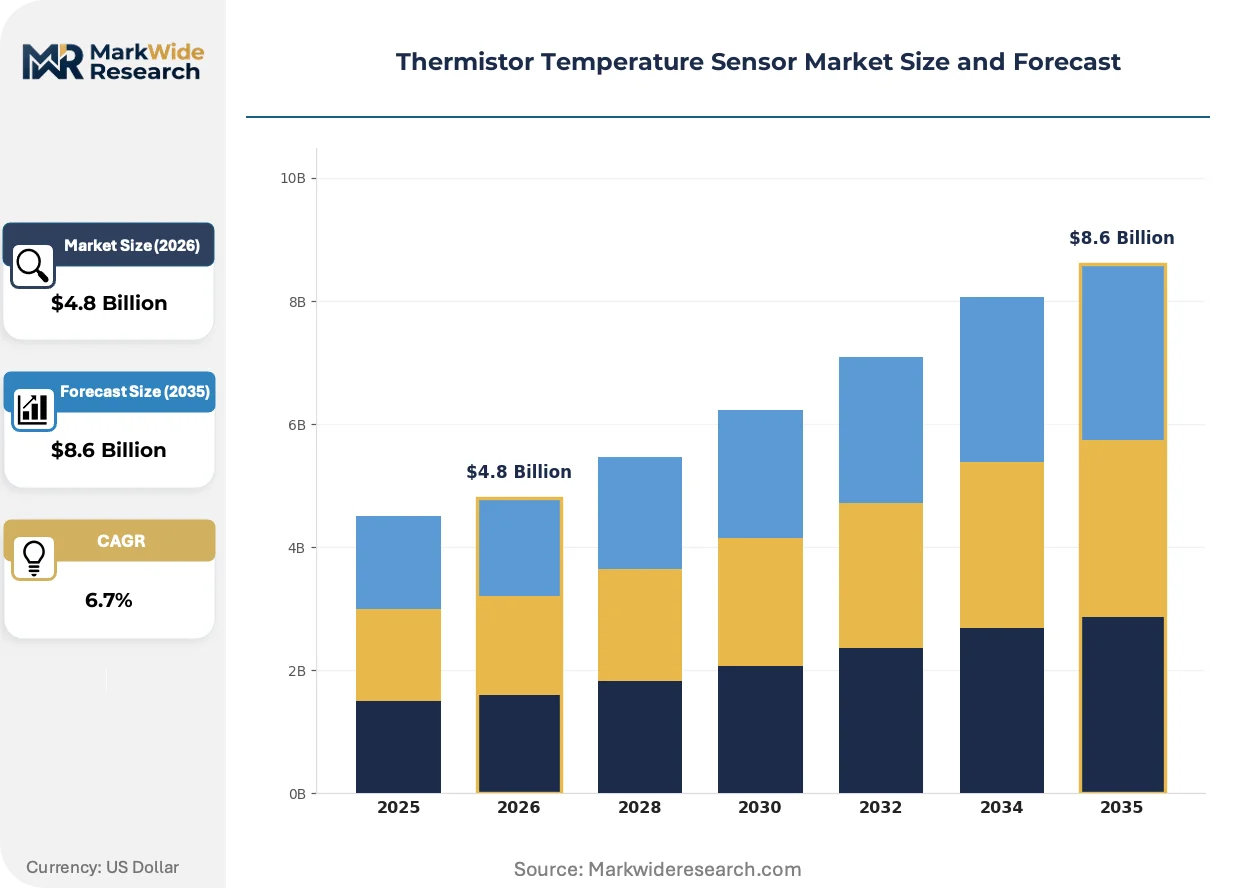
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NTC Thermistors, PTC Thermistors, Digital Thermistors, Linear Thermistors Application: Consumer Electronics, Industrial Equipment, Automotive Systems, Medical Devices End User: Manufacturers, Research Institutions, Healthcare Facilities, Retailers Technology: Analog Technology, Digital Technology, Wireless Technology, IoT Integration |
| Companies Covered | Honeywell International Inc., Vishay Intertechnology, Inc., Murata Manufacturing Co., Ltd., Panasonic Corporation, Amphenol Advanced Sensors, TDK Corporation, Texas Instruments Inc., Littelfuse, Inc., TE Connectivity Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermistor Temperature Sensor Market Evolving Landscape
Silicon-based temperature sensing elements are encroaching on traditional ceramic thermistor territory through semiconductor process economics, while regulatory mandates for refrigerant safety and battery thermal management are rewriting specification requirements across end-use verticals.
Thin-film platinum RTD-on-silicon devices are digitizing temperature measurement in automotive battery modules by combining sensing elements with integrated ADC and LIN/CAN communication protocols. Tier-one suppliers in Germany and South Korea are qualifying these devices for 2026-2027 electric vehicle platforms. This convergence is digitizing the value chain by collapsing external signal conditioning boards into single-chip solutions that reduce BOM complexity and assembly labor.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is mandating flammable natural coolant transitions that require redundant temperature monitoring with fail-safe architectures. Heat pump OEMs in Sweden, Poland, and the Netherlands are redesigning sensor arrays to meet EN 378 safety standards for propane and isobutane systems. Residential HVAC retrofits are absorbing the highest compliance costs as installers face recertification requirements for handling flammable refrigerants.
Buyer concentration among automotive tier-one suppliers is compressing commercial terms and forcing sensor vendors to assume inventory risk through vendor-managed stock programs. Bosch, Denso, and CATL's procurement organizations in China and Japan now dictate 90-day rolling forecasts with penalty clauses for delivery variance. This consolidation is most visible in German automotive clusters where electrification program awards bundle thermistor contracts across multiple vehicle platforms into single-source arrangements.
Thermistor Temperature Sensor Market Segmentation
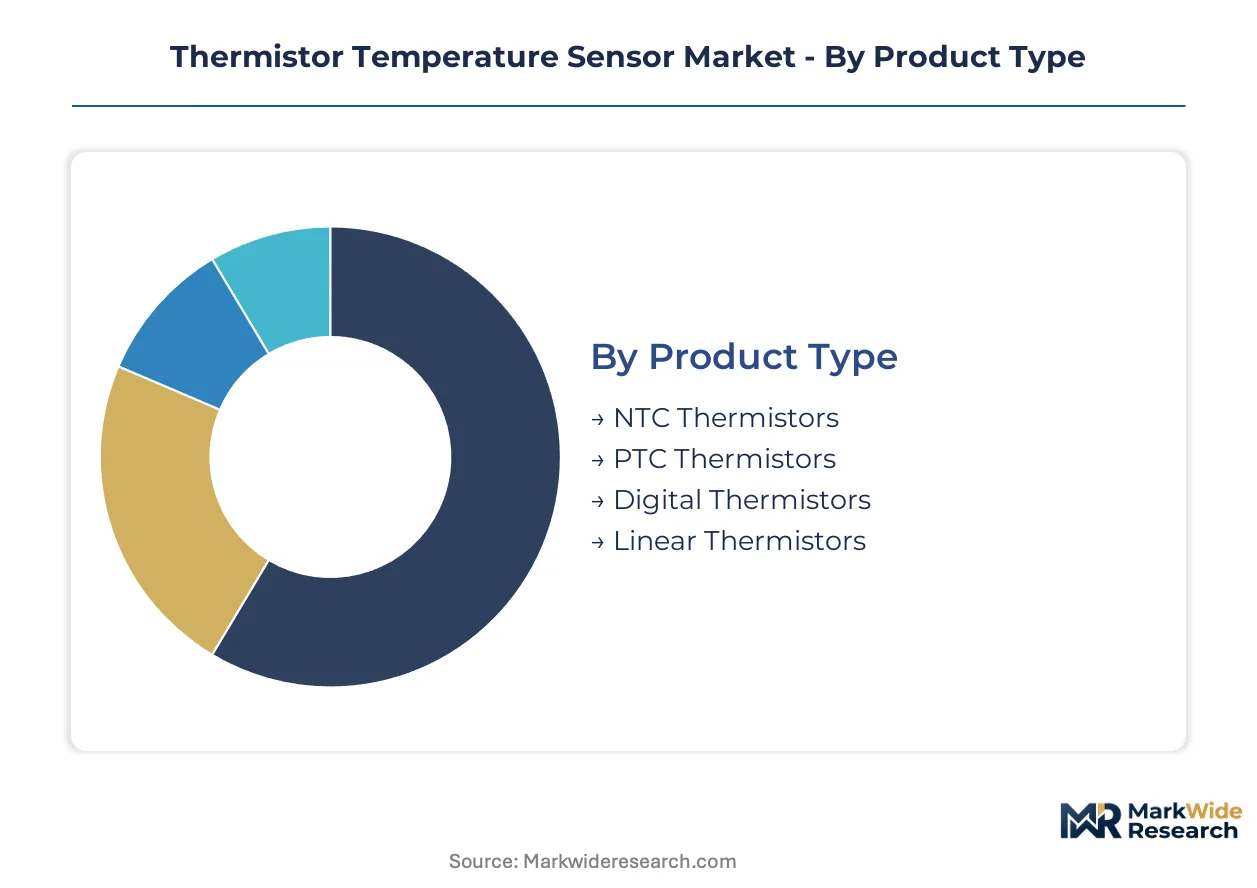
Thermistor sensor procurement cycles vary dramatically across segments, with automotive qualification timelines stretching to 18-24 months while consumer electronics refresh quarterly. Understanding these velocity differentials helps suppliers calibrate inventory strategies and R&D resource allocation.
Product Type:
NTC variants turn inventory fastest through white goods and mobile device channels, while digital thermistors sit in year-long industrial validation queues before volume deployment.
- NTC Thermistors:Metal oxide ceramics of manganese, nickel, and cobalt oxides deliver negative temperature coefficient behavior with resistance decreasing as temperature rises. German automotive OEMs and Japanese appliance manufacturers anchor demand for precision-calibrated NTC arrays in battery thermal management and refrigerator compressor protection.
- Digital Thermistors:Silicon-integrated devices combine sensing elements with onboard ADC and serial communication protocols, enabling direct microcontroller interfacing without external signal conditioning. Industrial IoT deployments in US manufacturing facilities and German Industry 4.0 retrofits are absorbing these units despite 40-60% unit cost premiums over analog alternatives.
- PTC Thermistors:Positive temperature coefficient devices manufactured from barium titanate ceramics serve self-regulating heating and overcurrent protection applications.
- Linear Thermistors:Voltage-linear output variants simplify system design by eliminating complex resistance-to-temperature conversion algorithms.
NTC Thermistors anchors the volume base while Digital Thermistors gains share at the steepest rate.
Application:
Cost tier stratification separates high-reliability automotive and medical applications from price-sensitive consumer electronics, with certification requirements driving 3-5x unit cost spreads between tiers.
- Automotive Systems:Battery management architectures for electric powertrains demand ±0.05°C accuracy with ISO 26262 ASIL-C/D functional safety ratings. Tier-one suppliers in Germany and South Korea are consolidating vendor lists around qualified ceramic sources capable of fault-tolerant designs and 15-year operational life.
- Medical Devices:Patient monitoring equipment requires FDA 510(k) or equivalent regulatory clearance with interchangeability guarantees under Japan's METI JIS standards. German diagnostic equipment manufacturers and US hospital system procurement organizations drive specification harmonization that reduces redesign costs for multi-market deployments.
- Consumer Electronics:Smartphones, laptops, and wearables prioritize miniaturization and cost minimization over absolute precision.
- Industrial Equipment:Process control systems in chemical, food processing, and HVAC applications balance accuracy with environmental robustness.
Automotive Systems commands the highest unit economics while Medical Devices demonstrates the most resilient pricing through regulatory moats.
End User:
Volume concentration among large-scale manufacturers enables dedicated production lines and custom formulation development, while fragmented healthcare and research demand pulls standard catalog products.
- Manufacturers:Automotive OEMs, tier-one suppliers, and appliance producers purchase thermistors at million-unit annual scales with vendor-managed inventory arrangements. Bosch, Denso, and CATL procurement organizations in China, Germany, and Japan dictate 90-day rolling forecasts with penalty clauses for delivery variance.
- Healthcare Facilities:Hospital systems and clinics source patient monitoring sensors through group purchasing organizations with emphasis on FDA-cleared, multi-parameter compatibility.
- Research Institutions:Academic and government laboratories require calibrated reference-grade sensors with traceable NIST documentation.
- Retailers:Distributors and aftermarket channels serve repair, replacement, and hobbyist demand with limited technical support requirements.
Manufacturers dominates procurement volumes while Healthcare Facilities generates the most stable recurring revenue streams through equipment refresh cycles.
Technology:
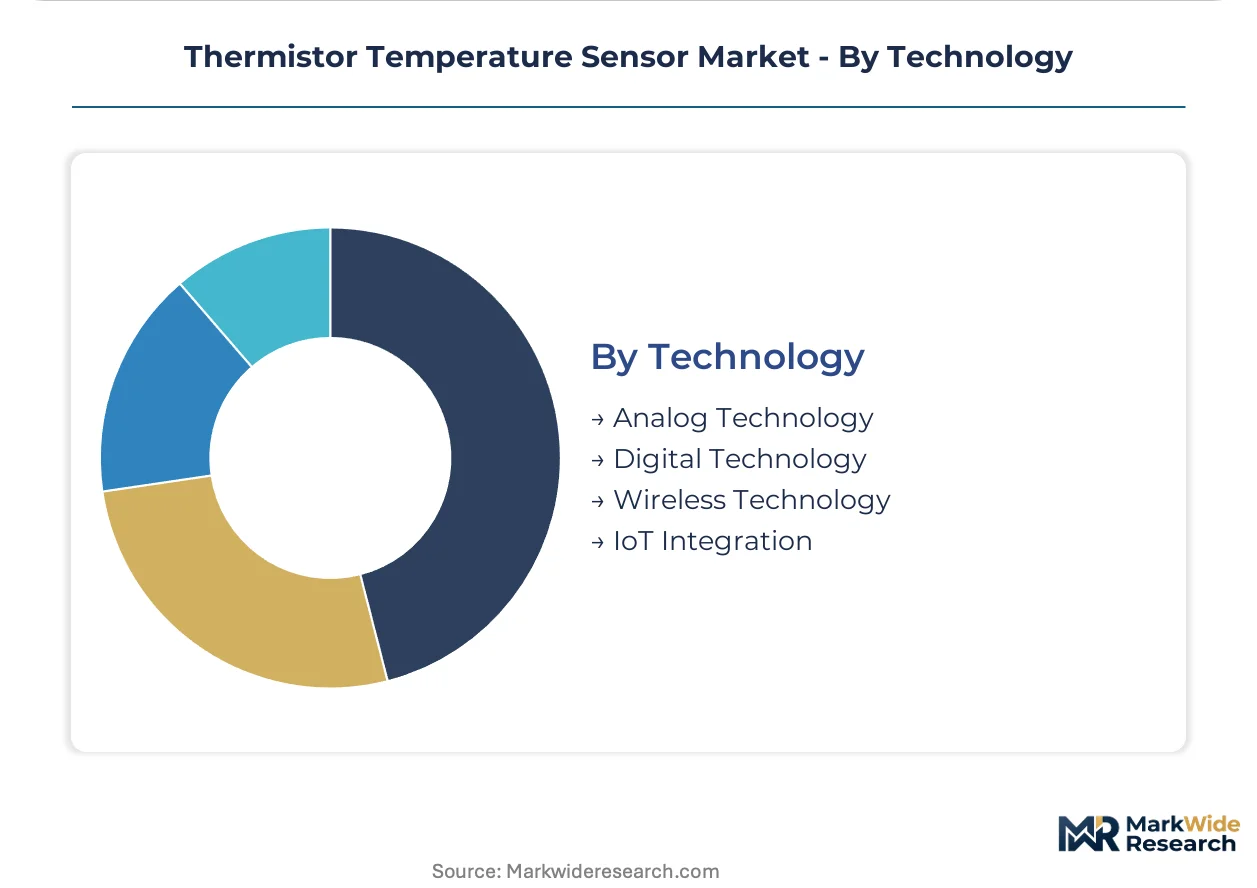
Supply concentration in analog ceramic manufacturing contrasts with distributed digital and wireless technology development across semiconductor and RF component ecosystems.
- Analog Technology:Traditional resistance-output thermistors dominate installed base with established supply chains for ceramic formulation, sintering, and calibration. Manganese and cobalt oxide supply chains concentrate in southern African mining and Chinese refining, exposing producers to geopolitical disruption.
- IoT Integration:Cloud-connected sensors with edge computing capabilities enable predictive maintenance contracts and usage-based service models. German industrial automation vendors and US facility management platforms are piloting subscription-based thermal monitoring that collapses hardware and analytics into single vendor relationships.
- Digital Technology:Integrated ADC and communication protocol devices reduce BOM complexity in space-constrained applications.
- Wireless Technology:Battery-powered, radio-enabled sensors eliminate wiring costs in retrofit and temporary monitoring scenarios.
Analog Technology retains the largest installed base while IoT Integration climbs fastest as industrial customers shift toward outcome-based service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites Europe's ceramic oxide import flows for thermistor manufacturing. German automotive OEMs and tier-one suppliers cluster along the Rhine-Ruhr corridor, drawing precision sensor components through this maritime gateway.
United States
The Inflation Reduction Act's domestic content requirements are localizing thermistor assembly for heat pump and battery manufacturing. NHTSA battery safety protocols mandate precision thermal monitoring for electric vehicle platforms. Detroit's automotive engineering corridor is absorbing qualified sensor vendors into electrification program supply chains.
Germany
EU F-Gas Regulation refrigerant transitions are expanding NTC sensor deployments in residential HVAC retrofits. The KBA enforces functional safety standards for automotive battery management thermistors. Stuttgart's automotive cluster is consolidating vendor lists around ceramic sensor sources capable of ISO 26262 ASIL-C/D ratings.
Japan
METI JIS standards for patient monitoring equipment are harmonizing specifications across medical device exports. PMDA regulatory clearance requirements create interchangeability guarantees that reduce redesign costs for multi-market deployments. Osaka's precision electronics manufacturing belt is scaling ceramic NTC production for domestic appliance and automotive demand.
China
MIIT dual carbon goals are accelerating electric vehicle thermal management sensor procurement. GB standards govern industrial automation sensor interchangeability in process control applications. Shenzhen's electronics manufacturing ecosystem is digitizing thermistor outputs for IoT-connected industrial platforms.
South Korea
MFDS medical device regulations are aligning with international standards to facilitate export-oriented sensor production. The Seoul Capital Area's battery manufacturing concentration is driving thermistor array integration into CATL and LG Energy Solution supply chains. Busan-Ulsan's port infrastructure is handling ceramic oxide imports for regional sensor fabrication.
Thermistor Temperature Sensor Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in ceramic formulation and thin-film deposition. The vendor base concentrates around three strategic tiers: diversified industrial conglomerates with aerospace heritage, vertically integrated ceramic manufacturers with captive oxide supply, and semiconductor specialists digitizing sensor outputs. Consolidation pressures are intensifying as automotive tier-one suppliers compress vendor lists and demand vendor-managed inventory arrangements. Geographic expansion and backward integration into ceramic raw materials represent the dominant competitive moves.
Within the diversified industrial tier, Honeywell International Inc. and Vishay Intertechnology, Inc. exemplify contrasting strategic positions. Honeywell anchors North American premium contracts through aerospace and industrial heritage. Vishay occupies a position emphasizing in-house production of ceramic formulations and thin-film deposition capabilities. Murata Manufacturing Co., Ltd. represents the scale-driven archetype with manufacturing presence across multiple Asian facilities.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Vishay Intertechnology, Inc. |
| Murata Manufacturing Co., Ltd. |
| Panasonic Corporation |
| Amphenol Advanced Sensors |
| TDK Corporation |
| Texas Instruments Inc. |
| Littelfuse, Inc. |
| TE Connectivity Ltd. |
| Others |
Value Network & Pricing Analysis
Raw material concentration in southern African manganese and cobalt oxide mining determines both the premium-mid-economy pricing differentiation across automotive, medical, and consumer tiers and the geographic clustering of ceramic formulation facilities near Chinese refining operations.
Pricing Analysis
Volume-discount tiering structures separate million-unit automotive contracts with vendor-managed inventory arrangements from spot-market consumer electronics procurement. Price differentiation hinges on ISO 26262 ASIL certification grade and customization depth for battery management integration. Cost compression in standard-grade NTC segments is intensifying because Chinese white goods manufacturers are consolidating supplier panels. Consumer electronics OEMs exhibit the highest price sensitivity, while German automotive tier-one suppliers prioritize qualification reliability over unit cost.
Supply Chain Analysis
Export-control regimes on advanced ceramic processing equipment limit technology transfer to emerging sensor fabrication facilities. Manufacturing gravity centers on China, Japan, and Germany for precision-calibrated NTC arrays. Supply chains draw from manganese and cobalt oxide feedstock concentrated in southern African mining districts and Chinese chemical refining complexes. Single-source vulnerability permeates medical-grade ceramic formulations subject to REACH nickel compound restrictions. Distribution runs through tier-one automotive supplier consolidation programs and direct OEM contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering through the automotive electrification cycle, with battery thermal management sensor counts per vehicle expanding from legacy ICE baselines.
For Market Incumbents: Insulate qualified supplier status through captive ceramic oxide supply arrangements and accelerated ASIL-D certification pipelines. Silicon-based temperature sensing elements threaten traditional NTC market share in automotive battery modules. Backward integration into manganese oxide refining hedges against geopolitical disruption of southern African supply corridors. For New Entrants and Emerging Players: Industrial IoT predictive maintenance platforms in US manufacturing facilities represent the most penetrable entry point for digital thermistor solutions with onboard calibration. India's PLI scheme electronics manufacturing zones offer localized assembly opportunities with reduced import dependency. Partner with German Industry 4.0 retrofit integrators to bypass lengthy direct-OEM qualification cycles. For Investors and Strategic Acquirers: EU F-Gas Regulation refrigerant phasedown deadlines reshape the acquisition landscape toward sensor vendors with EN 378-certified fail-safe architectures for flammable coolant systems. Long-term viability centers on automotive electrification program participation and medical device regulatory moat sustainability. Watch for tier-one supplier vendor list consolidation announcements as inflection indicators for market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Formulation Backward Integration | Captive manganese oxide supply secures qualified supplier status with Bosch and CATL procurement organizations. |
| ASIL-D Functional Safety Certification | ISO 26262 ratings unlock single-source arrangements for electric powertrain battery management architectures. |
| Digital Thermistor Platform Launch | MEMS-integrated sensors with onboard ADC enable subscription-based predictive maintenance contracts. |
| India Manufacturing Footprint Expansion | PLI scheme incentives attract assembly investments serving domestic process control and appliance demand. |
| EN 378 Safety Standard Pre-certification | Fail-safe sensor arrays position vendors for EU F-Gas Regulation heat pump retrofit procurement cycles. |
Research Methodology
Desk research of ceramic sensor technical datasheets, automotive supplier qualification databases, and regulatory filing repositories preceded structured interviews with tier-one supplier procurement directors, OEM platform engineers, ceramic formulation R&D leads, and industrial IoT integration specialists. Secondary validation drew from NHTSA battery safety protocols, EU F-Gas Regulation implementation guidance, METI JIS standard documentation, and SEC filings of diversified industrial sensor manufacturers. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Assumptions around automotive electrification penetration rates, heat pump refrigerant transition timelines, and medical device regulatory harmonization progressions were held fixed across sensitivity scenarios. Segmentation dimensions modeled include thermistor product type, application vertical, end-user scale tier, and technology integration level. CAGRs were derived from regression analysis of historical shipment data against named driver variables including battery pack sensor density and HVAC retrofit regulatory mandates.
Macroeconomic conditions sit as an overlay; deviation in electric vehicle adoption curves or rare earth oxide price volatility would shift the trajectory. Forecasts reflect documented assumptions regarding tier-one supplier consolidation velocity and REACH compliance timeline stability. Material shifts in EU F-Gas Regulation enforcement intensity or automotive functional safety standard revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Radar Sensor Market
Sensors and Controls
Surface Acoustic Wave Sensors Market
Sensors and Controls
Europe Air Purifier Market
Sensors and Controls
Asia-Pacific Wireless Brain Sensors Market
Sensors and Controls
Piezoresistive Pressure Sensor Market
Sensors and Controls
US Wireless Sensors Market
Sensors and Controls
Industrial Wireless Sensor Market
Sensors and Controls
North America Temperature Sensor Market
Sensors and Controls
Humidity Sensor Market
Sensors and Controls
Fork Sensor Market
Sensors and Controls
Fluid Sensors Market
Sensors and Controls
Water Quality Sensor Market
Sensors and Controls
Biomedical Pressure Sensors Market
Sensors and Controls
UV Sensors Market
Sensors and Controls
High Purity Flow Meter Market
Sensors and Controls
MEMS Combo Sensors Market