
 On-Board Magnetic Sensors Market | 2026-2036
On-Board Magnetic Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
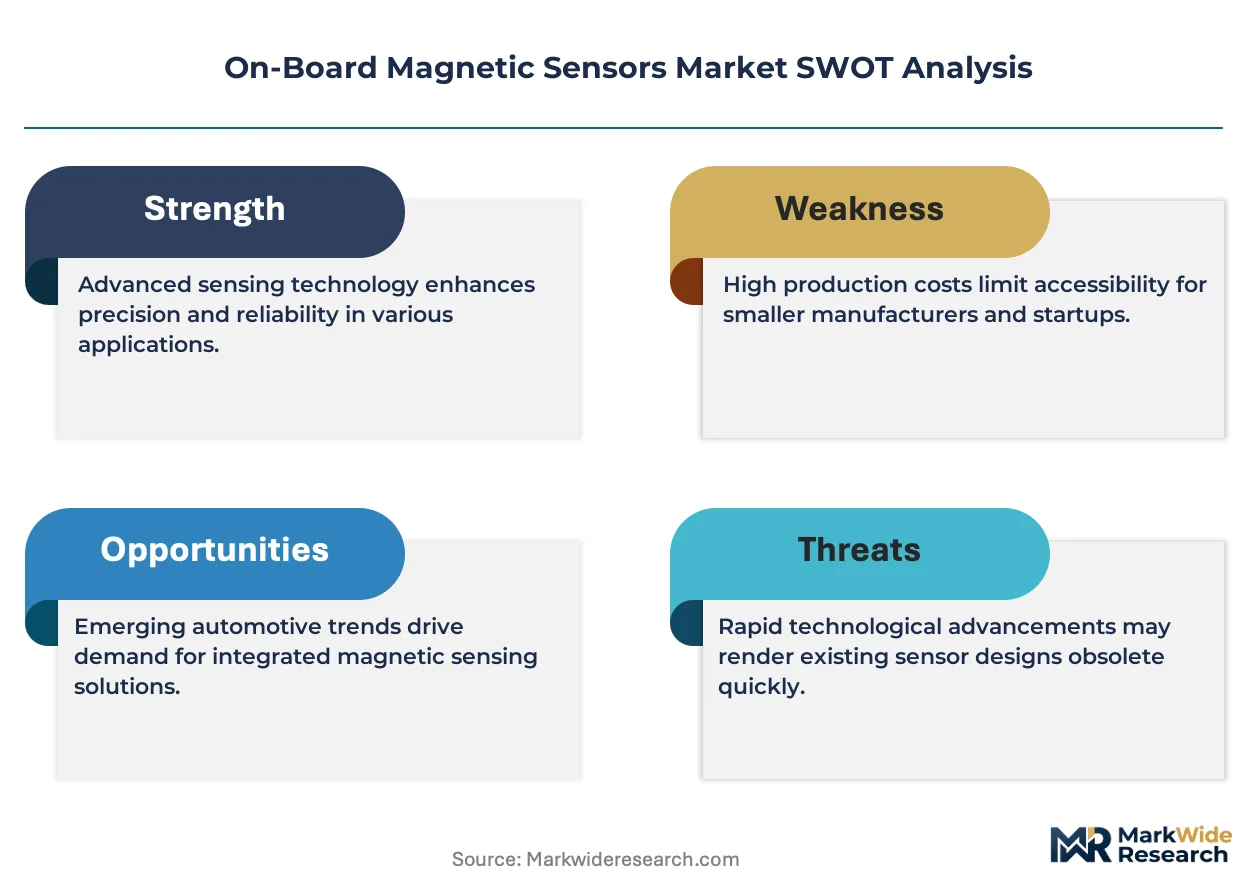
On-Board Magnetic Sensors Market Analysis
The direct OEM supply channel for magnetic sensing components is narrowing as tier-one module suppliers consolidate vendor lists. Infineon Technologies AG leverages its insulated-gate bipolar transistor co-packaging strategy to embed Hall sensors directly into power modules, reducing customer bill-of-materials complexity. Honeywell International anchors the aerospace segment with radiation-hardened fluxgate designs for satellite attitude control. NXP Semiconductors N.V. competes across automotive safety domains with programmable linear Hall devices qualified to ASIL-D integrity levels.
On-board magnetic sensors detect field strength, direction, or current through solid-state transduction, typically operating from -40°C to 150°C with microtesla to millitesla resolution depending on architecture. These devices serve as non-contact feedback elements in motion control, energy management, and navigation systems where mechanical wear or galvanic isolation precludes alternative technologies. Hall Effect sensors lead volume shipments due to cost scalability in silicon CMOS foundries, while Giant Magnetoresistance variants capture premium positioning in hard disk drives and precision encoders where nanometer-scale resolution justifies higher wafer processing costs. Fluxgate technology occupies niche military and geophysical applications demanding sub-nanotesla stability.
The US NHTSA mandates electronic stability control and automatic emergency braking systems that embed wheel-speed and steering-angle magnetic sensors, while EU REACH and RoHS frameworks restrict hazardous substances in semiconductor packaging materials. Japan's METI enforces JIS standards for industrial automation equipment that specify electromagnetic compatibility thresholds for sensor interfaces. Stakeholders must monitor how China's GB standards for new energy vehicles evolve their current-sensing accuracy requirements, as these specifications will determine which transduction architectures achieve design wins in the world's largest EV production base.
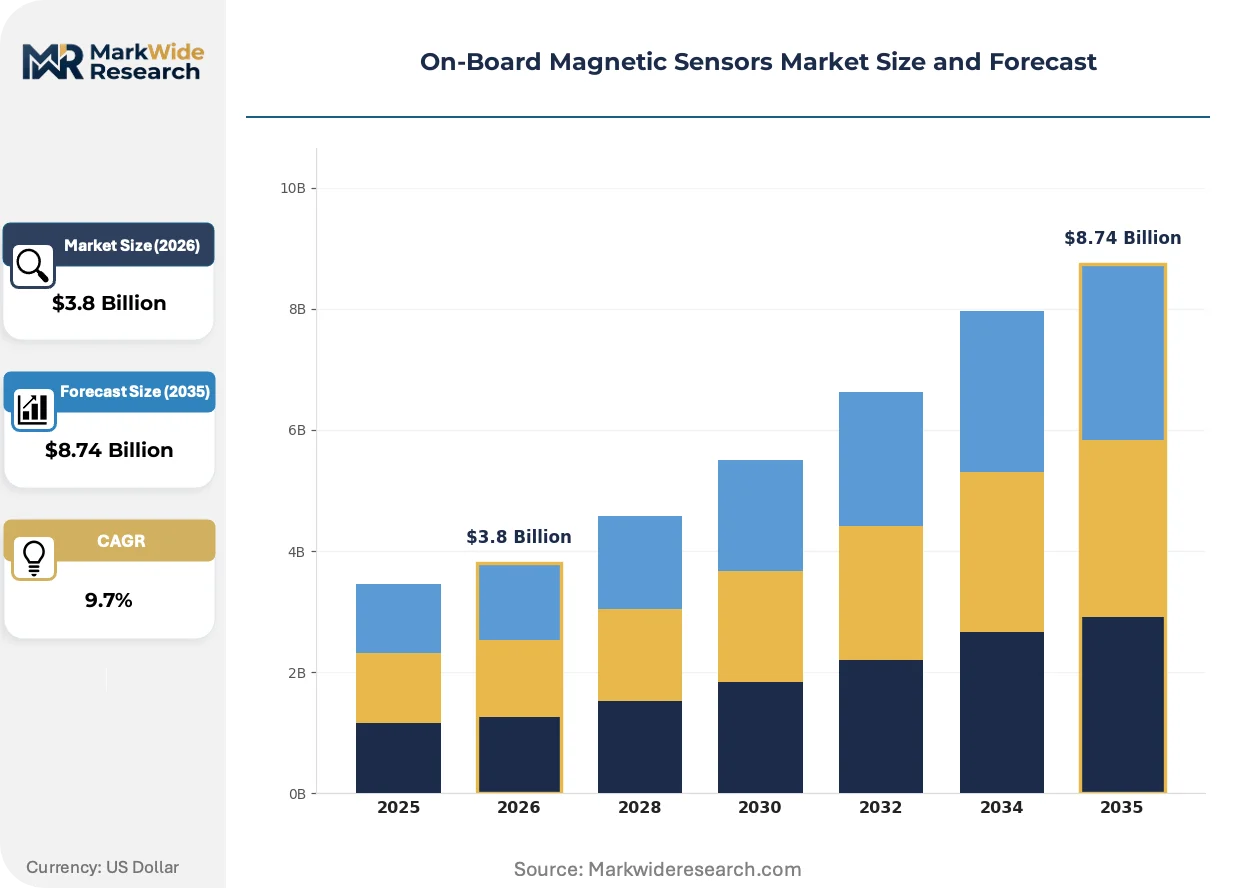
Market Dynamics
Automotive electrification programs in Germany, Japan, and the United States are consolidating magnetic sensor procurement around Hall Effect architectures embedded directly into power modules, compressing vendor lists and raising qualification barriers for second-tier suppliers.
Growth Catalysts
- NHTSA Safety Mandates:Electronic stability control and automatic emergency braking regulations require wheel-speed and steering-angle magnetic sensors, embedding demand into every new vehicle platform sold in the United States.
- China EV Production Corridors:Domestic OEMs in Shenzhen, Shanghai, and Hefei specify on-board magnetic sensors for motor control and regenerative braking systems, concentrating volume demand in the world's largest battery-electric manufacturing base.
- Silicon CMOS Cost Scalability:Hall Effect sensors manufactured on standard foundry processes achieve unit economics that Giant Magnetoresistance and fluxgate alternatives cannot match at automotive production volumes.
Market Restraints
- Wafer Processing Cost Differential:Giant Magnetoresistance variants require specialized thin-film deposition equipment, limiting fabrication to captive lines at Toshiba and TDK rather than merchant foundries.
- Raw Magnet Material Concentration:Neodymium and dysprosium supply chains route through Chinese rare-earth processing facilities, exposing sensor manufacturers to export quota volatility and price spikes.
- EU REACH Packaging Restrictions:Hazardous substance limitations on lead frames and mold compounds force redesigns of qualified automotive sensor packages, extending re-certification timelines by 18-24 months.
Strategic Opportunities
- India Industrial Automation:METI-aligned Japanese equipment makers are localizing production under India's PLI scheme for manufacturing, creating fresh demand for JIS-standard magnetic encoders in Pune and Chennai automation clusters.
- Sensor-Fusion Convergence:Integration of Hall Effect current sensing with MEMS inertial measurement units enables single-module traction motor feedback, reducing wiring harness complexity in 800-volt EV architectures.
- US Inflation Reduction Act:Domestic content bonuses for battery and electric drive assembly incentivize reshoring of magnetic sensor module production to Michigan and Ohio supplier parks.
Industry Challenges
- ASIL-D Functional Safety Certification:Automotive safety integrity level qualification for programmable linear Hall devices requires fault-mode analysis documentation exceeding 2,000 pages per product variant.
- Legacy System Integration Friction:12-volt vehicle architectures in commercial truck segments resist 48-volt sensor interface adoption, forcing dual-voltage product line maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | On-Board Magnetic Sensors Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Hall Effect, Anisotropic Magnetoresistance, Giant Magnetoresistance, Fluxgate End User: Aerospace, Automotive, Consumer Electronics, Industrial Automation Application: Navigation Systems, Position Sensing, Current Sensing, Magnetic Field Measurement Deployment: Embedded Systems, Portable Devices, Fixed Installations, Wearable Technology |
| Companies Covered | Infineon Technologies AG, Honeywell International, TE Connectivity, NXP Semiconductors N.V., Asahi Kasei Microdevices Corporation, TDK Corporation, Allegro MicroSystems, Melexis NV, Austria Mikro Systeme, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
On-Board Magnetic Sensors Market Emerging Trajectories
Magnetic sensing architectures are virtualizing physical measurement functions, collapsing discrete component counts while embedding intelligence at the sense node. Three developments are compressing traditional supply chain structures.
Current reconstruction algorithms are virtualizing physical shunt resistors in battery management systems. Tier-one module suppliers in Stuttgart and Nagoya are adopting software-defined current sensing for 400-volt and 800-volt traction inverters. This virtualization is eliminating copper shunt material from high-voltage isolation barriers, reducing module mass and thermal management complexity.
EU F-Gas Regulation phase-down schedules are pressuring refrigerant monitoring in electric vehicle thermal management systems. Magnetic sensors detecting compressor motor position and current are displacing Hall Effect alternatives in heat pump architectures. German OEMs are qualifying fluxgate-based current transducers for R-1234yf system monitoring, anticipating refrigerant containment mandates tightening through 2027.
Direct OEM contracting is displacing tier-two distribution for high-volume magnetic sensor procurement. EV platform teams at domestic Chinese manufacturers are negotiating specification locks directly with NXP and Infineon field application engineers, bypassing traditional component distributors. This channel compression is most visible in Shenzhen and Hefei, where battery pack integrators consolidate magnetic feedback device sourcing under single-supplier agreements.
On-Board Magnetic Sensors Market Segmentation
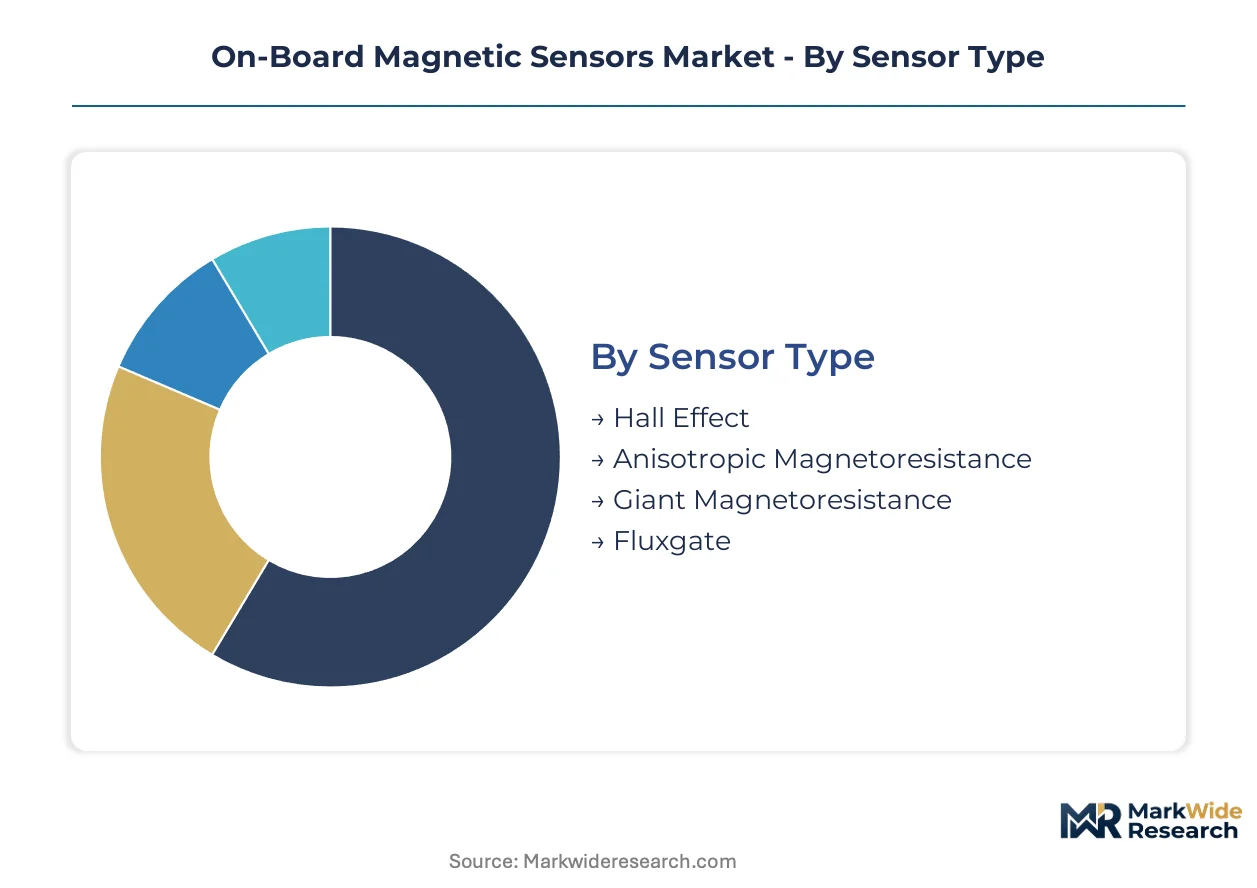
On-board magnetic sensors serve divergent cycle-time requirements across automotive, aerospace, and industrial domains. Hall Effect devices refresh design cycles every 18-24 months to match powertrain electrification roadmaps, while fluxgate sensors in satellite applications endure decade-long qualification timelines. Understanding these velocity differentials enables suppliers to align R&D cadence with customer procurement rhythms.
Sensor Type:
Hall Effect sensors compress design-to-production cycles through standard CMOS foundry compatibility, whereas fluxgate architectures demand specialized magnetic core fabrication extending lead times by 8-12 months.
- Hall Effect:Silicon-based transduction manufactured on 180nm and 130nm foundry nodes achieves -40°C to 150°C automotive qualification. NHTSA-mandated electronic stability control systems in Detroit and Stuttgart vehicle platforms embed these devices for wheel-speed feedback. Infineon's co-packaging with IGBT power modules eliminates discrete sensor mounting.
- Giant Magnetoresistance:Multilayer thin-film structures of cobalt, iron, and nickel alloys deliver sub-nanometer resolution for precision encoder applications. Hard disk drive manufacturers in Japan's Tohoku region specify GMR heads despite 40% wafer cost premiums over Hall alternatives.
- Anisotropic Magnetoresistance:Permalloy thin-film sensors bridge cost-performance gaps in mid-tier industrial encoders.
- Fluxgate:Saturation-core designs achieve sub-nanotesla stability for satellite attitude control and geophysical surveying equipment.
Hall Effect anchors the volume base while Giant Magnetoresistance gains share at the steepest rate in precision positioning applications.
End User:
Cost tier stratification separates aerospace qualification premiums from automotive scale economics, with industrial automation occupying intermediate pricing bands.
- Automotive:Powertrain electrification in Germany, Japan, and the United States consumes Hall Effect current sensors for 400V and 800V battery management. China's Shenzhen and Hefei EV corridors specify on-board magnetic feedback for motor control and regenerative braking systems.
- Aerospace:Radiation-hardened fluxgate designs for satellite attitude determination command 15-20x unit pricing over commercial-grade alternatives. Honeywell's radiation-tolerant packaging qualifies for 15-year orbital missions under NASA and ESA procurement standards.
- Consumer Electronics:MEMS-competing magnetic switches in smartphones and laptops prioritize 0.5mm package height over field resolution.
- Industrial Automation:JIS-standard magnetic encoders from Japanese equipment makers localize production under India's PLI scheme for Pune and Chennai manufacturing clusters.
Automotive dominates shipment volumes while aerospace sustains margin concentration through qualification barriers.
Application:
Application maturity curves separate navigation systems with decades of field validation from emerging current-sensing virtualization in battery management.
- Current Sensing:Software-defined reconstruction algorithms in Stuttgart and Nagoya tier-one modules are displacing copper shunt resistors in 400V and 800V traction inverters. EU F-Gas Regulation phase-down schedules further expand magnetic monitoring in R-1234yf heat pump compressors.
- Position Sensing:Steering-angle and pedal-position feedback for NHTSA automatic emergency braking mandates embed Hall devices in every US-market vehicle platform.
- Navigation Systems:Fluxgate magnetometers in unmanned aerial vehicles and autonomous marine vessels provide heading reference independent of GPS jamming.
- Magnetic Field Measurement:Geophysical surveying equipment and scientific instrumentation demand sub-nanotesla stability for mineral exploration and space weather monitoring.
Position sensing anchors installed base stability while current sensing expands most quickly through electrification program procurement.
Deployment:
Customer type fragmentation separates embedded system procurement through tier-one automotive suppliers from portable device spot-buying through electronics distributors.
- Embedded Systems:Power module integration in Michigan and Ohio supplier parks leverages US Inflation Reduction Act domestic content incentives. Direct OEM contracting in Shenzhen and Hefei bypasses traditional distribution channels for high-volume specification locks.
- Portable Devices:Smartphone compass and lid-closure detection sensors prioritize 1.0mm x 1.0mm WLCP packaging over absolute accuracy specifications.
- Fixed Installations:Factory automation line encoders and wind turbine pitch control systems specify IP67-rated magnetic feedback for 20-year service life.
- Wearable Technology:Fitness tracker orientation sensing accepts relaxed linearity specifications in exchange for sub-milliwatt power consumption.
Embedded systems concentrate revenue density while portable devices extend unit volume through consumer electronics refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors Asia-Pacific semiconductor logistics, channeling magnetic sensor wafers from foundries to automotive module assembly lines across China's eastern seaboard.
United States
NHTSA electronic stability control mandates embed wheel-speed and steering-angle sensors in every Detroit-assembled vehicle platform. The US Inflation Reduction Act domestic content bonuses pull magnetic sensor module production toward Michigan and Ohio supplier parks. EV platform teams in Austin and Fremont negotiate direct specification locks with semiconductor field engineers.
Germany
IGBT co-packaging strategies from Munich-based power semiconductor specialists compress vendor lists for Hall sensor procurement. EU F-Gas Regulation phase-down schedules accelerate fluxgate-based current transducer qualification for R-1234yf heat pump monitoring. Stuttgart tier-one suppliers adopt software-defined current sensing for 800-volt traction inverters.
China
GB standards for new energy vehicles evolve current-sensing accuracy requirements that determine design wins in Shenzhen and Hefei battery pack integration corridors. Domestic OEMs specify on-board magnetic feedback for motor control and regenerative braking systems. Shanghai's wafer foundries achieve 180nm Hall sensor qualification at automotive production volumes.
Japan
METI-enforced JIS standards for industrial automation equipment specify electromagnetic compatibility thresholds for sensor interfaces in Nagoya manufacturing clusters. Tohoku-region hard disk drive manufacturers specify Giant Magnetoresistance heads despite wafer cost premiums. Japanese equipment makers localize encoder production under India's PLI scheme for Pune and Chennai clusters.
India
PLI scheme manufacturing incentives attract METI-aligned Japanese automation equipment makers to Maharashtra and Tamil Nadu industrial corridors. BIS standards for industrial machinery specify magnetic encoder integration in factory automation lines. Pune automation clusters generate fresh demand for JIS-standard magnetic feedback devices.
On-Board Magnetic Sensors Market Vendor Landscape
On the supply side, the industry is consolidating around tier-one module suppliers who compress vendor lists and raise qualification barriers for second-tier component manufacturers. Hall Effect architectures manufactured on standard CMOS foundry nodes achieve unit economics that specialized thin-film alternatives cannot match. Three strategic archetypes dominate: silicon-foundry-integrated power semiconductor specialists, radiation-hardened aerospace component suppliers, and programmable automotive safety device manufacturers. Competitive moves center on IGBT co-packaging integration and direct OEM contracting that bypasses traditional distribution channels.
Among European semiconductor specialists, Infineon Technologies AG and NXP Semiconductors N.V. occupy positions that exemplify the foundry-integrated archetype, embedding sensing functions directly into power modules to reduce customer bill-of-materials complexity. Honeywell International represents the radiation-hardened tier, anchoring aerospace segment positioning through fluxgate designs qualified for extended orbital missions. These three companies illustrate how qualification intensity and packaging integration separate premium-tier suppliers from merchant foundry competitors.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| Honeywell International |
| TE Connectivity |
| NXP Semiconductors N.V. |
| Asahi Kasei Microdevices Corporation |
| TDK Corporation |
| Allegro MicroSystems |
| Melexis NV |
| Austria Mikro Systeme |
| Others |
Supply Flow & Price Mechanics
The Port of Shanghai's container throughput cost dynamics compress margins for Hall Effect sensor wafers transiting from foundries to automotive module assembly lines, concentrating pricing power among tier-one power semiconductor specialists while fragmenting margin capture across second-tier packaging houses.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D automotive safety certification from industrial-grade and consumer-tier alternatives. Price differentiation hinges on functional safety integrity level and foundry volume commitment, with automotive OEM direct contracts commanding steeper discounts than distributor spot purchases. Cost compression in consumer-grade Hall devices is intensifying because merchant foundry competition erodes silicon CMOS wafer premiums. Battery-electric vehicle platform teams exhibit lowest price sensitivity due to specification lock requirements, while smartphone compass integrators maximize supplier switching to extract volume concessions.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic planning for magnetic sensor module suppliers serving Detroit and Austin EV corridors. Manufacturing concentrates in China, Taiwan, and South Korea for wafer fabrication, with Germany and Japan anchoring precision fluxgate core production. Rare-earth magnet supply draws from Chinese neodymium and dysprosium processing facilities, exposing sensor manufacturers to export quota volatility. Single-source vulnerability in specialized thin-film deposition equipment for Giant Magnetoresistance architectures limits fabrication flexibility. Distribution runs through tier-one automotive module suppliers consolidating vendor lists, with direct OEM contracting displacing traditional component distributors in Shenzhen and Hefei.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The on-board magnetic sensors market is emerging from a cyclical trough driven by automotive electrification capital expenditure cycles, with OEM platform standardization programs now restocking sensor inventories after inventory destocking phases.
For Market Incumbents: Insulate qualification moats by deepening ASIL-D documentation libraries beyond 2,000 pages per variant to delay second-tier supplier certification timelines. Capture backward integration into rare-earth magnet processing through offtake agreements with Chinese processors, mitigating dysprosium price spike exposure. Lock direct OEM specification relationships in Shenzhen and Hefei before emerging programmable Hall competitors achieve automotive qualification.
For New Entrants and Emerging Players: Build out JIS-standard magnetic encoder production capacity in Pune and Chennai to serve METI-aligned Japanese equipment makers localizing under India's PLI scheme. Target industrial automation retrofit segments where 12-volt legacy architectures resist 48-volt migration, creating dual-voltage product gaps incumbent automotive specialists ignore. Pursue sensor-fusion module partnerships with MEMS inertial measurement unit suppliers to penetrate 800-volt EV traction motor feedback.
For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down schedules through 2027 reshape the acquisition landscape, elevating fluxgate-based current transducer specialists qualified for R-1234yf heat pump monitoring. Five-to-ten-year viability favors radiation-hardened aerospace component suppliers with NASA and ESA pedigree over merchant foundry competitors. Watch for GB standard evolution on new energy vehicle current-sensing accuracy as the signal indicating which transduction architectures achieve design wins in China's EV production corridors.
| Strategic Initiative | Industry Significance |
|---|---|
| IGBT Co-Packaging Integration | Infineon's embedded Hall sensor strategy eliminates discrete mounting for Detroit powertrain modules. |
| Direct OEM Contracting | Bypassing tier-two distributors in Shenzhen secures specification locks with domestic Chinese battery pack integrators. |
| Rare-Earth Supply Agreement | Captive neodymium sourcing insulates against Chinese export quota volatility affecting sensor magnet costs. |
| Sensor-Fusion Module Development | Combining Hall Effect current sensing with MEMS inertial units reduces wiring harness complexity in 800-volt architectures. |
| ASIL-D Certification Investment | Programmable linear Hall qualification to automotive safety integrity levels raises barriers for second-tier entrants. |
Methodological Framework
A standing panel of Tier 1 supplier procurement directors, OEM platform engineers, semiconductor foundry operations managers, and automotive safety system architects provided ongoing calibration across primary interview cycles. Secondary validation drew from NHTSA regulatory filings, EU REACH substance restriction updates, METI JIS standard publications, and China GB new energy vehicle specifications. Bottom-up unit shipment estimates from wafer foundry output data triangulated against top-down automotive production forecasts from vehicle registration databases.
Scenario-bracketing framed low, base, and high cases across the projection horizon without year-specific anchoring. Segmentation dimensions modeled include sensor type transduction architecture, end-user industry vertical, application function, deployment customer type, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to base-year market sizing, with automotive electrification program timelines and industrial automation capital expenditure cycles serving as key forecast inputs.
Stress conditions across rare-earth export quota volatility, EU packaging material restriction enforcement timelines, and automotive platform standardization adoption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on foundry capacity expansion, certification timeline compression, and direct OEM contracting velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Steam Trap Monitor Market
Sensors and Controls
Digital Temperature Gauge Market
Sensors and Controls
Japan Sensor Market
Sensors and Controls
Europe Smart Glove Market
Sensors and Controls
Battery Leakage Detection Sensor Market
Sensors and Controls
Light Detection and Ranging (Lidar) Market
Sensors and Controls
Vibration Sensor Market
Sensors and Controls
Magnetic Sensor Market
Sensors and Controls
Electric Vehicle (EV) Sensor Market
Sensors and Controls
Latin America Wearable Sensors Market
Sensors and Controls
TMAH Concentration Monitor Market
Sensors and Controls
High-Performance IMU Market
Sensors and Controls
Middle East and Africa Wearable Sensors Market
Sensors and Controls
Clamp-On Ultrasonic Gas Flow Meter Market
Sensors and Controls
Magnetoresistance Sensor Market
Sensors and Controls
Industrial Combustion Control Components and Systems Market