
 Europe Advanced CO2 Sensor Market | 2026-2036
Europe Advanced CO2 Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Advanced CO2 Sensor Market Analysis
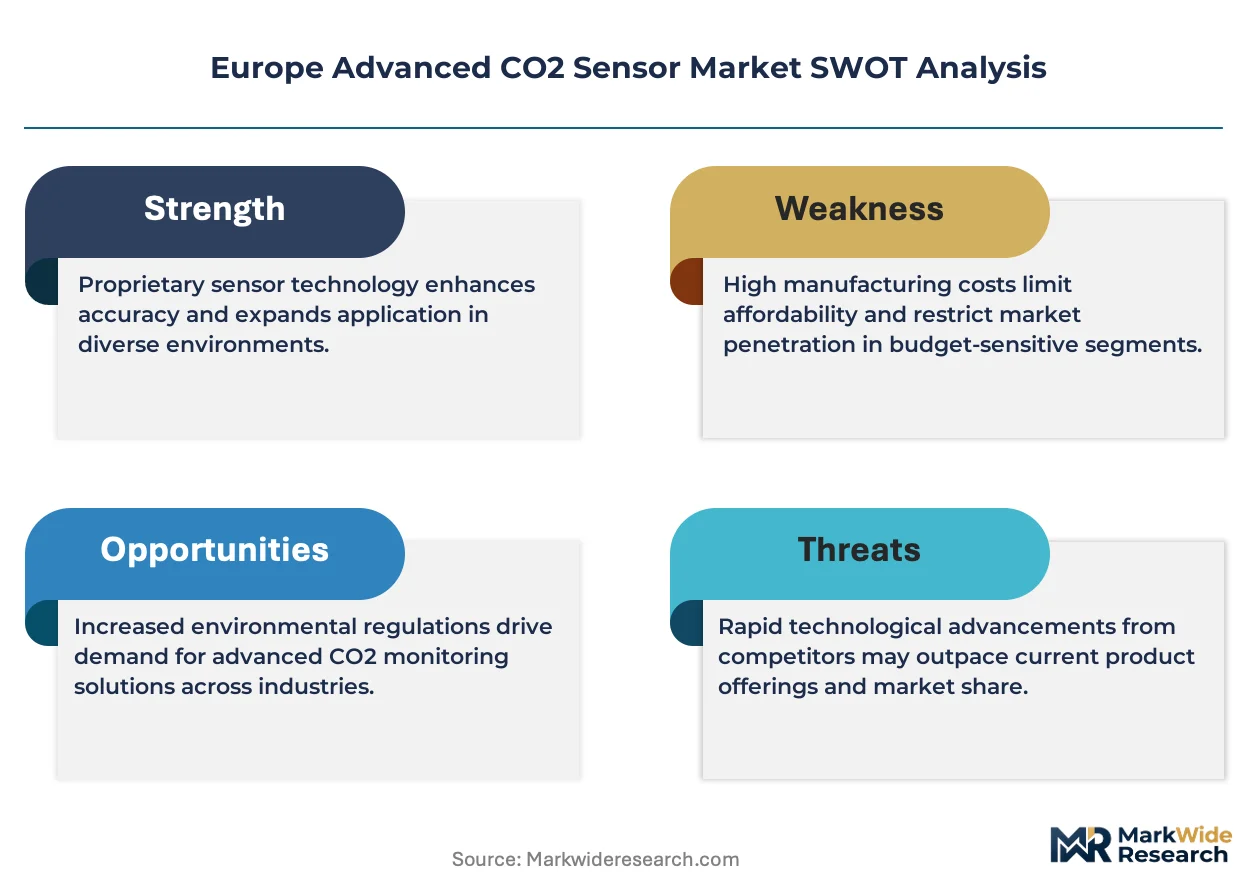
The EU Green Deal's building renovation targets is expanding the addressable base for advanced CO2 sensing across commercial and residential stock. Honeywell leverages its building automation portfolio to anchor retrofit contracts in Western European metropolitan zones. Siemens sustains technology leadership through integrated HVAC control architectures that embed optical sensing modules. Sensirion competes on miniaturization, occupying the portable and battery-powered instrument segment with MEMS-based designs.
Europe advanced CO2 sensors are electrochemical or photonic devices that measure carbon dioxide concentration in ambient or process environments, typically resolving differences of 50-100 ppm to trigger ventilation or alarm responses. Their primary purpose is to protect occupant health, optimize energy consumption, and ensure process integrity in controlled atmospheres. Non-Dispersive Infrared technology dominates installed value due to proven stability and wide dynamic range, while Photoacoustic designs are gaining fastest in battery-constrained applications where power draw determines deployment economics. Indoor Air Quality applications command the deepest margin pools as certification schemes for WELL and BREEAM buildings mandate continuous environmental logging.
EMA, ECHA, and the EU Green Deal framework collectively shape product standards, chemical substance restrictions, and energy performance obligations that determine market access across member states. The F-Gas Regulation indirectly reinforces CO2 sensor demand by accelerating refrigerant transition projects that require leak monitoring and ventilation verification. Stakeholders must monitor how the CSRD's scope-three emissions disclosure rules expand corporate demand for granular indoor environmental data.
Market Dynamics
The EU Green Deal's building renovation mandates are compressing procurement cycles for networked CO2 sensing systems across European commercial real estate, forcing vendors to align product roadmaps with tightening ventilation monitoring obligations.
Growth Catalysts
- F-Gas Regulation:Refrigerant transition projects across Germany and France require leak monitoring and ventilation verification, expanding sensor deployment in HVAC retrofit contracts.
- Commercial real estate:Smart building operators in Western European metropolitan zones are accelerating procurement of optical sensing modules for energy optimization.
- WELL and BREEAM certification:Continuous environmental logging mandates are deepening margin pools in Indoor Air Quality applications across certified building stock.
Market Restraints
- Optical component supply:Concentration of NDIR source and detector manufacturing in East Asian foundries creates input cost volatility and extended lead times for European integrators.
- REACH substance restrictions:Chemical compliance burdens on electrochemical cell materials limit design flexibility and extend qualification timelines for new sensor variants.
- Photoacoustic substitution:Emerging battery-constrained applications favor lower-power alternatives, compressing addressable share for traditional NDIR architectures in portable instruments.
Strategic Opportunities
- Poland and Romania:Underpenetrated commercial building stock in Eastern European member states offers expansion paths as EU cohesion funds flow toward energy efficiency upgrades.
- CSRD scope-three disclosure:Corporate emissions reporting rules are expanding demand for granular indoor environmental data from facility management departments.
- MEMS-photonics convergence:Miniaturized sensing platforms enable new deployment modes in battery-powered and wearable instruments previously inaccessible to conventional architectures.
Industry Challenges
- Calibration technician scarcity:Field service networks lack sufficient trained personnel to support the volume of sensor commissioning required by accelerated retrofit timelines.
- CE marking complexity:Multi-module certification for integrated HVAC control systems creates compliance bottlenecks that delay product launches.
- Legacy BAS integration:BACnet and Modbus protocol fragmentation across existing building automation systems forces custom engineering for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Advanced CO2 Sensor Market |
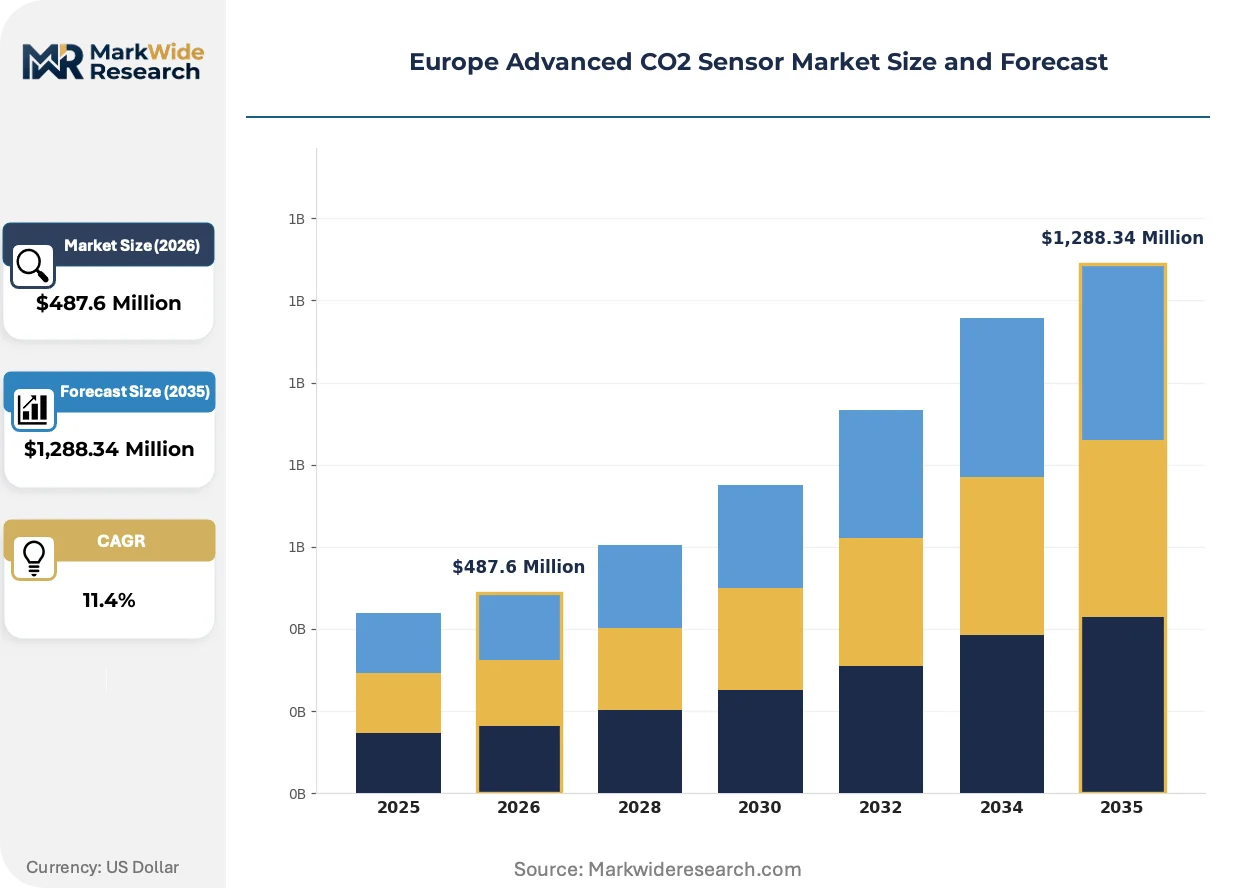
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Dispersive Infrared, Chemical Absorption, Photoacoustic, Optical End User: Industrial Facilities, Smart Buildings, Agriculture Sector, HVAC Systems Technology: Wireless, Wired, Portable, Integrated Application: Indoor Air Quality, Environmental Monitoring, Process Control, Agriculture Management |
| Companies Covered | Honeywell, Siemens, Vaisala, Emerson, Sensirion, Ametek, Gas Sensing Solutions, E + E ELEKTRONIK, Figaro Engineering, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Advanced CO2 Sensor Market Emerging Trajectories
Technology evolution and regulatory compression are reshaping how CO2 sensing platforms deliver value, with power efficiency and data granularity emerging as the primary axes of differentiation.
Photoacoustic spectroscopy is rewriting deployment economics for battery-constrained instruments. Facility managers in Nordic commercial buildings are specifying these modules for wireless sensor networks. The technology is compressing maintenance intervals and enabling dense spatial coverage previously uneconomical with NDIR alternatives.
EMA and ECHA frameworks are tightening substance transparency requirements for sensing components. Manufacturers must now document full material content for electrochemical cells to maintain market access. German HVAC integrators are responding by qualifying optical-only architectures that sidestep chemical restriction risks.
Building operators are unbundling sensor procurement from turnkey automation contracts. Direct purchasing through specialized distributors is displacing bundled OEM supply in French and Dutch commercial retrofits. This pattern is most visible in mid-size office buildings where facility teams possess sufficient technical capability to specify and commission standalone sensing networks.
Europe Advanced CO2 Sensor Market Segmentation
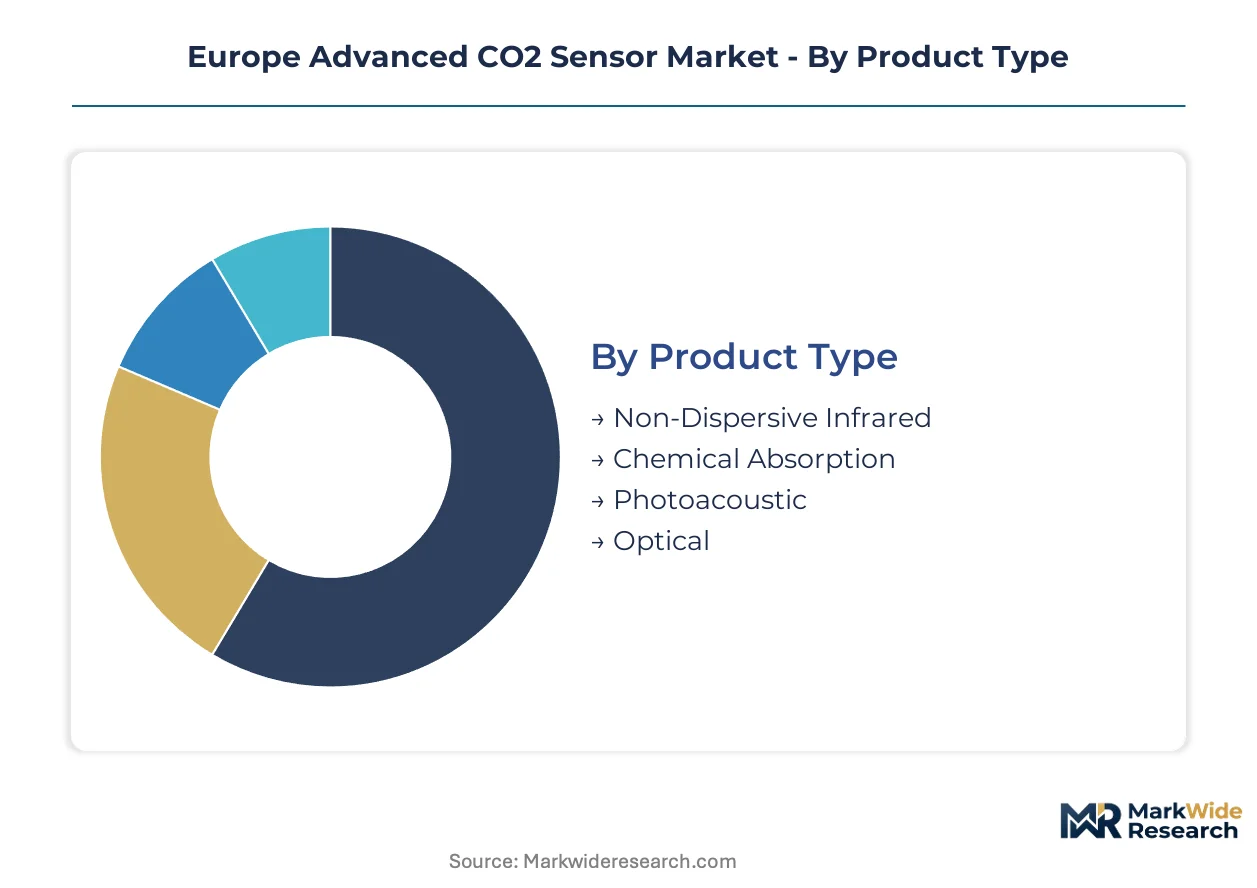
Technology selection in Europe's advanced CO2 sensor market hinges on regulatory compliance pathways. CE marking requirements under the EU Green Deal framework vary sharply across sensing architectures, creating tiered market access costs that reshape competitive positioning.
Product Type:
Non-Dispersive Infrared and Photoacoustic variants face divergent REACH substance documentation burdens under ECHA frameworks, while Optical and Chemical Absorption platforms navigate distinct RoHS exemption categories for photonic versus electrochemical components.
- Non-Dispersive Infrared:NDIR sensors measure CO2 concentration by detecting infrared absorption at specific wavelengths using a thermopile or pyroelectric detector paired with a broadband source. German commercial real estate retrofitters specify these modules for permanent HVAC integration where calibration stability over 10-15 years outweighs upfront cost. REACH compliance concentrates on lead-free solder and halogen-free housing materials.
- Photoacoustic:These sensors detect pressure waves generated by pulsed light absorption in a resonant chamber, achieving sub-ppm resolution at milliwatt power draws. Nordic facility managers deploy them in battery-powered wireless networks across BREEAM-certified office stock, where the F-Gas Regulation's ventilation verification mandates demand dense spatial coverage without wiring infrastructure.
- Chemical Absorption:Electrochemical cells rely on acid-base reactions in liquid electrolytes, offering lower unit costs but requiring periodic replacement. French agricultural greenhouse operators favor them for process control in controlled-atmosphere storage where sensor density justifies disposable economics.
- Optical:Solid-state photonic designs using tunable laser diodes or LED photodetectors bypass chemical substance restrictions entirely. Dutch building automation integrators specify these for WELL certification projects demanding full material transparency documentation.
Non-Dispersive Infrared sits at the top of the volume ranking, with Photoacoustic climbing the fastest.
End User:
Procurement authority and technical specification capability vary dramatically across customer types, fragmenting pricing power and channel economics.
- Smart Buildings:Facility management departments in Western European metropolitan zones drive specifications for networked sensing systems. WELL and BREEAM certification mandates force continuous environmental logging investments, deepening margin pools for integrated hardware-software bundles.
- HVAC Systems:OEM contracts with German and French mechanical contractors dominate volume, though unbundling trends accelerate direct procurement through specialized distributors. EU Green Deal renovation targets compress installation timelines, favoring plug-and-play sensor modules over custom-engineered solutions.
- Industrial Facilities:Process control applications in chemical and food manufacturing demand explosion-proof housings and SIL-rated safety integrity. EMA frameworks for pharmaceutical cleanrooms impose validation protocols that extend qualification timelines.
- Agriculture Sector:Controlled-atmosphere storage and vertical farming operations in Poland and Romania represent expansion frontiers as EU cohesion funds flow toward agricultural modernization. Price sensitivity here favors Chemical Absorption and lower-specification NDIR variants.
Smart Buildings command the dominant revenue share, with Agriculture Sector expanding most quickly.
Technology:
Power architecture and connectivity protocols determine deployment feasibility across building vintages and application mobility requirements.
- Wireless:Battery-powered Zigbee and LoRaWAN modules enable retrofit installation without structural disruption. Nordic commercial buildings specify these for dense spatial coverage where BACnet wiring would prove cost-prohibitive.
- Wired:Power-over-Ethernet and dedicated 24V DC supplies deliver calibration stability and cybersecurity assurance. German industrial facilities mandate these for process control loops where signal integrity is safety-critical.
- Portable:Handheld and wearable instruments serve commissioning technicians and indoor air quality auditors. Photoacoustic miniaturization from Sensirion and competitors enables pocket-sized designs previously inaccessible to conventional architectures.
- Integrated:Sensor modules embedded directly into HVAC controllers and building automation gateways. Siemens and Honeywell dominate this tier through captive demand from their installed base of climate control systems.
Wired technology retains the largest installed base, with Wireless gaining share fastest.
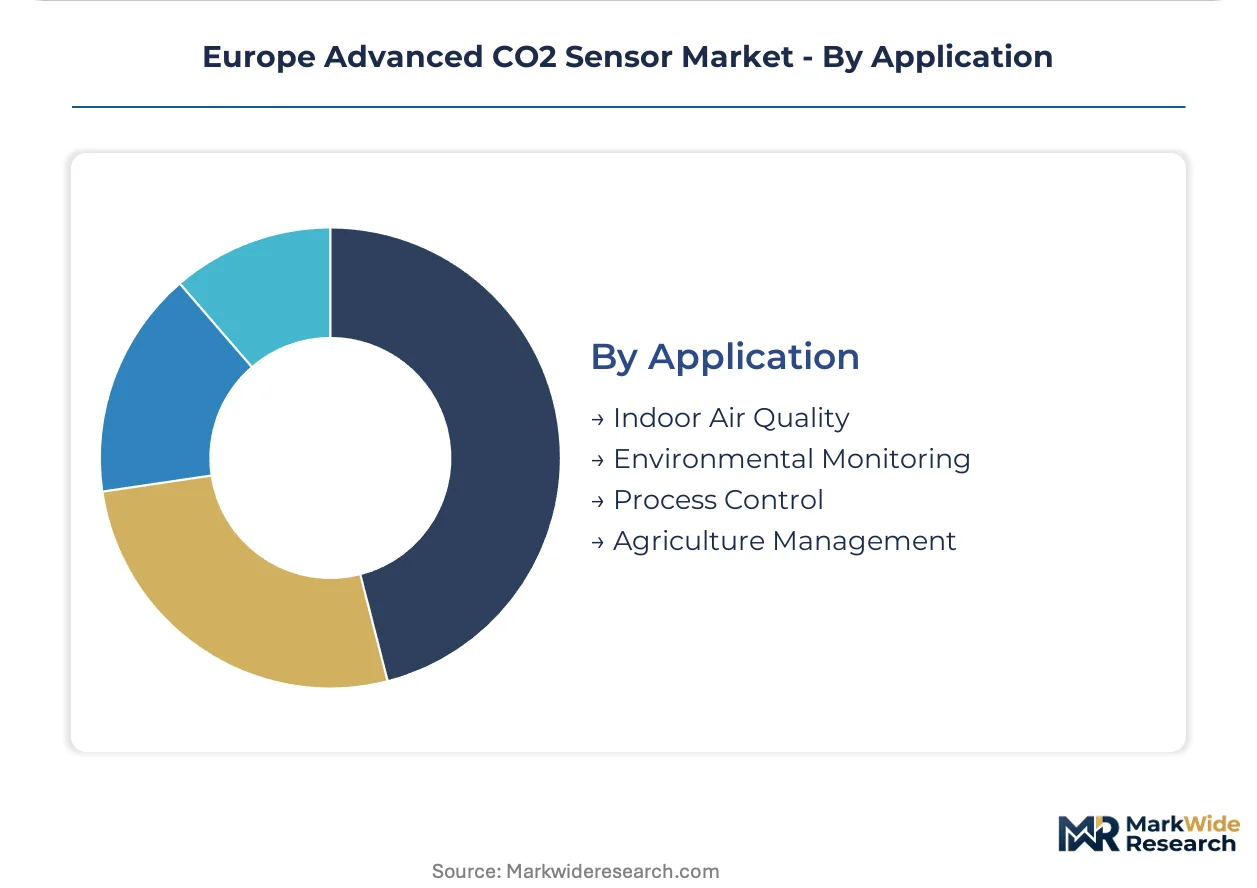
Application:
Data granularity requirements and regulatory enforcement intensity create steep margin gradients across use cases.
- Indoor Air Quality:Continuous CO2 monitoring for occupant health and cognitive performance optimization. WELL certification schemes mandate 1,000 ppm thresholds with 15-minute logging intervals, driving specification of high-accuracy NDIR and Photoacoustic platforms in premium commercial stock.
- Environmental Monitoring:Ambient air quality networks and climate research installations. EEA reporting obligations and urban heat island studies in French and Dutch cities sustain demand for research-grade instrumentation.
- Process Control:Manufacturing atmosphere regulation in food packaging, electronics assembly, and pharmaceutical production. CSRD scope-three disclosure rules expand corporate demand for granular emissions data from facility management departments.
- Agriculture Management:Greenhouse enrichment and controlled-atmosphere storage optimization. Polish horticultural cooperatives represent emerging demand as CAP subsidies modernize post-harvest infrastructure.
Indoor Air Quality generates the deepest margin pools, with Agriculture Management showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced CO2 sensing technology first achieved commercial scale in Germany's industrial automation corridor during the 1990s, when NDIR architectures matured for HVAC integration. German engineering standards subsequently diffused across Western Europe, establishing the technical foundation for today's EU Green Deal monitoring mandates.
Germany
Commercial real estate retrofitters in Frankfurt and Munich drive demand for wired NDIR modules with 15-year calibration stability. The F-Gas Regulation accelerates refrigerant transition projects requiring ventilation verification sensors. Bavarian HVAC contractors dominate integration work for smart building automation systems.
France
Parisian facility managers specify photoacoustic sensors for dense wireless coverage in BREEAM-certified office stock. ECHA substance documentation requirements push integrators toward optical-only architectures. The Île-de-France region concentrates unbundled procurement through specialized distributors serving mid-size buildings.
Netherlands
Amsterdam and Rotterdam building operators prioritize WELL certification projects demanding full material transparency. RoHS exemption navigation favors solid-state photonic designs over electrochemical alternatives. Dutch greenhouse automation clusters in Westland export controlled-atmosphere sensing expertise.
Poland
Warsaw and Krakow commercial stock remains underpenetrated relative to Western benchmarks. EU cohesion funds channel toward energy efficiency upgrades, expanding addressable base for networked sensing systems. Polish horticultural cooperatives represent emerging demand for lower-specification NDIR variants in post-harvest infrastructure.
Sweden
Nordic facility managers deploy battery-powered wireless networks across Stockholm and Gothenburg commercial buildings. Photoacoustic miniaturization enables dense spatial coverage without structural wiring disruption. Swedish building codes mandate continuous environmental logging that deepens specification requirements.
Europe Advanced CO2 Sensor Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification-grade and standard-grade sensing modules, with tiered pricing separating WELL-compliant optical platforms from basic electrochemical units. The vendor base clusters around three strategic archetypes: diversified automation conglomerates with captive HVAC demand, specialized photonics firms competing on miniaturization, and regional electrochemical suppliers serving price-sensitive agricultural segments. Dominant competitive moves include backward integration into optical component sourcing and technology licensing partnerships for MEMS-photonics convergence.
Among diversified automation conglomerates, Honeywell and Siemens occupy positions anchoring retrofit contracts through integrated building control portfolios. Sensirion exemplifies the miniaturization-focused specialist tier, competing in battery-constrained instrument segments where power draw determines deployment economics. These three represent distinct competitive vectors: scale-driven system integration, technology-led component specialization, and application-specific form factor innovation.
| Leading Market Players |
|---|
| Honeywell |
| Siemens |
| Vaisala |
| Emerson |
| Sensirion |
| Ametek |
| Gas Sensing Solutions |
| E + E ELEKTRONIK |
| Figaro Engineering |
| Others |
Supply Flow & Price Mechanics
Photoacoustic miniaturization in Nordic wireless deployments compresses unit economics while concentrating optical component sourcing in East Asian foundries. This dual shift simultaneously lowers deployment costs for battery-constrained instruments and amplifies input price volatility for European integrators facing REACH compliance burdens on alternative electrochemical architectures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates WELL-certified optical platforms from basic HVAC-integrated modules and disposable agricultural units. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the standard tier intensifies because unbundled procurement through specialized distributors displaces turnkey OEM contracts. Agricultural greenhouse operators in Poland exhibit the highest price sensitivity, while Dutch WELL certification projects show the least.
Supply Chain Analysis
Calibration technician scarcity in German and French field service networks constrains deployment velocity for retrofit contracts. Manufacturing concentrates in China for NDIR source and detector components, Germany for precision optical assembly, and Switzerland for MEMS-photonics integration. Raw material dependencies include lead-free solder alloys, halogen-free housing polymers, and tunable laser diodes. Single-source vulnerability in East Asian foundry capacity creates supply chain risk. Distribution runs through specialized HVAC distributors in Western Europe and agricultural equipment channels in Eastern member states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland and Romania offer geographic-arbitrage upside as EU cohesion fund flows meet underpenetrated commercial stock and lower labor costs for installation networks relative to Western European benchmarks.
For Market Incumbents: Lock in retrofit contracts in German metropolitan zones by anchoring building automation portfolios to F-Gas Regulation compliance timelines. Backward integration into optical component sourcing mitigates East Asian foundry concentration risk. Invest in CE marking pre-certification for integrated HVAC control systems to compress product launch delays.
For New Entrants and Emerging Players: Enter via Polish horticultural cooperatives and Romanian commercial retrofits where price sensitivity favors lower-specification NDIR variants over premium optical platforms. Target agriculture management applications where EU CAP subsidies modernize post-harvest infrastructure. Pursue direct distributor relationships to bypass incumbent OEM channel control.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional electrochemical suppliers serving price-sensitive agricultural segments. Long-term viability centers on MEMS-photonics convergence capabilities enabling battery-powered instrument expansion. Watch photoacoustic adoption rates in Nordic wireless deployments as inflection indicator for technology substitution trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Components | Captive sourcing of NDIR sources and detectors reduces East Asian foundry dependency and REACH compliance exposure. |
| CE Marking Pre-Certification Investment | Accelerated product launches for integrated HVAC systems serving EU Green Deal renovation timelines. |
| MEMS-Photonics Convergence R&D | Miniaturized platforms unlock battery-powered and wearable instrument segments previously inaccessible to conventional architectures. |
| Direct Distributor Channel Development | Unbundled procurement patterns in French and Dutch commercial retrofits favor specialized distribution over OEM bundling. |
| Eastern European Geographic Expansion | EU cohesion fund flows into Polish and Romanian energy efficiency upgrades expand addressable base for networked sensing systems. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with HVAC integration engineers, facility management directors, agricultural cooperative procurement leads, and building automation distributors combined with secondary validation from ECHA substance restriction databases, F-Gas Regulation implementation reports, EU Green Deal building renovation tracking, and SEC filings from listed automation conglomerates. Triangulation across these sources ensures coverage of both demand-side specification patterns and supply-side manufacturing constraints.
Input-output matrices map technology adoption rates, regulatory compliance costs, and channel economics across the projection horizon. Segmentation dimensions include sensing architecture, end-user vertical, connectivity protocol, and application granularity. CAGRs derive from fitted growth curves calibrated to historical diffusion patterns in building automation and agricultural modernization. Industry-specific forecast inputs incorporate EU cohesion fund disbursement schedules and CSRD scope-three disclosure implementation timelines.
The model holds under stable regulatory enforcement intensity and continued EU Green Deal funding continuity; deviation in F-Gas Regulation amendment timing or REACH substance restriction expansion would shift deployment trajectories. Forecasts reflect assumptions about technician training pipeline expansion and optical component supply normalization. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Hydrogen Monitor Market
Sensors and Controls
Digital Pump Controller Market
Sensors and Controls
Two Wheeler Sensors Market
Sensors and Controls
US Digital Thermometer Market
Sensors and Controls
Fiber Optic Pressure Sensors Market
Sensors and Controls
North America Temperature Sensor Market
Sensors and Controls
Germany Non-Contact Infrared Thermometer Market
Sensors and Controls
Insulation Monitoring Devices (IMD) Market
Sensors and Controls
Laser Scanner Market
Sensors and Controls
Air Particle Monitor System Market
Sensors and Controls
LAMEA Active Sensor Market
Sensors and Controls
Solid Flow Rate Valve Control Market
Sensors and Controls
Asia-Pacific Sensors Market
Sensors and Controls
Inertial Measurement Unit (IMU) Market
Sensors and Controls
Piezoelectric Polymers Market
Sensors and Controls
Global Space Sensors and Actuators Market