
 Optical Chemical Sensor Market | 2026-2036
Optical Chemical Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Chemical Sensor Market Outlook
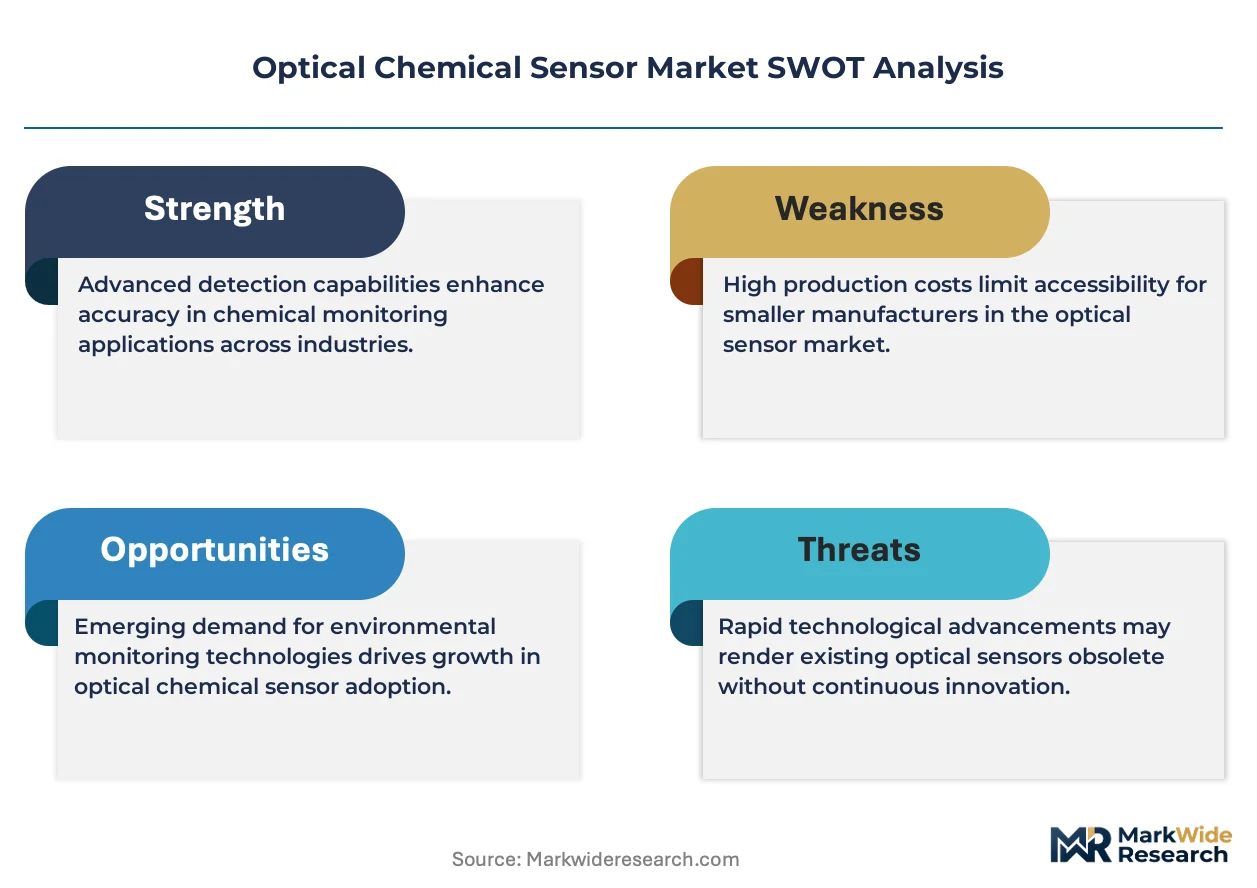
Silicon photonics is repositioning traditional fiber optic sensor economics by enabling smaller form factors and lower power consumption at comparable sensitivity thresholds. Honeywell International leverages its aerospace heritage to dominate high-reliability environmental monitoring deployments. Siemens anchors its position through deep integration with industrial automation architectures. Teledyne Technologies specializes in subsea and harsh-environment variants where optical stability under pressure differentiates performance.
Optical chemical sensors detect and quantify analytes through measurable changes in light properties—absorption, fluorescence, reflectance, or scattering—typically employing fiber optic waveguides, luminescent indicator dyes, or plasmonic metal films functionalized with receptor molecules. These devices serve critical roles in continuous process monitoring, where electrochemical methods fail due to electromagnetic interference or reagent depletion constraints. Fiber optic sensors occupy the largest installed base across oil and gas pipeline networks, though luminescent sensors represent the fastest-expanding category in biopharmaceutical manufacturing where dissolved oxygen and pH monitoring demand non-invasive measurement. Colorimetric sensors retain strong positions in point-of-use food safety testing, where low cost and visual readout simplicity offset lower precision.
The US FDA enforces stringent biocompatibility and sterility validations for sensors deployed in healthcare diagnostics, while the EPA mandates detection thresholds for hazardous substance monitoring in groundwater and ambient air matrices. REACH and RoHS frameworks in Europe restrict heavy metal content in optical coatings and indicator chemistries, forcing reformulation of legacy sensor compositions. Stakeholders must monitor evolving material compliance catalogs and anticipate convergence between medical device and environmental regulatory schemas.
Market Dynamics
Silicon photonics integration is compressing sensor form factors while tightening substrate material compliance under REACH and RoHS reformulations. German pharmaceutical clusters around Munich are accelerating bioprocess sensor deployments, forcing substrate suppliers to requalify indicator chemistries.
Growth Catalysts
- EU MDR substrate mandates:Medical device manufacturers must recertify optical coatings under tightened biocompatibility frameworks, generating replacement demand for compliant sensor platforms.
- Luminescent dissolved oxygen monitoring:Biopharmaceutical fermentation processes require continuous non-invasive measurement, displacing electrochemical probes in sterile environments.
- Bavaria medical technology corridor:Concentrated R&D spending around Munich creates localized demand pull for miniaturized fiber optic sensors in diagnostic instrumentation.
Market Restraints
- Heavy metal coating volatility:ECHA restrictions on cadmium and lead in indicator chemistries force reformulation of legacy plasmonic films, raising unit production costs.
- Specialized photonics foundry concentration:Silicon photonics fabrication capacity clusters in Taiwan and the Netherlands, creating single-source vulnerability for advanced waveguide substrates.
- Electrochemical probe substitution:Low-cost pH and oxygen electrodes retain installed base in non-sterile industrial settings, capping optical sensor penetration in price-sensitive segments.
Strategic Opportunities
- Subsea oil and gas expansion:Norwegian and Brazilian offshore fields require pressure-stable optical sensors for reservoir monitoring, opening harsh-environment specialization niches.
- Point-of-use food safety testing:Colorimetric sensors with smartphone-readable outputs address decentralized supply chain verification needs in retail and logistics.
- Silicon photonics-luminescent dye convergence:Hybrid platforms combining CMOS-compatible waveguides with ratiometric indicator systems enable single-chip multiparameter sensing.
Industry Challenges
- Photonics-electronics integration expertise:Packaging optical waveguides with CMOS readout circuits requires rare cross-functional engineering talent concentrated in German and Dutch research institutes.
- Dual REACH-RoHS certification timelines:Reformulated coating submissions face eighteen-month ECHA evaluation cycles, delaying product launches and freezing development roadmaps.
- Legacy fiber optic infrastructure retrofit:Oil and gas pipeline operators confront integration complexity when upgrading distributed sensing networks without operational shutdowns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Chemical Sensor Market |
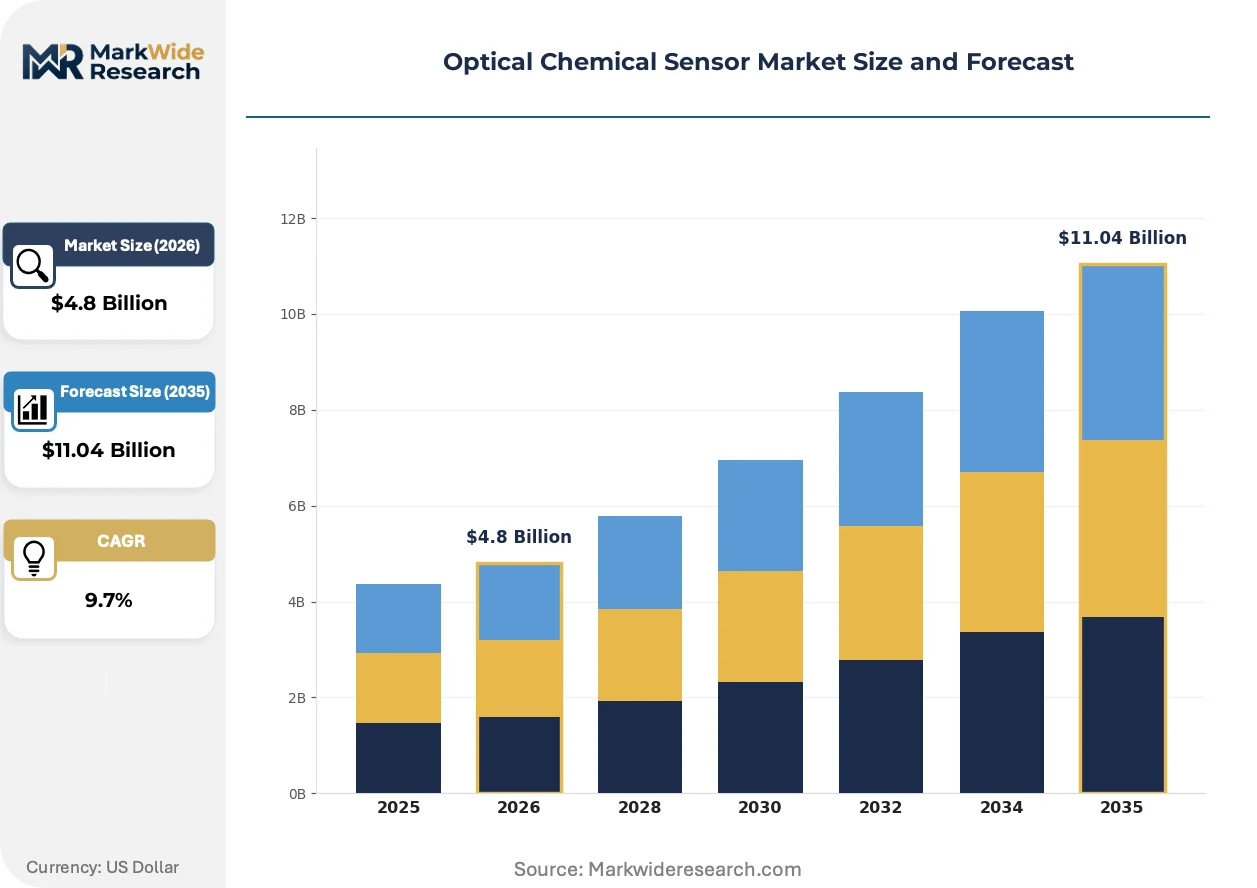
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Optic Sensors, Luminescent Sensors, Surface Plasmon Resonance Sensors, Colorimetric Sensors Application: Environmental Monitoring, Food Safety Testing, Industrial Process Control, Healthcare Diagnostics Technology: Optical Absorption, Fluorescence, Reflectance, Scattering End User: Research Laboratories, Manufacturing Units, Hospitals, Universities |
| Companies Covered | Honeywell International, Siemens, General Electric, Emerson Electric, ABB, Teledyne Technologies, Robert Bosch, Alpha MOS, Halma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Chemical Sensor Market Strategic Shifts
Waveguide miniaturization and indicator chemistry reformulation are converging to redefine performance benchmarks across pharmaceutical and environmental monitoring deployments. Regulatory material restrictions are accelerating substitution timelines for legacy coating compositions.
Silicon photonics is automating the fabrication of interferometric sensors through CMOS-compatible foundry processes. Pharmaceutical equipment OEMs in Germany and Switzerland are adopting these platforms at compressed development cycles. The technology is automating quality control steps previously requiring manual optical alignment, collapsing production lead times for custom sensor configurations.
REACH Annex XVII expansions are restricting chromium VI and cadmium compounds in optical indicator films. Coating suppliers must reformulate receptor chemistries using europium or ruthenium complexes, raising raw material costs. Biopharmaceutical sensor manufacturers in Ireland and Denmark are responding by qualifying alternative luminescent dyes ahead of enforcement deadlines.
Biopharmaceutical procurement teams are consolidating sensor suppliers around platforms offering integrated dissolved oxygen, pH, and carbon dioxide measurement. Single-use bioreactor OEMs are displacing standalone probe vendors through bundled sensor contracts. This concentration is most visible in German and Swiss contract manufacturing organizations standardizing on multi-analyte platforms to reduce validation overhead.
Optical Chemical Sensor Market Segmentation
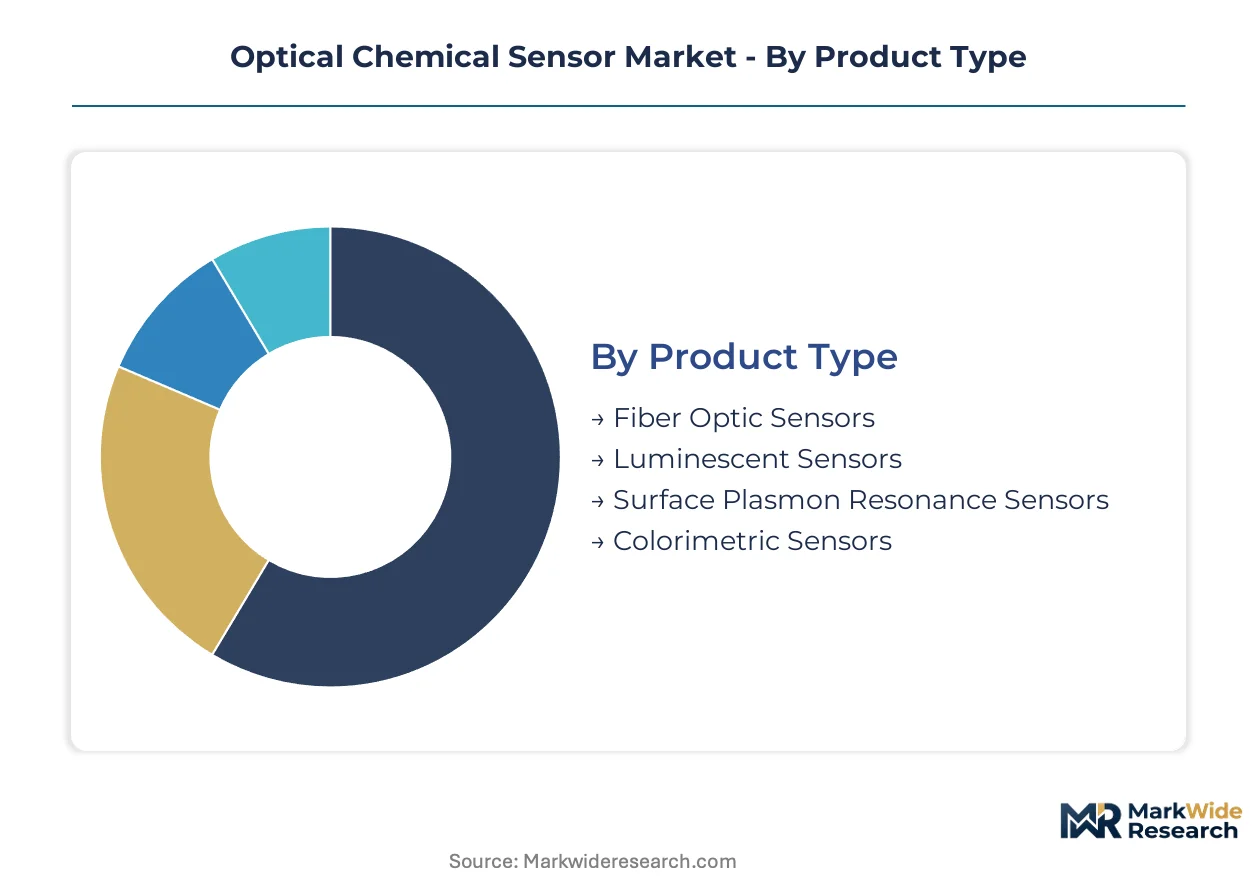
Optical chemical sensor segmentation reveals divergent capital requirements across fabrication methods, with silicon photonics integration demanding foundry investments that reshape competitive entry barriers. Product type distinctions drive the steepest variance in upfront tooling, while application and end-user categories fragment procurement authority across technical buyers with incompatible validation protocols.
Product Type:
Capital intensity peaks with surface plasmon resonance platforms requiring thin-film deposition chambers and cleanroom packaging, while colorimetric sensors demand minimal fixed asset commitment.
- Fiber Optic Sensors:These devices transmit modulated light through silica or polymer waveguides functionalized with analyte-specific coatings. Demand concentrates in Norwegian and Brazilian offshore oil networks where pressure-stable distributed sensing replaces electrochemical probes in subsea pipeline monitoring. The installed base here reflects decades of hydrocarbon infrastructure deployment.
- Luminescent Sensors:Employing ruthenium or europium complexes embedded in oxygen-permeable matrices, these sensors enable non-invasive dissolved gas measurement. Bavarian pharmaceutical clusters around Munich are accelerating single-use bioreactor integration, displacing electrochemical probes in sterile fermentation environments. REACH Annex XVII cadmium restrictions are forcing rapid reformulation of legacy indicator chemistries.
- Surface Plasmon Resonance Sensors:Require noble metal nanofilm deposition and precision refractometry for label-free biomolecular detection. Research laboratory procurement in Switzerland and Denmark dominates specialized deployments.
- Colorimetric Sensors:Leverage pH-sensitive or redox-active dyes on paper or polymer substrates for visual or smartphone-readable outputs. Food safety testing in decentralized retail supply chains drives volume demand with minimal capital barriers.
Most installed capacity flows through fiber optic sensors. Expansion is steepest in luminescent sensors.
Application:
Regulatory validation burden varies sharply across applications, with healthcare diagnostics imposing FDA and EU MDR biocompatibility timelines that extend procurement cycles versus environmental monitoring.
- Environmental Monitoring:Groundwater and ambient air matrices require EPA-mandated detection thresholds for hazardous substances. US municipal water authorities and European environmental agencies drive replacement demand as legacy electrochemical stations age out.
- Food Safety Testing:Point-of-use colorimetric platforms with smartphone integration address decentralized supply chain verification. Logistics operators and retail grocers in Germany and France are adopting portable mycotoxin and pathogen detection.
- Industrial Process Control:Continuous dissolved oxygen and pH monitoring in chemical manufacturing favors luminescent and fiber optic platforms immune to electromagnetic interference. German industrial automation OEMs bundle multi-parameter sensors into process skids.
- Healthcare Diagnostics:Blood gas and metabolite measurement demand sterility-validated, biocompatible coatings under FDA and EMA frameworks. Hospital procurement consolidates around integrated diagnostic platforms rather than standalone sensors.
Environmental monitoring carries the largest historical deployment base. Healthcare diagnostics commands the highest unit margins.
Technology:
Measurement modality determines foundry compatibility, with fluorescence and optical absorption offering clearest paths to silicon photonics integration versus scattering-based approaches.
- Fluorescence:Ratiometric indicator systems enable self-referenced measurements immune to source intensity drift. Biopharmaceutical fermentation monitoring in Ireland and Denmark favors these platforms for dissolved oxygen and pH tracking in single-use bags.
- Optical Absorption:Beer-Lambert law implementations using LED sources and photodiode arrays suit cost-sensitive environmental and food safety applications. CMOS-compatible integration is compressing form factors for portable deployments.
- Reflectance:Interrogates thin-film coatings or colloidal nanoparticles for surface-bound analyte detection. Surface plasmon resonance variants require precision angular or wavelength scanning.
- Scattering:Exploits Rayleigh or Mie scattering from particle-laden samples, common in turbidity and aerosol monitoring. Environmental compliance networks in the US and Germany deploy these for particulate matter quantification.
Fluorescence platforms are gaining share fastest in sterile process applications. Optical absorption retains dominance in price-sensitive segments.
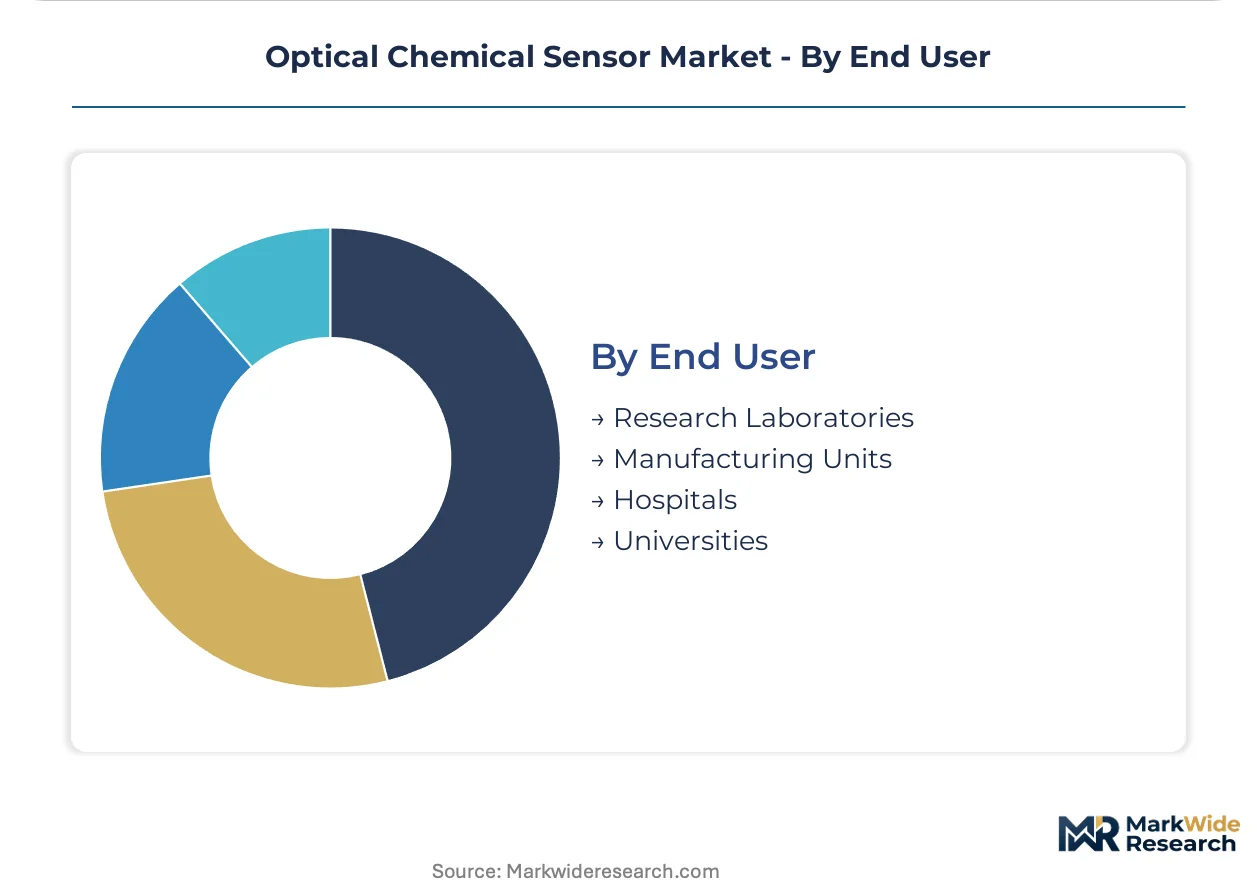
End User:
Procurement sophistication diverges across end users, with manufacturing units demanding integrated automation compatibility versus research laboratories prioritizing configurability over scale economics.
- Manufacturing Units:Pharmaceutical and chemical producers require continuous validation documentation and supplier audit trails. German and Swiss contract manufacturing organizations are consolidating sensor vendors to reduce qualification overhead.
- Research Laboratories:Academic and government labs prioritize multi-analyte flexibility and publication-grade precision. Funding cycles drive episodic procurement concentrated in Q1 and Q3.
- Hospitals:Clinical engineering departments integrate sensors into point-of-care analyzers and continuous patient monitors. EU MDR recertification deadlines are accelerating replacement of legacy coating formulations.
- Universities:Teaching and research programs favor modular platforms with open software interfaces. Budget constraints favor lower-cost colorimetric and absorption-based systems for undergraduate laboratories.
Manufacturing units generate the most concentrated revenue per account. Research laboratories provide the broadest technology testbed for platform validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's medical technology corridor anchors global demand concentration for optical chemical sensors, with Munich-area pharmaceutical equipment OEMs driving specifications for miniaturized fiber optic platforms. German industrial automation clusters and Swiss precision instrumentation hubs reinforce European dominance in bioprocess monitoring applications.
Germany
Pharmaceutical manufacturers in Bavaria and Baden-Württemberg are expanding luminescent sensor deployments for real-time dissolved oxygen monitoring in single-use bioreactors. EU MDR substrate mandates force recertification of optical coatings under tightened biocompatibility frameworks. The Munich-Stuttgart axis concentrates R&D spending for diagnostic instrumentation miniaturization.
United States
Environmental monitoring networks drive fiber optic sensor replacement demand as legacy electrochemical stations age out of compliance. EPA-mandated detection thresholds for hazardous substances in groundwater matrices accelerate platform upgrades. Houston's energy corridor and California's Central Valley water districts anchor subsea and agricultural deployment clusters respectively.
Switzerland
Precision instrumentation OEMs in Basel and Zurich adopt silicon photonics platforms for compressed pharmaceutical development cycles. Swissmedic enforces sterility validations that exceed baseline EU MDR requirements for healthcare diagnostic sensors. The Basel biotech cluster demands multi-analyte platforms integrating dissolved oxygen, pH, and carbon dioxide measurement.
China
Industrial process control applications favor cost-optimized absorption-based sensors for chemical manufacturing automation. NMPA biocompatibility frameworks for imported medical devices create qualification barriers for foreign sensor suppliers. The Yangtze River Delta pharmaceutical manufacturing belt concentrates domestic demand for sterile fermentation monitoring equipment.
Norway
Offshore oil and gas operators require pressure-stable optical sensors for subsea reservoir monitoring in North Sea fields. National regulators enforce environmental discharge limits that drive continuous pipeline leak detection deployments. Stavanger's energy technology cluster specializes in harsh-environment sensor packaging for deepwater applications.
Optical Chemical Sensor Market Competitive Environment
Strategic partnerships dominate the current landscape as sensor specialists align with pharmaceutical equipment OEMs and industrial automation platforms. The vendor base stratifies across three tiers: diversified conglomerates with aerospace or automation heritage, mid-cap photonics specialists with foundry partnerships, and regional component suppliers serving price-sensitive environmental applications. Two archetypes define competitive positioning: integrated platform providers bundling multi-analyte capabilities, and harsh-environment specialists capturing premium margins in subsea and high-pressure deployments. Technology licensing and capacity expansion at silicon photonics foundries represent the dominant competitive moves reshaping supply-side economics.
Among diversified industrial technology groups, Honeywell International, Siemens, and Teledyne Technologies occupy positions spanning environmental monitoring, industrial automation, and harsh-environment specializations respectively. These entities exemplify archetypes where aerospace heritage, automation integration depth, and subsea optical stability expertise create differentiated market positions. Honeywell represents the high-reliability environmental monitoring specialist, Siemens anchors industrial automation compatibility requirements, and Teledyne Technologies sits within the pressure-rated instrumentation tier where optical stability under differential loading commands technical specification authority.
| Leading Market Players |
|---|
| Honeywell International |
| Siemens |
| General Electric |
| Emerson Electric |
| ABB |
| Teledyne Technologies |
| Robert Bosch |
| Alpha MOS |
| Halma |
| Others |
Value Chain & Pricing Dynamics
Ruthenium complex spot prices cascade through luminescent sensor manufacturing, compressing margins at coating reformulation suppliers while amplifying pricing power for integrated platform vendors serving Bavarian pharmaceutical OEMs.
Pricing Analysis
Input-cost pass-through from noble metal indicator chemistries drives three-tier pricing structure across premium, standard, and economy levels. Certification grade under EU MDR and FDA biocompatibility frameworks creates the steepest price differentiation, with sterile-validated coatings commanding substantial premiums over industrial-grade alternatives. Pricing pressure stems from REACH Annex XVII reformulation mandates extending ECHA evaluation timelines. Contract manufacturing organizations in Germany exhibit lowest price sensitivity due to bundled multi-analyte procurement, while municipal water authorities in price-constrained markets resist upgrade cycles.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from German pharmaceutical equipment manufacturers, while distributor networks serve fragmented environmental monitoring installations. Silicon photonics fabrication concentrates in Taiwan and the Netherlands, with specialty coating production anchored in Germany and Switzerland. Raw material dependencies include ruthenium complexes, europium salts, and precision silica waveguides. Single-source vulnerability at advanced foundries creates structural risk for CMOS-compatible substrate supply. Distribution runs through technical specialists for healthcare diagnostics and industrial automation integrators for process control applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory complexity into durable demand, with EU MDR substrate recertification deadlines forcing systematic replacement of legacy optical coatings across European medical device installations.
For Market Incumbents: Anchor market position through backward integration into indicator chemistry production, securing supply continuity as ECHA restrictions tighten. Siemens and Honeywell should expand foundry partnerships in the Netherlands to reduce Taiwan concentration risk. Certification investment in dual REACH-RoHS compliant coating platforms defends against emerging photonics specialists. For New Entrants and Emerging Players: Capture white-space opportunity in point-of-use food safety testing, where colorimetric smartphone-readable platforms face minimal incumbent saturation. Norwegian subsea oil and gas sensor maintenance contracts represent the most penetrable premium segment for harsh-environment specialization. Partner with single-use bioreactor OEMs for bundled sensor integration rather than standalone probe competition. For Investors and Strategic Acquirers: Asymmetric upside sits with silicon photonics-luminescent dye convergence specialists holding CMOS-compatible IP and pharmaceutical validation credentials. Long-term viability favors platform vendors over component suppliers as procurement consolidation accelerates. Watch ECHA enforcement timelines for cadmium and chromium VI restrictions as inflection signals for coating reformulation demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Foundry Partnership | Secures CMOS-compatible substrate supply for German pharmaceutical OEM integration programs. |
| REACH-Compliant Coating Reformulation | Accelerates ECHA approval timelines ahead of Annex XVII enforcement deadlines. |
| Multi-Analyte Platform Bundling | Reduces validation overhead for Swiss and German contract manufacturing organizations. |
| Subsea Harsh-Environment Certification | Opens Norwegian offshore oil and gas reservoir monitoring replacement cycles. |
| Smartphone-Readable Colorimetric Launch | Addresses decentralized food safety verification in German and French retail supply chains. |
Study Parameters
Direct dialogue with biomedical engineers, pharmaceutical procurement directors, coating chemistry R&D leads, and environmental compliance officers grounded qualitative findings in operational reality. Secondary validation drew from FDA 510(k) filings, ECHA restriction proposal databases, SEC 10-K disclosures from diversified industrial technology groups, and German medical device registration records. Bottom-up and top-down triangulation cross-checked sensor unit demand against pharmaceutical capital expenditure cycles and oil and gas infrastructure maintenance schedules.
Bottom-up modeling segmented volume and value across product type, application, technology, and end-user categories, with additional granularity for regulatory compliance tier and geographic production cluster. CAGRs were derived from fitted growth curves calibrated to historical replacement rates and announced capacity expansions. Forecast inputs incorporated REACH enforcement timelines, single-use bioreactor adoption curves in Bavaria, and subsea oil field development pipelines in Norway and Brazil.
Regulatory enforcement delays, foundry capacity constraints, and electrochemical probe price competition are the dominant revision risks across the projection horizon. Forecasts reflect assumptions about ECHA evaluation cycle durations and pharmaceutical OEM consolidation trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Turbomachinery Control Systems Market
Sensors and Controls
Global Pyrometer Market
Sensors and Controls
Volatile Organic Compound Gas Sensor Market
Sensors and Controls
Global Printed Sensor Market
Sensors and Controls
MEMS Accelerometer and Gyroscope Market
Sensors and Controls
Capacitive Tactile Sensor Market
Sensors and Controls
Piezoelectric MEMS Resonators Market
Sensors and Controls
High Purity Flow Meter Market
Sensors and Controls
France Digital Thermometer Market
Sensors and Controls
Latin America Occupancy Sensors Market
Sensors and Controls
Global Wireless Brain Sensors Market
Sensors and Controls
Electronics Control Management Market
Sensors and Controls
MEMS Microphones Market
Sensors and Controls
Sensor Fusion Market
Sensors and Controls
Position Sensor Market
Sensors and Controls
Hall-Effect Sensors Market