
 Europe MEMS and Sensors Market | 2026-2036
Europe MEMS and Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe MEMS and Sensors Market Foresight
REACH is realigning the cost-of-entry calculus for European MEMS suppliers by mandating full material traceability and restricting certain substrate chemistries. Robert Bosch GmbH leverages its captive foundry network to absorb compliance costs internally. STMicroelectronics anchors its competitive position through deep R&D intensity across silicon microfabrication platforms. Infineon Technologies AG specializes in automotive-grade pressure sensors, navigating certification thresholds that smaller rivals struggle to meet.
Micro-electromechanical systems and sensors integrate mechanical elements, sensors, actuators, and electronics on a common silicon substrate through photolithography and etching processes, typically operating at micron-scale dimensions with milliwatt power budgets to enable motion detection, environmental monitoring, and acoustic capture. Their primary commercial purpose spans autonomous vehicle perception, smartphone orientation tracking, and industrial predictive maintenance systems. Silicon microfabrication dominates European output due to established semiconductor infrastructure, while pressure sensors command premium positioning in automotive safety applications where ASIL-rated reliability is non-negotiable. Bulk acoustic wave technology is displacing legacy approaches in telecommunications filtering, though surface acoustic wave retains cost advantages in select industrial automation deployments.
EMA medical device regulations and the EU AI Act are reshaping validation protocols for sensors deployed in wearable health monitors and diagnostic equipment. CE marking requirements under the MDR extend certification burdens to software-integrated sensor modules, compressing margins for non-specialist vendors. The F-Gas Regulation constrains certain etching chemistries used in MEMS manufacturing, pushing foundries toward alternative process chemistries. Stakeholders must monitor how CSRD disclosure mandates will force tier-one suppliers to document sensor lifecycle emissions across extended value chains.
Market Dynamics
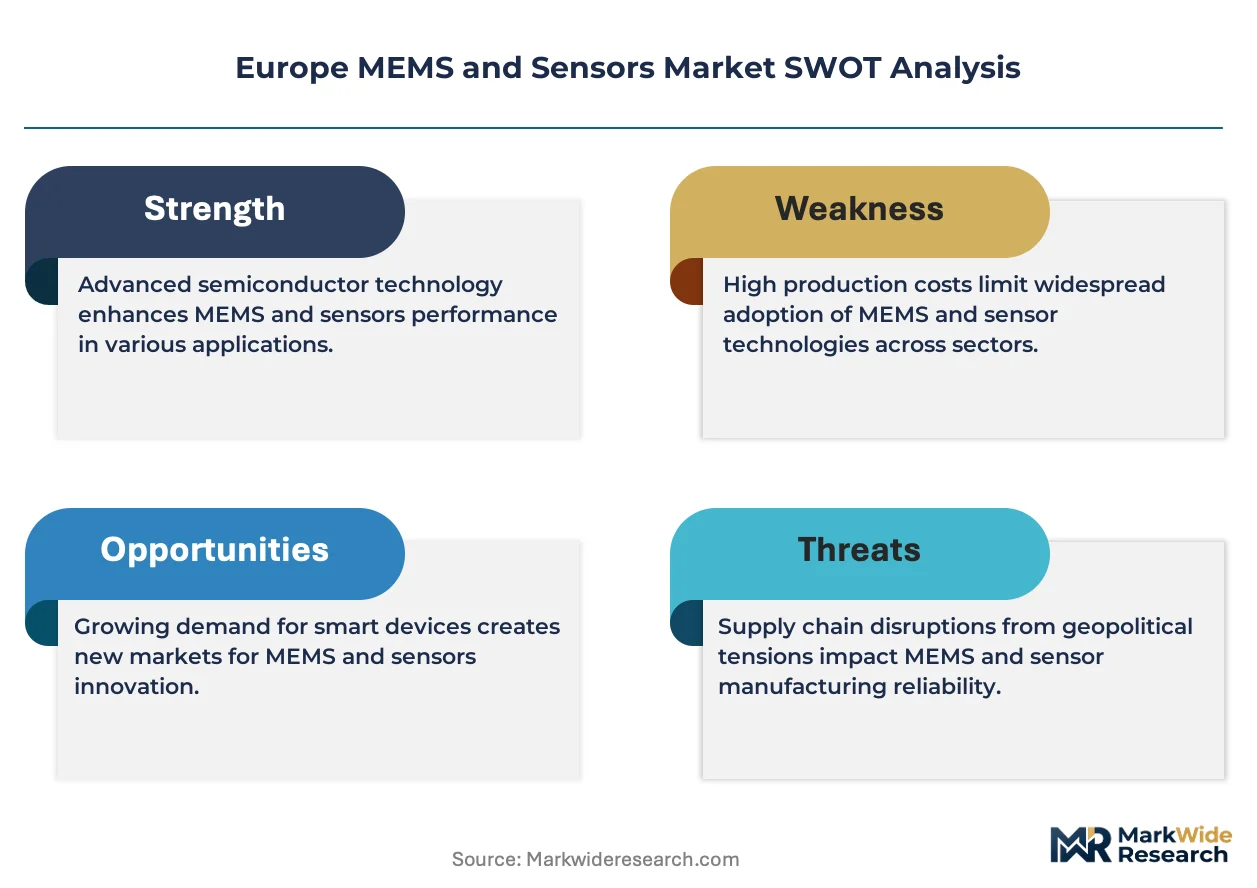
REACH compliance mandates are forcing European MEMS suppliers to reengineer material sourcing and substrate chemistries, compressing margins for non-integrated foundries while advantaging captive manufacturing networks.
Growth Catalysts
- EU Green Deal decarbonization targets:Automotive OEMs in Germany and France are procuring pressure sensors and inertial measurement units for electric powertrain monitoring and battery thermal management systems.
- MDR certification requirements:Wearable health monitor manufacturers must source CE-marked sensor modules, expanding addressable demand for biocompatible MEMS foundries in the Netherlands and Switzerland.
- Bulk acoustic wave technology:Telecommunications infrastructure deployments across Nordic markets are displacing surface acoustic wave filters in 5G base stations and smartphone RF front ends.
Market Restraints
- Silicon wafer supply concentration:Foundry capacity bottlenecks in Germany and the Netherlands limit substrate availability for fabless European MEMS designers.
- F-Gas Regulation constraints:Alternative etching chemistries for MEMS microfabrication carry yield penalties and equipment retooling costs that compress foundry operating margins.
- ASIL-D certification thresholds:Automotive safety system suppliers face 18-24 month validation timelines that lock out smaller sensor vendors from German OEM supply chains.
Strategic Opportunities
- Eastern European manufacturing expansion:Czech Republic and Poland are attracting sensor packaging and test facilities to serve German automotive corridors with lower labor costs.
- CSRD disclosure mandates:Tier-one suppliers must document sensor lifecycle emissions, creating service revenue streams for European foundries offering carbon-accounted manufacturing.
- AI Act compliance services:Sensor-software integration for diagnostic equipment requires validated data pipelines, opening consulting and certification revenue for specialized European engineering firms.
Industry Challenges
- Photolithography process engineering talent:European universities produce insufficient MEMS-specific fabrication specialists to staff expanding foundry operations in France and Germany.
- Legacy automotive platform integration:Sensor suppliers must maintain parallel production lines for CAN bus and Ethernet-based vehicle architectures during extended transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe MEMS and Sensors Market |
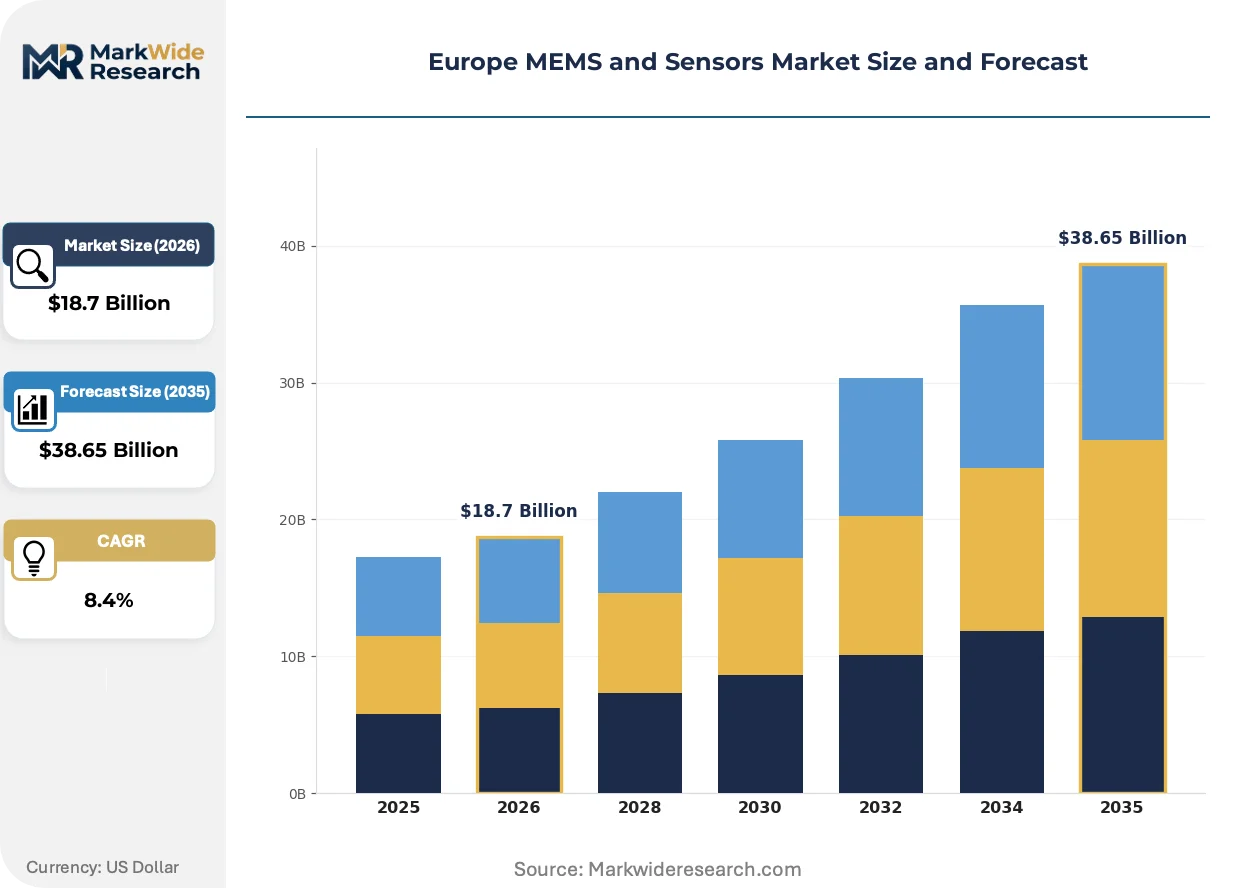
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Accelerometers, Gyroscopes, Pressure Sensors, Microphones End User: Consumer Electronics, Automotive, Industrial Automation, Healthcare Technology: Silicon Microfabrication, Bulk Acoustic Wave, Surface Acoustic Wave, Optical Application: Smartphones, Wearable Devices, Automotive Safety, Home Automation |
| Companies Covered | Robert Bosch GmbH, STMicroelectronics, Infineon Technologies AG, Murata Manufacturing Co., Ltd, Analog Devices Inc., Panasonic Corporation, NXP Semiconductors, Honeywell International Inc., Sensata Technologies Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe MEMS and Sensors Market Shifts & Advancements
Silicon microfabrication platforms are converging with advanced packaging techniques to enable heterogeneous integration of sensors, compute, and power management in single modules.
System-in-package architectures are integrating MEMS dies with CMOS readout circuits and AI accelerators into compact modules for edge inference applications. German automotive suppliers are adopting these configurations for cabin monitoring and predictive maintenance systems. The technology is integrating previously discrete functions, compressing bill-of-materials counts and shortening supply chains for safety-critical applications.
REACH substance restrictions are banning certain photoresist chemistries and substrate dopants used in legacy MEMS processes. ECHA enforcement is accelerating foundry migration to alternative material systems with documented toxicity profiles. French and Dutch manufacturing clusters are absorbing compliance costs through consolidated chemical management platforms.
Automotive OEM procurement teams are consolidating sensor supplier panels from fifteen-plus vendors to six or fewer qualified partners per category. Tier-one suppliers in Germany are responding with multi-year framework agreements that guarantee volume commitments in exchange for dedicated foundry capacity. This concentration is most visible in pressure sensor categories where ASIL-rated reliability requirements limit viable sourcing alternatives.
Europe MEMS and Sensors Market Segmentation
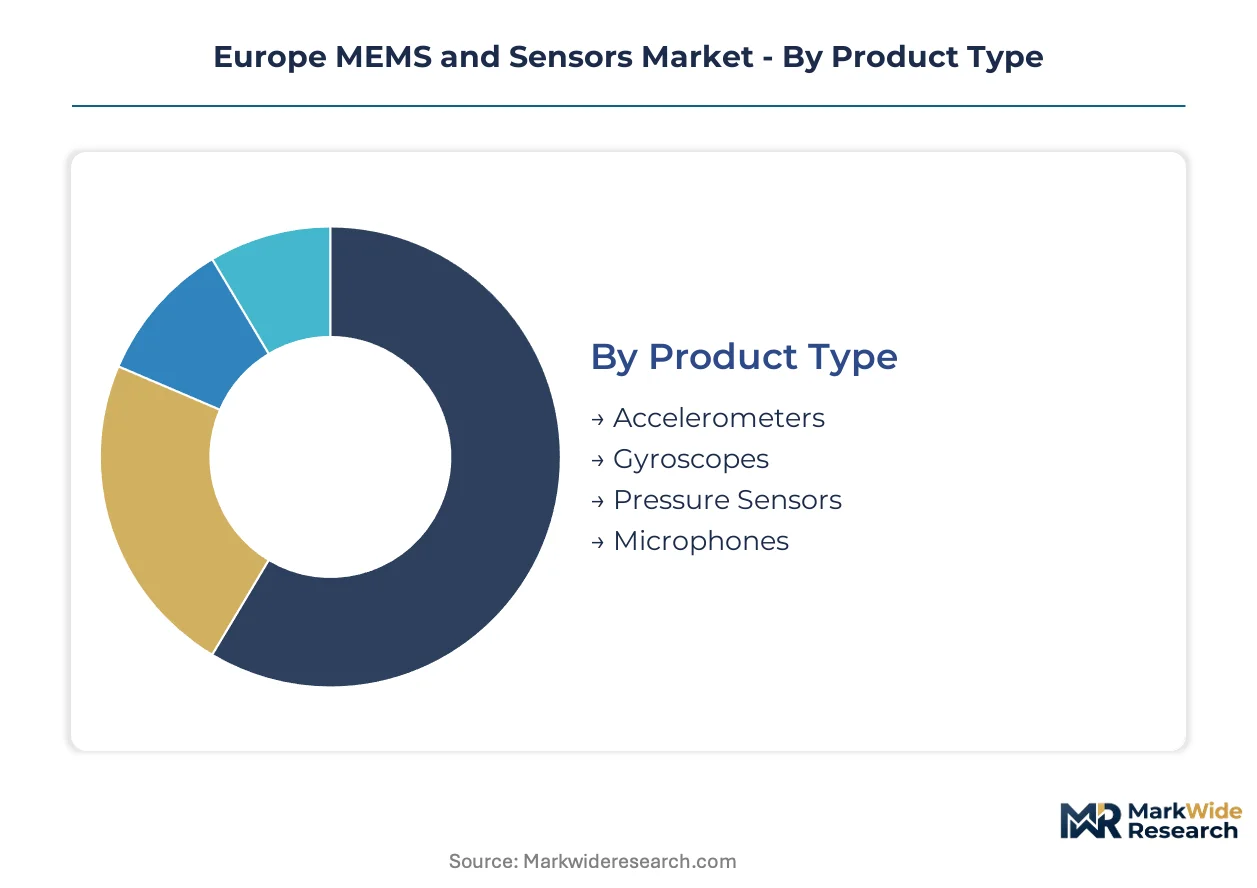
European MEMS and sensors suppliers configure product portfolios around certification tiers and integration complexity rather than pure performance metrics. Segmentation reveals where captive foundry investments concentrate versus fabless design opportunities.
Product Type:
Customization intensity spans from commodity motion sensors to automotive-grade pressure transducers requiring ASIL-rated validation protocols.
- Pressure Sensors:Piezoresistive or capacitive transducers measuring fluid and gas pressure differentials with millibar precision. German automotive OEMs embed these in electric powertrain thermal management and battery monitoring systems where ECE R100 compliance is mandatory.
- Accelerometers:Capacitive or piezoelectric devices detecting linear acceleration along one to three axes. Dutch and Swiss industrial automation vendors specify these for predictive maintenance on rotating machinery under Machinery Directive 2006/42/EC requirements.
- Gyroscopes:MEMS-based angular rate sensors using Coriolis force detection for orientation tracking.
- Microphones:Capacitive MEMS acoustic transducers with integrated preamplification for voice capture and environmental sensing.
Most installed capacity flows through Pressure Sensors. Expansion is steepest in Accelerometers.
End User:
Margin structures diverge sharply between consumer volume plays and automotive long-cycle qualification programs.
- Automotive:Safety-critical sensor modules requiring ISO 26262 functional safety certification and KBA type approval for German vehicle registration. French and Italian OEMs are consolidating supplier panels for electric powertrain sensors under EU Green Deal procurement mandates.
- Healthcare:Biocompatible MEMS for wearable monitors and implantable devices governed by EMA medical device regulations and MDR CE marking requirements. Swiss and Dutch foundries specialize in ISO 13485-certified cleanroom production for diagnostic equipment.
- Consumer Electronics:High-volume, cost-optimized sensors for smartphone and tablet integration.
- Industrial Automation:Ruggedized sensors for factory floor condition monitoring and process control.
Revenue concentration sits with Automotive. Healthcare is gaining share fastest.
Technology:
Process maturity determines which platforms absorb REACH compliance costs without yield degradation.
- Silicon Microfabrication:Photolithography-based etching and deposition processes on single-crystal silicon substrates. German and French manufacturing clusters dominate this platform due to legacy semiconductor infrastructure and consolidated chemical management for ECHA substance restrictions.
- Bulk Acoustic Wave:Piezoelectric resonators using thickness-mode vibrations for RF filtering in telecommunications infrastructure. Nordic 5G base station deployments are displacing legacy SAW filters in smartphone front ends.
- Surface Acoustic Wave:Interdigital transducer structures on piezoelectric substrates for lower-frequency filtering applications.
- Optical:MEMS micromirrors and interferometric structures for LiDAR and spectroscopic sensing.
Production gravity centers on Silicon Microfabrication. Bulk Acoustic Wave is climbing the fastest.
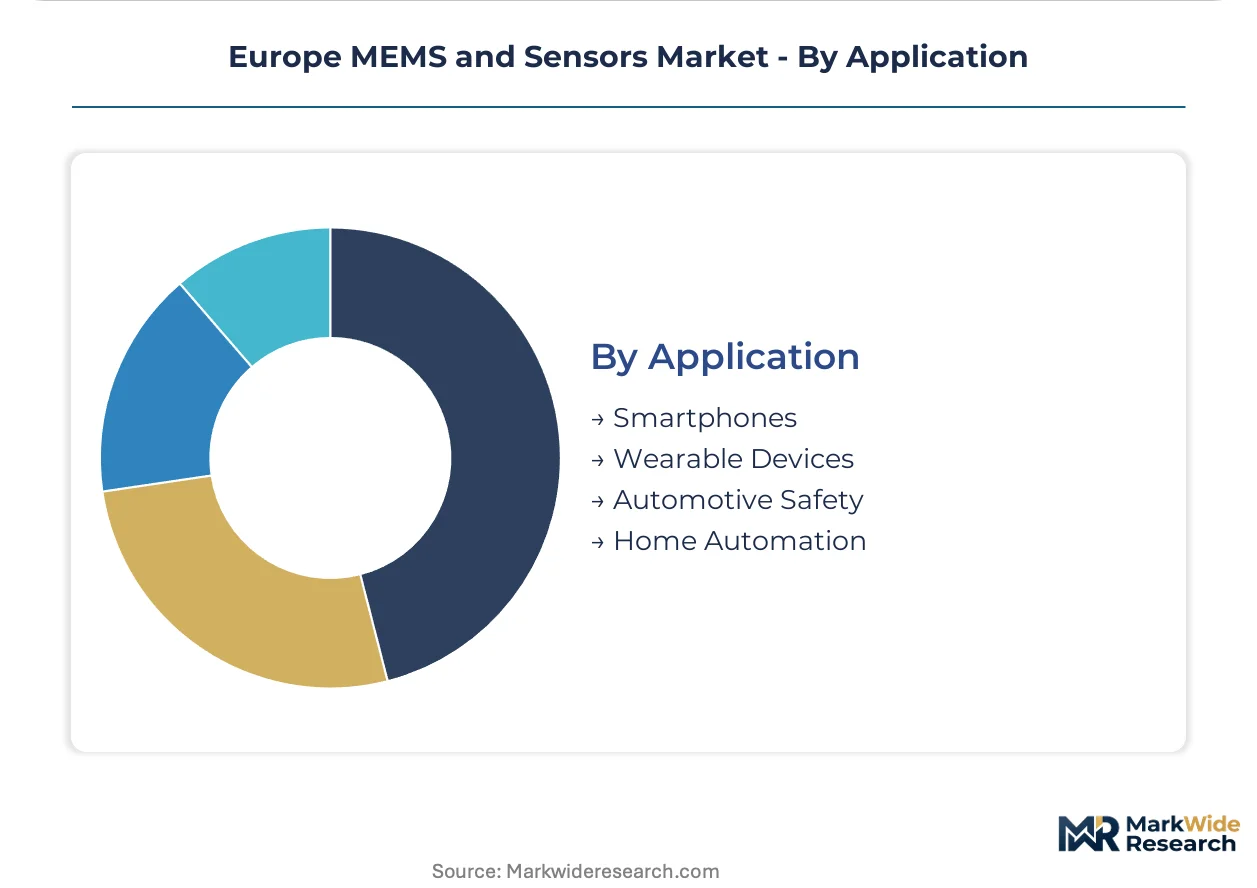
Application:
Integration complexity escalates from discrete component supply to system-in-package modules combining sensing, compute, and connectivity.
- Automotive Safety:Airbag deployment sensors, electronic stability control modules, and tire pressure monitoring systems. ASIL-D certification timelines of 18-24 months lock in German tier-one suppliers against smaller competitors.
- Wearable Devices:Health and fitness monitors requiring biocompatible encapsulation and ultra-low power operation. Netherlands-based design houses are specializing in CE-marked sensor-software integration for EMA regulatory compliance.
- Smartphones:Orientation, motion, and acoustic sensing for mobile device user interfaces.
- Home Automation:Environmental and occupancy sensors for smart building climate and security systems.
Supplier qualification investment peaks in Automotive Safety. Wearable Devices show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision fabrication specialists concentrate in German and Dutch university corridors, feeding foundry expansion across the Rhine-Ruhr and Eindhoven manufacturing belts. French cleanroom engineers and Swiss MEMS designers complete the regional talent matrix.
Germany
Automotive OEM procurement teams in Stuttgart and Munich are consolidating pressure sensor supplier panels for electric powertrain thermal management. KBA type approval requirements extend certification timelines to 18-24 months for ASIL-rated modules. The Baden-Württemberg manufacturing corridor anchors captive foundry investments serving tier-one safety system suppliers.
Netherlands
Biocompatible MEMS demand from wearable health monitor manufacturers is expanding cleanroom capacity near Eindhoven. MDR CE marking requirements under EMA regulations compress margins for non-specialist vendors. The Brainport Eindhoven cluster specializes in ISO 13485-certified production for diagnostic equipment integration.
France
Telecommunications infrastructure deployments are accelerating bulk acoustic wave filter adoption for 5G base stations. ANSM oversight of medical device sensor exports tightens validation protocols for wearable diagnostic modules. The Grenoble microelectronics cluster integrates photolithography expertise with CEA-backed research programs.
Switzerland
Swissmedic certification requirements for implantable sensor devices are extending qualification timelines for biocompatible foundries. Precision manufacturing traditions in the Jura Arc support MEMS packaging specialization for hearing aid and diagnostic applications. Zurich-based design houses are expanding CE-marked sensor-software integration services.
Poland
Lower labor costs are attracting sensor packaging and test facilities to serve German automotive corridors near Wrocław and Kraków. EU Green Deal procurement mandates from French and German OEMs are redirecting tier-two supplier investments eastward. The Silesian manufacturing zone is absorbing backend assembly migration from higher-cost western European sites.
Europe MEMS and Sensors Market Competitive Landscape
The competitive structure tilts toward vertically integrated conglomerates with captive foundry networks absorbing REACH compliance costs internally. Captive manufacturing advantages separate tier-one suppliers from fabless designers facing silicon wafer supply bottlenecks. Three archetypes dominate: integrated conglomerates with internal foundries, specialized automotive-grade suppliers, and fabless design houses dependent on external fabrication. Consolidation pressures and multi-year framework agreements are the dominant competitive moves, with OEM procurement teams reducing supplier panels from fifteen-plus vendors to six or fewer qualified partners.
Among German-based integrated suppliers, Robert Bosch GmbH and Infineon Technologies AG exemplify the captive foundry archetype, while STMicroelectronics represents Franco-Italian manufacturing consolidation with deep R&D intensity across silicon microfabrication platforms. These three entities occupy positions where internal process control and consolidated chemical management platforms absorb ECHA substance restriction costs that compress margins for non-integrated competitors.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| STMicroelectronics |
| Infineon Technologies AG |
| Murata Manufacturing Co., Ltd |
| Analog Devices Inc. |
| Panasonic Corporation |
| NXP Semiconductors |
| Honeywell International Inc. |
| Sensata Technologies Inc. |
| Others |
Supply & Pricing Matrix
Silicon wafer spot price indices cascade through European MEMS supply chains into three distinct pricing tiers that separate ASIL-certified automotive modules from industrial-grade components and consumer electronics commodities. REACH compliance costs absorb margin at foundries lacking captive chemical management, compressing mid-tier suppliers between premium captive producers and low-cost Asian packaging houses.
Pricing Analysis
Bundled foundry-plus-certification services command premium positioning against unbundled component supply where buyers source validation separately. Pricing stratifies across ASIL-D certified automotive modules, ISO 13485 medical-grade sensors, and standard industrial components, with differentiation driven by certification timeline risk and volume commitment scale. Cost compression in consumer-facing tiers intensifies as smartphone OEMs consolidate supplier panels. Automotive OEM procurement teams show lowest price sensitivity given 18-24 month qualification lock-in, while consumer electronics buyers drive aggressive annual cost-down targets.
Supply Chain Analysis
EU Green Deal domestic-content mandates for critical component sourcing are reshaping substrate procurement patterns across German and Dutch manufacturing corridors. Silicon feedstock draws from German polysilicon refiners and Norwegian metallurgical-grade suppliers, while photoresist chemistries hinge on consolidated ECHA-approved vendors in France and Belgium. Single-source vulnerability concentrates in 300mm silicon wafer supply from German and Dutch foundries. Distribution runs through tier-one automotive suppliers and specialized medical device distributors rather than open-market electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European MEMS markets offer margin expansion pathways through REACH compliance absorption at integrated foundries and premium-tier shift toward medical-grade biocompatible sensors. Captive chemical management and ASIL certification capabilities separate sustainable profit pools from commoditization zones.
For Market Incumbents: Deploy captive foundry network expansion to internalize REACH compliance costs that fabless rivals cannot absorb. Consolidate supplier panel positions through multi-year framework agreements with German automotive OEMs, locking out emerging competitors from ASIL-D qualification pipelines. Deepen R&D intensity in silicon microfabrication platforms to maintain process yield advantages as F-Gas Regulation constraints force alternative chemistry adoption. For New Entrants and Emerging Players: Enter via Eastern European packaging and test facility investments serving German automotive corridors with lower labor cost structures than western European sites. Target wearable health monitor sensor modules where MDR CE marking requirements create specialist demand that non-certified foundries cannot meet. Pursue foundry-less design house models partnering with ISO 13485-certified Dutch cleanroom operators to bypass capital-intensive fabrication barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale biocompatible MEMS specialists possessing ISO 13485 certification and established EMA regulatory pathways. Long-term viability favors targets with defensible positions in medical-grade sensor segments where MDR validation timelines protect incumbent returns. Watch Nordic 5G infrastructure deployment pace as inflection indicator for bulk acoustic wave filter demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Capacity Expansion | REACH compliance absorption protects margin structures against fabless competitors in German manufacturing corridors. |
| ASIL-D Certification Investment | 18-24 month validation timelines lock in automotive OEM supply relationships against emerging sensor vendors. |
| Eastern European Packaging Migration | Czech and Polish test facilities capture EU Green Deal procurement flows with lower labor cost structures. |
| Biocompatible MEMS Specialization | ISO 13485 certification opens EMA-regulated wearable diagnostic markets with premium pricing durability. |
| Bulk Acoustic Wave Technology Transition | Nordic 5G deployments displace legacy SAW filters in telecommunications infrastructure applications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both volume trajectories and regulatory implementation timelines. Primary discussions engaged MEMS foundry operations managers, automotive tier-one procurement directors, EMA regulatory affairs specialists, and biomedical engineering leads at Dutch health monitor manufacturers. Secondary validation drew from ECHA substance restriction databases, KBA type approval registries, SEC filings of listed semiconductor suppliers, and EU Green Deal procurement disclosure records. Bottom-up wafer shipment data and top-down OEM sensor content estimates were cross-referenced for triangulation.
Segment-weighting approaches distributed value across pressure sensors, accelerometers, gyroscopes, and microphones according to certification intensity and integration complexity. Technology dimensions modeled silicon microfabrication, bulk acoustic wave, surface acoustic wave, and optical platforms. End-use segmentation captured automotive safety systems, healthcare wearables, consumer electronics, and industrial automation with distinct margin and qualification profiles. CAGRs were derived from fitted growth curves applied to baseline capacity and demand elasticity estimates across the projection horizon. Forecast inputs incorporated REACH compliance cost absorption rates and F-Gas Regulation chemistry transition timelines.
Inputs from EMA regulatory filings and KBA approval databases were available through the study window; gaps in real-time foundry utilization data introduce uncertainty bands around near-term capacity expansion estimates. Forecasts reflect documented assumptions regarding EU Green Deal procurement enforcement and MDR CE marking adoption curves. Silicon wafer supply bottlenecks, ECHA substance restriction expansions, and Nordic 5G deployment acceleration constitute a small set of triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Mass Flow Controller Market
Sensors and Controls
Global Nanosensors Market
Sensors and Controls
North America Fingerprint Sensor Market
Sensors and Controls
Silicon Photomultiplier (Sipm) Market
Sensors and Controls
Europe Advanced CO2 Sensor Market
Sensors and Controls
Wireless Flow Sensors Market
Sensors and Controls
Battery Monitor Market
Sensors and Controls
Electric Pipette Controllers Market
Sensors and Controls
Capacitive Tactile Sensor Market
Sensors and Controls
High-End Accelerometer Market
Sensors and Controls
MEMS Pressure Sensors Market
Sensors and Controls
TMAH Concentration Monitor Market
Sensors and Controls
APAC Occupancy Sensors Market
Sensors and Controls
Global E-Compass Market
Sensors and Controls
PID Controller Market
Sensors and Controls
Photonic Sensors and Detectors Market