
 Distance Measurement Sensor Market | 2026-2036
Distance Measurement Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Distance Measurement Sensor Market Analysis
Distributor networks for industrial sensing components is reconfiguring as direct-to-OEM digital channels gain share. Sick AG leverages its factory-automation heritage to sustain channel control across European machine builders. Keyence Corporation anchors its position through high-touch direct sales teams that dominate precision manufacturing segments in Japan and North America. Pepperl+Fuchs GmbH competes on hazardous-area certifications, extending its reach into oil and gas applications where intrinsic safety standards apply.
Distance measurement sensors are electro-optical or electro-acoustic devices that emit energy pulses and calculate spatial separation by measuring return-signal time, phase shift, or triangulation angle, typically resolving targets from millimeters to hundreds of meters. These devices serve primarily to enable automated positioning, collision avoidance, and dimensional verification in machinery and vehicles. Laser sensors based on time-of-flight technology lead product-type revenue due to their balance of range, accuracy, and declining semiconductor costs. Ultrasonic sensors retain strongholds in level-measurement applications where transparent or irregular surfaces defeat optical methods. Phase-shift technology within the technology dimension captures margin pools in high-speed industrial automation where sub-millimeter repeatability commands premium pricing.
The EU Machinery Directive and ISO 13849 functional-safety standards compel sensor manufacturers to certify products for predictable failure modes, raising R&D barriers for market entry. FDA scrutiny of sensor-enabled medical robotics and NHTSA requirements for automotive advanced driver-assistance systems further segment compliance pathways by end-use jurisdiction. Stakeholders must monitor how IEC 62998 safety-of-machinery standards evolve to harmonize with emerging collaborative robotics deployments.
Market Dynamics
The Distance Measurement Sensor Market is compressing around functional-safety mandates that force sensor architectures toward redundant, certifiable designs. Automotive OEMs and collaborative robot manufacturers now specify ISO 13849-compliant components as baseline requirements, not premium options.
Growth Catalysts
- EU Machinery Directive enforcement:The directive's 2023 amendments require documented failure-mode analysis for sensor-integrated safety systems. Machine builders in Germany and Italy are retrofitting production lines with certified time-of-flight sensors to maintain CE marking.
- Automotive ADAS penetration:NHTSA's proposed automatic emergency braking mandate for light vehicles is accelerating procurement of long-range lidar and radar fusion sensors. Tier-1 suppliers are qualifying dual-redundant distance sensors for 2026 model-year platforms.
- Semiconductor cost curves:VCSEL array and SPAD photodetector prices have fallen below thresholds that enable sub-hundred-dollar automotive-grade time-of-flight modules. This cost structure is unlocking volume deployment in mid-range consumer vehicles.
Market Restraints
- Indium gallium arsenide supply concentration:High-performance lidar receivers depend on InGaAs photodetectors sourced primarily from Japanese and Chinese foundries. Geopolitical friction and export licensing delays are extending sensor lead times.
- Optical performance limits in adverse weather:Time-of-flight laser sensors experience range degradation and false returns in heavy precipitation, fog, and direct solar interference. This technical ceiling restricts deployment in outdoor mobile robotics and agricultural automation.
- FDA 510(k) pathway complexity:Sensor-enabled surgical robotics face multi-year approval timelines and substantial clinical data requirements. The regulatory friction slows market entry for medical-grade distance measurement systems.
Strategic Opportunities
- India manufacturing automation:The PLI scheme for electronics and automotive components is attracting sensor assembly investments. Domestic machine builders in Pune and Chennai represent underpenetrated demand for mid-range ultrasonic and laser sensors.
- Convergence of time-of-flight with event-based vision:Hybrid sensors combining Sony's IMX636 event camera with depth-sensing SPAD arrays enable sub-millisecond latency for high-speed pick-and-place. This technology convergence targets semiconductor packaging and battery cell assembly.
- Direct-to-factory digital channels:Sensor vendors are bypassing traditional distributors through configurators that generate part numbers from application parameters. This channel innovation captures margin and reduces specification errors in automotive and logistics end-uses.
Industry Challenges
- Functional-safety engineer scarcity:ISO 26262 and IEC 61508 certification requires specialized hardware and software competency that concentrates in Germany, Japan, and the US Southwest. This talent gap extends product development cycles.
- Multi-standard compliance burden:Automotive sensors must simultaneously satisfy NHTSA FMVSS, UNECE R79, and OEM-specific test protocols. The certification complexity demands parallel validation tracks that strain engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distance Measurement Sensor Market |
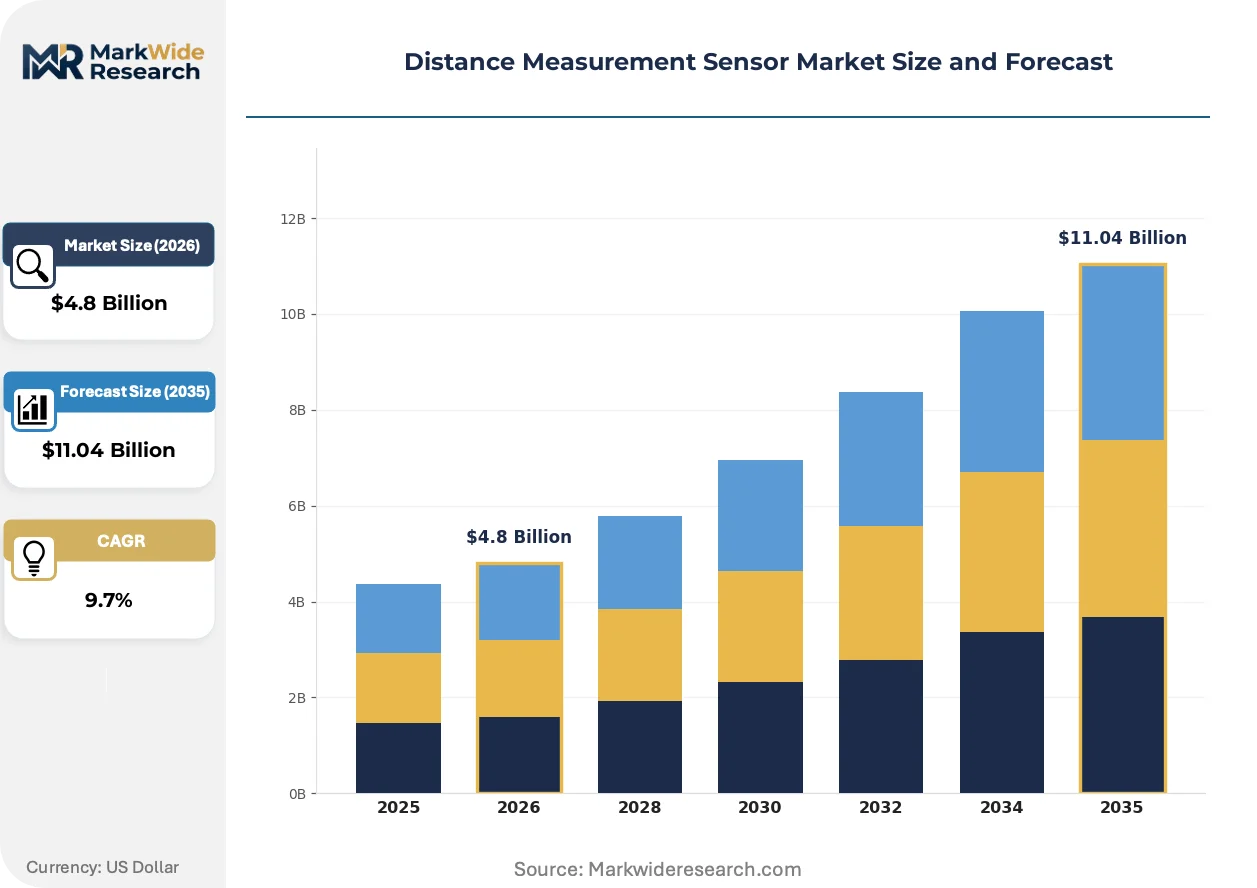
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
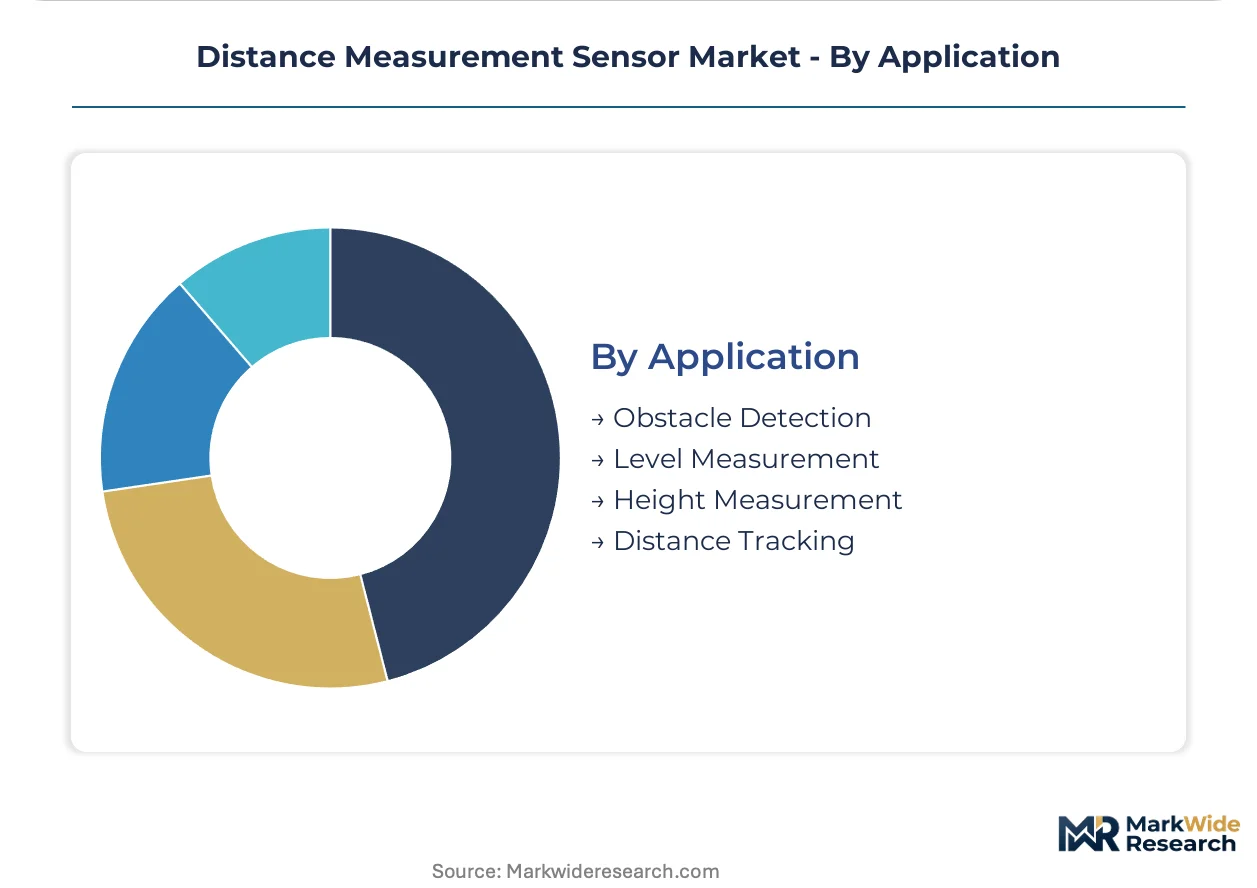
| Segmentation | Product Type: Laser Sensors, Ultrasonic Sensors, Infrared Sensors, Radar Sensors End User: Automotive, Aerospace, Robotics, Industrial Automation Technology: Time-of-Flight, Phase Shift, Triangulation, Frequency Modulation Application: Obstacle Detection, Level Measurement, Height Measurement, Distance Tracking |
| Companies Covered | Sick AG, Keyence Corporation, Pepperl+Fuchs GmbH, Honeywell International Inc., Balluff GmbH, Micro-Epsilon, Baumer Group, Eaton, Leuze Electronic GmbH + Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distance Measurement Sensor Market Emerging Trajectories
Sensor architectures are fragmenting between cost-optimized commodity modules and safety-critical redundant systems. This bifurcation is reshaping R&D allocation and vendor positioning across automotive, industrial, and medical verticals.
Time-of-flight SPAD arrays is hybridizing with conventional CMOS image sensors to create depth-enabled machine vision modules. Semiconductor packaging lines in South Korea and Taiwan are adopting these fused sensors for sub-millimeter component placement verification. The convergence is compressing the addressable market for standalone 2D vision systems in precision assembly.
REACH Annex XIV restrictions on lead and cadmium in electronic components are forcing sensor manufacturers to redesign solder joints and optical coatings. The industrial consequence is a qualification cycle for lead-free laser diode packages that extends time-to-market by 8-14 months. Automotive exterior sensors face the strictest material compliance deadlines under the EU Green Deal implementation timeline.
Buyer concentration among automotive OEMs is consolidating sensor procurement through platform-standardization mandates. Tier-1 suppliers are responding with modular sensor families that share optical engines across lidar, radar, and camera fusion products. This specification behavior is most visible in Germany, where Volkswagen Group and BMW are enforcing common sensor interfaces across vehicle architectures.
Distance Measurement Sensor Market Segmentation
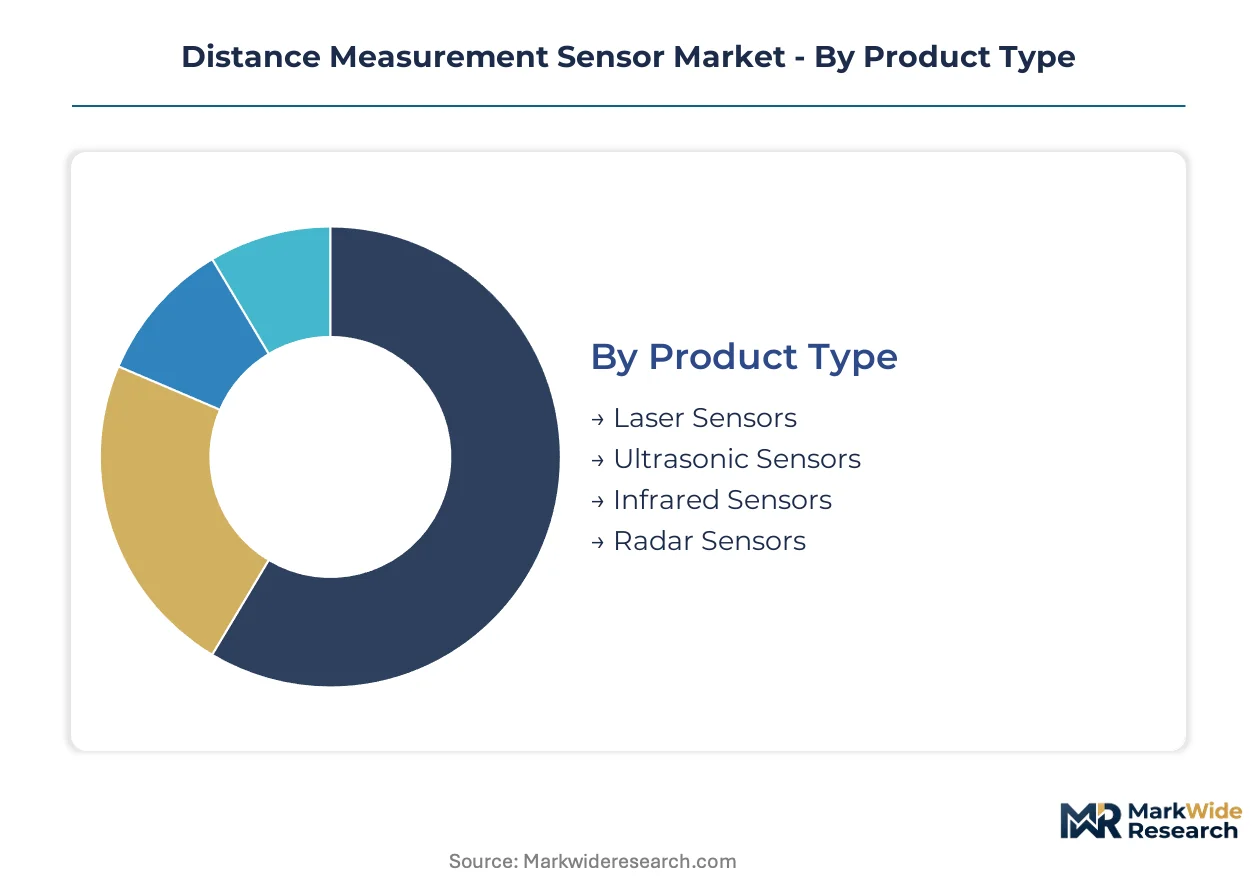
Distance measurement sensors serve divergent precision requirements across automotive safety systems and factory automation. Segmentation reveals how technology choices align with environmental constraints, regulatory mandates, and cost-performance tradeoffs in each vertical.
Product Type:
Product selection hinges on surface characteristics, ambient interference, and range requirements in target applications.
- Laser Sensors:Time-of-flight laser modules emit pulsed infrared beams and calculate distance via photon return timing, achieving millimeter accuracy at ranges exceeding 100 meters. Automotive OEMs in Germany specify these for adaptive cruise control and automated parking, driven by NHTSA emergency braking mandates and UNECE R79 lane-keeping requirements.
- Ultrasonic Sensors:Piezoelectric transducers generate high-frequency acoustic pulses that penetrate dust, fog, and transparent surfaces where optical methods fail. Industrial tank-level monitoring in chemical plants and food processing facilities depends on these devices, constrained only by slower response times and narrower detection cones.
- Infrared Sensors:Passive thermal detection systems measure emitted radiation without active illumination, serving presence detection in building automation and energy management.
- Radar Sensors:Frequency-modulated continuous-wave systems penetrate weather and debris for long-range object tracking in heavy machinery and aerospace ground operations.
The dominant share belongs to Laser Sensors, while Ultrasonic Sensors is closing the gap fastest in hazardous-environment applications.
End User:
End-user concentration determines certification pathways and procurement volume thresholds.
- Automotive:ADAS and autonomous vehicle programs consume multi-sensor fusion arrays combining lidar, radar, and camera inputs. ISO 26262 functional-safety compliance and UNECE WP.29 cybersecurity regulations dominate supplier qualification in this segment.
- Industrial Automation:Collaborative robots and automated guided vehicles require ISO 13849-certified distance sensors for human-robot interaction safety. Machine builders in Stuttgart and Munich specify redundant time-of-flight systems to maintain CE marking under amended EU Machinery Directive requirements.
- Aerospace:Ground proximity warning and cargo loading systems demand MIL-STD-810 environmental ruggedization and DO-160G electromagnetic compatibility.
- Robotics:Surgical and service robots integrate compact depth sensors for spatial mapping and instrument positioning, subject to FDA 510(k) or EMA medical device pathways.
Automotive commands the largest procurement volumes, though Industrial Automation is expanding most quickly as EU safety retrofit cycles accelerate.
Technology:
Technology adoption tracks the tradeoff between measurement speed, precision, and semiconductor cost curves.
- Time-of-Flight:Direct measurement of photon travel time enables high-speed distance capture with single-chip SPAD arrays. VCSEL and detector cost declines below critical thresholds have unlocked automotive volume deployment.
- Phase Shift:Continuous-wave interferometry achieves sub-millimeter repeatability for precision assembly and semiconductor packaging. Battery cell manufacturing in South Korea and Taiwan specifies these systems for electrode alignment verification.
- Triangulation:Angular displacement calculation from structured light patterns serves short-range, high-resolution applications in 3D scanning and quality inspection.
- Frequency Modulation:FMCW radar techniques enable simultaneous distance and velocity measurement for dynamic object tracking in logistics and mining equipment.
Time-of-Flight holds the installed base advantage, yet Phase Shift is gaining share fastest in precision manufacturing segments.
Application:
Application requirements dictate sensor specification priorities from response latency to environmental sealing.
- Obstacle Detection:Real-time collision avoidance in mobile robotics and vehicles demands sub-50-millisecond latency with redundant sensing architectures. Automotive exterior applications face REACH Annex XIV material restrictions and EU Green Deal compliance deadlines for lead-free optical coatings.
- Level Measurement:Continuous fill monitoring in silos, tanks, and vessels favors ultrasonic and radar technologies that tolerate vapor, foam, and dust. Food and beverage processors in Italy retrofit production lines with hygienic-certified sensors to satisfy CE marking updates.
- Height Measurement:Dimensional verification for palletizing, warehousing, and vehicle loading uses laser or time-of-flight modules with moderate range and high repeatability.
- Distance Tracking:Relative position monitoring for automated guided vehicles and crane systems integrates multi-sensor fusion with SLAM algorithms for navigation.
Obstacle Detection generates the highest unit volumes, while Level Measurement is climbing the fastest as process industry automation deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs command premium pricing for ISO 13849-certified sensors, while Indian machine builders purchase mid-range ultrasonic units at 40% lower price points. This asymmetry reflects divergent regulatory enforcement timelines and local manufacturing scale.
Germany
Automotive OEMs in Stuttgart and Munich specify redundant time-of-flight sensors for adaptive cruise control and automated parking systems. The EU Machinery Directive's 2023 amendments compel machine builders to retrofit production lines with CE-marked components to maintain market access. Industrial clusters around Stuttgart host dense concentrations of Tier-1 sensor integrators serving Volkswagen Group and BMW platform standardization mandates.
United States
NHTSA's proposed automatic emergency braking mandate for light vehicles accelerates procurement of long-range lidar and radar fusion sensors. FDA scrutiny of sensor-enabled surgical robotics creates multi-year approval timelines for medical-grade distance measurement systems. Southwest engineering talent pools in Arizona and Texas concentrate ISO 26262 functional-safety competency for automotive sensor development.
China
Domestic battery cell manufacturers in the Yangtze River Delta specify phase-shift laser systems for electrode alignment verification. MIIT semiconductor localization policies incentivize VCSEL array and SPAD photodetector foundry investments. Shenzhen and Shanghai host converging supply chains for time-of-flight modules serving consumer electronics and automotive ADAS programs.
Japan
Precision manufacturing segments in Osaka and Nagoya anchor demand for sub-millimeter repeatability sensors in semiconductor packaging. METI industrial automation subsidies support collaborative robot deployments requiring ISO 13849-certified distance sensors. Japanese foundries concentrate high-performance InGaAs photodetector production for lidar receivers.
India
The PLI scheme for electronics and automotive components attracts sensor assembly investments from multinational vendors. Domestic machine builders in Pune and Chennai represent underpenetrated demand for mid-range ultrasonic and laser sensors. BIS certification requirements for industrial safety equipment create compliance barriers for uncertified imports.
Distance Measurement Sensor Market Vendor Landscape
Factory-automation heritage specialists and precision-manufacturing direct-sales operators split the market between channel-controlled European machine builders and high-touch Asian electronics producers. The vendor base concentrates around three strategic archetypes: diversified industrial conglomerates with hazardous-area certifications, focused sensor technology pure-plays with functional-safety expertise, and semiconductor-integrated module suppliers leveraging cost-curve advantages. Competitive moves center on direct-to-factory digital channel expansion and modular sensor family development for platform-standardized automotive procurement.
Within the factory-automation archetype, Sick AG and Pepperl+Fuchs GmbH represent European heritage positions anchored in CE-marking compliance and hazardous-area certifications. Keyence Corporation exemplifies the precision-manufacturing direct-sales model through its dominance of high-touch technical engagement in Japanese and North American electronics assembly. These three companies occupy distinct competitive territories defined by channel strategy rather than product overlap.
| Leading Market Players |
|---|
| Sick AG |
| Keyence Corporation |
| Pepperl+Fuchs GmbH |
| Honeywell International Inc. |
| Balluff GmbH |
| Micro-Epsilon |
| Baumer Group |
| Eaton |
| Leuze Electronic GmbH + Co. KG |
| Others |
Supply Flow & Price Mechanics
Stuttgart's industrial sensor cluster concentrates time-of-flight module production capacity, feeding downstream pricing power to German automotive OEMs who specify redundant safety-certified configurations. Cost compression in VCSEL arrays and SPAD photodetectors is transmitting downward through mid-range tiers, while premium functional-safety SKUs retain margin insulation through ISO 13849 certification scarcity.
Pricing Analysis
The customization-premium spread separates configured-to-order laser sensors priced for automotive ADAS platforms from standard ultrasonic units serving industrial level measurement. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with ISO 26262-compliant automotive modules commanding substantial premiums over CE-marked industrial variants. Cost compression in semiconductor components is intensifying price competition within the standard tier, while collaborative robot manufacturers demonstrate highest price sensitivity due to margin pressure in cobot hardware.
Supply Chain Analysis
Export-control regimes restricting InGaAs photodetector technology flow from Japanese and Chinese foundries are constraining high-performance lidar receiver supply. Taiwan, South Korea, and Japan concentrate VCSEL array and CMOS-SPAD manufacturing capacity, while German and Chinese facilities dominate final sensor module assembly. InGaAs substrates, precision optical coatings, and hermetic packaging materials anchor raw material dependencies. Single-source vulnerability around Japanese InGaAs foundries poses structural risk. Distribution runs through direct-to-OEM digital channels and authorized distributor networks serving machine builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as functional-safety mandates splinter procurement between certified automotive-grade systems and cost-optimized industrial variants, creating distinct competitive arenas for specialized entrants.
For Market Incumbents: Pre-empt margin erosion in standard-tier industrial sensors by capturing ISO 13849 certification capacity before demand surges from EU Machinery Directive retrofit cycles. Consolidate channel control through direct-to-factory digital configurators that reduce specification errors and capture distributor margin. Threat of semiconductor-integrated module suppliers leveraging cost-curve advantages demands backward integration into VCSEL array sourcing. For New Entrants and Emerging Players: Mid-market machine builders in Pune and Chennai represent the most penetrable entry point for uncertified ultrasonic and short-range laser sensors, as BIS compliance barriers filter out unqualified imports. Battery cell assembly lines in South Korea seeking sub-millimeter phase-shift systems for electrode alignment offer a second white-space target. Go-to-market through regional automation integrators who bundle sensors with turnkey robot installations bypasses direct competition with established direct-sales organizations. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming sensor divisions lacking functional-safety engineering depth. Long-term viability over the next decade hinges on certification competency concentration in Germany and Japan rather than pure manufacturing scale. Watch for inflection when tier-1 automotive suppliers consolidate procurement through platform-standardization mandates, signaling which sensor architectures will capture volume.| Strategic Initiative | Industry Significance |
|---|---|
| Functional-Safety Certification Investment | ISO 13849 and ISO 26262 compliance unlocks automotive and collaborative robot procurement at premium pricing tiers. |
| Direct-to-Factory Digital Channel | Application-based configurators reduce specification errors and capture margin from traditional distributor networks. |
| Semiconductor Cost-Curve Exploitation | VCSEL and SPAD price declines enable sub-hundred-dollar automotive-grade module deployment in mid-range vehicles. |
| Regional Assembly Investment | PLI scheme alignment in India attracts sensor assembly capacity to serve underpenetrated domestic machine builder demand. |
| Hybrid Sensor Architecture Development | Time-of-flight SPAD fusion with event-based vision targets sub-millisecond latency in semiconductor packaging applications. |
Methodological Framework
A spread of perspectives from automotive Tier 1 procurement directors, industrial automation system integrators, functional-safety engineering consultants, and semiconductor component specialists converged on the working assumptions shaping this analysis. Primary interview findings were validated against secondary sources including NHTSA regulatory filings, EU Machinery Directive amendment texts, SEC 10-K disclosures from listed sensor vendors, and customs trade data for InGaAs photodetector flows. Bottom-up unit demand estimates from end-use applications were triangulated with top-down market size assessments across the projection horizon.
Demand-supply-balance framing anchored the analytical framework, modeling adoption trajectories across technology type, product architecture, end-use vertical, and regional regulatory cluster throughout the forecast period. CAGRs were derived from segment-level growth rates weighted by base-year revenue contribution. Forecast inputs incorporated automotive ADAS penetration curves, EU safety retrofit cycle timing, and semiconductor cost-curve trajectories for VCSEL and SPAD components.
Practitioners should monitor export licensing delays for InGaAs photodetectors, NHTSA mandate finalization timelines, and REACH Annex XIV material compliance deadlines for early signals of forecast deviation. Forecasts reflect documented assumptions about regulatory enforcement intensity and semiconductor supply expansion. Material shifts in geopolitical friction affecting Japanese-Chinese foundry output or accelerated EU Green Deal implementation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Wireless Temperature Sensor Market
Sensors and Controls
North America Occupancy Sensors Market
Sensors and Controls
Subcool Metering Device Market
Sensors and Controls
Two Wheeler Sensors Market
Sensors and Controls
Manifold Absolute Pressure Sensor Market
Sensors and Controls
Global Blind Spot Monitor Market
Sensors and Controls
Smart Thermometer Market
Sensors and Controls
Odor Detection Equipment Market
Sensors and Controls
Digital Sensor Sleeves Market
Sensors and Controls
Smart Control Socket Market
Sensors and Controls
Smart Glove Market
Sensors and Controls
Atomic Clock Market
Sensors and Controls
North America MEMS and Sensors Market
Sensors and Controls
Europe Nano Sensors Market
Sensors and Controls
Body Worn Antenna Market
Sensors and Controls
United States (US) Industrial Sensors Market