
 Europe Pressure Transmitter Market | 2026-2036
Europe Pressure Transmitter Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pressure Transmitter Market Intelligence
Remote diagnostics and predictive maintenance subscriptions is broadening what European buyers procure alongside hardware. Endress+Hauser AG leverages its Swiss-German service network to anchor long-term contracts across chemical clusters. Siemens AG sustains R&D intensity in software-defined pressure measurement, integrating transmitters into its industrial IoT stack. ABB Ltd competes through specialized digital offerings for hazardous-area installations in North Sea oil operations.
A pressure transmitter converts fluid or gas pressure into a standardized electrical signal, typically 4-20 mA or digital protocols, using sensing elements such as piezoresistive silicon or capacitive ceramic membranes to enable real-time process control in automated industrial environments. Smart transmitters with embedded microprocessors and wireless HART capability now dominate new installations, while analog units persist in cost-sensitive retrofit scenarios across Eastern European facilities. Piezoresistive technology leads unit shipments due to its compatibility with aggressive media in chemical processing, though resonant silicon designs are capturing share in precision aerospace and semiconductor applications where stability requirements are stringent.
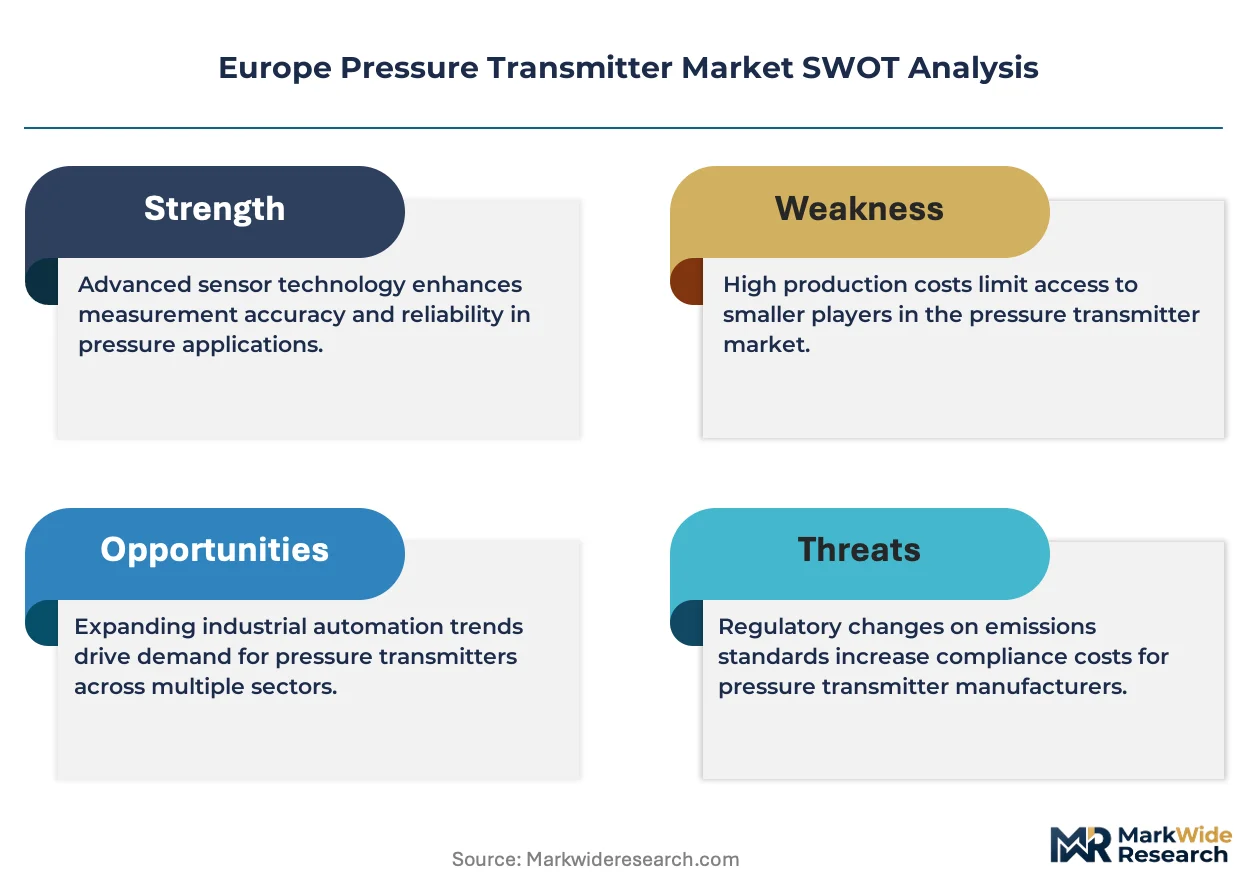
The EU F-Gas Regulation and ATEX directives enforced by national regulators shape product certification requirements and market access for pressure transmitters deployed in explosive atmospheres. CE marking under the Measuring Instruments Directive and compliance with IEC 61508 functional safety standards determine supplier eligibility for European process industries. EMA guidelines on pharmaceutical manufacturing and national environmental agencies' emissions monitoring mandates further tighten specification thresholds for instrumentation. Stakeholders must weigh the pace of wireless adoption against the installed base of wired 4-20 mA infrastructure when allocating development resources across product portfolios.
Market Dynamics
The EU F-Gas Regulation and ATEX directives are forcing accelerated replacement cycles across European process industries, compressing equipment lifecycles from fifteen years to under ten as facilities race to meet 2030 emissions benchmarks.
Growth Catalysts
- HART Protocol Integration:German chemical plants in the Ruhr corridor are upgrading legacy analog units to digital smart transmitters, creating pull for fieldbus-compatible instrumentation.
- EU Green Deal Implementation:National environmental agencies' emissions monitoring mandates are tightening specification thresholds for leak detection and process control systems.
- Piezoresistive Silicon Scaling:Advances in MEMS fabrication are lowering unit costs for aggressive-media-compatible sensors, expanding addressable applications in sulfuric acid and chlorine processing.
Market Restraints
- Stainless Steel Input Volatility:316L and Hastelloy price swings from Nordic suppliers are compressing margin buffers for transmitter housing manufacturers.
- Specialized Foundry Concentration:Capacitive ceramic membrane production concentrates in southern German precision ceramics clusters, creating single-source vulnerability.
- Wireless HART Interference Limits:Dense industrial RF environments in petrochemical complexes restrict reliable transmission range, delaying full cable replacement.
Strategic Opportunities
- Eastern European Retrofit Lag:Polish and Romanian facilities still operate 30% analog-installed bases, representing conversion-ready demand for smart transmitter vendors.
- Predictive Maintenance Subscriptions:Cloud-based diagnostics bundled with hardware sales are unlocking recurring revenue streams previously captured by third-party service providers.
- Semiconductor Cleanroom Expansion:Resonant silicon designs for ultra-high-purity gas distribution are finding new demand in Dutch and Irish fabs.
Industry Challenges
- IEC 61508 Functional Safety Certification:SIL-rated transmitter qualification timelines stretch 18-24 months, delaying product launches for safety-critical applications.
- Legacy 4-20 mA Integration Complexity:Brownfield installations require protocol converters and signal conditioners, inflating engineering costs and commissioning durations.
- ATEX Notified Body Backlogs:Explosion-proof certification queues at German and British testing houses are extending time-to-market for hazardous-area product variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pressure Transmitter Market |
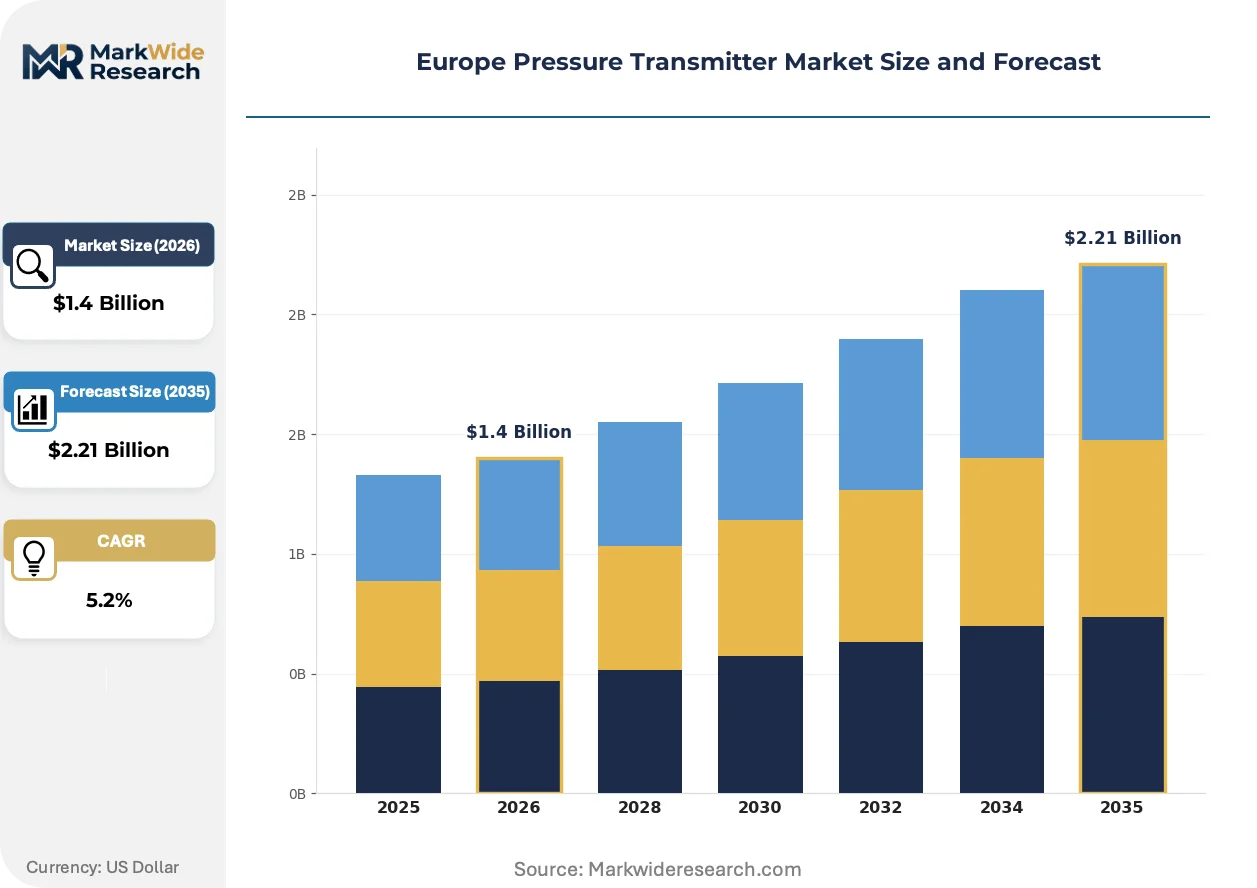
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.21 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, Smart, Wireless End User: Oil & Gas, Water & Wastewater, Chemical, Food & Beverage Technology: Piezoresistive, Capacitive, Strain Gauge, Resonant Installation: In-line, Compact, Flush Mount, Submersible |
| Companies Covered | Endress+Hauser AG, Siemens AG, ABB Ltd, Schneider Electric SE, Emerson Electric Co., Honeywell International Inc., Yokogawa Electric Corporation, Bosch Sensortec GmbH, Kistler Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pressure Transmitter Market Strategic Shifts & Innovations
Software-defined measurement architectures and edge-computing integration are redrawing competitive boundaries between pure-play instrument manufacturers and industrial automation platforms.
Silicon carbide sensing elements are rewriting durability benchmarks for high-temperature steam applications. Austrian and Czech power utilities are piloting SiC transmitters in turbine bypass stations operating above 400°C. The technology is compressing maintenance intervals from quarterly to annual cycles in geothermal and combined-cycle plants.
REACH substance restrictions on perfluorinated compounds are forcing membrane material substitutions in capacitive pressure sensors. ECHA's 2023 PFAS restriction proposal is compelling Swiss and German sensor houses to qualify ceramic-alternative dielectrics ahead of enforcement. Pharmaceutical manufacturers in Basel and Frankfurt are front-running compliance by specifying PFAS-free instruments in new capital projects.
Service unbundling is fragmenting traditional supplier-buyer relationships. End-users in North Sea oil operations are separating hardware procurement from calibration and diagnostic subscriptions, driving ABB and Endress+Hauser to establish standalone software revenue lines. The shift is most pronounced in Norwegian offshore platforms, where integrated service contracts now cover 60% of installed transmitter fleets.
Europe Pressure Transmitter Market Segmentation
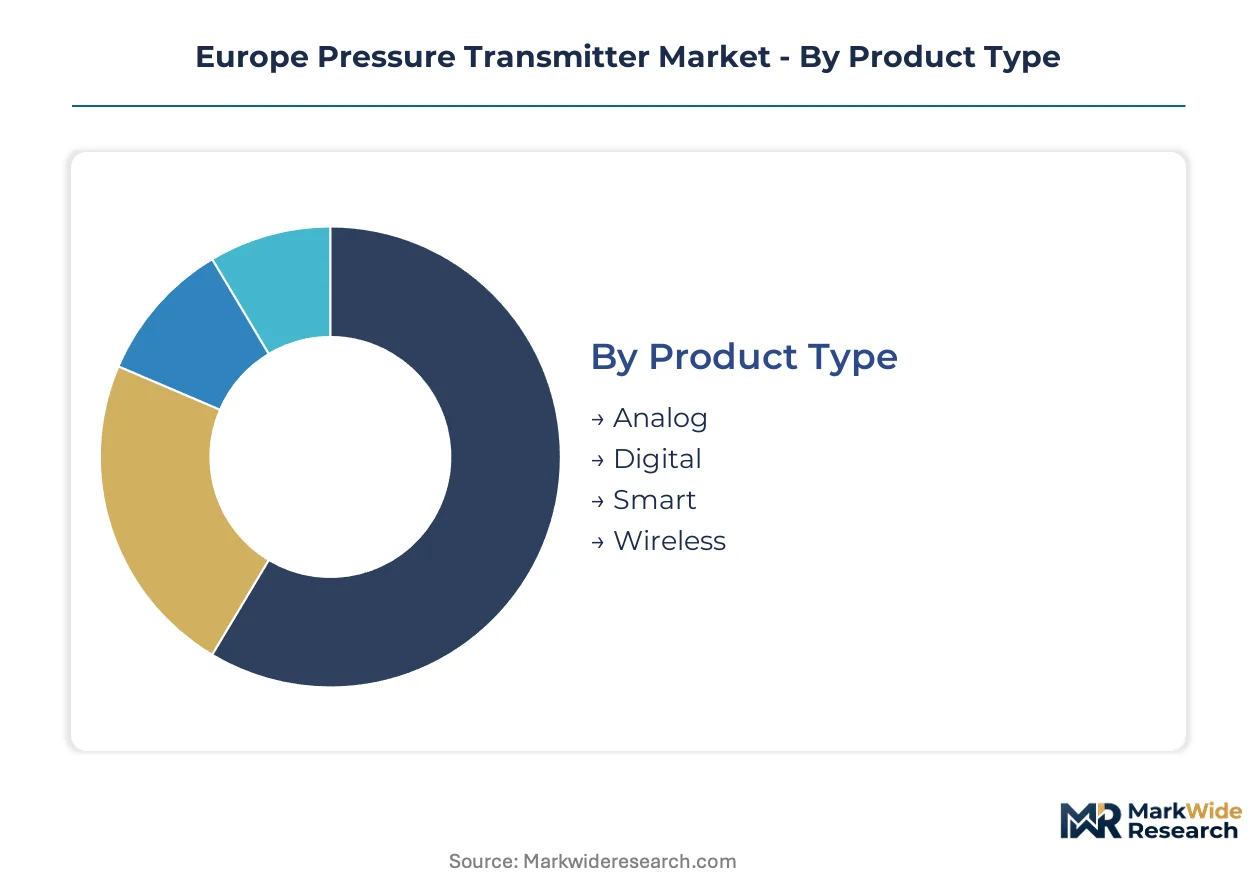
Segmentation in the European pressure transmitter market reveals how certification requirements, protocol compatibility, and media aggressiveness reshape procurement patterns across process industries. Buyers segment choices by functional safety ratings, ATEX zones, and HART integration needs rather than price alone.
Product Type:
ATEX Directive 2014/34/EU and IEC 61508 functional safety certifications impose divergent compliance burdens across transmitter categories, with SIL-rated smart units requiring 18-24 month qualification timelines.
- Smart:Embedded microprocessors enable HART protocol integration and predictive diagnostics. German chemical plants in the Ruhr corridor prioritize these units for emissions monitoring compliance under EU F-Gas Regulation mandates.
- Digital:Fieldbus-compatible architectures with FOUNDATION Fieldbus or Profibus PA interfaces dominate greenfield installations. Dutch and Belgian refineries specify these for integrated distributed control systems.
- Analog:4-20 mA output transmitters persist in Polish and Romanian retrofit scenarios where legacy DCS infrastructure limits protocol migration.
- Wireless:Battery-powered HART units face RF interference constraints in dense petrochemical complexes, restricting deployment to auxiliary monitoring applications.
Smart transmitters sit at the top of the volume ranking, with wireless climbing the fastest as Nordic offshore platforms trial cable-free architectures.
End User:
Margin structures diverge sharply by end-use sector, with hazardous-area certifications and material specifications determining pricing tiers.
- Chemical:Aggressive media compatibility with sulfuric acid and chlorine drives piezoresistive silicon specification. Basel and Frankfurt pharmaceutical clusters demand PFAS-free membrane alternatives ahead of ECHA restrictions.
- Oil & Gas:North Sea operations require IECEx and ATEX Zone 0/1 certification for subsea and platform installations. Norwegian integrated service contracts now cover diagnostic subscriptions separately from hardware.
- Water & Wastewater:Submersible and flush-mount configurations dominate municipal treatment facilities. Austrian utilities pilot silicon carbide elements for high-temperature steam monitoring.
- Food & Beverage:EHEDG and 3-A sanitary standards govern dairy and brewing applications. Irish and Dutch dairy processors specify CIP-compatible diaphragm seals.
Chemical applications command the highest specification density, with oil and gas showing the steepest expansion trajectory as offshore electrification accelerates sensor refresh cycles.
Technology:
Foundry concentration and raw material supply shape technology selection, with ceramic membrane production clustering in southern German precision ceramics regions.
- Piezoresistive:MEMS-fabricated silicon elements withstand aggressive chemical media. Sulfuric acid processing in German and Czech chemical parks relies on this technology for corrosion resistance.
- Resonant:Quartz-based designs deliver stability for semiconductor cleanroom gas distribution. Dutch and Irish fabs specify these for ultra-high-purity nitrogen and argon systems.
- Capacitive:Ceramic membrane construction faces REACH-driven material substitutions as ECHA PFAS restrictions compel dielectric reformulation.
- Strain Gauge:Bonded foil and thin-film configurations serve general industrial applications with moderate accuracy requirements.
Piezoresistive technology leads unit shipments, with resonant designs gaining share fastest in precision applications.
Installation:
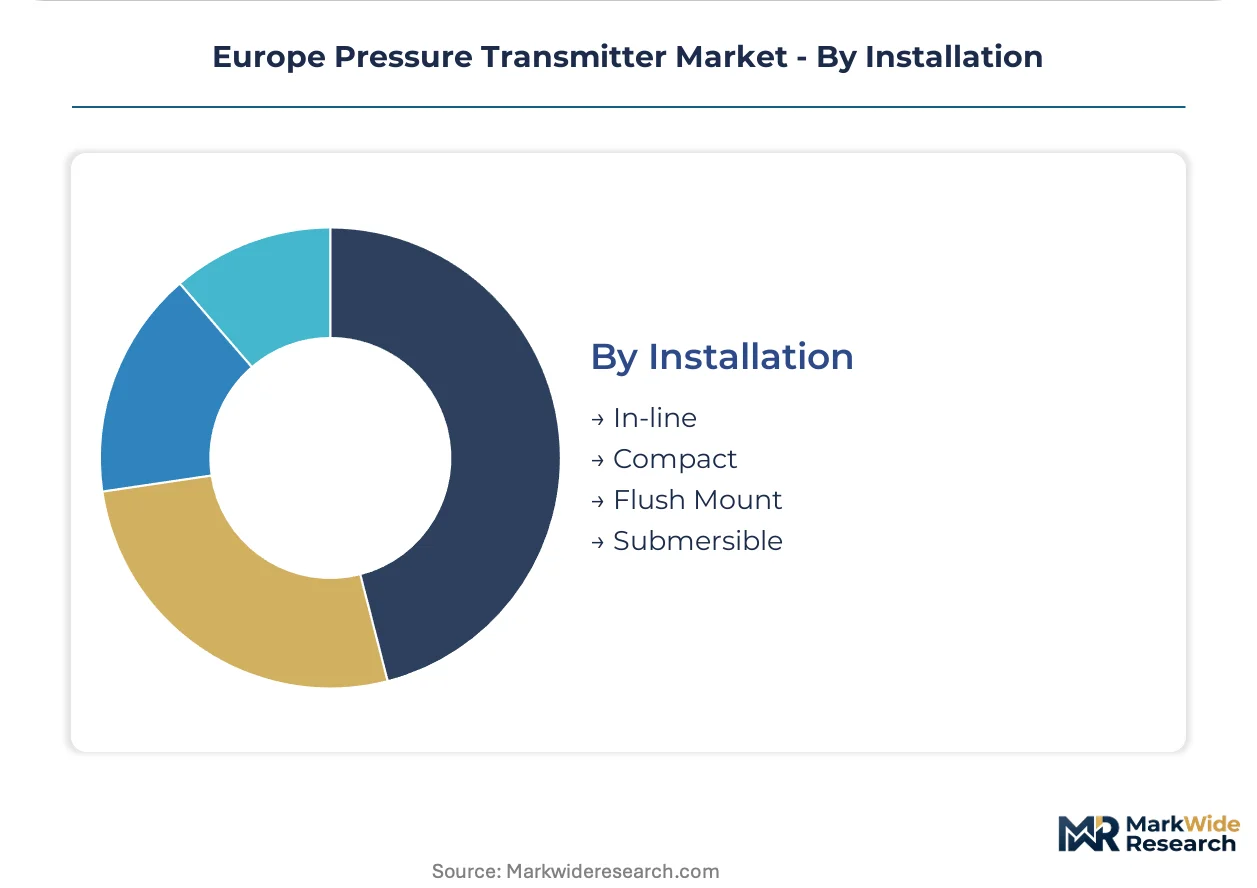
Physical configuration determines seal compatibility and maintenance accessibility, with compact designs commanding premium positioning in space-constrained skids.
- In-line:Threaded and flanged process connections dominate standard piping configurations. German chemical retrofit projects specify these for minimal downtime replacement.
- Compact:Integrated electronics housing reduces footprint for OEM skid builders. Italian and Spanish packaging machinery manufacturers specify these for hygienic washdown environments.
- Flush Mount:Diaphragm-fronted designs prevent clogging in pulp and viscous media. Nordic paper mills deploy these for black liquor processing.
- Submersible:Sealed cable entry and vented gauge references suit groundwater and tank level monitoring. French and British water utilities standardize on these for reservoir management.
In-line configurations anchor volume leadership, with compact formats expanding most quickly as modular process skids proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production footprints across Europe as manufacturers relocate assembly to jurisdictions with streamlined ATEX certification pathways. The EU F-Gas Regulation applies uniformly, but national implementation timelines and notified body capacities create compliance-cost differentials that influence sourcing decisions.
Germany
Ruhr corridor chemical plants are executing the continent's largest analog-to-digital retrofit program, replacing legacy 4-20 mA transmitters with HART-enabled smart units. The Federal Environment Agency enforces emissions monitoring mandates under EU Green Deal implementation. Stuttgart-based precision ceramics clusters supply capacitive membrane substrates for hazardous-area instrumentation.
France
Île-de-France pharmaceutical manufacturers are front-running ECHA PFAS restrictions by specifying membrane material alternatives in cleanroom gas distribution systems. ANSM guidelines on sterile manufacturing tighten specification thresholds for process instrumentation. Lyon and Grenoble semiconductor fabs drive resonant silicon transmitter demand for ultra-high-purity nitrogen systems.
Netherlands
Rotterdam-Botlek refining complexes specify FOUNDATION Fieldbus-compatible digital transmitters for integrated distributed control architectures. The Dutch Emissions Authority enforces leak detection mandates that compress equipment replacement cycles. Eindhoven semiconductor equipment manufacturers anchor precision pressure measurement demand for EUV lithography gas handling.
Poland
Upper Silesian chemical facilities operate substantial analog-installed bases that represent conversion-ready demand for smart transmitter vendors. The Chief Inspectorate of Environmental Protection implements EU F-Gas Regulation through national emissions trading linkages. Wrocław and Kraków process automation distributors are building calibration service capabilities to capture aftermarket revenue.
Norway
North Sea offshore platforms are separating hardware procurement from diagnostic subscriptions, with integrated service contracts now covering majority transmitter fleets. The Norwegian Environment Agency enforces Ospar Convention emissions monitoring that drives sensor refresh cycles. Stavanger and Bergen subsea technology clusters specify IECEx Zone 0 certified instrumentation for electrification projects.
Europe Pressure Transmitter Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with full-service instrumentation houses commanding premium positioning in chemical and pharmaceutical verticals while component suppliers capture volume in general industrial applications. The vendor base concentrates around Swiss-German engineering heritage and Nordic industrial automation platforms. Three archetypes dominate: integrated automation platforms with software-defined measurement stacks, precision sensor specialists with hazardous-area certification depth, and volume manufacturers serving cost-sensitive retrofit markets. Competitive moves center on predictive maintenance subscription bundling and silicon carbide sensing technology licensing.
Among Swiss-German precision instrumentation houses, Endress+Hauser AG and Siemens AG exemplify the integrated-service archetype, anchoring long-term contracts through captive calibration networks. ABB Ltd occupies a position within the hazardous-area specialization tier, representing Nordic engineering capabilities in subsea and platform applications. These three entities illustrate how geographic proximity to Ruhr chemical clusters and North Sea oil operations confers customer relationship advantages that transcend pure product specifications.
| Leading Market Players |
|---|
| Endress+Hauser AG |
| Siemens AG |
| ABB Ltd |
| Schneider Electric SE |
| Emerson Electric Co. |
| Honeywell International Inc. |
| Yokogawa Electric Corporation |
| Bosch Sensortec GmbH |
| Kistler Group |
| Others |
Cost & Logistics Intelligence
Silicon carbide sensing element adoption is compressing maintenance cycles while concentrating procurement power among Austrian and Czech utilities that pilot high-temperature steam applications above 400°C. This technology transition simultaneously elevates performance premiums for qualified suppliers and narrows the vendor pool capable of meeting combined-cycle plant specifications.
Pricing Analysis
Distributor margins in German chemical corridors absorb 15-25 points before hardware reaches Ruhr retrofit sites, while direct-to-OEM contracts for modular skid builders bypass this layer entirely. Three-tier pricing structure across SIL-certified premium, standard smart, and analog economy levels reflects ATEX zone requirements rather than raw performance. Pricing pressure stems from 316L and Hastelloy input volatility originating with Nordic stainless suppliers. Municipal water utilities exhibit highest price sensitivity; North Sea offshore operators prioritize certification over unit cost.
Supply Chain Analysis
ATEX and IECEx qualification timelines stretching 18-24 months function as supply-side gates that protect incumbent positions while delaying new entrant market access. Capacitive ceramic membrane production concentrates in southern German precision ceramics clusters, with piezoresistive silicon MEMS fabrication anchored in Swiss-German foundry networks. Raw material dependencies include 316L stainless steel from Nordic mills, Hastelloy C-276 for aggressive media housings, and high-purity silicon wafers for sensing elements. Single-source vulnerability in ceramic substrate supply creates exposure to ECHA PFAS restriction enforcement. Distribution runs through Stuttgart-based instrumentation distributors serving chemical clusters, with direct OEM relationships dominating greenfield project channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between Polish analog retrofit lag and German accelerated replacement cycles creates geographic cost differentials of 20-30 points in project economics, favoring staged market entry strategies.
For Market Incumbents: Anticipate REACH-driven membrane material substitutions by qualifying ceramic-alternative dielectrics ahead of ECHA enforcement timelines. Secure backward integration into southern German precision ceramics capacity to defend against single-source rupture. Deepen captive calibration network density in Upper Silesia to capture Polish conversion-ready demand before distributors build competing service capabilities. For New Entrants and Emerging Players: Launch via Wrocław and Kraków process automation distributors that are currently building calibration service capabilities but lack manufacturer-direct relationships. Target Romanian facilities with 30% analog-installed bases where legacy DCS infrastructure limits protocol migration and price sensitivity is acute. Lead with wireless HART units for auxiliary monitoring applications where RF interference constraints are less severe than in dense petrochemical complexes. For Investors and Strategic Acquirers: Valuations sit cheapest among Eastern European retrofit specialists with established analog-to-digital conversion capabilities but limited hazardous-area certification depth. Long-term viability over the analysis window favors targets with SIL-rated qualification pipelines and software-defined measurement architectures. Watch for inflection when ATEX Notified Body backlogs at German and British testing houses begin clearing, accelerating time-to-market for certified product variants.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Membrane Qualification | ECHA restrictions are forcing dielectric substitutions ahead of enforcement in Basel and Frankfurt pharmaceutical clusters. |
| Predictive Maintenance Subscription Bundling | Norwegian offshore platforms now separate hardware procurement from diagnostic subscriptions covering 60% of installed fleets. |
| Silicon Carbide Sensing Technology Licensing | Austrian and Czech utilities pilot SiC transmitters for turbine bypass stations operating above 400°C. |
| ATEX Certification Fast-Track Investment | Explosion-proof certification queues at German testing houses are extending time-to-market for hazardous-area variants. |
| Eastern European Calibration Network Buildout | Polish distributors in Wrocław and Kraków are capturing aftermarket revenue from analog-to-digital conversion demand. |
Research Approach
Direct dialogue with plant engineers at Ruhr chemical facilities, procurement leads at North Sea oil operators, calibration service heads at Swiss-German instrumentation houses, and aftermarket specialists at Polish distributors grounded qualitative findings. Secondary validation drew from EU F-Gas Regulation implementation documents, ECHA PFAS restriction proposals, ATEX Notified Body certification records, and customs data tracking 316L and Hastelloy trade flows. Bottom-up unit shipment estimates triangulated against top-down capital expenditure projections from national environmental agencies.
Installed base conversion rates across analog-to-smart transmitter migrations generated volume trajectories over the projection horizon. Segmentation dimensions modeled include product architecture (smart, digital, analog, wireless), end-use vertical (chemical, oil and gas, water, food and beverage), sensing technology (piezoresistive, resonant, capacitive, strain gauge), and installation configuration (in-line, compact, flush mount, submersible). CAGRs derived from replacement cycle compression under EU emissions mandates and MEMS fabrication cost curves. Industry-specific inputs incorporated IEC 61508 SIL qualification timelines and wireless HART interference constraints in dense RF environments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated ECHA enforcement or extended ATEX certification backlogs. Model assumptions reflect EU Green Deal implementation pace, REACH substance restriction timelines, and national emissions monitoring mandate adoption. A model refresh is warranted upon material change in Notified Body processing capacity or PFAS restriction enforcement dates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Automotive MEMS Sensor Market
Sensors and Controls
Fiber Bragg Grating Sensor Market
Sensors and Controls
Asia-Pacific Industrial Control System Market
Sensors and Controls
Tactile Indicators Market
Sensors and Controls
Instrumented Load Shackle Market
Sensors and Controls
United States Sensor Market
Sensors and Controls
Gyroscope Market
Sensors and Controls
High-Voltage Isolation and Leakage Sensor Components Market
Sensors and Controls
Condition Monitoring Sensors Market
Sensors and Controls
Global Solid State Lidar Sensor Market
Sensors and Controls
China Pressure Sensors Market
Sensors and Controls
Rain Sensors Market
Sensors and Controls
CO Gas Sensors Market
Sensors and Controls
Global Digital Temperature and Humidity Sensor Market
Sensors and Controls
Magnetic Absorption Data Line Market
Sensors and Controls
Smart Temperature Management Market