
 North America Acoustic Sensors Market | 2026-2036
North America Acoustic Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
North America Acoustic Sensors Market Foresight
Surface acoustic wave to bulk acoustic wave migration is tilting fabrication priorities across North American suppliers. Honeywell International Inc. anchors defense and aerospace contracts with in-house piezoelectric crystal growth. Siemens AG competes through industrial automation integration, embedding acoustic diagnostics into predictive maintenance platforms. Knowles Corporation dominates MEMS microphone supply for consumer voice interfaces.
Acoustic sensors are transducers that convert mechanical sound waves into electrical signals through piezoelectric, capacitive, or electromagnetic mechanisms, typically operating across frequency ranges from infrasonic to ultrasonic bands for detection, measurement, or control applications. Ultrasonic sensors command premium positioning in automotive park-assist and industrial non-destructive testing where resolution thresholds separate qualified suppliers. Smart sensor architectures are displacing analog outputs in healthcare and consumer electronics as edge-processing requirements intensify.
The U.S. Department of Transportation's FMVSS updates and FDA device classification standards shape product qualification pathways for automotive and medical acoustic components. FCC Part 15 emissions rules constrain wireless sensor design for industrial IoT deployments. Stakeholders must monitor NHTSA rulemaking on pedestrian alert systems and EPA noise enforcement thresholds to anticipate specification shifts.
Market Dynamics
Surface acoustic wave to bulk acoustic wave migration is compressing fabrication timelines across North American foundries while NHTSA pedestrian alert mandates force acoustic component redesigns in automotive supply chains.
Growth Catalysts
- FMVSS Pedestrian Alert Mandates:NHTSA rules requiring acoustic vehicle alerting systems for hybrid and electric vehicles are pulling ultrasonic and speaker-based sensors into every new automotive platform.
- MEMS Miniaturization:Semiconductor fabrication advances are shrinking microphone form factors for wearable health monitors and hearable devices.
- Great Lakes Aerospace Cluster:Concentrated defense and commercial aviation manufacturing around Detroit, Cleveland, and Toronto sustains demand for high-reliability piezoelectric arrays.
Market Restraints
- Lithium Niobate Supply Concentration:Bulk acoustic wave filter production depends on crystal substrates sourced from a narrow supplier base in Russia and China, exposing North American fabricators to input volatility.
- FCC Part 15 Emission Constraints:Industrial IoT wireless acoustic sensors face certification delays and design compromises from strict radiated emission limits.
- Optical Sensing Substitution:LiDAR and camera-based systems are capturing share in automotive park-assist and industrial distance measurement where line-of-sight conditions permit.
Strategic Opportunities
- Mexican Automotive Assembly Expansion:OEM capacity additions in Querétaro and Guanajuato create localized demand for tier-two acoustic sensor suppliers.
- FDA Breakthrough Device Pathway:Expedited review for acoustic-based diagnostic tools accelerates commercialization timelines for cardiovascular and pulmonary monitoring applications.
- Edge-AI Convergence:On-sensor neural network inference is opening premium positioning for smart acoustic transducers in predictive maintenance and voice authentication.
Industry Challenges
- Piezoelectric Materials Engineering Talent:North American universities produce insufficient graduates with expertise in ferroelectric crystal growth and thin-film deposition.
- ISO 26262 Automotive Safety Certification:ASIL-rated acoustic components require 18-24 month validation cycles that strain development budgets.
- Legacy Analog System Integration:Industrial facilities running decades-old control architectures resist retrofitting digital smart sensors without guaranteed backward compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Acoustic Sensors Market |
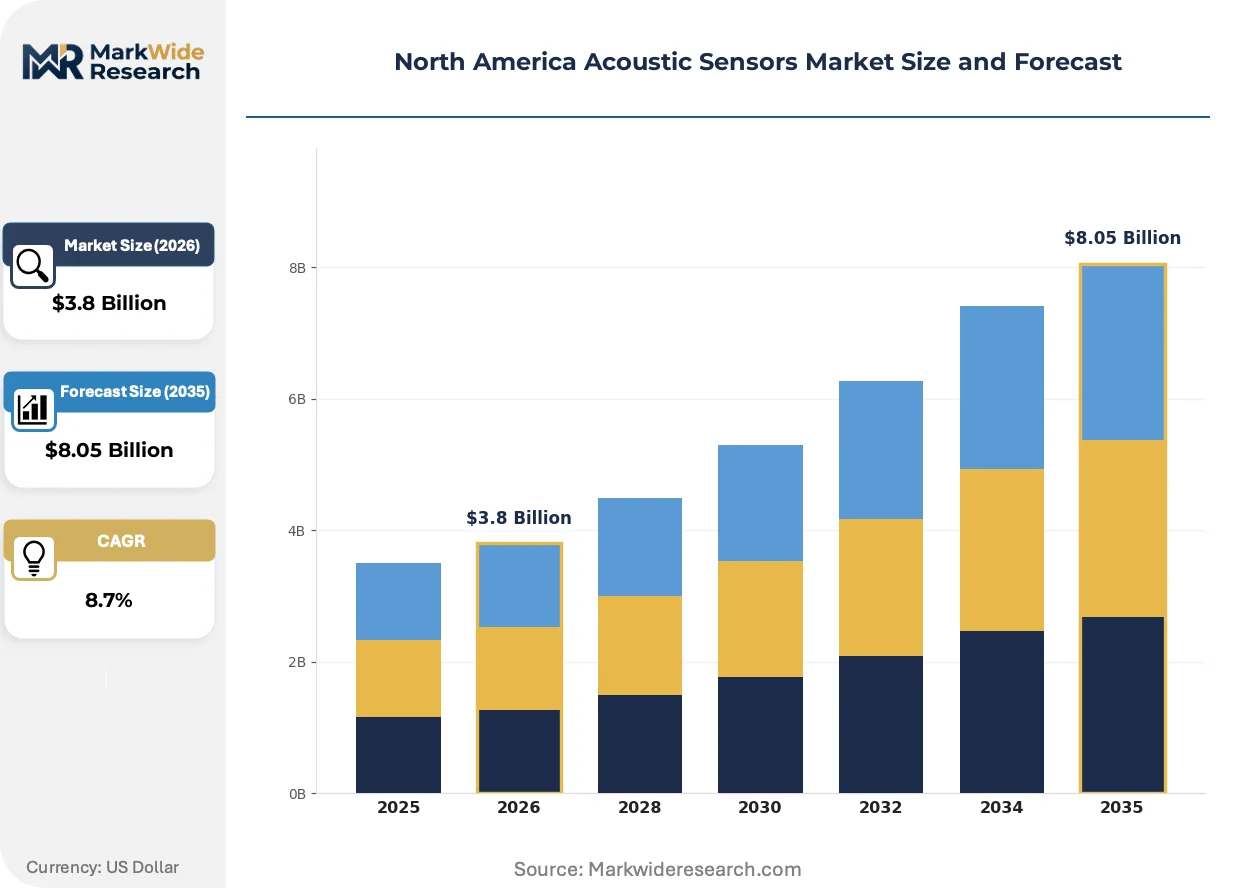
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microphones, Hydrophones, Piezoelectric Sensors, Ultrasonic Sensors Technology: Analog, Digital, Wireless, Smart Sensors End User: Consumer Electronics, Automotive, Healthcare, Industrial Application: Noise Monitoring, Underwater Exploration, Voice Recognition, Structural Health Monitoring |
| Companies Covered | Honeywell International Inc., Siemens AG, Murata Manufacturing Co., Ltd., Panasonic Corporation, KYOCERA Corporation, CTS Corporation, Knowles Corporation, Sensata Technologies Holding PLC, Teledyne Technologies Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Acoustic Sensors Market Shifts & Advancements
Digital signal processing is migrating onto sensor die, compressing latency and enabling real-time acoustic event classification without host processor dependency.
MEMS-based ultrasonic transducers are virtualizing traditional piezoelectric ceramic assemblies in automotive park-assist and industrial tank level sensing. Tier-one suppliers are qualifying silicon-micromachined alternatives for 2027 model year platforms. This transition is virtualizing the supply chain, collapsing the distinction between semiconductor and component vendor tiers.
NHTSA rulemaking on minimum sound requirements for quiet vehicles is mandating external speaker systems with precise frequency modulation. The regulation forces acoustic engineers to optimize for pedestrian detectability rather than driver preference. Automotive audio suppliers are responding by integrating directional sound projection into bumper-mounted modules.
Canadian healthcare procurement authorities are unbundling acoustic diagnostic device purchases from bundled imaging system contracts. Hospital buyers now specify standalone phonocardiography and lung auscultation tools for point-of-care deployment. This pattern is most visible in Ontario and British Columbia, where provincial health authorities pilot decentralized cardiac screening programs.
North America Acoustic Sensors Market Segmentation
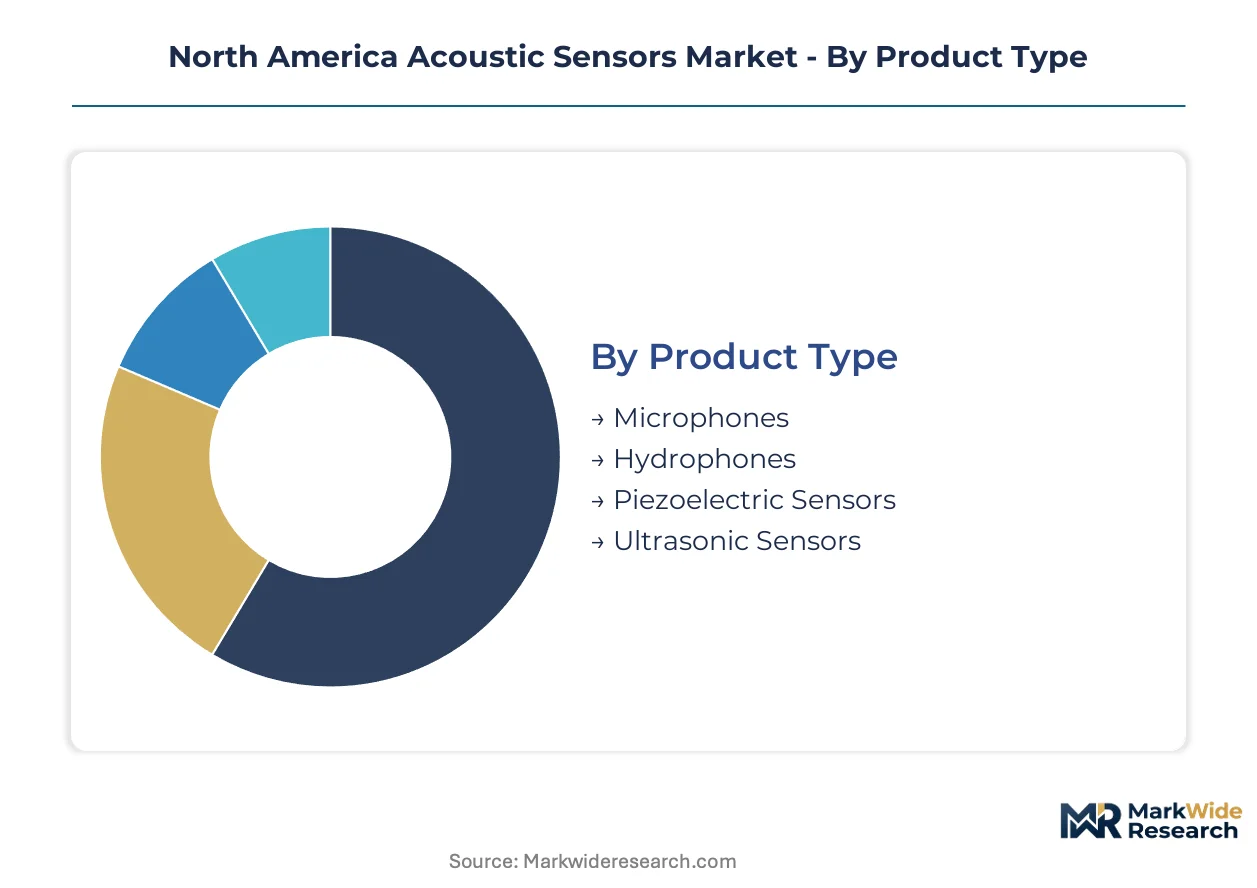
Acoustic sensor segmentation in North America reflects divergent maturity curves across transducer physics, signal processing architectures, and regulatory exposure. Understanding these divides clarifies where fabrication investments concentrate versus where emerging specifications are rewriting procurement criteria.
Product Type:
Mature electromechanical designs coexist with emerging MEMS-based alternatives, creating tiered sourcing strategies across defense and consumer supply chains.
- Microphones:Capacitive and MEMS diaphragm structures dominate voice capture for smart speakers, mobile devices, and automotive cabin interfaces. Demand clusters in California consumer electronics corridors and Michigan automotive audio programs where NHTSA cabin noise standards shape specification thresholds.
- Ultrasonic Sensors:Piezoelectric ceramic and MEMS-micromachined variants generate high-frequency pulses for distance measurement and object detection. Automotive park-assist and industrial tank level sensing in the Great Lakes manufacturing belt pull silicon-based alternatives into qualification for 2027 platforms.
- Hydrophones:Piezoelectric transducer arrays optimized for underwater pressure wave detection serve naval surveillance and offshore energy exploration off the Atlantic and Pacific coasts.
- Piezoelectric Sensors:Crystalline and ceramic transducers convert mechanical strain into electrical signals for vibration monitoring in aerospace propulsion systems.
Microphones retain volume leadership; ultrasonic sensors hold the steepest expansion curve.
Technology:
Cost tiers separate legacy analog deployments from premium digital architectures with embedded processing capabilities.
- Smart Sensors:Edge-AI integration enables on-die acoustic event classification without host processor dependency. Healthcare diagnostic tools and predictive maintenance platforms in Texas and Ohio industrial corridors pull these architectures for real-time anomaly detection.
- Digital:Pulse-density modulation and I2S output formats compress latency for voice authentication and noise cancellation systems. Consumer electronics OEMs in Washington and California drive procurement for USB-C and wireless audio accessories.
- Wireless:Bluetooth Low Energy and proprietary RF protocols free sensor placement from wired infrastructure constraints. FCC Part 15 certification requirements constrain industrial IoT deployment timelines.
- Analog:Continuous voltage output persists in legacy industrial control systems where backward compatibility resists digital retrofit investments.
Digital architectures command the broadest installed base; smart sensors are climbing the fastest.
End User:
Application-specific qualification regimes create divergent margin structures across regulated and consumer-facing verticals.
- Automotive:FMVSS pedestrian alert mandates and cabin monitoring requirements pull ultrasonic and microphone arrays into every hybrid and electric platform. Detroit-area OEMs and Mexican assembly expansion in Querétaro sustain tier-two supplier demand.
- Healthcare:FDA device classification standards govern acoustic diagnostic tools for cardiovascular and pulmonary monitoring. Ontario and British Columbia provincial health authorities pilot decentralized phonocardiography deployment.
- Consumer Electronics:Voice interface integration in smart speakers, wearables, and hearables drives MEMS microphone volume. California and Washington design centers specify form factor and power constraints.
- Industrial:Predictive maintenance platforms embed acoustic diagnostics for bearing fault detection and pipeline leak identification. Ohio and Pennsylvania manufacturing clusters sustain piezoelectric array demand.
Automotive anchors revenue concentration; healthcare carries the steepest specification premium trajectory.
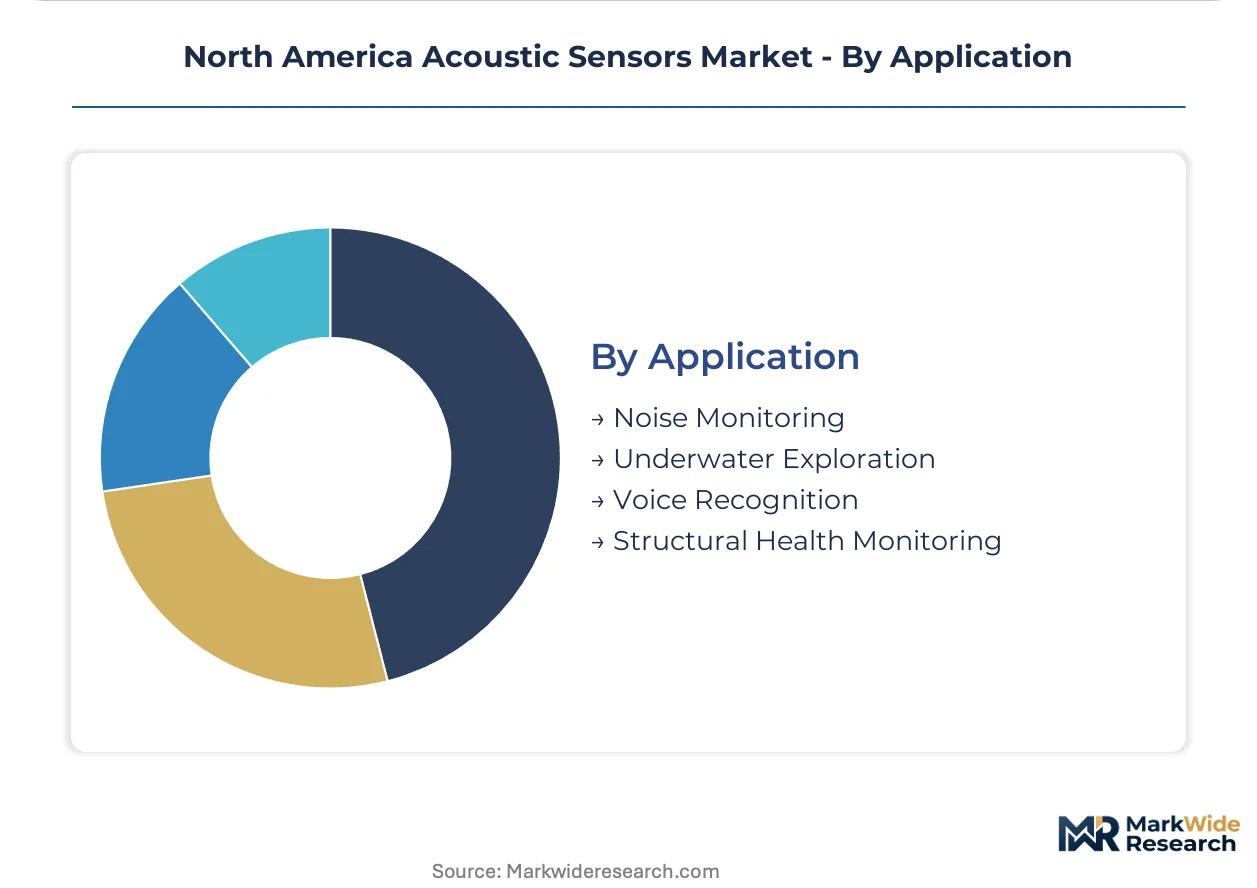
Application:
Geography-of-use shapes sensor packaging and environmental hardening requirements across maritime, civil infrastructure, and consumer contexts.
- Voice Recognition:Far-field microphone arrays with beamforming algorithms extract clean speech from noisy environments. Smart home and automotive cabin deployments in California and Michigan drive array integration complexity.
- Structural Health Monitoring:Piezoelectric transducer networks detect crack propagation and fatigue in bridges, aircraft fuselages, and wind turbine blades. FAA airworthiness directives and state DOT infrastructure programs shape qualification pathways.
- Noise Monitoring:Environmental compliance systems track industrial and transportation acoustic emissions against EPA enforcement thresholds. Port authorities and airport operators in California and New York sustain calibrated sensor deployment.
- Underwater Exploration:Pressure-resistant hydrophone arrays map seabed topography and detect subsea infrastructure anomalies. Naval research programs and Gulf of Mexico energy operators drive specification requirements.
Voice recognition holds the broadest consumer penetration; structural health monitoring is gaining specification momentum fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North America acoustic sensors market runs a structural trade surplus in high-reliability components, with U.S. and Canadian fabricators exporting precision piezoelectric arrays while importing commodity MEMS substrates from Asian foundries. Mexican assembly expansion is redrawing sourcing radii for tier-two suppliers.
United States
NHTSA pedestrian alert mandates and FDA breakthrough device pathways pull ultrasonic and diagnostic acoustic components into automotive and healthcare supply chains. FMVSS updates force acoustic component redesigns across Detroit-area OEM programs. The Great Lakes industrial corridor concentrates aerospace and automotive sensor demand around Cleveland and Detroit.
Canada
Provincial health authorities in Ontario and British Columbia unbundle acoustic diagnostic purchases from imaging system contracts, opening standalone phonocardiography procurement. Health Canada device classification standards govern cardiovascular monitoring tool approval. Toronto anchors defense and commercial aviation manufacturing clusters sustaining high-reliability piezoelectric array demand.
Mexico
OEM capacity additions in Querétaro and Guanajuato create localized demand for tier-two acoustic sensor suppliers serving automotive audio and park-assist programs. Mexican automotive safety regulations align with U.S. FMVSS frameworks, simplifying cross-border component qualification. The Bajío Region concentrates assembly operations pulling MEMS microphone and ultrasonic transducer sourcing southward.
North America Acoustic Sensors Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: defense-aerospace specialists with captive crystal growth, industrial automation integrators embedding acoustic diagnostics into predictive platforms, and consumer electronics MEMS suppliers competing on semiconductor fabrication scale. Strategic archetypes include vertically integrated material-science leaders, system-level automation vendors, and fabless design houses leveraging foundry partnerships. Competitive moves concentrate on backward integration into piezoelectric material supply and edge-AI capability acquisition.
Among North American-headquartered players, Honeywell International Inc. and Knowles Corporation exemplify divergent archetype positioning. Honeywell represents the defense-aerospace tier with in-house material capabilities, while Knowles occupies the consumer electronics MEMS vector. Siemens AG, despite its European base, competes aggressively across North American industrial automation deployments. Murata Manufacturing Co., Ltd. and KYOCERA Corporation anchor the Asian supplier presence through ceramic substrate and MEMS fabrication scale.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Siemens AG |
| Murata Manufacturing Co., Ltd. |
| Panasonic Corporation |
| KYOCERA Corporation |
| CTS Corporation |
| Knowles Corporation |
| Sensata Technologies Holding PLC |
| Teledyne Technologies Incorporated |
| Others |
Supply & Pricing Matrix
Lithium niobate crystal substrate supply concentrates in Russian and Chinese foundries, tethering North American bulk acoustic wave filter pricing to geopolitical volatility while downstream margin pools accrue to automotive OEMs with volume scale leverage.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across automotive and aerospace tiers. Price differentiation separates ASIL-certified automotive components from standard industrial grades, with ISO 26262 validation cycles adding 18-24 month cost premiums. Cost compression in MEMS microphone tiers intensifies because semiconductor fabrication scale advantages concentrate in Asian foundries. Consumer electronics procurement teams exhibit highest price sensitivity, while defense contractors absorb premium positioning for piezoelectric crystal reliability.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for ceramic substrate and MEMS die sourcing. Raw material dependencies center on lithium niobate crystals, aluminum nitride thin films, and silicon wafers from Taiwan, Japan, and South Korea. Single-source vulnerability persists in high-purity piezoelectric crystal growth capacity. Distribution runs through tier-one automotive suppliers and industrial automation integrators with captive qualification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around Detroit-area OEM platform engineering teams and Ontario provincial health procurement authorities, fragmenting tier-two supplier pricing leverage across automotive and healthcare verticals.
For Market Incumbents: Harden backward integration into piezoelectric material supply as optical sensing substitution threatens ultrasonic park-assist margins. Deepen captive lithium niobate crystal growth partnerships to offset Russian and Chinese input volatility. Fortify ASIL-D certification pipelines against 18-24 month validation bottlenecks that strain development budgets. For New Entrants and Emerging Players: Pursue Mexican automotive assembly expansion in Querétaro and Guanajuato as the most penetrable geography for tier-two acoustic component qualification. Target FDA breakthrough device pathway positioning for cardiovascular and pulmonary diagnostic tools. Anchor go-to-market through Ontario and British Columbia provincial health pilot programs for decentralized phonocardiography deployment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial automation specialists embedding acoustic diagnostics into predictive maintenance platforms. Five-to-ten year viability hinges on edge-AI convergence for on-sensor neural network inference. Watch NHTSA rulemaking velocity on pedestrian alert system specifications as inflection indicator for automotive audio supplier consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Piezoelectric Crystal Supply | Captive lithium niobate growth secures input stability against Russian and Chinese supply volatility. |
| Edge-AI Capability Acquisition | On-sensor inference enables real-time acoustic event classification for predictive maintenance platforms. |
| Mexican Manufacturing Footprint Expansion | Querétaro and Guanajuato assembly proximity reduces logistics costs for tier-two automotive suppliers. |
| FDA Breakthrough Device Pathway Investment | Expedited review accelerates cardiovascular and pulmonary diagnostic tool commercialization timelines. |
| MEMS Ultrasonic Transducer Qualification | Silicon-micromachined alternatives displace ceramic assemblies for 2027 automotive platform integration. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with acoustic sensor engineering directors, Tier 1 automotive procurement leads, FDA regulatory affairs specialists, and Ontario health authority contract managers; alongside secondary validation through NHTSA rulemaking dockets, FDA 510(k) clearance databases, FCC Part 15 certification records, and SEC filings from component suppliers. Bottom-up bill-of-materials modeling across microphone, ultrasonic, and piezoelectric product tiers triangulated against top-down OEM platform production forecasts.
Forecast inputs considered transducer physics segmentation, signal processing architecture tiers, and regulatory exposure clusters across the projection horizon. Vehicle class, propulsion architecture, and content-per-vehicle dimensions shaped automotive demand modeling. Healthcare segmentation incorporated diagnostic application type and provincial procurement unbundling patterns. CAGRs derived from installed base replacement cycles and emerging specification adoption curves.
Sensitivities concentrate around NHTSA pedestrian alert mandate implementation timing, lithium niobate supply disruption scenarios, and optical sensing substitution velocity in automotive distance measurement. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Fiber Bragg Grating Sensor Market
Sensors and Controls
Printed and Flexible Sensors Market
Sensors and Controls
Air Particle Monitor System Market
Sensors and Controls
Digital Pump Controller Market
Sensors and Controls
US Smart Air Purifier Market
Sensors and Controls
Latin America Lidar Market
Sensors and Controls
Vacuum Pressure Sensors Market
Sensors and Controls
High Purity Flow Meter Market
Sensors and Controls
3D Sensors Market
Sensors and Controls
Photonic Sensors and Detectors Market
Sensors and Controls
Magnetic Sensor Market
Sensors and Controls
Global Biosensors Market
Sensors and Controls
Digital Thermometer Market
Sensors and Controls
Middle East and Africa Temperature Sensors Market
Sensors and Controls
North America Fingerprint Sensor Market
Sensors and Controls
Europe Vibration Sensors Market