
 US Temperature Sensors Market | 2026-2036
US Temperature Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
US Temperature Sensors Market Analytics
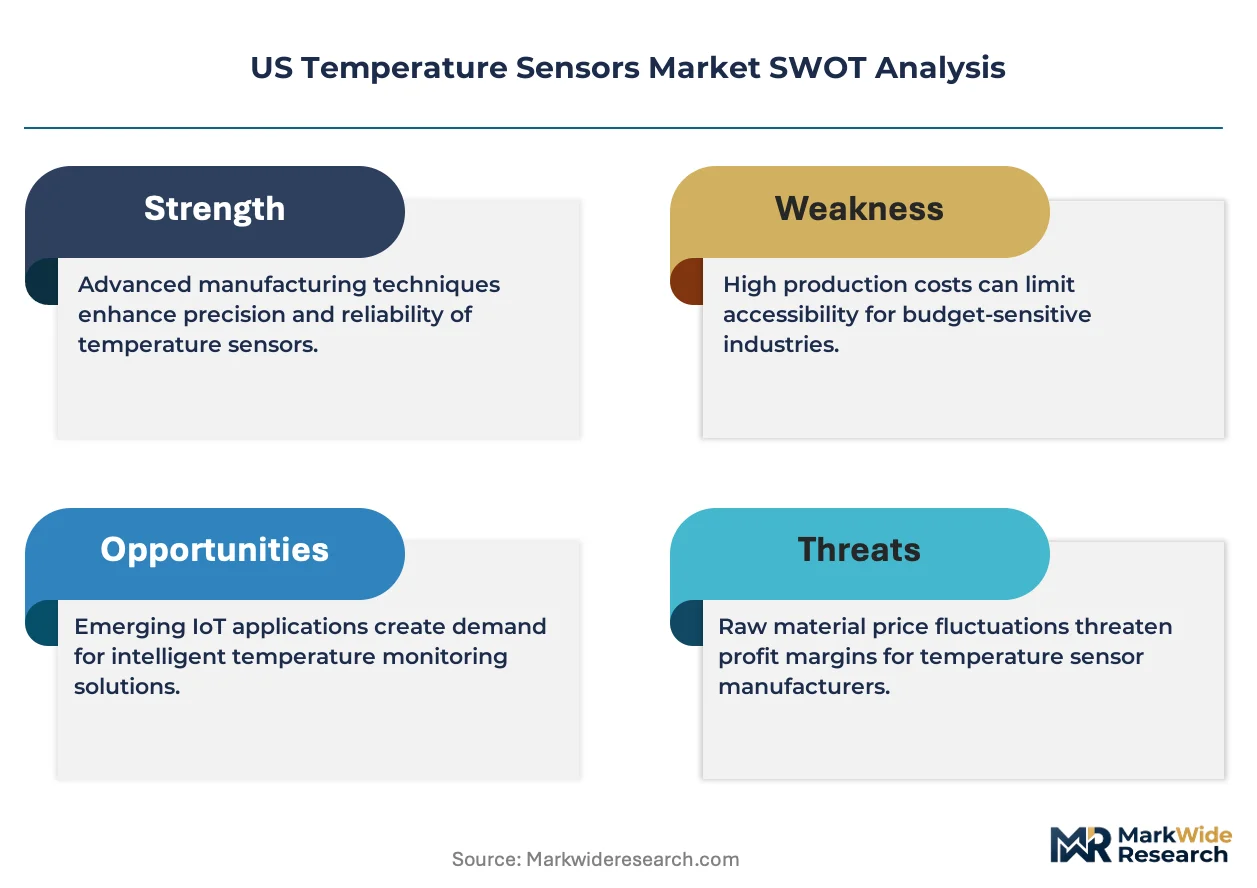
Industrial-grade accuracy tiers above ±0.1°C is rotating the US Temperature Sensors Market toward higher-specification procurement contracts. Texas Instruments leverages its Dallas-based fabrication network to sustain domestic supply continuity for precision RTD signal chains. Honeywell International Inc. anchors aerospace and defense temperature monitoring through its legacy thermocouple platforms. Emerson Electric Co. competes across process control installations with distributed sensor architectures that reduce wiring complexity.
A temperature sensor converts thermal energy into electrical signals through resistive, thermoelectric, or radiant detection mechanisms, typically operating across ranges from -200°C to 1700°C depending on junction materials or semiconductor composition. Its primary purpose spans process safety, equipment protection, and quality assurance in continuous manufacturing environments. Thermocouples dominate heavy industrial deployments where extreme temperatures and mechanical durability outweigh precision requirements, while infrared sensors capture the fastest expansion in non-contact food safety and medical screening applications. Digital technology segments concentrate margin pools where embedded calibration and bus connectivity reduce lifetime service costs.
FDA device regulations govern clinical-grade sensor accuracy and biocompatibility for patient-contact medical devices, while NHTSA and EPA standards mandate thermal monitoring in electric vehicle battery packs and catalytic systems. OSHA process safety management rules further compel petrochemical and refining operators to maintain redundant temperature monitoring with documented calibration trails. Stakeholders must monitor how NIST traceability requirements and emerging cybersecurity frameworks for wireless sensor networks reshape procurement specifications and vendor qualification cycles.
Market Dynamics
Automotive electrification is compressing calibration tolerances across battery thermal management systems, forcing sensor suppliers to requalify production lines for precision tiers previously reserved for aerospace and medical applications. This demand pull from Michigan and Ohio assembly clusters is reshaping vendor qualification cycles and procurement specifications simultaneously.
Growth Catalysts
- NHTSA Battery Safety Mandates:Federal thermal runaway detection requirements for electric vehicle packs are mandating redundant sensor arrays with ±0.1°C accuracy across all passenger and commercial platforms.
- Platinum-Rhodium Thermocouple Alloys:Advances in noble metal junction chemistry are extending upper temperature limits for heavy industrial catalytic monitoring, opening replacement cycles in refining and petrochemical installations.
- Ohio Powertrain Corridor:Concentrated battery assembly and electric drivetrain manufacturing in the Midwest is generating localized procurement volumes that justify dedicated sensor distribution centers.
Market Restraints
- Palladium and Platinum Price Volatility:Noble metal inputs for Type S and Type B thermocouples expose manufacturers to commodity swings that compress margin predictability on long-term industrial contracts.
- Single-Source Semiconductor Foundries:Precision RTD signal conditioning ASICs concentrate in domestic fabrication facilities with limited second-source qualification, creating supply vulnerability for automotive Tier 1 suppliers.
- IEEE 802.15.4 Interference Limitations:Wireless temperature monitoring in dense industrial environments faces packet collision and latency constraints that prevent full cable replacement in safety-critical loops.
Strategic Opportunities
- Texas Medical Device Corridor:FDA 21 CFR Part 820 quality system requirements for patient-contact temperature monitoring are creating certified supplier scarcity that rewards early compliance investments in Dallas-Austin corridor manufacturing.
- Infrared-Guided Thermography Fusion:Combining non-contact radiant sensors with machine vision algorithms is opening predictive maintenance contracts in data center thermal mapping and semiconductor fabrication equipment.
- OSHA Process Safety Management:Mandatory documented calibration trails for petrochemical and refining operators are converting aftermarket service relationships into multi-year sensor-as-a-service agreements.
Industry Challenges
- Metrology Technician Scarcity:NIST-traceable calibration expertise concentrates in aging workforce pools, extending lead times for precision-tier sensor qualification and recertification services.
- Legacy 4-20mA Integration Friction:Digital output sensors with embedded calibration require protocol converters and control system upgrades that prolong sales cycles in brownfield process installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Temperature Sensors Market |
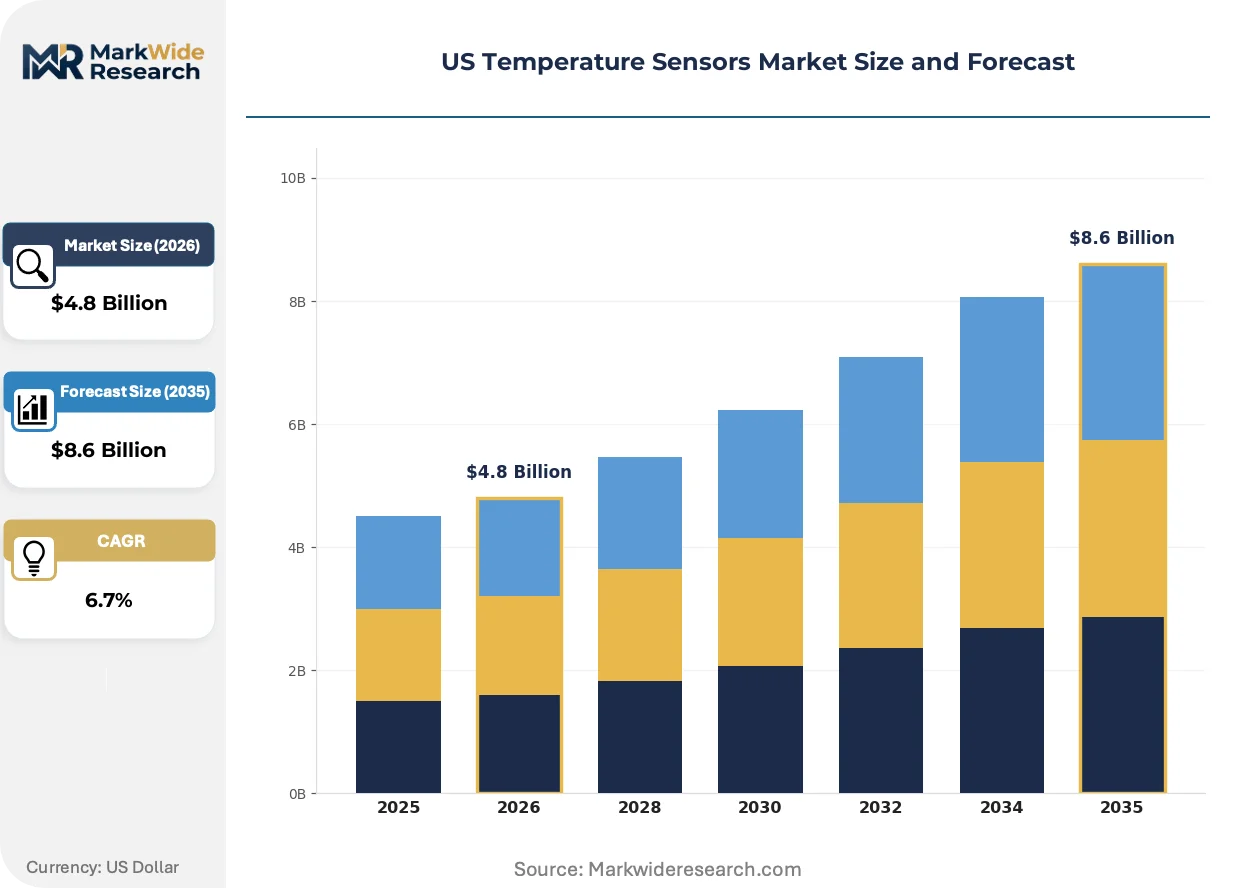
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermocouples, RTDs, Thermistors, Infrared Sensors Technology: Analog, Digital, Wireless, Hybrid End User: Manufacturing, Automotive, Healthcare, HVAC Application: Process Control, Environmental Monitoring, Food Safety, Medical Devices |
| Companies Covered | Texas Instruments, Honeywell International Inc., Analog Devices Inc., TE Connectivity, Emerson Electric Co., Fluke Process Instruments, Microchip Technology Inc., Amphenol Corporation, Siemens AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Temperature Sensors Market Evolving Landscape
Silicon carbide temperature sensing elements are penetrating applications previously dominated by noble metal thermocouples, while wireless mesh architectures and embedded machine learning are redefining how thermal data is processed at the edge. These converging threads are compressing the traditional separation between sensing hardware and analytics software.
Silicon carbide junction thermometry operates across -55°C to 1000°C ranges with faster response times than platinum RTDs in high-vibration environments. Automotive power electronics manufacturers in Michigan and Ohio are adopting SiC sensors for inverter and onboard charger thermal protection. The technology is bifurcating the market into high-frequency switching applications demanding sub-millisecond response versus steady-state process control tolerating slower platinum-based measurement.
EPA greenhouse gas monitoring rules for oil and gas production facilities are mandating continuous temperature measurement at compressor stations and processing equipment. This regulatory pressure is accelerating replacement of manual spot-check thermometry with permanently installed wireless sensor networks. Permian Basin operators in Texas and New Mexico are deploying solar-powered mesh nodes to satisfy quarterly reporting requirements without trenching for signal cable.
Automotive OEMs are consolidating sensor procurement under single-source platform contracts that bundle temperature, pressure, and current sensing into integrated thermal-electrical modules. Traditional discrete component distributors are losing specification influence to Tier 1 system integrators with direct OEM engineering relationships. This channel compression is most visible in Detroit Three electrification programs where battery management system suppliers now specify sensor subcomponents rather than purchasing departments.
US Temperature Sensors Market Segmentation
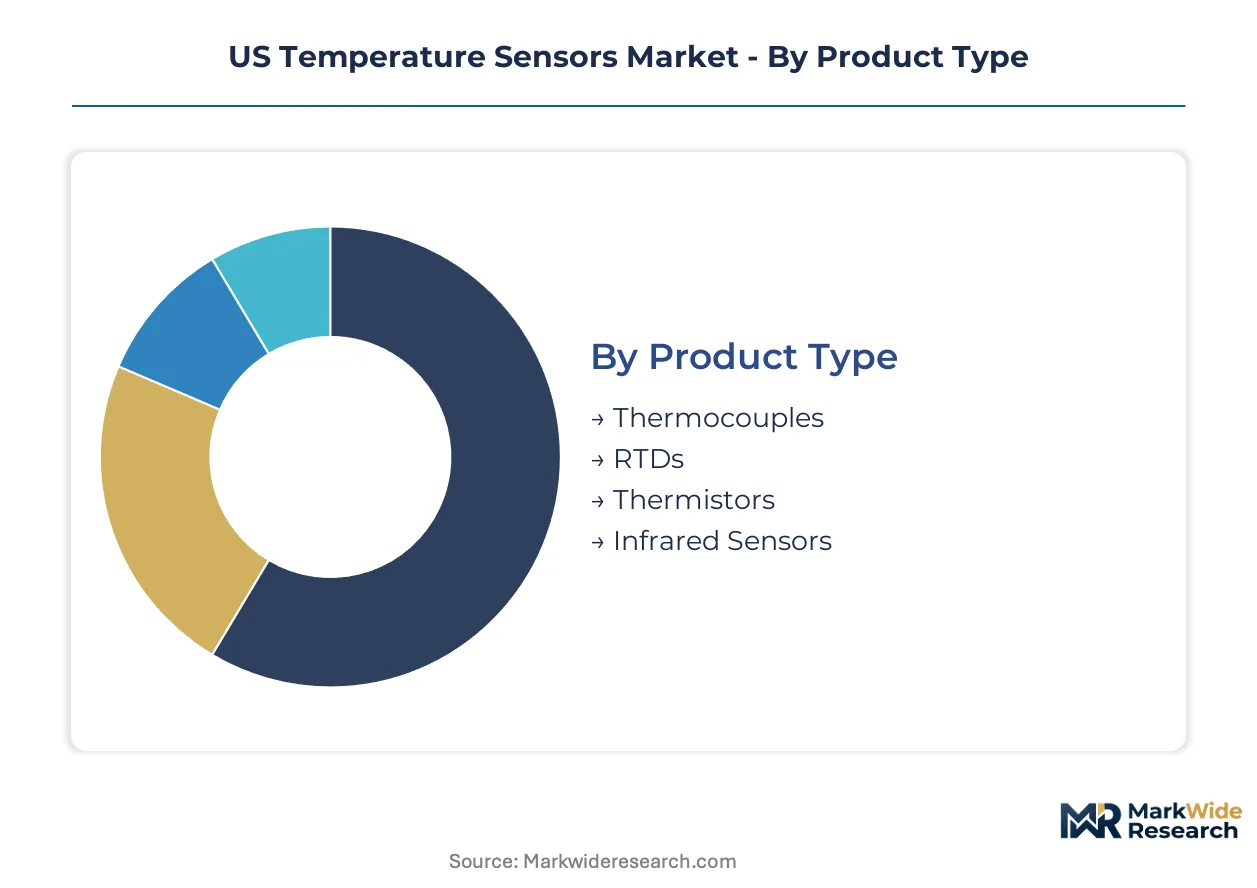
Temperature sensor procurement patterns diverge sharply across product architectures and end-use specifications. Segment boundaries reflect distinct calibration requirements, supply chain configurations, and regulatory compliance burdens that reshape vendor qualification cycles.
Product Type:
Thermocouple demand concentrates in domestic heavy industrial installations, while infrared and precision RTD segments serve export-oriented medical and aerospace OEMs with tighter NIST traceability requirements.
- Thermocouples:Noble metal junction devices utilizing platinum-rhodium or chromel-alumel alloys withstand continuous operation from -200°C to 1700°C. Michigan and Ohio automotive battery plants deploy Type K arrays for thermal runaway detection under NHTSA mandates.
- RTDs:Platinum resistance temperature detectors deliver ±0.1°C accuracy through thin-film or wire-wound sensing elements. Dallas-Austin medical device manufacturers specify RTD signal chains for FDA 21 CFR Part 820 patient-contact applications.
- Thermistors:Ceramic oxide semiconductors provide steep resistance-temperature curves for narrow-span precision.
- Infrared Sensors:Non-contact radiant detectors capture surface temperatures without thermal mass interference.
Thermocouples hold the largest share; momentum sits with infrared sensors.
Technology:
Cost tiers separate legacy analog installations from premium digital architectures with embedded calibration memory and bus connectivity.
- Analog:Voltage or current output devices require external signal conditioning and periodic recalibration. Brownfield process plants in Texas and Louisiana retain 4-20mA loops to avoid control system replacement costs.
- Digital:I2C, SPI, or proprietary protocol sensors integrate ADC and linearization algorithms on-chip. Automotive Tier 1 suppliers in Detroit specify digital outputs for battery management system consolidation.
- Wireless:IEEE 802.15.4 mesh nodes transmit temperature data without signal cabling. Permian Basin oil and gas operators deploy solar-powered wireless networks to satisfy EPA quarterly reporting without trenching.
- Hybrid:Dual-output architectures maintain analog fallback alongside digital primary channels for safety-critical redundancy.
Analog dominates installed base; digital is climbing the fastest.
End User:
Volume concentration varies by customer scale, with automotive OEMs driving specification consolidation and healthcare demanding certified supplier scarcity.
- Manufacturing:Continuous process industries require redundant temperature monitoring with documented calibration trails per OSHA Process Safety Management rules. Gulf Coast petrochemical complexes anchor thermocouple procurement volumes.
- Automotive:Electrification programs compress calibration tolerances for battery thermal management. Michigan and Ohio assembly clusters generate localized demand that justifies dedicated sensor distribution centers.
- Healthcare:FDA device regulations govern clinical-grade accuracy and biocompatibility.
- HVAC:Building automation systems prioritize cost-optimized thermistor networks for zone control.
Manufacturing holds the largest share; automotive shows steepest expansion trajectory.
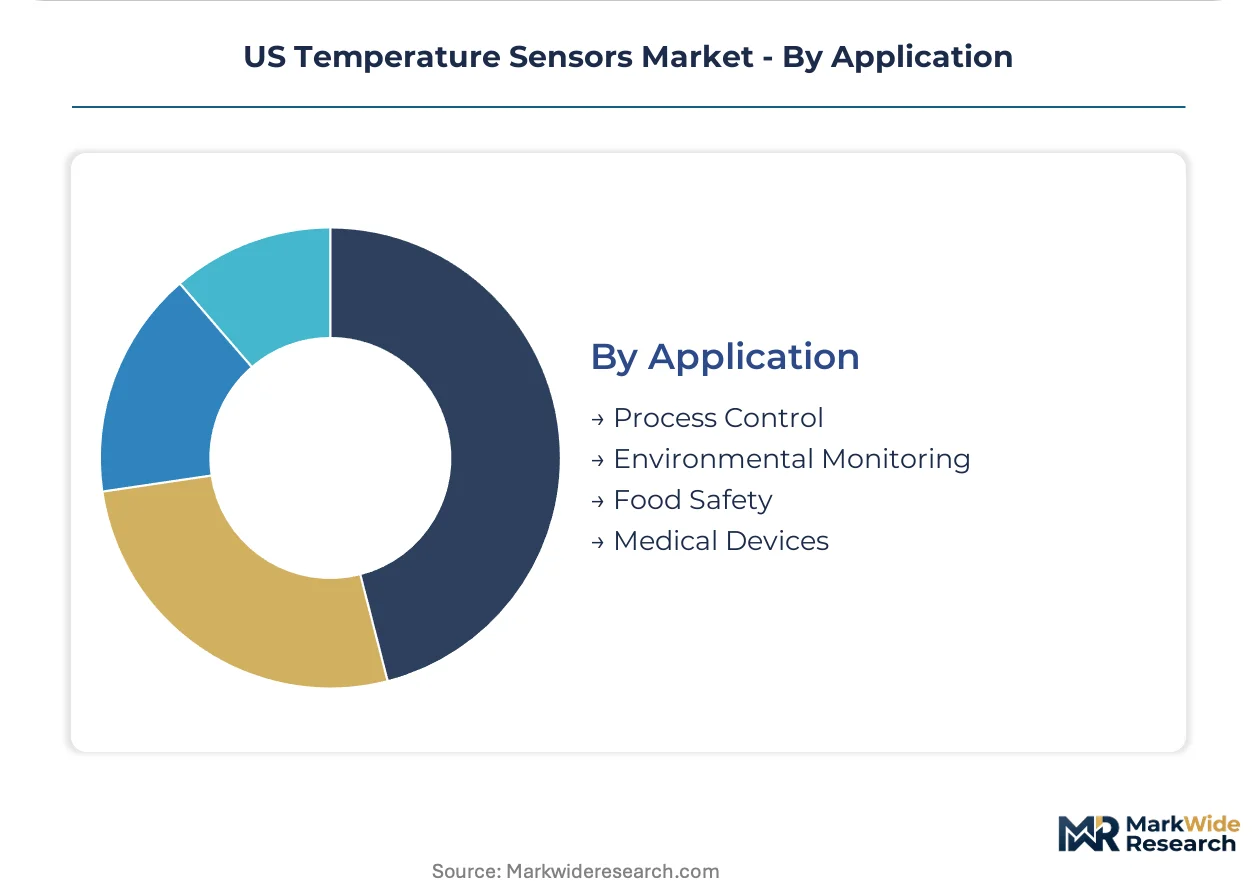
Application:
Application selection determines margin structure, with medical devices and food safety commanding premium pricing over environmental monitoring commoditization.
- Process Control:Closed-loop thermal regulation in refining, chemical, and power generation demands SIL-rated sensor redundancy. OSHA mandates drive replacement of manual spot-checks with permanently installed monitoring.
- Environmental Monitoring:Ambient and stack gas temperature tracking supports EPA emissions compliance. Oil and gas facilities face accelerating sensor refresh cycles under tightening greenhouse gas rules.
- Food Safety:HACCP-compliant temperature logging prevents pathogen proliferation across cold chain distribution.
- Medical Devices:Patient-contact applications require biocompatible housings and electromagnetic immunity certification.
Process control holds the largest share; medical devices are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US temperature sensor production flows primarily to domestic automotive and industrial buyers, with limited export volumes concentrated in medical and aerospace precision tiers serving European and Asian OEMs.
Michigan
Detroit Three electrification programs drive battery thermal management sensor procurement at volumes justifying dedicated distribution infrastructure. NHTSA battery safety mandates compress calibration tolerances to ±0.1°C across passenger and commercial vehicle platforms. The Ann Arbor-Detroit corridor anchors powertrain assembly clusters where Tier 1 suppliers now specify sensor subcomponents directly.
Ohio
Battery assembly and electric drivetrain manufacturing generate localized procurement volumes reshaping vendor qualification cycles. EPA emissions rules tighten thermal monitoring requirements for catalytic systems across vehicle platforms. The Columbus-Dayton manufacturing belt concentrates sensor demand from electrification programs competing for precision-tier supply.
Texas
Permian Basin oil and gas operators deploy solar-powered wireless sensor networks to satisfy EPA quarterly greenhouse gas reporting without trenching for signal cable. OSHA process safety management rules mandate redundant temperature monitoring with documented calibration trails at petrochemical complexes. The Dallas-Austin medical device corridor creates certified supplier scarcity under FDA 21 CFR Part 820 quality system requirements.
California
Semiconductor fabrication equipment manufacturers adopt infrared-guided thermography fusion for predictive maintenance contracts in thermal mapping applications. State-level emissions regulations accelerate replacement of manual spot-check thermometry with permanently installed monitoring at compressor stations. Silicon Valley data center operators drive demand for non-contact radiant sensors in high-density computing environments.
US Temperature Sensors Market Competitive Landscape
Listed leaders compete with private specialists across fabrication scale and vertical integration depth. The vendor base separates into three tiers: diversified electronics conglomerates with captive semiconductor foundries, industrial automation specialists with process control heritage, and precision sensor boutiques serving aerospace and medical niches. Dominant competitive moves include backward integration into noble metal alloy sourcing and strategic partnerships with automotive Tier 1 system integrators.
Among diversified electronics fabricators, Texas Instruments and Analog Devices occupy positions anchored by domestic signal conditioning ASIC production. Honeywell International Inc. exemplifies the industrial automation archetype with legacy thermocouple platforms serving aerospace and defense applications. Emerson Electric Co. represents the process control specialist tier competing through distributed sensor architectures that reduce wiring complexity in brownfield installations.
| Leading Market Players |
|---|
| Texas Instruments |
| Honeywell International Inc. |
| Analog Devices Inc. |
| TE Connectivity |
| Emerson Electric Co. |
| Fluke Process Instruments |
| Microchip Technology Inc. |
| Amphenol Corporation |
| Siemens AG |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts anchor sensor procurement for Michigan and Ohio automotive electrification programs, locking in platinum-rhodium alloy supply access while freezing unit pricing visibility across multi-year battery platform lifecycles. This contract structure insulates Tier 1 suppliers from noble metal spot volatility but transfers inventory risk upstream to specialty alloy fabricators.
Pricing Analysis
Next-generation silicon carbide junction sensors command 40-60% premiums over legacy platinum RTD equivalents, while analog 4-20mA devices face persistent cost compression from digital output alternatives. Three-tier pricing structure across precision aerospace, automotive-qualified, and industrial-grade tiers reflects NIST traceability certification levels rather than raw material costs alone. Pricing pressure stems from automotive OEM consolidation of sensor procurement under integrated thermal-electrical module contracts. Tier 1 battery management system suppliers exhibit lowest price sensitivity due to safety-critical liability exposure, while HVAC building automation buyers drive hardest unit-cost negotiations.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes elevates inbound logistics costs for thin-film platinum sensing elements fabricated in Japan and Germany. Domestic supply concentrates in Texas and Michigan for precision RTD signal conditioning ASICs, while noble metal thermocouple wire draws from South African platinum and Russian palladium feedstock. Raw material dependencies center on platinum-group metals, silicon carbide substrates, and specialized ceramic housings. Single-source vulnerability concentrates in domestic semiconductor foundries with limited second-source qualification for automotive-grade precision tiers. Distribution runs through Tier 1 system integrators with direct OEM engineering relationships, bypassing traditional component distributors in Detroit Three electrification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NIST-traceable calibration expertise concentrates in aging workforce pools, creating a capability bottleneck that extends lead times for precision-tier sensor qualification and threatens automotive electrification timelines.
For Market Incumbents: Fortify backward integration into noble metal alloy sourcing to insulate margins from palladium and platinum price volatility on long-term industrial contracts. Expand captive semiconductor fabrication capacity in Dallas-Austin corridor to reduce single-source foundry vulnerability for automotive Tier 1 customers. Prioritize certification investments under FDA 21 CFR Part 820 to defend position against emerging precision sensor boutiques in medical device applications. For New Entrants and Emerging Players: Differentiate on embedded machine learning at the edge, combining silicon carbide sensing elements with predictive analytics software for data center thermal mapping contracts. Target the Texas Medical Device Corridor where FDA quality system requirements create certified supplier scarcity that rewards early compliance investments. Pursue direct hospital system partnerships for patient-contact temperature monitoring rather than competing through traditional distribution channels. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision sensor boutiques with aerospace and medical niche dominance over diversified industrial conglomerates. Long-term viability hinges on automotive electrification sustaining demand pull from Michigan and Ohio assembly clusters through the next decade. Acquisition target archetype: mid-cap specialists with NIST-traceable calibration infrastructure and existing automotive Tier 2 relationships. Watch for IEEE 802.15.4 wireless standard revisions as inflection indicator for cable replacement acceleration in safety-critical loops.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Noble Metal Sourcing | Mitigates palladium price volatility exposure on Type S and Type B thermocouple contracts. |
| FDA 21 CFR Part 820 Certification Investment | Unlocks Dallas-Austin medical device corridor procurement previously blocked to uncertified suppliers. |
| SiC Junction Technology Transition | Captures automotive inverter thermal protection demand from Michigan and Ohio powertrain clusters. |
| Wireless Mesh Network Deployment | Satisfies EPA quarterly reporting requirements for Permian Basin operators without trenching costs. |
| Sensor-as-a-Service Agreement Conversion | Transforms OSHA-mandated calibration trail maintenance into recurring revenue streams at Gulf Coast petrochemical complexes. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with automotive Tier 1 procurement directors, NIST calibration laboratory technicians, FDA quality system auditors, petrochemical maintenance directors, and medical device biomedical engineers. Secondary validation drew from NHTSA Federal Motor Vehicle Safety Standards filings, EPA greenhouse gas monitoring rulemakings, OSHA Process Safety Management directives, SEC 10-K disclosures from listed sensor manufacturers, and IHS Markit vehicle production databases. Bottom-up sensor unit demand estimates triangulated against top-down market value reconstructions.
Across the analysis window, forecasts model five segmentation dimensions: product architecture, output technology, end-user industry, application criticality, and regional production cluster concentration. CAGRs derive from regression analysis of historical procurement volumes against regulatory mandate implementation timelines and automotive platform electrification schedules. Industry-specific inputs include battery thermal management sensor content per vehicle and FDA-certified supplier capacity constraints in precision medical tiers.
The analysis sits within stated boundaries; outcomes outside sustained NHTSA battery safety mandate enforcement or abrupt noble metal supply disruption would require recalibration. Forecasts reflect documented assumptions regarding automotive electrification penetration rates and wireless sensor network adoption in oil and gas facilities. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Industrial Wireless Sensor Market
Sensors and Controls
Gyro Sensors Market
Sensors and Controls
Smart Pressure Gauge Market
Sensors and Controls
Piezoelectric Sensor Market
Sensors and Controls
Middle East and Africa Temperature Sensors Market
Sensors and Controls
US Smart Air Purifier Market
Sensors and Controls
Acoustic Sensors Market
Sensors and Controls
Wearable Temperature Sensors Market
Sensors and Controls
Global Hall Effect Current Sensor Market
Sensors and Controls
Global Digital Electronic Thermometers Market
Sensors and Controls
Europe Proximity Sensors Market
Sensors and Controls
Current Transducer Market
Sensors and Controls
North America Temperature Sensor Market
Sensors and Controls
Yaw Rate Sensors Market
Sensors and Controls
Differential Pressure Sensor Market
Sensors and Controls
Inertial Measurement Unit (IMU) Market