
 Americas Medium and Large Caliber Ammunition Market | 2026-2036
Americas Medium and Large Caliber Ammunition Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Medium and Large Caliber Ammunition Market Outlook
Platform licensing is reshaping competitive economics in the Americas Medium and Large Caliber Ammunition Market, as defense contractors seek recurring revenue beyond one-time hardware sales. General Dynamics Corporation leverages its vertical integration across propellant chemistry and precision forging to sustain margin capture from raw material through finished shell. BAE Systems PLC anchors transatlantic supply relationships that position its U.S. operations for NATO-interoperable artillery programs. CBC Global Ammunition competes on scale, operating Latin America's largest small-to-medium caliber foundry while extending into naval shells for regional navies.
Medium and large caliber ammunition encompasses projectiles ranging from 20mm to 155mm and above, typically incorporating steel or tungsten cores with brass or steel cartridge cases, produced through multi-stage forging, heat treatment, and precision machining for direct and indirect fire weapons systems. Its primary purpose is to deliver kinetic or explosive effects against hardened targets, armored vehicles, fortified positions, and area threats across land and maritime domains. Artillery shells and tank ammunition concentrate the highest value per unit within product type segments, reflecting the metallurgical complexity and propellant precision required for tube-launched systems. Military use cases dominate volume absorption, though training exercises represent a structurally growing segment as forces cycle through stockpiles to maintain readiness under NATO and bilateral readiness protocols. Armed forces remain the anchor end user, yet private security firms and defense contractors are carving out niche procurement channels for specialized threat environments.
The U.S. State Department's Directorate of Defense Trade Controls and the International Traffic in Arms Regulations govern cross-border transfer of medium and large caliber ammunition, creating compliance barriers that favor incumbent suppliers with established licensing infrastructure. Brazil's Comissão de Controle de Exportação and Mexico's Secretaría de Economía administer parallel national controls that shape regional trade corridors and local content requirements. Canada's Export and Import Permits Act adds a third regulatory layer for North American producers seeking integrated supply chains. Stakeholders must monitor how evolving U.S. foreign military financing priorities and emerging Latin American defense industrial base policies recalibrate procurement access across the hemisphere.
Market Dynamics
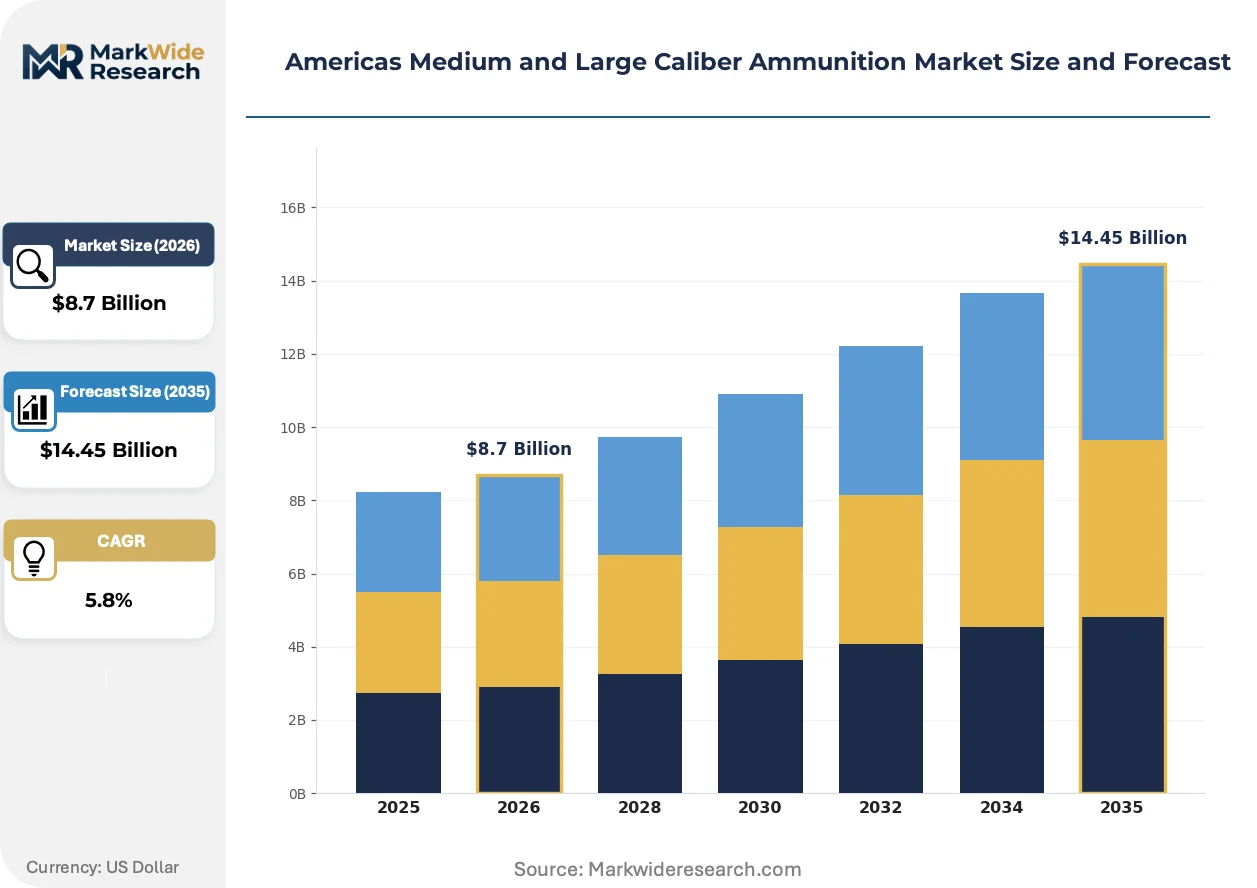
Platform licensing economics are restructuring competitive positioning across the Americas Medium and Large Caliber Ammunition Market, as contractors prioritize recurring revenue streams over transactional hardware sales. This shift concentrates margin capture in propellant chemistry and precision forging capabilities, favoring vertically integrated producers with captive supply chains.
Growth Catalysts
- Latin American Modernization Programs:Brazilian, Colombian, and Chilean armed forces are accelerating artillery shell and tank ammunition procurement under bilateral readiness protocols with U.S. Southern Command.
- NATO Interoperability Mandates:Standardization requirements for 155mm artillery and 120mm tank rounds are harmonizing specifications across U.S., Canadian, and allied Latin American inventories.
- Next Generation Squad Weapon Adoption:The U.S. Army's 6.8mm caliber transition is generating spillover demand for medium-caliber production line retooling across regional suppliers.
Market Restraints
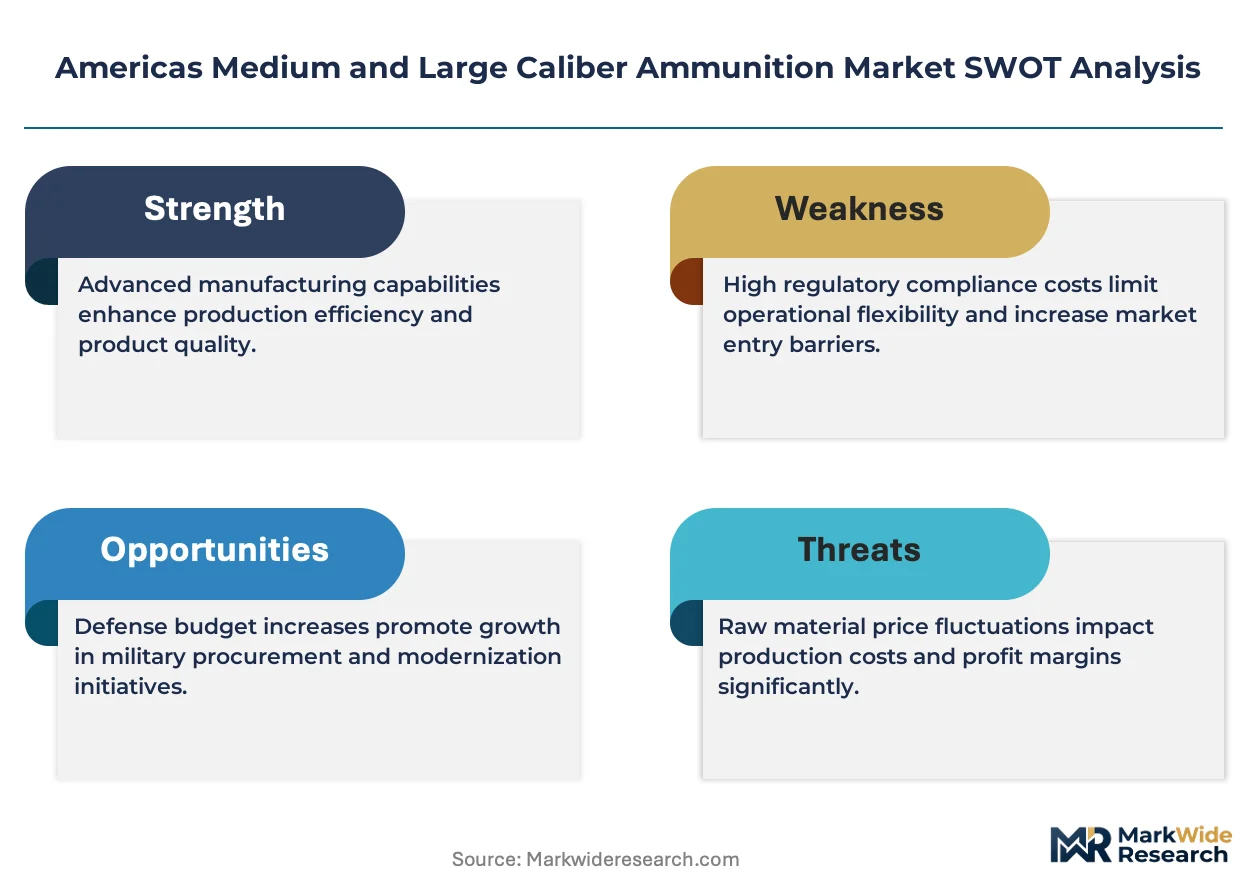
- Tungsten Supply Concentration:China dominates raw tungsten processing for armor-piercing penetrators, exposing Western Hemisphere producers to input cost volatility and export restriction risk.
- ITAR Licensing Friction:The U.S. State Department's Directorate of Defense Trade Controls creates multi-month approval timelines that constrain cross-border ammunition transfers to Latin American customers.
- Propellant Chemistry Limitations:Nitrocellulose supply bottlenecks and aging U.S. Army Radford Arsenal capacity restrict surge production capability for precision-guided artillery.
Strategic Opportunities
- Underpenetrated Andean Markets:Peru and Ecuador maintain minimal domestic ammunition production, creating import-dependent demand for NATO-standard artillery and naval gun ammunition.
- Dual-Use Naval Shell Production:Regional navies in Brazil, Chile, and Mexico are expanding frigate and corvette fleets, opening procurement channels for 76mm and 127mm naval gun rounds.
- Canadian Arctic Security Investment:Ottawa's Northern Defence Strategy is generating demand for cold-weather stabilized propellants and specialized artillery systems for polar operations.
Industry Challenges
- Skilled Pyrotechnician Shortage:The U.S. and Brazil face acute deficits in propellant formulation chemists and precision forging engineers with security clearance eligibility.
- Legacy System Integration Complexity:New precision-guided munitions must maintain backward compatibility with Vietnam-era M109 howitzer platforms still operational across Latin American arsenals.
- Multi-Jurisdiction Certification Timelines:Simultaneous compliance with U.S. ITAR, Brazil's Comissão de Controle de Exportação, and Canada's Export and Import Permits Act extends product qualification cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Medium and Large Caliber Ammunition Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artillery Shells, Mortars, Tank Ammunition, Naval Shells Use Case: Military, National Defense, Law Enforcement, Training Exercises End User: Armed Forces, Private Security Firms, Government Agencies, Defense Contractors Packaging Type: Bulk Packaging, Boxed Packages, Tactical Containers, Single Units |
| Companies Covered | General Dynamics Corporation, Northrop Grumman Corporation, BAE Systems PLC, CBC Global Ammunition, IMBEL, FAMAE, American Ordnance LLC, EMGEPRON, CSG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Medium and Large Caliber Ammunition Market Strategic Shifts
Precision guidance electronics and insensitive munition formulations are redefining performance benchmarks across artillery and tank ammunition categories. These advances compress the traditional trade-off between lethality and logistics safety while enabling engagement of moving targets at extended ranges.
Insensitive munition technology is migrating from specialized naval applications to mainstream army artillery programs. The U.S. Army's Picatinny Arsenal has accelerated IM-compliant 155mm shell qualification for brigade combat teams. This migration from conventional high-explosive fills is forcing propellant suppliers to reformulate nitramine compositions without sacrificing muzzle velocity.
Canada's Export and Import Permits Act amendments are tightening end-use monitoring for ammunition transfers to non-NATO Latin American recipients. Ottawa now requires documented chain-of-custody protocols for all 12.7mm and above transfers. Canadian producers serving Brazilian and Mexican defense ministries must deploy enhanced tracking systems or face permit revocation.
Life-cycle service contracts are displacing spot procurement for artillery ammunition across major Latin American militaries. Brazilian Army logistics commands now negotiate five-year availability agreements with embedded stockpile rotation and technical refresh provisions. This pattern concentrates purchasing authority in national-level procurement directorates while marginalizing unit-level discretionary buying.
Americas Medium and Large Caliber Ammunition Market Segmentation
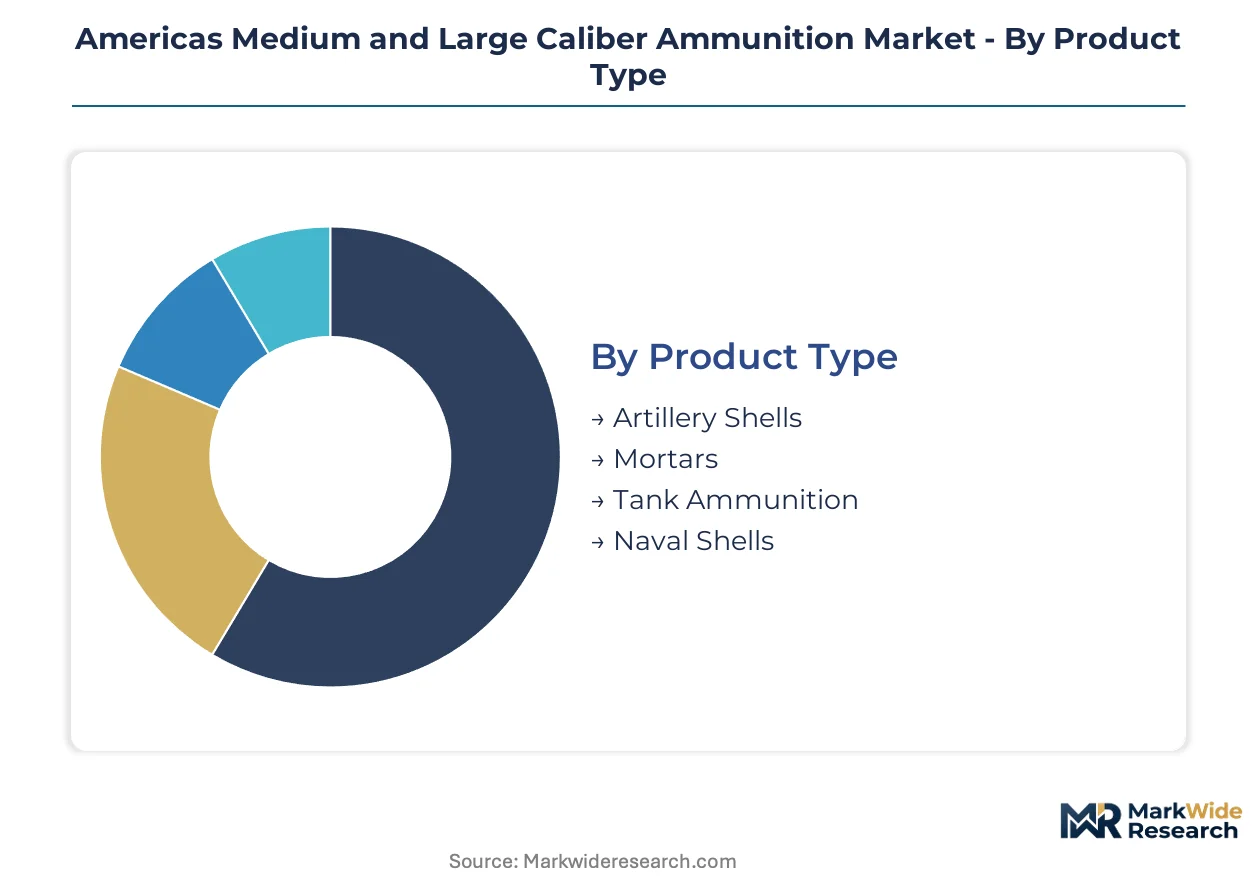
Segmentation in the Americas Medium and Large Caliber Ammunition Market reveals how procurement authority, operational tempo, and logistics infrastructure shape demand patterns across distinct product categories and customer channels.
Product Type:
Cost tier differentiation separates precision-forged artillery systems from standardized mortar and tank rounds, with metallurgical complexity and propellant sophistication determining unit economics.
- Artillery Shells:These 105mm to 155mm projectiles incorporate steel bodies with variable explosive fills and base-bleed or rocket-assisted propulsion for extended range. Brazilian Army procurement under bilateral readiness protocols with U.S. Southern Command concentrates demand for NATO-interoperable 155mm rounds.
- Tank Ammunition:Armor-piercing fin-stabilized discarding sabot rounds require tungsten or depleted uranium penetrators with multi-piece cartridge cases. Chilean and Colombian modernization programs are accelerating 120mm smoothbore procurement as legacy 105mm rifled systems retire.
- Mortars:These high-angle, low-velocity systems employ simplified forging with cast iron or steel bodies for 60mm through 120mm calibers.
- Naval Shells:76mm and 127mm naval gun ammunition for Brazilian, Chilean, and Mexican frigate fleets demands specialized anti-corrosion coatings and seawater-resistant propellants.
Artillery shells command the established base. The steepest expansion runs through naval shells as regional navies modernize surface combatant fleets.
Use Case:
Application intensity varies sharply between live-fire combat consumption and training cycle throughput, with readiness protocols mandating predictable replacement rates.
- Military:Combat employment of artillery and tank ammunition in direct and indirect fire missions requires full-spectrum lethality including anti-armor, anti-personnel, and obscurant capabilities. Colombian counter-insurgency operations sustain elevated consumption rates for 155mm and 120mm systems.
- National Defense:Strategic stockpiling for territorial defense scenarios emphasizes shelf-stable propellants and climate-resistant packaging for extended storage in Brazilian and Mexican arsenals.
- Training Exercises:NATO and bilateral readiness protocols mandate live-fire qualification cycles that absorb substantial mortar and artillery volumes.
- Law Enforcement:Specialized breaching and counter-sniper applications employ reduced-range 12.7mm and 40mm ammunition with limited penetration characteristics.
Military use cases anchor volume absorption. Training exercises are gaining share fastest as forces cycle through stockpiles to maintain certification.
End User:
Customer type determines procurement channel structure, with national-level tenders dominating while private channels emerge for specialized threat environments.
- Armed Forces:National military services procure through defense ministry tender processes with multi-year framework agreements. Brazilian Army logistics commands negotiate five-year availability contracts with embedded stockpile rotation provisions.
- Government Agencies:Border security and coast guard organizations acquire specialized ammunition for maritime interdiction and territorial enforcement.
- Private Security Firms:High-risk extraction and asset protection operations in Latin America procure limited quantities of 7.62mm and 12.7mm ammunition through licensed dealers.
- Defense Contractors:Systems integrators and training providers source ammunition for weapons platform demonstration and foreign military sales support.
Armed forces retain purchasing dominance. Defense contractors are expanding fastest as platform licensing economics shift procurement authority to systems integrators.
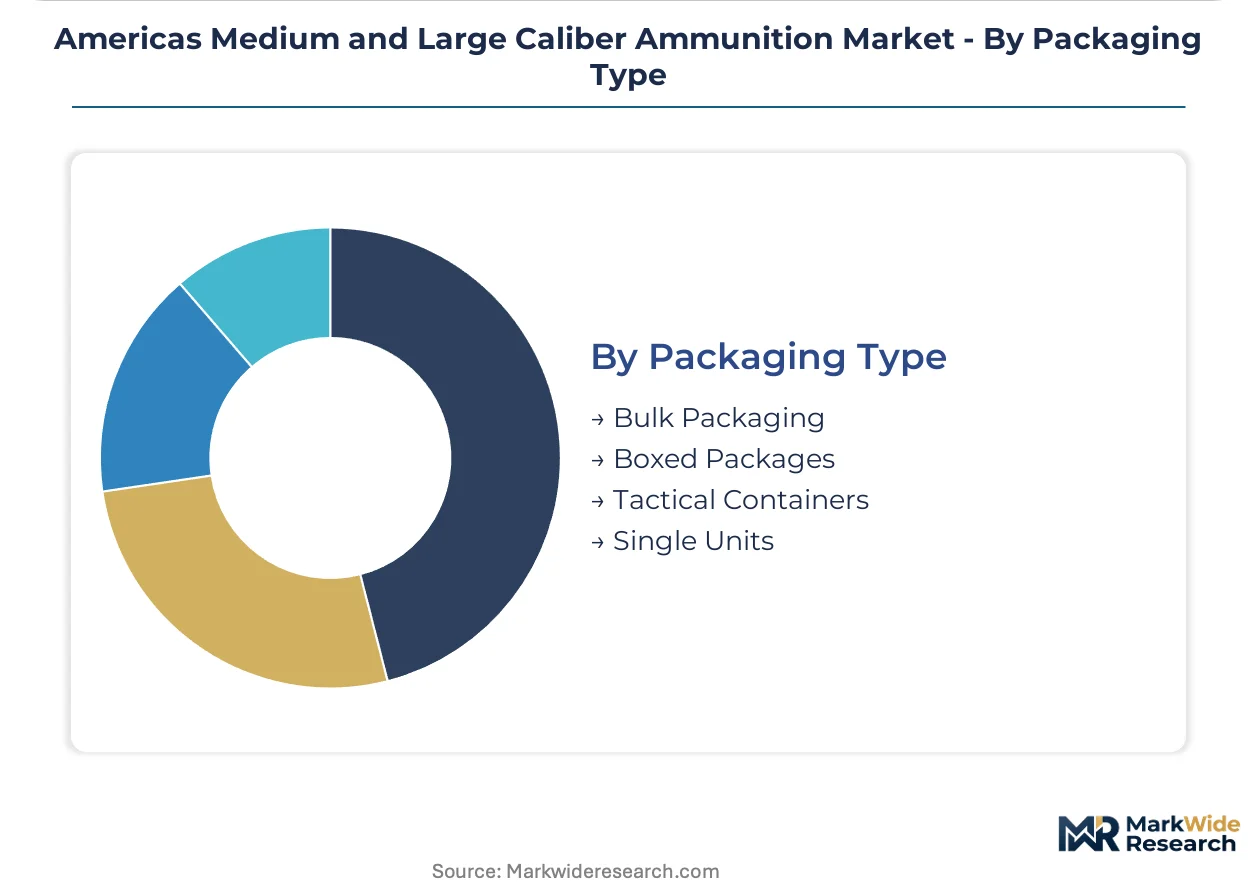
Packaging Type:
Volume and handling requirements dictate packaging configuration, with climate exposure and mobility needs driving specification divergence.
- Bulk Packaging:Palletized wooden or metal containers holding hundreds of rounds optimize depot-level storage and strategic transport. Canadian Arctic stockpiles require cold-weather stabilized propellants in hermetically sealed bulk configurations.
- Tactical Containers:Modular ammunition containers compatible with military vehicle loading systems enable forward deployment.
- Boxed Packages:Corrugated or wooden boxes with individual round separation suit unit-level distribution and training allocation.
- Single Units:Individual hermetic packaging preserves precision-guided munition electronics and insensitive munition formulations during extended storage.
Bulk packaging dominates strategic stockpiling. Tactical containers are expanding most quickly as expeditionary readiness requirements reshape logistics planning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the Americas, with the United States prioritizing precision-guided artillery modernization while Latin American forces emphasize NATO-interoperable stockpiles for territorial defense scenarios. This mix differential shapes procurement timelines, regulatory exposure, and supplier qualification requirements across hemispheric markets.
United States
The U.S. Army's Next Generation Squad Weapon program and Picatinny Arsenal precision munitions initiatives drive demand for 6.8mm and 155mm systems. ITAR licensing through the State Department's Directorate of Defense Trade Controls constrains export velocity to Latin American allies. Radford Arsenal in Virginia and Lake City Army Ammunition Plant in Missouri anchor domestic propellant and small-to-medium caliber production capacity.
Brazil
Brazilian Army artillery modernization under bilateral readiness protocols with U.S. Southern Command accelerates 155mm shell procurement. Comissão de Controle de Exportação administers national export controls that shape regional trade corridors. FAMAE in São Paulo and IMBEL in Minas Gerais anchor Latin America's largest integrated ammunition production cluster for national defense and export markets.
Canada
Ottawa's Northern Defence Strategy generates specialized demand for cold-weather stabilized propellants and Arctic-capable artillery systems. Export and Import Permits Act amendments tighten end-use monitoring for ammunition transfers to non-NATO Latin American recipients. Quebec and Ontario host the principal defense industrial base concentrations serving domestic and allied procurement.
Chile
Chilean Army tank fleet modernization drives 120mm smoothbore ammunition procurement as legacy 105mm rifled systems retire. National defense ministry tenders emphasize NATO interoperability for Andean mountain warfare applications. Santiago anchors procurement decision-making while Antofagasta and Valparaíso support naval ammunition logistics for Pacific fleet operations.
Colombia
Counter-insurgency operations sustain elevated consumption rates for 155mm artillery and 120mm tank systems under continued U.S. foreign military financing. National defense ministry framework agreements concentrate purchasing authority in Bogotá-based procurement directorates. The country's Andean geography drives demand for high-angle mortar systems and precision mountain artillery.
Americas Medium and Large Caliber Ammunition Market Competitive Environment
Capability concentration sits with vertically integrated defense primes possessing captive propellant chemistry and precision forging assets; scale advantage sits with regional producers operating Latin America's largest foundry complexes. The market structures around three tiers: transatlantic systems integrators with NATO certification infrastructure, hemisphere-scale ammunition specialists with multi-caliber flexibility, and national champions serving captive domestic demand. Dominant competitive moves include platform licensing economics prioritizing recurring service revenue and strategic partnerships securing tungsten supply chains against Chinese processing concentration.
Within the transatlantic systems integrator tier, BAE Systems PLC and General Dynamics Corporation exemplify archetypes combining NATO-interoperable certification with vertical integration across propellant and metallurgical operations. CBC Global Ammunition occupies a position representing scale-driven regional production capacity. These three anchors illustrate how competitive positioning stratifies between certification-heavy primes and volume-focused specialists.
| Leading Market Players |
|---|
| General Dynamics Corporation |
| Northrop Grumman Corporation |
| BAE Systems PLC |
| CBC Global Ammunition |
| IMBEL |
| FAMAE |
| American Ordnance LLC |
| EMGEPRON |
| CSG |
| Others |
Value Chain & Pricing Dynamics
Chinese tungsten processing concentration for armor-piercing penetrators captures upstream margin pools, while downstream pricing power concentrates with vertically integrated primes possessing captive propellant chemistry and precision forging assets across the U.S. and Brazil.
Pricing Analysis
Long-term availability agreements with embedded stockpile rotation provisions dominate procurement between Latin American defense ministries and ammunition suppliers. Price differentiation hinges on NATO-interoperable certification grade and volume scale in multi-year framework contracts. Cost compression in standardized mortar and tank rounds intensifies as Brazilian and Mexican producers expand foundry capacity. National procurement directorates exhibit highest price sensitivity, while private security firms and defense contractors absorb premium pricing for specialized threat-environment ammunition.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Brazilian and U.S. primes reduce working capital pressure on nitrocellulose and tungsten suppliers. Raw material sourcing draws from Chinese tungsten processors, U.S. nitrocellulose producers at Radford Arsenal, and Canadian propellant chemistry specialists. Single-source vulnerability in Chinese tungsten concentrate exposes Western Hemisphere producers to export restriction risk. Distribution runs through national defense ministry logistics commands with depot-level bulk storage and forward tactical container deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment, where ITAR licensing infrastructure and multi-jurisdiction certification timelines create structural barriers that favor incumbent suppliers with established compliance architectures.
For Market Incumbents: Build regulatory certification moats by accelerating ITAR-compliant production line qualification for precision-guided artillery and insensitive munition formulations. Expand backward integration into nitrocellulose propellant chemistry to offset Radford Arsenal capacity constraints. Deepen captive tungsten supply relationships through strategic partnerships with Australian and Canadian mining interests to mitigate Chinese processing concentration risk. For New Entrants and Emerging Players: Andean markets in Peru and Ecuador represent the most penetrable entry point, given minimal domestic production capacity and import-dependent demand for NATO-standard artillery. Naval shell production for Brazilian, Chilean, and Mexican frigate modernization programs offers a second white-space target. Pursue platform licensing economics with regional systems integrators rather than direct defense ministry tender participation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed ammunition specialists possessing Brazilian or Mexican production footprints but lacking NATO-interoperable certification infrastructure. Long-term viability rests on regulatory compliance scalability and propellant chemistry R&D depth. Watch for U.S. foreign military financing priority shifts toward Latin American artillery modernization as an inflection indicator for regional demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Insensitive Munition Certification | U.S. Army Picatinny Arsenal qualification accelerates brigade combat team adoption. |
| Tungsten Supply Security Partnership | Australian and Canadian mining alliances reduce Chinese processing concentration exposure. |
| Platform Licensing Economics | Recurring service revenue displaces spot procurement across Latin American defense ministries. |
| Arctic-Capable Propellant Development | Canadian Northern Defence Strategy generates specialized cold-weather stabilized demand. |
| Naval Shell Production Expansion | Brazilian, Chilean, and Mexican frigate fleets open 76mm and 127mm procurement channels. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of U.S. State Department Directorate of Defense Trade Controls filings, Brazilian Comissão de Controle de Exportação records, Canadian Export and Import Permits Act documentation, and NATO standardization committee protocols. Primary interviews encompassed defense ministry procurement directors, ammunition plant operations managers, propellant chemistry R&D leads, and military logistics commanders across the U.S., Brazil, Canada, Chile, and Colombia. Bottom-up triangulation across product type demand curves and top-down validation against national defense budget appropriations anchored volume and value estimates.
Forecast inputs incorporate artillery shell and tank ammunition procurement timelines under bilateral readiness protocols, NATO interoperability mandate implementation schedules, and Next Generation Squad Weapon program retooling spillover effects across regional suppliers. Segmentation modeling spanned product type, use case, end user, and packaging type dimensions alongside propellant chemistry sophistication tiers. CAGRs were derived from regression analysis of historical procurement cycles and projected modernization program acceleration across the analysis window.
Practitioners should monitor U.S. foreign military financing reallocation, Chinese tungsten export restriction policy shifts, and Latin American defense industrial base localization mandates for early signals of demand trajectory revision. Forecasts reflect documented assumptions regarding procurement continuity under existing bilateral protocols; macroeconomic volatility, regulatory restriction tightening, or precision guidance technology disruption would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Surface to Air Missiles Market
Weapons and Ammunition
Intercontinental Ballistic Missile Market
Weapons and Ammunition
Medium Caliber Ammunition Market
Weapons and Ammunition
Global Shoulder-Fired Weapons Market
Weapons and Ammunition
Ballistic Composite Market
Weapons and Ammunition
NATO Ammunition Market
Weapons and Ammunition
Shotgun Shell Market
Weapons and Ammunition
Missile Seekers Market
Weapons and Ammunition
Smart Bombs Market
Weapons and Ammunition
Shoulder Fixed Weapons Market
Weapons and Ammunition
Hypersonic Missile Market
Weapons and Ammunition
Less Lethal Ammunition Market
Weapons and Ammunition
Automatic Weapons Market
Weapons and Ammunition
Small and Medium Caliber Ammunition Market
Weapons and Ammunition
France Nuclear Bombs and Missiles Market
Weapons and Ammunition
North Korea Nuclear Bombs and Missiles Market