
 Global Military Laser Designator Market | 2026-2036
Global Military Laser Designator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Military Laser Designator Market Intelligence
The integration of man-portable, high-energy laser systems is redrawing battlefield targeting capabilities. Northrop Grumman Corporation leverages its deep expertise in advanced electronics and sensor fusion for next-generation platforms. L3Harris Technologies, Inc. specializes in compact, high-performance electro-optical systems for dismounted soldiers and special forces. Thales Group competes through its extensive international presence and diverse portfolio spanning air, land, and naval domains.
A military laser designator is an electro-optical device that emits a coded laser beam to mark a target for precision-guided munitions. These systems operate at specific wavelengths, such as 1064 nm, and use pulse repetition frequency codes compliant with standards like NATO STANAG 3733 for interoperability. Airborne Laser Designators command the highest value due to complex platform integration. The Target Acquisition and Missile Guidance applications drive the core technology development across all end-user segments.
Export controls like the United States' International Traffic in Arms Regulations (ITAR) and multilateral agreements such as the Wassenaar Arrangement heavily influence market access. NATO Standardization Agreements (STANAGs) dictate design and performance requirements for interoperability among allied forces. Future system viability depends on balancing increased power output with the persistent need for reduced size, weight, and power consumption.
Market Dynamics
The persistent military requirement for reduced Size, Weight, and Power (SWaP) is the central structural force shaping the military laser designator market. This pressure compels innovation in materials and electronics to create lighter, more efficient systems for dismounted soldiers.
Growth Catalysts
- Miniaturized Solid-State Lasers:The development of compact, highly efficient diode-pumped solid-state (DPSS) lasers enables the creation of new man-portable and weapon-mounted designators, expanding deployment options for infantry and special operations forces.
- Joint Defense Modernization:Collaborative defense programs among NATO and allied nations drive demand for interoperable systems. These initiatives pool resources and create a large, standardized market for compliant targeting equipment.
- Evolving Threat Environments:The proliferation of small, fast-moving targets like unmanned aerial systems (UAS) and the challenges of urban warfare require more precise and responsive targeting capabilities, accelerating the adoption of advanced laser designators.
Market Restraints
- Export Control Regimes:Strict regulations like the United States' ITAR and the multilateral Wassenaar Arrangement create significant administrative hurdles and limit the addressable market for manufacturers, restricting sales to approved nations only.
- Technical Performance Trade-offs:A fundamental engineering conflict exists between increasing a laser's effective range and power output while simultaneously reducing the system's overall size, weight, and thermal signature, constraining design possibilities for portable units.
- High Unit Costs:The use of specialized, ruggedized optical components and advanced sensor packages results in high per-unit costs. This expense limits procurement to high-value platforms and elite units, slowing broader force-wide adoption.
Strategic Opportunities
- Indo-Pacific Force Modernization:Nations like Australia, Japan, and South Korea are significantly increasing defense spending to upgrade their targeting and surveillance capabilities, representing a major growth opportunity outside of the traditional NATO sphere.
- Network-Centric Warfare Integration:There is an opportunity to develop designators with embedded data links that can share target information directly with other assets on a network, enhancing situational awareness and shortening sensor-to-shooter timelines.
- AI-Powered Target Recognition:Integrating edge-based artificial intelligence for automated target detection and classification can reduce operator cognitive load and improve targeting speed and accuracy, offering a distinct performance advantage for next-generation systems.
Industry Challenges
- Legacy System Integration:A primary operational challenge is ensuring new laser designators are fully compatible with the vast and diverse inventory of existing aircraft, vehicles, and precision-guided munitions, which often involves complex software and hardware modifications. *Specialized Component Sourcing: The supply chain for critical components like high-power laser diodes and non-linear optical crystals is highly concentrated. This creates vulnerability to disruptions and limits the ability of new entrants to scale production.
- Interoperability Certification:Achieving and maintaining compliance with standards like NATO STANAG 3733 is a lengthy and expensive process. It requires rigorous testing to guarantee that a system can communicate effectively with assets from multiple allied nations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Military Laser Designator Market |
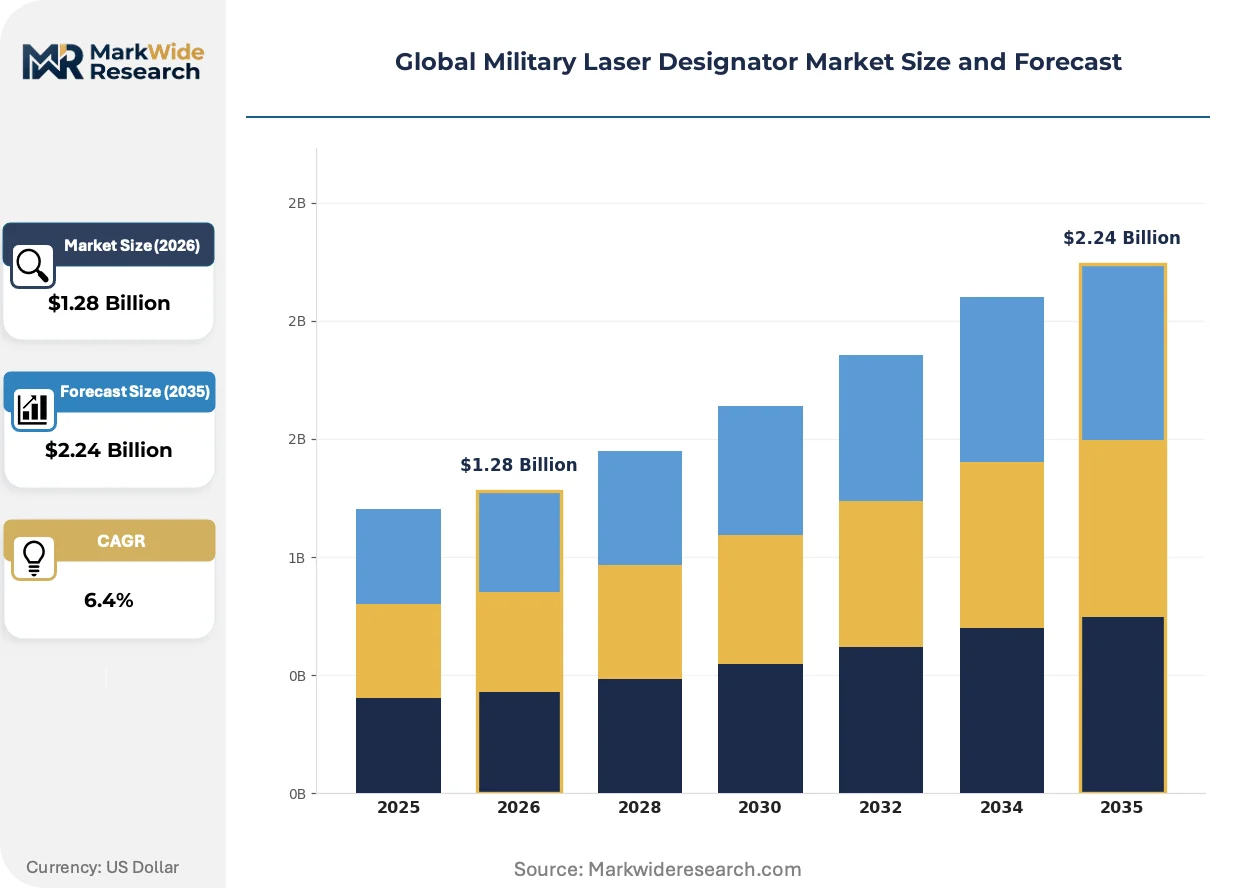
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.24 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Laser Designators, Vehicle-Mounted Systems, Airborne Laser Designators, Shipborne Targeting Modules Technology: Semiconductor Laser, Fiber Laser, Diode-Pumped Solid-State Laser, Gas Laser, Solid-State Laser Application: Target Acquisition, Range Finding, Surveillance, Target Tracking, Missile Guidance End User: Army Ground Forces, Naval Forces, Air Defense Units, Special Operations Groups |
| Companies Covered | Thales Group, L3Harris Technologies, Inc., Lockheed Martin Corporation, BAE Systems plc, RTX Corporation, Northrop Grumman Corporation, Leonardo S.p.A., Rheinmetall AG, Elbit Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Military Laser Designator Market Strategic Shifts & Innovations
System design is shifting from standalone devices to nodes within a larger, networked battlespace. This evolution prioritizes data sharing and interoperability, influencing the technological composition of next-generation laser designation platforms and their integration with command and control systems.
Gallium Nitride (GaN) semiconductor technology provides a pathway to more efficient and powerful diode pumps for solid-state lasers. Special operations forces and airborne platform integrators are adopting GaN-based components to achieve higher performance within strict SWaP constraints. The superior power efficiency and thermal management of GaN is displacing older Gallium Arsenide (GaAs) architectures in new system designs.
The Wassenaar Arrangement on Export Controls for Conventional Arms and Dual-Use Goods and Technologies governs the international transfer of military-grade laser systems. This multilateral agreement establishes common guidelines that participating states, including the United States and many European nations, incorporate into their national export laws. Defense contractors must navigate these complex regulations, which directly impact international sales strategies and market access.
A notable behavioral shift is the move toward acquiring targeting pods and designators as part of a fully integrated mission systems package rather than as standalone components. This disrupts the traditional procurement model by favoring prime contractors who can provide a complete sensor-to-shooter solution. This trend is most visible in large-scale aircraft modernization programs in the United States and allied European air forces.
Global Military Laser Designator Market Segmentation
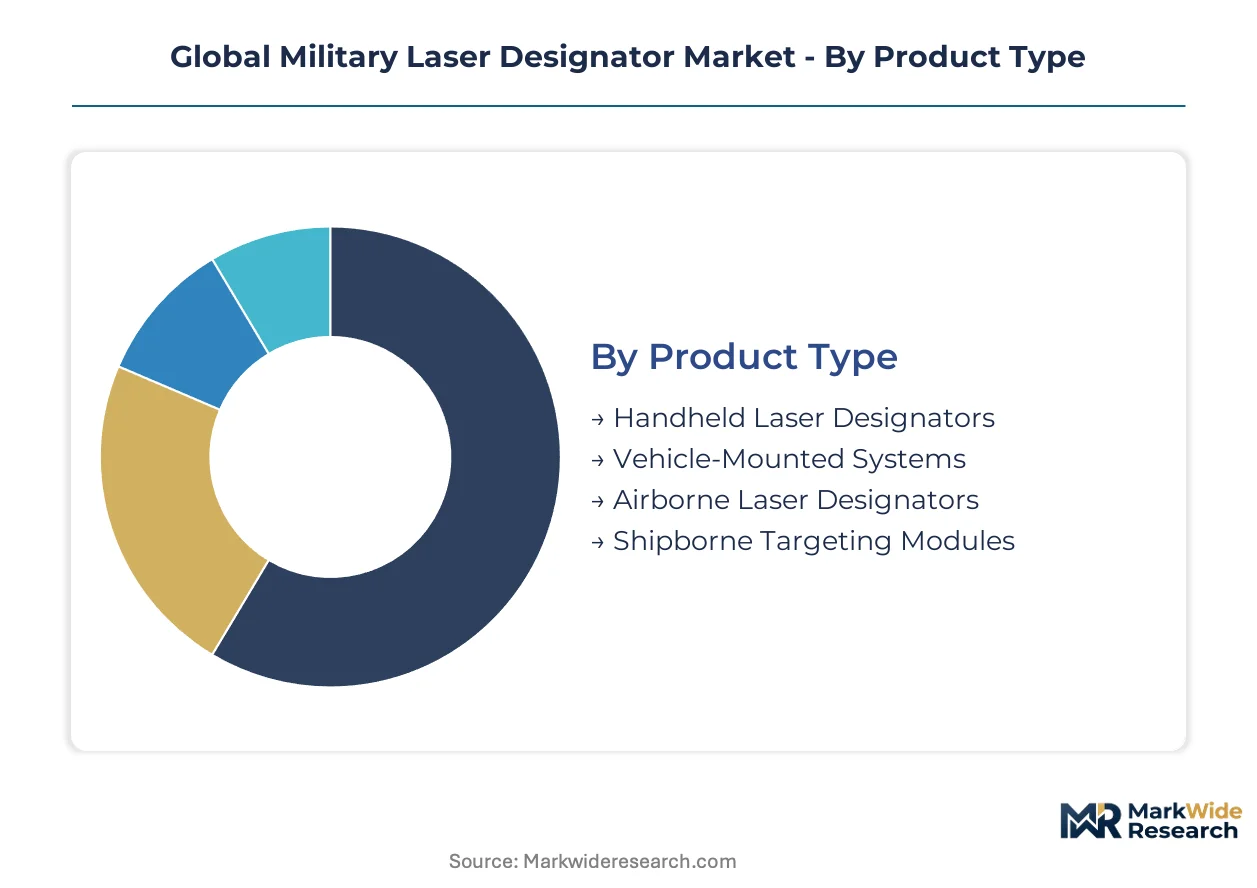
The military laser designator market comprises diverse product types, technologies, applications, and end-user groups. Understanding these distinct segments reveals specific demand patterns and technological priorities across different operational environments. This segmentation highlights where innovation is concentrating and where market access is critical.
Product Type:
The product type segmentation reflects varying deployment scales, from individual soldier systems to complex platform integrations, with demand often split between domestic defense needs and export programs across allied nations.
- Airborne Laser Designators:These sophisticated systems integrate into aircraft, providing precision targeting for air-to-ground munitions. Their high value stems from complex sensor fusion, with demand concentrated in the United States and European air forces.
- Handheld Laser Designators:Designed for dismounted soldiers and special operations forces, these lightweight, man-portable devices enable forward observers to mark targets. Miniaturization of DPSS lasers drives enhanced portability.
- Vehicle-Mounted Systems:These designators integrate with ground vehicles, providing targeting capabilities. Their robust construction handles harsh conditions.
- Shipborne Targeting Modules:Employed on naval vessels, these modules provide long-range target illumination. Integration with ship combat systems ensures maritime awareness.
Vehicle-Mounted Systems commands the established base. The steepest expansion runs through Handheld Laser Designators.
Technology:
Technological differentiation correlates with development cost and performance tiers, with advanced laser architectures offering superior efficiency and power output at higher expense for specific mission profiles.
- Diode-Pumped Solid-State Laser:DPSS lasers utilize semiconductor diodes to pump a solid-state gain medium, offering high efficiency and compact size. This technology is critical for miniaturized man-portable designators due to its superior power-to-weight ratio.
- Fiber Laser:Fiber lasers channel the laser beam through an optical fiber, allowing for excellent beam quality and thermal management. These systems offer high power scalability for demanding airborne platforms.
- Semiconductor Laser:These lasers use semiconductor junctions to produce light, serving as compact pump sources.
- Gas Laser:Gas lasers generate high-power beams by exciting gas molecules; however, their larger size limits portable use.
- Solid-State Laser:Traditional solid-state lasers use a doped crystal or glass as the gain medium, providing robust performance.
While Solid-State Laser technology provides a foundational capability, innovations in Diode-Pumped Solid-State Laser architectures are rapidly driving new performance benchmarks.
Application:
Application segments reflect primary operational roles, with some functions representing high-volume requirements across multiple platforms and others serving specialized, high-impact missions.
- Missile Guidance:This application involves illuminating a target with a laser beam, allowing laser-guided munitions to home in on reflected energy. It is a core function driving precise and stable laser outputs for advanced weaponry.
- Target Acquisition:Designators support target acquisition by rapidly identifying and locking onto objects of interest for subsequent engagement. This capability is crucial for dismounted soldiers in urban environments.
- Range Finding:Laser range finders accurately measure distance to a target by calculating pulse return time. This data is essential for ballistic calculations.
- Surveillance:Laser designators assist surveillance by providing enhanced visibility or marking objects for observation. This function supports intelligence gathering.
- Target Tracking:These systems continuously follow a designated target, maintaining illumination for extended periods. Target tracking is vital for engaging fast-moving objects.
Target Acquisition remains a fundamental operational need, while Missile Guidance applications continue to demand the most stringent performance specifications.
End User:
End-user segmentation reveals distinct operational requirements and procurement cycles, with specialized units prioritizing compact, high-performance systems and larger forces focusing on interoperability.
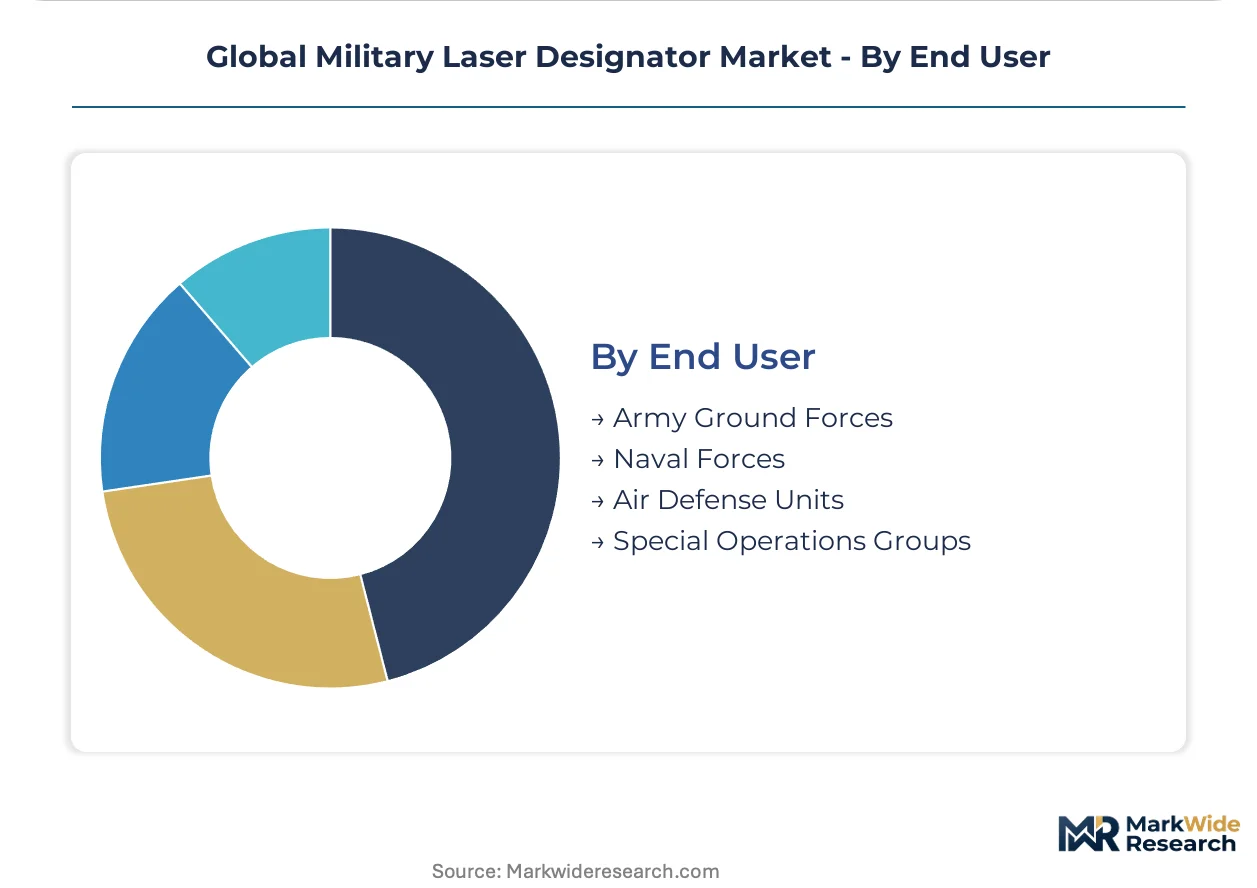
- Special Operations Groups:These elite units require highly portable, rugged, and precise laser designators for covert operations and rapid target engagement. Their demand drives miniaturization and advanced battery technologies.
- Army Ground Forces:Comprising the largest segment, Army Ground Forces utilize laser designators for infantry, armored vehicles, and artillery support. Modernization programs in the United States and NATO nations drive demand.
- Naval Forces:Ship-based and maritime patrol aircraft platforms use laser designators for surface and air target engagement. Resistance to harsh marine environments is a key requirement.
- Air Defense Units:These units employ laser designators to identify and track aerial threats, including UAS. Precision targeting for anti-aircraft systems is a critical capability.
The market volume for Army Ground Forces remains substantial, yet Special Operations Groups are consistently pushing the boundaries of system capability and portability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global military laser designator market exhibits a complex export-import balance, with a handful of nations driving significant production and innovation, while allied partners worldwide represent crucial demand centers for advanced targeting technologies and systems integration.
United States
Demand for advanced man-portable systems and sophisticated airborne platforms drives market expansion. The International Traffic in Arms Regulations (ITAR) heavily influences export policies for defense technology. Major defense contractors in California and Texas continue to develop cutting-edge electro-optical systems for domestic and allied forces.
United Kingdom
Modernization programs within the armed forces stimulate procurement of interoperable laser designators. The UK's export control regulations govern the international transfer of military-grade equipment. Defense clusters in Bristol and London focus on advanced sensor integration and next-generation targeting solutions.
Germany
European defense initiatives and national security requirements boost the procurement of high-performance designators. The Wassenaar Arrangement significantly impacts German export policies for dual-use technologies. Bavarian defense companies specialize in precision targeting and optical technologies for ground and air platforms.
Japan
Increased defense spending to address regional security challenges fuels demand for modern targeting capabilities. The Ministry of Economy, Trade and and Industry (METI) oversees dual-use technology exports. Industrial hubs in Tokyo and Nagoya concentrate on advanced optical and sensor development for integrated defense systems.
Australia
Force modernization programs across the Indo-Pacific region generate substantial demand for advanced laser designators. Australian export control laws regulate the transfer of defense technologies to international partners. Defense innovation centers in Adelaide and Canberra support new system integration and local manufacturing capabilities.
Global Military Laser Designator Market Key Industry Players
Concentration sits with established defense primes possessing extensive system integration capabilities for complex platforms. The market structure is moderately consolidated, with a few large players dominating high-value segments like airborne designators. Strategic archetypes include global defense contractors, specialized electro-optical system manufacturers, and niche technology developers. Dominant competitive moves involve strategic partnerships for complex program bids and continuous portfolio diversification into adjacent sensor technologies.
Global defense contractors exemplify the broad integration capabilities required for advanced military laser designators. Northrop Grumman Corporation, a US-based entity, and the France-headquartered Thales Group represent this tier, leveraging their vast defense portfolios for air, land, and naval applications. L3Harris Technologies, Inc., another US corporation, occupies a position focused on compact, high-performance electro-optical systems for specialized ground forces. These firms anchor the market's high-performance segments with their extensive R&D and manufacturing footprints.
| Leading Market Players |
|---|
| Thales Group |
| L3Harris Technologies, Inc. |
| Lockheed Martin Corporation |
| BAE Systems plc |
| RTX Corporation |
| Northrop Grumman Corporation |
| Leonardo S.p.A. |
| Rheinmetall AG |
| Elbit Systems Ltd. |
| Others |
Cost & Logistics Intelligence
NATO STANAG 3733 certification gates both supply qualification and price differentiation for military laser designators. Compliance with this standard ensures interoperability among allied forces, commanding premium pricing for certified systems.
Pricing Analysis
Military procurement agencies anchor a contract-based pricing model for laser designators. Price differentiation stems from NATO STANAG 3733 certification, system customization for specific airborne or ground platforms, and the established brand premium of defense contractors. Pricing pressure stems from the substantial R&D investments and the specialized, ruggedized optical components required for battlefield durability. Special Operations Groups exhibit lower price sensitivity for mission-critical performance, while Army Ground Forces prioritize cost-effectiveness for larger volume procurements.
Supply Chain Analysis
Specialized component transport costs significantly influence the military laser designator supply chain. Supply concentrates in the United States, Germany, and Japan for critical inputs like high-power laser diodes and non-linear optical crystals. This concentration creates single-source vulnerability for manufacturers. Distribution typically runs through direct sales channels to national defense ministries and major prime contractors for system integration into larger platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The military laser designator market is experiencing high-growth disruption, driven by the miniaturization of solid-state lasers. This technological inflection enables new man-portable applications, fundamentally changing battlefield targeting capabilities.
For Market Incumbents: Consolidate specialized component supply chains through strategic acquisitions of niche technology developers. This mitigates single-source vulnerability from highly concentrated suppliers and reinforces control over critical inputs like GaN semiconductors. Incumbents must also deepen R&D into AI-powered target recognition to counter emerging threats like small UAS and maintain a competitive edge.
For New Entrants and Emerging Players: Specialized training and support for dismounted units represents a service-layer gap where incumbents often under-serve. New entrants can target the Handheld Laser Designators segment, leveraging miniaturized DPSS technology for enhanced portability. Developing AI-powered target recognition capabilities offers a distinct performance advantage and a compelling go-to-market angle for agile players.
For Investors and Strategic Acquirers: Wassenaar Arrangement export controls reshape the acquisition landscape for military laser designators. Long-term viability over the next decade favors companies with strong intellectual property in compact, high-performance systems. Investors should target specialized electro-optical system manufacturers or AI software developers for strategic integration. Increased defense spending in the Indo-Pacific region serves as a critical signal to watch for accelerating market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: GaN-based Man-Portable Designators | Introduces higher power output within strict Size, Weight, and Power (SWaP) constraints for special forces. |
| Strategic Partnership: AI Target Recognition Integration | Accelerates deployment of automated detection capabilities, reducing operator workload and improving accuracy. |
| Capacity Expansion: Critical Component Manufacturing | Reduces reliance on concentrated supply chains, enhancing resilience against geopolitical disruptions and ensuring supply. |
| Certification Investment: NATO STANAG 3733 Compliance | Unlocks access to large, standardized procurement programs among allied forces, expanding market reach. |
| Geographic Expansion: Indo-Pacific Market Entry | Captures demand from nations modernizing defense capabilities, diversifying revenue streams beyond traditional markets. |
Research Approach
Desk research of government defense reports, industry association publications, and academic journals preceded structured interviews with defense procurement officers, R&D engineers, and special operations commanders. This primary and secondary data triangulation ensured a comprehensive understanding of market dynamics and technological advancements. A bottom-up approach validated insights derived from top-down market sizing.
Variance decomposition models quantified the impact of key market drivers and restraints across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regional defense spending patterns. Compound annual growth rates were derived from historical trends and projected technological adoption. Geopolitical tensions and defense budget allocations served as critical forecast inputs.
Material uncertainties — unforeseen geopolitical conflicts, rapid technological breakthroughs, or major export policy shifts — sit outside the modeled envelope. Forecasts reflect assumptions documented at the time of publication. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Europe Defense Market
Defense and Military Systems and Equipment
Smart War Weapon Market
Defense and Military Systems and Equipment
Search and Rescue Equipment Market
Defense and Military Systems and Equipment
Military High Altitude Radio Jamming System Market
Defense and Military Systems and Equipment
Military Laser Systems Market
Defense and Military Systems and Equipment
Global Military Defense Vehicle Intercom System Market
Defense and Military Systems and Equipment
Military Embedded System Software Market
Defense and Military Systems and Equipment
Saudi Arabia Defense Market
Defense and Military Systems and Equipment
Military Load Carriage System Market
Defense and Military Systems and Equipment
Global Battlefield Management System Market
Defense and Military Systems and Equipment
Defense Integrated Antenna Market
Defense and Military Systems and Equipment
Missiles and Missile Defense Systems Market
Defense and Military Systems and Equipment
Mine Clearance System Market
Defense and Military Systems and Equipment
Network Centric Warfare (NCW) Market
Defense and Military Systems and Equipment
Soldier System Market
Defense and Military Systems and Equipment
Defense Tactical Computers Market