
 Intercontinental Ballistic Missile Market | 2026-2036
Intercontinental Ballistic Missile Market Size, Share, and Industry Trends Forecast 2026-2036
Intercontinental Ballistic Missile Market Outlook
The performance gap between premium precision-strike systems and legacy commodity platforms is broadening as solid propellant and hybrid architectures command premium positioning against aging liquid-fuel inventories. Northrop Grumman Corporation dominates next-generation ground-based strategic deterrent engineering through its sustained investment in modular reentry vehicle platforms. Lockheed Martin Corporation leverages integrated command-and-control networks to anchor its position across the entire kill chain from launch detection to target engagement.
An intercontinental ballistic missile is a strategic weapon system with a minimum range exceeding 5,500 kilometers, typically employing either liquid or solid propellant multi-stage boosters to deliver nuclear or conventional warheads via ballistic trajectories through sub-orbital space. Its primary purpose is to provide assured second-strike capability as the land-based leg of a nuclear triad, with modern variants incorporating maneuverable reentry vehicles and countermeasures to penetrate integrated air defense networks. Solid propellant systems now lead procurement volumes due to their reduced launch preparation time and enhanced survivability against counterforce targeting, while guidance systems technology captures disproportionate R&D allocation as accuracy improvements directly reduce required warhead yield. The space launch application segment shows structural momentum as decommissioned ICBM boosters convert to orbital payload delivery under government-industry partnerships.
The US Department of Defense and China's State Administration for Science, Technology and Industry for National Defense impose stringent product standards that effectively restrict market access to prime contractors with existing security clearances and proven flight-test records. NATO STANAG frameworks and bilateral technology control regimes further constrain component sourcing and knowledge transfer across the supplier base. Stakeholders must monitor emerging hypersonic glide vehicle integration requirements and corresponding test-range capacity constraints as these programs compete for the same specialized engineering talent and propulsion test infrastructure.
Market Dynamics
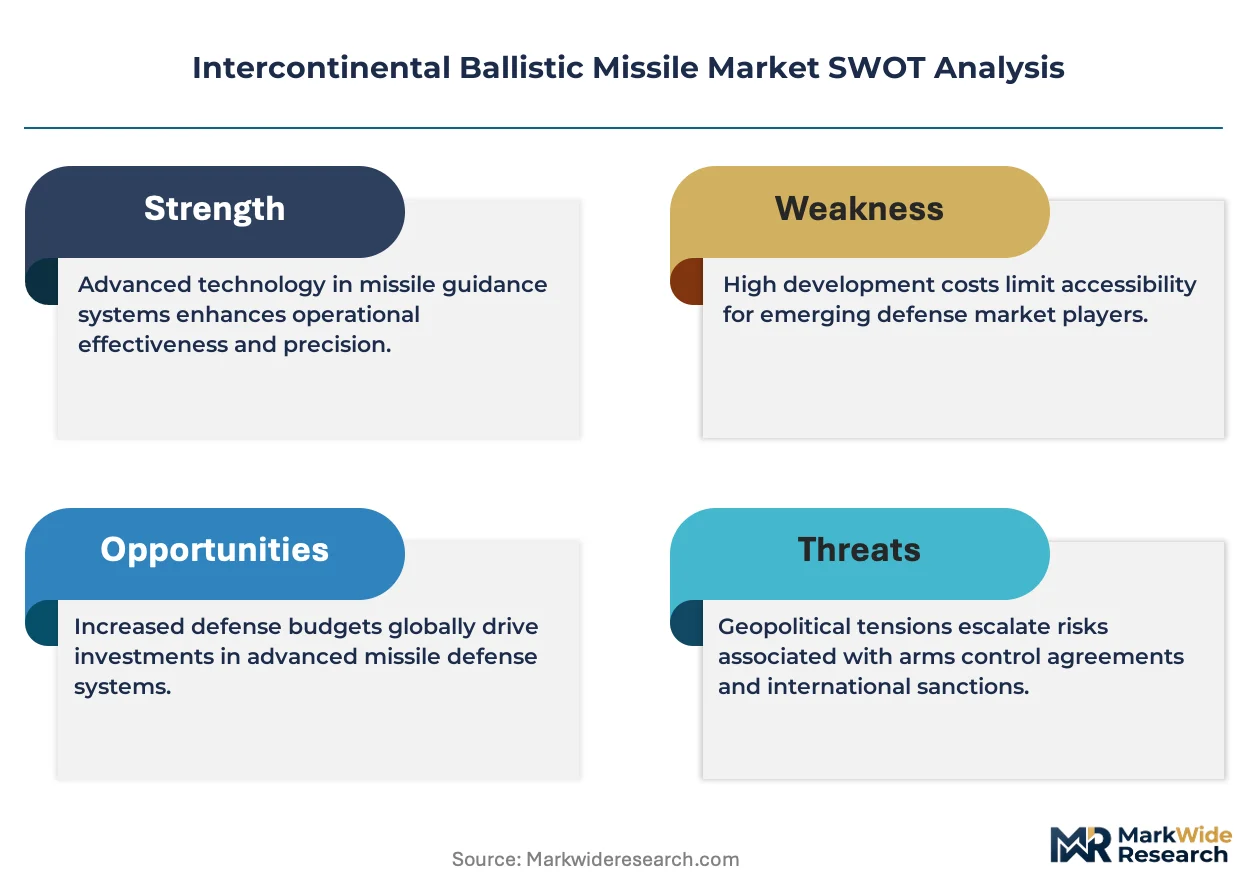
Solid propellant architectures are compressing development cycles while environmental safety protocols from the EPA and China's MEE force early retirement of liquid-fuel infrastructure across operational arsenals.
Growth Catalysts
- Ground-Based Strategic Deterrent modernization:The US Department of Defense's GBSD program is replacing Minuteman III systems with modular platforms, sustaining prime contractor engineering capacity through 2040.
- REACH compliance tailwinds:European environmental frameworks are accelerating solid propellant adoption by restricting hydrazine-based liquid fuel handling and storage protocols.
- Hypersonic glide vehicle integration:Conventional prompt global strike missions are driving demand for maneuverable reentry vehicles that penetrate integrated air defense networks.
Market Restraints
- Ammonium perchlorate supply concentration:Domestic US production of this solid propellant oxidizer depends on a single facility in Utah, creating single-point vulnerability.
- Security clearance bottlenecks:The Pentagon's personnel vetting backlog stretches 18-24 months, constraining engineering workforce expansion for classified programs.
- Limited test range capacity:Vandenberg Space Force Base and Pacific Test Range scheduling conflicts between ICBM flight tests and hypersonic vehicle programs delay qualification timelines.
Strategic Opportunities
- Orbital payload conversion:Decommissioned Minuteman and Peacekeeper boosters are repurposing under NASA and Space Force partnerships for small satellite launch services.
- India's emerging triad requirements:The Defence Research and Development Organisation is expanding Agni-V production capacity to complete land-based deterrence alongside sea-based systems.
- Digital engineering mandates:The US Department of Defense's Model-Based Systems Engineering directive is opening software and simulation subcontractor opportunities outside traditional hardware primes.
Industry Challenges
- Propulsion test infrastructure scarcity:Hypersonic and ICBM programs compete for the same altitude test facilities at Arnold Air Force Base, creating queue congestion.
- Legacy system integration complexity:New solid propellant motors must interface with 1960s-era command-and-control architectures until full NC3 modernization completes.
- Specialized materials workforce gaps:Carbon-carbon nozzle fabrication and filament-wound motor case expertise is concentrating among retiring technicians without adequate apprenticeship pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intercontinental Ballistic Missile Market |
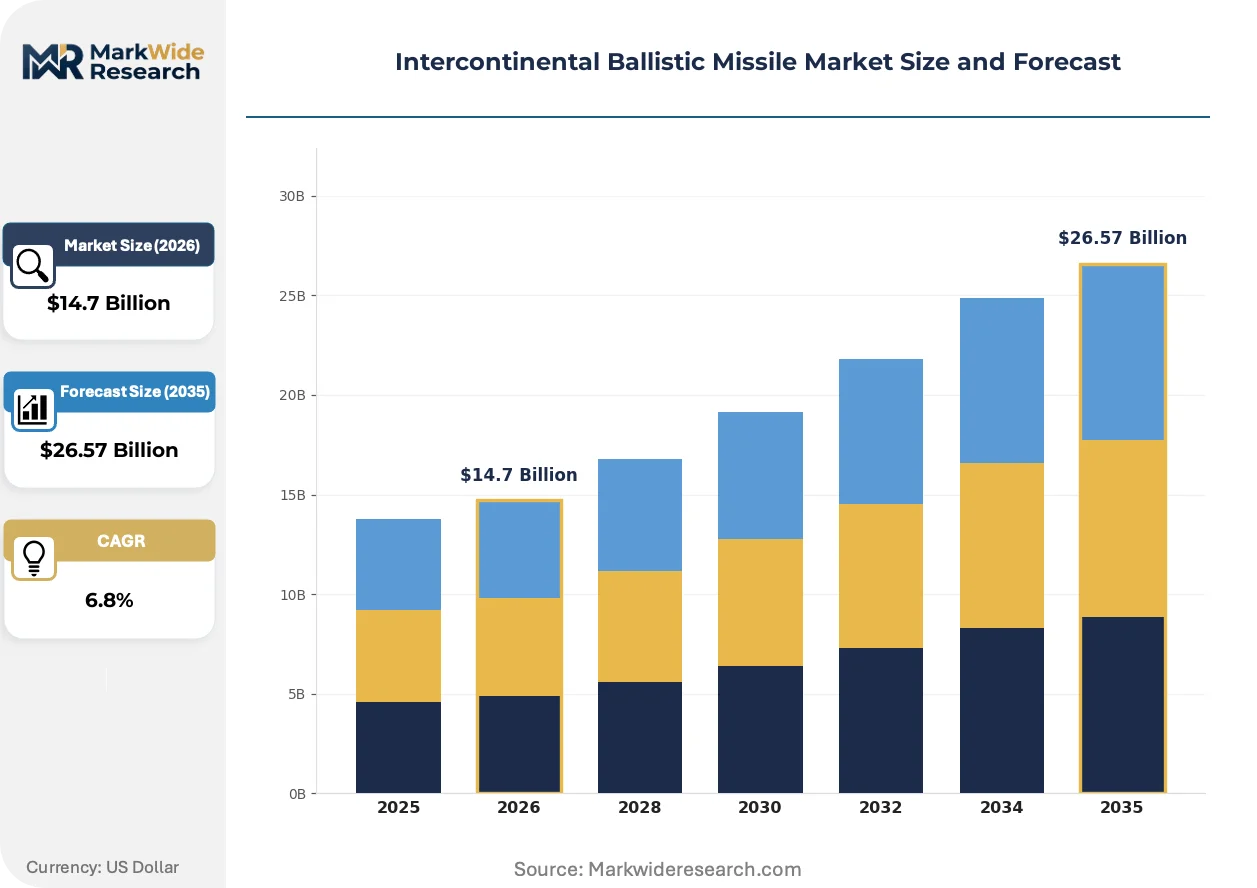
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Liquid Propellant, Solid Propellant, Hybrid Propellant, Nuclear Application: Strategic Deterrence, Defense, Space Launch, Research End User: Military, Government, Defense Contractors, International Organizations Technology: Guidance Systems, Launch Platforms, Payload Delivery, Propulsion |
| Companies Covered | China Aerospace Science and Technology Corporation, Northrop Grumman Corporation, Lockheed Martin Corporation, Israel Aerospace Industries, ArianeGroup, The Boeing Company, L3Harris Technologies Inc., General Dynamics Corporation, Raytheon Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intercontinental Ballistic Missile Market Strategic Shifts
Modular reentry vehicle architectures and digital engineering workflows are compressing design-to-test intervals while hypersonic convergence pressures legacy ballistic trajectories. These forces are restructuring supplier relationships and qualification protocols across the sector.
Advanced composite motor cases are expanding into fifth-generation ICBM platforms by replacing steel and titanium structures with carbon-fiber filament wound designs. The US Air Force and China's State Administration for Science, Technology and Industry for National Defense are both qualifying these materials for extended-range missions. This weight reduction is expanding into payload capacity trades, allowing either increased throw-weight or reduced booster stages.
China's GB standards for hazardous material handling are tightening solid propellant manufacturing protocols through mandatory automated mixing and casting systems. Industrial consequence includes facility retrofit costs that favor greenfield construction over legacy plant upgrades. Western prime contractors are responding by qualifying Chinese titanium suppliers under end-use certification frameworks rather than blanket import restrictions.
Defense procurement offices are consolidating vendor bases through multi-year fixed-price contracts that transfer development risk to primes. The traditional cost-plus model is yielding to milestone-based payments tied to digital twin verification rather than physical hardware delivery. This behavioral shift is most visible in the US Department of Defense's Next Generation Interceptor and GBSD programs, where Northrop Grumman and Lockheed Martin have accepted unprecedented fixed-price development phases.
Intercontinental Ballistic Missile Market Segmentation
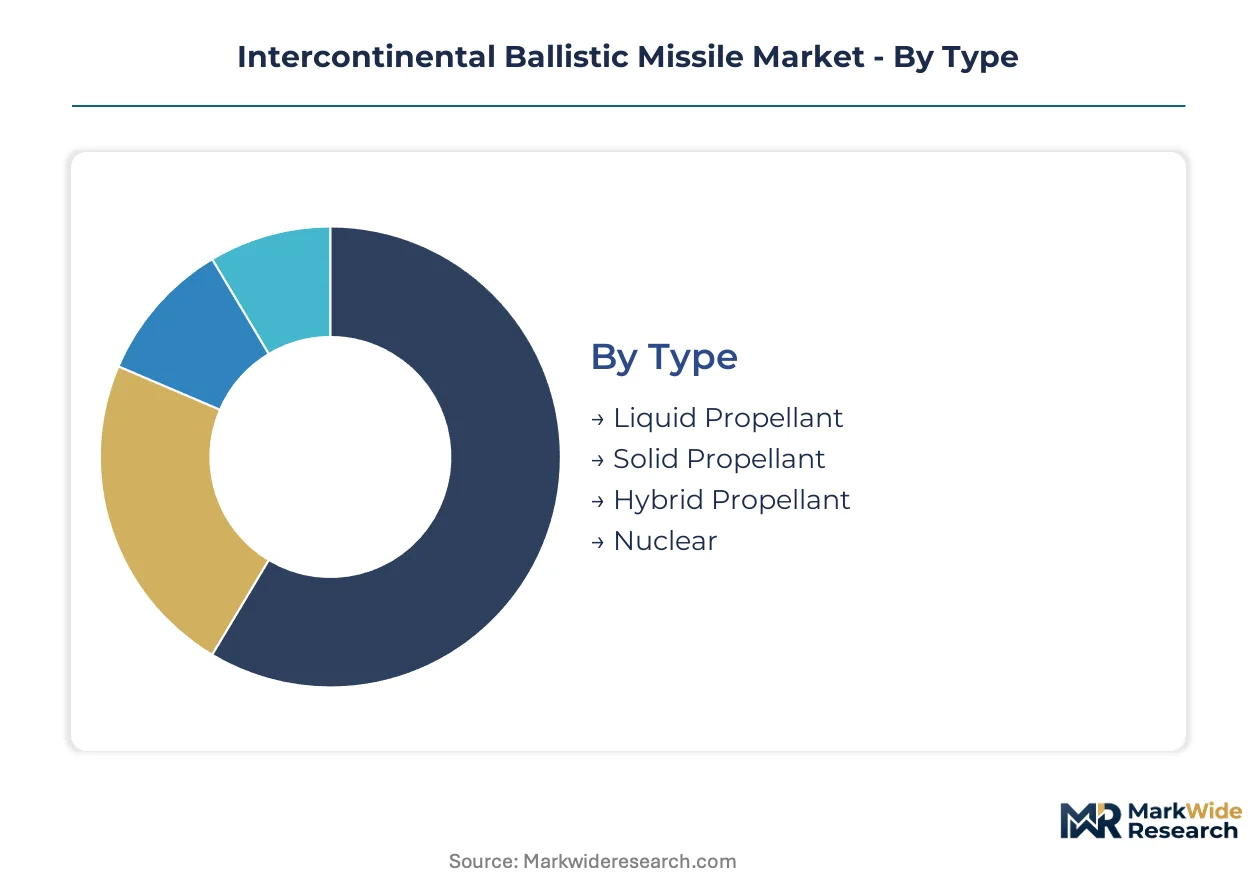
ICBM procurement patterns diverge sharply across propulsion architectures, mission profiles, and institutional buyers. Each segmentation axis reveals distinct capability requirements and budget authority structures that reshape supplier relationships.
Type:
Buyers differentiate primarily by operational readiness requirements and environmental compliance burdens rather than unit acquisition cost.
- Solid Propellant:Cast-composite motors store indefinitely without fueling operations. The US Department of Defense's GBSD program and China's State Administration for Science, Technology and Industry for National Defense both prioritize this architecture for reduced launch preparation time and enhanced survivability against counterforce targeting.
- Liquid Propellant:Storable and cryogenic liquid systems persist in legacy arsenals requiring sustained maintenance infrastructure. Russia maintains operational silos with these systems despite longer countdown sequences, constrained by facility replacement costs and existing engineering workforce specialization.
- Hybrid Propellant:Combines liquid oxidizer with solid fuel grain for throttle control and shutdown capability.
- Nuclear:Designates warhead delivery configurations rather than propulsion chemistry, covering MIRV and single-warhead architectures.
Volume sits with Solid Propellant; growth tilts toward Hybrid Propellant as maneuverable reentry vehicle requirements demand thrust modulation.
Application:
Mission scope determines funding authority, with nuclear-certified programs commanding multi-decade appropriations against single-year research budgets.
- Strategic Deterrence:Assured second-strike capability under national command authority. The US, China, and Russia maintain independent modernization timelines, each funding land-based legs of nuclear triads through dedicated budget lines insulated from conventional procurement cycles.
- Defense:Conventional prompt global strike and regional deterrence missions. The US Department of Defense and China's People's Liberation Army Rocket Force are expanding maneuverable reentry vehicle testing for non-nuclear payloads, though treaty constraints limit deployment.
- Space Launch:Decommissioned boosters convert to orbital payload delivery under NASA and Space Force partnerships.
- Research:Suborbital flight testbeds for reentry physics and guidance algorithm validation.
Revenue concentrates in Strategic Deterrence; expansion accelerates most quickly in Space Launch as Minuteman III retirement creates booster surplus.
End User:
Contracting authority and security clearance thresholds fragment the addressable market across institutional categories with incompatible procurement protocols.
- Military:Operational commanders with requirements for deployed readiness and rapid retargeting. The US Air Force Global Strike Command and China's PLA Rocket Force control silo infrastructure and mobile launcher basing, driving specifications for electromagnetic pulse hardening and nuclear command continuity.
- Government:National laboratories and test range operators responsible for stockpile stewardship. Sandia National Laboratories and Los Alamos National Laboratory in the US, alongside China's Northwest Institute of Nuclear Technology, define qualification protocols that suppliers must satisfy.
- Defense Contractors:Prime integrators subcontracting propulsion, guidance, and reentry vehicle fabrication.
- International Organizations:NATO shared early warning and limited dual-capability planning cells.
Procurement volume aggregates with Military; contract velocity is climbing fastest among Defense Contractors as fixed-price development risk transfers accelerate.
Technology:
R&D allocation concentrates where accuracy improvements directly reduce required warhead yield and enable conventional mission expansion.
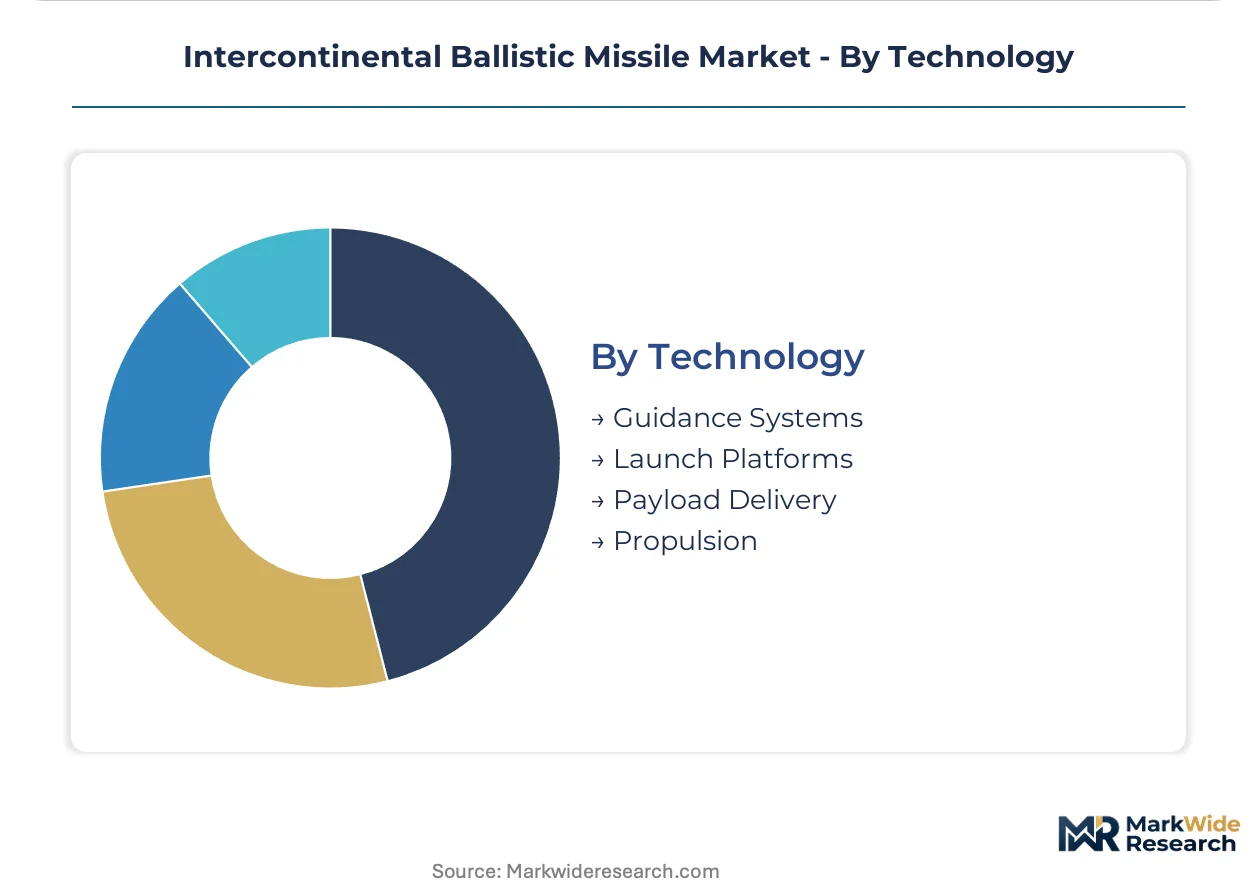
- Guidance Systems:Astro-inertial navigation with GPS augmentation and stellar updates. Northrop Grumman's modular reentry vehicle platforms and China's BeiDou-integrated guidance packages are capturing disproportionate engineering investment as circular error probable reductions reshape targeting requirements.
- Propulsion:Multi-stage booster design and thrust vector control. Advanced composite motor cases from carbon-fiber filament wound designs are replacing steel and titanium across fifth-generation platforms in both US and Chinese qualification pipelines.
- Launch Platforms:Silo-based, road-mobile, and rail-mobile basing modes.
- Payload Delivery:Reentry vehicle thermal protection and penetration aids.
Engineering headcount clusters in Guidance Systems; capability gaps are widening fastest in Launch Platforms as mobile basing requirements strain survivability analysis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vandenberg Space Force Base anchors Western Hemisphere test infrastructure, while Korla Missile Test Complex drives Chinese qualification velocity. Each operational theater imposes distinct security clearance thresholds and environmental compliance burdens that reshape supplier access.
United States
The Department of Defense's GBSD program sustains prime contractor engineering capacity through 2040 at Hill Air Force Base and Tinker Air Force Base maintenance depots. EPA hazardous material handling protocols force early retirement of liquid-fuel infrastructure across operational arsenals. Utah's ammonium perchlorate production facility supplies solid propellant oxidizer under single-point vulnerability constraints.
China
State Administration for Science, Technology and Industry for National Defense accelerates nuclear triad modernization through modular reentry vehicle platforms. MEE hazardous material handling standards tighten solid propellant manufacturing protocols via mandatory automated mixing systems. Xi'an aerospace corridor concentrates carbon-fiber filament wound motor case fabrication under greenfield construction preference.
Russia
Roscosmos and strategic rocket forces maintain operational silos with legacy liquid-fuel systems despite longer countdown sequences. Facility replacement costs constrain solid propellant migration timelines at existing engineering workforce concentrations. Krasnoyarsk Machine-Building Plant anchors reentry vehicle thermal protection production amid international technology control regime constraints.
India
Defence Research and Development Organisation expands Agni-V production capacity to complete land-based deterrence alongside sea-based systems. BIS certification requirements for strategic materials create domestic sourcing mandates for titanium suppliers. Hyderabad-integrated missile complex concentrates guidance system integration under Model-Based Systems Engineering directives.
Intercontinental Ballistic Missile Market Competitive Environment
Capital-heavy prime contractors compete with specialized subsystem suppliers for fixed-price development risk across next-generation strategic deterrent programs. The vendor base concentrates among security-cleared entities with proven flight-test records and existing nuclear command continuity infrastructure. Two strategic archetypes dominate: integrated kill-chain architects spanning launch detection to target engagement, and modular reentry vehicle specialists optimizing payload delivery configurations. Competitive moves center on multi-year fixed-price contract acceptance and digital engineering capability acquisition.
Among US-based integrated primes, Northrop Grumman Corporation and Lockheed Martin Corporation exemplify the kill-chain architect archetype through sustained investment in command-and-control network integration. China Aerospace Science and Technology Corporation occupies a parallel position within the Chinese strategic deterrent ecosystem, representing state-directed vertical coordination across propulsion, guidance, and basing mode development. Each entity anchors procurement consolidation trends through milestone-based payment structures tied to digital twin verification rather than physical hardware delivery.
| Leading Market Players |
|---|
| China Aerospace Science and Technology Corporation |
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| Israel Aerospace Industries |
| ArianeGroup |
| The Boeing Company |
| L3Harris Technologies Inc. |
| General Dynamics Corporation |
| Raytheon Technologies Inc. |
| Others |
Value Chain & Pricing Dynamics
Captive ammonium perchlorate production in Utah anchors both supply security and pricing power for US prime contractors bidding on Ground-Based Strategic Deterrent segments. This backward integration into solid propellant oxidizer manufacturing insulates Northrop Grumman and Lockheed Martin from commodity volatility while compressing competitor margins on fixed-price development phases.
Pricing Analysis
Outcome-based pricing tied to circular error probable reductions governs guidance system procurement, with Northrop Grumman's modular reentry vehicle platforms commanding premium positioning against legacy commodity alternatives. Price differentiation separates GPS-augmented astro-inertial packages from basic stellar update configurations, while cost compression in liquid-fuel retirement programs intensifies as EPA hazardous material handling protocols accelerate infrastructure decommissioning. Military end users exhibit lowest price sensitivity given nuclear command continuity requirements, whereas space launch conversion buyers negotiate aggressively on decommissioned Minuteman booster surplus.
Supply Chain Analysis
Dual-sourcing mandates from the Pentagon's Defense Contract Management Agency require prime contractors to qualify secondary suppliers for carbon-carbon nozzle fabrication and filament-wound motor case production. Geographic supply concentration centers on the United States for ammonium perchlorate oxidizer, China for titanium feedstock under end-use certification frameworks, and domestic filament-winding capacity for advanced composite motor cases. Raw material dependencies include ammonium perchlorate, carbon fiber precursor, and beryllium copper for thrust vector control mechanisms. Single-source vulnerability at Utah's oxidizer facility creates structural supply chain risk. Distribution runs through prime contractor integration facilities at Hill Air Force Base and Tinker Air Force Base maintenance depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where control over solid propellant oxidizer production and guidance system fabrication determines who captures fixed-price development risk on next-generation strategic deterrent programs.
For Market Incumbents: Lock in ammonium perchlorate supply through long-term offtake agreements with Utah's sole domestic production facility before emerging entrants qualify alternative oxidizer suppliers. Secure carbon-carbon nozzle fabrication apprenticeships at Arnold Air Force Base to preempt workforce gaps as retiring technicians concentrate specialized expertise. Counter hypersonic glide vehicle programs competing for identical propulsion test infrastructure by reserving altitude test facility slots through multi-year scheduling commitments. For New Entrants and Emerging Players: Digital engineering subcontracting offers the most penetrable entry vector under the US Department of Defense's Model-Based Systems Engineering directive, bypassing security clearance bottlenecks that constrain hardware prime access. Target software and simulation opportunities in guidance algorithm validation and digital twin verification rather than competing directly on propulsion hardware. Establish partnerships with national laboratories like Sandia and Los Alamos to build flight-test credibility without prime contractor infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in prime contractor acquisition of specialized subsystem suppliers with proven security clearances and nuclear command continuity infrastructure. Long-term viability hinges on sustained appropriations through nuclear triad modernization cycles insulated from conventional defense budget volatility. Monitor Vandenberg Space Force Base and Pacific Test Range scheduling conflicts between ICBM and hypersonic programs as the critical inflection signal for qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oxidizer Production | Captive ammonium perchlorate supply eliminates single-point vulnerability for solid propellant motors. |
| Digital Engineering Capability Acquisition | Model-Based Systems Engineering expertise opens fixed-price subcontractor opportunities outside traditional hardware primes. |
| Test Range Capacity Reservation | Multi-year scheduling commitments at Arnold Air Force Base preempt hypersonic program queue congestion. |
| Carbon-Carbon Nozzle Apprenticeship Pipeline | Specialized fabrication expertise transfer mitigates retiring technician concentration risk. |
| Orbital Payload Conversion Partnership | NASA and Space Force agreements monetize decommissioned Minuteman III booster surplus. |
Study Parameters
Independent corroboration across prime contractor engineering executives, national laboratory qualification directors, and Defense Contract Management Agency procurement officers underwrites the qualitative findings on fixed-price contract migration. Secondary validation draws from US Department of Defense budget justification materials, EPA hazardous material handling enforcement records, and China's State Administration for Science, Technology and Industry for National Defense procurement disclosures. Bottom-up segment sizing triangulates against top-down nuclear triad modernization appropriation trends.
Comparable-period anchoring to Minuteman III deployment cycles and Peacekeeper retirement timelines structured the forecast window across the projection horizon. Segmentation modeling incorporates propulsion architecture, mission profile certification, and end-user contracting authority dimensions. CAGRs derive from procurement volume trajectories adjusted for test range capacity constraints and security clearance pipeline bottlenecks. Hypersonic glide vehicle program competition for identical engineering talent and infrastructure feeds into scenario-weighted outputs.
The model holds under sustained nuclear triad modernization appropriations; deviation in congressional budget authority allocation or treaty constraint imposition would shift the outlook materially. Deviation in ammonium perchlorate facility operational status or EPA enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Anti-Tank Missile System Market
Weapons and Ammunition
North Korea Nuclear Bombs and Missiles Market
Weapons and Ammunition
Global Small Arms and Light Weapons (SALW) Market
Weapons and Ammunition
North America Ammunition Market
Weapons and Ammunition
Light Weapons Market
Weapons and Ammunition
Aircraft Weapons Market
Weapons and Ammunition
Smoke Grenade Market
Weapons and Ammunition
Asia-Pacific Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Military Fuze Market
Weapons and Ammunition
Americas Ballistic Missile Market
Weapons and Ammunition
Riflescope Market
Weapons and Ammunition
Explosives for Civil Uses Market
Weapons and Ammunition
Americas Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Airborne Weapon System Market
Weapons and Ammunition
Weapons Carriage and Release System Market
Weapons and Ammunition
Close-In Weapon Systems Market