
 Smart Bullets Market | 2026-2036
Smart Bullets Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Bullets Market Intelligence
Carbon-fiber composite casings is repositioning smart bullet economics by reducing unit weight while maintaining barrel-pressure tolerance. Lockheed Martin leverages in-house guidance-chip fabrication to protect margin pools on GPS-enabled rounds. Raytheon Technologies sustains dual-source sensor supply chains across its precision-effects division. BAE Systems anchors European sovereign production through UK and Swedish assembly lines.
Smart bullets are self-steering projectiles incorporating microprocessors, aerodynamic control surfaces, and real-time guidance algorithms to correct trajectory mid-flight toward designated targets. Typical systems operate at muzzle velocities exceeding Mach 2 while maintaining electronic stability against rotational forces exceeding 300,000 G. Guided Bullets command the largest current revenue share due to established military procurement pathways for sniper and designated-marksman applications. Wireless Communication and Smart Targeting technologies are expanding fastest as forces demand networked fire-and-adjust capabilities against mobile targets. Margin pools concentrate in infrared-tracking and miniaturized-sensor configurations where component scarcity limits vendor entry.
The US Department of Defense, NATO Standardization Office, and EU Green Deal frameworks collectively shape product standards, with the US DoD mandating interoperable datalinks and REACH-derived substance restrictions affecting propellant chemistry. Export-control regimes under ITAR and Wassenaar Arrangement categories constrain cross-border technology transfer for guidance electronics. Stakeholders must monitor divergence between US ITAR-controlled architectures and emerging European sovereign-guidance specifications when allocating R&D funding.
Market Dynamics
Carbon-fiber composite casings are compressing unit economics while NATO procurement mandates for precision-guided munitions accelerate sensor miniaturization timelines across defense supply chains.
Growth Catalysts
- ITAR-compliant datalink mandates:US DoD interoperability requirements are standardizing encrypted communication protocols across allied procurement programs, expanding addressable vendor pools.
- Urban combat doctrine evolution:NATO member state defense agencies are prioritizing collateral-damage reduction in dense operational environments, pulling demand for real-time trajectory correction.
- Miniaturized MEMS gyroscopes:Silicon fabrication advances are enabling guidance-chip production at tactical-round scale, collapsing previous size constraints on projectile electronics.
Market Restraints
- Guidance electronics export controls:Wassenaar Arrangement Category VIII restrictions fragment R&D collaboration between US and European engineering teams.
- Rare-earth magnet supply concentration:Neodymium-dysprosium sourcing dependencies in East Asian processing facilities expose actuator production to geopolitical disruption.
- Propellant chemistry substance restrictions:REACH-derived limitations on nitrocellulose stabilizers are forcing reformulation of established NATO-standard round compositions.
Strategic Opportunities
- Swedish sovereign production lines:BAE Systems' UK-Sweden assembly network offers European vendors a compliance pathway outside direct ITAR jurisdiction.
- Networked fire-and-adjust protocols:Wireless communication modules enabling real-time target handoff between spotters and shooters represent unpenetrated capability layers.
- Infrared-tracking configuration scarcity:Miniaturized thermal sensor production bottlenecks create margin capture potential for vendors with captive semiconductor fabrication.
Industry Challenges
- Rotational force engineering talent:Specialists capable of designing electronics stable beyond 300,000 G remain concentrated in legacy aerospace programs.
- Multi-source sensor qualification timelines:Dual-source supply chain validation for precision-effects divisions extends certification cycles by 18-24 months.
- Legacy mechanical fusing integration:Hybrid systems bridging traditional and smart architectures introduce failure-mode complexity during field deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Bullets Market |
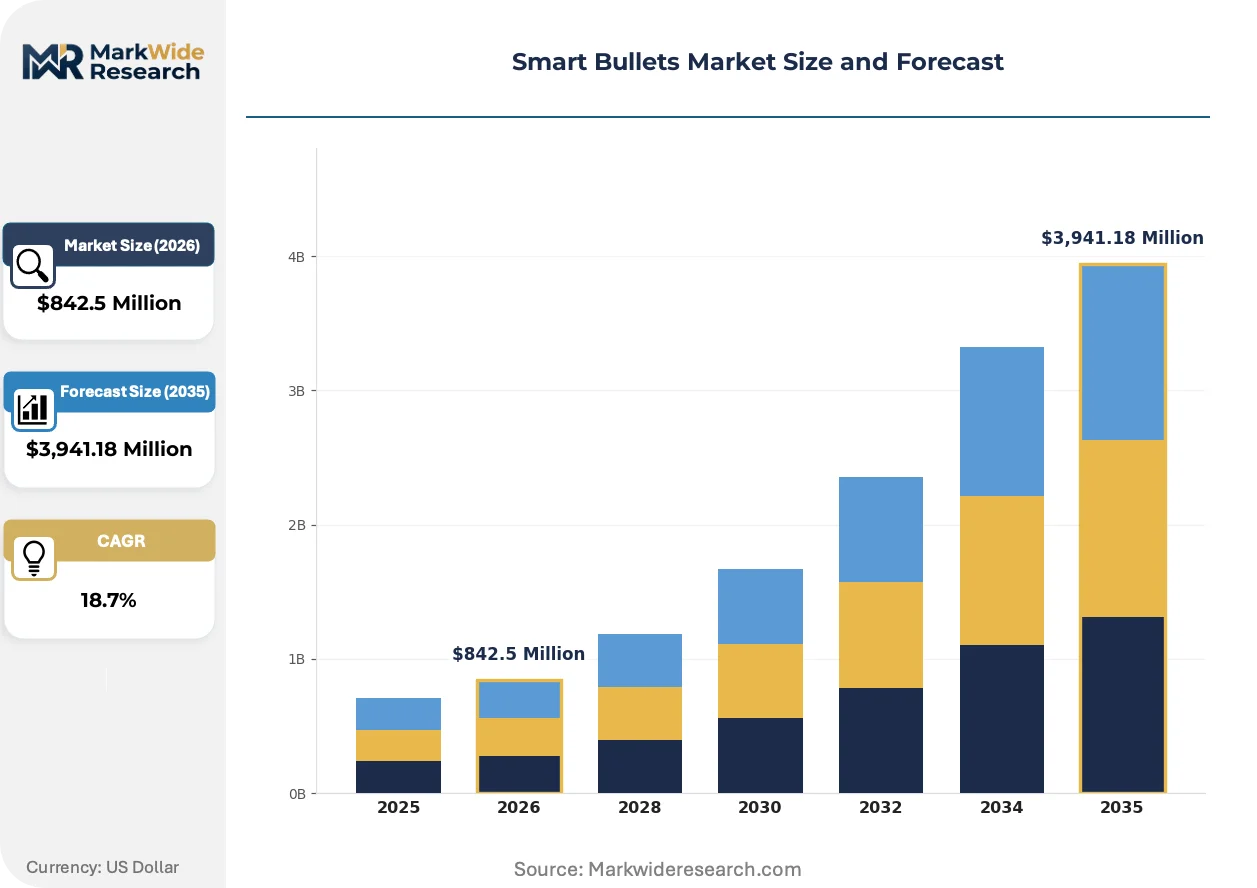
| Market Size in 2026 | $842.5 Million |
| Market Size in 2035 | $3,941.18 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Guided Bullets, Tracking Bullets, Explosive Bullets, Non-Lethal Bullets, Armor-Piercing Bullets Technology: GPS Guidance, Infrared Tracking, Wireless Communication, Miniaturized Sensors, Smart Targeting Application: Military Operations, Law Enforcement, Counterterrorism, Security Forces, Tactical Training End User: Defense Agencies, Paramilitary Units, Border Control, Private Security, Special Forces |
| Companies Covered | Lockheed Martin Corporation, Raytheon Technologies Corporation, Northrop Grumman Corporation, BAE Systems plc, Thales Group, General Dynamics Corporation, L3Harris Technologies, Inc., Leonardo S.p.A, Elbit Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Bullets Market Strategic Shifts & Innovations
Real-time guidance algorithms and aerodynamic control surfaces are converging to enable mid-flight trajectory correction against mobile targets, compressing the kill-chain timeline for designated marksman applications.
Microelectromechanical systems is integrating silicon-based inertial measurement units directly onto projectile bodies. Defense procurement programs in NATO member states are accelerating adoption of these guidance-chip configurations. This integration is compressing the minimum viable caliber for smart functionality from 12.7mm toward 7.62mm platforms.
REACH-derived substance restrictions are forcing propellant chemistry reformulation across European supply chains. Industrial consequence includes accelerated R&D spending on nitrogen-rich energetic materials compliant with EU Green Deal frameworks. Precision-effects divisions with in-house propellant laboratories are responding by verticalizing formulation capabilities.
Buyer concentration around US Department of Defense and NATO Standardization Office procurement is compressing vendor qualification timelines. Traditional multi-year field-testing protocols are yielding to simulation-validated rapid certification for urgent operational requirements. This behavioral shift is most visible in urban combat scenario procurement where collateral-damage constraints override legacy evaluation cycles.
Smart Bullets Market Segmentation
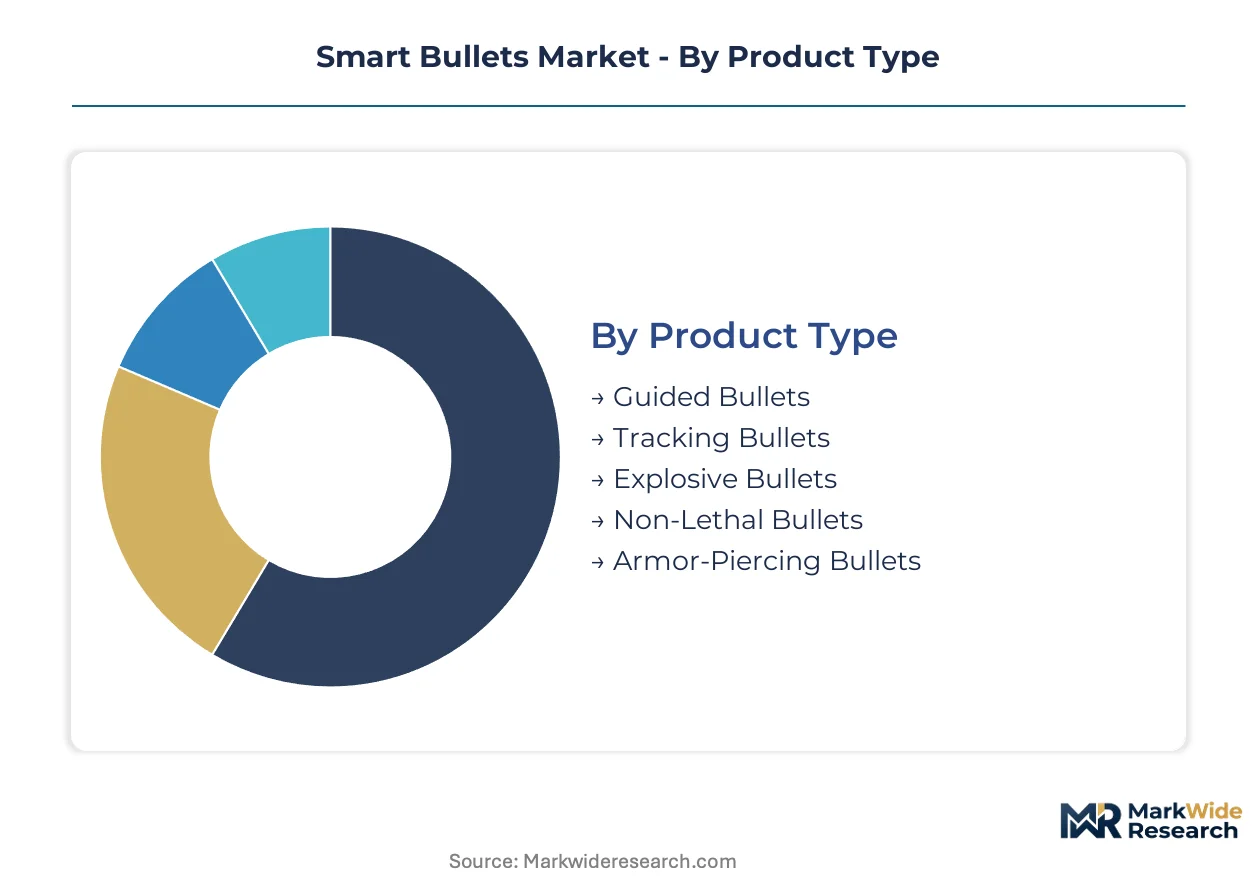
Smart bullet architectures fragment across precision requirements, target profiles, and operational constraints. Procurement patterns diverge sharply between established military programs and emerging tactical applications. Each segmentation axis reveals distinct margin structures and vendor qualification barriers.
Product Type:
Volume concentration favors proven guidance platforms while premium capture gravitates toward specialized effectors with restricted field deployment.
- Guided Bullets:Self-steering projectiles incorporate microprocessors and aerodynamic control surfaces to correct trajectory mid-flight. US Department of Defense procurement pathways for sniper and designated-marksman applications concentrate demand here, with NATO standardization accelerating vendor qualification timelines. Mature deployment sits with Guided Bullets. Newer deployment is concentrated in Tracking Bullets.
- Tracking Bullets:Embedded telemetry systems relay real-time position data to fire-control networks, enabling shoot-and-adjust protocols against mobile targets. Wireless communication modules for networked spotter-shooter coordination are climbing the fastest as urban combat doctrine evolves.
- Explosive Bullets:Programmable fusing enables airburst or delayed detonation against concealed positions.
- Non-Lethal Bullets:Kinetic or chemical payloads designed for incapacitation without lethal force.
- Armor-Piercing Bullets:Tungsten or depleted-uranium penetrators with guidance augmentation for hardened target engagement.
Cost tiering separates precision-guided platforms from effector-specialized variants with narrower addressable markets.
Technology:
Application context determines sensor modality selection, with networked operations demanding interoperable datalink architectures.
- GPS Guidance:Satellite-referenced positioning enables fire-and-forget engagement against static coordinates. In-house guidance-chip fabrication at major defense primes protects margin pools on GPS-enabled rounds through supply chain control.
- Infrared Tracking:Miniaturized thermal sensors enable passive target acquisition in low-visibility conditions. Component scarcity in captive semiconductor fabrication creates margin capture potential for qualified vendors.
- Wireless Communication:Encrypted datalinks enable real-time target handoff and trajectory adjustment.
- Miniaturized Sensors:MEMS-based inertial measurement units replace mechanical fusing systems.
- Smart Targeting:Multi-sensor fusion algorithms integrate heterogeneous tracking inputs.
Procurement prioritization favors GPS-enabled platforms for volume contracts. Capability gaps concentrate in infrared-tracking configurations with limited qualified suppliers.
Application:
Operational environment dictates collateral-damage constraints and rules-of-engagement flexibility.
- Military Operations:Conventional force-on-force engagement with full precision-effects authorization. NATO member state defense agencies are expanding procurement for urban combat scenarios with strict collateral-damage reduction mandates.
- Counterterrorism:Time-sensitive targeting against high-value individuals in denied environments. Specialized unit procurement bypasses standard acquisition timelines for urgent operational requirements.
- Law Enforcement:Domestic deployment with elevated scrutiny on use-of-force protocols.
- Security Forces:Critical infrastructure protection and VIP security details.
- Tactical Training:Simulation-validated certification rounds with telemetry feedback.
Established doctrine anchors Military Operations procurement. Fastest capability evolution is visible in Counterterrorism applications with compressed kill-chain requirements.
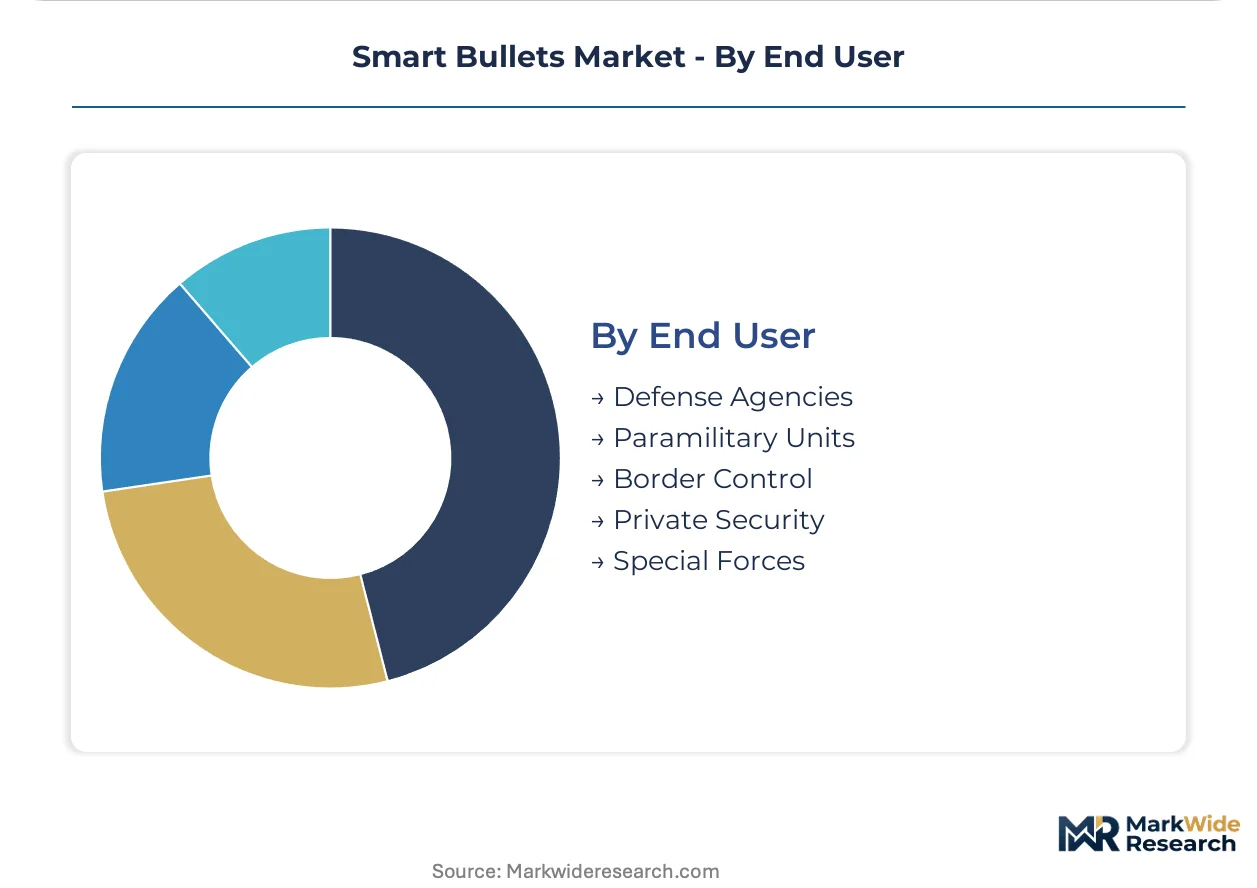
End User:
Budget scale and operational autonomy determine access to restricted guidance technologies.
- Defense Agencies:National military establishments with sovereign procurement authority. US Department of Defense concentration shapes vendor R&D priorities through ITAR-compliant datalink mandates and interoperability requirements.
- Special Forces:Units with delegated acquisition authority for mission-specific equipment. Rapid fielding protocols compress multi-year testing cycles for urgent capability gaps.
- Paramilitary Units:State-affiliated forces with limited access to export-controlled technologies.
- Border Control:Interdiction-focused operations with rules-of-engagement constraints.
- Private Security:Commercial entities restricted to non-lethal or training configurations.
Technology access stratifies sharply between sovereign defense agencies and sub-state end users subject to export control fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement for precision-guided munitions concentrates heavily in the United States, with NATO allies following at scaled-down commitment levels. Urban combat doctrine evolution across allied forces is accelerating sensor miniaturization investments in specific national industrial bases.
United States
The US Department of Defense drives procurement volume through ITAR-compliant datalink mandates and sniper-system modernization programs. The International Traffic in Arms Regulations constrain technology transfer while standardizing encrypted protocols across allied programs. Tucson, Arizona and Dallas-Fort Worth host precision-effects manufacturing clusters where guidance-chip fabrication facilities are expanding capacity.
United Kingdom
British defense procurement prioritizes sovereign production capabilities for designated-marksman applications under Ministry of Defence urgent capability requirements. REACH-derived substance restrictions are forcing propellant chemistry reformulation at BAE Systems' assembly lines. Stevenage and Glasgow anchor guidance-system engineering clusters with expanding MEMS gyroscope integration programs.
Sweden
Swedish defense materiel administration procurement offers European vendors ITAR-independent compliance pathways for precision-guided munitions. EU Green Deal frameworks are accelerating nitrogen-rich energetic materials R&D at national propellant laboratories. Linköping's aerospace engineering cluster hosts BAE Systems-Saab collaborative production lines for networked fire-and-adjust protocols.
Germany
German defense procurement through the Federal Office of Bundeswehr Equipment prioritizes collateral-damage reduction for urban combat scenarios. KBA oversight intersects with REACH restrictions on nitrocellulose stabilizers, forcing reformulation of NATO-standard compositions. Oberndorf am Neckar's precision-engineering cluster concentrates mechanical-to-smart fusing hybrid system development.
Israel
Israeli defense procurement emphasizes time-sensitive targeting against mobile targets in denied environments with compressed kill-chain requirements. Ministry of Defense rapid fielding protocols bypass standard acquisition timelines for urgent operational needs. Haifa's defense technology cluster concentrates infrared-tracking sensor miniaturization for thermal acquisition systems.
Smart Bullets Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with defense primes commanding integrated-system procurement while component vendors capture sensor and guidance-chip niches. The vendor base concentrates around aerospace-defense conglomerates with in-house fabrication capabilities, creating tiered qualification barriers for new entrants. Two strategic archetypes dominate: vertically integrated primes with captive semiconductor production, and specialized sensor vendors with MEMS fabrication expertise. Competitive dynamics center on dual-source supply chain validation and sovereign production line establishment.
Within the prime-contractor tier, Lockheed Martin Corporation and Raytheon Technologies Corporation exemplify integrated-systems positioning through in-house guidance-chip capabilities. BAE Systems plc occupies a distinct geography-focused archetype, anchoring European sovereign production outside direct ITAR jurisdiction through UK-Sweden assembly networks. These three entities represent contrasting strategic postures: captive fabrication control, multi-source sensor supply chains, and regional compliance pathway development.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Raytheon Technologies Corporation |
| Northrop Grumman Corporation |
| BAE Systems plc |
| Thales Group |
| General Dynamics Corporation |
| L3Harris Technologies, Inc. |
| Leonardo S.p.A |
| Elbit Systems Ltd. |
| Others |
Cost & Logistics Intelligence
Captive guidance-chip fabrication at Lockheed Martin and Raytheon Technologies anchors both supply security and premium pricing power for GPS-enabled rounds, insulating these primes from component scarcity that compresses margins for assembly-dependent vendors.
Pricing Analysis
Volume procurement concentrates in GPS-enabled platforms with standardized NATO datalinks, while margin capture gravitates toward infrared-tracking configurations where miniaturized thermal sensor scarcity limits qualified suppliers. Price differentiation separates ITAR-compliant US architectures from European sovereign-guidance specifications, with the latter commanding modest premiums for compliance-pathway certainty. Pricing pressure stems from REACH-derived propellant reformulation costs passing through European supply chains. Defense agencies exhibit lowest price sensitivity for urgent operational requirements, while paramilitary units face constrained budgets for export-controlled technologies.
Supply Chain Analysis
Rare-earth magnet supply rests on East Asian neodymium-dysprosium processing facilities concentrated in China and Japan, exposing actuator production to geopolitical disruption. Guidance electronics draw from US and Israeli semiconductor fabrication clusters, with MEMS gyroscope silicon wafers sourced from Taiwan and South Korea. Single-source vulnerability concentrates in miniaturized infrared sensor die production. Distribution runs through prime-contractor direct sales to defense agencies, bypassing traditional distribution channels for ITAR-controlled architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ITAR and Wassenaar Arrangement Category VIII restrictions create barrier-to-entry moats for vendors with established export-control infrastructure.
For Market Incumbents: Deepen captive semiconductor fabrication capabilities to defend margin pools against emerging MEMS specialists. Lock in dual-source sensor qualification timelines ahead of NATO standardization acceleration. Prioritize Swedish sovereign production line expansion to capture European procurement outside direct US jurisdiction.
For New Entrants and Emerging Players: Begin with wireless communication module development for networked fire-and-adjust protocols, the fastest-expanding capability layer with limited incumbent lock-in. Target counterterrorism applications where rapid fielding protocols compress multi-year testing cycles. Pursue joint development agreements with BAE Systems' UK-Sweden network for ITAR-independent market access.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by aerospace-defense conglomerates seeking MEMS fabrication expertise. Long-term viability favors vendors with in-house propellant laboratories navigating REACH reformulation mandates. Watch Swedish defense materiel administration procurement volumes as inflection indicator for European sovereign-guidance specification adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Guidance-Chip Fabrication Expansion | Captive silicon production at Lockheed Martin protects margin pools from component scarcity. |
| Dual-Source Sensor Qualification | Raytheon Technologies validates alternative MEMS suppliers against NATO interoperability mandates. |
| Sovereign Production Line Establishment | BAE Systems' UK-Sweden assembly network offers European compliance outside ITAR jurisdiction. |
| Wireless Communication Module Development | Networked fire-and-adjust protocols enable real-time spotter-shooter coordination for urban combat. |
| Propellant Chemistry Reformulation | Nitrogen-rich energetic materials R&D responds to REACH restrictions on nitrocellulose stabilizers. |
Research Approach
Independent corroboration across defense procurement officers, precision-effects division executives, MEMS fabrication engineers, and export-control compliance specialists underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation from ITAR filing databases, NATO standardization office documentation, EU Green Deal regulatory filings, and customs trade records for rare-earth magnet flows. Bottom-up vendor capacity assessments triangulated against top-down defense budget allocation analysis.
Comparable-period anchoring to historical procurement cycles informed the projection horizon, with segmentation modeling across product type, technology modality, application context, and end-user budget tier. CAGRs derived from weighted average of vendor shipment forecasts and defense agency modernization program timelines. Industry-specific inputs included MEMS gyroscope miniaturization curves and propellant chemistry reformulation cost trajectories.
Export-control regime expansion, rare-earth supply disruption, and urban combat doctrine revision are the dominant revision risks. Forecasts reflect documented assumptions on NATO procurement acceleration and REACH enforcement consistency. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Vehicle Mounted Anti-Tank Missile System Market
Weapons and Ammunition
Small and Medium Caliber Ammunition Market
Weapons and Ammunition
Mortar Ammunition Market
Weapons and Ammunition
Less Lethal Ammunition Market
Weapons and Ammunition
Global Submarine Launched Missile Market
Weapons and Ammunition
Ballistic Composite Market
Weapons and Ammunition
Intercontinental Ballistic Missile Market
Weapons and Ammunition
NATO Ammunition Market
Weapons and Ammunition
Missile Launching Systems Market
Weapons and Ammunition
Global Artillery Systems Market
Weapons and Ammunition
Military Fire Control Systems Market
Weapons and Ammunition
Weapons Release System Market
Weapons and Ammunition
Surface to Air Missiles Market
Weapons and Ammunition
Precision Guided Munition Market
Weapons and Ammunition
Aircraft Weapons Market
Weapons and Ammunition
North Korea Nuclear Bombs and Missiles Market