
 Cruise Missile Market | 2026-2036
Cruise Missile Market Size, Share, and Industry Trends Forecast 2026-2036
Cruise Missile Market Intelligence
The capability gap between prime contractors and emerging defense technology entrants is collapsing as software-defined architectures lower barriers to propulsion and guidance integration. Lockheed Martin Corporation leverages decades of turbofan propulsion expertise to sustain long-range strike contracts across multiple service branches. Anduril Industries competes through rapid software iteration and modular payload designs that challenge traditional development cycles.
A cruise missile is a self-propelled, precision-guided munition that maintains sustained flight through aerodynamic lift, typically employing turbojet or turbofan engines to achieve ranges exceeding 500 kilometers while navigating via GPS, inertial, or terrain-matching guidance systems. Its primary purpose is to deliver conventional or strategic warheads against defended targets with minimal platform exposure. The hypersonic type segment commands premium development budgets despite technical immaturity, while loitering systems attract asymmetric warfare investment. Ground-based platforms dominate procurement volumes, though airborne launch configurations retain higher per-unit pricing.
The US Department of Defense, NATO standardization bodies, and the Missile Technology Control Regime collectively shape market access through end-use monitoring, interoperability mandates, and export control classifications that restrict propulsion and guidance technology transfer. Compliance with these frameworks determines supplier eligibility for allied procurement programs and foreign military sales channels. Stakeholders must monitor evolving autonomous targeting policies and counter-proliferation enforcement to anticipate program cancellations or accelerated funding reallocations.
Market Dynamics
Autonomous targeting architectures are compressing development cycles and collapsing the traditional prime-subcontractor hierarchy as software-defined systems permit rapid capability iteration outside legacy defense procurement channels.
Growth Catalysts
- US National Defense Authorization Act:Multi-year munitions procurement commitments under the NDAA are locking in sustained production volumes for long-range strike platforms across Pacific theater basing requirements.
- Naval strike platforms:Surface combatant and submarine launch integration programs are expanding the addressable platform base beyond legacy airborne configurations.
- Loitering munitions:Asymmetric warfare investment flows from contested-area denial strategies are creating parallel demand streams for expendable precision systems.
Market Restraints
- Turbofan propulsion supply concentration:Specialized engine manufacturing capacity clusters in a limited supplier base, creating single-source vulnerability for extended-range programs.
- Missile Technology Control Regime:MTCR Category I restrictions on 500 kg/300 km thresholds block technology transfer to non-signatory states, fragmenting addressable export markets.
- Hypersonic technical immaturity:Thermal management and atmospheric flight control limitations delay operational deployment timelines despite premium budget allocation.
Strategic Opportunities
- Modular payload architectures:Software-defined seeker and warhead integration permits mission-specific reconfiguration without platform redesign, opening multi-role contract opportunities.
- NATO interoperability mandates:Standardized datalink and targeting protocols under allied procurement frameworks create cross-border supply eligibility for certified integrators.
- Ground-based platform expansion:Mobile coastal defense and land-attack systems represent underpenetrated application segments with shorter procurement cycles than airborne programs.
Industry Challenges
- Guidance algorithm validation:Autonomous target recognition systems face extended operational test and evaluation timelines under evolving rules of engagement protocols.
- Legacy platform integration:Retrofitting fourth-generation aircraft with modern cruise missile interfaces requires airframe structural modifications that compress mission radius.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cruise Missile Market |
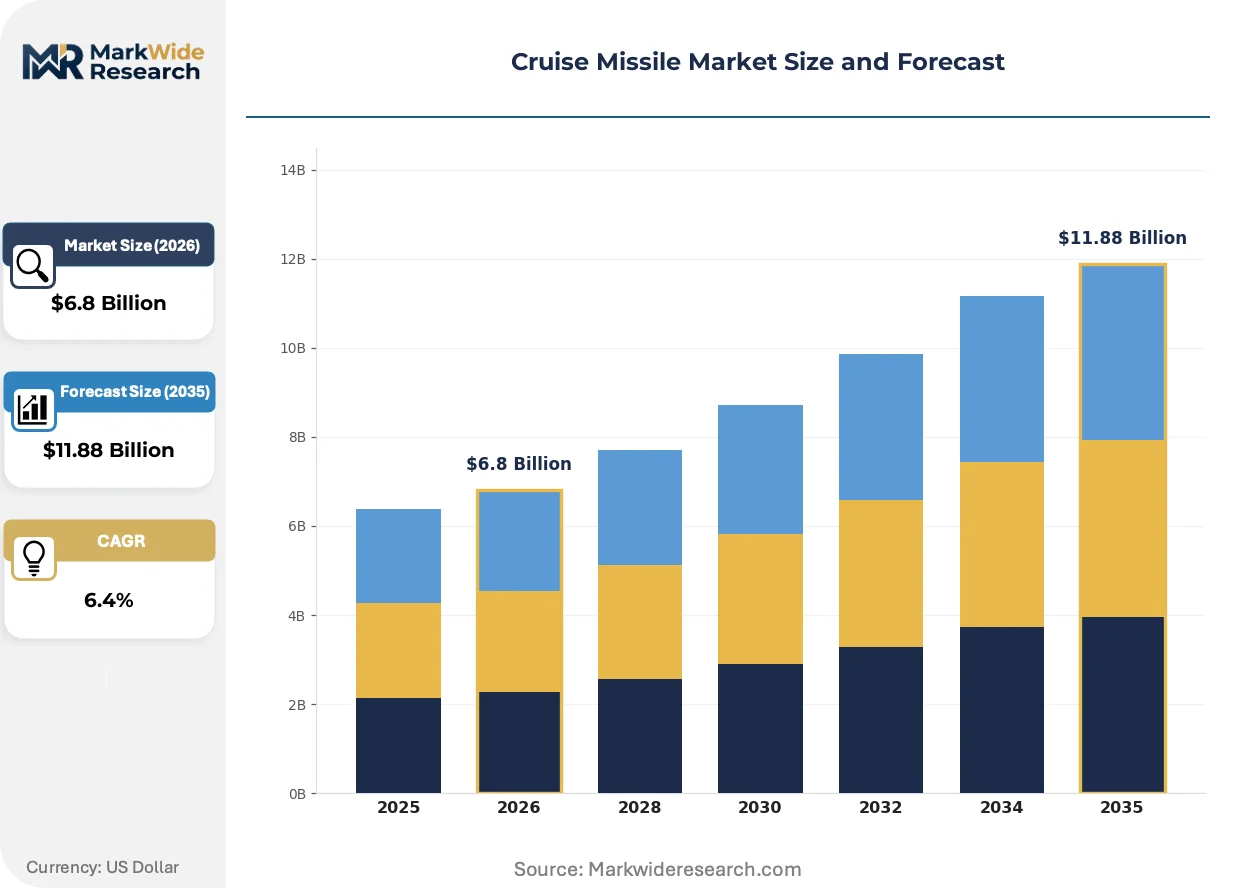
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Subsonic, Supersonic, Hypersonic, Loitering Platform: Airborne, Naval, Ground-based, Space-based Propulsion: Turbojet, Turbofan, Ramjet, Rocket Guidance: GPS, Inertial, Terrain Contour Matching, Command Guidance |
| Companies Covered | Northrop Grumman Corporation, BAE Systems plc, Lockheed Martin Corporation, Saab AB, Anduril Industries, Raytheon Technologies Corporation, MBDA Missile Systems, RTX Corporation, The Boeing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cruise Missile Market Strategic Shifts & Innovations
Software-defined guidance systems are severing the historical link between airframe design cycles and capability refresh, enabling functional upgrades through firmware rather than hardware replacement.
Multi-mode seekers combining electro-optical, synthetic aperture radar, and passive radio-frequency sensing are supplanting single-sensor architectures in next-generation programs. Naval aviation procurement offices are mandating fused-sensor capability for contested electronic warfare environments. This convergence is compressing the sensor-to-shooter timeline while elevating software verification burdens above hardware qualification costs.
The US Department of Defense's autonomous weapons policy framework under the NDAA is imposing human-machine interface requirements that extend development timelines for full-autonomy targeting modes. Prime contractors must demonstrate meaningful human control protocols before operational release. Strike platform programs are responding by bifurcating procurement into human-in-the-loop and human-on-the-loop variants with differentiated capability ceilings.
Allied nations are consolidating munitions procurement through NATO Support and Procurement Agency frameworks, displacing bilateral foreign military sales channels for standard cruise missile categories. Denmark, Norway, and the Netherlands are pooling acquisition volumes for naval strike variants. This aggregation is concentrating contract awards on vendors with established NATO interoperability certifications while excluding emerging entrants lacking allied test range access.
Cruise Missile Market Segmentation
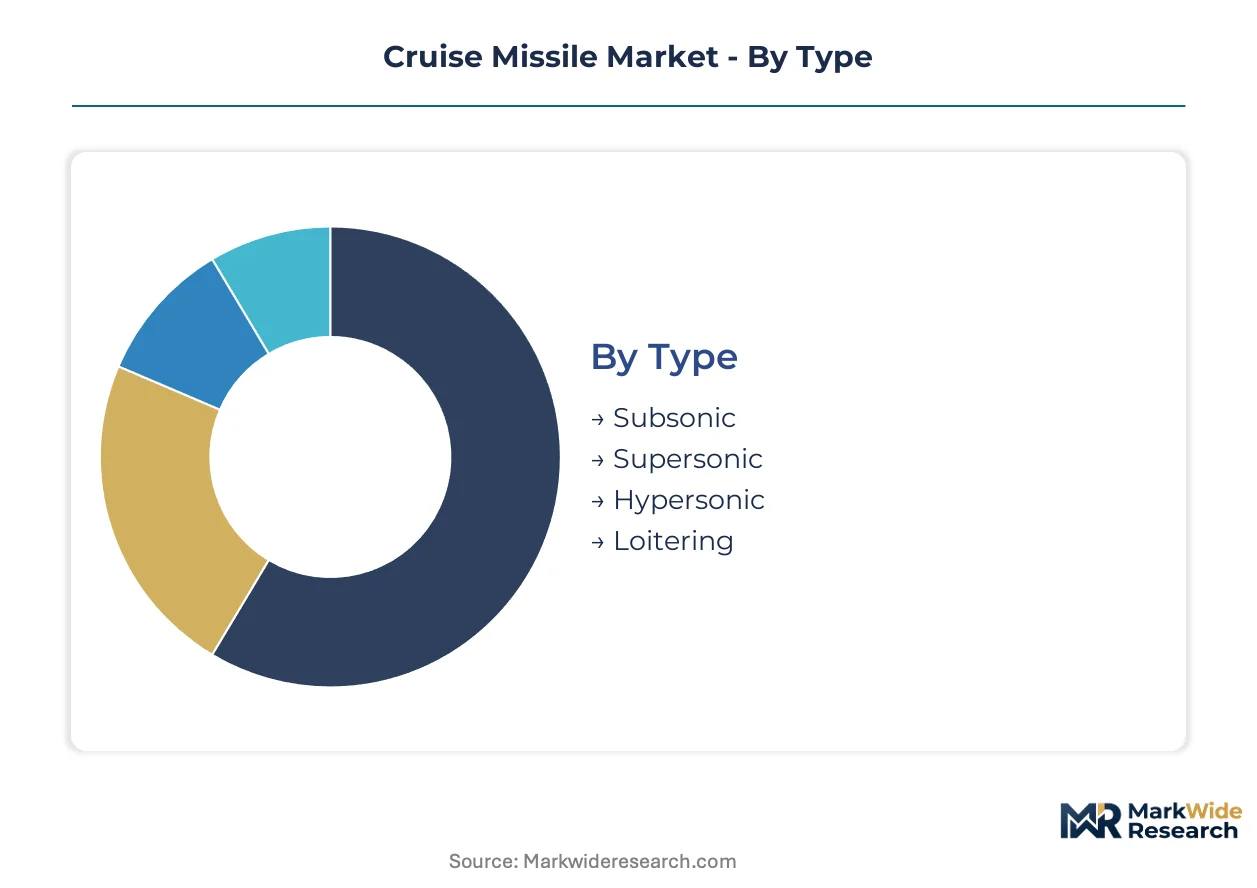
Cruise missile procurement patterns diverge sharply across performance tiers and launch configurations. Segment boundaries reflect distinct engineering requirements, regulatory thresholds, and operational doctrines that shape supplier specialization and contract award criteria.
Type:
Domestic procurement concentrates in subsonic and loitering variants for Pacific theater basing, while hypersonic development attracts classified budget allocation with restricted export eligibility.
- Subsonic:Turbofan-powered systems cruise at Mach 0.8-0.9, optimizing fuel efficiency for ranges exceeding 1,500 kilometers. US Navy and Air Force multi-year procurement commitments under NDAA Title I prioritize these platforms for anti-ship and land-attack missions across Indo-Pacific operating areas.
- Hypersonic:Scramjet or boost-glide vehicles operating above Mach 5 face thermal management and atmospheric control barriers that delay operational deployment. DARPA and Air Force Research Laboratory funding dominates development, with allied access limited by MTCR Category I thresholds and bilateral technology protection agreements.
- Supersonic:Ramjet-assisted systems bridge speed-range tradeoffs for time-sensitive targeting.
- Loitering:Expendable platforms with electro-optical terminal guidance attract asymmetric warfare investment from contested-area denial strategies.
Subsonic holds the largest share; momentum sits with Loitering.
Platform:
Cost tier separation distinguishes strategic airborne programs from tactical ground-based systems with shorter procurement cycles.
- Naval:Vertical launch system integration on Arleigh Burke-class destroyers and Virginia-class submarines expands the addressable platform base beyond legacy air-launched configurations. Surface combatant procurement under the US Navy's Shipbuilding and Conversion budget line drives volume concentration.
- Ground-based:Mobile coastal defense and land-attack systems employ containerized launchers for rapid repositioning. Polish and Romanian procurement under NATO's Enhanced Forward Presence framework exemplifies demand concentration in frontline allied states.
- Airborne:Integration with fifth-generation fighters and strategic bombers retains premium per-unit pricing through complex interface certification.
- Space-based:Orbital deployment concepts remain experimental, constrained by Outer Space Treaty interpretations and atmospheric re-entry thermal loads.
Airborne retains the highest contract values; ground-based systems are climbing the fastest.
Propulsion:
Supply concentration in specialized engine manufacturing creates single-source vulnerability for extended-range programs.
- Turbofan:Small-diameter turbofans with high bypass ratios deliver optimal thrust-specific fuel consumption for subsonic endurance missions. Williams International and Technical Directions Incorporated dominate domestic supplier base concentration, with allied nations dependent on foreign military sales channels for engine access.
- Ramjet:Airbreathing supersonic propulsion eliminates compressor machinery, reducing mass for high-speed intercept profiles. Russian and Chinese indigenous development programs challenge Western technical leadership in integrated inlet-combustor design.
- Turbojet:Simpler single-spool architectures persist in legacy platform sustainment and lower-tier export variants.
- Rocket:Solid-propellant boosters provide initial acceleration for boost-glide hypersonic vehicles and short-range tactical systems.
Turbofan holds the largest share; ramjet investment shows steepest expansion trajectory.
Guidance:
Customer type segmentation separates precision-strike militaries from asymmetric operators with limited satellite access.
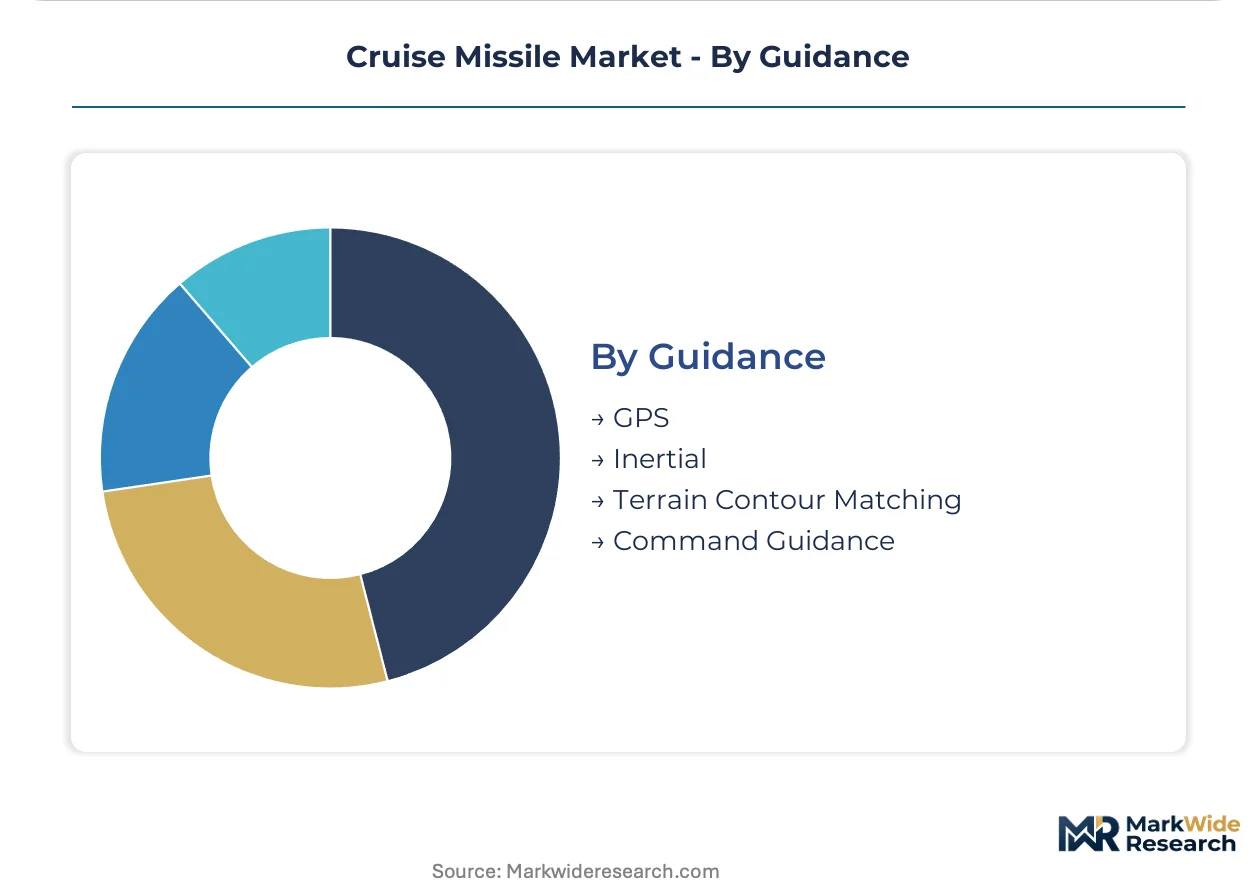
- GPS:Satellite-aided navigation with military-code signal encryption enables meter-level accuracy in benign electronic warfare environments. Jamming vulnerability in contested theaters drives multi-mode seeker integration requirements under US Navy and Air Force operational test protocols.
- Multi-mode fusion:Electro-optical, synthetic aperture radar, and passive radio-frequency sensing convergence addresses GPS denial scenarios. NATO standardization bodies mandate interoperable datalink protocols for allied combined arms operations.
- Inertial:Ring laser gyro and fiber-optic gyro systems provide navigation continuity during satellite signal interruption.
- Terrain Contour Matching:Radar altimeter correlation with digital elevation models enables covert low-level penetration in GPS-denied conditions.
- Command Guidance:Man-in-the-loop control persists in loitering munitions and restricted-rules-of-engagement scenarios.
GPS holds the largest share; multi-mode fusion is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates procurement in long-range subsonic platforms for Pacific theater deterrence, while European allies prioritize shorter-range coastal defense systems under NATO interoperability mandates. This consumption-mix differential reflects divergent operational doctrines and threat geometries across theaters.
United States
Pacific theater basing requirements and multi-year munitions procurement commitments under the NDAA drive sustained production volumes. The Department of Defense's autonomous weapons policy framework imposes human-machine interface requirements that extend development timelines. Prime contractors cluster around Washington D.C. corridor and California defense technology clusters, where software-defined guidance development accelerates capability iteration cycles.
United Kingdom
Naval strike platform integration programs for Astute-class submarines and Type 45 destroyers expand the addressable platform base. The Ministry of Defence's procurement through NATO Support and Procurement Agency frameworks displaces bilateral foreign military sales channels. MBDA Missile Systems' facilities in Stevenage and Bolton anchor domestic propulsion and guidance integration capabilities for allied standardization.
France
Independent nuclear deterrence requirements sustain investment in sea-launched cruise missile variants with restricted export eligibility. The Direction Générale de l'Armement enforces technology protection agreements that limit allied access to scramjet and boost-glide development programs. Industrial concentration in the Île-de-France region around MBDA's Paris headquarters supports sovereign capability maintenance.
Germany
Enhanced Forward Presence commitments under NATO's eastern flank posture drive mobile ground-based coastal defense procurement. The Federal Office of Bundeswehr Equipment, Information Technology and In-Service Support mandates interoperability certifications for cross-border supply eligibility. Defense technology clusters in Bavaria and Baden-Württemberg host subsystem suppliers for turbofan propulsion and inertial guidance components.
Japan
Counter-strike capability acquisition under revised defense guidelines prioritizes extended-range platforms for contested-area denial strategies. The Ministry of Defense's equipment procurement agency consolidates munitions acquisition through multi-year contracts with US foreign military sales channels. Industrial partnerships in the Kanto region around Tokyo integrate US guidance systems with domestic airframe manufacturing.
Cruise Missile Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with consolidation concentrated in turbofan propulsion and multi-mode seeker integration. The upper tier commands long-range strike contracts through decades of airframe certification heritage, while mid-tier entrants compete on software iteration velocity and modular payload architectures. Three archetypes dominate: legacy prime contractors with turbofan expertise, software-native challengers with rapid development cycles, and European consortium structures with NATO interoperability certifications. Competitive dynamics center on strategic partnerships for propulsion supply security and technology licensing for guidance algorithm access.
Among US-based integrated primes, Lockheed Martin Corporation and Raytheon Technologies Corporation exemplify the established tier with sustained multi-service branch contract positions. Anduril Industries occupies a challenger position within the software-native archetype, representing rapid iteration approaches that compress traditional development timelines. These three anchors illustrate the structural tension between certification heritage and development velocity that shapes program award criteria.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| BAE Systems plc |
| Lockheed Martin Corporation |
| Saab AB |
| Anduril Industries |
| Raytheon Technologies Corporation |
| MBDA Missile Systems |
| RTX Corporation |
| The Boeing Company |
| Others |
Cost & Logistics Intelligence
Eighteen-to-twenty-four-month engine procurement lead times for specialized turbofan propulsion systems concentrate pricing power with Williams International and Technical Directions Incorporated, compressing margin flexibility for airframe integrators dependent on sole-source supply.
Pricing Analysis
Multi-year offtake agreements under NDAA Title I procurement commitments dominate contract structures, locking unit economics across Pacific theater production runs. Three-tier pricing stratifies across human-in-the-loop certified variants, standard GPS-guided configurations, and export-restricted economy tiers with degraded seekers. Cost compression in subsonic platforms intensifies as software-native challengers iterate guidance firmware outside legacy airframe redesign cycles. Allied NATO procurement offices exhibit lowest price sensitivity due to interoperability certification requirements, while asymmetric warfare operators in contested-area denial strategies drive volume demand at economy tier price points.
Supply Chain Analysis
Inbound logistics costs for precision-machined turbine components face congestion at Long Beach and Norfolk port complexes, extending dock-to-factory intervals for European-sourced superalloy castings. Turbofan engine manufacturing concentrates in the United States, United Kingdom, and France, with guidance system semiconductor fabrication anchored in Taiwan and South Korea. Supply chains draw from specialty steel alloys, ring laser gyro substrates, and radiation-hardened microelectronics. Single-source vulnerability in small-diameter turbofan production creates structural risk for extended-range program schedules. Distribution runs through foreign military sales channels for non-NATO allies and direct commercial contracts for NATO interoperability-certified integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software upgrade subscriptions and fleet sustainment service contracts expand faster than hardware procurement volumes, repositioning revenue capture toward recurring aftermarket streams.
For Market Incumbents: Shield long-range strike contract positions through captive turbofan engine supply arrangements with Williams International or Technical Directions Incorporated, neutralizing emerging entrant software iteration advantages by accelerating firmware refresh cycles within certified airframe architectures. For New Entrants and Emerging Players: Anchor in ground-based mobile coastal defense segments where procurement cycles compress below airborne platform timelines, exploiting Polish and Romanian Enhanced Forward Presence demand concentration with modular payload architectures that bypass legacy interface certification requirements. For Investors and Strategic Acquirers: Long-term, this sits as a dual-use technology convergence play because autonomous targeting algorithms developed for loitering munitions migrate into commercial drone navigation, with inflection signals concentrated in MTCR Category I threshold relaxation negotiations and NATO Support and Procurement Agency framework expansions.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-year Munitions Procurement Commitment | NDAA Title I funding locks production volumes across Pacific theater basing requirements. |
| Modular Payload Architecture Development | Software-defined seeker integration enables mission-specific reconfiguration without platform redesign. |
| NATO Interoperability Certification Investment | Standardized datalink protocols create cross-border supply eligibility for allied procurement frameworks. |
| Autonomous Targeting Algorithm Partnership | Human-machine interface protocols accelerate operational release for human-on-the-loop variants. |
| Turbofan Propulsion Supply Security Agreement | Long-term engine offtake contracts neutralize single-source vulnerability in extended-range programs. |
Research Approach
Cross-validation between program manager interviews at US Navy and Air Force procurement offices and secondary validation through NDAA budget justification documents, Missile Technology Control Regime compliance filings, and NATO Support and Procurement Agency tender records anchors the qualitative findings. Primary fieldwork engaged defense acquisition executives, turbofan propulsion engineering directors, guidance systems integration specialists, and allied nation military attachés. Secondary sources included Department of Defense budget exhibits, Congressional Research Service weapon system reports, and export control classification determinations. Bottom-up platform procurement forecasts triangulate against top-down defense expenditure projections.
Sensitivity analysis around Pacific theater basing scenario variations and autonomous weapons policy timeline assumptions shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include speed tier, launch platform configuration, propulsion architecture, guidance modality, and end-use customer type. CAGRs derive from production run commitments, foreign military sales pipeline conversions, and allied interoperability certification schedules. Hypersonic thermal management breakthrough trajectories and loitering munition asymmetric warfare investment flows constitute industry-specific forecast inputs.
Underlying assumptions cover sustained NDAA multi-year procurement continuity, stable MTCR enforcement posture, and nominal turbofan engine supplier capacity expansion, with deviation risk concentrated in autonomous targeting rules of engagement protocol revisions and Pacific theater deterrence priority reallocations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Asia-Pacific Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Weapon Mounts Market
Weapons and Ammunition
Ballistic Composite Market
Weapons and Ammunition
Electrical Weapon Market
Weapons and Ammunition
Mortar Ammunition Market
Weapons and Ammunition
Small Arms Market
Weapons and Ammunition
Global Rockets and Missiles Market
Weapons and Ammunition
Bomb Suppression Blanket (BSB) Ballistic Blankets V50 Standard Market
Weapons and Ammunition
Smart Bombs Market
Weapons and Ammunition
Weapons and Ammunition Market
Weapons and Ammunition
North Korea Nuclear Bombs and Missiles Market
Weapons and Ammunition
NIJ III Ballistic Bullet Resistant Panel Market
Weapons and Ammunition
Smart Bullets Market
Weapons and Ammunition
Missile Seekers Market
Weapons and Ammunition
Ammunition Storage Market
Weapons and Ammunition
Asia-Pacific Ammunition Market