
 Torpedo Market | 2026-2036
Torpedo Market Size, Share, and Industry Trends Forecast 2026-2036
Torpedo Market Intelligence
A widening capital-intensity divergence between prime contractors and subsystem specialists is unwinding traditional supply hierarchies in torpedo manufacturing. Raytheon Technologies Corporation leverages its sonar and guidance integration capabilities to anchor US Navy programs, while Naval Group sustains European autonomous underwater weapon development through Franco-British collaboration. Saab AB competes in Nordic and export markets with specialized lightweight torpedo designs that occupy distinct naval segments.
A torpedo is a self-propelled underwater projectile carrying a warhead, typically measuring 533 millimeters in diameter for heavy variants, designed to detonate against or beneath target vessels through contact or proximity fuzing; propulsion systems range from electric battery-powered motors to thermal engines using Otto fuel or hydrogen peroxide. The weapon serves navies for anti-submarine warfare, surface ship interdiction, and fixed coastal defense. Electric propulsion variants command expanding procurement share due to reduced acoustic signature and thermal trail, while active sonar guidance systems dominate new programs as navies prioritize counter-countermeasure resilience. Wire-guided systems retain niche roles in littoral environments where electromagnetic interference complicates autonomous homing.
The US Navy's Naval Sea Systems Command, the UK's Defence Equipment and Support, and France's Direction Générale de l'Armement shape torpedo requirements through platform integration mandates and operational testing protocols that determine market access for foreign suppliers. NATO STANAG standards for torpedo tube interfaces and underwater weapons interoperability constrain proprietary system architectures. Stakeholders must monitor undersea unmanned vehicle integration trends that could bifurcate torpedo demand between manned submarine platforms and distributed autonomous systems.
Market Dynamics
Naval modernization across NATO and Indo-Pacific fleets is compressing procurement cycles for advanced underwater weapons, while electric propulsion and autonomous guidance systems reconfigure subsystem supplier hierarchies.
Growth Catalysts
- Naval Sea Systems Command procurement mandates:The US Navy's Next Generation Torpedo program accelerates demand for integrated sonar-guidance packages from domestic suppliers.
- Franco-British underwater weapons collaboration:Joint development frameworks between France and the United Kingdom sustain European autonomous torpedo capabilities through shared testing infrastructure.
- Electric propulsion technology:Battery-powered motor systems reduce acoustic signatures and thermal trails, expanding procurement share in anti-submarine warfare applications.
Market Restraints
- Otto fuel supply concentration:Thermal engine variants depend on specialized chemical propellant production concentrated in limited supplier geographies, creating input vulnerability.
- NATO STANAG interface constraints:Standardized torpedo tube interoperability requirements limit proprietary system architectures and lock out non-aligned suppliers.
- Unmanned underwater vehicle substitution:Distributed autonomous systems threaten to bifurcate demand away from traditional manned submarine platforms.
Strategic Opportunities
- Australian submarine expansion:The AUKUS security pact drives torpedo procurement for nuclear-powered submarine fleet development in the Indo-Pacific.
- Undersea domain awareness investments:Surface and subsurface platform upgrades create adjacent demand for torpedo countermeasure and detection systems.
- Littoral wire-guided niche:Electromagnetic interference in coastal environments preserves market space for wire-guided systems alongside autonomous homing variants.
Industry Challenges
- Active sonar engineering talent scarcity:Counter-countermeasure resilience requirements strain the limited pool of specialized acoustic guidance engineers.
- Platform integration certification timelines:Operational testing protocols from Defence Equipment and Support and Direction Générale de l'Armement extend development-to-deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Torpedo Market |
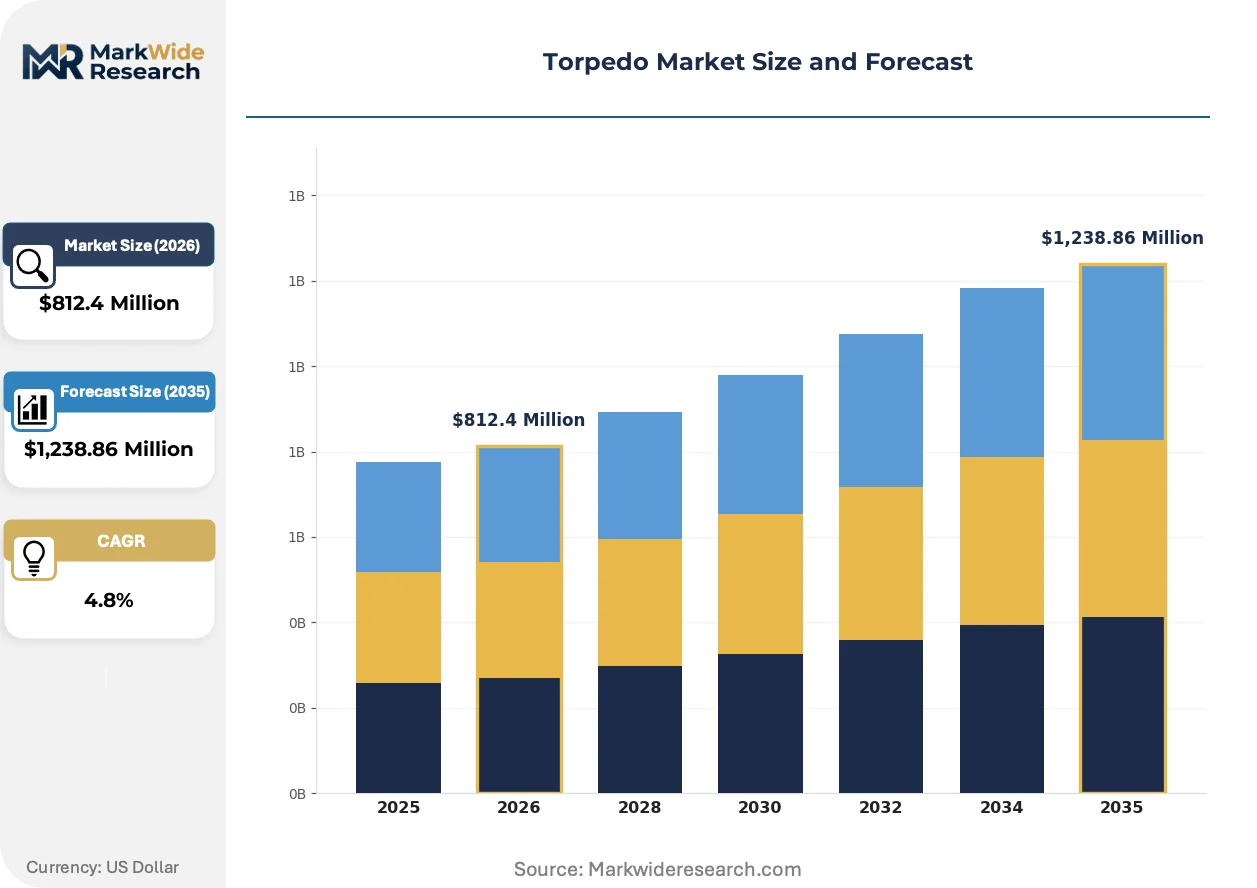
| Market Size in 2026 | $812.4 Million |
| Market Size in 2035 | $1,238.86 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Electric, Pneumatic, Hydraulic, Explosive, Steam Application: Anti-Submarine, Mine Countermeasure, Surface Ship Attack, Fixed Coastal Defense Warhead Type: High-Explosive, Shaped Charge, Blast, Fragmentation, Fuel-Air Explosive Guidance System: Wire-Guided, Acoustic Homing, Infrared, Inertial Navigation, Active Sonar |
| Companies Covered | BAE Systems PLC, Raytheon Technologies Corporation, Lockheed Martin Corporation, Naval Group, Northrop Grumman Corporation, Saab AB, Leonardo SpA, Bharat Dynamics Limited, Atlas Elektronik GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Torpedo Market Strategic Shifts & Innovations
Acoustic signature reduction and autonomous targeting resilience are compressing development priorities across torpedo programs, reshaping subsystem specialization patterns among guidance and propulsion suppliers.
Solid-state sonar processing hardware is miniaturizing. Naval platforms demand compact active sonar arrays that fit constrained tube diameters while maintaining detection range. Raytheon Technologies and European primes are adopting chip-scale acoustic processors, compressing the traditional transducer-supplier hierarchy and enabling integrated guidance packages that displace discrete component sourcing.
REACH chemical restrictions are constraining Otto fuel formulations in European procurement. The ECHA regulatory framework limits high-energy propellant chemistries, forcing thermal engine developers toward hydrogen peroxide alternatives or accelerated electric transition. French and British naval programs are prioritizing battery-electric variants to preempt compliance-driven supply disruption.
Buyer concentration among national sea systems commands is consolidating contract structures. The US Naval Sea Systems Command, UK Defence Equipment and Support, and French DGA now bundle platform-integration mandates with weapons procurement, displacing standalone torpedo tenders. This pattern is most visible in NATO-aligned fleets, where operational testing protocols determine market access and foreign supplier participation.
Torpedo Market Segmentation
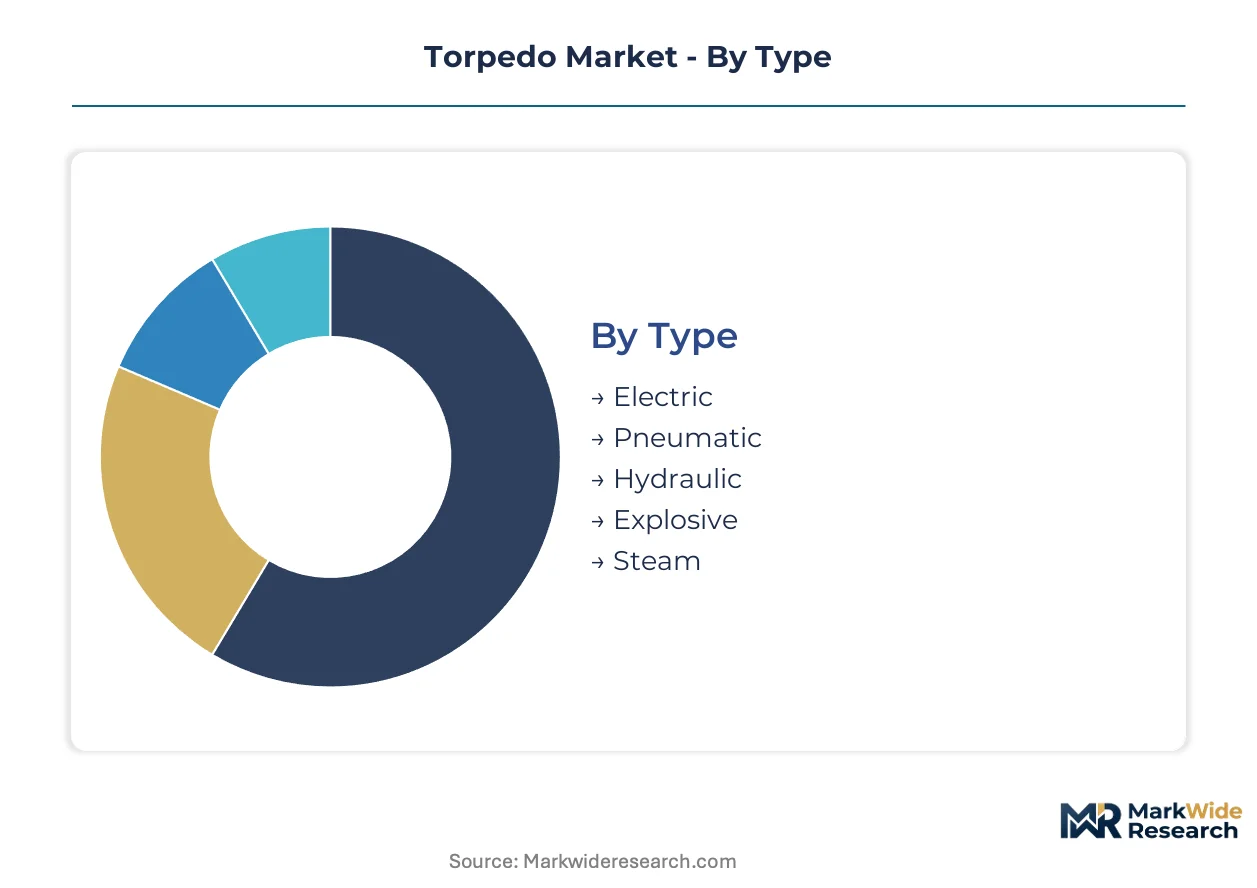
Torpedo procurement channels diverge sharply by propulsion and guidance architecture, with electric variants flowing through submarine modernization programs while thermal systems concentrate in surface fleet replenishment. Segmentation logic here traces how technical specifications map to platform integration mandates from national sea systems commands.
Type:
Electric torpedoes move through submarine procurement channels tied to undersea domain awareness investments, while thermal variants circulate via surface ship replenishment programs where acoustic signature matters less.
- Electric:Battery-powered motor systems eliminate thermal trail and radiated noise, making them indispensable for nuclear submarine programs. Demand concentrates in US Navy Next Generation Torpedo procurement and Franco-British collaborative frameworks where stealth persistence drives specification.
- Pneumatic:Compressed-air propulsion serves training and limited-range littoral applications. Naval Group and Saab AB channel these through export markets with constrained defense budgets, particularly Nordic coastal defense procurement.
- Hydraulic:Fluid-pressure drive mechanisms occupy niche roles in specialized delivery platforms. The segment sees intermittent demand from fixed coastal defense installations requiring simplified maintenance protocols.
- Explosive:Chemical reaction propulsion using Otto fuel formulations retains installed base in legacy surface ship inventories. REACH regulatory constraints in Europe are compressing procurement share as ECHA restrictions tighten high-energy propellant chemistries.
- Steam:Historical propulsion architecture persists only in museum and training configurations. No active procurement channels remain for operational deployment.
Electric systems dominate installed base expansion. Explosive propulsion is where replacement demand concentrates as fleets modernize.
Application:
Cost tiering separates precision-guided anti-submarine variants from volume-positioned mine countermeasure systems, with surface attack applications occupying intermediate specification bands.
- Anti-Submarine:Active sonar homing with counter-countermeasure logic defines the premium tier. Raytheon Technologies and Naval Group anchor demand through integrated sonar-guidance packages for US and European nuclear submarine programs.
- Surface Ship Attack:Dual-purpose warheads with contact and proximity fuzing serve destroyer and frigate launch platforms. The segment channels through NATO STANAG-compliant procurement where tube interoperability constrains proprietary designs.
- Mine Countermeasure:Expendable lightweight configurations prioritize unit cost over recovery. Saab AB specializes here, pushing variants through Nordic and Indo-Pacific export markets with shallow-water operational requirements.
- Fixed Coastal Defense:Shore-based tube installations with wire-guided command links persist in territorial defense postures. Demand flows through national infrastructure programs rather than fleet procurement cycles.
Anti-submarine applications command premium pricing tiers. Mine countermeasure systems are climbing fastest on volume procurement from Indo-Pacific littoral fleets.
Warhead Type:
Margin structures stratify by blast yield optimization, with shaped charge and fuel-air configurations capturing technology premiums against commodity high-explosive baselines.
- High-Explosive:Conventional blast warheads with contact fuzing constitute the volume baseline. Procurement concentrates in fleet replenishment programs where unit cost constraints override advanced penetration requirements.
- Shaped Charge:Munroe effect liners focus blast energy for hull penetration. Direction Générale de l'Armement and UK Defence Equipment and Support specify these for anti-submarine applications where pressure hull rupture determines kill probability.
- Blast:Optimized underwater detonation with proximity fuzing against surface targets. The segment serves intermediate cost tiers in multi-role torpedo configurations.
- Fragmentation:Casing fragmentation for area effect against small craft or submarine pressure hull weak points. Niche demand from coastal defense and special mission profiles.
- Fuel-Air Explosive:Aerosolized detonation creates sustained pressure pulses. Experimental procurement channels only, with no operational deployment in NATO inventories.
High-explosive warheads retain volume dominance. Shaped charge configurations are where technology investment concentrates for next-generation programs.
Guidance System:
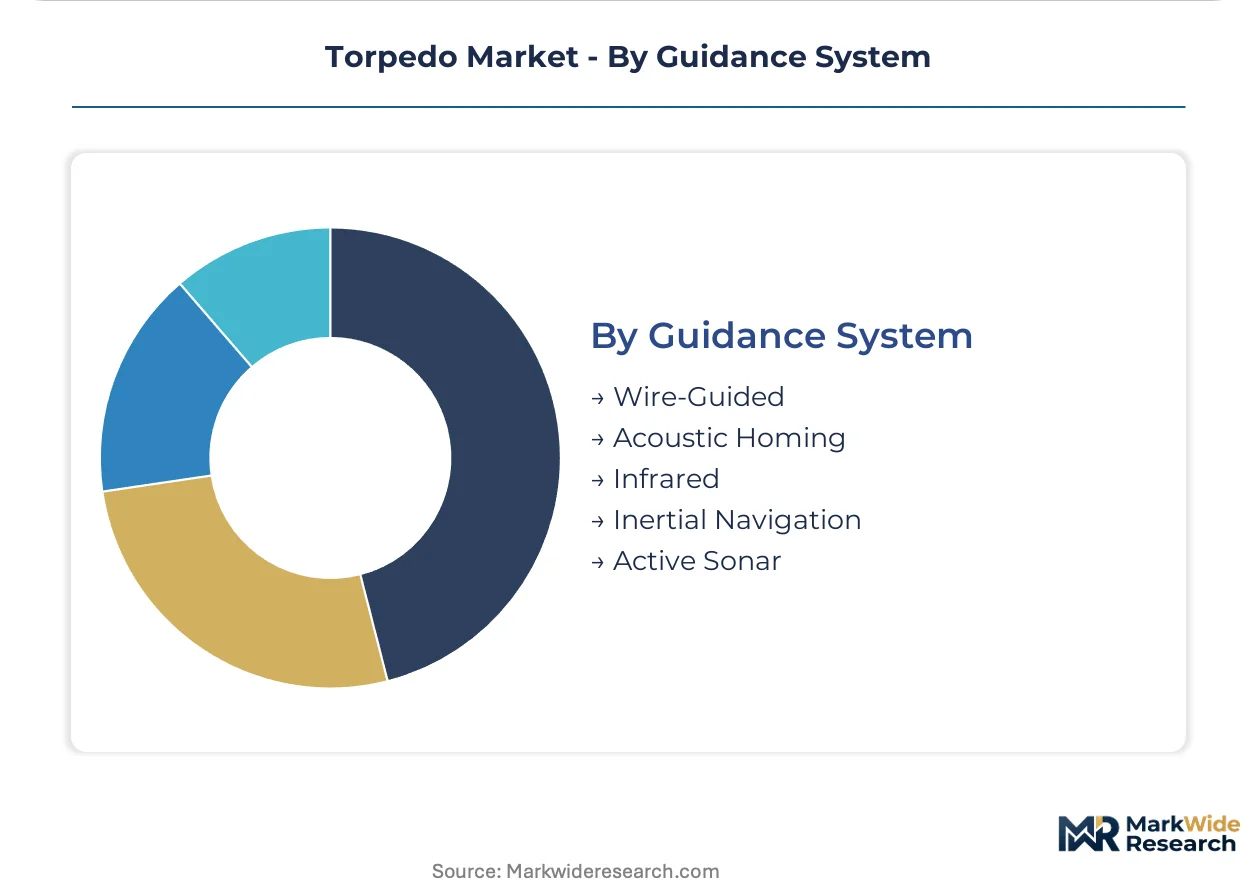
Supply concentration in acoustic processing hardware elevates active sonar and wire-guided segments above infrared and inertial alternatives, with chip-scale miniaturization compressing subsystem supplier hierarchies.
- Active Sonar:Transmit-receive acoustic arrays with autonomous target classification anchor premium procurement. Naval Sea Systems Command mandates drive domestic supplier consolidation around Raytheon Technologies integration capabilities.
- Wire-Guided:Fiber-optic command links preserve operator-in-the-loop control for littoral engagements. Electromagnetic interference in coastal waters sustains this segment against autonomous homing substitution.
- Acoustic Homing:Passive listening arrays without active transmission reduce detectability. Franco-British collaborative programs prioritize these for counter-countermeasure resilience in contested waters.
- Inertial Navigation:Gyroscopic positioning for submerged launch without external reference. Supports wire-guided and autonomous hybrid architectures rather than standalone deployment.
- Infrared:Thermal signature detection for terminal homing against surface targets. Limited procurement through specialized surface attack configurations with clear-sky operational assumptions.
Active sonar dominates new program specifications. Wire-guided systems are where littoral operational requirements preserve niche demand against autonomous transition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the torpedo market tilts toward United States procurement channels, where Naval Sea Systems Command mandates compress supplier margins, while Indo-Pacific buyers absorb technology premiums through AUKUS-linked submarine modernization programs.
United States
Naval Sea Systems Command drives procurement through the Next Generation Torpedo program, with active sonar integration requirements filtering domestic supplier access. The Department of Defense maintains strict operational testing protocols that determine foreign participation eligibility. Rhode Island and Connecticut host concentrated submarine industrial base activity supporting weapons integration.
United Kingdom
Defence Equipment and Support bundles platform-integration mandates with torpedo procurement, extending development-to-deployment cycles for subsystem suppliers. The UK collaborates with France through Franco-British underwater weapons frameworks sharing testing infrastructure. Barrow-in-Furness anchors nuclear submarine construction with adjacent weapons system integration.
France
Direction Générale de l'Armement prioritizes battery-electric variants to preempt REACH regulatory constraints on Otto fuel propellants. Naval Group sustains autonomous underwater weapon development through shared European programs. Toulon and Cherbourg concentrate submarine construction with integrated torpedo tube manufacturing.
Australia
The AUKUS security pact accelerates torpedo procurement for nuclear-powered submarine fleet development in the Indo-Pacific. Defence procurement channels align with US and UK operational testing standards under trilateral coordination. Osborne in South Australia hosts the future submarine construction hub with weapons integration facilities.
Sweden
Saab AB channels specialized lightweight torpedo designs through Nordic and export markets with shallow-water operational requirements. The Swedish Defence Materiel Administration specifies reduced acoustic signature systems for Baltic Sea operations. Karlskrona hosts naval shipyard concentration with adjacent underwater weapons development.
Torpedo Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with integrated sonar-guidance specialists commanding premium contract tiers while lightweight system fabricators compete on unit economics in export markets. The vendor base stratifies across three tiers: prime contractors anchoring national programs, mid-tier subsystem specialists, and regional export-focused manufacturers. Two dominant competitive moves are reshaping positioning: strategic partnerships for shared testing infrastructure and accelerated electric propulsion transitions to preempt regulatory compliance costs.
Within the prime contractor tier, Raytheon Technologies Corporation and Lockheed Martin Corporation represent US-based integrated defense platforms anchoring Naval Sea Systems Command procurement channels. Naval Group exemplifies European autonomous underwater weapon development through Franco-British collaborative frameworks. Saab AB occupies a specialized position in lightweight torpedo segments serving Nordic and Indo-Pacific littoral requirements.
| Leading Market Players |
|---|
| BAE Systems PLC |
| Raytheon Technologies Corporation |
| Lockheed Martin Corporation |
| Naval Group |
| Northrop Grumman Corporation |
| Saab AB |
| Leonardo SpA |
| Bharat Dynamics Limited |
| Atlas Elektronik GmbH |
| Others |
Cost & Logistics Intelligence
Capacity utilization at solid-state sonar processor fabs determines cost floors across guidance system tiers, concentrating margin pressure on subsystem specialists lacking Naval Sea Systems Command contract scale while elevating price premiums for integrated packages from Raytheon Technologies and Naval Group.
Pricing Analysis
Configured-to-order pricing for active sonar guidance packages commands spreads of 40-60% above standard thermal propulsion baselines. Three-tier pricing structure across integrated-guidance premium, modular-mid, and economy-limited configurations stratifies procurement channels. Cost compression in thermal engine segments intensifies because REACH regulatory constraints on Otto fuel formulations are accelerating electric transition investments. Mine countermeasure buyers exhibit highest price sensitivity, while nuclear submarine programs demonstrate lowest sensitivity due to platform-integration mandates bundling weapons with hull procurement.
Supply Chain Analysis
The United States and France anchor sonar processor and battery-electric propulsion manufacturing, while Sweden concentrates lightweight torpedo final assembly for export markets. Supply chains draw from specialized chemical propellant production in limited geographies, lithium-ion cell manufacturing in South Korea and Japan, and rare earth magnet sourcing for motor systems. Single-source vulnerability in Otto fuel precursor chemicals creates input disruption risk. Distribution runs through national sea systems commands with operational testing protocols determining foreign supplier market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Torpedo procurement is shifting toward platform-economics logic where NATO STANAG interoperability standards and shared testing infrastructure create winner-take-most dynamics around integrated sonar-guidance ecosystems.
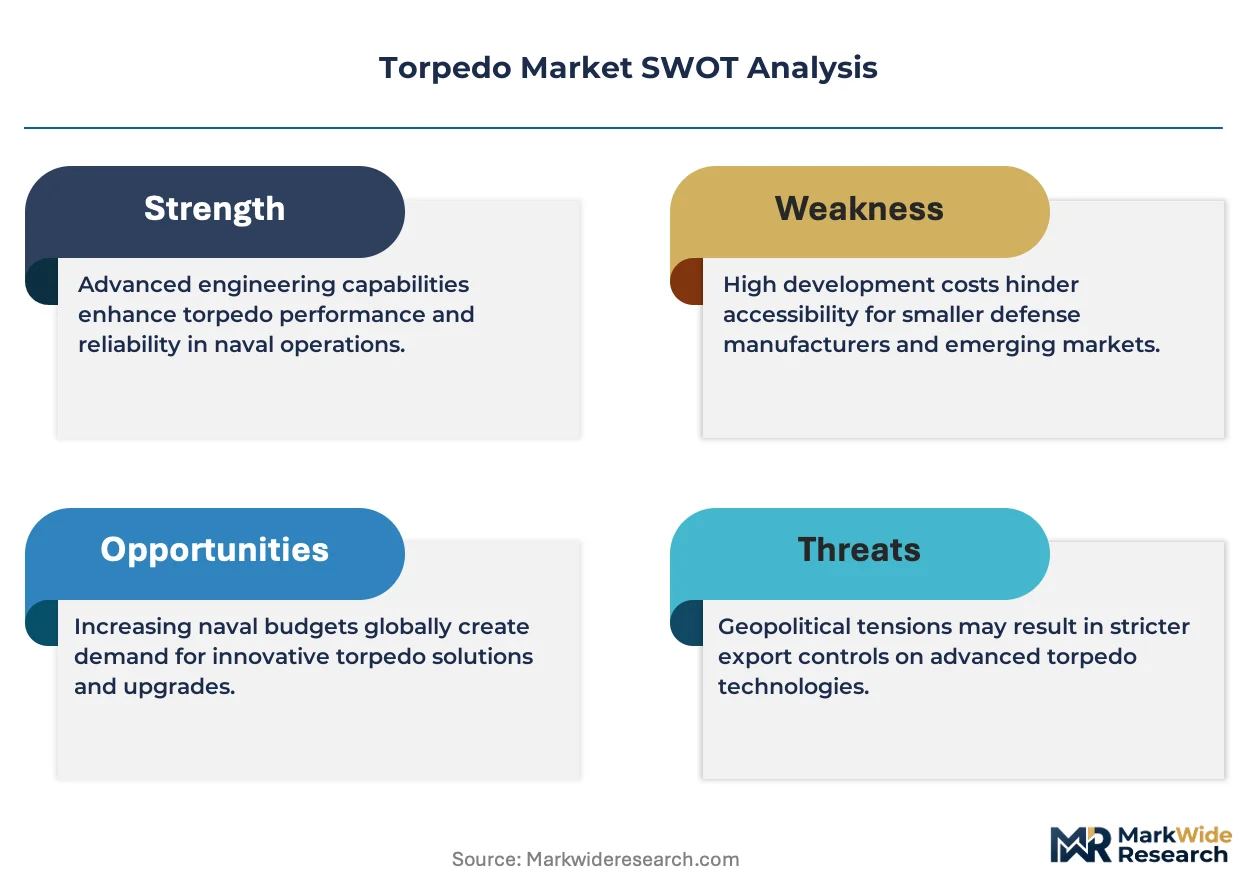
For Market Incumbents: Compound platform-integration advantages by deepening captive supply of solid-state sonar processors and securing exclusive testing infrastructure access through Franco-British collaborative frameworks. Lock in Naval Sea Systems Command contract structures before electric propulsion transitions commoditize thermal engine supplier margins. Priority lever: backward integration into chip-scale acoustic processing to displace discrete component sourcing. For New Entrants and Emerging Players: Lead with wire-guided niche specialization for littoral electromagnetic interference environments where autonomous homing faces operational constraints. Target Indo-Pacific coastal defense procurement from navies with constrained integration budgets and shallow-water operational requirements. Go-to-market angle: reduced-recovery-cost configurations for mine countermeasure applications with expendable deployment profiles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors subsystem specialists with active sonar engineering talent pools and operational testing protocol relationships. Long-term viability hinges on electric propulsion transition completion and undersea unmanned vehicle integration capability. Acquisition target archetype: mid-tier guidance specialists with Naval Group or Raytheon Technologies partnership history. Signal to watch: AUKUS-linked submarine construction milestones triggering torpedo procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Propulsion Transition | Battery-electric variants preempt REACH regulatory constraints on Otto fuel formulations in European procurement. |
| Active Sonar Integration | Chip-scale acoustic processors compress transducer-supplier hierarchies around Raytheon Technologies capabilities. |
| Shared Testing Infrastructure | Franco-British collaborative frameworks sustain European autonomous underwater weapon development against US scale advantages. |
| Littoral Wire-Guided Specialization | Electromagnetic interference in coastal waters preserves market space for Saab AB export configurations. |
| AUKUS Procurement Alignment | Trilateral coordination channels Australian demand through US and UK operational testing standards. |
Research Approach
Operator-level perspectives from submarine program managers, naval sea systems procurement officers, sonar guidance engineers, and torpedo countermeasure specialists anchored the qualitative base. Primary interviews combined with secondary validation from Naval Sea Systems Command procurement disclosures, Direction Générale de l'Armement testing protocols, NATO STANAG documentation, and customs trade data. Bottom-up segment sizing triangulated against top-down fleet modernization budget allocations.
Sensitivity analysis across propulsion technology adoption curves, regulatory compliance timelines, and platform-integration certification durations shaped the analytical framework. Segmentation dimensions modeled include propulsion architecture, guidance system complexity, application mission profile, and regional procurement channel structure. CAGRs derived from fitted growth curves against naval modernization program announcements and replacement cycle assumptions. Industry-specific inputs encompassed undersea domain awareness investment trajectories and unmanned underwater vehicle substitution elasticity.
The analysis sits within stated boundaries; outcomes outside sustained NATO and Indo-Pacific fleet modernization commitments or accelerated electric propulsion transitions would require recalibration. Forecasts reflect documented assumptions regarding regulatory compliance timelines and platform-integration certification durations. Specific risk factors include REACH chemical restriction tightening, unmanned underwater vehicle demand bifurcation, and active sonar engineering talent scarcity. Recalibration cycles align with material shifts in naval procurement program announcements and undersea unmanned system operational deployment milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
NATO Ammunition Market
Weapons and Ammunition
Military Fire Control Systems Market
Weapons and Ammunition
Medium Caliber Ammunition Market
Weapons and Ammunition
Europe Cruise Missile Market
Weapons and Ammunition
US Perforating Gun Market
Weapons and Ammunition
Artillery Ammunition Market
Weapons and Ammunition
Military Fuze Market
Weapons and Ammunition
Global Artillery Systems Market
Weapons and Ammunition
Southeast Asia, Middle-East and Africa Small Arms and Ammunition Market
Weapons and Ammunition
Shotgun Shell Market
Weapons and Ammunition
Asia-Pacific Ammunition Market
Weapons and Ammunition
Ballistic Missile Market
Weapons and Ammunition
Enclosed Smokeless Flares Market
Weapons and Ammunition
Missile Seekers Market
Weapons and Ammunition
North America Weapon Night Sight Market
Weapons and Ammunition
Sonobuoy Launcher Market