
 Precision Agriculture Market | 2026-2036
Precision Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Precision Agriculture Market Intelligence
The shift toward real-time, AI-driven decision support from basic data collection is bifurcating the market. This creates a divide between integrated platform providers and component suppliers. Deere & Company leverages its extensive machinery footprint to offer end-to-end solutions. Trimble, Inc. specializes in high-precision GPS and guidance systems, while Bayer AG focuses on digital farming platforms that integrate agronomic data.
Precision agriculture employs a suite of technologies to manage spatial and temporal variability within fields for optimized returns. It relies on data inputs from sources like satellite imagery with sub-meter resolution to inform site-specific applications of inputs. The technology landscape is dominated by GPS and IoT devices, which form the hardware backbone for data collection. In terms of application, crop monitoring and yield prediction solutions represent the fastest-growing segments, driven by their direct impact on farm profitability.
Regulatory frameworks are shaping market access and product standards. In the United States, the USDA provides grants for technology adoption, while the EU's Green Deal incentivizes sustainable practices that rely on precision tools. These policies directly influence the design of software and hardware for compliance. The critical decision for equipment manufacturers and software developers is whether to pursue open, interoperable platforms or closed, proprietary ecosystems.
Market Dynamics
The central tension shaping the precision agriculture market is the conflict between proprietary, closed ecosystems and the demand for open, interoperable data platforms. This divide is amplified by regulatory pressures, such as the EU Green Deal, which necessitate data sharing for sustainability verification across diverse farm equipment.
Growth Catalysts
- Policy Mandates:The European Union's Green Deal and its associated Farm to Fork strategy create direct demand for precision technologies that enable compliance with targets for reduced pesticide and fertilizer use, tying subsidies to sustainable practices.
- Technology Advancement:Continuous improvements in satellite imagery, including higher resolution and more frequent revisits, enhance the accuracy of crop monitoring and variable rate application maps, boosting the value proposition for farmers.
- Agribusiness Efficiency:Large-scale commercial farms are driving adoption to manage vast operations, optimize input costs like fuel and fertilizer, and maximize yield potential to improve overall farm profitability and operational efficiency.
Market Restraints
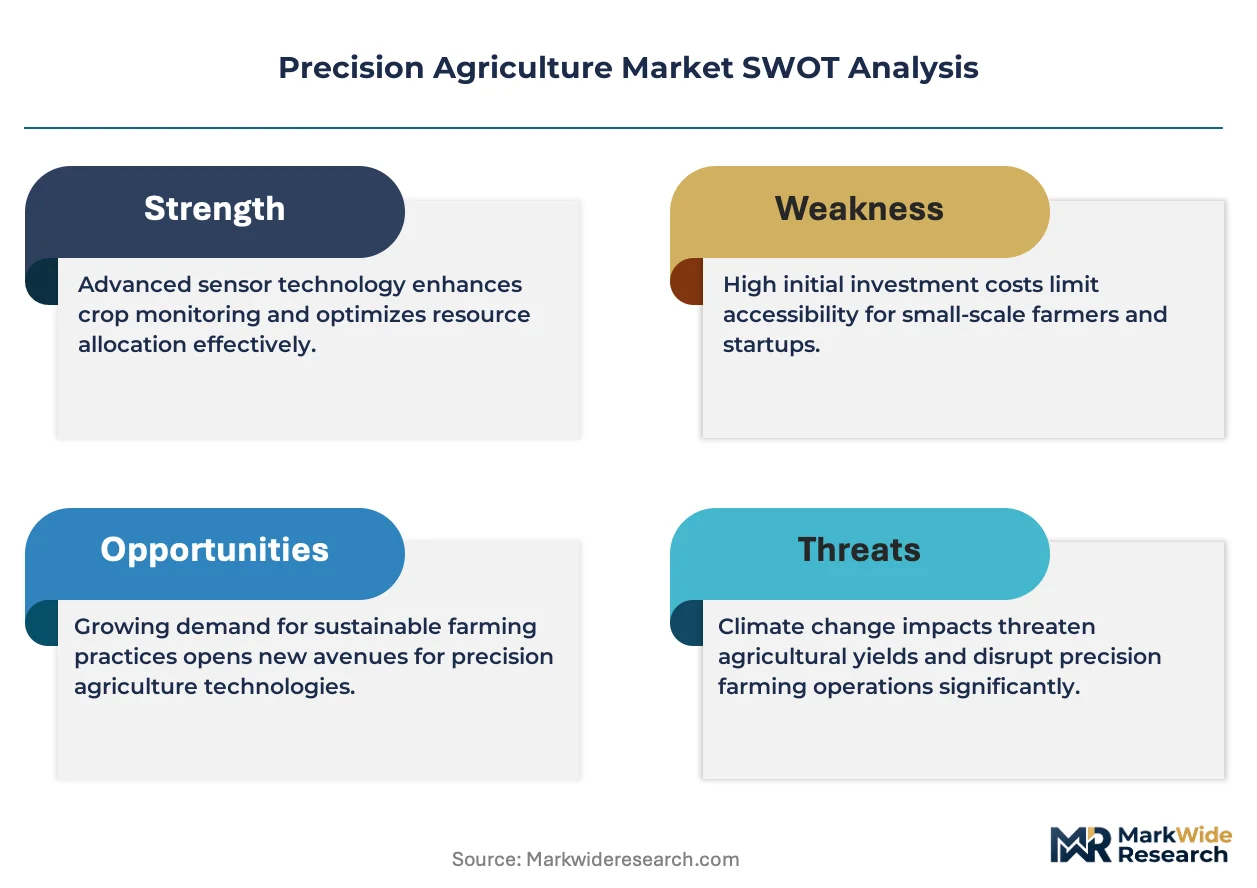
- High Capital Investment:The significant upfront cost of GPS guidance systems, drones, and IoT sensors remains a primary barrier to adoption for small and medium-sized farms, limiting market penetration in regions dominated by smaller landholdings.
- Data Interoperability:A lack of universal standards for data formats and communication protocols between equipment from different manufacturers creates data silos, complicating the integration of a cohesive, farm-wide precision agriculture system.
- Connectivity Gaps:In many rural agricultural regions across the globe, unreliable or nonexistent broadband and cellular connectivity hinders the functionality of cloud-based platforms and real-time data transfer from in-field IoT devices.
Strategic Opportunities
- AI-Driven Predictive Analytics:Developing AI models that move beyond monitoring to predict disease outbreaks, pest infestations, and optimal harvest times offers a significant value-add, creating new service revenue streams for software providers.
- Emerging Economies:Agricultural powerhouses in Latin America, such as Brazil and Argentina, represent significant growth opportunities as farmers seek to adopt technology to manage large-scale soybean and corn operations more efficiently.
- Water Management Solutions:With increasing water scarcity, there is a growing opportunity for precision irrigation systems that use soil moisture sensors and weather data to optimize water use, especially in arid and semi-arid farming regions.
Industry Challenges
- Agronomic Talent Gap:A persistent shortage of agronomists and farm managers with the data science and analytics skills required to interpret complex datasets and translate them into actionable field-level decisions slows technology adoption and limits ROI.
- Legacy System Integration:Integrating new, sophisticated precision agriculture software with existing, often outdated, farm management information systems and accounting software presents a significant technical and operational hurdle for many farming enterprises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precision Agriculture Market |
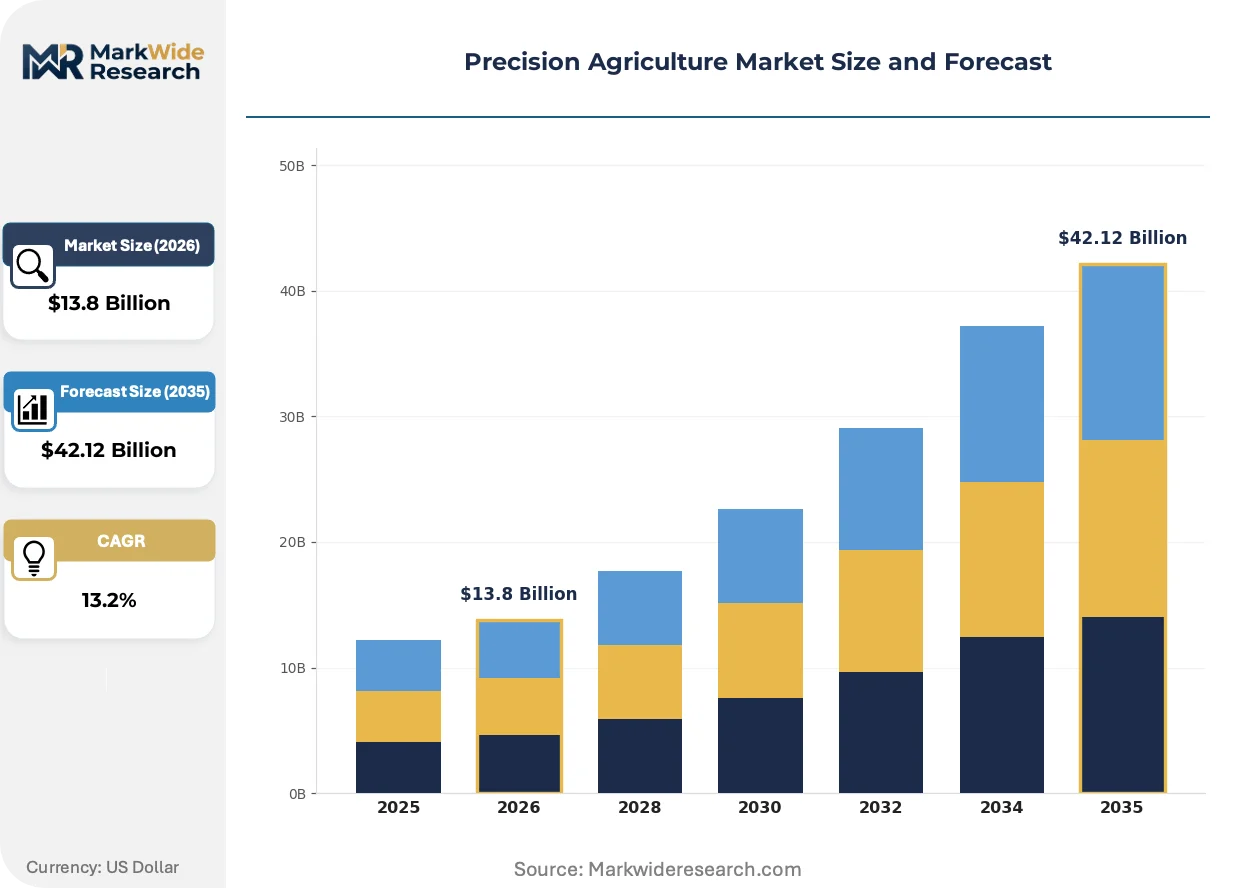
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $42.12 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensors, Drones, Software, Variable Rate Technology End User: Farmers, Agricultural Cooperatives, Agribusiness, Research Institutions Technology: GPS, IoT, Big Data Analytics, Machine Learning Application: Crop Monitoring, Soil Management, Irrigation Management, Yield Prediction |
| Companies Covered | Deere & Company, Trimble, Inc., AGCO Corporation, Topcon Corporation, Raven Industries, CNH Industrial, Ag Leader Technology, Kubota Corporation, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precision Agriculture Market Strategic Shifts & Innovations
The market's evolution is defined by a transition from hardware-centric data collection to software-driven autonomous decision-making. This shift elevates the importance of AI, machine learning, and platform interoperability in delivering tangible agronomic and financial outcomes for producers.
In-field IoT sensors provide real-time, granular data on variables like soil moisture, nutrient levels, and ambient temperature. Large-scale agribusiness operations and specialty crop producers are leading the adoption of these devices to enable micro-management of field zones. This technology is miniaturizing data collection, shifting the process from periodic manual sampling to continuous, autonomous monitoring that feeds directly into digital farming platforms.
The United States Department of Agriculture (USDA) provides numerous grants and loan programs to encourage the adoption of climate-smart agricultural practices. These financial incentives directly lower the investment barrier for farmers looking to acquire precision tools for nutrient management and conservation tillage. The variable-rate technology and guidance system segments are responding by positioning their products as key enablers for accessing these government funds.
A clear behavioral change is the move away from one-time capital equipment sales toward service-oriented contracts focused on agronomic outcomes. This model, often involving data analytics subscriptions, disrupts the traditional dealer channel by bundling hardware, software, and advisory services. The trend is most pronounced in the major agricultural economies of North America and Western Europe, where farmers are increasingly willing to pay for guaranteed performance improvements.
Precision Agriculture Market Segmentation
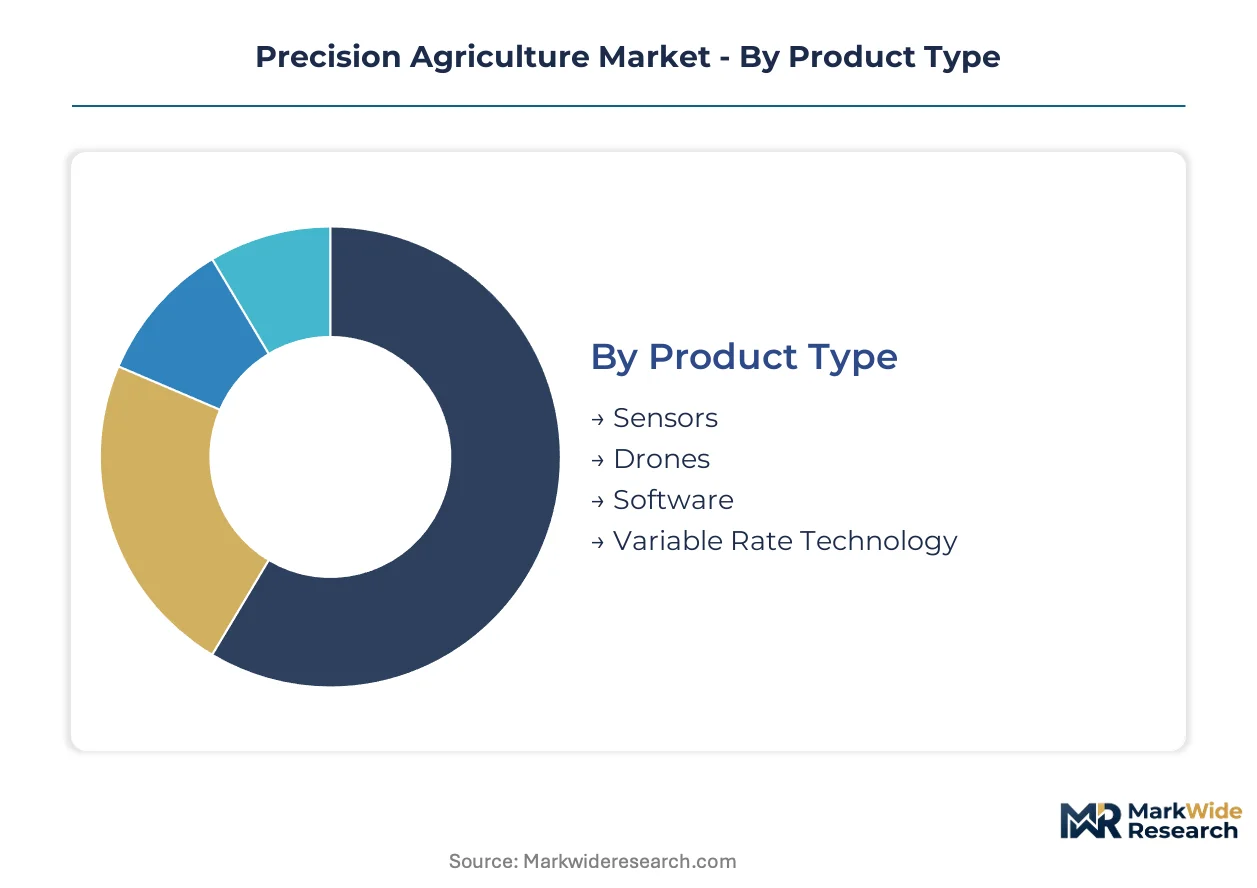
The precision agriculture market bifurcates across distinct product types, end-user categories, core technologies, and specific applications. Understanding these segments reveals how various solutions meet diverse agricultural needs. This breakdown highlights the channels through which innovation reaches the farm and influences operational efficiency.
Product Type:
The distribution channels for precision agriculture products vary significantly, reflecting their complexity and integration requirements, from direct sales for machinery components to subscription models for software platforms.
- Sensors:These devices capture real-time, granular data on soil moisture and nutrient levels, feeding continuous information into digital farming platforms. Demand concentrates in high-value specialty crop production.
- Software:Digital farming platforms and AI-driven decision support tools integrate diverse data inputs for actionable agronomic insights. North American farmers increasingly adopt these solutions via service-oriented contracts.
- Drones:Unmanned aerial vehicles provide aerial imagery for crop health monitoring and field mapping. Adoption faces barriers in regions with high capital investment costs.
- Variable Rate Technology:These systems enable precise, site-specific application of inputs like fertilizers and water. The EU Green Deal creates direct demand for these technologies.
By volume, Sensors lead the market due to their foundational role in data collection. By growth pace, Software represents the fastest-growing segment, driven by the shift towards AI-driven decision support.
End User:
End-user segments are differentiated by their operational scale and financial capacity, influencing adoption rates and preferred solutions, from individual farmers to large corporate agribusinesses.
- Agribusiness:Large-scale commercial farms drive significant adoption to manage vast operations and optimize input costs. These entities prioritize integrated, end-to-end solutions for maximizing yield.
- Farmers:Individual farmers, particularly those with small and medium-sized landholdings, face high capital investment barriers. Their adoption is often incentivized by government grants, such as from the USDA in the United States.
- Agricultural Cooperatives:These organizations pool resources for technology adoption, enabling members to access shared precision farming tools and data analytics.
- Research Institutions:Academic and private research bodies utilize precision agriculture tools for developing new crop varieties and optimizing cultivation.
Agribusinesses anchor demand for comprehensive precision agriculture platforms, while farmers represent a segment with significant untapped potential for targeted solutions.
Technology:
The technological landscape underpins precision agriculture, with solutions ranging from foundational positioning systems to advanced analytical engines that transform raw data into actionable intelligence.
- IoT:Internet of Things devices, including in-field sensors, form the hardware backbone for real-time data collection on soil and crop conditions. Connectivity gaps in rural regions hinder cloud-based platform functionality.
- Big Data Analytics:This technology processes vast datasets from satellite imagery and IoT sensors, identifying patterns and generating insights. It is crucial for AI-driven decision support.
- GPS:Global Positioning Systems provide high-precision location data essential for guidance systems and variable rate applications. Upfront cost remains a barrier for smaller farms.
- Machine Learning:Algorithms analyze historical and real-time data to predict outcomes like disease outbreaks and optimal harvest times. This offers significant value-add for software providers.
The adoption rate for IoT indicates its foundational role in data gathering, while Big Data Analytics is experiencing rapid uptake as farms seek deeper insights.
Application:
Precision agriculture applications directly address critical farming challenges, offering solutions that enhance resource efficiency, mitigate risks, and directly impact farm profitability and sustainability.
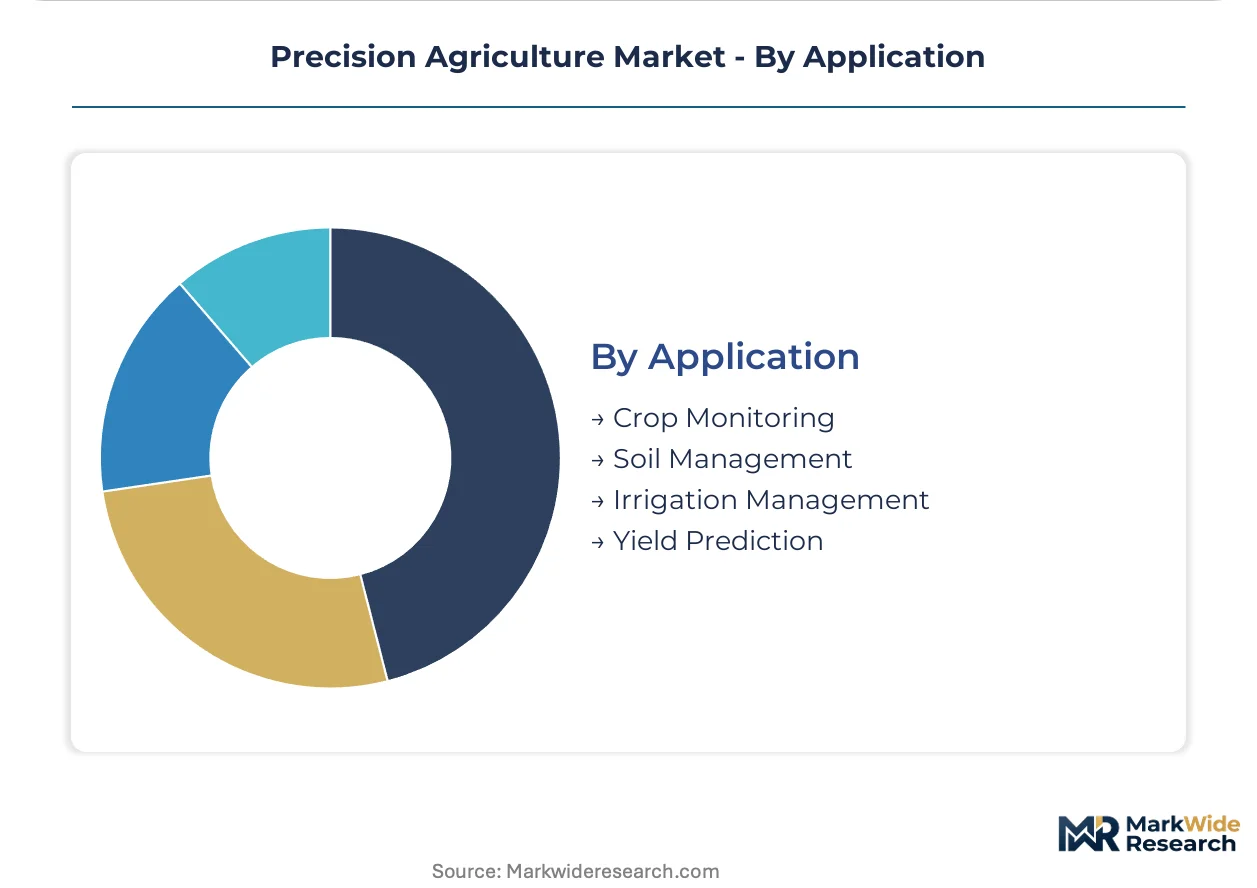
- Crop Monitoring:This application utilizes satellite imagery, drones, and in-field sensors to assess crop health, detect anomalies, and track growth. It directly impacts farm profitability through timely interventions.
- Yield Prediction:Leveraging AI and machine learning models, this application forecasts anticipated crop yields based on historical data and environmental factors. It enables better harvest planning and market decision-making.
- Soil Management:Precision soil management involves site-specific analysis of soil properties to optimize nutrient application and tillage. This supports sustainable farming practices mandated by the EU Green Deal.
- Irrigation Management:These systems use soil moisture sensors and weather data to precisely control water application, minimizing waste and optimizing plant hydration. This is crucial for addressing water scarcity.
Profitability gains from Crop Monitoring are substantial, with Yield Prediction offering significant long-term strategic benefits for farm planning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global precision agriculture market exhibits varied regional adoption, often reflecting domestic agricultural output and trade balances. Countries with significant agricultural export profiles aggressively deploy precision tools to enhance competitiveness and meet international quality standards. Conversely, regions focused on food security also invest to optimize local production and reduce import dependency.
United States
The United States drives significant demand for advanced precision agriculture solutions, particularly for large-scale corn and soybean operations. USDA grants encourage technology adoption, supporting climate-smart agricultural practices and nutrient management. California's Central Valley farmers extensively deploy sensors and irrigation management systems to optimize high-value specialty crop production.
Brazil
Brazil represents a significant growth opportunity for precision agriculture, driven by its expansive soybean and corn cultivation. Government initiatives support the integration of advanced farming technologies to boost productivity and sustainability. Farmers in the Mato Grosso region increasingly adopt GPS guidance and variable rate technology for efficient resource management across vast fields.
France
French agriculture is rapidly integrating precision tools to comply with the EU Green Deal's stringent environmental targets. Policy mandates incentivize farmers to adopt variable rate technology for optimized fertilizer and pesticide application. The agricultural regions of the Loire Valley utilize satellite imagery and soil sensors to enhance vineyard and cereal crop management.
India
India's precision agriculture market is expanding, driven by the need to enhance food security and optimize resource use for its vast farming population. Government subsidies encourage small and medium-sized farmers to adopt modern irrigation and crop monitoring solutions. The Punjab region sees increasing deployment of IoT sensors for efficient water management in its intensive rice and wheat fields.
Australia
Australian farmers adopt precision agriculture to address significant challenges like water scarcity and the management of extensive dryland operations. State and federal programs promote technologies that enhance drought resilience and improve land sustainability. The broadacre cropping regions of New South Wales actively implement GPS-guided machinery and yield mapping for optimized grain production.
Precision Agriculture Market Key Industry Players
Listed leaders compete with private specialists across the precision agriculture technology stack, from hardware manufacturing to advanced analytics. The market exhibits a tiered structure, with established agricultural machinery manufacturers offering integrated platforms alongside specialized software and sensor providers. Competitive positioning often involves strategic partnerships to broaden solution portfolios and geographic expansion into emerging agricultural economies. Companies pursue both M&A activities and R&D investments to maintain technological leadership and capture new market segments.
Within the integrated platform segment, Deere & Company leverages its extensive machinery footprint to provide end-to-end solutions, encompassing both physical equipment and digital services for comprehensive farm management. Trimble, Inc. exemplifies a specialist in high-precision GPS and guidance systems, anchoring its offerings around geospatial data accuracy crucial for variable rate applications and autonomous operations. Bayer AG sits within the digital farming platform archetype, focusing on integrating agronomic data and biological insights for enhanced farm-level decision-making, supporting sustainable practices and yield optimization.
| Leading Market Players |
|---|
| Deere & Company |
| Trimble, Inc. |
| AGCO Corporation |
| Topcon Corporation |
| Raven Industries |
| CNH Industrial |
| Ag Leader Technology |
| Kubota Corporation |
| Bayer AG |
| Others |
Cost & Logistics Intelligence
The EU Green Deal, with its stringent environmental targets, gates both technology supply qualification and price differentiation for compliant precision agriculture solutions. This regulatory pressure influences the cost structures and market access for various precision farming tools across European agricultural economies.
Pricing Analysis
Agribusiness buyers anchor value-based pricing models for integrated precision agriculture platforms. Customization levels for software solutions and the depth of data analytics provided drive significant price differentiation. Pricing pressure stems from the high capital investment required for initial technology adoption, particularly impacting smaller farms. Small and medium-sized farmers exhibit the highest price sensitivity, while large agribusinesses prioritize comprehensive solutions and proven ROI, making them less price-sensitive.
Supply Chain Analysis
Port congestion in major agricultural export hubs, particularly in North America and South America, impacts the inbound logistics costs for precision agriculture components. The supply chain for advanced sensors and GPS modules draws from manufacturing concentrations in China, the United States, and Germany. Dependencies on specialized microcontrollers and high-precision sensor arrays introduce single-source vulnerability for advanced chipsets. Distribution primarily runs through established agricultural machinery dealer networks for hardware and direct SaaS models for software platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a substitution defense as traditional farming methods, while less efficient, present a lower-cost alternative that incumbents must navigate.
For Market Incumbents: Consolidate market share by acquiring niche software developers specializing in AI-driven predictive analytics. This strategy counters the threat from agile emerging AI specialists. Expand digital service offerings to deepen customer engagement and leverage existing machinery footprints. Continued R&D investment in autonomous systems remains a critical lever for long-term differentiation.
For New Entrants and Emerging Players: Anchor in underserved regional markets like India and Brazil, focusing on low-capital-intensive solutions. Target small and medium-sized farms with modular, outcome-based service models rather than large upfront equipment purchases. A compelling go-to-market angle involves offering interoperable platforms that integrate with existing farm equipment, addressing data silo challenges.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting in an upward direction across advanced sensor manufacturing and AI platform development. The market shows long-term viability driven by global food security and sustainability mandates. Acquisition targets should prioritize integrated platform providers with robust data analytics capabilities and strong recurring revenue streams. Regulatory shifts incentivizing sustainable practices serve as a key signal to watch for accelerated adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire AI Analytics Firm | Expands software capabilities for predictive insights, enhancing value for agribusiness clients. |
| Develop Open Interoperability Standards | Reduces data silos across diverse farm equipment, increasing platform adoption among farmers. |
| Expand Outcome-Based Service Contracts | Shifts revenue models from one-time sales to recurring subscriptions, appealing to price-sensitive farmers. |
| Invest in Advanced Sensor Miniaturization | Lowers hardware costs and enables wider deployment of real-time data collection devices. |
| Target Emerging Agricultural Economies | Captures new demand in regions like Latin America and Asia with growing need for efficiency gains. |
Research Approach
Desk research of government reports, academic journals, and company filings preceded structured interviews with agronomists, farm managers, technology developers, and policy makers. This primary research validated secondary data from USDA reports, EU Green Deal documents, company annual reports, and agricultural statistics. A rigorous bottom-up and top-down triangulation approach ensured comprehensive market sizing and segmentation across all data points.
Variance decomposition models underpinned the analytical framework, segmenting the market by product type, end user, technology, application, and regional agricultural output. Compound annual growth rates were derived from historical trends and projected adoption rates across the modeling period. Key industry-specific forecast inputs included global crop prices and farm subsidy levels, influencing farmer investment decisions.
Underlying assumptions cover stable regulatory environments and consistent technology adoption rates, with deviation risk concentrated in unforeseen climate events or global trade policy shifts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Global Digital Farming Market
Precision Agriculture
Precision Livestock Market
Precision Agriculture
North America Precision Agriculture Market
Precision Agriculture
Agriculture Drone Mapping and Analytics Market
Precision Agriculture
Digital Agriculture Market
Precision Agriculture
Agricultural Sensors Market
Precision Agriculture
Global Precision Livestock Farming Market
Precision Agriculture
Global Digital Agriculture Platform Market
Precision Agriculture
Crop Monitoring Market
Precision Agriculture
Soil Moisture Meter Market
Precision Agriculture
Crop Nutrient Management Market
Precision Agriculture
United States Precision Farming Software Market
Precision Agriculture
Crop Monitoring Technology in Precision Farming Market
Precision Agriculture
Soil Moisture Sensor Market
Precision Agriculture
Precision Farming Market
Precision Agriculture
Precision Agriculture Soil Nutrient and Microbiome Field Test Devices Market