
 North America Precision Agriculture Market | 2026-2036
North America Precision Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
North America Precision Agriculture Market Intelligence
Silicon-based sensor arrays is shifting toward compound semiconductor substrates in precision agriculture hardware, cutting per-unit sensing costs while improving spectral resolution. John Deere leverages its captive dealer network to dominate installed-base upgrades across the Midwest. Trimble anchors its position through GNSS correction services that lock in recurring revenue from agribusiness accounts. Raven Industries specializes in spray application autonomy, competing on real-time droplet-size modulation.
Precision agriculture encompasses site-specific crop management systems that integrate geospatial positioning, remote sensing, and machine-actuated field operations to optimize input application at sub-acre resolution. These systems typically process NDVI imagery at 10-centimeter ground sample distances while executing variable-rate prescriptions through ISO 11783-compliant task controllers. Software and automated equipment capture the deepest margin pools as farmers prioritize subscription-based farm management information systems and autonomous machinery fleets over point-hardware purchases. IoT-enabled sensor networks represent the fastest-expanding technology segment, though GPS remains the foundational layer for virtually all spatially-referenced field operations.
The EPA enforces pesticide application standards that mandate buffer-zone documentation and drift mitigation, directly stimulating demand for GIS-tracked sprayers and automated boom-section control. The USDA's conservation programs incentivize nutrient management planning that rewards variable-rate fertilization adoption, while the FAA governs commercial drone operations below 400 feet for crop scouting and multispectral imaging. Stakeholders must weigh capital deployment between retrofit autonomy kits for existing machinery and full-platform replacements as equipment cycles converge with 5G private-network rollouts.
Market Dynamics
Variable-rate input adoption across the Corn Belt is compressing equipment replacement cycles as farmers prioritize ISO 11783-compliant task controllers over legacy guidance systems.
Growth Catalysts
- USDA Conservation Programs:Nutrient management planning incentives reward variable-rate fertilization adoption across Midwest row-crop operations.
- EPA Pesticide Standards:Revised buffer-zone documentation mandates drive demand for GIS-tracked sprayers with automated boom-section control.
- Canadian Prairie Scale:Large-scale operations in Alberta and Saskatchewan accelerate automation uptake through fleet-wide sensor deployment.
Market Restraints
- Compound Semiconductor Supply:Silicon carbide substrate shortages constrain sensor array production for spectral imaging hardware.
- Dealer Network Concentration:Captive distribution channels in the Midwest limit price competition for retrofit autonomy kits.
- 5G Rural Coverage Gaps:Private network rollouts lag in Nebraska and Kansas, delaying real-time data transmission for edge-computing applications.
Strategic Opportunities
- Mexico Northern States:Chihuahua and Sonora irrigation districts present underpenetrated demand for precision water management systems.
- Drone-as-a-Service Models:FAA Part 107 compliance frameworks enable third-party multispectral imaging without farmer capital outlay.
- 5G-IoT Convergence:Private network infrastructure supports dense sensor mesh deployments for sub-acre soil moisture monitoring.
Industry Challenges
- Data Interoperability:Proprietary farm management information systems resist API standardization, complicating multi-vendor fleet integration.
- ISO 11783 Certification Timelines:Task controller validation delays equipment deployment by two to three growing seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Precision Agriculture Market |
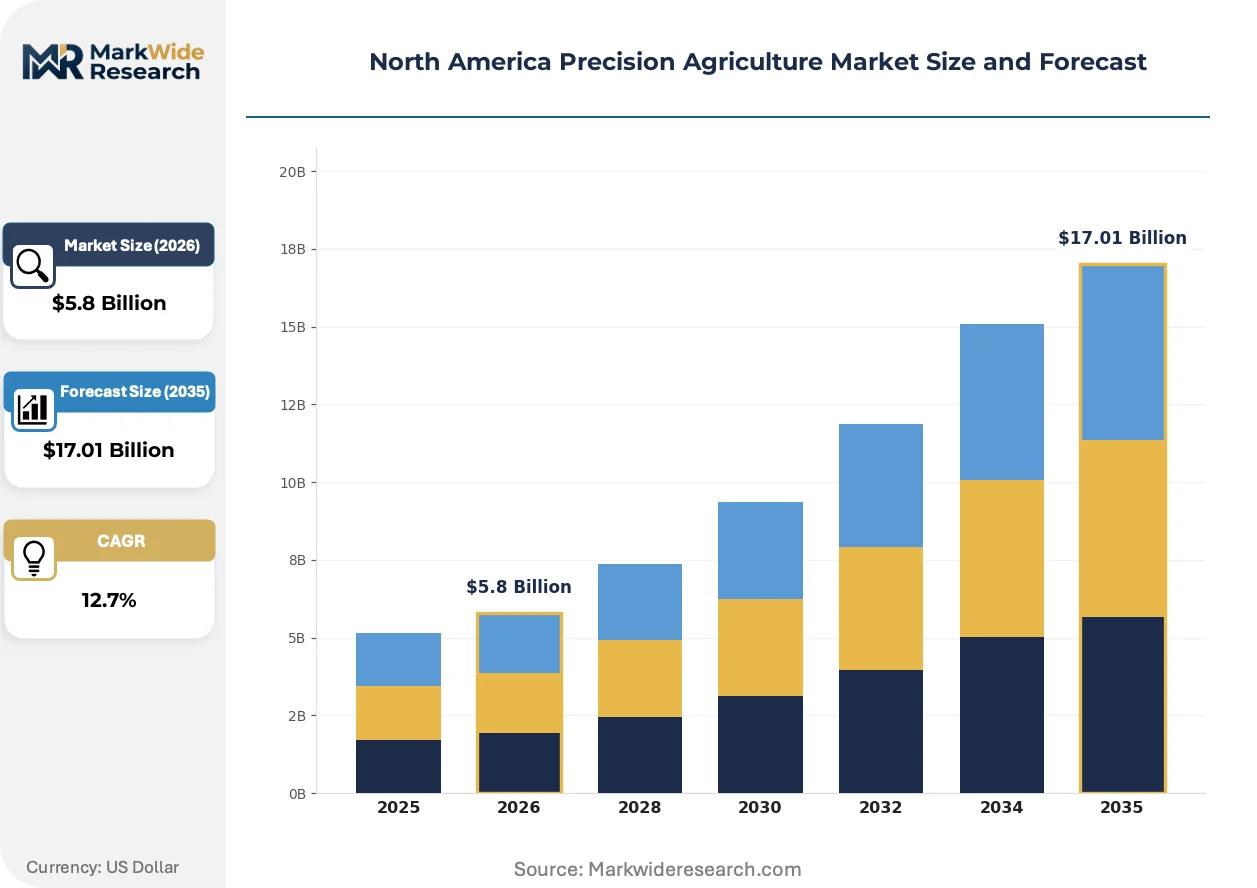
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $17.01 Billion |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drones, Sensors, Software, Automated Equipment End User: Farmers, Agribusinesses, Co-operatives, Research Institutions Technology: GPS, IoT, Artificial Intelligence, Big Data Analytics Application: Crop Monitoring, Soil Analysis, Yield Prediction, Irrigation Management |
| Companies Covered | CNH Industrial, Raven Industries, John Deere, Farmers Edge, Ag Leader Technology, Trimble, Topcon Agriculture, Climate LLC, AGCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Precision Agriculture Market Strategic Shifts & Innovations
Hardware substrate transitions and regulatory compliance mandates are redefining competitive advantage in field-level automation systems.
Spectral imaging arrays are integrating compound semiconductor substrates to replace silicon-based sensors, improving resolution for nitrogen stress detection. Corn Belt cooperatives are adopting these arrays at replacement-cycle pace for variable-rate nitrogen prescription. The technology is integrating real-time droplet-size modulation with boom-section control, compressing application error margins below three percent.
The EPA's drift mitigation mandates require GIS-tracked documentation for every pesticide application event. Spray equipment manufacturers must embed automated logging systems to satisfy compliance audits. Nebraska and Iowa retailers face the steepest retrofit obligations as their installed bases lack ISO 11783-compliant task controllers.
Subscription-based farm management information systems displace perpetual-license software across mid-scale operations. Dealer networks unbundle hardware sales from data-analytics services, shifting revenue to recurring models. Ontario and Manitoba demonstrate the fastest transition as large-scale farms prioritize operational expenditure over capital deployment.
North America Precision Agriculture Market Segmentation
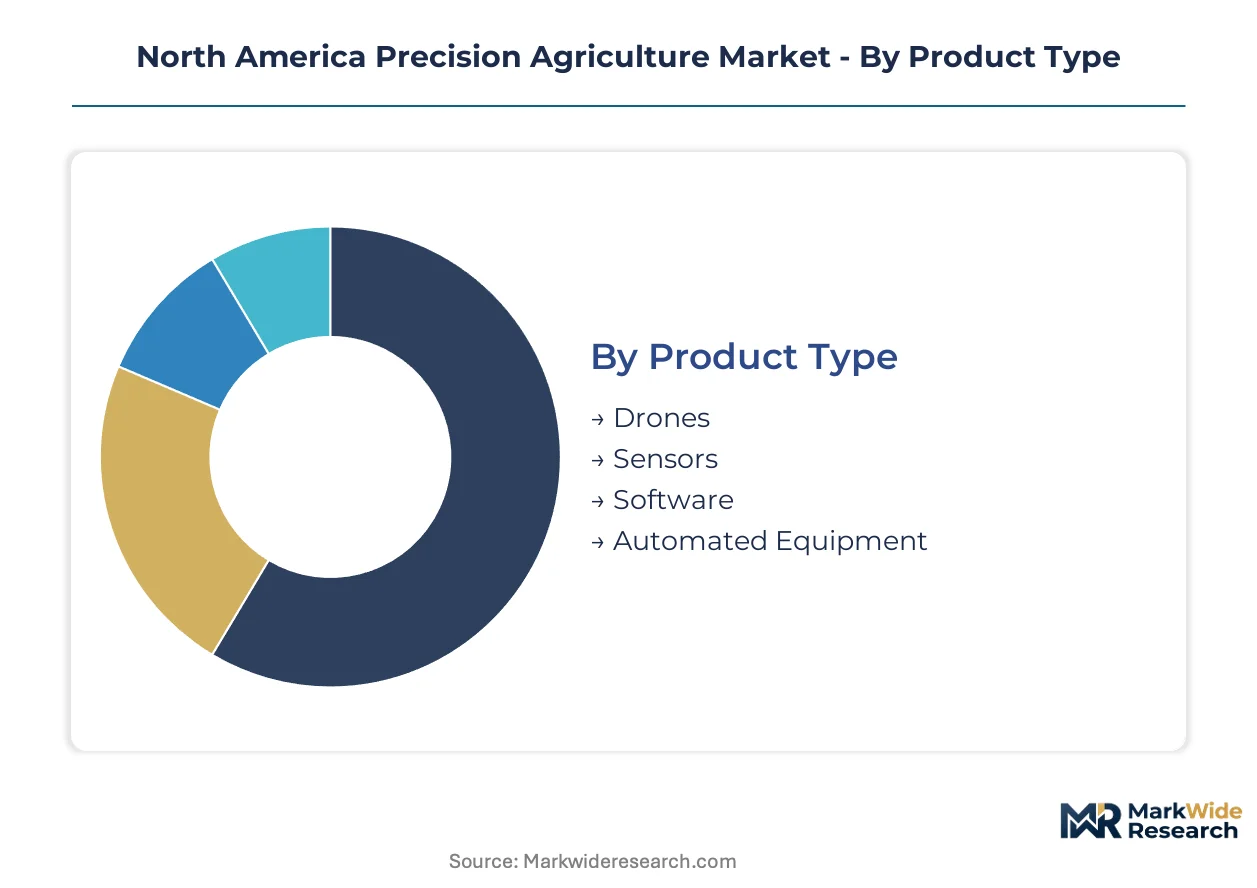
Precision agriculture vendors configure product portfolios around farm-scale economics and regulatory compliance requirements. Segmentation reveals where subscription revenue concentrates versus capital equipment sales. The analysis tracks how ISO 11783 compliance and EPA documentation mandates reshape purchasing patterns across customer tiers.
Product Type:
Customization intensity spans from off-the-shelf software subscriptions to fully integrated autonomous machinery requiring dealer installation networks.
- Automated Equipment:Self-propelled sprayers and autonomous tractors integrate ISO 11783 task controllers with variable-rate actuators. Nebraska and Iowa retailers face steepest retrofit demand as legacy guidance systems lack EPA-mandated GIS documentation capabilities.
- Software:Farm management information systems process NDVI imagery and generate variable-rate prescriptions at sub-acre resolution. Subscription models displace perpetual licenses across Ontario and Manitoba as large-scale operations prioritize operational expenditure structures.
- Sensors:Spectral imaging arrays on compound semiconductor substrates detect nitrogen stress for real-time prescription adjustment.
- Drones:Multispectral platforms operate under FAA Part 107 below 400 feet for crop scouting and vegetation index mapping.
Leading the category by volume: Automated Equipment. Growing fastest: Software.
End User:
Purchasing sophistication ranges from individual farmer capital constraints to agribusiness fleet-scale standardization mandates.
- Agribusinesses:Multi-thousand-acre operations deploy fleet-wide sensor meshes through captive dealer networks. These entities negotiate enterprise software licenses with API integration requirements for multi-vendor equipment interoperability.
- Co-operatives:Member-owned entities aggregate purchasing power for variable-rate technology adoption across the Corn Belt. Shared machinery pools amortize ISO 11783 compliance costs across participating farms in Illinois and Indiana.
- Farmers:Individual operators select retrofit autonomy kits or entry-level guidance systems based on equipment replacement cycles.
- Research Institutions:University extension services and USDA facilities validate task controller algorithms for regional agronomic conditions.
Dominant by procurement scale: Agribusinesses. Expanding most quickly: Co-operatives.
Technology:
Technology layers stack from foundational positioning infrastructure through edge-computing intelligence requiring 5G backhaul.
- GPS:GNSS correction services deliver centimeter-level accuracy for automated steering and boundary mapping. Trimble anchors recurring revenue through subscription correction networks across Midwest row-crop territories.
- IoT:Dense sensor meshes monitor soil moisture and microclimate conditions at sub-acre resolution. Private 5G network rollouts in Alberta and Saskatchewan enable real-time data transmission for irrigation automation.
- Big Data Analytics:Cloud platforms aggregate multi-season yield data to optimize input prescriptions and predict commodity marketing windows.
- Artificial Intelligence:Machine vision systems classify weed species and crop stress patterns for targeted intervention.
Foundation of all spatial operations: GPS. Climbing the fastest: IoT.
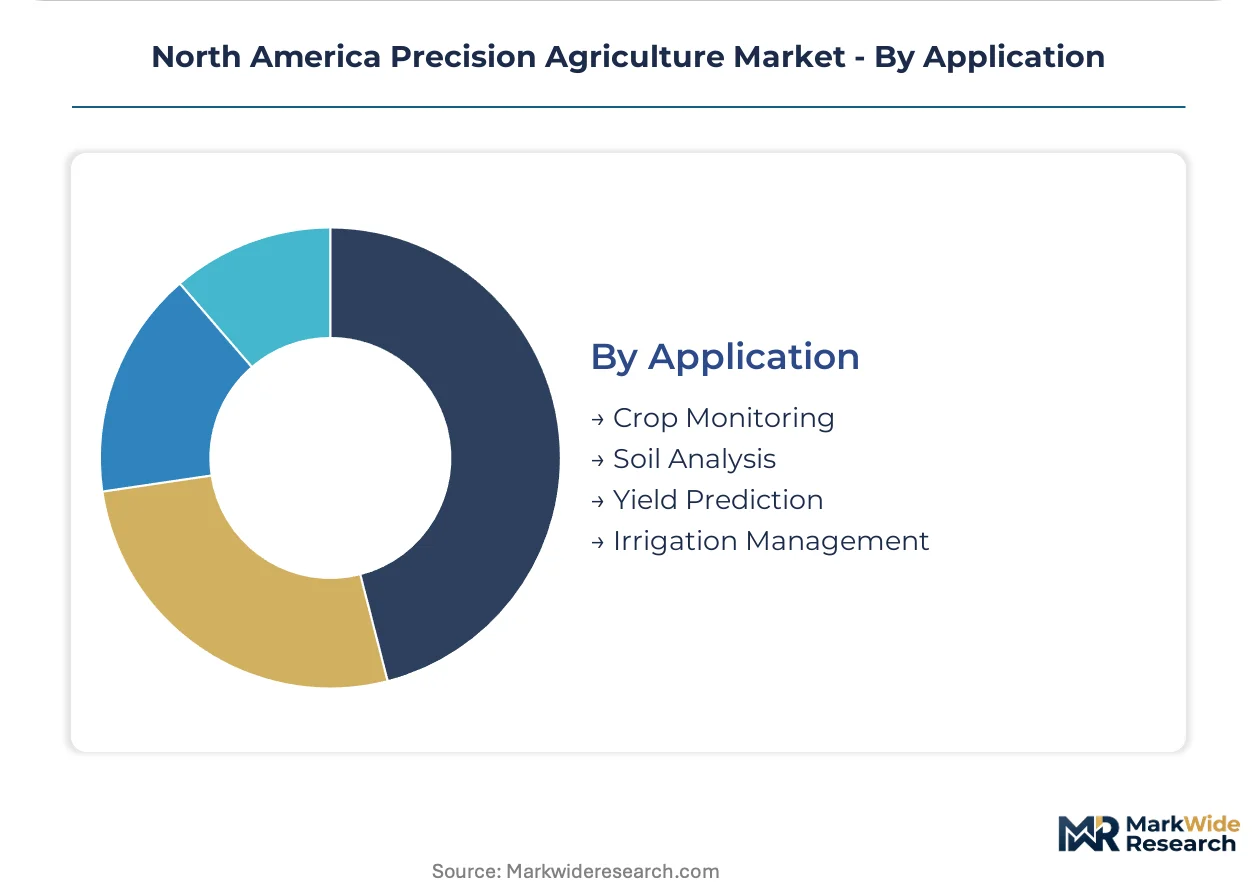
Application:
Application workflows progress from diagnostic monitoring through predictive intervention and closed-loop control systems.
- Crop Monitoring:NDVI imagery at 10-centimeter ground sample distances identifies vegetation stress for targeted scouting. Drone-as-a-service providers in Chihuahua and Sonora irrigation districts deliver multispectral surveys without farmer capital deployment.
- Irrigation Management:Variable-rate water application responds to soil moisture sensor feedback and evapotranspiration models. Northern Mexico districts present underpenetrated demand for precision water management amid groundwater constraints.
- Soil Analysis:Electromagnetic conductivity mapping and grid sampling guide lime and micronutrient variable-rate application.
- Yield Prediction:Multi-sensor fusion models forecast harvest volumes for logistics and marketing optimization.
Widest installed base: Crop Monitoring. Steepest expansion trajectory: Irrigation Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Opportunity Zone program and Canadian Prairie tax incentives concentrate precision agriculture investment across the Great Plains and Midwest corridors, channeling capital into sensor manufacturing clusters and autonomous equipment deployment zones.
United States
Corn Belt row-crop operations drive variable-rate technology adoption through equipment replacement cycles. The EPA's revised pesticide application standards mandate GIS-tracked documentation and automated boom-section control for drift mitigation. Illinois and Iowa host dense dealer networks installing ISO 11783-compliant task controllers across aging sprayer fleets.
Canada
Alberta and Saskatchewan large-scale operations accelerate fleet-wide sensor deployment through economies of scale. Agriculture and Agri-Food Canada conservation programs incentivize variable-rate fertilization adoption across Prairie provinces. Winnipeg and Regina anchor precision agriculture service hubs supporting cross-border equipment integration.
Mexico
Chihuahua and Sonora irrigation districts present underpenetrated demand for precision water management amid groundwater constraints. The national water authority CONAGA promotes drip irrigation efficiency standards requiring soil moisture sensor integration. Culiacán and Los Mochis clusters demonstrate early drone-as-a-service adoption for multispectral crop scouting.
North America Precision Agriculture Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated OEMs commanding retrofit upgrade cycles while independent sensor vendors penetrate greenfield automation deployments. The market structure concentrates around three strategic archetypes: captive dealer-network operators, GNSS correction-service platforms, and spray-application autonomy specialists. Dominant competitive moves include backward integration into compound semiconductor substrates and strategic partnerships for 5G private-network infrastructure.
Among North American equipment manufacturers, John Deere, Trimble, and Raven Industries exemplify distinct competitive positioning. John Deere occupies the integrated OEM tier through captive distribution control. Trimble anchors the precision-positioning services segment through recurring-revenue GNSS correction networks. Raven Industries represents the application-specific autonomy vector with specialization in real-time spray modulation systems.
| Leading Market Players |
|---|
| CNH Industrial |
| Raven Industries |
| John Deere |
| Farmers Edge |
| Ag Leader Technology |
| Trimble |
| Topcon Agriculture |
| Climate LLC |
| AGCO Corporation |
| Others |
Cost & Logistics Intelligence
Backward integration into compound semiconductor substrates anchors both supply security and pricing power for spectral imaging hardware vendors serving Corn Belt equipment retrofits. John Deere's captive dealer network locks in ISO 11783-compliant task controller premiums while constraining price competition for retrofit autonomy kits across Nebraska and Iowa.
Pricing Analysis
Volume concentrates in automated equipment sales while margin pools deepen in subscription-based farm management information systems. Pricing stratifies across premium dealer-installed autonomy platforms, standard retrofit guidance kits, and economy entry-level GPS systems. Cost compression in sensor arrays is intensifying because silicon carbide substrate shortages force longer lead times. Agribusiness fleet operators demonstrate lowest price sensitivity; individual farmers in equipment replacement cycles show highest.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for compound semiconductor wafer production feeding spectral imaging arrays. Raw material dependencies span silicon carbide substrates, GNSS receiver modules, and ISO 11783-compliant controller boards. Tariff exposure runs through China-sourced electromagnetic sensor components. Distribution runs through captive dealer networks in the Midwest and independent precision agriculture service hubs in Alberta and Saskatchewan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is forcing smaller sensor vendors and regional software providers toward strategic exits as EPA compliance mandates raise certification barriers. ISO 11783 validation timelines and compound semiconductor supply constraints favor scaled players with captive dealer networks.
For Market Incumbents: Cement dealer network loyalty through exclusive ISO 11783 task controller distribution rights in Illinois and Indiana. Lock in recurring revenue by bundling GNSS correction services with automated equipment sales. Raven Industries' spray application specialization demonstrates how application-specific autonomy defends against full-platform OEMs.
For New Entrants and Emerging Players: Drone-as-a-service providers in Chihuahua and Sonora irrigation districts offer the most penetrable entry vector without capital equipment sales. Target Mexican northern states for precision water management systems amid CONAGA efficiency mandates. Partner with established agribusiness cooperatives for shared machinery pool deployments.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated OEMs seeking spray application autonomy or GNSS correction service capabilities. Five-to-ten-year viability favors vendors with backward integration into compound semiconductor substrates. Watch EPA pesticide standard enforcement intensity as the inflection signal for retrofit demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compound Semiconductors | Silicon carbide substrate control insulates sensor production costs from Taiwan supply volatility. |
| 5G Private Network Infrastructure Partnership | Alberta and Saskatchewan deployments enable real-time IoT sensor mesh data transmission. |
| Drone-as-a-Service Platform Launch | FAA Part 107 compliance frameworks unlock Chihuahua and Sonora irrigation district penetration. |
| ISO 11783 Certification Investment | Task controller validation accelerates Nebraska and Iowa sprayer fleet retrofit cycles. |
| Subscription-Based FMIS Transition | Ontario and Manitoba large-scale operations shift capital expenditure to operational expenditure structures. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with precision agriculture OEM product managers, dealer network operators, agribusiness fleet managers, and USDA extension agronomists validated demand patterns. EPA pesticide application standards, FAA Part 107 commercial drone regulations, and Agriculture and Agri-Food Canada conservation program documentation provided regulatory anchors. Bottom-up equipment shipment tracking and top-down addressable market sizing triangulated volume estimates.
Segmentation granularity modeled product type at the platform level, end user at the operational scale tier, technology at the infrastructure layer, and application at the workflow stage across the projection horizon. Compound semiconductor supply constraints, 5G rural coverage rollout pace, and ISO 11783 certification queue lengths informed scenario-weighted CAGRs. Spatial resolution specifications and NDVI imagery processing capabilities provided hardware-specific forecast inputs.
Caveats apply where EPA enforcement intensity, silicon carbide substrate availability, or 5G private network deployment delays could materially shift the outlook. Forecasts reflect documented assumptions about equipment replacement cycle convergence and regulatory compliance timeline adherence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Precision Livestock Market
Precision Agriculture
Remote Fertigation Monitoring Services Market
Precision Agriculture
Global Agriculture Sensors Market
Precision Agriculture
Agricultural Mapping Services Market
Precision Agriculture
Asia-Pacific Agricultural Sensors Market
Precision Agriculture
Variable Rate Technology Market
Precision Agriculture
Precision Farming Software Market
Precision Agriculture
Precision Agriculture Soil Nutrient and Microbiome Field Test Devices Market
Precision Agriculture
Crop Monitoring Market
Precision Agriculture
Digital Farming Technology Market
Precision Agriculture
Digital Agriculture Solutions Market
Precision Agriculture
Global Internet of Things (IoT) Agriculture Market
Precision Agriculture
Digital Agriculture Market
Precision Agriculture
Americas Precision Farming Software Market
Precision Agriculture
Crop Nutrient Management Market
Precision Agriculture
Global Precision Farming Software and Services Market