
 Precision Agriculture Soil Nutrient and Microbiome Field Test Devices Market | 2026-2036
Precision Agriculture Soil Nutrient and Microbiome Field Test Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Precision Agriculture Soil Nutrient and Microbiome Field Test Devices Market Insights
Specialty crop growers is redrawing procurement patterns for field test devices as commodity grain operations trim capital budgets. HORIBA leverages its optical sensor expertise to dominate high-value horticulture segments. Thermo Fisher Scientific anchors the DNA sequencing tier for microbiome analyzers. AgroCares Technology competes through portable spectrometer platforms built for unskilled field operators.
Precision agriculture soil nutrient and microbiome field test devices comprise electrochemical and optical sensor assemblies, fluorescence detection modules, and portable DNA sequencing units designed to quantify macronutrient availability and microbial community composition directly at the sampling site without laboratory transit delays. These instruments typically resolve nitrogen, phosphorus, and potassium concentrations within minutes while flagging biological indicators such as bacterial-fungal ratios that govern nutrient cycling efficiency. Soil nutrient testers command the largest installed base, though microbiome analyzers represent the fastest-expanding margin pool as biological farming protocols gain traction. Electrochemical sensors sustain cost leadership in fertilizer management applications, while optical sensors capture premium positioning in soil health assessment workflows where multispectral resolution determines diagnostic value.
The EPA regulates agricultural runoff thresholds that directly mandate soil testing frequency under the Clean Water Act, while the EU Green Deal's soil health directives require standardized microbiome monitoring across member state agricultural zones. ISO 11277 and ISO 11464 frame particle-size and pretreatment protocols that device manufacturers must embed for cross-border certification acceptance. Stakeholders must weigh electrochemical platform refresh cycles against optical and DNA-based upgrade paths as regulatory baselines tighten.
Market Dynamics
The EU Green Deal's soil health monitoring mandates are compressing certification timelines for field test device manufacturers while simultaneously opening procurement channels for biological farming cooperatives across member states.
Growth Catalysts
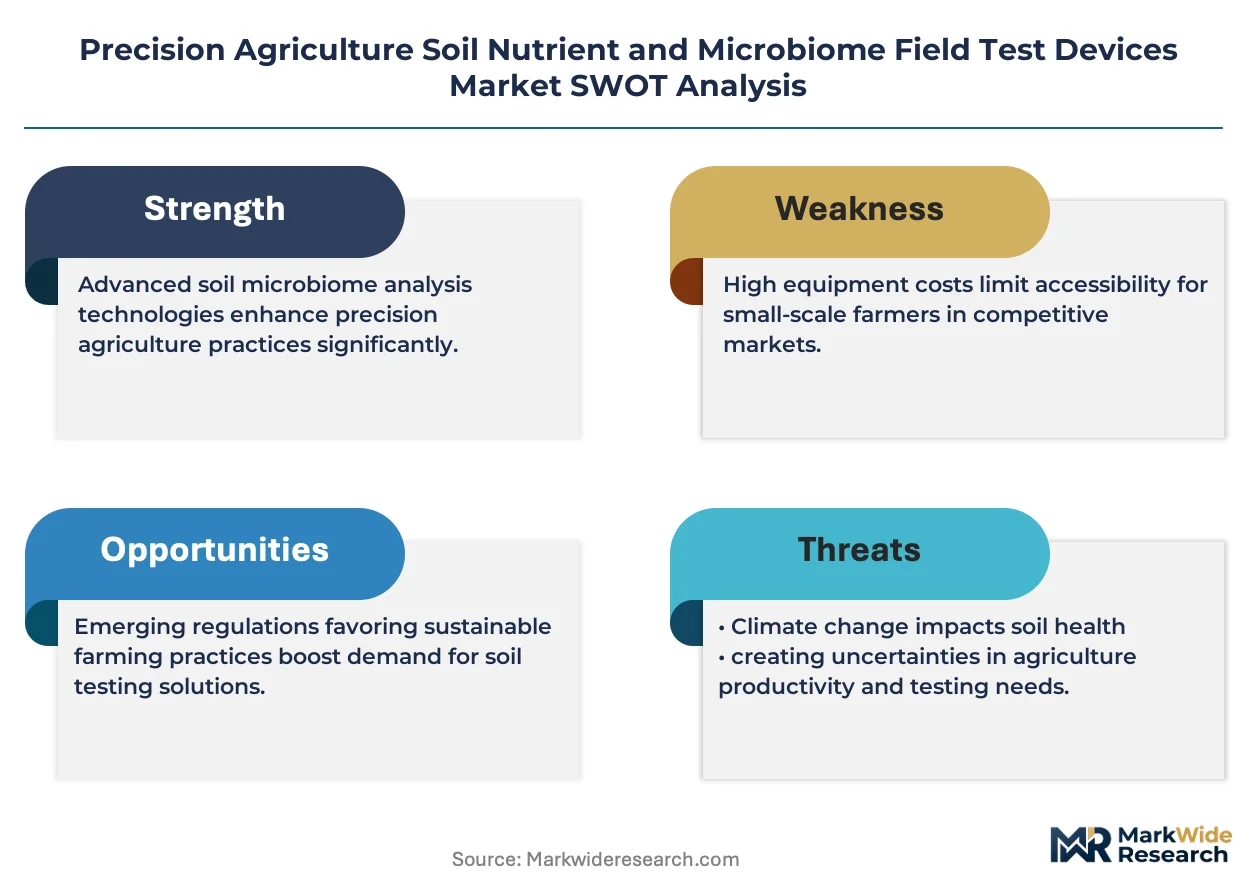
- EU Green Deal soil directives:Standardized microbiome monitoring requirements across agricultural zones are creating mandatory replacement cycles for legacy nutrient-only testers.
- Large-scale row-crop operations:On-site diagnostics eliminate laboratory transit delays, compressing fertilizer application windows and reducing input waste.
- Fluorescence detection modules:Real-time bacterial-fungal ratio quantification enables biological farming protocols that command premium crop pricing.
Market Restraints
- Optical sensor component concentration:German and Japanese precision optics suppliers control critical multispectral detector supply, creating single-source vulnerability.
- DNA sequencing reagent cost volatility:Proprietary consumable cartridges for portable microbiome analyzers carry 40-60% gross margins that squeeze operator economics.
- ISO 11277 certification friction:Particle-size protocol compliance requires embedded firmware validation that extends product development cycles.
Strategic Opportunities
- Specialty crop horticulture:High-value vineyard and greenhouse operations in Italy and Spain are deploying combined nutrient-microbiome sensors for terroir optimization.
- CE marking pathway acceleration:Harmonized EU device certification enables cross-border sales without member-state re-registration.
- Electrochemical-optical convergence:Hybrid platforms integrating low-cost ion-selective electrodes with multispectral validation are capturing mid-market fertilizer management workflows.
Industry Challenges
- Field operator skill deficit:Portable spectrometer platforms require training in sample pretreatment protocols that agronomists historically delegated to laboratory technicians.
- Legacy laboratory integration:On-site devices must synchronize data formats with established farm management information systems, creating API development burdens.
- Calibration drift management:Electrochemical sensors demand frequent recalibration against certified reference materials that rural operators struggle to source.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precision Agriculture Soil Nutrient and Microbiome Field Test Devices Market |
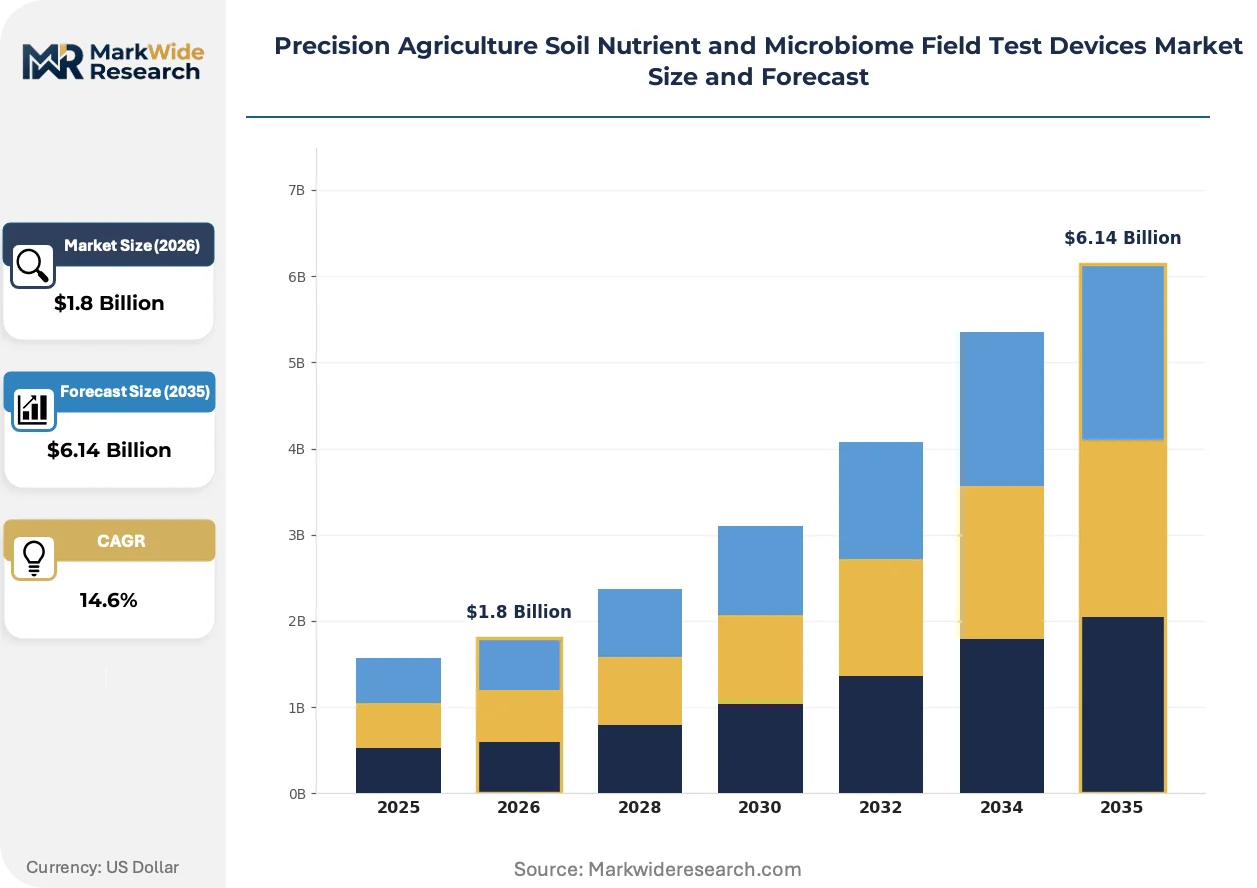
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soil Nutrient Testers, Microbiome Analyzers, Combined Soil Sensors, Portable Spectrometers Technology: Electrochemical Sensors, Optical Sensors, DNA Sequencing, Fluorescence Analysis Application: Crop Yield Optimization, Soil Health Assessment, Fertilizer Management, Precision Irrigation End User: Agri-Tech Companies, Crop Consultants, Horticulturists, Soil Testing Labs |
| Companies Covered | HORIBA, Hanna Instruments, LaMotte, Sentek Technologies, Teralytic, Prolific Earth Sciences, Agilent Technologies, Thermo Fisher Scientific, AgroCares Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precision Agriculture Soil Nutrient and Microbiome Field Test Devices Market Trends and Innovations
Portable DNA sequencing hardware is compressing the time-to-result for microbial community analysis from weeks to hours, enabling real-time biological farming decisions that were previously impossible.
Handheld nanopore sequencing units are miniaturizing microbiome analysis for unskilled field operators. Specialty crop growers in high-value horticulture segments are adopting these platforms at accelerating rates. The technology is miniaturizing laboratory-grade bacterial-fungal ratio detection into sub-kilogram devices that integrate with smartphone interfaces.
EPA agricultural runoff thresholds under the Clean Water Act are tightening soil testing frequency mandates for operations near watershed boundaries. Fertilizer management applications face stepped compliance documentation requirements. Large-scale row-crop operations in the Corn Belt are responding by deploying electrochemical sensor networks with automated data logging.
Cooperative procurement consortia are consolidating demand for field test devices across German precision farming networks. Traditional distributor channels face disintermediation as buying groups negotiate direct manufacturer relationships. This pattern concentrates most visibly in Bavaria and Baden-Württemberg, where agricultural cooperatives pool capital equipment investments.
Precision Agriculture Soil Nutrient and Microbiome Field Test Devices Market Segmentation
Segmentation in precision agriculture soil diagnostics reveals how device capabilities align with distinct operational workflows and regulatory compliance tiers. Procurement patterns diverge sharply between commodity grain operations seeking cost efficiency and specialty crop growers pursuing terroir differentiation.
Product Type:
German precision farming cooperatives drive domestic demand for combined soil sensors, while export markets in Italy and Spain concentrate orders for portable spectrometers suited to high-value horticulture.
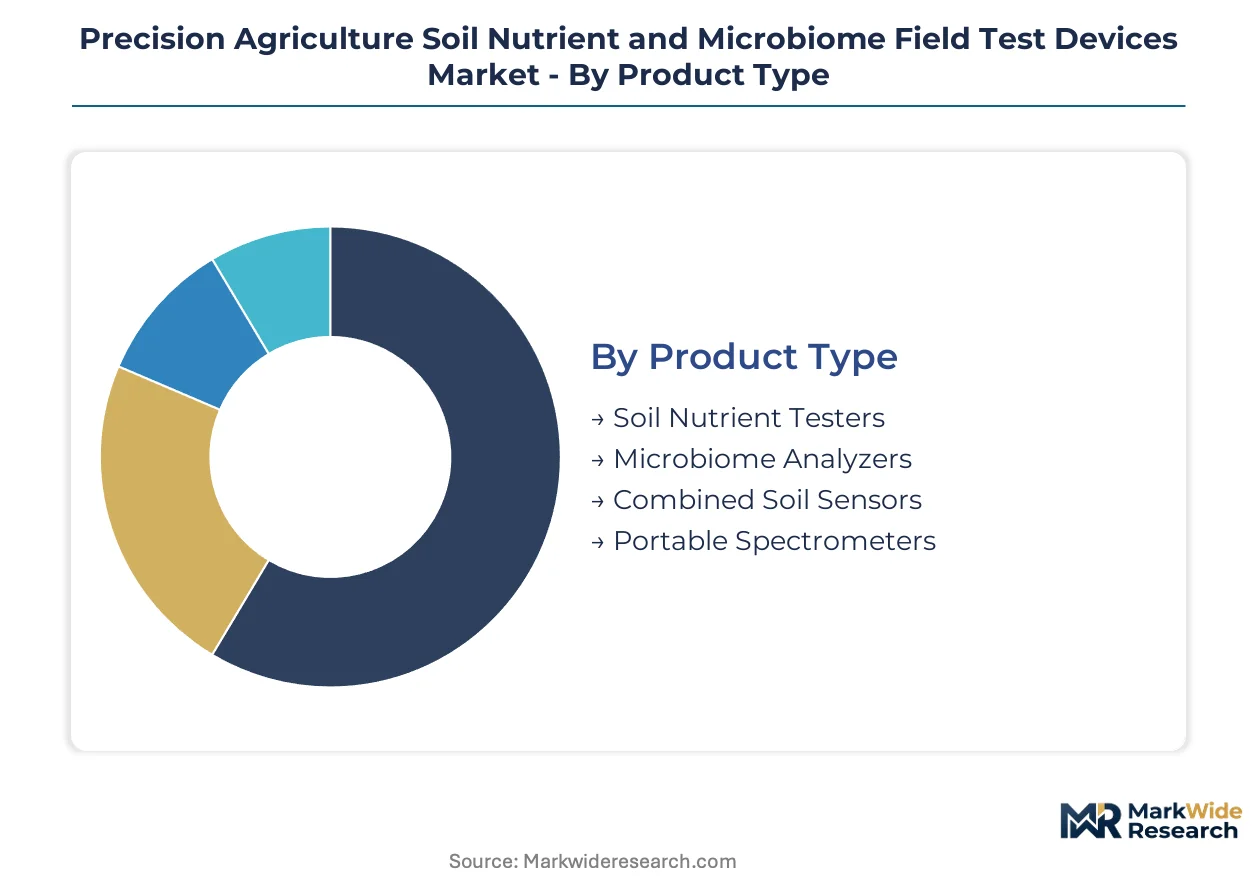
- Soil Nutrient Testers:Electrochemical sensor assemblies measuring nitrogen, phosphorus, and potassium concentrations through ion-selective electrodes. Large-scale row-crop operations in the Corn Belt deploy these for fertilizer management compliance with EPA Clean Water Act runoff thresholds.
- Microbiome Analyzers:Portable DNA sequencing units and fluorescence detection modules quantifying bacterial-fungal ratios. Biological farming cooperatives across EU member states adopt these for EU Green Deal soil health monitoring mandates.
- Combined Soil Sensors:Hybrid platforms integrating electrochemical and optical detection for simultaneous nutrient and biological assessment.
- Portable Spectrometers:Handheld multispectral devices requiring minimal operator training for vineyard and greenhouse terroir optimization.
Soil Nutrient Testers commands the established base. The steepest expansion runs through Microbiome Analyzers.
Technology:
Cost tier differentiation separates electrochemical platforms serving budget-conscious fertilizer management from premium optical and DNA-based systems commanding soil health assessment workflows.
- Electrochemical Sensors:Ion-selective electrodes and voltammetric cells delivering cost leadership in macronutrient quantification. Calibration drift against certified reference materials creates operational friction for rural operators.
- Optical Sensors:Multispectral and hyperspectral detectors capturing soil organic matter and moisture signatures. German and Japanese precision optics suppliers control critical detector supply chains.
- DNA Sequencing:Nanopore and fluorescence-based portable units compressing microbial community analysis from weeks to hours.
- Fluorescence Analysis:Real-time bacterial-fungal ratio detection enabling biological farming protocol adoption.
Electrochemical Sensors anchor volume deployment. Optical Sensors capture the fastest margin expansion.
Application:
Volume concentration in Fertilizer Management reflects commodity agriculture scale, while margin expansion clusters in Soil Health Assessment driven by premium crop pricing and regulatory documentation requirements.
- Crop Yield Optimization:Integrated nutrient and microbiome monitoring for maximizing output per hectare.
- Soil Health Assessment:Comprehensive biological and chemical profiling for regenerative agriculture certification. EU Green Deal directives mandate standardized monitoring protocols across member state agricultural zones.
- Fertilizer Management:Macronutrient testing aligned with EPA agricultural runoff thresholds and precision input reduction targets.
- Precision Irrigation:Moisture and salinity detection integrated with automated water delivery systems.
Fertilizer Management dominates unit shipments. Soil Health Assessment is climbing the fastest.
End User:
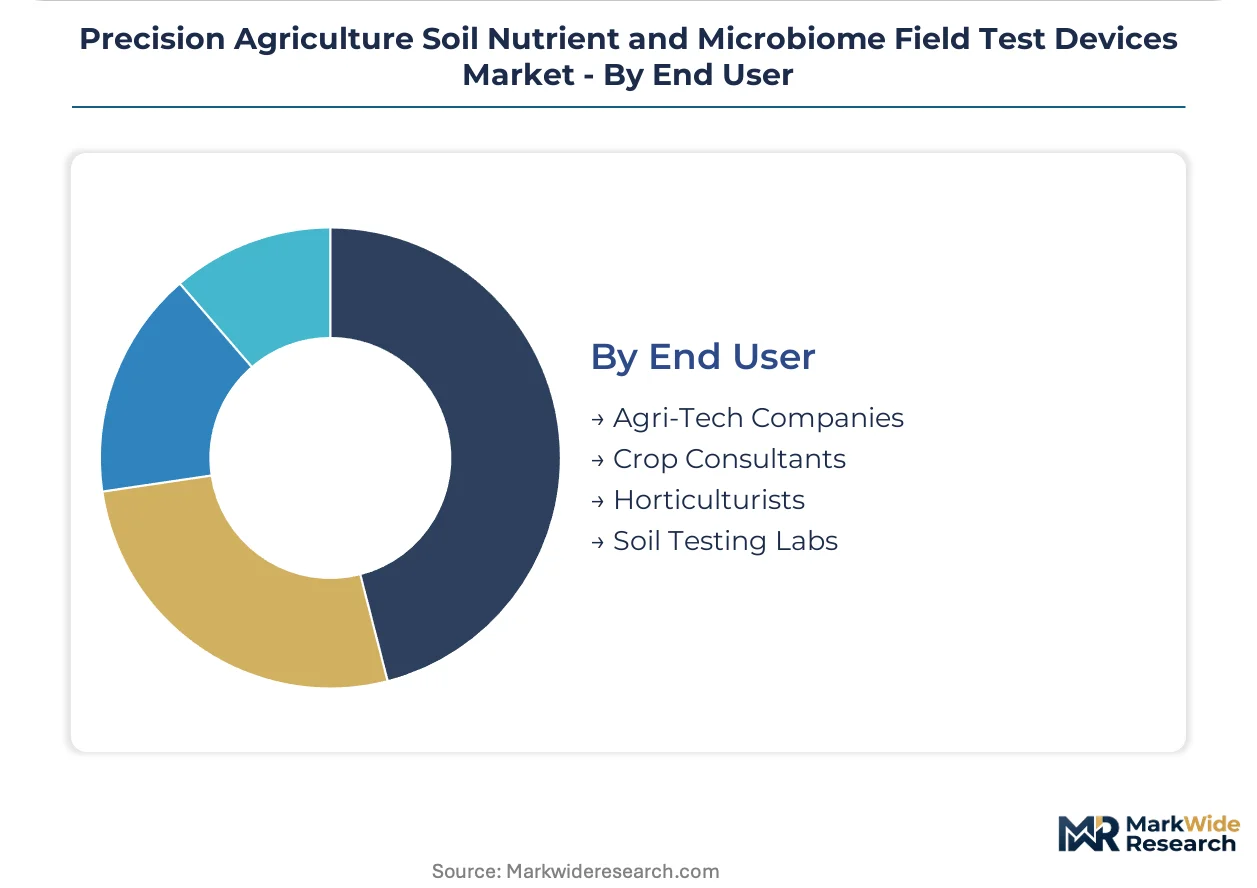
Customer type stratification shows Agri-Tech Companies consolidating procurement through cooperative networks, while Soil Testing Labs face disintermediation from on-site diagnostic adoption.
- Agri-Tech Companies:Technology integrators bundling field test devices with farm management information systems and data analytics platforms.
- Crop Consultants:Independent agronomists deploying portable units for client advisory services requiring rapid turnaround.
- Horticulturists:Specialty crop growers in high-value segments pursuing terroir optimization through combined nutrient-microbiome sensing.
- Soil Testing Labs:Traditional laboratory operators integrating portable devices for field validation or facing displacement from direct-to-farm diagnostic adoption.
Agri-Tech Companies concentrate procurement volume. Horticulturists show the steepest adoption trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Danube freight corridor underwrites Central Europe's dominance in precision agriculture device distribution, connecting German manufacturing clusters to Black Sea agricultural zones. Container throughput at Rotterdam's Europoort terminal funnels Asian optical sensor components into EU assembly plants. The Union Pacific rail network links California component suppliers to Midwest row-crop deployment sites.
Germany
Bavarian precision farming cooperatives pool capital equipment investments for combined soil sensor deployments. The EU Green Deal's soil health monitoring mandates compress certification timelines for device manufacturers seeking CE marking acceptance. Stuttgart's precision optics cluster supplies multispectral detectors to domestic instrument assemblers facing export demand from Italian vineyards.
United States
Corn Belt row-crop operations deploy electrochemical sensor networks to meet EPA Clean Water Act runoff documentation requirements. The Inflation Reduction Act's conservation incentive programs accelerate on-site diagnostic procurement for fertilizer management compliance. Illinois and Iowa agricultural zones concentrate automated soil testing infrastructure along watershed boundaries.
China
Yangtze River Delta greenhouse operators import portable spectrometers for high-value horticulture quality control. The Ministry of Ecology and Environment's agricultural non-point source pollution controls tighten soil testing frequency mandates near Taihu Lake. Nanjing's instrument manufacturing base produces cost-optimized electrochemical sensors for domestic fertilizer management applications.
Italy
Tuscan and Piedmont vineyard operations adopt combined nutrient-microbiome sensors for terroir differentiation in premium wine segments. EU Green Deal standardized monitoring protocols drive replacement cycles for legacy laboratory-dependent testing workflows. Bologna's agricultural technology cluster hosts integration specialists bundling field devices with farm management information systems.
Australia
Murray-Darling Basin irrigation districts deploy precision soil diagnostics to comply with basin-wide salinity and nutrient management plans. The country's national agricultural regulator mandates standardized soil health reporting for water access entitlement renewals. Adelaide's sensor calibration facilities service electrochemical platforms across southeastern grain-growing regions.
Precision Agriculture Soil Nutrient and Microbiome Field Test Devices Market Competitive Landscape
Concentration sits with diversified analytical instrument conglomerates and specialized agricultural technology developers. The vendor base stratifies across three tiers: premium optical sensor specialists commanding soil health assessment workflows, mid-market electrochemical platform providers serving fertilizer management compliance, and emerging portable DNA sequencing entrants capturing biological farming adoption curves. Dominant competitive moves include backward integration into precision optics supply and strategic partnerships with farm management software platforms.
Among diversified analytical conglomerates, HORIBA and Thermo Fisher Scientific exemplify contrasting archetype positions. HORIBA leverages its Japanese optical sensor heritage to anchor premium horticulture segments. Thermo Fisher Scientific occupies the DNA sequencing tier for microbiome analyzers through its North American life sciences infrastructure. AgroCares Technology, a Netherlands-based developer, represents the specialized agricultural technology archetype with portable spectrometer platforms engineered for unskilled field deployment.
| Leading Market Players |
|---|
| HORIBA |
| Hanna Instruments |
| LaMotte |
| Sentek Technologies |
| Teralytic |
| Prolific Earth Sciences |
| Agilent Technologies |
| Thermo Fisher Scientific |
| AgroCares Technology |
| Others |
Pricing and Supply Chain Analysis
Optical sensor substitution for electrochemical platforms in premium soil health assessments redraws procurement geography toward German and Japanese precision optics clusters while compressing margin structures for legacy ion-selective electrode manufacturers serving commodity fertilizer management workflows.
Pricing Analysis
Volume-discount tiering structures stratify across cooperative procurement consortia, individual agri-tech integrators, and laboratory service operators. Price differentiation rests on ISO 11277 certification grade and bundled after-sales calibration support. Cost compression in the electrochemical tier intensifies as Chinese manufacturers scale ion-selective electrode production for domestic fertilizer compliance markets. Cooperative buyers in German precision farming networks exhibit lowest price sensitivity; independent crop consultants face acute margin pressure from reagent cartridge economics.
Supply Chain Analysis
Container availability constraints on the Asia-Europe trade lane elevate inbound logistics costs for multispectral detector components sourced from Japanese precision optics suppliers. Manufacturing concentration centers on Germany, China, and the Netherlands for final instrument assembly. Critical dependencies include ion-selective electrode membranes, nanopore sequencing flow cells, and certified reference material calibration standards. Single-source vulnerability runs through German optical component suppliers. Distribution runs through cooperative procurement networks disintermediating traditional agricultural equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal soil health mandates constitute a regulatory inflection compressing replacement cycles for legacy nutrient-only testers while opening procurement channels for biological farming cooperatives across member states.
For Market Incumbents: Fortify backward integration into precision optics supply chains to secure multispectral detector availability against Japanese supplier concentration. Expand CE marking pathway investments to compress certification timelines as EU directives tighten. Defensive positioning requires preemptive firmware validation for ISO 11277 protocol compliance before regulatory baselines shift. For New Entrants and Emerging Players: Field operator training deficits in sample pretreatment protocols present a service-layer gap where incumbents under-serve. Portable spectrometer deployment support for unskilled vineyard operators in Italian and Spanish high-value horticulture segments offers the most penetrable white space. Go-to-market execution should anchor on smartphone-integrated interfaces that eliminate agronomist dependency. For Investors and Strategic Acquirers: The market sits at an early-expansion phase that favors portable DNA sequencing platform developers with regulatory pre-qualification. Long-term viability over the next decade hinges on microbiome analyzer margins sustaining biological farming adoption curves. Watch EU member state implementation timelines for standardized monitoring protocols as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | Harmonized EU certification enables cross-border sales without member-state re-registration friction. |
| Backward Integration into Optics | In-house multispectral detector production mitigates single-source dependency on German and Japanese suppliers. |
| Platform Integration with Farm Management Systems | API development for established agricultural software platforms reduces legacy laboratory displacement resistance. |
| Portable DNA Sequencing Miniaturization | Sub-kilogram nanopore units capture biological farming cooperative procurement outside laboratory-dependent workflows. |
| Cooperative Procurement Channel Development | Direct manufacturer relationships with German precision farming networks bypass traditional distributor markups. |
Research Methodology
A standing panel of precision agriculture equipment procurement managers, soil testing laboratory directors, agronomic service providers, and regulatory compliance officers provided ongoing calibration throughout the study. Primary field engagement combined structured interviews with cooperative network representatives and secondary validation against EU regulatory filing databases, EPA Clean Water Act compliance documentation, and ISO certification registry records. Bottom-up unit shipment estimates from device manufacturers triangulated against top-down agricultural expenditure surveys across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including customs trade data for optical sensor component flows and agricultural cooperative capital equipment disclosure filings. The analytical framework modeled segmentation dimensions spanning product type, detection technology, application workflow, and end-user archetype across the projection horizon. CAGRs derived from logistic adoption curves fitted to biological farming protocol penetration rates and regulatory mandate implementation schedules.
Underlying assumptions cover EU Green Deal directive enforcement consistency, reagent cartridge cost stability, and optical component supply continuity, with deviation risk concentrated in member state regulatory implementation delays and trade lane logistics disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Crop Monitoring Market
Precision Agriculture
Global Advanced Farming Market
Precision Agriculture
Connected Agriculture Software Market
Precision Agriculture
Global Agriculture Sensors Market
Precision Agriculture
Europe Precision Farming Market
Precision Agriculture
Autonomous Crop Management Market
Precision Agriculture
Digital Agriculture Solutions Market
Precision Agriculture
Remote Fertigation Monitoring Services Market
Precision Agriculture
Digital Agriculture Market
Precision Agriculture
Soil Monitoring System Market
Precision Agriculture
Precision Livestock Market
Precision Agriculture
Digital Farming Technology Market
Precision Agriculture
Crop Nutrient Management Market
Precision Agriculture
Agriculture IoT Sensor Market
Precision Agriculture
Agricultural Mapping Services Market
Precision Agriculture
Crop Monitoring Technology in Precision Farming Market