
 Rice Milling Machinery Market | 2026-2036
Rice Milling Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Rice Milling Machinery Market Outlook
Dealer networks for rice milling equipment is fragmenting as manufacturers build direct-to-miller digital platforms and localized service hubs. Bühler Group leverages its Swiss engineering heritage to sustain premium positioning in large-scale automation lines across Asian markets. Satake Corporation anchors its competitive stance through deep specialization in optical sorting and precision grading systems. AG Growth International competes by extending its North American grain handling expertise into complementary rice processing portfolios.
Rice milling machinery encompasses equipment designed to convert paddy rice into polished, market-ready grain through sequential dehusking, whitening, polishing, and grading operations, with modern units achieving throughput rates exceeding 10 tonnes per hour and broken-grain control below 15 percent. The primary commercial purpose centers on maximizing head-rice yield while preserving nutritional value and meeting export-grade uniformity standards. Huskers and polishers dominate installed base value due to their irreplaceable role in the core processing chain, though automation technology commands the fastest expansion as labor costs climb across major producing regions. Small-scale capacity equipment retains the largest unit volume but carries thinner margin pools, while industrial-scale systems concentrate profitability among a narrower supplier set.
India's BIS machinery safety standards, Vietnam's Ministry of Agriculture quality protocols, and ISO 22000 food safety management systems collectively shape product design requirements and cross-border market access for equipment vendors. Regulatory compliance costs are filtering downstream, favoring suppliers with in-house certification capabilities and documented traceability systems. Stakeholders must weigh automation investment cycles against evolving carbon-efficiency benchmarks and shifting import-substitution policies in major rice-producing economies.
Market Dynamics
Automated optical sorting systems are compressing traditional labor-dependent processing economics across Southeast Asian milling corridors, forcing equipment vendors to recalibrate service architectures and pricing models around throughput guarantees rather than hardware margins.
Growth Catalysts
- India's BIS certification mandates:Food-contact machinery standards are accelerating replacement cycles among mid-scale millers seeking export eligibility. Compliance investments filter toward suppliers with in-house testing laboratories.
- Labor cost trajectories in Vietnam:Mekong Delta processing clusters are automating husking and polishing lines to offset wage inflation in agricultural wage pools. Equipment financing through agricultural cooperatives is expanding addressable demand.
- Optical sorter integration:Precision grading technology is pulling capital allocation away from conventional mechanical separators. Premium head-rice yield improvements justify shorter payback periods for technology upgrades.
Market Restraints
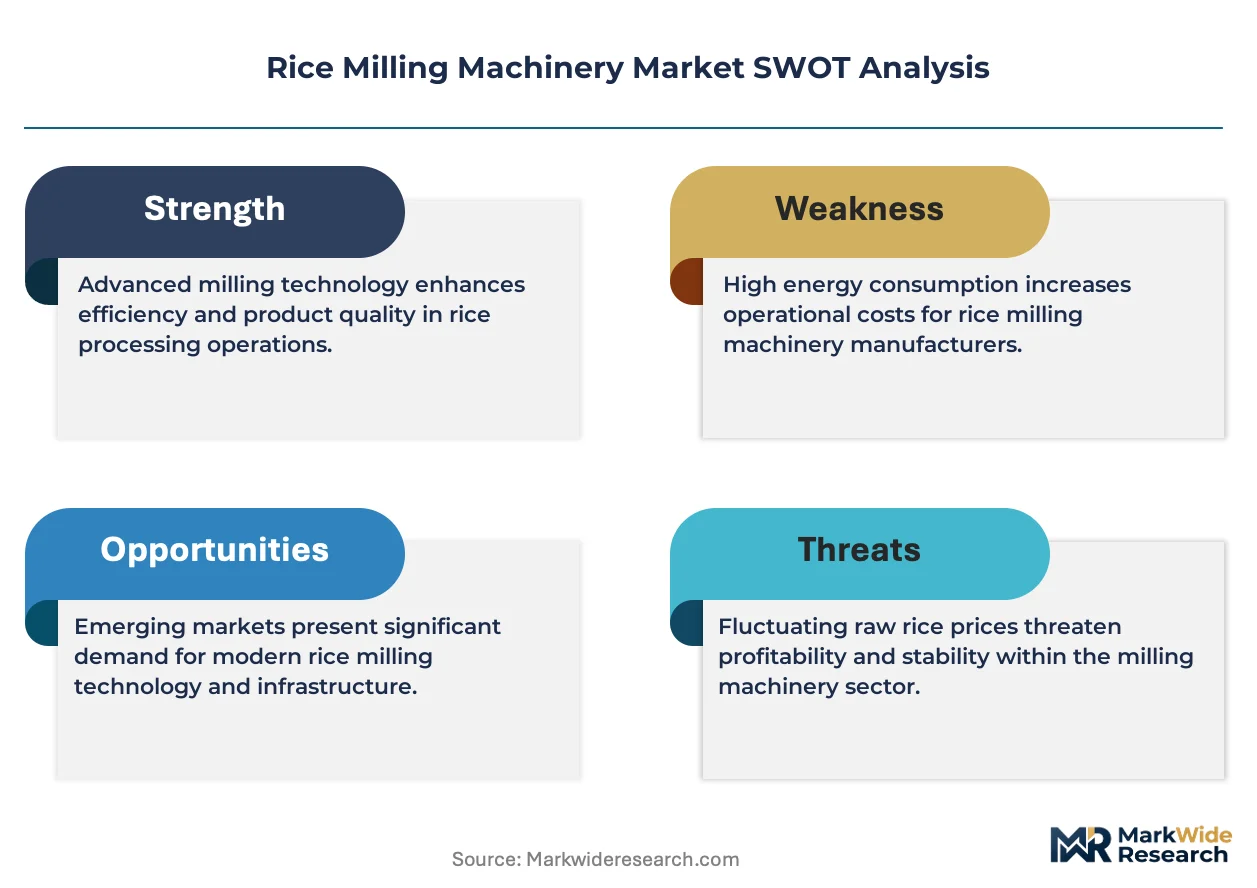
- Steel and alloy input volatility:Milling roll and whitener liner production faces margin compression from nickel and chromium price swings. Equipment manufacturers lack pricing power to pass through material cost spikes.
- Component supply concentration:High-precision optical sensors and pneumatic ejection modules concentrate among Japanese and German component specialists. Geopolitical friction threatens delivery reliability for Asian system integrators.
- Capital intensity thresholds:Automated lines require minimum 50-tonne-per-day throughput to achieve viable unit economics. Smallholder-dominated supply bases in Myanmar and Cambodia remain below viable automation scale.
Strategic Opportunities
- Myanmar's underpenetrated processing base:Post-conflict reconstruction of Irrawaddy Delta milling infrastructure presents first-mover positioning for vendors with localized service capabilities. Chinese equipment suppliers are already establishing Yangon distribution hubs.
- Solar-powered off-grid systems:Photovoltaic-integrated milling units address electrification gaps in Bangladesh's char regions and Indonesia's outer island chains. Development finance institutions are piloting equipment-leasing programs.
- Carbon-efficiency benchmarking:Emerging sustainability disclosure requirements from European rice importers are creating preference for energy-recovery whiteners and husk-fired cogeneration systems. ISO 14001-certified suppliers gain procurement advantage.
Industry Challenges
- Mechatronics technician scarcity:Automated line maintenance requires hybrid mechanical-electrical-software skill sets absent from traditional agricultural machinery vocational tracks. Training program development lags installation growth in Vietnam and Thailand.
- Legacy equipment interoperability:Brownfield mill retrofits face control system integration failures between 1990s-era mechanical separators and modern optical sorter feedback loops. Custom engineering costs erode project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rice Milling Machinery Market |
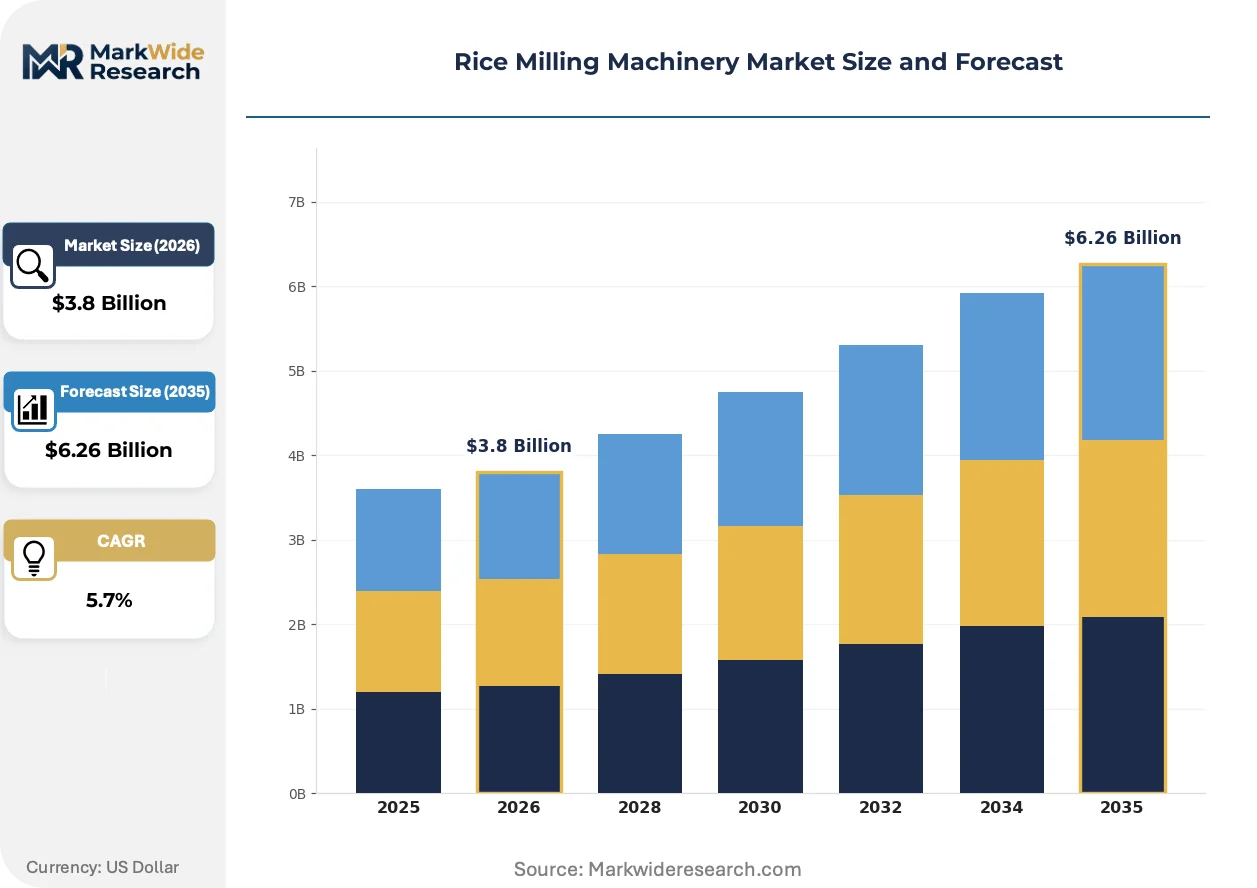
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Huskers, Grinders, Dryers, Polishers Technology: Mechanical, Pneumatic, Hydraulics, Automation End User: Farmers, Millers, Distributors, Exporters Capacity: Small Scale, Medium Scale, Large Scale, Industrial |
| Companies Covered | Bühler Group, Satake Corporation, AG Growth International, Fowler Westrup, Zhejiang QiLi Machinery, Alvan Blanch Development, G.G. Dandekar Machine Works, Hubei Fotma Machinery, Mill Master Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rice Milling Machinery Market Strategic Shifts
Digital thread technologies are rewiring how milling performance is measured, sold, and guaranteed, compressing the traditional separation between equipment vendor and operational outcome.
AI-driven grain defect detection is collapsing the economic viability of manual inspection stations in high-volume export mills. Vietnamese and Thai commercial processors are deploying neural-network sorters at throughput rates exceeding 15 tonnes per hour. The technology is collapsing quality-control labor headcounts while tightening broken-grain ratios to sub-12 percent thresholds.
India's BIS machinery safety standards are mandating emergency stop systems and interlocked guarding on all new dehusker installations. The regulation is forcing design modifications to legacy platform architectures and extending product development cycles by 8-14 months. Domestic manufacturers with existing BIS testing infrastructure are capturing specification-driven replacement demand from smaller regional competitors.
Performance-based service contracts are displacing traditional spare-parts revenue models among premium equipment vendors. Large-scale millers in Vietnam's An Giang and Dong Thap provinces now negotiate throughput guarantees bundled with predictive maintenance subscriptions. This contracting shift is most visible among exporters supplying EU and Middle Eastern markets where downtime penalties exceed equipment depreciation costs.
Rice Milling Machinery Market Segmentation
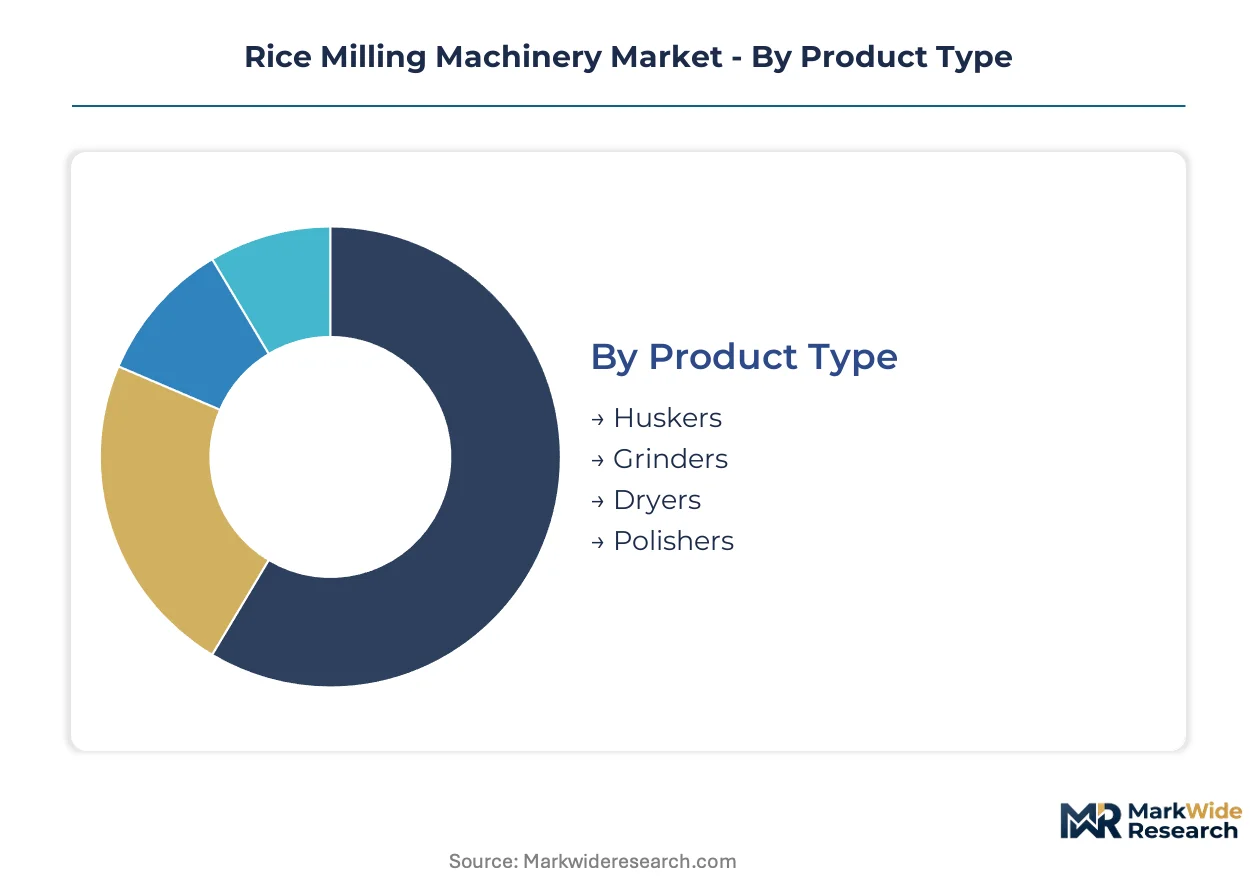
Equipment specification, automation level, and throughput capacity create distinct procurement clusters across rice milling operations. Segmentation reveals where capital allocation concentrates and which technology tiers command premium positioning.
Product Type:
Cost tier differentiation separates commodity dehusking equipment from precision finishing systems that determine export-grade output quality.
- Huskers:Rubber-roll and impeller configurations dominate initial paddy processing, stripping hulls while preserving grain integrity. Mekong Delta millers in Vietnam's An Giang province prioritize throughput rates above 8 tonnes per hour to match harvest seasonality windows.
- Polishers:Friction-type and water-jet systems apply the final surface treatment, directly influencing head-rice yield percentages that determine export pricing tiers. Indian commercial millers seeking BIS certification are retrofitting older abrasive units with temperature-controlled polishing chambers.
- Grinders:Coarse and fine milling configurations process broken grains into rice flour and bran derivatives for food manufacturing feedstock.
- Dryers:Batch and continuous-flow thermal systems reduce moisture content from 20-25 percent harvest levels to 12-14 percent storage thresholds.
Huskers hold installed capacity. Polishers are rotating up the share rankings.
Technology:
Application-specific technology deployment tracks labor substitution economics and precision grading requirements across processing corridors.
- Automation:Integrated sensor networks and programmable logic controllers synchronize dehusking, whitening, and sorting sequences with minimal operator intervention. Vietnamese exporters supplying EU markets deploy AI-driven optical sorters achieving sub-12 percent broken-grain ratios.
- Mechanical:Gear-driven roller mills and friction polishers persist in smallholder cooperatives where capital constraints limit electrification infrastructure.
- Pneumatic:Air-classification systems separate husk, bran, and milled rice fractions using differential density separation without water consumption.
- Hydraulics:Pressure-controlled whitening chambers apply uniform abrasive force across variable grain hardness profiles.
Mechanical systems hold installed capacity. Automation is rotating up the share rankings.
End User:
Customer type determines equipment specification complexity, financing structure, and service contract terms across the procurement spectrum.
- Millers:Commercial processing facilities with 50-500 tonne-per-day capacity negotiate performance-based service contracts bundling throughput guarantees with predictive maintenance subscriptions. Vietnam's Dong Thap province clusters exemplify this procurement pattern.
- Exporters:Export-grade certification requirements drive specification toward optical sorting integration and traceability documentation systems.
- Farmers:Individual and cooperative smallholders below 10-tonne-per-day throughput rely on mobile milling services and shared equipment pools.
- Distributors:Trading houses and agricultural cooperatives procure standardized units for lease-to-own arrangements across fragmented supply bases.
Millers hold installed capacity. Exporters are rotating up the share rankings.
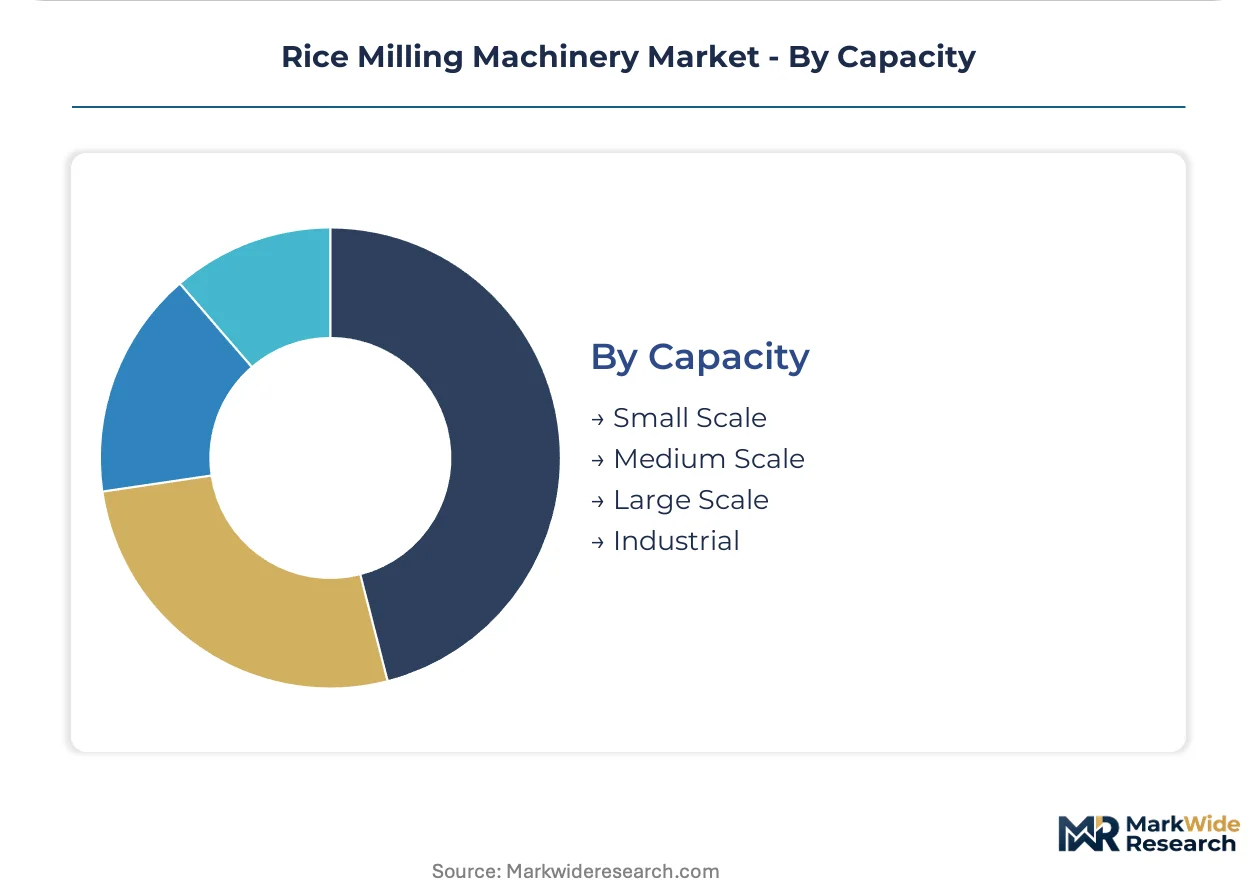
Capacity:
Volume scale directly correlates with automation feasibility, energy recovery system viability, and supplier concentration among equipment vendors.
- Large Scale:100-500 tonne-per-day integrated lines achieve viable unit economics for automated optical sorting and husk-fired cogeneration. Indian millers in Punjab's Amritsar district concentrate procurement in this tier to meet BIS export certification mandates.
- Industrial:Above 500 tonne-per-day mega-facilities command dedicated engineering teams and captive spare parts inventories.
- Medium Scale:20-100 tonne-per-day operations balance mechanization investment against seasonal utilization rates.
- Small Scale:Below 20 tonne-per-day village-level mills dominate unit volume but carry compressed margin pools and limited technology upgrade cycles.
Small Scale holds installed capacity. Large Scale is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BIS certification mandates in India are tightening food-contact machinery standards and accelerating replacement cycles among mid-scale millers. Vietnam's Mekong Delta processing corridors are automating husking and polishing lines to offset agricultural wage inflation. Regulatory compliance costs are filtering downstream across Asian producing regions.
India
Punjab's Amritsar district millers are scaling automated installations to meet BIS export certification requirements for food-contact machinery. The Bureau of Indian Standards mandates emergency stop systems and interlocked guarding on all new dehusker installations. Haryana's Karnal processing cluster is retrofitting temperature-controlled polishing chambers to achieve compliance-driven specification upgrades.
Vietnam
Mekong Delta commercial processors in An Giang and Dong Thap provinces are deploying AI-driven optical sorters achieving sub-12 percent broken-grain ratios. Agricultural cooperative financing is expanding addressable demand for capital-intensive automated lines. Can Tho city's integrated milling facilities are negotiating throughput guarantees bundled with predictive maintenance subscriptions for EU-bound exports.
China
Hubei province's rice processing belt is absorbing domestic optical sensor and pneumatic ejection module production to reduce import dependency on Japanese and German component specialists. MIIT industrial upgrading programs are subsidizing precision grading technology adoption among state-affiliated grain bureaus. Hunan's Changsha-Zhuzhou-Xiangtan cluster is concentrating large-scale whitener and polisher manufacturing capacity.
Thailand
Central Plains millers in Suphan Buri and Chainat provinces are integrating husk-fired cogeneration systems to meet emerging carbon-efficiency benchmarks from European rice importers. The Ministry of Agriculture's quality protocols are shaping optical sorting integration requirements for export-grade certification. Bangkok-based equipment distributors are establishing localized service hubs to compress response times for automated line maintenance.
Bangladesh
Char region processors are piloting photovoltaic-integrated milling units through development finance institution equipment-leasing programs. The Power Division's rural electrification gaps are driving demand for solar-powered off-grid systems below 20-tonne-per-day capacity. Rajshahi Division's cooperative milling pools are sharing mechanized drying infrastructure to reduce post-harvest losses.
Rice Milling Machinery Market Competitive Environment
Swiss-engineered automation specialists and Japanese precision-grading specialists split the market into premium-tier and technology-tier competitive spheres. The installed base concentrates among three to five integrated system vendors with captive certification laboratories and documented traceability systems. Equipment manufacturers compete through performance-based service contracts displacing traditional spare-parts revenue models, while regional fabricators compete on localized service response and agricultural cooperative financing relationships. Geographic expansion through Yangon and Dhaka distribution hubs and technology licensing for optical sorter integration represent dominant competitive vectors.
Within the precision-grading tier, Satake Corporation exemplifies deep specialization in optical sorting architectures, while Bühler Group anchors Swiss-engineered automation positioning across Asian large-scale installations. AG Growth International occupies a position extending North American grain handling expertise into complementary processing portfolios. Among India-based fabricators, Fowler Westrup and G.G. Dandekar Machine Works represent mid-scale automation providers navigating BIS certification-driven specification upgrades. Zhejiang QiLi Machinery and Hubei Fotma Machinery exemplify Chinese equipment suppliers establishing Southeast Asian distribution presence.
| Leading Market Players |
|---|
| Bühler Group |
| Satake Corporation |
| AG Growth International |
| Fowler Westrup |
| Zhejiang QiLi Machinery |
| Alvan Blanch Development |
| G.G. Dandekar Machine Works |
| Hubei Fotma Machinery |
| Mill Master Machinery |
| Others |
Value Chain & Pricing Dynamics
Hunan's Changsha-Zhuzhou-Xiangtan manufacturing cluster concentrates large-scale whitener and polisher production capacity, compressing pricing power for commodity equipment tiers while amplifying premiums for Swiss-engineered automation lines. Steel and alloy input volatility in milling roll production feeds downstream margin pressure that equipment manufacturers struggle to pass through to buyers.
Pricing Analysis
Vietnamese Mekong Delta millers pay 40-60 percent premiums over Bangladeshi char region equivalents for identically specced automated husking lines. Three-tier pricing structure across premium, standard, and economy levels separates Bühler-engineered systems from Chinese fabricators and local artisanal suppliers. Cost compression in standard-tier mechanical polishers is intensifying because nickel and chromium price swings erode already-thin fabrication margins. Smallholder cooperatives below 20-tonne-per-day throughput exhibit highest price sensitivity, while Vietnam's EU-bound exporters absorb premium automation costs through performance-based service contracts.
Supply Chain Analysis
High-precision optical sensors and pneumatic ejection modules draw from Japanese and German component specialists, creating single-source vulnerability for Asian system integrators. Milling roll production rests on nickel-chromium alloy feedstock from Chinese and South African smelters. Steel and alloy input volatility presents the dominant supply chain risk, with equipment manufacturers lacking pricing power to hedge material cost spikes. Distribution runs through manufacturer-direct digital platforms and localized Yangon and Dhaka service hubs that displace traditional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI-driven optical sorting is collapsing manual inspection economics across Southeast Asian export corridors, creating a high-growth disruption window. India's BIS certification mandates for food-contact machinery are accelerating replacement cycles among mid-scale millers.
For Market Incumbents: Insulate premium positioning by deepening captive certification laboratory capabilities and documented traceability systems. Bühler Group and Satake Corporation should extend performance-based service contracts with throughput guarantees to lock in Vietnamese EU-bound exporters. Vertical integration into optical sensor assembly reduces exposure to Japanese and German component concentration risk. For New Entrants and Emerging Players: Myanmar's Irrawaddy Delta post-conflict reconstruction represents the most penetrable entry point for vendors with localized service capabilities. Bangladesh's char region solar-powered off-grid systems below 20-tonne-per-day capacity offer second-tier white space. Development finance institution equipment-leasing partnerships provide the critical go-to-market angle for capital-constrained agricultural cooperatives. For Investors and Strategic Acquirers: Long-term, this sits as a mechanization-substitution play because labor cost trajectories in Vietnam and Thailand are structurally irreversible. Acquisition targets should cluster around mid-scale automation providers with existing BIS testing infrastructure and Southeast Asian distribution presence. Watch for inflection when EU carbon-efficiency disclosure requirements tighten procurement specifications for energy-recovery whiteners.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Service Contract Expansion | Bündles throughput guarantees with predictive maintenance for Vietnam's Dong Thap exporters. |
| Backward Integration into Optical Sensor Assembly | Reduces single-source dependency on Japanese and German component specialists. |
| BIS Certification Laboratory Investment | Captures specification-driven replacement demand from smaller Indian regional competitors. |
| Solar-Powered Off-Grid System Piloting | Addresses electrification gaps in Bangladesh's char regions through DFIs. |
| Yangon Distribution Hub Establishment | Compresses response times for automated line maintenance in Myanmar's reconstruction phase. |
Study Parameters
Initial hypotheses were tested against primary input from commercial mill operations directors, agricultural cooperative financing officers, OEM procurement teams at integrated equipment vendors, and aftermarket service heads. These perspectives were refined through secondary validation against BIS machinery safety standards documentation, Vietnam Ministry of Agriculture quality protocols, customs and trade data for milling equipment imports, and SEC filings from publicly traded grain handling specialists. Bottom-up installation counts across Mekong Delta processing corridors were triangulated with top-down market sizing from regional production statistics.
Demand-supply balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include equipment type, automation level, end-user category, and throughput capacity tier. CAGRs were derived from elasticity-adjusted adoption curves for optical sorting technology and labor-cost-driven automation substitution rates. Industry-specific forecast inputs incorporated BIS certification mandate compliance timelines and EU carbon-efficiency benchmarking emergence.
Macroeconomic conditions sit as an overlay; deviation in agricultural wage inflation trajectories, steel alloy commodity prices, or yen-euro exchange rates affecting component sourcing would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology adoption S-curves. Cross-checking against FAO rice production statistics and national grain processing capacity surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Corn Thresher Market
Agricultural Processing Equipment
Rotary Drum Dryers Market
Agricultural Processing Equipment
Manure Handling Equipment Market
Agricultural Processing Equipment
Defeathering Machine Market
Agricultural Processing Equipment
Vegetable Dicing Machines Market
Agricultural Processing Equipment
Solar Herbs Dryer Market
Agricultural Processing Equipment
Rice Polishers Market
Agricultural Processing Equipment
Egg Processing Machine Market
Agricultural Processing Equipment
Pulp Wash Equipment Market
Agricultural Processing Equipment
Solar Powered Agricultural Dryer Market
Agricultural Processing Equipment
Meat Dicing Machine Market
Agricultural Processing Equipment
Rice Processing Machine Market
Agricultural Processing Equipment
Grain Processing Equipment Market
Agricultural Processing Equipment
Corn Milling Machine Market
Agricultural Processing Equipment
Screw Press Dewatering Machine Market
Agricultural Processing Equipment
Destemmer Machine Market