
 Canada Agricultural Machinery Market | 2026-2036
Canada Agricultural Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Agricultural Machinery Market Analysis
Skilled technician availability is bifurcating the Canada agricultural machinery landscape into dealerships that can support precision systems and those that cannot. Deere & Company leverages its proprietary GPS guidance ecosystem to lock in service-dependent revenue streams. CNH Industrial N.V. anchors its Prairie presence through extensive dealer networks spanning Manitoba to Alberta. Buhler Industries Inc. specializes in domestically manufactured equipment tailored to Canadian climate conditions.
Canada agricultural machinery encompasses self-propelled and towed equipment engineered for soil preparation, planting, cultivation, and harvest operations, typically featuring diesel powertrains rated from 40 to 600 horsepower and precision guidance compatibility. Tractors dominate installed base value across Canadian farms due to their year-round utility in tillage, hauling, and power take-off applications. Harvesters capture concentrated demand during narrow seasonal windows, creating acute financing and logistics intensity. Precision farming technology represents the fastest-expanding segment as Prairie grain operations adopt variable-rate seeding and automated steering to optimize input costs per hectare.
Health Canada and PMRA govern pesticide application equipment standards, while Transport Canada regulates farm machinery roadworthiness and lighting requirements for inter-farm transit. The Canadian Environmental Protection Act and provincial emissions frameworks progressively tighten engine exhaust thresholds, compelling OEMs to certify Tier 4 Final and emerging Stage V powertrains for Canadian import. Stakeholders must monitor how federal sustainable agriculture funding programs and provincial equipment incentive structures reshape capital replacement cycles across farm size tiers.
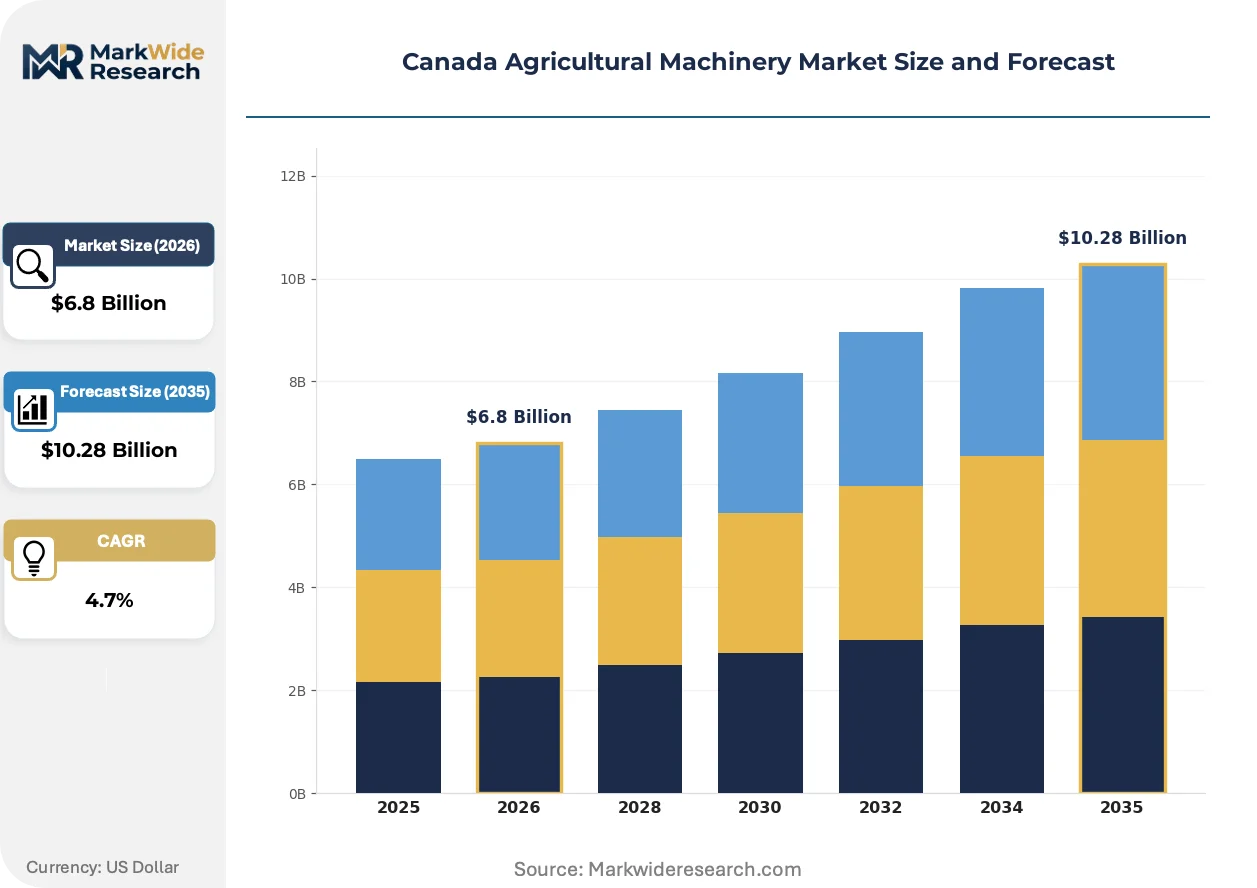
Market Dynamics
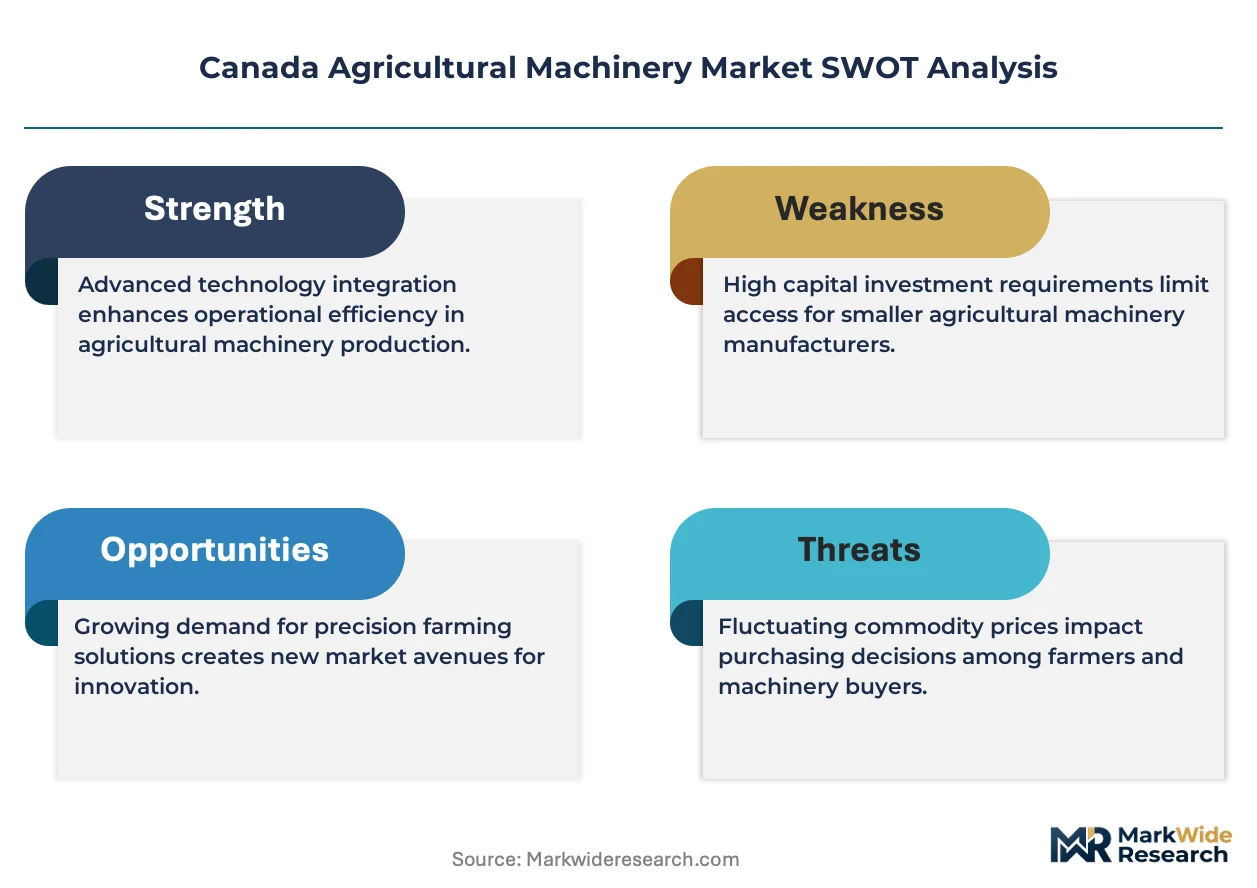
Farm consolidation across Saskatchewan and Alberta is compressing replacement cycles for high-horsepower equipment while Tier 4 Final compliance costs restructure OEM margins and dealer service capabilities.
Growth Catalysts
- Clean Fuel Regulations:Federal mandates for lower-carbon intensity fuels accelerate farmer investment in precision application equipment to optimize input efficiency and reduce fuel burn per hectare.
- Variable-rate seeding technology:Prairie grain operations deploy GPS-guided planters to cut seed costs and maximize yield per acre, driving hardware upgrades across Manitoba and Alberta.
- Alberta-Saskatchewan farm consolidation:Larger operational footprints generate capital-intensive procurement of 400+ horsepower tractors and self-propelled harvesters with integrated telemetry.
Market Restraints
- Diesel engine cost inflation:Tier 4 Final aftertreatment systems add substantial capital burden to mid-range tractor segments, squeezing margins for cash-constrained operations under 2,000 acres.
- Dealer service concentration:Precision agriculture support requires specialized technicians concentrated in Winnipeg, Regina, and Calgary corridors, leaving rural Manitoba with extended downtime risks.
- Steel and aluminum input volatility:Fluctuating commodity prices for chassis materials destabilize OEM pricing commitments during extended order backlogs.
Strategic Opportunities
- Telematics-enabled predictive maintenance:Remote diagnostics platforms allow dealers to monetize uptime guarantees and parts forecasting contracts beyond traditional equipment sales.
- Quebec dairy and horticulture mechanization:Underpenetrated segments in Eastern Canada present white space for compact tractor and automated milking system expansion.
- Provincial sustainable agriculture funding:Equipment incentive programs in Saskatchewan and Alberta subsidize precision technology adoption for eligible farm size tiers.
Industry Challenges
- Precision agriculture technician scarcity:Dealer networks struggle to recruit and retain certified diagnostics specialists capable of supporting GPS guidance and telemetry integration.
- Legacy fleet interoperability:Mixed-voltage hydraulic systems and proprietary CAN bus protocols complicate retrofitting older tractors with automated steering upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Agricultural Machinery Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
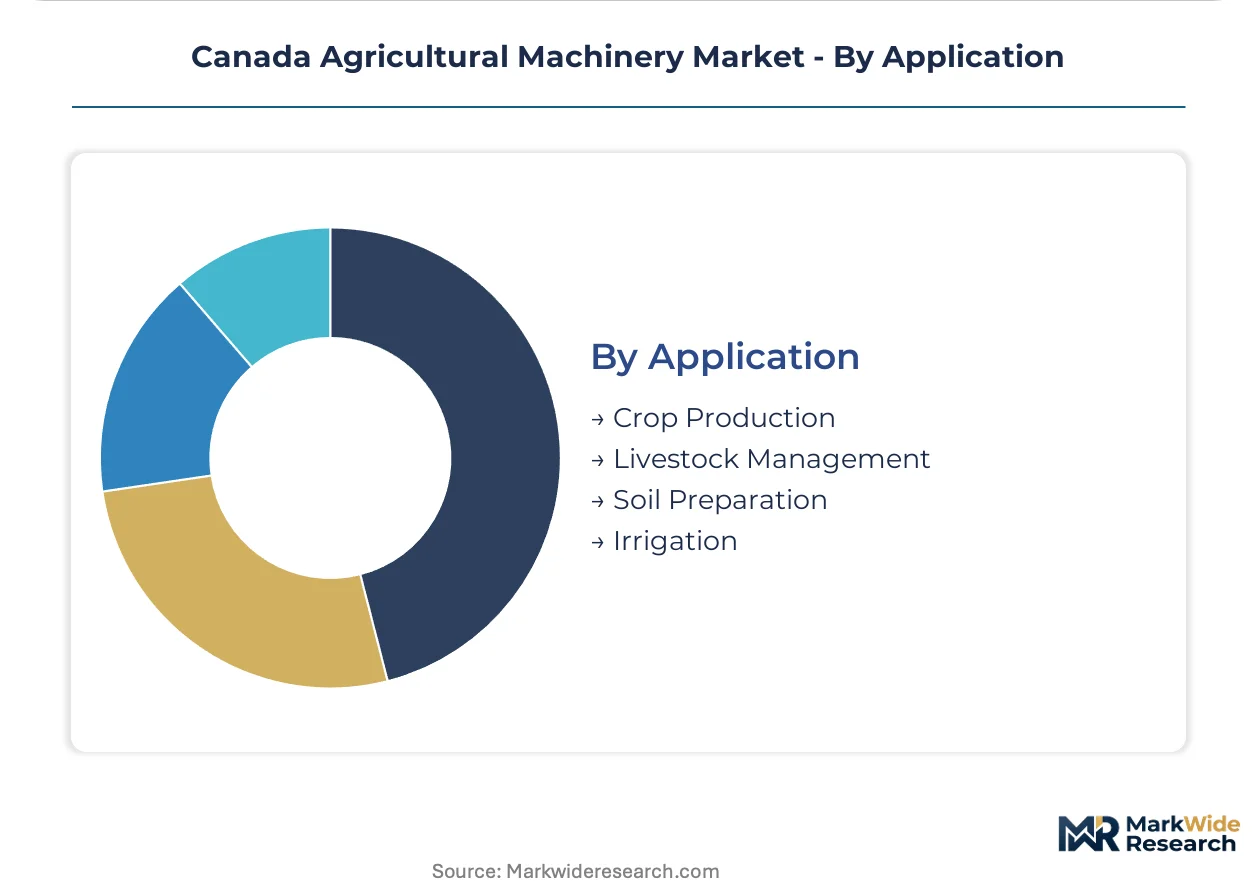
| Segmentation | Product Type: Tractors, Harvesters, Seeders, Plows Technology: GPS Guidance, Precision Farming, Automation, IoT Solutions End User: Farmers, Agricultural Contractors, Cooperative Societies, Government Agencies Application: Crop Production, Livestock Management, Soil Preparation, Irrigation |
| Companies Covered | Kubota Corporation, Same Deutz-Fahr, Deere & Company, Mahindra and Mahindra Ltd., Kuhn Group, CNH Industrial N.V., CLAAS KGaA mbH, Buhler Industries Inc., AGCO Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Agricultural Machinery Market Emerging Trajectories
Electrification pressure and autonomy development are converging to redefine powertrain architectures and operator roles across Canadian farm operations.
Sensor arrays for real-time soil mapping and crop health monitoring are miniaturizing from standalone units to integrated planter and sprayer modules. Prairie grain operations adopt these embedded systems fastest, with Alberta leading installation rates. This integration is miniaturizing the aftermarket precision hardware segment while compressing standalone guidance system margins.
Canada's Clean Fuel Regulations and provincial emissions frameworks tighten exhaust thresholds progressively, compelling OEMs to certify Stage V powertrains for import eligibility. Engine manufacturers face recertification costs and supply chain reconfiguration for aftertreatment components. Prairie provinces with the oldest installed base face the steepest compliance-driven replacement pressure.
Equipment-as-service contracting is displacing traditional ownership models among mid-scale operations seeking to transfer residual value risk. Dealer finance arms and OEM captive lenders pilot usage-based leasing with telemetry-verified hour accumulation. Saskatchewan and Alberta show highest uptake where seasonal cash flow volatility makes fixed payments attractive.
Canada Agricultural Machinery Market Segmentation
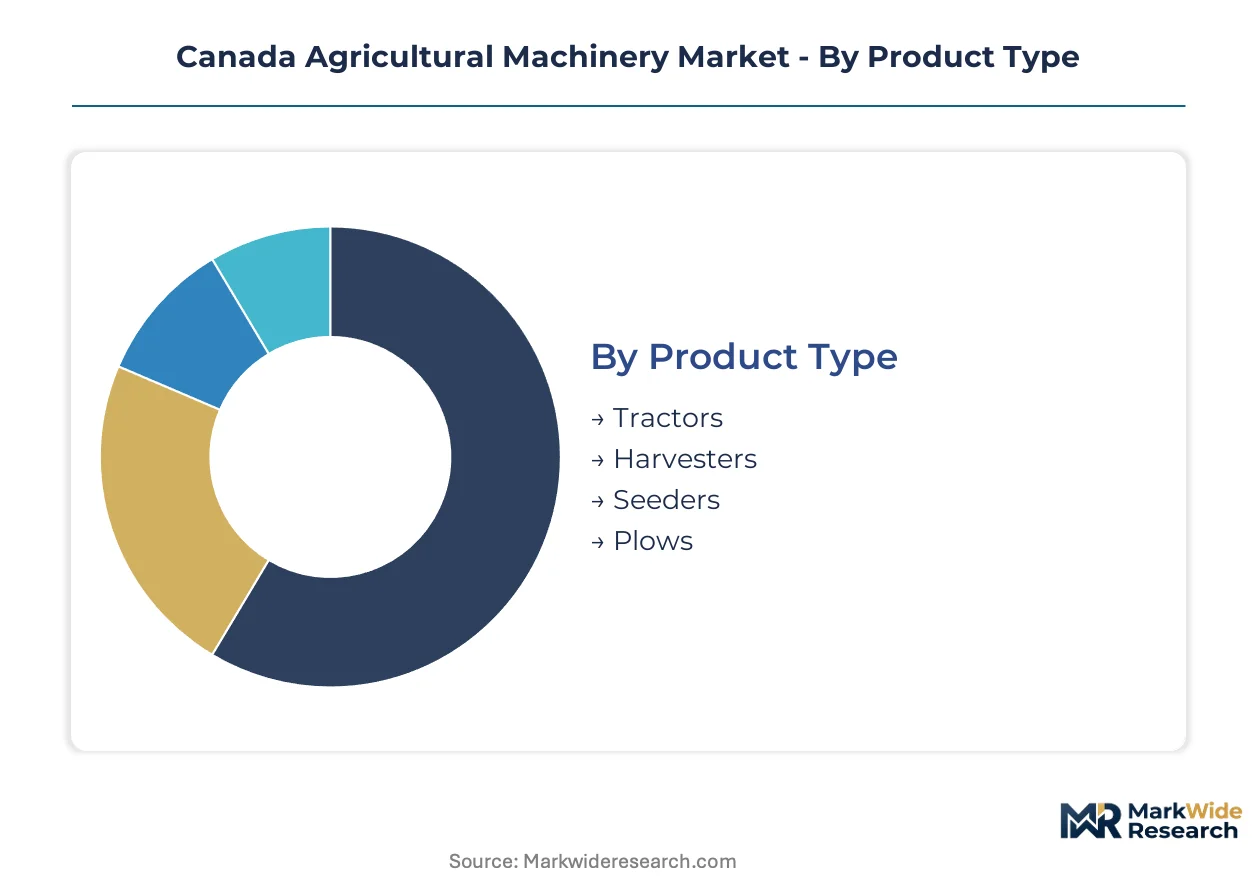
Canada agricultural machinery procurement patterns diverge sharply between Prairie grain operations driving high-horsepower equipment demand and Eastern Canadian specialty farms prioritizing compact mechanization. Understanding these segment boundaries reveals where capital replacement cycles concentrate and which technology platforms achieve scale economics.
Product Type:
Prairie provinces dominate domestic absorption for high-value equipment categories, while export-oriented manufacturing concentrates in Manitoba and Saskatchewan production facilities.
- Tractors:Self-propelled units ranging from 40 to 600 horsepower with power take-off compatibility and three-point hitch configurations. Saskatchewan and Alberta grain operations above 2,000 acres drive demand for 400+ horsepower models with integrated telemetry, though Tier 4 Final aftertreatment costs compress margins on mid-range segments. Tractors hold the largest share; momentum sits with high-horsepower precision-ready platforms.
- Harvesters:Self-propelled combines and forage harvesters engineered for narrow seasonal operating windows with grain tank capacities exceeding 400 bushels. Alberta farm consolidation generates concentrated procurement of Class 8 and 9 machines with automated yield mapping, creating acute financing intensity during September-October delivery windows.
- Seeders:Air drill and planter configurations with variable-rate metering capabilities for canola, wheat, and pulse crops.
- Plows:Moldboard and disc plow implements for primary tillage operations, predominantly sourced from domestic manufacturers in Winnipeg corridor.
Tractor value concentration in Prairie provinces exceeds harvester revenue density despite lower unit margins per machine.
Technology:
Adoption velocity correlates with farm size thresholds, creating a bifurcated landscape between precision-enabled operations and conventional equipment users.
- GPS Guidance:RTK-corrected steering systems achieving sub-inch accuracy for controlled traffic farming. Manitoba Red River Valley potato operations and Alberta canola producers lead installation rates, with Deere's proprietary ecosystem locking in service-dependent revenue streams through subscription-based correction signals. GPS Guidance holds the largest share; precision farming platforms are climbing the fastest.
- Precision Farming:Variable-rate application systems for seed, fertilizer, and crop protection inputs based on prescription maps derived from soil sampling and yield history. Saskatchewan grain operations above 5,000 acres achieve input cost reductions sufficient to justify hardware capital expenditure within three-season payback periods.
- Automation:Autonomous tractor platforms and robotic implement control systems in pilot deployment across research stations and large corporate farms.
- IoT Solutions:Telemetry-enabled remote diagnostics and fleet management platforms transmitting engine parameters, location data, and maintenance alerts to dealer service centers.
Dealer service concentration in Winnipeg, Regina, and Calgary corridors limits rural adoption velocity for technology-dependent segments.
End User:
Procurement authority concentrates with owner-operators above 3,000 acres, while contractor models expand among mid-scale farms seeking equipment access without capital commitment.
- Farmers:Owner-operators and family partnerships managing cultivated land directly, representing the dominant procurement channel for new equipment with captive financing through OEM lenders. Farmers hold the largest share; agricultural contractors are gaining share fastest.
- Agricultural Contractors:Custom service providers offering tillage, planting, and harvest operations on fee-per-acre terms, driving demand for high-utilization machines with rapid depreciation schedules.
- Cooperative Societies:Member-owned equipment sharing arrangements pooling capital for seasonal machinery access across multiple farm operations.
- Government Agencies:Federal and provincial research stations, demonstration farms, and extension service fleets with procurement governed by public tender processes.
Equipment-as-service contracting pilots show highest uptake among contractor and cooperative segments where utilization rates justify telemetry-verified hour accumulation models.
Application:
Revenue concentration aligns with Prairie grain production cycles, though livestock mechanization presents underpenetrated expansion territory in Quebec and Ontario dairy corridors.
- Crop Production:Machinery dedicated to field crop cultivation including planting, cultivation, spraying, and harvest operations across wheat, canola, pulse, and corn rotations. Alberta and Saskatchewan account for disproportionate equipment value absorption relative to national farm count. Crop production holds the largest share; livestock management shows steepest expansion trajectory.
- Livestock Management:Feeding systems, manure handling equipment, and automated milking infrastructure serving dairy, beef, and pork operations. Quebec's dairy sector mechanization lags Prairie grain automation by approximately one replacement cycle, creating white space for compact tractor and robotic milking system vendors.
- Soil Preparation:Tillage, drainage, and land leveling equipment for seedbed establishment and moisture management.
- Irrigation:Center-pivot and drip irrigation systems with integrated pumping and filtration, concentrated in Southern Alberta's semi-arid production zones.
Soil preparation equipment replacement cycles compress under farm consolidation pressure, while irrigation expansion depends on provincial water licensing frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health Canada and PMRA anchor regulatory oversight across Prairie provinces where farm consolidation accelerates capital-intensive machinery replacement cycles.
Alberta
Large-scale grain operations above 5,000 acres drive concentrated demand for 400+ horsepower tractors and Class 8 combines. Federal Clean Fuel Regulations push producers toward precision application equipment to optimize fuel efficiency per hectare. Calgary and Lethbridge corridors host the densest dealer service networks supporting GPS-guided seeding systems.
Saskatchewan
Farm consolidation compresses replacement cycles for high-horsepower equipment as operational footprints expand. Provincial sustainable agriculture funding programs subsidize precision technology adoption for eligible farm size tiers. Regina and Saskatoon anchor the dominant machinery distribution corridor stretching to Manitoba border.
Manitoba
Red River Valley potato operations and diversified grain farms generate mixed demand for mid-range tractors and specialty harvesters. Transport Canada regulations govern roadworthiness requirements for inter-farm machinery transit across provincial highways. Winnipeg corridor concentrates domestic manufacturing and dealer technical support capabilities.
Quebec
Dairy and horticulture mechanization lags Prairie grain automation by approximately one replacement cycle, creating expansion white space. Provincial agricultural development programs target robotic milking systems and compact tractor adoption. Eastern Townships and Montérégie regions show concentrated dairy operation density.
Ontario
Mixed livestock and cash crop operations generate diversified equipment demand across horsepower segments. Federal sustainable agriculture funding flows through provincial delivery mechanisms reshaping capital replacement timelines. Southwestern Ontario corn-soybean belt drives seasonal demand for planters and combines.
Canada Agricultural Machinery Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the Canadian agricultural machinery landscape. The market structure consolidates around integrated full-line manufacturers with proprietary precision ecosystems alongside specialized regional fabricators. Three archetypes dominate: precision-technology integrators leveraging telemetry lock-in, domestic climate-specialists, and scale-driven international OEMs. Competitive moves concentrate on telematics-enabled service contracting and provincial incentive program alignment.
Within the precision-technology integrator tier, Deere & Company and CNH Industrial N.V. exemplify archetypes built on proprietary GPS guidance ecosystems and extensive Prairie dealer networks. Buhler Industries Inc. represents the domestic climate-specialist position with Winnipeg-based manufacturing tailored to Canadian operating conditions. These three anchors illustrate how technology integration, geographic coverage, and regional specialization create distinct competitive positioning vectors across Alberta, Saskatchewan, and Manitoba demand corridors.
| Leading Market Players |
|---|
| Kubota Corporation |
| Same Deutz-Fahr |
| Deere & Company |
| Mahindra and Mahindra Ltd. |
| Kuhn Group |
| CNH Industrial N.V. |
| CLAAS KGaA mbH |
| Buhler Industries Inc. |
| AGCO Corporation |
| Others |
Supply Flow & Price Mechanics
Tier 4 Final and emerging Stage V engine certification regimes gate both supply qualification and price differentiation simultaneously, compelling OEMs to absorb recertification costs while passing aftertreatment premiums to Prairie grain operations above 2,000 acres. Health Canada and PMRA pesticide application standards further stratify equipment tiers by compliance burden, concentrating pricing power with full-line manufacturers capable of integrated certification management.
Pricing Analysis
Alberta-Saskatchewan corridors command 15-20% premiums over Eastern Canadian markets for equivalent high-horsepower tractors, reflecting dealer service density and precision-technology bundling. Three-tier pricing structure across premium, standard, and economy levels separates telemetry-integrated platforms from basic mechanical configurations, with Tier 4 Final compliance costs compressing margins most acutely in mid-range segments. Pricing pressure stems from steel and aluminum input volatility destabilizing OEM commitments during extended order backlogs. Cash-constrained operations under 2,000 acres exhibit highest price sensitivity, while consolidated grain operations above 5,000 acres prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
Port congestion across Vancouver and Prince Rupert trade lanes elevates inbound logistics costs for aftertreatment components sourced from German and Japanese engine manufacturers. Manufacturing concentration in the United States, Germany, and Japan anchors supply for precision guidance systems and Tier 4 Final powertrains, while domestic Winnipeg corridor production covers climate-adapted tillage implements. Raw material dependencies on high-grade steel, aluminum alloys, and semiconductor chips for GPS modules expose OEMs to commodity price volatility and single-source vulnerability for RTK correction signal hardware. Distribution runs through Prairie dealer networks concentrated in Calgary, Regina, and Winnipeg corridors, with rural Manitoba facing extended lead times due to technician scarcity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Farm consolidation across Alberta and Saskatchewan shifts procurement leverage toward fewer, larger buyers capable of dictating service terms and financing structures. This concentration fragments price-setting power among OEMs while elevating the importance of telemetry-enabled uptime guarantees.
For Market Incumbents: Consolidate dealer technical capabilities in Winnipeg, Regina, and Calgary corridors to defend against emerging precision-agriculture service specialists. Acquire certified diagnostics capacity to offset technician scarcity threatening rural Manitoba support networks. Deepen backward integration into telematics platforms to capture recurring revenue streams beyond equipment sales.
For New Entrants and Emerging Players: Precision-agriculture service gaps in rural Manitoba and Saskatchewan present white-space opportunities where incumbent dealer networks under-serve smaller operations. Target compact tractor and automated milking system penetration in Quebec's dairy corridor, where mechanization lags Prairie grain automation by approximately one replacement cycle. Pursue equipment-as-service contracting models with telemetry-verified hour accumulation to bypass capital-intensive dealer infrastructure requirements.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial parents seeking to divest climate-specialized agricultural equipment divisions with Winnipeg-based manufacturing footprints. Long-term viability centers on telematics-enabled predictive maintenance platforms capable of monetizing uptime guarantees across consolidated Prairie operations. Watch for inflection signals in provincial sustainable agriculture funding program allocations, which reshape capital replacement cycles across farm size tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Remote diagnostics monetization locks in recurring revenue beyond equipment sales through dealer service contracts. |
| Precision Agriculture Certification Investment | RTK-corrected guidance capabilities differentiate offerings in Saskatchewan and Alberta grain operations above 5,000 acres. |
| Provincial Funding Program Alignment | Saskatchewan and Alberta equipment incentive structures subsidize technology adoption for eligible farm size tiers. |
| Service Technician Training Scale-Up | Certified diagnostics capacity addresses scarcity constraining rural Manitoba precision-agriculture adoption velocity. |
| Quebec Dairy Mechanization Expansion | Robotic milking systems and compact tractors address underpenetrated Eastern Canadian livestock segments. |
Methodological Framework
Initial hypotheses were tested against primary input from OEM product planning directors, Prairie dealer network operators, farm equipment procurement managers at consolidated grain operations, and precision-agriculture technology specialists, then refined through secondary validation. Primary interviews captured replacement cycle timing, financing structure preferences, and technology adoption barriers across Alberta, Saskatchewan, and Manitoba demand corridors. Secondary sources encompassed Health Canada and PMRA regulatory filings, Transport Canada roadworthiness standards, provincial sustainable agriculture program documentation, and OEM captive finance arm disclosures. Bottom-up equipment unit economics triangulated against top-down Prairie farm consolidation trends to anchor market size estimation.
Variance decomposition across horsepower segments, technology tiers, and provincial demand corridors structured the analytical framework over the projection horizon. Segmentation modeling incorporated product type, precision-technology adoption stage, farm size tier, and application intensity across crop production and livestock management. CAGRs derived from replacement cycle compression rates under farm consolidation pressure and Clean Fuel Regulations compliance timelines. Forecast inputs included Prairie precipitation patterns affecting seasonal utilization rates and provincial equipment incentive program eligibility thresholds.
Forecasts assume regulatory continuity in Health Canada, PMRA, and Transport Canada regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
India Agricultural Machinery Market
Agricultural Machinery
Vietnam Agricultural Machinery Market
Agricultural Machinery
South America Agricultural Sprayers Market
Agricultural Machinery
Forestry Machinery Market
Agricultural Machinery
Europe Agricultural Irrigation Machinery Market
Agricultural Machinery
Orchard Tractor Market
Agricultural Machinery
Agricultural Tractor Market
Agricultural Machinery
Agricultural Food Grade Rubber Conveyor Belt Market
Agricultural Machinery
North America Haying and Forage Machinery Market
Agricultural Machinery
Agriculture and Farm Machinery Market
Agricultural Machinery
Two Wheel Walking Tractor Market
Agricultural Machinery
Europe Agricultural Tractors Market
Agricultural Machinery
Spain Agricultural Machinery Market
Agricultural Machinery
Australia Agricultural Machinery Market
Agricultural Machinery
Netherlands Hydrogen Powered Tractor Market
Agricultural Machinery
Hydrogen Powered Tractor Market