
 Europe Controlled Release Fertilizer Market | 2026-2036
Europe Controlled Release Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Controlled Release Fertilizer Market Foresight
Specialty crop producers is bifurcating from commodity grain operators as the primary demand anchor for controlled release fertilizers in Europe. ICL Group Ltd leverages its integrated phosphate supply chain to sustain cost-competitive polymer-coated production. Compo Expert GmbH specializes in high-value horticulture blends that command premium positioning in Dutch glasshouse clusters. Yara International dominates bulk nitrogen logistics while extending its digital agronomy platform to lock in grower loyalty across Scandinavia.
Controlled release fertilizers are nutrient delivery systems engineered with semi-permeable polymer or sulfur coatings that meter nitrogen, phosphorus, and potassium release over 30 to 180 days through soil temperature and moisture gradients. Their primary commercial purpose is to synchronize nutrient availability with crop uptake curves, minimizing leaching losses and reducing application frequency. Polymer-coated urea captures the fastest expansion trajectory as growers trade up from sulfur-coated alternatives for extended release windows in high-value perennial crops. Urea-formaldehyde maintains entrenched share in turf management and golf course maintenance across the UK and Ireland where lower cost-per-acre governs procurement. Granular delivery mode anchors volume flows through established broadcaster equipment fleets, though liquid formulations are gaining traction in drip-irrigated Spanish and Italian orchards.
The EU Green Deal and its Farm to Fork Strategy mandate 50% nutrient loss reduction targets that directly elevate controlled release fertilizer demand against conventional soluble products. REACH compliance and CE marking requirements for polymer coatings create regulatory moats that favor established compounders with dedicated toxicology and environmental fate dossiers. EMA and national regulators in Germany, France, and Italy are converging on soil amendment registration pathways that will determine market access speed for novel coating chemistries. Stakeholders must monitor whether the EU's carbon border adjustment mechanism eventually embeds fertilizer production emissions into import parity calculations, reshaping sourcing economics for non-European suppliers.
Market Dynamics
The EU Green Deal's nutrient loss reduction mandates are compressing conventional fertilizer demand while polymer-coated alternatives capture procurement share across Dutch glasshouse clusters and German precision farming networks.
Growth Catalysts
- EU Farm to Fork Strategy:The 50% nutrient loss reduction target creates direct substitution pressure against soluble fertilizers in member state agricultural subsidy programs.
- Precision agriculture infrastructure:Variable-rate application equipment penetration in France and the Netherlands enables controlled release product calibration at sub-field resolution.
- Perennial crop expansion:Spanish and Italian orchard operators are trading up to extended-release formulations for tree nut and citrus operations.
Market Restraints
- Phosphate rock supply concentration:Moroccan and Russian phosphate dominance creates input cost volatility for polymer-coated urea manufacturers.
- REACH registration timelines:ECHA dossier requirements for novel coating chemistries extend market entry cycles by 18-24 months.
- Sulfur-coated urea substitution:Lower-cost sulfur alternatives retain entrenched share in UK turf management and Irish pasture applications.
Strategic Opportunities
- Eastern European underpenetration:Polish and Romanian arable farming operations remain below 5% controlled release adoption despite EU subsidy alignment.
- Liquid formulation channels:Drip-irrigated Spanish olive and vineyard operations are creating pull for liquid controlled release compatible with fertigation systems.
- Carbon border adjustment mechanism:Future EU CBAM fertilizer inclusion would reshape import parity for non-European polymer-coated suppliers.
Industry Challenges
- Coating technician scarcity:Polymer formulation chemistry expertise concentrates in German and Dutch research clusters, constraining southern European production scale-up.
- CE marking harmonization delays:Divergent national soil amendment registration pathways between France's ANSM-equivalent and Italy's environmental ministry create compliance fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Controlled Release Fertilizer Market |
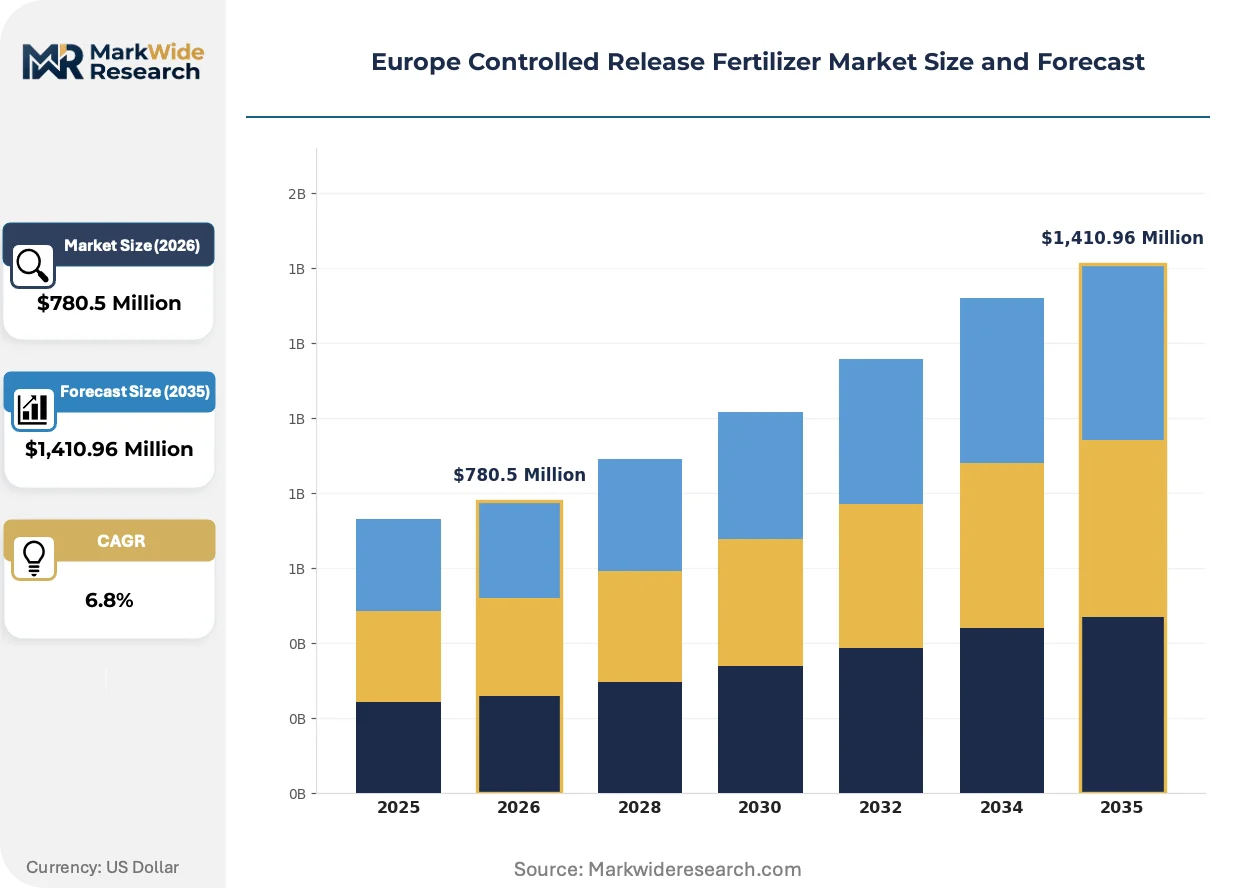
| Market Size in 2026 | $780.5 Million |
| Market Size in 2035 | $1,410.96 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea-Formaldehyde, Sulfur-Coated Urea, Polymer-Coated Urea, Neovan Application: Agronomy, Horticulture, Turf Management, Landscaping End User: Agricultural Producers, Commercial Growers, Landscape Contractors, Home Gardeners Delivery Mode: Granular, Liquid, Soluble, Film-Coated |
| Companies Covered | ICL Group Ltd, Nutrien Ltd, Compo Expert GmbH, Ekompany International BV, Grupa Azoty S.A., Yara International, Mivena BV, Van Iperen International, DeltaChem, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Controlled Release Fertilizer Market Shifts & Advancements
Coating technology convergence with digital agronomy platforms is redefining how nutrient release curves get calibrated to specific cultivar phenology stages across European growing regions.
Biodegradable polymer coatings derived from starch and cellulose matrices are miniaturizing the environmental persistence of controlled release fertilizers. Specialty vegetable producers in Belgium and the Netherlands are piloting these formulations for leafy green operations. The technology is miniaturizing the regulatory compliance burden for growers facing tightening microplastic scrutiny under REACH amendments.
EMA and national regulators in Germany, France, and Italy are converging on unified soil amendment registration pathways for novel coating chemistries. This harmonization compresses multi-market approval timelines for compounders with established toxicology dossiers. Polymer-coated urea manufacturers with pre-submitted environmental fate data are securing accelerated market access.
Buyer concentration among Dutch cooperative purchasing federations is consolidating procurement leverage for controlled release formulations. These federations are unbundling agronomic advisory from product supply, forcing compounders to compete on release-curve specificity rather than bundled service. The shift is most visible in the Netherlands where three cooperatives control 60% of glasshouse nutrient procurement.
Europe Controlled Release Fertilizer Market Segmentation
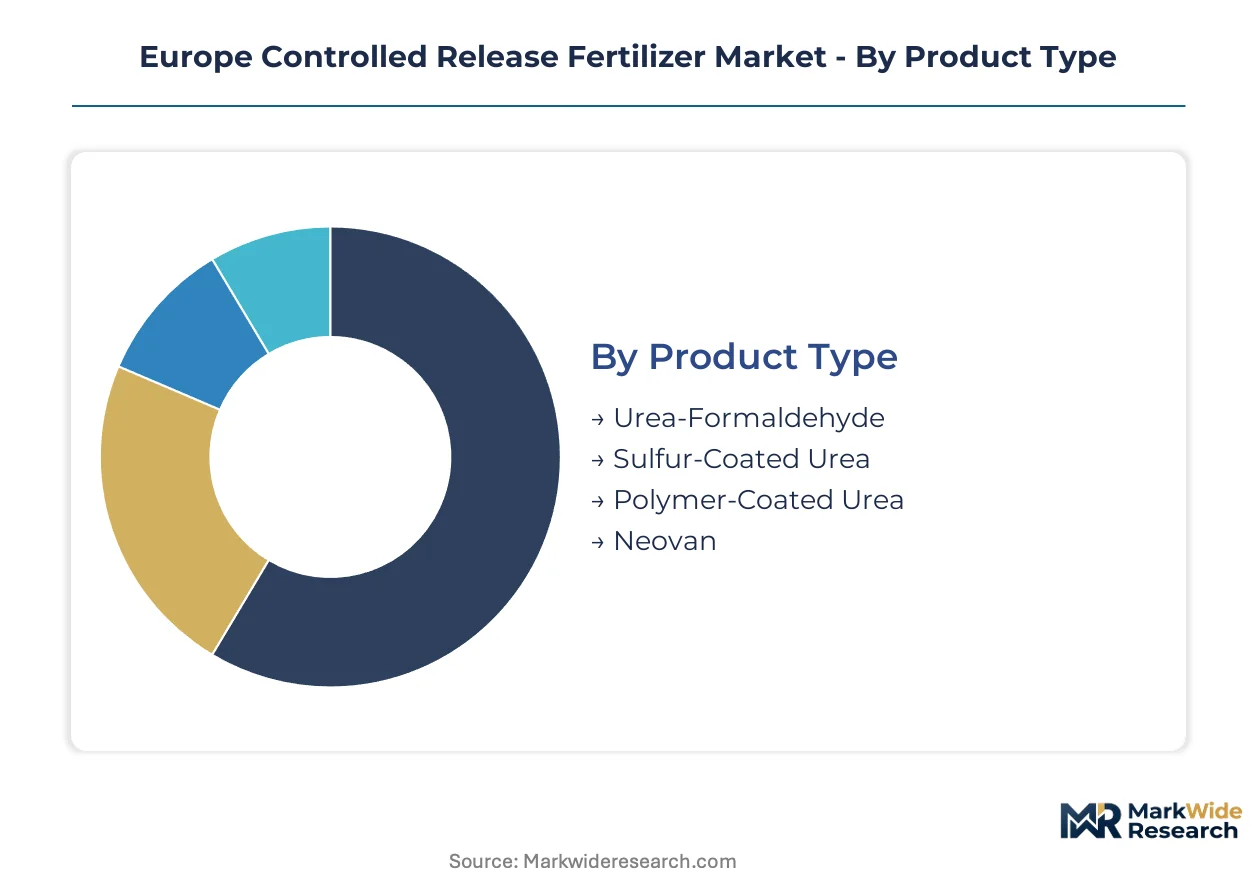
Controlled release fertilizer segmentation in Europe reflects divergent pressure points from regulatory mandates, crop economics, and application infrastructure. Product chemistry and delivery mode choices determine compliance pathways against EU Green Deal nutrient loss targets, while end-user categories fragment across subsidy eligibility and precision agriculture adoption curves.
Product Type:
Sulfur-coated urea faces the most acute substitution threat as polymer-coated alternatives extend release windows and satisfy tightening runoff standards.
- Polymer-Coated Urea:Semi-permeable synthetic or biodegradable polymer membranes meter nitrogen release over 60 to 180 days through soil temperature activation. Dutch glasshouse operators and German precision farming networks are consolidating procurement around these formulations to meet Farm to Fork Strategy compliance deadlines.
- Sulfur-Coated Urea:Elemental sulfur barrier layers provide 30 to 60 day release windows at lower unit cost but exhibit higher leaching coefficients. UK turf management contractors and Irish pasture operators retain entrenched positions where cost-per-acre governs procurement decisions.
- Urea-Formaldehyde:Methylene-urea condensation products release nitrogen through microbial decomposition. Belgian and UK golf course maintenance programs specify these formulations for predictable greenkeeping schedules.
- Neovan:Isobutylidene diurea compound delivers controlled nitrogen release through hydrolysis kinetics. French viticulture and Italian olive orchard specialists are piloting these chemistries for perennial crop nutrition.
Sulfur-coated urea retains volume leadership across price-sensitive applications; polymer-coated urea holds the steepest expansion curve as regulatory compliance tightens.
Application:
Cost tier stratification separates premium horticulture from commodity agronomy, with turf management occupying a mid-tier position defined by maintenance contract structures.
- Horticulture:High-value protected cultivation in Dutch Venlo glasshouses and Belgian leafy green operations demands calibrated release curves synchronized with cultivar phenology stages. Precision fertigation infrastructure enables sub-field nutrient management.
- Agronomy:Broadacre cereal and oilseed production across French Beauce and German Brandenburg regions deploys controlled release products primarily where EU subsidy programs offset premium pricing. Variable-rate application equipment penetration remains uneven.
- Turf Management:Sports field and golf course maintenance programs in the UK and Ireland specify sulfur-coated and urea-formaldehyde products for predictable seasonal greenkeeping without frequent reapplication.
- Landscaping:Municipal and commercial ornamental plantings across German urban centers and French public gardens utilize controlled release formulations to reduce labor intensity in maintenance contracts.
Agronomy commands absolute volume flows through hectare scale; horticulture generates the highest margin realization per kilogram applied.
End User:
Customer type determines purchasing modality, with cooperative federations consolidating leverage for agricultural producers while commercial growers negotiate directly for formulation specificity.
- Agricultural Producers:Cooperative purchasing federations in the Netherlands control substantial glasshouse nutrient procurement, unbundling agronomic advisory from product supply to force compounder competition on release-curve specificity.
- Commercial Growers:Specialty vegetable and ornamental operations in Belgium and southern Spain require customized coating chemistries and flexible batch sizing, purchasing through distributor technical sales channels.
- Landscape Contractors:Municipal and commercial maintenance firms across German cities and French departments specify controlled release products through public tender processes with multi-season performance guarantees.
- Home Gardeners:Retail packaged products distributed through garden center chains in the UK and Germany represent a price-sensitive segment with limited formulation sophistication.
Agricultural producers concentrate procurement volume through cooperative structures; commercial growers drive formulation innovation through direct technical relationships.
Delivery Mode:
Application infrastructure legacy determines adoption speed, with granular formulations anchored to existing broadcaster fleets while liquid systems require drip irrigation capital investment.
- Granular:Spreader-compatible prilled or extruded formulations dominate volume flows across European broadacre operations. Established machinery fleets in France and Germany perpetuate granular preference despite precision limitations.
- Liquid:Fertigation-compatible suspensions and solutions are gaining traction in Spanish olive groves and Italian vineyards with drip infrastructure investments. Compatibility with automated irrigation systems enables precise timing control.
- Soluble:Rapid-dissolving granules for stock tank preparation serve protected horticulture operations requiring immediate nutrient availability supplementation alongside controlled release baselines.
- Film-Coated:Ultra-thin polymer surface treatments on conventional granules provide entry-level controlled release functionality at intermediate price positioning for transitional adopters.
Granular delivery retains installed base dominance; liquid formulations are climbing the fastest as fertigation infrastructure expands in Mediterranean perennial crops.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israeli phosphate exports supply coating chemistries to Dutch and German compounders, creating a trade-flow corridor that anchors polymer-coated urea production across northwestern Europe.
Germany
Precision farming networks in Brandenburg and Lower Saxony deploy variable-rate application equipment that calibrates controlled release formulations at sub-field resolution. The EU Green Deal's Farm to Fork Strategy mandates 50% nutrient loss reduction, accelerating substitution away from soluble fertilizers. Bavarian research clusters concentrate polymer formulation expertise, constraining southern European production scale-up.
Netherlands
Venlo glasshouse operators synchronize nutrient release curves with cultivar phenology stages through precision fertigation infrastructure. Cooperative purchasing federations control 60% of protected cultivation procurement, unbundling agronomic advisory from product supply. Randstad-based compounders compete on release-curve specificity rather than bundled service.
France
Beauce cereal producers deploy controlled release products where EU subsidy programs offset premium pricing against conventional alternatives. ANSM-equivalent soil amendment registration pathways diverge from Italian environmental ministry protocols, creating compliance fragmentation. French viticulture specialists pilot isobutylidene diurea chemistries in Champagne and Burgundy perennial operations.
Spain
Andalusian olive groves and Mediterranean vineyards drive liquid formulation adoption through drip irrigation capital investments. Spanish orchard operators trade up to extended-release formulations for tree nut and citrus operations. EMA convergence on unified registration pathways accelerates market access for compounders with pre-submitted environmental fate data.
United Kingdom
UK turf management contractors and Irish pasture operators retain sulfur-coated urea positions where cost-per-acre governs procurement decisions. Golf course maintenance programs across England and Scotland specify urea-formaldehyde for predictable seasonal greenkeeping. REACH compliance requirements for polymer coatings create regulatory moats favoring established compounders with dedicated toxicology dossiers.
Europe Controlled Release Fertilizer Market Competitive Landscape
Player mix skews toward integrated phosphate suppliers and specialty horticulture compounders, with mid-tier regional blenders occupying price-sensitive segments. The structure concentrates procurement leverage among Dutch cooperative federations while fragmenting technical sales channels for customized formulations. Strategic archetypes include upstream-integrated phosphate producers, precision agronomy platform operators, and regional distribution specialists. Dominant competitive moves center on backward integration into phosphate rock sourcing and digital advisory platform deployment to lock in grower loyalty.
Within the integrated-supply tier, ICL Group Ltd and Yara International represent archetypes of upstream phosphate control and bulk nitrogen logistics respectively. Compo Expert GmbH exemplifies the specialty horticulture compounder positioning that commands premium placement in high-value cultivation clusters. These three anchors demonstrate how coating technology expertise and distribution infrastructure determine competitive positioning across regulatory-compliant and price-sensitive segments.
| Leading Market Players |
|---|
| ICL Group Ltd |
| Nutrien Ltd |
| Compo Expert GmbH |
| Ekompany International BV |
| Grupa Azoty S.A. |
| Yara International |
| Mivena BV |
| Van Iperen International |
| DeltaChem |
| Others |
Supply & Pricing Matrix
Phosphate rock processing scale economies in northwestern Europe anchor polymer-coated urea production cost floors, concentrating supply leverage among integrated compounders while fragmenting pricing power for regional blenders dependent on imported coating chemistries.
Pricing Analysis
Polymer-coated urea commands substantial premiums over sulfur-coated alternatives, with biodegradable next-generation formulations targeting further markup capture from Dutch glasshouse operators facing REACH microplastic scrutiny. Three-tier pricing structure across premium polymer-coated, standard sulfur-coated, and economy urea-formaldehyde levels stratifies procurement across horticulture, agronomy, and turf management segments. Pricing pressure stems from Moroccan phosphate input volatility and Russian supply disruptions compressing margins for non-integrated manufacturers. UK turf contractors and Irish pasture operators exhibit highest price sensitivity, while Dutch cooperative federations prioritize release-curve precision over unit cost.
Supply Chain Analysis
Strait of Gibraltar transit underwrites phosphate rock flows from Moroccan mines to Rotterdam and Antwerp processing hubs, creating logistics chokepoint exposure for European coating chemistry supply. Production concentrates in Germany, the Netherlands, and Belgium where polymer formulation expertise clusters around Bavarian research institutes and Randstad compounding facilities. Raw material dependencies span phosphate rock, elemental sulfur, and synthetic polymer resins sourced from Middle Eastern and Asian petrochemical complexes. Single-source vulnerability runs through Moroccan phosphate dominance and Russian sulfur exports. Distribution runs through Dutch cooperative federations controlling bulk procurement, supplemented by technical sales channels for customized horticulture formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital agronomy platform interoperability is consolidating grower loyalty around integrated advisory-product bundles, creating platform-economics inflection where standalone compounders risk disintermediation by data-enabled supply chains.
For Market Incumbents: Fortify backward integration into phosphate rock sourcing to insulate margin structures from Moroccan and Russian supply volatility. Secure accelerated REACH dossier approvals for biodegradable coating chemistries before ECHA microplastic amendments tighten. Prioritize digital platform deployment across Scandinavian precision farming networks to preempt Yara International's agronomy lock-in. For New Entrants and Emerging Players: CE marking fast-track through pre-submitted environmental fate data compresses market entry timelines against established compounders. Eastern European underpenetration in Polish and Romanian arable operations offers white-space expansion below 5% adoption thresholds. Liquid formulation channels for Spanish drip-irrigation infrastructure provide lowest competitive density entry point. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors coating chemistry specialists with pre-validated biodegradable polymer platforms over bulk nitrogen logistics operators facing carbon border adjustment exposure. Long-term viability hinges on regulatory compliance moats and digital advisory integration depth. Watch EMA harmonization progress on unified soil amendment registration as inflection signal for multi-market approval velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock | Captive Moroccan supply insulates ICL Group and integrated compounders from input cost volatility. |
| Biodegradable Coating R&D Acceleration | Starch and cellulose matrix platforms preempt REACH microplastic restrictions for Dutch glasshouse procurement. |
| Digital Agronomy Platform Deployment | Variable-rate calibration tools lock grower loyalty across German precision farming networks. |
| Eastern European Distribution Expansion | Polish and Romanian channel buildout captures EU subsidy-aligned conversion from conventional fertilizers. |
| CE Marking Dossier Pre-Submission | Accelerated ECHA approvals compress 18-24 month entry cycles for novel coating chemistries. |
Research Methodology
A spread of perspectives from polymer formulation chemists, Dutch cooperative procurement managers, German precision farming equipment operators, and ECHA regulatory affairs specialists converged on the working assumptions driving supply concentration and pricing power dynamics. Primary field engagement with coating technology R&D directors and glasshouse cultivation advisors combined with secondary validation through customs trade data, Cefic fertilizer industry reports, SEC filings of listed compounders, and EU Farm to Fork Strategy implementation documents. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic nutrient loss reduction targets.
Segmentation dimensions modeled span product chemistry tier, application intensity level, end-user procurement structure, and delivery mode infrastructure compatibility across the projection horizon. CAGRs derived from time-series decomposition of historical adoption curves and policy-mandated substitution elasticities. Forecast inputs incorporated EU Green Deal compliance deadline phasing and variable-rate equipment penetration trajectories in France and the Netherlands.
Decision-makers should treat outputs as directional under sustained EU subsidy alignment and REACH enforcement intensity assumptions; material deviation in carbon border adjustment fertilizer inclusion timing or phosphate supply disruption severity would warrant model refresh. Practitioners should keep alternative scenarios live as EMA harmonization progress and biodegradable coating performance validation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
North America Micronutrient Fertilizers Market
Fertilizers
Ammonium Thiosulfate Fertilizer Market
Fertilizers
Controlled and Slow Release Fertilizers Market
Fertilizers
Brazil Fertilizers Market
Fertilizers
Enhanced Efficiency Fertilizer Market
Fertilizers
Italy Water Soluble Fertilizer Market
Fertilizers
India Urea Market
Fertilizers
Europe Micronutrient Fertilizer Market
Fertilizers
Global Potash Fertilizer Market
Fertilizers
Fertilizer Bags Market
Fertilizers
India Fertilizers Market
Fertilizers
Europe Organic Fertilizer Market
Fertilizers
High-Brix Fruit Quality Enhancement Fertilizer Market
Fertilizers
Brazil Specialty Fertilizer Market
Fertilizers
Global Water Soluble Fertilizer Market
Fertilizers
North America Fertilizers Market