
 United States Precision Farming Software Market | 2026-2036
United States Precision Farming Software Market Size, Share, and Industry Trends Forecast 2026-2036
United States Precision Farming Software Market Insights
The United States precision farming software market is consolidating around a widening gap between enterprise-grade platforms and basic farm management apps. Deere & Company leverages its embedded hardware-software ecosystem to dominate integrated precision agriculture systems across Midwest row-crop operations. Trimble Inc. competes through specialized GNSS correction services and agronomic guidance tools that anchor its position in high-accuracy field operations. AGCO Corporation differentiates via open-platform architecture that allows third-party data integration across mixed-equipment fleets.
Precision farming software encompasses digital platforms that collect, process, and visualize agronomic data from IoT sensors, GPS receivers, and aerial imaging to optimize input application and harvest logistics. These systems typically process sub-meter spatial resolution field data through cloud-based or edge-computing architectures to generate prescription maps for seeding, fertilization, and crop protection. Cloud-based deployment captures expanding margin pools as recurring subscription revenue replaces perpetual licenses, while on-premises installations retain footholds among operations with limited broadband connectivity. Farm Management platforms lead in user adoption by consolidating financial, operational, and agronomic workflows into unified dashboards. Data Analytics technology drives fastest growth as machine learning models convert historical yield records into predictive agronomic recommendations.
The USDA Natural Resources Conservation Service shapes platform requirements through Environmental Quality Incentives Program standards that reward documented input reduction. State-level nutrient loss reduction strategies in Illinois and Iowa mandate precision application methods for participating operations, creating compliance-driven software demand. Stakeholders must monitor evolving EPA pesticide application recordkeeping requirements and state data privacy legislation affecting farm-level agronomic data ownership.
Market Dynamics
Farm consolidation across the Corn Belt is compressing the addressable customer base while amplifying per-account software spend, forcing vendors to pivot from volume acquisition to platform stickiness and data lock-in strategies.
Growth Catalysts
- USDA Conservation Compliance:Environmental Quality Incentives Program cost-share provisions mandate documented input reduction, compelling adoption of variable-rate application software among participating operations.
- GNSS Correction Services:Sub-decimeter accuracy from real-time kinematic networks enables prescription mapping for strip-till and targeted spraying, expanding addressable acreage for precision platforms.
- Illinois Nutrient Loss Reduction Strategy:State-level mandates for precision nutrient management on tile-drained acres create compliance-driven procurement timelines for farm management software.
Market Restraints
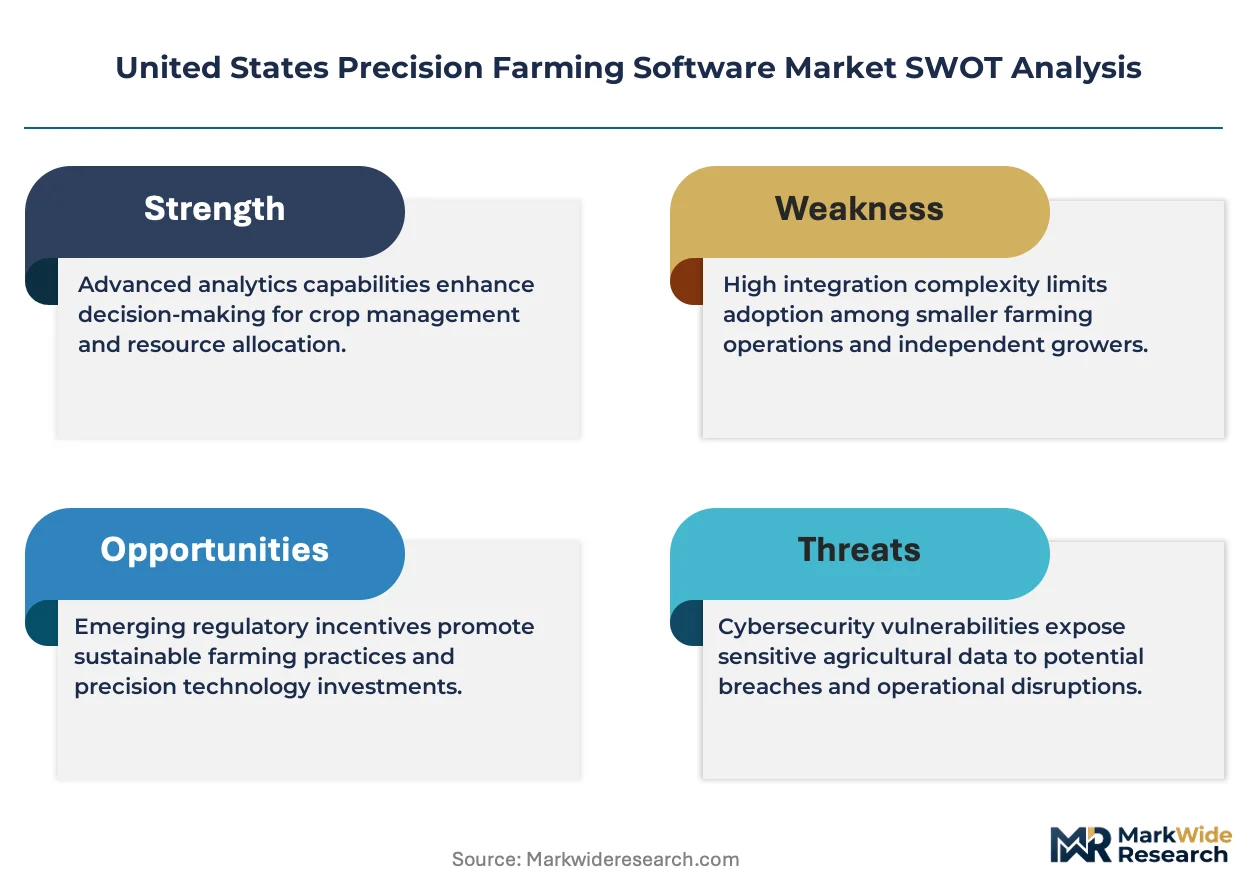
- Broadband Infrastructure Gaps:Rural connectivity deficits in Nebraska Sandhills and western Kansas limit cloud-based platform functionality, forcing vendors to maintain costly edge-computing alternatives.
- Equipment Interoperability Friction:Proprietary data formats from major agricultural OEMs create switching costs that suppress multi-platform adoption among mid-scale operations.
- Cybersecurity Liability Exposure:Farm-level data breaches expose operators to crop pattern theft and input timing manipulation, elevating insurance costs and procurement hesitation.
Strategic Opportunities
- Carbon Credit Verification:Emerging soil carbon protocols reward documented practice change, positioning precision software as the audit trail infrastructure for agricultural carbon markets.
- Drone Imagery Integration:Fusion of multispectral aerial data with ground-based sensor networks enables real-time nitrogen stress detection, opening subscription tiers for high-frequency monitoring.
- Texas High Plains Expansion:Pivot irrigation adoption in the Southern Plains creates greenfield demand for water optimization algorithms outside saturated Midwest markets.
Industry Challenges
- Agronomic Data Science Talent Scarcity:Shortage of professionals combining crop science expertise with geospatial analytics limits vendor R&D velocity and customer success scaling.
- Legacy Equipment Integration Complexity:Retrofitting 15-20 year-old tractors with ISOBUS-compatible terminals requires hardware middleware that fragments software deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Precision Farming Software Market |
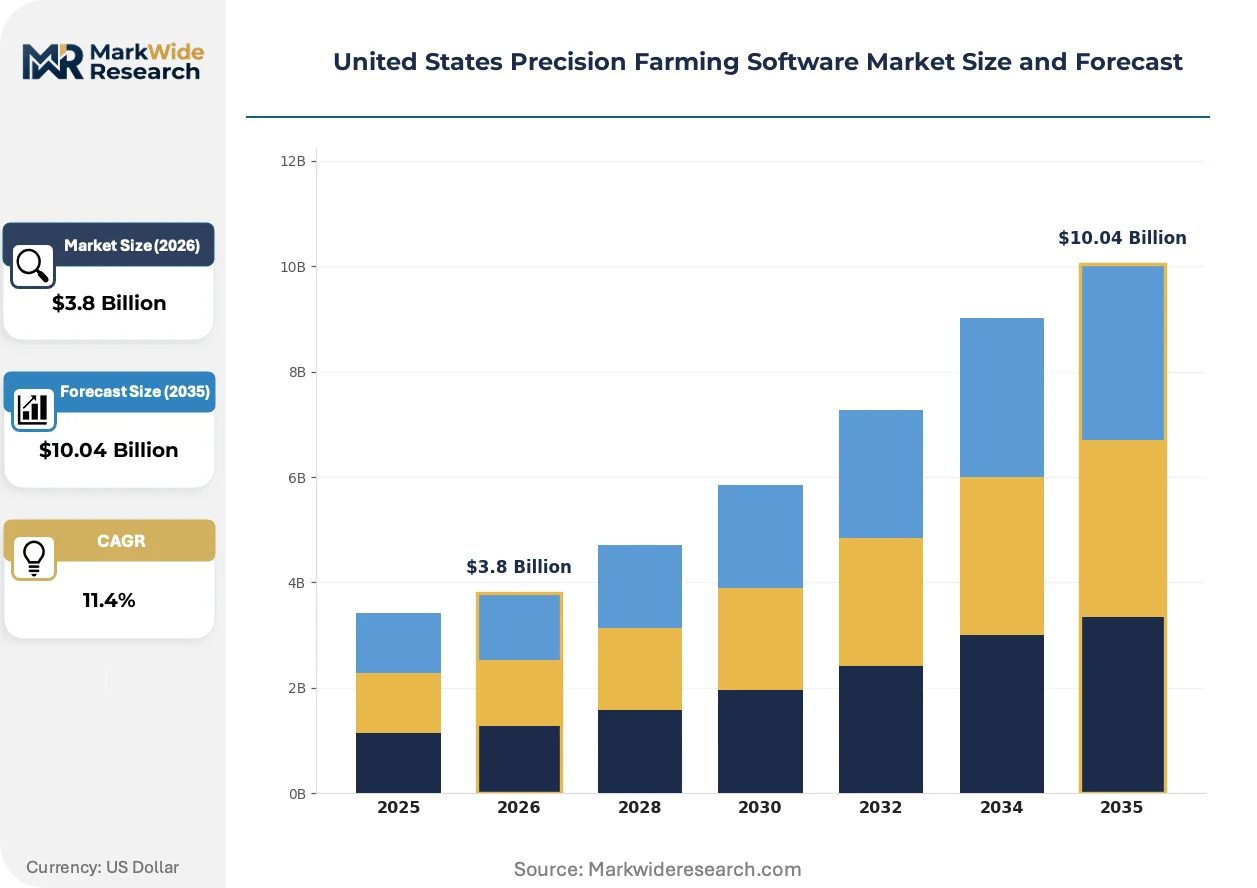
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Field Mapping, Yield Monitoring, Crop Scouting, Farm Management Deployment: On-Premises, Cloud-Based, Hybrid, Mobile End User: Agricultural Producers, Farm Cooperatives, Agronomists, Consultants Technology: IoT Sensors, GPS, Data Analytics, Drones |
| Companies Covered | Deere & Company, Trimble Inc., AGCO Corporation, Corteva Agriscience, Bayer AG, Ag Leader Technology, Kubota Corporation, Farmers Edge Inc., Topcon Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Precision Farming Software Market Trends and Innovations
Machine learning architectures are absorbing agronomic decision workflows that previously required certified crop advisors, compressing the advisory value chain and elevating software platform centrality in farm operations.
Edge computing nodes deployed directly on planting and application equipment are absorbing real-time sensor streams for immediate prescription adjustment without cloud latency. Large-scale operations in Iowa and Illinois are deploying these systems across 10,000-plus acre footprints to enable sub-field resolution management. This distributed architecture is absorbing margin from traditional cloud-only subscription tiers by enabling premium offline functionality.
The EPA's evolving pesticide application recordkeeping requirements under the Federal Insecticide, Fungicide, and Rodenticide Act are mandating geospatial documentation of every chemical application. Software vendors must embed automated boundary mapping and weather-stamped spray logs to maintain platform eligibility for commercial applicator licensing. Nebraska and Iowa operations are responding fastest, driven by state department of agriculture audit intensity.
Buying committees at consolidated farm operations now span operations managers, financial controllers, and sustainability officers rather than sole proprietor decision-making. This multi-stakeholder procurement is compressing sales cycles while elevating data export and API accessibility as non-negotiable requirements. The pattern is most visible across Illinois grain cooperatives where capital allocation committees now vet software contracts exceeding fifty thousand dollars annually.
United States Precision Farming Software Market Segmentation
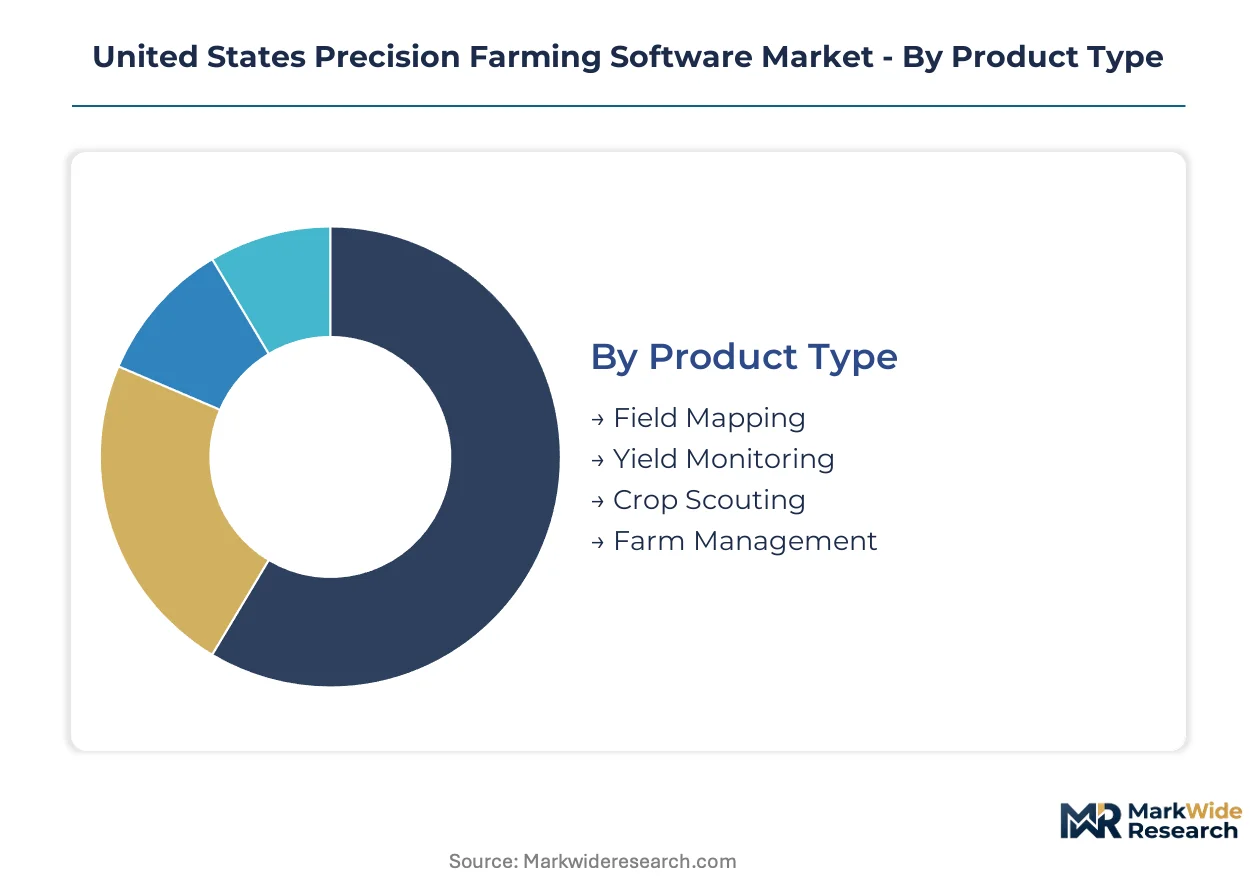
Precision farming software segmentation reveals how compliance requirements and operational scale dictate procurement patterns. USDA Environmental Quality Incentives Program standards create divergent certification burdens across deployment modes and end-user categories, reshaping vendor go-to-market strategies.
Product Type:
Farm Management platforms carry the heaviest documentation burden under EPA Federal Insecticide, Fungicide, and Rodenticide Act recordkeeping mandates, while Field Mapping tools face lighter USDA Natural Resources Conservation Service audit requirements.
- Farm Management:Unified dashboards consolidate financial, operational, and agronomic workflows into single interfaces. Large-scale producers in Iowa and Illinois demand these platforms for capital allocation committee oversight, driven by multi-stakeholder procurement processes exceeding fifty thousand dollar annual contracts.
- Data Analytics:Machine learning architectures convert historical yield records into predictive agronomic recommendations. Corn Belt operations prioritize these tools for nitrogen stress detection and prescription mapping, constrained by agronomic data science talent scarcity limiting vendor R&D velocity.
- Field Mapping:Sub-meter spatial resolution tools generate prescription maps for variable-rate application.
- Yield Monitoring:Real-time harvest data collection systems optimize logistics and grain marketing decisions.
- Crop Scouting:Mobile field inspection platforms document pest pressure and growth stage observations.
Leading the category by volume: Farm Management. Growing fastest: Data Analytics.
Deployment:
Cost tier stratification separates premium cloud subscriptions from economy on-premises installations, with hybrid architectures capturing mid-market operations seeking bandwidth flexibility.
- Cloud-Based:Recurring subscription revenue models replace perpetual licenses, capturing expanding margin pools through automated updates and API accessibility. Illinois and Iowa operations lead adoption where broadband infrastructure supports real-time data synchronization across consolidated acreage.
- On-Premises:Edge-computing architectures retain footholds among Nebraska Sandhills and western Kansas operations with limited connectivity. These installations require costly vendor maintenance of offline functionality, compressing margins versus cloud counterparts.
- Hybrid:Distributed architectures combine cloud analytics with local edge nodes for latency-sensitive field operations.
- Mobile:Smartphone-native applications serve scouting and light recordkeeping functions for smaller producers.
Cloud-Based commands the largest revenue base. Hybrid deployments are gaining share fastest among 10,000-plus acre operations.
End User:
Customer type determines sales cycle complexity and platform customization depth, with cooperatives demanding multi-tenant architectures unavailable to sole proprietors.
- Agricultural Producers:Large-scale Midwest row-crop operations drive per-account software spend, with buying committees spanning operations managers, financial controllers, and sustainability officers. USDA conservation compliance requirements accelerate platform deployment through cost-share program participation.
- Farm Cooperatives:Illinois grain cooperatives require data export and API accessibility as non-negotiable procurement terms, forcing vendors to support multi-platform integration across mixed-equipment fleets.
- Agronomists:Certified crop advisors leverage software for client prescription recommendations and input timing optimization.
- Consultants:Independent advisors prioritize portability and cross-farm benchmarking capabilities.
Agricultural Producers dominate segment revenue. Farm Cooperatives are expanding most quickly through capital allocation committee centralization.
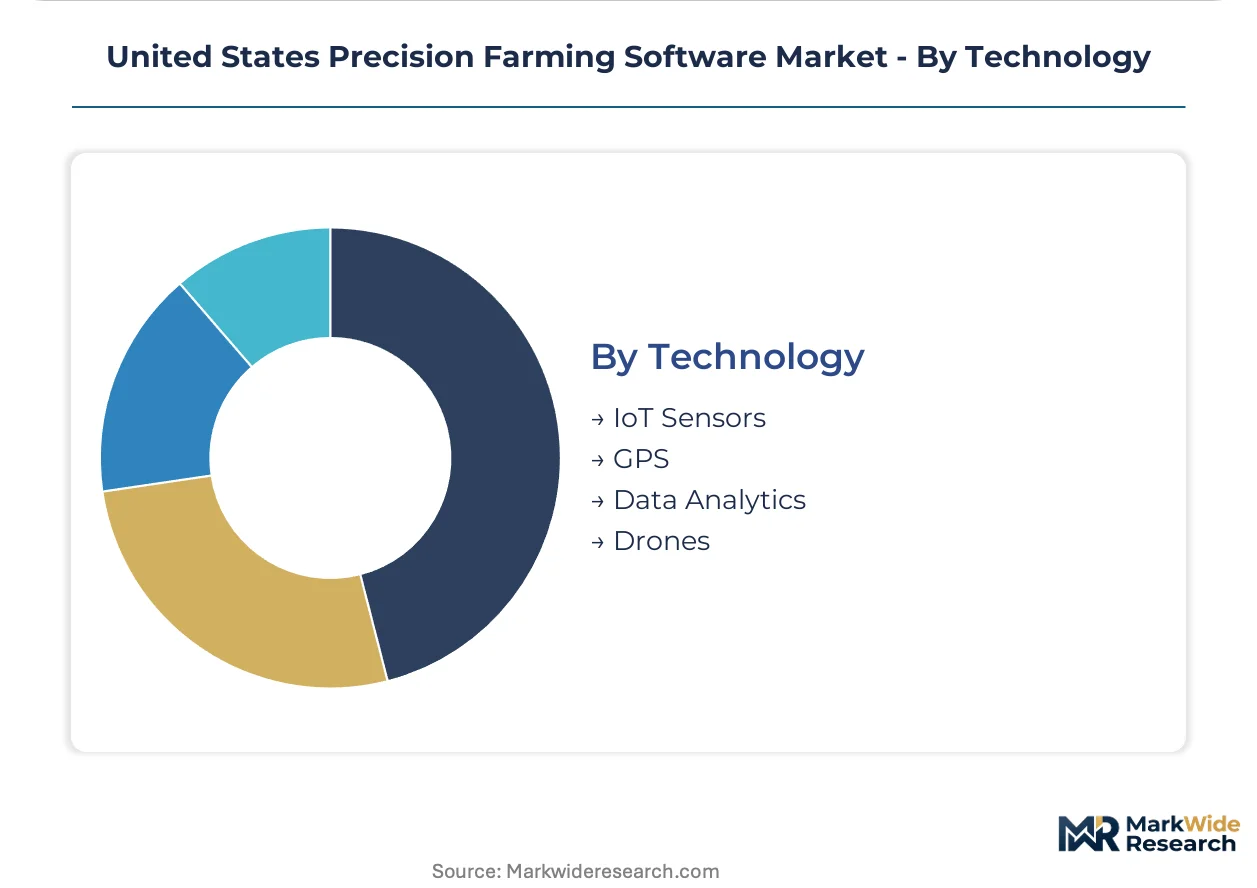
Technology:
Maturity curves separate established GPS and IoT infrastructure from emerging drone platforms still navigating FAA Part 107 operational constraints.
- GPS:Real-time kinematic correction networks deliver sub-decimeter accuracy for strip-till and targeted spraying. Nebraska and Iowa operations anchor demand through state department of agriculture audit intensity mandating geospatial application documentation.
- Data Analytics:Predictive models absorb agronomic decision workflows previously requiring certified advisors, elevating software centrality in farm operations while compressing advisory value chains.
- IoT Sensors:Ground-based soil moisture and weather station networks feed prescription algorithms.
- Drones:Multispectral aerial imaging enables real-time nitrogen stress detection, with fusion to ground sensor networks opening high-frequency monitoring subscription tiers.
GPS represents the most mature revenue base. Drone integration is climbing the fastest as FAA regulatory clarity improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors precision farming software deployment through its concentration of grain trading infrastructure and agribusiness headquarters. The Corn Belt corridor stretching westward generates concentrated demand for variable-rate application platforms and compliance documentation systems.
Illinois
Tile-drained row-crop operations drive demand for nutrient management software under the state's Nutrient Loss Reduction Strategy. The Illinois Department of Agriculture mandates precision application methods for participating producers, accelerating procurement timelines. Chicago and central Illinois grain cooperatives deploy multi-tenant platforms across consolidated acreage exceeding 10,000 acres per operation.
Iowa
Large-scale corn and soybean producers prioritize farm management dashboards for capital allocation committee oversight. The Iowa Department of Natural Resources enforces documented input reduction for cost-share program eligibility. Des Moines and Cedar Rapids corridors host expanding deployments of edge-computing nodes for real-time prescription adjustment.
Nebraska
Pivot irrigation operations in the Platte River Valley generate demand for water optimization algorithms. The Nebraska Department of Agriculture intensifies audit protocols for geospatial pesticide application records. Sandhills regions with limited broadband infrastructure retain on-premises installations despite higher vendor maintenance costs.
Kansas
Western Kansas dryland wheat operations face connectivity deficits that suppress cloud-based platform functionality. The Kansas Department of Agriculture administers conservation compliance verification through documented variable-rate application. High Plains corridors see emerging adoption of hybrid deployment architectures combining local edge nodes with intermittent cloud synchronization.
United States Precision Farming Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across data integration depth and hardware-software bundling capabilities. The market structure concentrates around three to five dominant platform ecosystems with substantial installed bases, while mid-tier vendors compete through specialized agronomic modules or regional service density. Strategic archetypes include embedded hardware-software integrators, open-platform middleware providers, and standalone analytics specialists. Dominant competitive moves encompass API accessibility expansion to reduce switching costs and carbon credit verification module development to capture emerging compliance revenue streams.
Within the embedded ecosystem tier, Deere & Company and AGCO Corporation exemplify contrasting architectural philosophies. Trimble Inc. anchors the high-accuracy positioning segment through specialized GNSS correction services. These three entities represent distinct competitive vectors: proprietary hardware-software integration, open-platform third-party compatibility, and precision measurement infrastructure respectively.
| Leading Market Players |
|---|
| Deere & Company |
| Trimble Inc. |
| AGCO Corporation |
| Corteva Agriscience |
| Bayer AG |
| Ag Leader Technology |
| Kubota Corporation |
| Farmers Edge Inc. |
| Topcon Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive hardware-software integration at Deere & Company and AGCO Corporation anchors supply positioning and pricing power across Midwest row-crop operations. These embedded ecosystems extract premium subscription tiers by tethering software functionality to proprietary telemetry terminals, compressing margin for standalone analytics vendors competing against bundled offerings.
Pricing Analysis
Yield-per-acre outcomes anchor value-based pricing tiers across precision farming platforms. Three-tier pricing structure across premium, standard, and economy levels separates enterprise farm management dashboards from basic field mapping tools. Price differentiation rests on API accessibility depth and carbon credit verification module inclusion. Cost compression in the standard tier intensifies because AGCO Corporation's open-platform architecture reduces switching costs for mixed-equipment fleets. Agricultural producers with sub-5,000 acre operations exhibit highest price sensitivity, while Illinois grain cooperatives with capital allocation committees tolerate premium positioning for multi-tenant compliance documentation.
Supply Chain Analysis
Agronomic data science talent scarcity in Iowa and Illinois manufacturing corridors constrains vendor R&D velocity and platform customization capacity. Hardware component sourcing draws from Taiwan for GNSS chipsets, Germany for ISOBUS-compatible telemetry terminals, and domestic Midwest fabrication for edge-computing nodes. Single-source vulnerability concentrates in real-time kinematic correction network infrastructure operated by Trimble Inc. Distribution runs through Deere & Company and AGCO Corporation dealer networks, with independent agronomists accessing platforms via direct SaaS procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native machine learning architectures are displacing legacy on-premises farm management systems across the Corn Belt. This technology transition compresses deployment timelines while elevating data export and API accessibility as non-negotiable procurement requirements.
For Market Incumbents: To counter open-platform interoperability threats from AGCO Corporation, Deere & Company should deepen backward integration into edge-computing node manufacturing and expand carbon credit verification module development. Trimble Inc. must defend GNSS correction service margins by embedding automated boundary mapping functionality that satisfies EPA Federal Insecticide, Fungicide, and Rodenticide Act recordkeeping mandates. For New Entrants and Emerging Players: Enter via Texas High Plains pivot irrigation operations, where water optimization algorithms face limited incumbent saturation compared to Midwest row-crop markets. Target Nebraska Sandhills producers with hybrid deployment architectures combining local edge nodes with intermittent cloud synchronization. Pursue white-label partnerships with independent agronomists seeking portable cross-farm benchmarking capabilities. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by embedded ecosystem players seeking agronomic data science talent and carbon market audit trail infrastructure. Long-term viability hinges on platform stickiness through data lock-in rather than volume acquisition. Watch for Illinois Nutrient Loss Reduction Strategy expansion into mandatory precision application methods as the inflection indicator for compliance-driven procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Credit Verification Module Development | Positions precision software as audit trail infrastructure for emerging agricultural carbon markets under USDA standards. |
| API Accessibility Expansion | Reduces switching costs for Illinois grain cooperatives demanding multi-platform integration across mixed-equipment fleets. |
| Edge-Computing Node Deployment | Enables sub-field resolution management across 10,000-plus acre Iowa operations without cloud latency constraints. |
| Drone Imagery Integration | Fuses multispectral aerial data with ground sensors for real-time nitrogen stress detection subscription tiers. |
| Texas High Plains Geographic Expansion | Captures greenfield demand for water optimization algorithms outside saturated Midwest variable-rate application markets. |
Research Methodology
USDA cost-share program documentation, EPA Federal Insecticide, Fungicide, and Rodenticide Act filings, and state-level nutrient loss reduction strategy compliance records formed the secondary backbone for regulatory demand quantification. Primary interviews with farm operations managers, precision agriculture specialists at equipment dealerships, certified crop advisors, and sustainability officers at grain cooperatives validated platform adoption drivers. SEC 10-K disclosures from Deere & Company, Trimble Inc., and AGCO Corporation provided hardware-software revenue segmentation. Bottom-up acreage deployment estimates triangulated against top-down subscription revenue models.
Historical trendline analysis of farm consolidation rates and broadband infrastructure deployment across Illinois, Iowa, and Nebraska informed penetration assumptions across the analysis window. Segmentation dimensions modeled encompassed deployment mode, operational scale tier, technology integration complexity, and regional compliance intensity. CAGRs derived from S-curve adoption pattern fitting against precision agriculture cost-share program participation trajectories. Forecast inputs incorporated USDA Environmental Quality Incentives Program budget allocations and EPA evolving pesticide application recordkeeping requirement timelines.
Revisions become necessary when USDA conservation compliance requirements materially expand or contract, broadband infrastructure gaps in Nebraska Sandhills narrow faster than projected, or agronomic data science talent scarcity intensifies beyond current substitution rates. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Crop Monitoring Market
Precision Agriculture
Agriculture Analytics Market
Precision Agriculture
Crop Nutrient Management Market
Precision Agriculture
Variable Rate Technology Market
Precision Agriculture
Soil Moisture Meter Market
Precision Agriculture
Precision Farming Software Market
Precision Agriculture
Global Precision Irrigation Market
Precision Agriculture
Global Internet of Things (IoT) Agriculture Market
Precision Agriculture
Telemetry-Linked Smart Fertilizer Program Market
Precision Agriculture
Soil Moisture Sensor Market
Precision Agriculture
Connected Agriculture Software Market
Precision Agriculture
Agricultural Sensors Market
Precision Agriculture
Global Advanced Farming Market
Precision Agriculture
Autonomous Crop Management Market
Precision Agriculture
Global Precision Livestock Farming Market
Precision Agriculture
Agriculture IoT Sensor Market