
 Crop Nutrient Management Market | 2026-2036
Crop Nutrient Management Market Size, Share, and Industry Trends Forecast 2026-2036
Crop Nutrient Management Market Outlook
Biostimulant-derived compounds are displacing conventional synthetic nitrogen in high-value horticulture, which is realigning product economics toward biological-input portfolios. Yara International ASA leverages its integrated ammonia-to-nitrate supply chain to sustain cost leadership in liquid fertilizer systems. Nutrien Ltd. anchors North American distribution through its retail agronomy network, while Coromandel International Ltd. dominates India's phosphatic fertilizer manufacturing with captive phosphate rock access.
Crop nutrient management encompasses the systematic planning, application, and monitoring of macro and micronutrient inputs to optimize plant uptake efficiency, typically involving nitrogen-phosphorus-potassium ratios calibrated to soil test values and crop removal rates. The practice aims to maximize yield per unit of applied nutrient while minimizing environmental losses through leaching, volatilization, or runoff. Fertilizers occupy the largest revenue share within product type segments, though bio-stimulants represent the fastest-expanding margin pool as growers seek root-zone activation products. Application through agriculture channels generates the dominant volume, while hydroponics commands premium pricing per hectare due to closed-system nutrient recirculation requirements. Granular delivery mode leads in emerging markets where mechanized spreading equipment predominates, whereas liquid formulations gain share in precision application systems.
The EPA regulates nutrient management through Clean Water Act permits for concentrated animal feeding operations and non-point source runoff controls, while the EU Green Deal's Farm to Fork strategy mandates integrated nutrient management plans with synthetic fertilizer reduction targets. Brazil's national fertilizer plan under the Ministry of Agriculture requires nutrient balance sheets for farms exceeding specified acreage thresholds. Stakeholders must monitor evolving carbon-accounting frameworks that credit verified nutrient-use-efficiency improvements toward Scope 3 emissions reductions.
Market Dynamics
Variable-rate application technology is compressing input costs for large-scale row-crop operators while regulatory mandates in the EU and Brazil force systemic nutrient accounting across farm operations.
Growth Catalysts
- EU Green Deal Farm to Fork mandates:Synthetic fertilizer reduction targets and integrated nutrient management plan requirements are accelerating demand for precision application equipment and soil monitoring services across member states.
- Brazilian Cerrado intensification:Soybean-corn double-cropping systems deplete soil nutrients faster than single-crop rotations, driving replacement demand for balanced NPK formulations and micronutrient supplementation.
- Remote sensing integration:Satellite imagery and drone-based NDVI mapping enable real-time canopy health assessment, triggering targeted fertigation adjustments that improve nitrogen use efficiency.
Market Restraints
- Natural gas price volatility:Ammonia synthesis consumes natural gas as both feedstock and energy input, exposing nitrogen fertilizer margins to European and Asian benchmark price swings.
- Phosphate rock concentration:Morocco, Western Sahara, and China control over 80% of minable phosphate reserves, creating supply security risks for phosphatic fertilizer manufacturers without captive mining assets.
- Application equipment compatibility:Legacy broadcast spreaders lack precision control hardware, forcing capital-intensive retrofits or replacement before farmers can adopt variable-rate systems.
Strategic Opportunities
- Carbon credit monetization:Verified nutrient-use-efficiency improvements under emerging Scope 3 accounting frameworks allow food processors to offset supply chain emissions through farmer incentive programs.
- Hydroponic closed-loop systems:Vertical farming and greenhouse operations require recirculating nutrient solutions with real-time ion monitoring, creating premium service contracts for technical support and formulation supply.
- India's PLI scheme for specialty fertilizers:Production-linked incentives for nano-urea and customized fertilizer manufacturing attract domestic capacity expansion beyond traditional commodity grades.
Industry Challenges
- Agronomic data integration:Soil test labs, weather services, and equipment telematics generate incompatible file formats, forcing farmers to manually reconcile datasets before generating prescription maps.
- 4R Nutrient Stewardship certification timelines:Third-party verification of right source, rate, time, and place application requires multi-season documentation that delays premium pricing access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crop Nutrient Management Market |
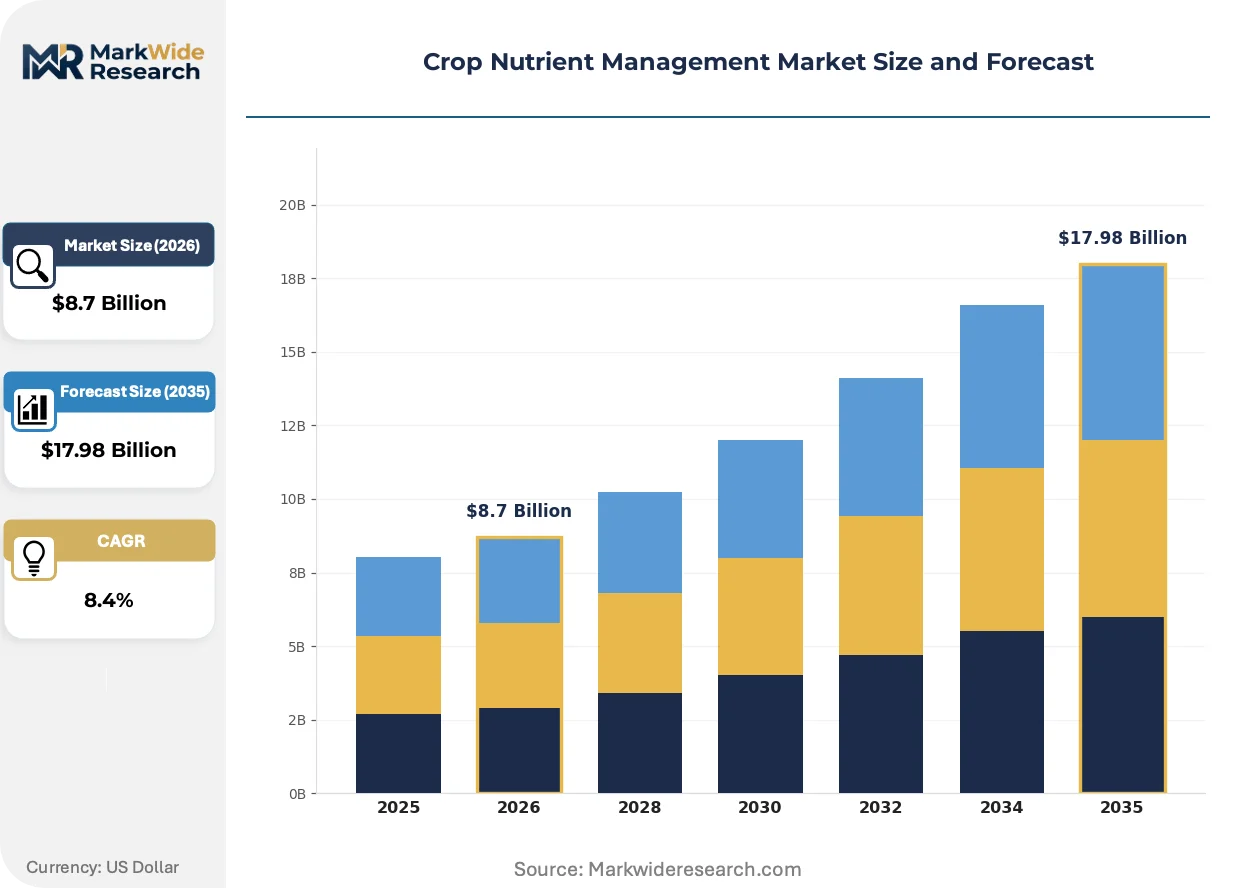
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fertilizers, Micro-Nutrients, Bio-Stimulants, Soil Conditioners Application: Agriculture, Horticulture, Organic Farming, Hydroponics Delivery Mode: Granular, Liquid, Powder, Coated End User: Farmers, Agro Dealers, Cooperatives, Agronomists |
| Companies Covered | Yara International ASA, Nutrien Ltd., ICL Group Ltd., BASF SE, The Mosaic Company, Nouryon, Coromandel International Ltd., Israel Chemicals Ltd., CF Industries Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crop Nutrient Management Market Strategic Shifts
Biological input portfolios are gaining formulation sophistication as microbial inoculants and biostimulant compounds demonstrate consistent yield responses in replicated trials.
Sensor-enabled fertigation hardware is converging with cloud-based decision support platforms to automate nutrient delivery based on real-time soil moisture and electrical conductivity readings. Large-scale vegetable producers in California's Central Valley and Spain's Almería province are deploying these systems at commercial scale. The structural compression of labor requirements and input waste is reshaping operating cost structures for protected cropping operations.
The EPA's non-point source runoff controls under the Clean Water Act are tightening discharge permits for agricultural watersheds, particularly in the Chesapeake Bay and Mississippi River basins. Farmers in affected drainage districts must now document nutrient management plans to maintain operating licenses. This regulatory pressure is accelerating demand for edge-of-field bioreactors and saturated buffers that intercept tile drainage before surface water entry.
Retail agronomy networks are unbundling product supply from technical advisory services, charging per-hectare subscription fees for prescription generation rather than marking up input volumes. This decoupling aligns dealer incentives with farmer outcomes rather than tonnage throughput. The model is spreading fastest in the US Corn Belt where cooperatives compete for acreage contracts with integrated grain origination and nutrient management packages.
Crop Nutrient Management Market Segmentation
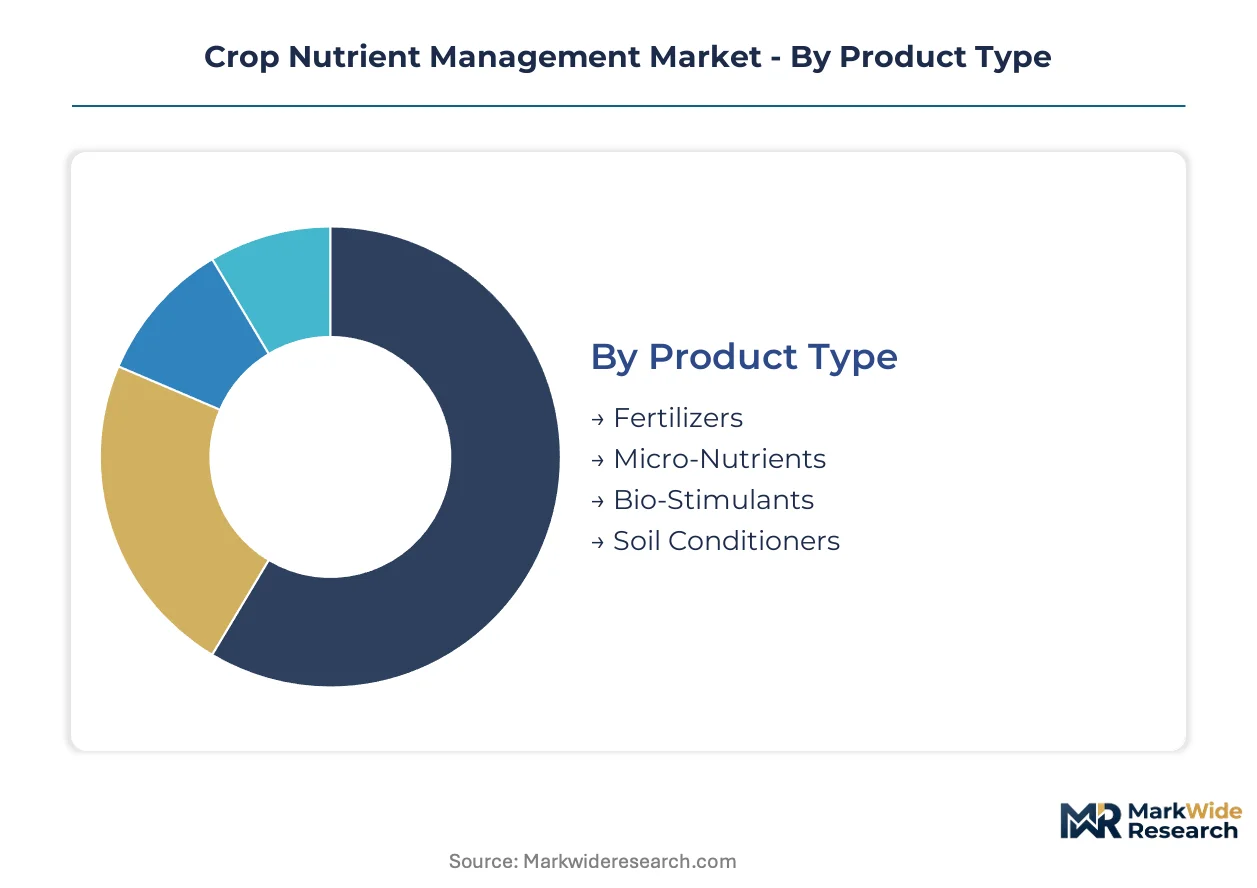
Crop nutrient management segments diverge sharply by input chemistry, application precision, and buyer sophistication. Each dimension carries distinct margin profiles and regulatory exposure that reshape competitive positioning across the value chain.
Product Type:
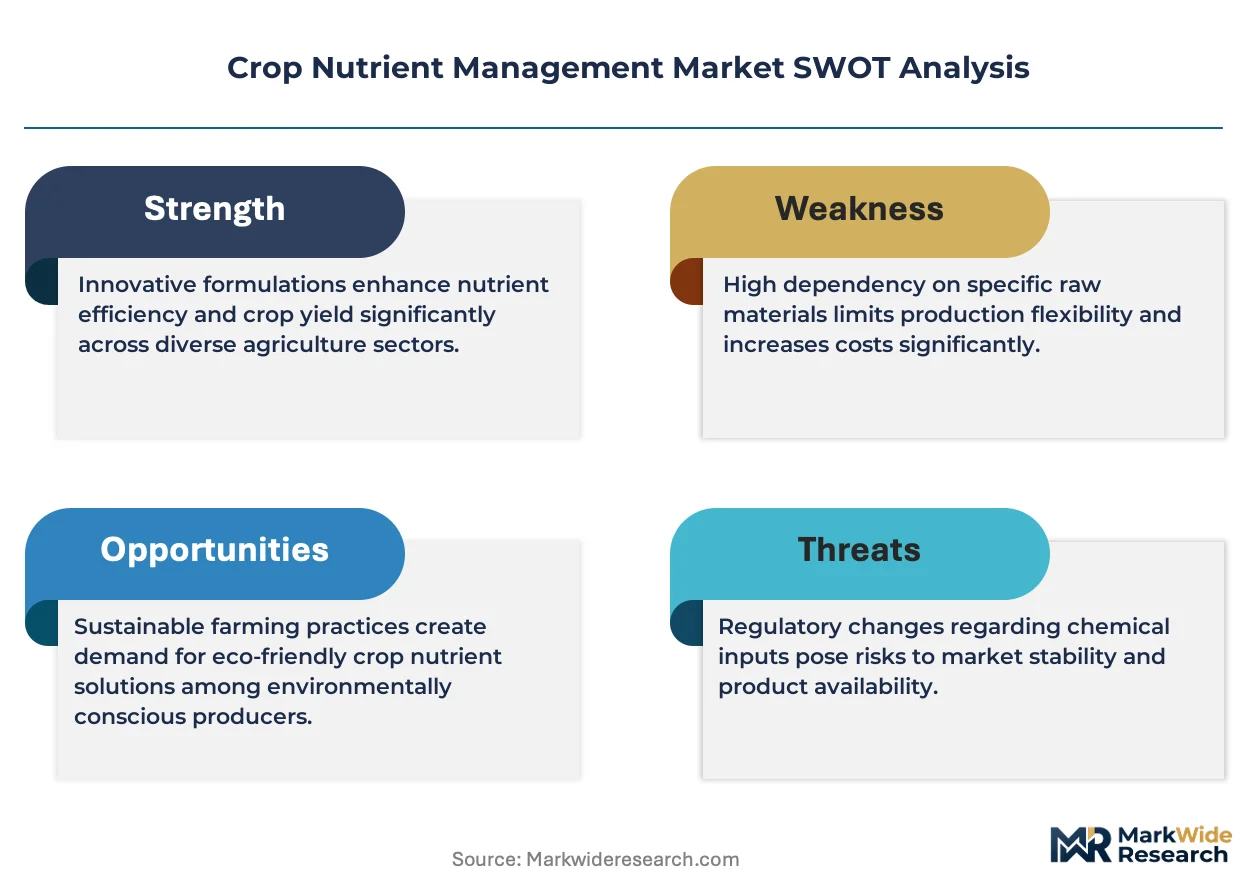
Supply concentration in ammonia synthesis and phosphate mining tilts manufacturing economics toward integrated producers with captive raw material access.
- Fertilizers:Nitrogen-phosphorus-potassium formulations dominate tonnage throughput, with ammonia-derived urea and ammonium nitrate anchoring commodity pricing benchmarks. Demand concentrates in Brazil's Cerrado soybean-corn rotations where double-cropping intensifies nutrient replacement cycles.
- Bio-Stimulants:Microbial inoculants, seaweed extracts, and protein hydrolysates activate root-zone metabolic pathways without direct nutrient provision. High-value horticulture in Spain's Almería province and California's Central Valley drives premium pricing as growers seek synthetic nitrogen displacement.
- Micro-Nutrients:Zinc, boron, and manganese formulations address deficiency corrections in alkaline soils.
- Soil Conditioners:Gypsum, lime, and organic matter amendments modify pH and cation exchange capacity.
Today's leader: Fertilizers. Tomorrow's challenger: Bio-Stimulants.
Application:
Volume-maturity separation creates divergent customer acquisition economics across open-field and controlled-environment systems.
- Agriculture:Row-crop and broadacre operations consume the dominant nutrient volumes, with variable-rate application technology compressing per-hectare input costs. Large-scale operators in the US Corn Belt and Brazil's Mato Grosso deploy prescription mapping to align NPK ratios with yield potential zones.
- Hydroponics:Closed-loop recirculating systems demand real-time ion monitoring and precise electrical conductivity management, commanding premium service contracts. Vertical farming installations in the Netherlands and Singapore require continuous technical support for nutrient solution formulation.
- Horticulture:Protected cropping of vegetables and ornamentals favors fertigation integration.
- Organic Farming:Certified operations restrict synthetic input eligibility, redirecting procurement toward approved mineral and biological sources.
Today's leader: Agriculture. Tomorrow's challenger: Hydroponics.
Delivery Mode:
Equipment compatibility constraints fragment adoption timelines between legacy broadcast systems and precision application infrastructure.
- Liquid:Suspension and solution formulations integrate with fertigation infrastructure and variable-rate spray equipment, enabling real-time rate adjustments based on canopy sensors. Adoption accelerates in precision agriculture deployments across Germany's Bavaria and France's Champagne regions.
- Granular:Dry prilled and compacted products dominate emerging markets where mechanized spreading equipment predominates and storage infrastructure favors solid handling. India's rice-wheat belt and Ukraine's black-soil regions maintain heavy reliance on broadcast application.
- Powder:Fine-ground formulations serve specialty blending and hydroponic dissolution requirements.
- Coated:Polymer and sulfur encapsulation enables controlled-release nutrient delivery.
Today's leader: Granular. Tomorrow's challenger: Liquid.
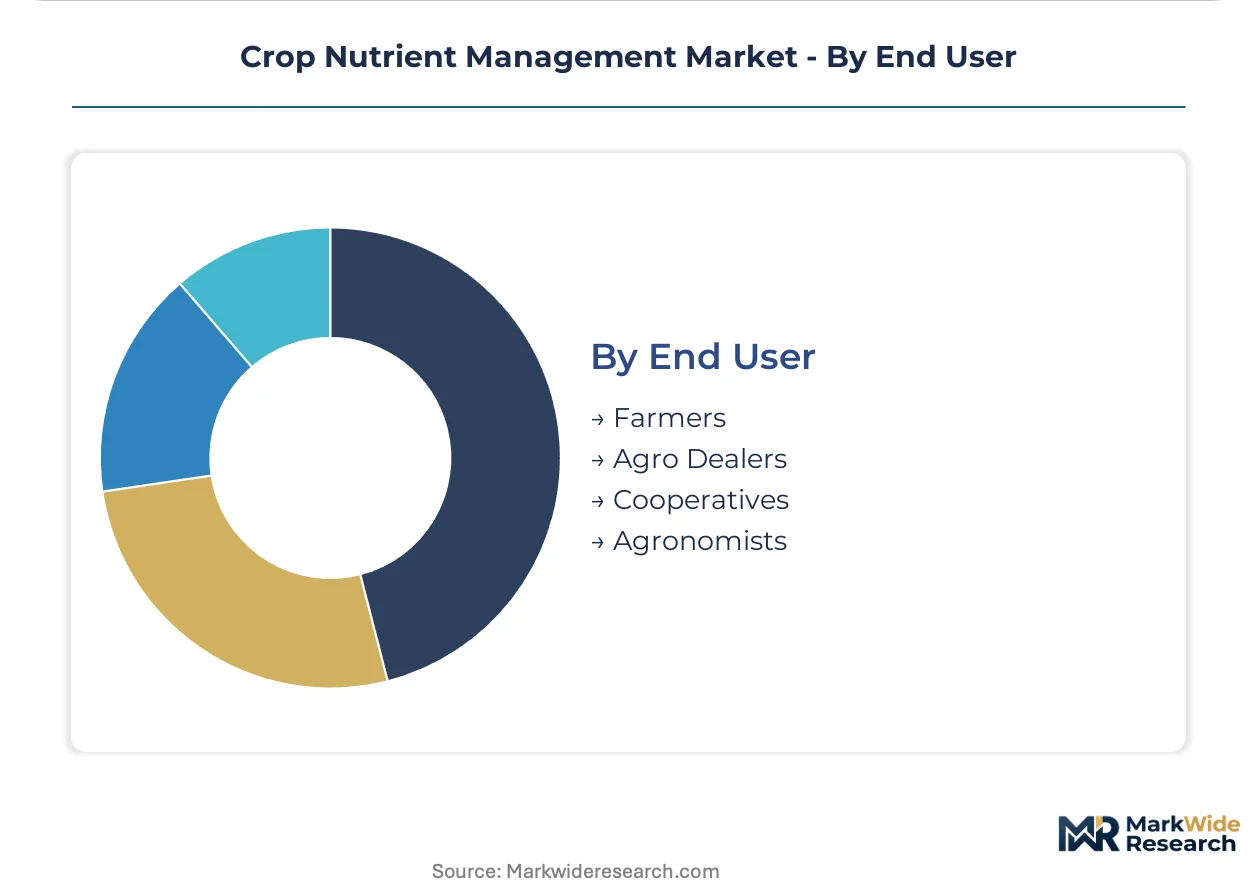
End User:
Procurement authority concentration determines pricing power and technical advisory bundling structures.
- Farmers:Direct purchasers range from subsistence operators to large-scale commercial enterprises, with decision sophistication varying by acreage and capital access. Brazilian soybean producers above 1,000 hectares increasingly demand integrated nutrient management plans to satisfy Ministry of Agriculture reporting requirements.
- Cooperatives:Member-owned aggregations consolidate input purchasing and grain origination, leveraging volume scale for preferential pricing. Midwestern US cooperatives compete for acreage contracts through bundled agronomy subscriptions.
- Agro Dealers:Retail distribution networks intermediate product supply and prescription generation services.
- Agronomists:Independent consultants and cooperative staff provide fee-based recommendation services.
Today's leader: Farmers. Tomorrow's challenger: Cooperatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Corn Belt concentrates precision agriculture deployment and variable-rate nutrient adoption, with large-scale operators driving equipment upgrades and prescription mapping services across Iowa, Illinois, and Indiana.
United States
Soybean-corn rotations dominate nutrient demand, with farmers above 5,000 hectares deploying satellite-guided application systems. The EPA's Clean Water Act non-point source controls tighten discharge permits in the Chesapeake Bay and Mississippi River basins. Iowa's Des Moines Lobe exhibits the densest concentration of nitrogen management plan compliance requirements.
Brazil
Soybean-corn double-cropping in Mato Grosso and Goiás accelerates soil nutrient depletion cycles. The Ministry of Agriculture mandates nutrient balance sheets for farms exceeding 1,000 hectares under the national fertilizer plan. The Cerrado region surrounding Rondonópolis anchors replacement demand for balanced NPK formulations.
Germany
Bavaria's precision agriculture adoption leads European variable-rate liquid fertilizer deployment. The EU Green Deal's Farm to Fork strategy imposes synthetic fertilizer reduction targets and integrated nutrient management plan requirements. The Rhine-Ruhr corridor hosts formulation blending facilities serving Dutch and French export markets.
India
Rice-wheat belt farmers in Punjab and Haryana transition from urea-heavy regimes toward customized fertilizer grades. The PLI scheme for specialty fertilizers incentivizes nano-urea and micronutrient manufacturing capacity expansion. Gujarat's fertilizer manufacturing cluster leverages captive phosphate rock processing for domestic phosphatic supply security.
China
Shandong Province's vegetable greenhouse operations drive fertigation system integration and real-time nutrient monitoring adoption. The Ministry of Ecology and Environment tightens runoff controls in Taihu Lake watershed agricultural districts. The Yangtze River Delta concentrates hydroponic research facilities serving vertical farming export technology development.
Crop Nutrient Management Market Competitive Environment
Global majors compete with regional champions across ammonia synthesis, phosphate mining, and precision application technology vectors. The vendor base clusters around integrated producers with captive raw material access and specialized distributors with agronomy advisory capabilities. Three archetypes dominate: integrated ammonia-nitrate manufacturers, phosphate rock miners with downstream formulation assets, and retail agronomy networks bundling prescription services with input supply. Competitive moves center on backward integration into phosphate mining and forward integration into carbon credit verification platforms.
Within the integrated manufacturing tier, Yara International ASA and Nutrien Ltd. exemplify scale-driven ammonia supply chain control, while Coromandel International Ltd. anchors regional phosphate processing specialization. These three occupy positions spanning Nordic integrated nitrogen systems, North American retail distribution density, and Indian phosphatic manufacturing with captive mineral access.
| Leading Market Players |
|---|
| Yara International ASA |
| Nutrien Ltd. |
| ICL Group Ltd. |
| BASF SE |
| The Mosaic Company |
| Nouryon |
| Coromandel International Ltd. |
| Israel Chemicals Ltd. |
| CF Industries Holdings, Inc. |
| Others |
Value Chain & Pricing Dynamics
The EU Green Deal's Farm to Fork synthetic fertilizer reduction targets gate both qualified supply and premium-tier pricing access, as manufacturers must certify integrated nutrient management compliance before entering contracted procurement channels serving large-scale row-crop operators.
Pricing Analysis
Input-cost pass-through from natural gas feedstock volatility dominates nitrogen fertilizer pricing, with ammonia synthesis margins tethered to European and Asian benchmark swings. Three-tier pricing structure across premium, standard, and economy levels separates 4R Nutrient Stewardship-certified formulations from commodity grades and unblended bulk products. Cost compression in standard-tier urea is intensifying because Brazilian and Indian buyers consolidate procurement through cooperative aggregations. Smallholder farmers in South Asia exhibit highest price sensitivity, while Dutch greenhouse operators accept premium liquid formulation pricing for closed-loop system compatibility.
Supply Chain Analysis
India's PLI scheme for specialty fertilizers and Brazil's national fertilizer plan domestic-content requirements are reshaping sourcing, compelling multinational blenders to establish localized formulation capacity. Manufacturing gravity centers on China, Morocco, and Russia for phosphate rock and ammonia derivatives, with India's Gujarat corridor emerging as a phosphatic processing hub. Raw material flows draw from natural gas fields, phosphate rock deposits, and potash mines across Belarus and Canada. Single-source vulnerability concentrates in Moroccan phosphate rock access, where captive mining assets determine supply security. Distribution runs through retail agronomy networks bundling prescription services with input supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in crop nutrient management rests on precision application technology cost-down curves and the shift toward subscription-based agronomy advisory services decoupled from product tonnage.
For Market Incumbents: Extend carbon credit verification platform capabilities to capture Scope 3 accounting demand from food processors, while deepening backward integration into phosphate rock mining to offset Moroccan supply concentration risk. Defend against biostimulant disruptors by acquiring microbial inoculant formulation specialists with replicated trial datasets.
For New Entrants and Emerging Players: Enter via hydroponic nutrient solution technical support contracts in vertical farming clusters across Singapore and the Netherlands, where closed-loop system complexity creates service stickiness. Target India's nano-urea manufacturing incentives under PLI scheme provisions, partnering with Gujarat-based distribution cooperatives for market access.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional phosphate blenders lacking captive rock access but holding Ministry of Agriculture certification relationships in Brazil. Five-to-ten-year viability favors integrated ammonia-nitrate manufacturers with European carbon-border adjustment positioning. Monitor EPA Clean Water Act permit tightening in Chesapeake Bay watersheds as regulatory inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Mining | Captive Moroccan or Western Sahara rock access insulates margin from OCP supply rationing. |
| Carbon Credit Verification Platform Development | Verified nutrient-use-efficiency protocols unlock Scope 3 offset contracts with Cargill and ADM. |
| Precision Application Equipment Partnership | John Deere Operations Center integration enables real-time variable-rate prescription delivery. |
| Hydroponic Technical Support Service Launch | Recirculating system monitoring contracts command recurring revenue per hectare in Almería greenhouses. |
| 4R Nutrient Stewardship Certification Investment | Third-party verification opens premium pricing channels with EU Green Deal compliance requirements. |
Study Parameters
Multiple input streams — agronomist interviews, cooperative procurement manager discussions, fertilizer manufacturer executive consultations, and regulatory affairs specialist briefings — were reconciled against customs trade databases, SEC 10-K filings, EU fertilizer consumption statistics, and Brazilian Ministry of Agriculture reporting. Bottom-up field-level adoption estimates triangulated with top-down national fertilizer consumption aggregates.
Historical volume trajectories cross-referenced against expert panel input on technology diffusion rates and regulatory implementation timelines across the projection horizon. Segmentation modeling captured product type chemistry tiers, application precision levels, delivery mode equipment compatibility, and end-user procurement authority concentration. CAGRs derived from slope-consistency checks against input-cost elasticity assumptions and acreage expansion patterns in Brazil's Cerrado.
Inputs from EPA discharge permit databases and EU Farm to Fork strategy implementation trackers were available through the study window; gaps in real-time farmer prescription mapping adoption rates introduce uncertainty bands around precision agriculture penetration assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Precision Livestock Market
Precision Agriculture
Global Digital Agriculture Platform Market
Precision Agriculture
Agriculture IoT Sensor Market
Precision Agriculture
Americas Precision Farming Software Market
Precision Agriculture
Telemetry-Linked Smart Fertilizer Program Market
Precision Agriculture
Soil Moisture Sensor Market
Precision Agriculture
Variable Rate Technology Market
Precision Agriculture
Digital Agriculture Market
Precision Agriculture
Global Agriculture Sensors Market
Precision Agriculture
Global Internet of Things (IoT) Agriculture Market
Precision Agriculture
Autonomous Crop Management Market
Precision Agriculture
Remote Fertigation Monitoring Services Market
Precision Agriculture
Precision Agriculture Soil Nutrient and Microbiome Field Test Devices Market
Precision Agriculture
Soil Moisture Meter Market
Precision Agriculture
Automated Pest Monitoring System Market
Precision Agriculture
North America Precision Agriculture Market