
 Global Digital Farming Market | 2026-2036
Global Digital Farming Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Farming Market Analysis
Agronomic data science talent scarcity is unwinding across the Global Digital Farming Market as universities struggle to produce graduates fluent in both crop physiology and machine learning. Deere & Company leverages its dealer network and proprietary Operations Center platform to anchor precision equipment sales across the Americas. AGCO Corporation competes through Fuse open-architecture connectivity that allows mixed-fleet interoperability. Trimble Inc. specializes in correction services and GNSS hardware that dominates high-accuracy guidance applications.
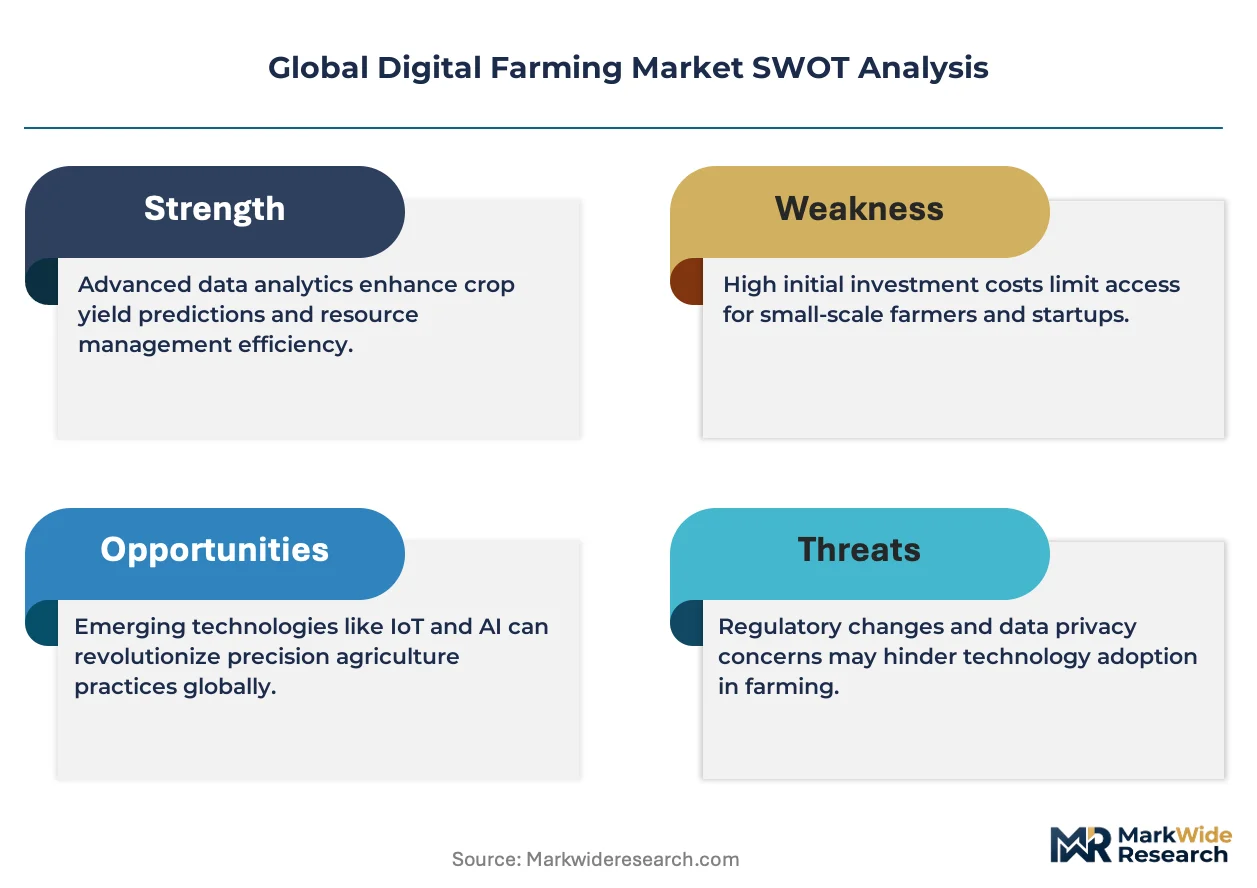
Digital farming encompasses the integration of information and communication technologies into agricultural production systems, combining variable-rate application controllers, remote sensing payloads, and cloud-based decision support tools to optimize biological and physical inputs at sub-field resolution. The technology stack spans precision agriculture hardware, IoT sensor networks, aerial imaging platforms, and AI analytics engines that process multispectral and thermal data into actionable agronomic recommendations. Farm management software currently occupies the central margin pool as recurring subscription revenue displaces one-time equipment sales, while crop monitoring tools and soil health kits represent faster-growing product categories as regenerative agriculture protocols gain traction among commercial farmers and agricultural cooperatives.
The United States Department of Agriculture and the Federal Communications Commission shape market access through rural broadband subsidy programs and spectrum allocation for agricultural IoT, while the European Commission's Farm to Fork strategy and CSRD reporting requirements redirect procurement toward carbon-accounting-enabled platforms. Brazil's ANVISA and national agricultural research corporation Embrapa influence pesticide application regulations that determine sensor and drone compliance specifications for pest control workflows. Stakeholders must monitor evolving data ownership frameworks and interoperability mandates that will determine platform switching costs and ecosystem lock-in intensity across major producing regions.
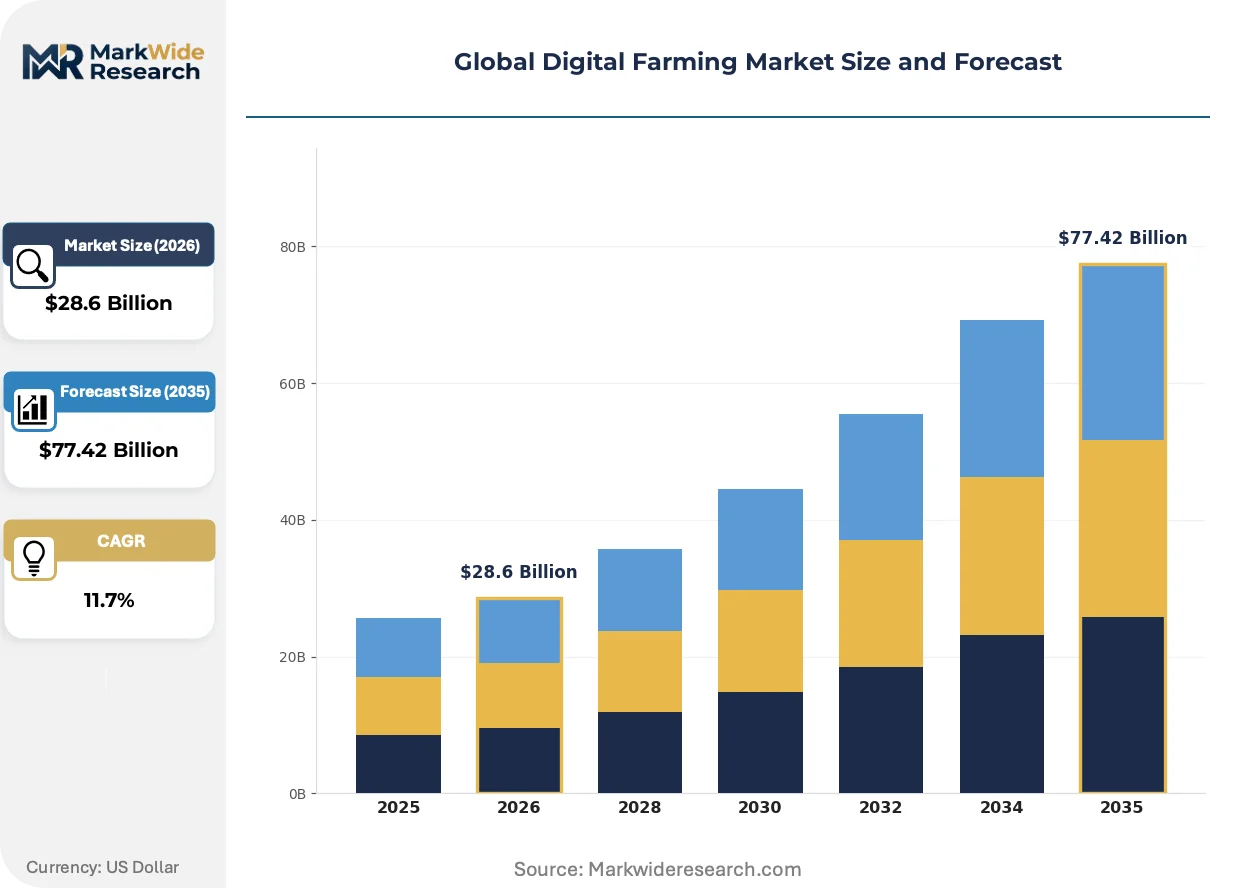
Market Dynamics
Subscription-based farm management software is displacing one-time equipment sales as the dominant revenue model, compressing capital cycles and locking growers into recurring data ecosystems that deepen platform dependency.
Growth Catalysts
- USDA Rural Broadband Subsidies:Federal Communications Commission spectrum allocations for agricultural IoT expand connectivity infrastructure across remote cropland, enabling real-time sensor networks.
- Variable-Rate Application Controllers:Precision hardware reduces fertilizer and pesticide input costs by applying inputs at sub-field resolution based on soil mapping data.
- EU Green Deal Incentives:Farm to Fork strategy subsidies accelerate procurement of carbon-accounting platforms among European agricultural cooperatives.
Market Restraints
- GNSS Correction Service Concentration:High-accuracy guidance depends on concentrated correction infrastructure, creating vulnerability to signal degradation or pricing power abuse.
- Legacy Equipment Interoperability:Mixed-fleet operations face technical friction integrating proprietary OEM data protocols with open-architecture platforms.
- Silicon Supply Volatility:Semiconductor shortages disrupt manufacturing timelines for IoT sensors and edge computing devices essential to precision workflows.
Strategic Opportunities
- Regenerative Agriculture Protocols:Soil health monitoring kits capture expanding demand from carbon credit verification and biodiversity certification schemes.
- Brazilian Compliance Specifications:ANVISA pesticide application regulations create specialized sensor and drone requirements for Latin American pest control markets.
- AI-Multispectral Convergence:Machine learning analytics processing thermal and hyperspectral imagery unlock automated disease detection capabilities.
Industry Challenges
- Agronomic Data Science Scarcity:Universities fail to produce sufficient graduates fluent in both crop physiology and machine learning, constraining platform development.
- Data Ownership Framework Uncertainty:Ambiguous legal regimes governing farm-generated data create liability risks and limit third-party integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Farming Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $77.42 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Precision Agriculture, IoT Sensors, Drones, AI Analytics Product Type: Farm Management Software, Crop Monitoring Tools, Livestock Tracking Solutions, Soil Health Kits End User: Commercial Farmers, Agricultural Cooperatives, Research Institutions, Government Agencies Application: Crop Management, Yield Prediction, Pest Control, Resource Optimization |
| Companies Covered | Deere & Company, AGCO Corporation, CNH Industrial N.V., Trimble Inc., Bayer AG, Syngenta Group Co., Ltd., IBM Corporation, Topcon Corporation, Kubota Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Farming Market Emerging Trajectories
Cloud-native decision support tools are compressing the latency between field data collection and agronomic action, enabling same-day input adjustments that static prescription maps cannot match.
Hyperspectral imaging payloads mounted on fixed-wing drones is displacing satellite-based crop monitoring for high-value specialty crops. Large-scale vegetable operations in California's Central Valley adopt these systems for weekly canopy health assessments. The technology is displacing slower revisit-cycle satellite subscriptions that miss critical irrigation stress windows.
EU CSRD reporting requirements mandate scope 3 emissions disclosure from agricultural supply chains, forcing food processors to demand carbon-accounting-enabled farm management platforms. European cooperatives respond by bundling sustainability dashboards with core subscription tiers. Specialty crop exporters to EU markets face the steepest compliance timeline pressure.
Cooperative procurement consortia now aggregate software licensing across hundreds of member farms to extract volume discounts from platform vendors. This buyer concentration compresses vendor margins and accelerates feature standardization. The pattern is most visible across Midwestern US row-crop operations where scale economies dominate adoption decisions.
Global Digital Farming Market Segmentation
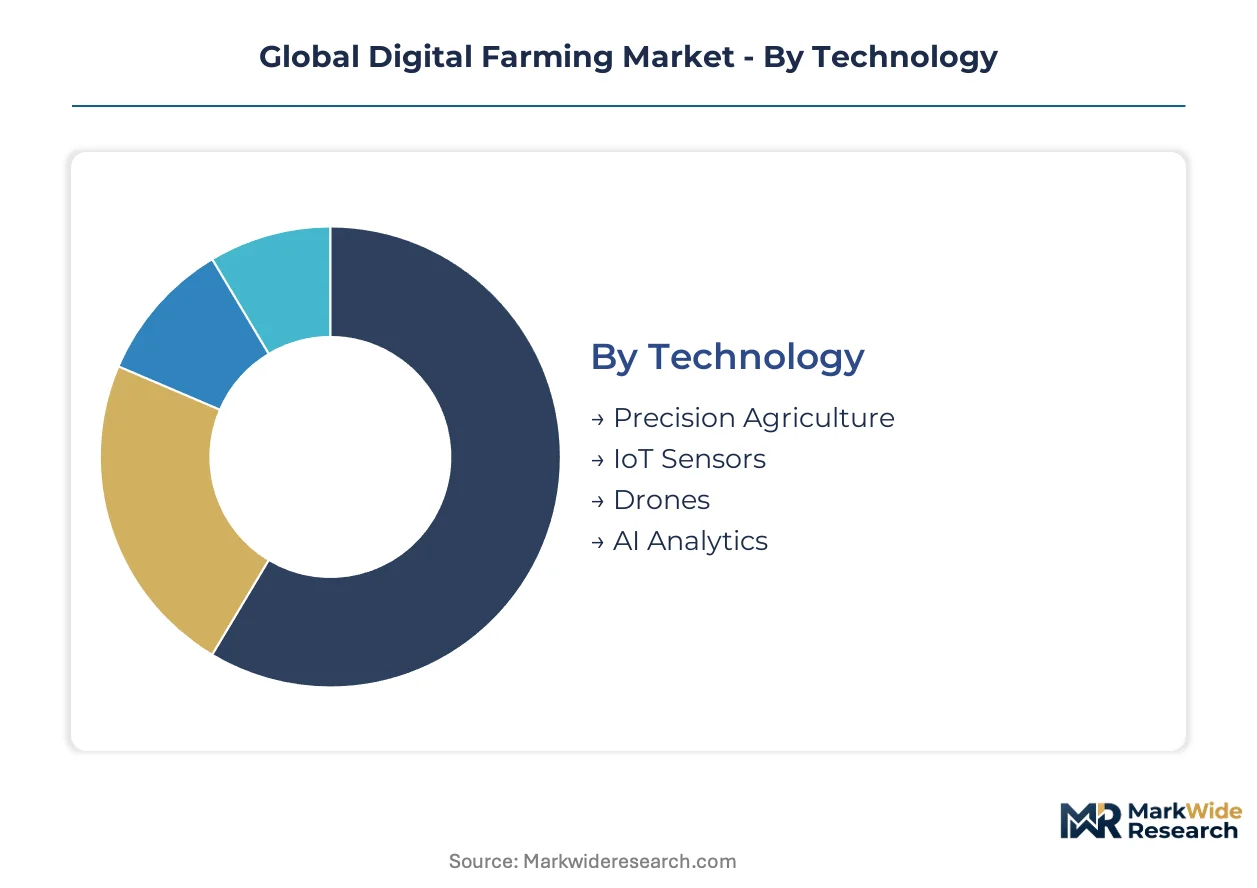
Technology heterogeneity across the Global Digital Farming Market demands granular segmentation to map procurement patterns, margin structures, and deployment timelines. Each dimension reveals distinct geographic concentration and customer archetype dependencies.
Technology:
Precision Agriculture systems anchor domestic procurement in large-scale farming economies, while AI Analytics and drone platforms exhibit stronger export-led demand from technology-originating markets.
- Precision Agriculture:Variable-rate application controllers and GNSS-guided equipment dominate capital expenditure cycles across Midwestern United States row-crop operations. Deere's Operations Center and AGCO's Fuse platform lock growers into proprietary data ecosystems that deepen replacement part dependency and compress upgrade intervals.
- AI Analytics:Machine learning engines processing multispectral imagery into agronomic prescriptions concentrate demand among Brazilian soybean cooperatives and Australian broadacre wheat producers. The technology requires cloud connectivity infrastructure that remains patchy across Sub-Saharan Africa and Central Asian steppe regions.
- IoT Sensors:Soil moisture and weather station networks deploy most densely in Dutch greenhouse clusters and Israeli drip-irrigation districts where water scarcity justifies real-time monitoring capital outlays.
- Drones:Fixed-wing and multirotor platforms for aerial imaging face regulatory fragmentation; FAA Part 107 compliance shapes United States adoption timelines while EASA drone regulations standardize European procurement specifications.
Precision Agriculture commands the established base. The steepest expansion runs through AI Analytics.
Product Type:
Subscription pricing models concentrate recurring revenue in software categories, while hardware kits exhibit higher upfront capital barriers and longer replacement cycles.
- Farm Management Software:Cloud-based platforms aggregate field data, financial records, and compliance documentation into unified dashboards. European cooperatives bundle CSRD-aligned carbon accounting modules as regulatory pressure intensifies scope 3 disclosure requirements from food processors.
- Soil Health Kits:Portable spectroscopy devices and biological assay tools verify regenerative agriculture protocols for carbon credit markets. Demand clusters in Australian carbon farming schemes and United States Department of Agriculture conservation program enrollment districts.
- Crop Monitoring Tools:Satellite and drone-derived vegetation index subscriptions serve specialty crop exporters in Chilean fruit valleys and Kenyan flower farms where irrigation stress detection timing determines quality premiums.
- Livestock Tracking Solutions:RFID ear tags and automated weighing systems concentrate in Brazilian cattle feedlots and New Zealand dairy cooperatives where traceability mandates from importing markets drive procurement.
Farm Management Software captures the recurring revenue concentration. Soil Health Kits are climbing the fastest as carbon verification protocols proliferate.
End User:
Scale economies differentiate procurement patterns; large consolidated operations extract volume discounts while fragmented smallholders rely on cooperative aggregation.
- Commercial Farmers:United States corn-soy operations above 5,000 acres generate the highest per-farm software licensing values and precision equipment depreciation schedules. These operators pilot autonomous machinery before broader market availability.
- Agricultural Cooperatives:French cereal cooperatives and Indian Farmers Fertiliser Cooperative Limited members aggregate procurement across thousands of smallholders to negotiate platform licensing terms and shared agronomist services.
- Research Institutions:Wageningen University and Embrapa field stations validate algorithm performance across diverse agroecological zones, influencing national subsidy eligibility criteria for commercial adoption.
- Government Agencies:United States Department of Agriculture and Australia's Bureau of Meteorology fund rural broadband and sensor network infrastructure that lowers private sector deployment barriers.
Commercial Farmers anchor the revenue base. Agricultural Cooperatives are expanding most quickly as buyer consolidation accelerates.
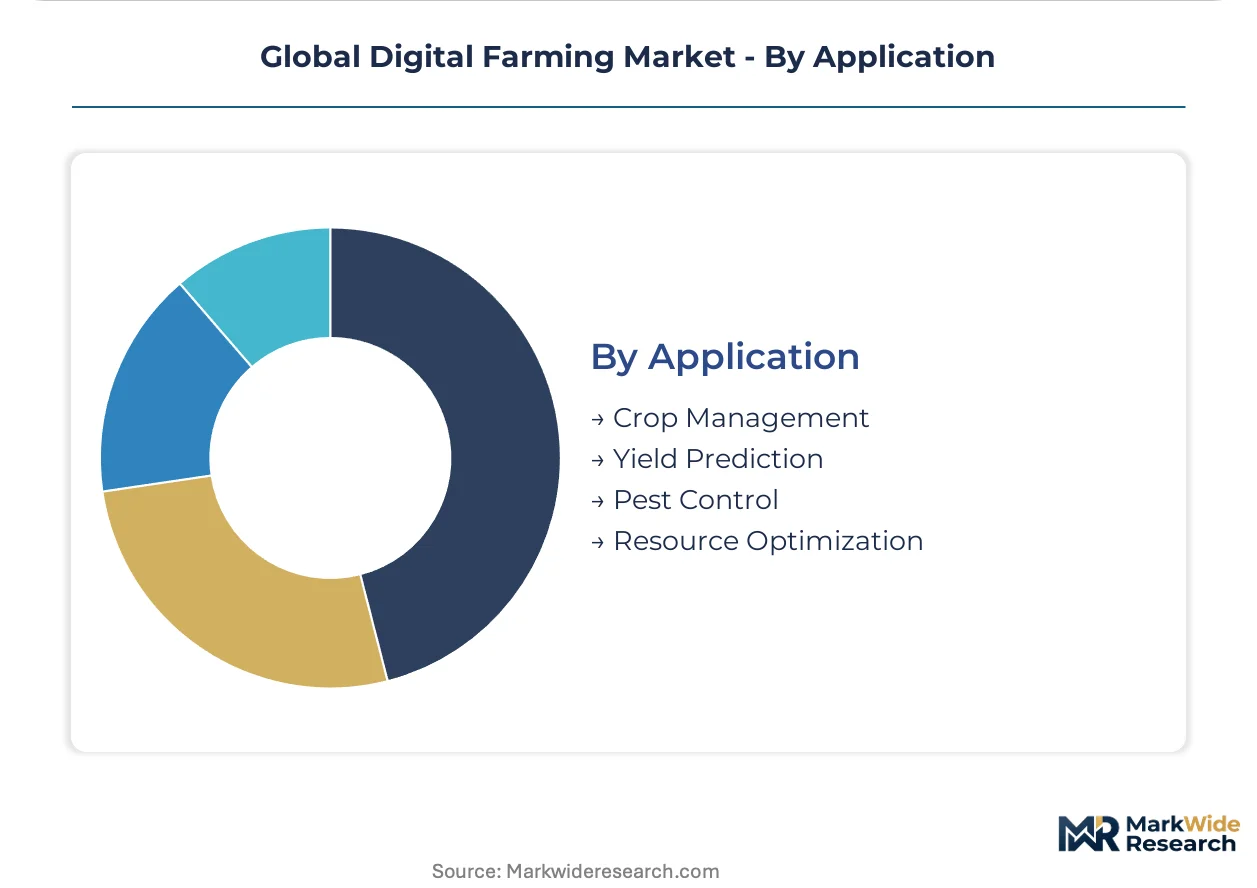
Application:
Input cost volatility drives adoption sequencing; fertilizer price spikes accelerate resource optimization deployments faster than yield prediction analytics.
- Resource Optimization:Variable-rate nitrogen and irrigation scheduling algorithms reduce input waste across California Central Valley almond orchards and Punjab rice-wheat systems where water and fertilizer costs dominate operating budgets.
- Pest Control:Automated drone spraying and pheromone trap sensor networks comply with ANVISA regulations in Brazilian citrus districts and European Union sustainable use directive requirements in French vineyards.
- Crop Management:Growth stage monitoring and harvest timing recommendations concentrate in Argentine soybean operations and Ukrainian grain export corridors where logistics coordination determines price realization.
- Yield Prediction:Satellite-based biomass modeling supports crop insurance underwriting and commodity trading decisions across Australian wheat belts and Canadian prairie provinces.
Resource Optimization holds the installed base concentration. Pest Control is gaining share fastest as biological regulation compliance tightens across major producing regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major agricultural economies. United States operators prioritize yield optimization through precision hardware, while European procurement tilts toward carbon-accounting compliance, and Brazilian adoption clusters around pest control automation for export certification.
United States
Large-scale corn-soy operations above 5,000 acres generate the highest software licensing volumes and precision equipment depreciation schedules. USDA Rural Broadband subsidies and FCC spectrum allocations for agricultural IoT expand connectivity infrastructure across remote cropland. The Iowa-Illinois corn belt concentrates autonomous machinery pilot programs before broader market availability.
Germany
EU Green Deal incentives and Farm to Fork strategy subsidies accelerate procurement of climate-smart digital tools among cereal cooperatives. CSRD reporting requirements mandate scope 3 emissions disclosure from agricultural supply chains. Bavarian dairy clusters adopt livestock tracking solutions to meet traceability mandates from importing markets.
Brazil
Soybean cooperatives and citrus districts drive demand for AI analytics and automated drone spraying systems. ANVISA pesticide application regulations determine sensor and drone compliance specifications for pest control workflows. São Paulo state concentrates specialized equipment procurement for export certification to European and Asian markets.
Australia
Broadacre wheat producers and carbon farming schemes generate concentrated demand for AI analytics and soil health verification kits. The Bureau of Meteorology funds rural sensor network infrastructure that lowers private sector deployment barriers. New South Wales grain belts adopt satellite-based biomass modeling for crop insurance underwriting decisions.
Netherlands
Dutch greenhouse clusters and drip-irrigation districts deploy soil moisture and weather station networks most densely where water scarcity justifies real-time monitoring capital outlays. EU AI Act and data governance frameworks shape platform interoperability requirements. Wageningen University field stations validate algorithm performance across diverse agroecological zones.
Global Digital Farming Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. The upper tier combines proprietary hardware platforms with recurring software subscriptions that deepen grower dependency and compress replacement cycles. Below, specialists concentrate on correction services, open-architecture connectivity, or hyperspectral analytics. Dominant competitive moves include backward integration into sensor manufacturing and strategic partnerships with agricultural cooperatives for volume licensing.
Within the integrated equipment tier, Deere & Company and AGCO Corporation exemplify divergent platform strategies—one leveraging closed dealer networks, the other emphasizing mixed-fleet interoperability. Trimble Inc. anchors the precision guidance specialist position. These three represent the primary competitive archetypes shaping procurement patterns across Americas and European row-crop markets.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| CNH Industrial N.V. |
| Trimble Inc. |
| Bayer AG |
| Syngenta Group Co., Ltd. |
| IBM Corporation |
| Topcon Corporation |
| Kubota Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term SaaS subscription contracts with embedded hardware bundles lock in supply access and price visibility across precision agriculture procurement cycles. The United States Department of Agriculture Rural Broadband subsidies and FCC spectrum allocations stabilize connectivity infrastructure costs, while EU Farm to Fork compliance requirements add certification premiums to European pricing structures.
Pricing Analysis
SaaS-tiered subscription models dominate, with farm management software capturing recurring revenue through cloud-based dashboards and precision equipment bundles. Price differentiation rests on carbon-accounting certification tiers and cooperative volume scale, with European CSRD-aligned platforms commanding premiums over baseline tiers. Pricing pressure stems from cooperative procurement consortia aggregating hundreds of member farms to extract volume discounts. Smallholder cooperatives exhibit highest price sensitivity, while large-scale United States row-crop operations above 5,000 acres absorb premium tiers for autonomous machinery pilot access.
Supply Chain Analysis
China and Taiwan anchor semiconductor fabrication for IoT sensors and edge computing devices essential to precision workflows. The supply chain draws from Malaysian sensor assembly facilities and German optical component manufacturers for hyperspectral imaging payloads. Single-source vulnerability concentrates in GNSS correction service infrastructure, where signal degradation risks disrupt high-accuracy guidance applications. Distribution runs through Deere and AGCO captive dealer networks in the Americas, alongside open-architecture platform partnerships with European agricultural cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital farming represents a service-attach opportunity where recurring software subscriptions expand faster than precision hardware depreciation cycles. Data analytics modules and carbon verification dashboards now outpace sensor equipment revenue growth across major agricultural economies.
For Market Incumbents: Shield installed base relationships by deepening proprietary Operations Center and Fuse platform integration that raises switching costs for mixed-fleet operators. Backward integration into sensor manufacturing secures supply continuity against semiconductor volatility, while dealer network control limits emerging open-architecture entrants from gaining service access to legacy equipment fleets.
For New Entrants and Emerging Players: Differentiate on AI-multispectral convergence for automated disease detection in Brazilian soybean cooperatives and Australian broadacre wheat systems, where cloud connectivity infrastructure gaps have slowed incumbent platform deployment. Target soil health kit verification services for carbon credit markets, leveraging portable spectroscopy devices to capture regenerative agriculture protocol demand ahead of bundled incumbent offerings.
For Investors and Strategic Acquirers: Specialist hyperspectral analytics firms with validated algorithm performance across diverse agroecological zones present acquisition targets as platform vendors seek imaging capabilities. Long-term viability hinges on data ownership framework clarity, with regulatory resolution in the United States and European Union serving as the critical inflection signal for platform switching cost intensity and ecosystem lock-in durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Fuse open-architecture connectivity enables mixed-fleet interoperability across AGCO's cooperative partnerships. |
| Backward Integration | In-house sensor manufacturing reduces semiconductor shortage exposure for precision guidance hardware vendors. |
| Strategic Partnership | Cooperative procurement consortia aggregate licensing volumes to compress vendor margins across Midwestern operations. |
| Product Launch | Carbon-accounting-enabled farm management platforms address EU CSRD scope 3 disclosure mandates for food processors. |
| Geographic Expansion | ANVISA-compliant drone spraying systems capture Brazilian citrus district demand for export certification workflows. |
Methodological Framework
Cross-validation between primary interviews with precision agriculture platform engineers, cooperative procurement managers, and USDA policy specialists and secondary validation anchors the qualitative findings. Secondary sources include FCC spectrum allocation records, EU Farm to Fork strategy documentation, SEC 10-K filings from equipment manufacturers, and Embrapa field trial databases. Bottom-up farm-level adoption modeling and top-down regional expenditure aggregation enable triangulation across technology deployment timelines.
Sensitivity analysis around rural broadband infrastructure buildout pace and carbon credit market liquidity shapes the analytical framework across the projection horizon. Segmentation dimensions include technology type, product category, end-user scale archetype, and application workflow, with regional regulatory cluster as an additional modeled dimension. CAGRs derive from fitted adoption curves calibrated against historical precision equipment replacement cycles and software subscription renewal rates, incorporating ANVISA compliance timeline assumptions for Latin American pest control automation.
Material uncertainties — semiconductor supply volatility, data ownership framework evolution, and EU AI Act interoperability mandates — sit outside the modeled envelope. Forecasts reflect assumptions about cooperative buyer consolidation intensity and cloud connectivity infrastructure expansion pace. Recalibration cycles align with material shifts in subsidy program allocations and carbon verification protocol standardization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
North America Precision Agriculture Market
Precision Agriculture
Variable Rate Technology Market
Precision Agriculture
Automated Pest Monitoring System Market
Precision Agriculture
Digital Agriculture Solutions Market
Precision Agriculture
Crop Nutrient Management Market
Precision Agriculture
Global Agriculture Sensors Market
Precision Agriculture
Digital Agriculture Market
Precision Agriculture
Precision Farming Software Market
Precision Agriculture
Agricultural Mapping Services Market
Precision Agriculture
Precision Livestock Market
Precision Agriculture
Crop Monitoring Market
Precision Agriculture
Remote Fertigation Monitoring Services Market
Precision Agriculture
Americas Precision Farming Software Market
Precision Agriculture
Agriculture IoT Sensor Market
Precision Agriculture
Soil Monitoring System Market
Precision Agriculture
Precision Agriculture Market